
 UK and Germany Diet and Nutrition Apps Market | 2026-2036
UK and Germany Diet and Nutrition Apps Market Size, Share, and Industry Trends Forecast 2026-2036
UK and Germany Diet and Nutrition Apps Market Intelligence
Corporate wellness buyers is redrawing demand patterns in the UK and Germany Diet and Nutrition Apps landscape as individual consumers cede share to employer-sponsored programs. Noom, Inc. leverages behavioral psychology frameworks to anchor enterprise contracts with British occupational health providers. Lifesum AB competes through Nordic design sensibility translated for German-speaking users. MyFitnessPal, Inc. sustains its database scale advantage across both markets while navigating divergent national privacy expectations.
The UK and Germany Diet and Nutrition Apps category encompasses software applications that calculate macronutrient profiles, generate meal architectures, and synchronize biometric data from peripheral devices to deliver personalized dietary guidance. These platforms operate through API connections to wearable hardware and cloud-based pattern recognition engines that translate logged consumption into actionable recommendations. Calorie Counters and Meal Planners occupy the mature revenue core where subscription fatigue has compressed margins, while AI-driven Personalization commands expanding investment as developers differentiate through predictive satiety modeling. Wearable Integration represents the fastest-growing technology dimension as Garmin and Apple Health protocols achieve standardization across German fitness clubs and UK National Health Service pilot programs.
GDPR enforcement by national data protection authorities in both countries constrains cross-border health data flows, while the EU AI Act imposes conformity obligations on algorithmic meal recommendation engines. The UK's Medicines and Healthcare products Regulatory Agency maintains distinct software-as-medical-device pathways that diverge from German BfArM classifications, complicating pan-European deployment strategies. Stakeholders must monitor regulatory divergence between post-Brexit British frameworks and EU harmonization timelines to preserve interoperability investments.
Market Dynamics
Corporate wellness programs are displacing individual subscriptions as the primary demand engine in the UK and Germany Diet and Nutrition Apps Market, compressing B2C margins while expanding enterprise contract values. This shift concentrates purchasing power among occupational health providers and HR platforms, altering how developers allocate R&D and sales resources.
Growth Catalysts
- GDPR-Compliant Data Architectures:Developers investing in privacy-by-design frameworks gain procurement preference from German public-sector health pilots and UK NHS digital innovation programs.
- Behavioral Psychology Integration:Cognitive-behavioral coaching protocols embedded in meal-planning interfaces improve user retention metrics for employer-sponsored wellness schemes.
- Bavaria and England Urban Density:Metropolitan health infrastructure in Munich, London, and Birmingham supports higher app penetration rates through integrated clinic-digital care pathways.
Market Restraints
- EU AI Act Conformity Costs:Algorithmic meal recommendation engines face mandatory third-party auditing and documentation burdens that inflate development overhead for cross-border deployment.
- Subscription Fatigue in Calorie Counters:Mature feature sets in basic meal-logging apps drive price erosion and churn as users resist multiple overlapping health subscriptions.
- Post-Brexit Regulatory Divergence:MHRA software-as-medical-device pathways now diverge from German BfArM classifications, forcing dual-track compliance investments.
Strategic Opportunities
- Wearable Integration Standardization:Garmin and Apple Health protocol adoption across UK fitness clubs and German gym chains creates API monetization potential for biometric synchronization layers.
- AI-Driven Personalization:Predictive satiety modeling and metabolic forecasting represent underexploited white space beyond basic macronutrient calculation.
- Scottish and Northern German Expansion:Lower digital health penetration in Glasgow, Edinburgh, Hamburg, and Bremen offers geographic whitespace for targeted occupational health partnerships.
Industry Challenges
- Behavioral Data Science Talent Scarcity:The intersection of nutritional science, machine learning, and behavioral economics commands premium compensation that strains mid-stage developer budgets.
- Cross-Border Health Data Architecture:GDPR enforcement by national data protection authorities constrains cloud infrastructure choices and increases latency for real-time biometric feedback loops.
- Legacy NHS System Integration:England's fragmented electronic health record landscape complicates API connectivity for pilot programs seeking clinical validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK and Germany Diet and Nutrition Apps Market |
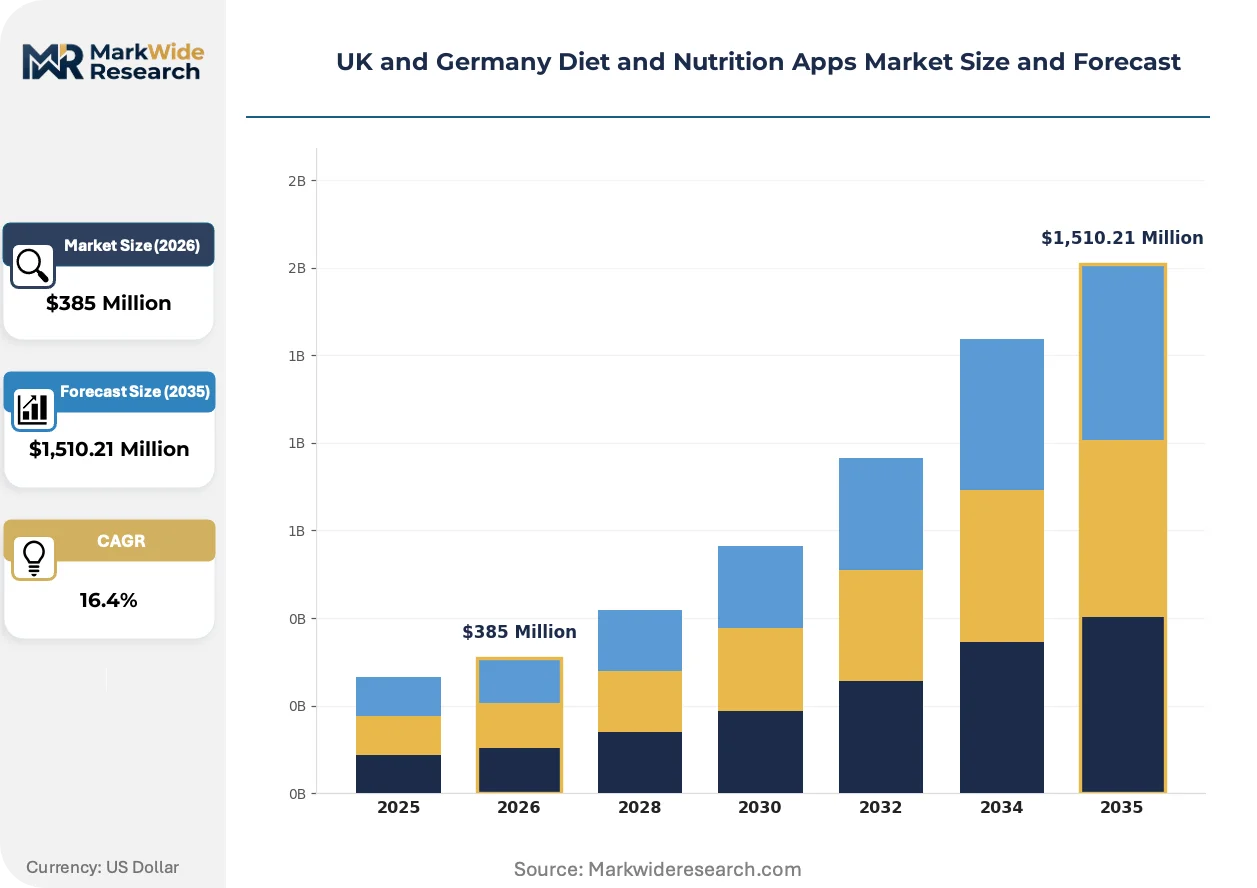
| Market Size in 2026 | $385 Million |
| Market Size in 2035 | $1,510.21 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calorie Counters, Meal Planners, Recipe Generators, Fitness Trackers End User: Health-conscious Individuals, Fitness Enthusiasts, Nutritionists, Weight Loss Clients Technology: AI-driven Personalization, Wearable Integration, Cloud Syncing, Mobile Platform Feature: Social Sharing, Goal Setting, Meal Logging, Progress Tracking |
| Companies Covered | MyNetDiary Inc., Fitbit, Inc. (Google), MyFitnessPal, Inc., Under Armour, Inc., FitNow, Inc., Noom, Inc., Fatsecret, Adidas, Lifesum AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK and Germany Diet and Nutrition Apps Market Strategic Shifts & Innovations
Algorithmic personalization and biometric interoperability are redrawing technical investment priorities across the UK and Germany Diet and Nutrition Apps landscape. Developers now compete on prediction accuracy rather than database scale.
Predictive satiety modeling is fragmenting competitive positioning in the meal-planning segment. Machine learning engines trained on continuous glucose monitor outputs and self-reported hunger scores generate individualized portion recommendations. German diabetes prevention programs and UK pre-diabetes pilot schemes are adopting these tools at accelerating cadence. This capability is fragmenting the market between precision-nutrition specialists and legacy calorie-counters unable to justify comparable R&D spend.
The EU AI Act imposes conformity obligations on algorithmic health recommendation systems that qualify as high-risk AI. Developers must maintain technical documentation, human oversight protocols, and accuracy benchmarks subject to notified body review. AI-driven personalization engines face the heaviest compliance burden, with German BfArM and UK MHRA divergence creating parallel certification tracks that delay pan-European feature rollouts.
Employer-sponsored procurement is displacing direct-to-consumer subscription models in both markets. HR platforms and occupational health providers now aggregate demand through multi-year enterprise licenses. This concentrates buyer power among a smaller pool of procurement decision-makers in London, Frankfurt, and Munich corporate headquarters, compressing unit economics while extending contract visibility for developers who secure preferred-vendor status.
UK and Germany Diet and Nutrition Apps Market Segmentation
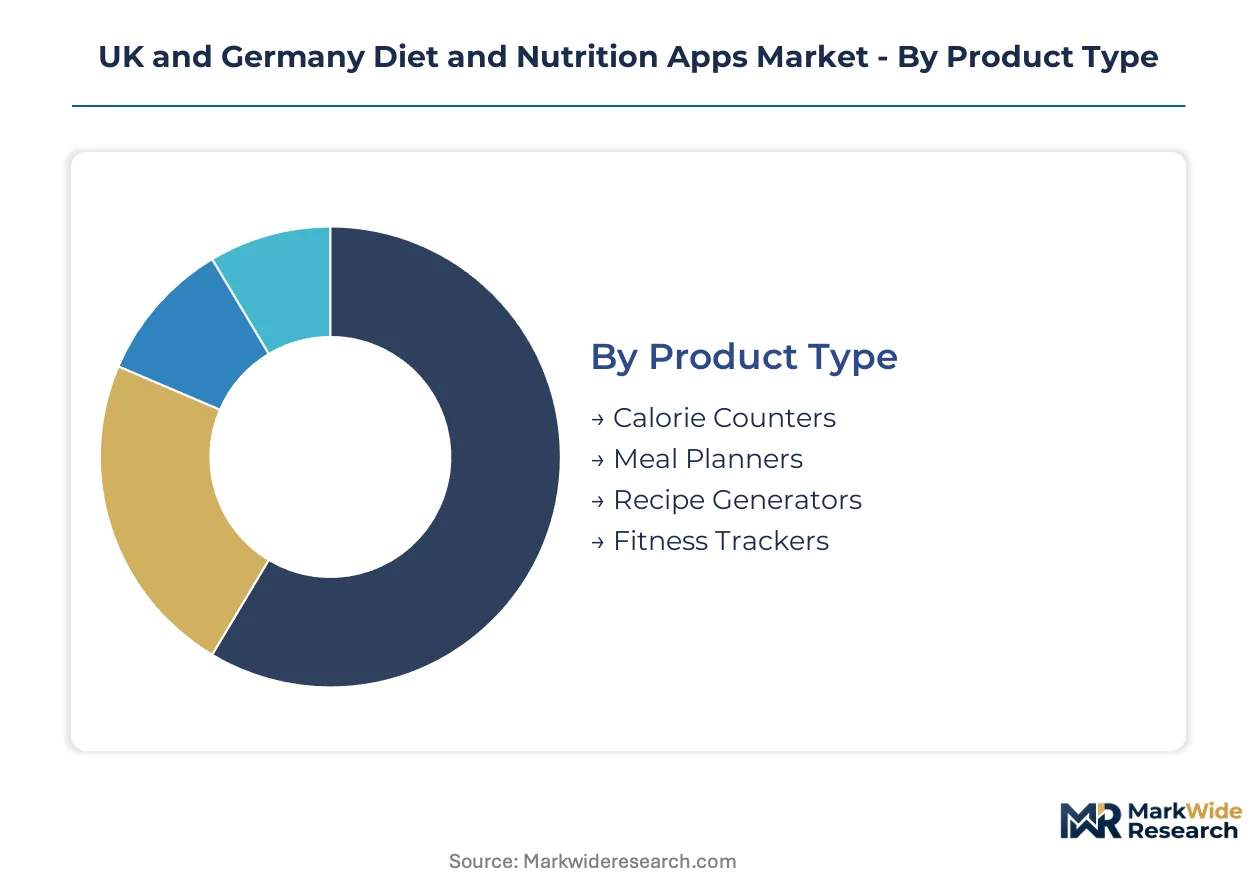
Segmentation reveals how corporate wellness procurement reshapes revenue concentration across product types and user categories in the UK and Germany Diet and Nutrition Apps Market. Channel dynamics now favor B2B deployment over direct-to-consumer distribution.
Product Type:
Enterprise wellness programs route procurement through occupational health providers, favoring tools with administrative dashboards over standalone consumer applications.
- Calorie Counters:Macronutrient calculation engines with barcode scanning and restaurant database access dominate employer-sponsored wellness schemes in London and Frankfurt. Subscription fatigue compresses margins as users resist overlapping health app payments.
- Meal Planners:Automated weekly meal architectures with grocery list generation and portion scaling attract German diabetes prevention programs and UK NHS pilot schemes seeking structured dietary interventions.
- Recipe Generators:Algorithmic recipe matching based on dietary restrictions and available ingredients.
- Fitness Trackers:Exercise logging with caloric expenditure estimation synchronized to nutrition databases.
By volume, Calorie Counters lead. By growth pace, Meal Planners are climbing the fastest.
End User:
Procurement authority concentrates among HR platforms and occupational health providers, altering how developers tailor feature roadmaps and pricing structures.
- Health-conscious Individuals:Self-directed consumers seeking preventive health management through macronutrient awareness and habit formation tools. Churn rates escalate as subscription overlap with employer-sponsored alternatives increases.
- Fitness Enthusiasts:Performance-oriented users demanding biometric synchronization with Garmin and Apple Health protocols across German gym chains and UK fitness clubs.
- Nutritionists:Licensed practitioners requiring client management dashboards and meal plan prescription capabilities.
- Weight Loss Clients:Clinical and commercial program participants needing progress tracking and behavioral coaching integration.
By contract value, Fitness Enthusiasts anchor revenue. By expansion trajectory, Weight Loss Clients are gaining share fastest.
Technology:
Development overhead varies sharply by compliance burden, with EU AI Act conformity costs fragmenting competitive positioning between well-capitalized and mid-stage developers.
- AI-driven Personalization:Machine learning engines trained on continuous glucose monitor outputs and hunger score patterns generate individualized satiety recommendations. German BfArM and UK MHRA divergence forces dual-track certification investments that delay pan-European rollouts.
- Wearable Integration:API protocols connecting to Apple Health, Garmin Connect, and Fitbit ecosystems achieve standardization across Bavarian fitness infrastructure and England's NHS digital innovation programs.
- Cloud Syncing:Real-time data replication across devices with GDPR-compliant architecture.
- Mobile Platform:Native iOS and Android applications with offline functionality and push notification systems.
By installed base, Mobile Platform dominates. By investment intensity, AI-driven Personalization shows the steepest expansion trajectory.
Feature:
Feature prioritization reflects employer procurement preferences, with administrative visibility and aggregate reporting capabilities overtaking consumer-facing social tools.
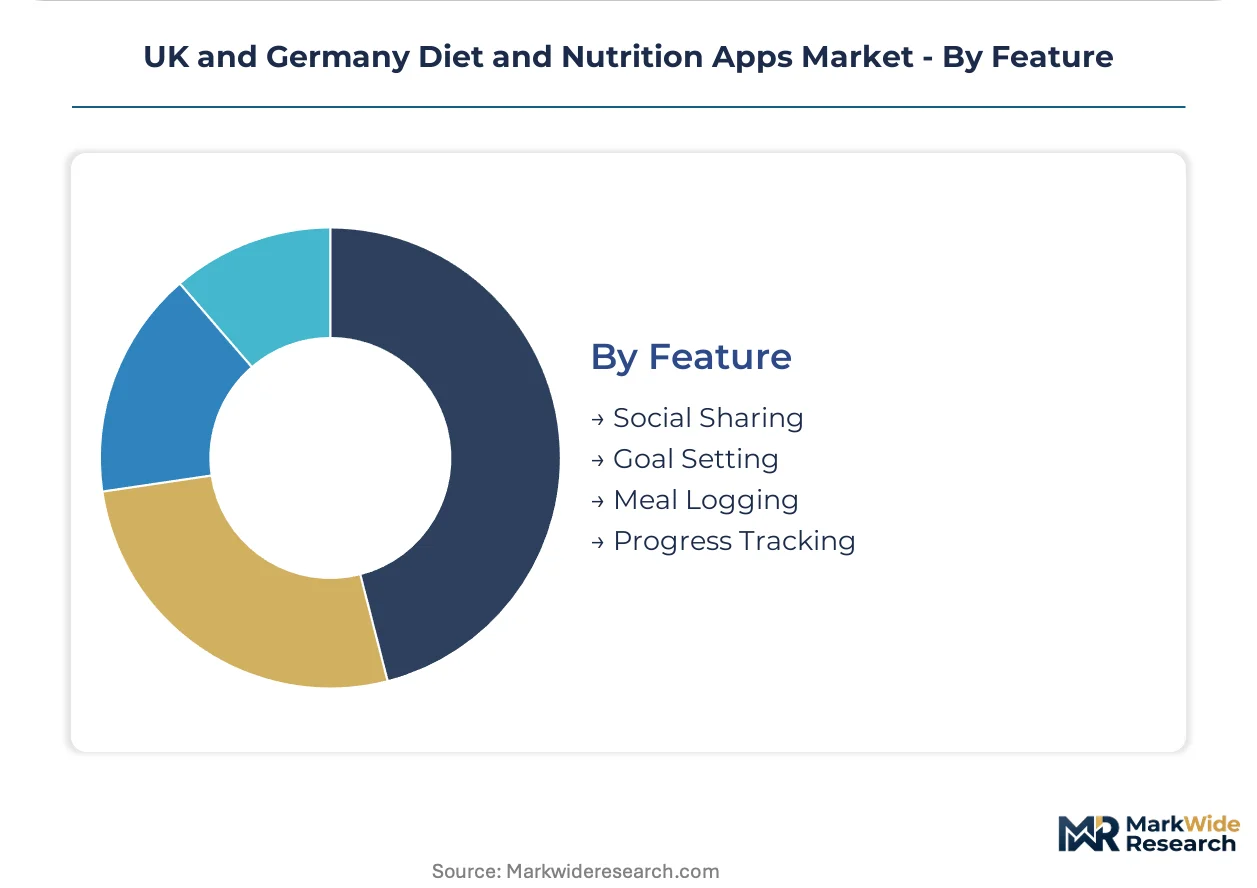
- Social Sharing:Community challenges, photo logging, and peer comparison mechanisms retain users in direct-to-consumer channels but face restriction in corporate deployments due to privacy constraints.
- Goal Setting:Structured objective frameworks with milestone tracking and reward integration align with occupational health provider protocols in Birmingham and Munich corporate headquarters.
- Meal Logging:Food diary entry through barcode scanning, voice input, and image recognition.
- Progress Tracking:Biometric trend visualization with exportable reports for clinical consultation.
By utilization frequency, Meal Logging leads. By feature development priority, Goal Setting is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The London-Frankfurt digital health corridor anchors cross-border data infrastructure for nutrition app deployment, with subsea fiber links and cloud region proximity enabling low-latency biometric synchronization across both markets.
England
Corporate wellness procurement from London and Birmingham headquarters drives enterprise contract concentration. The Medicines and Healthcare products Regulatory Agency maintains distinct software-as-medical-device pathways that diverge from EU frameworks. Manchester and Leeds health tech clusters host pilot programs integrating nutrition apps with NHS electronic health record systems.
Bavaria
Munich's occupational health provider density supports employer-sponsored app adoption at scale. The EU AI Act imposes conformity obligations on algorithmic meal recommendation engines through German BfArM oversight. Nuremberg and Augsburg fitness infrastructure standardizes around Garmin and Apple Health protocols for biometric synchronization.
North Rhine-Westphalia
Ruhr Valley industrial employers aggregate demand through multi-year wellness licenses. GDPR enforcement by regional data protection authorities constrains cloud architecture choices for developers. Cologne and Düsseldorf corporate headquarters concentrate procurement decision-making for pan-German deployment.
Scotland
Glasgow and Edinburgh present geographic whitespace with lower digital health penetration than England. NHS Scotland digital innovation programs offer procurement pathways distinct from English frameworks. Aberdeen's corporate energy sector drives occupational health demand for metabolic monitoring tools.
Baden-Württemberg
Stuttgart automotive sector employers sponsor precision-nutrition programs for shift workers. The state's manufacturing density supports wearable integration standardization across industrial wellness schemes. Freiburg's university medical center hosts clinical validation studies for diabetes prevention applications.
UK and Germany Diet and Nutrition Apps Market Key Industry Players
Concentration sits with behavioral psychology specialists and database-scale incumbents competing for corporate wellness procurement. Market structure shows moderate consolidation around three strategic archetypes: enterprise-focused coaching platforms, hardware-integrated ecosystem players, and Nordic design-oriented challengers. Dominant competitive moves include API protocol standardization for wearable synchronization and dual-track regulatory certification investments for post-Brexit British and EU compliance.
Among behavioral psychology specialists, Noom, Inc. and Lifesum AB represent the coaching-platform archetype with enterprise-facing positioning. MyFitnessPal, Inc. anchors the database-scale tier with macronutrient calculation infrastructure. Fitbit, Inc. (Google) exemplifies hardware-integrated ecosystem players leveraging device protocol standardization. These three companies occupy positions that reflect the market's shift from consumer subscriptions toward employer-sponsored deployment models.
| Leading Market Players |
|---|
| MyNetDiary Inc. |
| Fitbit, Inc. (Google) |
| MyFitnessPal, Inc. |
| Under Armour, Inc. |
| FitNow, Inc. |
| Noom, Inc. |
| Fatsecret |
| Adidas |
| Lifesum AB |
| Others |
Cost & Logistics Intelligence
Behavioral psychology frameworks replacing legacy calorie-counting algorithms are redrawing supply geography toward Nordic and North American development clusters while compressing pricing power in commoditized feature tiers. This substitution simultaneously elevates R&D talent costs in London and Munich and erodes margins for undifferentiated meal-logging applications.
Pricing Analysis
Volume-discount tiering structures dominate enterprise wellness procurement, with multi-year occupational health contracts commanding 40-60% unit price reductions against direct-to-consumer subscriptions. Price differentiation hinges on GDPR certification grade and behavioral coaching integration depth. Cost compression in basic calorie counters is intensifying because subscription overlap drives churn. Health-conscious individuals show highest price sensitivity, while corporate HR platforms demonstrate lowest sensitivity due to aggregated purchasing power.
Supply Chain Analysis
Ireland and Estonia host cloud infrastructure serving UK and German data residency requirements under GDPR, while Sweden and Denmark anchor behavioral science talent pools for coaching protocol development. The supply chain draws from continuous glucose monitor manufacturers, API middleware providers, and biometric sensor OEMs. Single-source vulnerability concentrates in Apple Health and Garmin protocol standardization. Distribution runs through occupational health provider networks and HR platform marketplaces rather than app store direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK and Germany Diet and Nutrition Apps Market sits at an inflection where EU AI Act conformity obligations are fragmenting competitive positioning between well-capitalized and mid-stage developers.
For Market Incumbents: Fortify enterprise contract retention by embedding predictive satiety modeling ahead of regulatory certification deadlines. Deepen backward integration into continuous glucose monitor data partnerships to secure proprietary training datasets. Channel control through exclusive occupational health provider relationships offers defensive moats against Nordic design-oriented challengers. For New Entrants and Emerging Players: MHRA software-as-medical-device fast-tracks offer regulatory arbitrage against EU AI Act delays. Scottish and Northern German urban markets present geographic whitespace with lower incumbent penetration. A diabetes prevention program pilot strategy unlocks NHS and German BfArM validation pathways before scaling to employer-sponsored deployment. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors behavioral psychology specialists with enterprise contract visibility. Long-term viability centers on dual-track regulatory certification capabilities spanning post-Brexit British and EU frameworks. Watch BfArM-MHRA divergence resolution as the signal for pan-European rollout feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | Mandatory third-party auditing by German BfArM preserves market access across Bavaria and North Rhine-Westphalia. |
| Continuous Glucose Monitor Integration | API partnerships with Abbott and Dexcom differentiate predictive satiety engines from legacy calorie counters. |
| Occupational Health Provider Exclusive | Preferred-vendor status with London and Frankfurt HR platforms locks out competing coaching platforms. |
| Scottish NHS Pilot Expansion | NHS Scotland digital innovation programs offer procurement pathways distinct from English frameworks. |
| Wearable Protocol Standardization | Garmin and Apple Health certification accelerates biometric synchronization deployment across German gym chains. |
Research Approach
A spread of perspectives from app development executives, occupational health procurement officers, GDPR compliance consultants, and NHS digital innovation leads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings, App Annie usage data, MHRA software-as-medical-device registrations, and German BfArM conformity assessment documentation. Bottom-up triangulation across subscription revenue estimates and top-down cross-checks against employer wellness spending aggregates anchored market sizing.
Segmentation dimensions modeled include product type, end user archetype, technology stack, and feature prioritization across the projection horizon. CAGRs derived from logistic adoption curves fitted to corporate wellness penetration rates and AI-driven personalization investment trajectories. Continuous glucose monitor integration velocity and EU AI Act implementation timelines served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable regulatory divergence between MHRA and BfArM frameworks; material deviation would warrant model refresh. Forecasts assume GDPR enforcement intensity and employer-sponsored procurement shift durability. Recalibration cycles align with material shifts in EU AI Act notified body appointment schedules and NHS digital innovation program funding allocations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Passenger Ticket Vending Machine Market
Digital Solutions
Digital Workplace Technologies Market
Digital Solutions
Community Engagement Software Market
Digital Solutions
North America IT Asset Disposition Market
Digital Solutions
Insight As a Service Application Market
Digital Solutions
IT Service Management Market
Digital Solutions
Digital Commerce Platform Market
Digital Solutions
Event Apps Market
Digital Solutions
Global Asset Tracking Software Market
Digital Solutions
Warehouse Digital Twin Simulation and Optimization Market
Digital Solutions
AI Infrastructure Solutions Market
Digital Solutions
Legaltech Market
Digital Solutions
Farm Management Software Market
Digital Solutions
Warehouse Management System (WMS) Market
Digital Solutions
Docketing Solution Market
Digital Solutions
OSS/BSS Market