
 Asia-Pacific Route Optimization Software Market | 2026-2036
Asia-Pacific Route Optimization Software Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Route Optimization Software Market Analytics
Third-party logistics channel partnerships are reconfiguring across the Asia-Pacific as cloud infrastructure providers deepen ties with fleet operators. Samsara leverages its IoT sensor ecosystem to anchor real-time visibility contracts with Australian mining transport fleets. HERE Technologies competes through proprietary mapping layers that dominate Japan's dense urban routing requirements. Descartes Systems Group extends its customs-compliance integration into last-mile optimization for Southeast Asian e-commerce corridors.
Asia-Pacific route optimization software encompasses algorithmic platforms that compute shortest-path and least-cost routing for commercial vehicle fleets, typically processing GPS telemetry, traffic pattern data, and delivery time-window constraints through heuristic or exact optimization engines. These systems primarily reduce fuel expenditure and driver overtime while improving on-time delivery performance in high-fragmentation logistics environments. Cloud-based deployment leads adoption as logistics companies prioritize elastic compute capacity over capital-intensive server infrastructure, though on-premise solutions retain traction among public sector transport authorities with stringent data sovereignty requirements. Real-time tracking solutions capture the fastest growth trajectory as e-commerce firms demand sub-minute visibility into driver location and exception events across urban delivery networks.
India's BIS data localization guidelines and Australia's Privacy Act frameworks shape how vendors architect server residency and encryption protocols for cross-border fleet data. Japan's METI has issued smart mobility roadmaps that embed route optimization standards within connected vehicle certification requirements. Stakeholders must monitor how ASEAN member states harmonize digital trade rules governing telematics data flows, as regulatory fragmentation threatens platform interoperability across multi-country logistics networks.
Market Dynamics
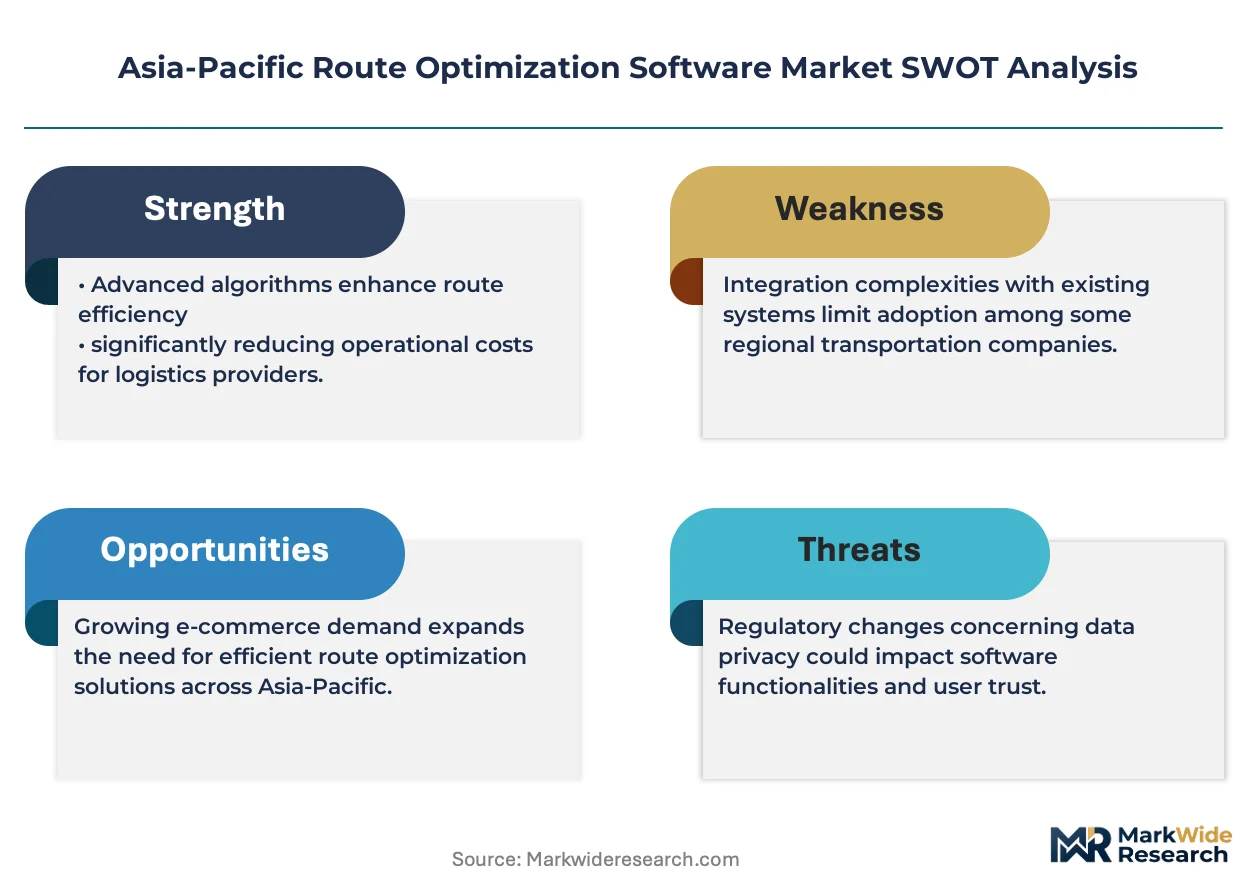
Cloud infrastructure elasticity is compressing capital barriers for mid-tier logistics operators across Southeast Asia, while India's BIS data localization mandates force architectural decisions on server residency that fragment platform standardization.
Growth Catalysts
- India's PLI scheme for automotive and electronics:Manufacturing incentives accelerate fleet digitization mandates among contract logistics providers serving export-oriented assembly plants.
- Real-time visibility platforms:E-commerce fulfillment networks in Indonesia and Vietnam demand sub-minute GPS telemetry integration to manage urban delivery density.
- Australia's mining corridor electrification:Long-haul supply chains require algorithmic load balancing across remote routes with limited charging infrastructure.
Market Restraints
- Cross-border data friction:ASEAN's unharmonized digital trade rules create compliance overhead for multi-country fleet operators routing through Singapore, Thailand, and Malaysia.
- Legacy ERP integration costs:On-premise transport management systems in Japan's consolidated logistics sector resist API migration without substantial middleware expenditure.
- Telematics hardware concentration:Sensor module supply depends on concentrated semiconductor fabrication outside the region, exposing lead time volatility.
Strategic Opportunities
- Philippines archipelago logistics:Island-hopping freight networks remain underpenetrated by algorithmic routing, favoring first-mover cloud platform deployment.
- Japan's METI smart mobility certification:Embedded optimization standards in connected vehicle type-approval create captive demand for compliant software stacks.
- Multi-modal convergence:Integration of port terminal operating systems with truck dispatch algorithms is compressing dwell times at Southeast Asian container hubs.
Industry Challenges
- Optimization engineering talent scarcity:Heuristic algorithm development requires operations research expertise concentrated in Bangalore and Singapore, constraining vendor expansion.
- API standardization delays:Inconsistent telematics data formats across Chinese, Korean, and Japanese vehicle OEMs force redundant integration layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Route Optimization Software Market |
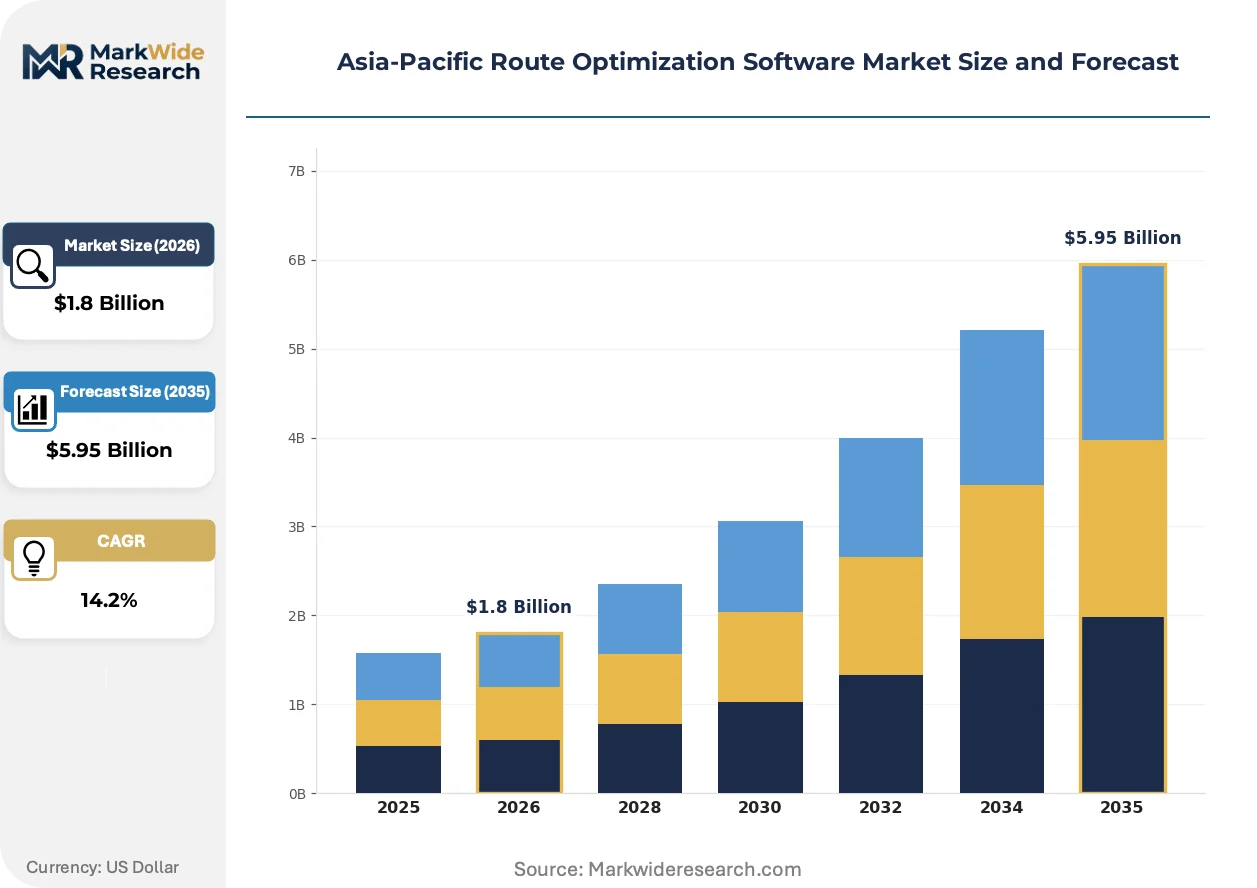
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Logistics Companies, E-Commerce Firms, Transportation Providers, Public Sector Solution: Real-Time Tracking, Fleet Management, Route Planning, Data Analytics Application: Urban Delivery, Long-Haul Transportation, Freight Management, Supply Chain Optimization |
| Companies Covered | Samsara, Verizon Connect, Descartes Systems Group, PTV Group, Trimble Inc., FarEye, Omnitracs, Route4Me, HERE Technologies, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Route Optimization Software Market Evolving Landscape
Algorithmic platforms are embedding predictive traffic models and dynamic re-routing capabilities that compress delivery window variance. Three developments are restructuring competitive requirements.
Edge computing architectures are digitizing last-mile dispatch decisions. Singapore-based e-commerce fulfillment networks deploy containerized micro-data centers at urban distribution nodes. This topology reduces latency for driver re-routing commands from cloud round-trips to local processing.
Australia's Privacy Act frameworks mandate encryption protocols for cross-border fleet telemetry that exceed baseline commercial practice. Transport operators must architect data residency with jurisdictional segmentation. Mining logistics providers in Western Australia and Queensland are responding with sovereign cloud partnerships that isolate driver biometric data.
Subscription pricing for route optimization modules is displacing perpetual license structures among mid-market third-party logistics providers. Annual recurring revenue models align vendor incentives with customer uptime metrics. This shift concentrates in India's urban delivery corridors where working capital constraints favor operational expenditure treatment.
Asia-Pacific Route Optimization Software Market Segmentation
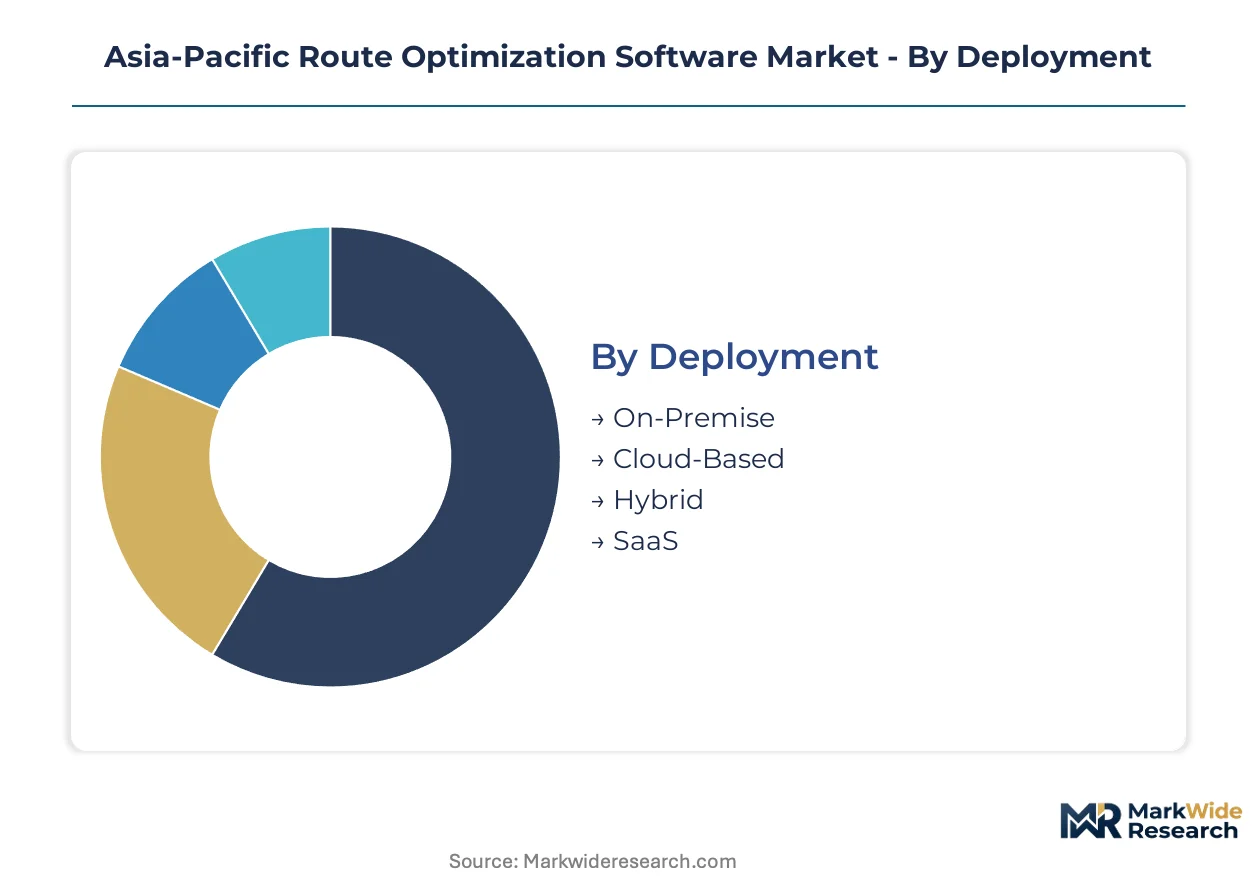
Route optimization software in Asia-Pacific fragments across deployment architectures, end-user verticals, solution capabilities, and application contexts. Each dimension carries distinct margin profiles, integration complexity, and regulatory exposure that shape vendor positioning strategies.
Deployment:
After-sales-service intensity varies sharply across deployment modes, with on-premise installations demanding sustained engineering support while cloud-native deployments shift maintenance burdens to vendor infrastructure teams.
- On-Premise:Licensed software running on customer-managed servers with full data sovereignty control. Japan's public sector transport authorities and Australia's mining logistics operators favor this architecture to satisfy Privacy Act and state-level data residency mandates.
- Cloud-Based:Vendor-hosted platforms delivering elastic compute capacity without capital expenditure. Southeast Asian third-party logistics providers in Indonesia and Vietnam are migrating here to bypass server infrastructure investments.
- Hybrid:Split architectures keeping sensitive dispatch data local while pushing optimization compute to cloud nodes. India's automotive contract logistics sector adopts this to balance BIS localization rules with algorithmic throughput needs.
- SaaS:Subscription-priced modules with API-first integration patterns. Mid-market e-commerce fulfillment networks in the Philippines and Malaysia prefer this for working capital flexibility.
Cloud-based deployments hold the largest share; momentum sits with SaaS as recurring revenue models align vendor incentives with customer uptime metrics.
End User:
Cost tier differentiation separates enterprise-grade implementations from scaled mid-market deployments across the four vertical clusters.
- Logistics Companies:Third-party and fourth-party operators managing multi-client fleet networks with complex cross-dock requirements. These buyers prioritize real-time visibility APIs and dynamic re-routing engines for Southeast Asian corridor density.
- E-Commerce Firms:Direct-to-consumer fulfillment networks demanding sub-minute GPS telemetry and predictive delivery windows. Indonesia's urban delivery corridors and India's tier-1 cities concentrate demand here.
- Transportation Providers:Asset-heavy trucking and bus operators optimizing owned fleet utilization. Australia's long-haul mining supply chains and Japan's consolidated trucking sector dominate this segment.
- Public Sector:Municipal and national transport authorities with procurement transparency requirements and data sovereignty constraints. METI-connected vehicle certification programs in Japan and BIS mandates in India shape specifications.
Logistics companies hold the largest share; momentum sits with e-commerce firms as urban delivery density intensifies algorithmic requirements.
Solution:
Application maturity curves separate established fleet management modules from emerging data analytics capabilities with steeper expansion trajectories.
- Real-Time Tracking:GPS telemetry platforms processing sub-minute location updates with exception alerting. E-commerce networks in Vietnam and Singapore deploy edge-computing architectures to compress latency for driver re-routing commands.
- Fleet Management:Integrated dispatch, maintenance scheduling, and driver compliance systems. Australia's mining transport operators and India's automotive contract logistics providers anchor demand with large asset bases.
- Route Planning:Static and dynamic optimization engines computing shortest-path and least-cost routing. Japan's dense urban environments with complex time-window constraints favor HERE Technologies' proprietary mapping layers.
- Data Analytics:Predictive models for fuel expenditure, driver overtime, and delivery variance. This capability is expanding most quickly as machine learning talent concentrates in Bangalore and Singapore operations research clusters.
Fleet management holds the largest share; momentum sits with data analytics as predictive traffic models reshape competitive requirements.
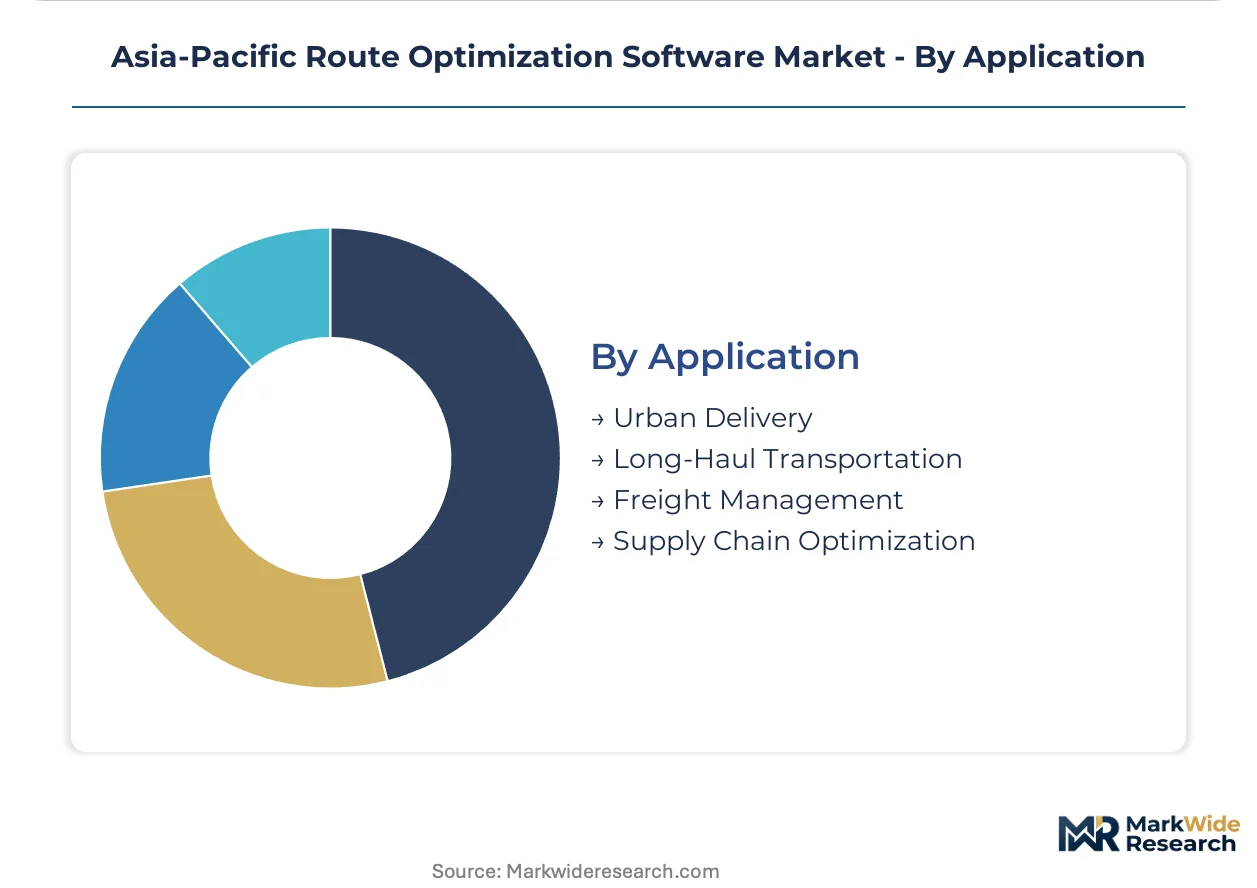
Application:
Geography-driven fragmentation separates urban density challenges from remote infrastructure constraints across the four use-case clusters.
- Urban Delivery:Last-mile optimization for high-frequency, short-radius routes with parking and congestion constraints. India's metropolitan corridors and Indonesia's Jakarta-Bandung logistics belt concentrate demand.
- Long-Haul Transportation:Multi-day routing across sparse infrastructure with fuel station and charging point optimization. Australia's Western Australia and Queensland mining supply chains dominate, with electrification mandates forcing algorithmic load balancing.
- Freight Management:Intermodal coordination across port, rail, and truck networks. Southeast Asian container hubs in Singapore, Thailand, and Malaysia drive integration with terminal operating systems.
- Supply Chain Optimization:End-to-end network design spanning procurement through last-mile. This application is gaining share fastest as ASEAN digital trade harmonization efforts compress multi-country compliance overhead.
Urban delivery holds the largest share; momentum sits with supply chain optimization as multi-modal convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Singapore anchors Asia-Pacific's maritime-land interface, processing transhipment flows that feed algorithmic dispatch networks across Southeast Asian manufacturing belts. Cloud infrastructure investments at this hub compress latency for real-time fleet coordination throughout the region.
India
Automotive contract logistics providers serving PLI-subsidized assembly plants drive fleet digitization mandates. BIS data localization guidelines force server residency decisions that fragment platform architectures. Bangalore's operations research talent clusters support heuristic algorithm development for urban delivery corridors in Mumbai and Delhi-NCR.
Australia
Western Australia and Queensland mining supply chains require algorithmic load balancing across remote routes with sparse charging infrastructure. Privacy Act frameworks mandate encryption protocols exceeding baseline commercial practice for cross-border telemetry. Sovereign cloud partnerships isolate driver biometric data at Perth and Brisbane logistics nodes.
Japan
Dense urban routing requirements in Tokyo and Osaka favor proprietary mapping layers with complex time-window optimization. METI smart mobility roadmaps embed route optimization standards within connected vehicle certification. Kanto and Kansai logistics operators face legacy ERP integration costs resisting API migration.
Indonesia
Jakarta-Bandung logistics belt concentrates e-commerce fulfillment networks demanding sub-minute GPS telemetry. Unharmonized ASEAN digital trade rules create compliance overhead for multi-country fleet operators routing through Singapore. Cloud platform deployment accelerates among mid-tier third-party logistics providers bypassing capital-intensive server investments.
Vietnam
Urban delivery density in Ho Chi Minh City and Hanoi intensifies algorithmic requirements for last-mile optimization. Edge-computing architectures at distribution nodes reduce latency for driver re-routing commands. Manufacturing export corridors from Hai Phong to Da Nang drive freight management integration with port terminal operating systems.
Asia-Pacific Route Optimization Software Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers. Cloud-native platforms compete against legacy on-premise vendors and hybrid deployment specialists. Strategic archetypes include IoT sensor ecosystem providers, proprietary mapping layer developers, and customs-compliance integrators. Dominant competitive moves encompass API-first partnership architectures and sovereign cloud alliances addressing data residency mandates.
Within the IoT-anchored tier, Samsara leverages sensor ecosystem density to secure real-time visibility contracts. HERE Technologies exemplifies the mapping-centric archetype through proprietary layers dominating dense urban routing requirements. Descartes Systems Group occupies a position bridging customs-compliance integration with last-mile optimization for Southeast Asian e-commerce corridors.
| Leading Market Players |
|---|
| Samsara |
| Verizon Connect |
| Descartes Systems Group |
| PTV Group |
| Trimble Inc. |
| FarEye |
| Omnitracs |
| Route4Me |
| HERE Technologies |
| Others |
Value Network & Pricing Analysis
The Jakarta-Bandung logistics belt channels SaaS subscription growth into tiered pricing architectures that compress margins for on-premise vendors while rewarding cloud-native platforms with volume-scaled enterprise contracts. Supply concentration in Taiwan's semiconductor foundries and South Korea's sensor module production feeds directly into platform cost structures, forcing Indian and Indonesian logistics operators toward operational expenditure models that bypass capital-intensive hardware procurement.
Pricing Analysis
Volume-discount tiering structures stratify across premium enterprise deployments, standard mid-market SaaS modules, and economy-tier API-only access for small fleet operators. Price differentiation hinges on real-time telemetry granularity and BIS-compliant data residency certification for Indian government contracts. Cost compression in the economy tier intensifies as Indonesian third-party logistics providers consolidate vendor relationships to reduce per-seat licensing overhead. E-commerce fulfillment networks exhibit highest price sensitivity due to working capital constraints, while Australian mining operators accept premium pricing for sovereign cloud isolation of driver biometric data.
Supply Chain Analysis
Extended payment terms from cloud infrastructure providers are easing cash flow pressure for Southeast Asian logistics platforms purchasing Taiwanese GPS chipsets and South Korean telematics sensors. Raw material dependencies center on semiconductor wafers, lithium-ion battery cells for electric fleet hardware, and precision antenna components for edge-computing nodes. Single-source vulnerability concentrates in Taiwan's advanced node fabrication, where lead time volatility ripples through sensor module availability. Distribution runs through Singapore's transhipment hub, consolidating hardware procurement for Indonesian and Vietnamese fleet digitization programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific route optimization sits in early-cycle expansion as India's PLI manufacturing incentives and Australia's mining electrification mandates force fleet digitization across contract logistics networks previously dependent on manual dispatch.
For Market Incumbents: Harden API-first partnership architectures against emerging cloud-native challengers by embedding customs-compliance modules directly into port terminal operating systems. Deepen sovereign cloud alliances in Perth and Brisbane to preempt Australian Privacy Act enforcement actions targeting cross-border telemetry. Vertical integration into edge-computing hardware distribution secures sensor supply continuity against Taiwanese fabrication bottlenecks. For New Entrants and Emerging Players: Mid-market SaaS gaps in the Philippines archipelago logistics sector represent the most penetrable entry point, with island-hopping freight networks lacking algorithmic routing penetration. Vietnam's manufacturing export corridors from Hai Phong to Da Nang offer secondary white-space for freight management integration with port terminal systems. Channel partnerships with Indonesian e-commerce fulfillment networks provide the strongest go-to-market velocity given their sub-minute GPS telemetry requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from Japanese logistics conglomerates divesting non-core software assets amid legacy ERP integration cost pressures. Long-term viability centers on platforms with METI smart mobility certification embedded in connected vehicle type-approval standards. The inflection signal to watch is ASEAN digital trade harmonization progress, as regulatory consolidation would compress compliance overhead and accelerate multi-country fleet operator consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding customs-compliance modules into Singapore port terminal systems compresses dwell times. |
| Strategic Partnership | Sovereign cloud alliances in Perth isolate Australian mining operator data under Privacy Act mandates. |
| Acquisition of Specialist Firm | Bangalore operations research talent clusters accelerate heuristic algorithm development for urban density. |
| Geographic Expansion | Philippines archipelago deployment captures first-mover advantage in underpenetrated island-hopping networks. |
| Product Launch | METI-certified optimization stacks lock in Japanese connected vehicle certification requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings from listed logistics technology vendors, BIS regulatory circulars on data localization, and ASEAN digital trade framework documents. Primary interviews engaged fleet operations directors at Indian automotive contract logistics providers, platform engineering leads at Singapore-based e-commerce fulfillment networks, and procurement officers at Australian mining transport operators. Secondary validation drew from METI smart mobility roadmap publications, Australian Privacy Act enforcement guidance, and customs data on telematics hardware imports. Bottom-up triangulation across deployment mode adoption curves and top-down reconciliation against regional cloud infrastructure capex disclosures anchored value estimates.
Forecast inputs incorporate deployment architecture migration rates, real-time visibility platform penetration across urban delivery corridors, and multi-modal integration depth at Southeast Asian container hubs. Segmentation dimensions span cloud-native versus on-premise deployment, logistics company versus e-commerce end-user verticals, and urban delivery versus long-haul application contexts. CAGRs derive from algorithmic adoption curves calibrated against India's PLI scheme implementation pace and Australia's mining electrification timeline. Fleet digitization mandates and edge-computing infrastructure rollouts constitute industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in regional cloud infrastructure investment cycles or semiconductor supply normalization would shift the trajectory. Forecasts reflect documented assumptions on regulatory harmonization progress and sensor module availability. Macroeconomic contraction, ASEAN digital trade fragmentation, or Taiwanese fabrication disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Social Employee Recognition Systems Market
Digital Solutions
Enterprise Mobility in Manufacturing Market
Digital Solutions
APAC Smart Office Market
Digital Solutions
Virtual Desktop Infrastructure (VDI) Market
Digital Solutions
Europe ICT Market
Digital Solutions
Virtual Closet Market
Digital Solutions
Asia-Pacific API Management Market
Digital Solutions
Digital Pen Market
Digital Solutions
Database Management Platform Market
Digital Solutions
Global Connected Workplace Market
Digital Solutions
Global Digital Accessibility Software Market
Digital Solutions
Cheque Scanner Market
Digital Solutions
Global Asset Tracking Software Market
Digital Solutions
Bangladesh ICT Market
Digital Solutions
Warranty Management System Market
Digital Solutions
IT Operations Management Market