
 Stylus Pen for Education Market | 2026-2036
Stylus Pen for Education Market Size, Share, and Industry Trends Forecast 2026-2036
Stylus Pen for Education Market Analysis
K-12 digital classrooms is expanding as the fastest-growing end-use vertical for stylus pens, displacing traditional note-taking in higher education. Apple leverages its ecosystem lock-in to sustain premium positioning across institutional procurement channels. Wacom specializes in pressure-sensitive graphic tablet pens for digital art curricula. XP-PEN Technology competes aggressively on price-performance ratios for entry-level educational bundles.
A stylus pen for education is a handheld input device incorporating capacitive, electromagnetic, or Bluetooth-enabled digitizer technology, typically featuring pressure sensitivity levels above 4,096 and palm-rejection algorithms, designed to enable precise handwriting capture and interactive content manipulation on tablet displays. Active stylus variants lead product type demand due to their tilt recognition and low latency, while passive stylus holds residual share in cost-constrained primary school deployments. E-learning application segments command widening margin pools as subscription-based platform integrations deepen hardware attachment rates.
FCC equipment authorization requirements govern wireless stylus emissions in the United States, while CE marking under EU RoHS and REACH directives restricts hazardous substance content for European educational procurement. ISO 9241 ergonomic standards increasingly influence district-level purchasing specifications for extended student use. Stakeholders must monitor how NHTSA-adjacent accessibility mandates and evolving GDPR-compliant data handling in connected pens reshape product design roadmaps and channel certification requirements.
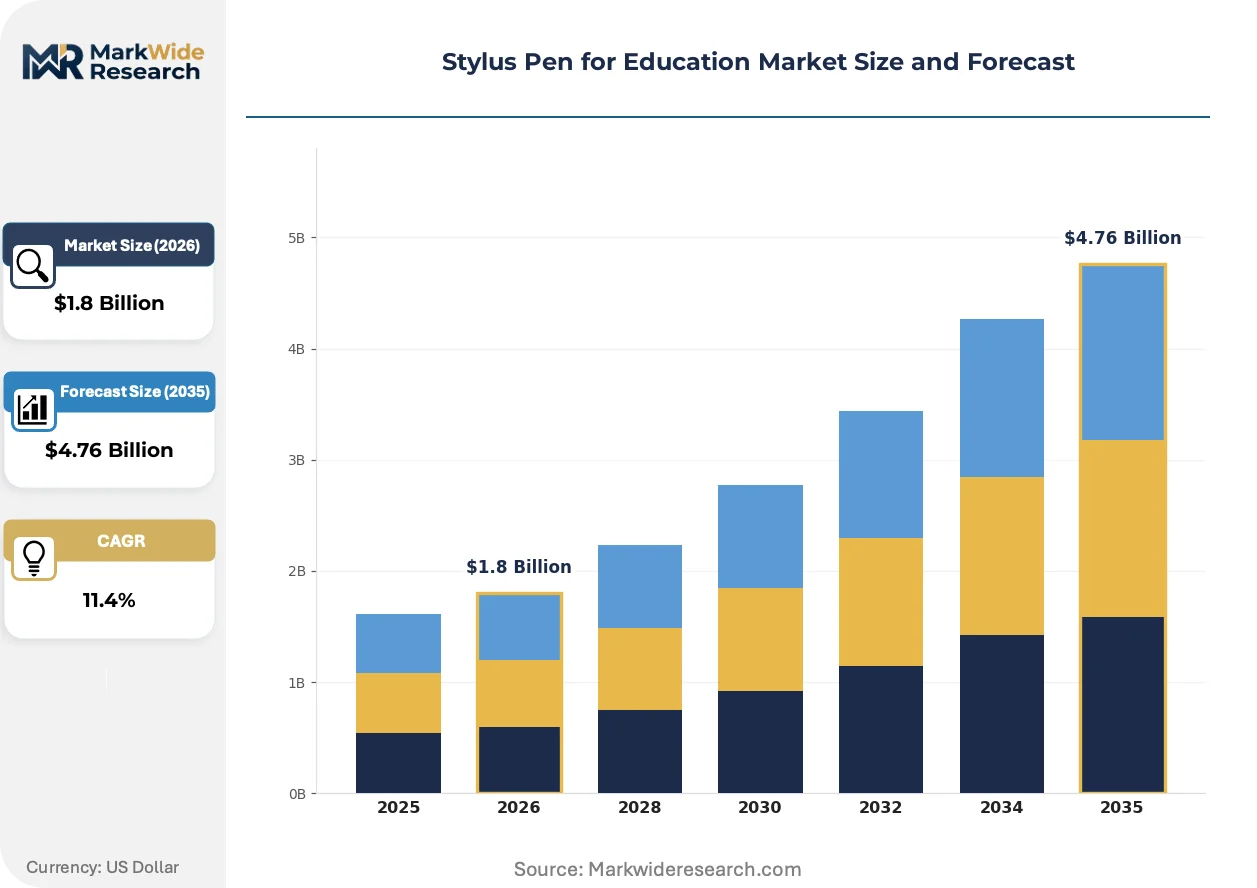
Market Dynamics
Federal ed-tech funding in the United States is compressing procurement cycles and tilting district purchasing toward Bluetooth-enabled active stylus systems that satisfy FCC equipment authorization requirements.
Growth Catalysts
- ESSER III Funding Allocation:United States school districts are deploying remaining Elementary and Secondary School Emergency Relief funds toward interactive hardware bundles that include pressure-sensitive stylus pens for 1:1 tablet programs.
- ISO 9241 Ergonomic Mandates:European educational procurement specifications increasingly require palm-rejection algorithms and tilt recognition features that only active stylus variants deliver.
- Digital Art Curricula Expansion:Secondary schools in Canada and Australia are integrating graphic design courses that specify electromagnetic digitizer pens with 4,096+ pressure levels.
Market Restraints
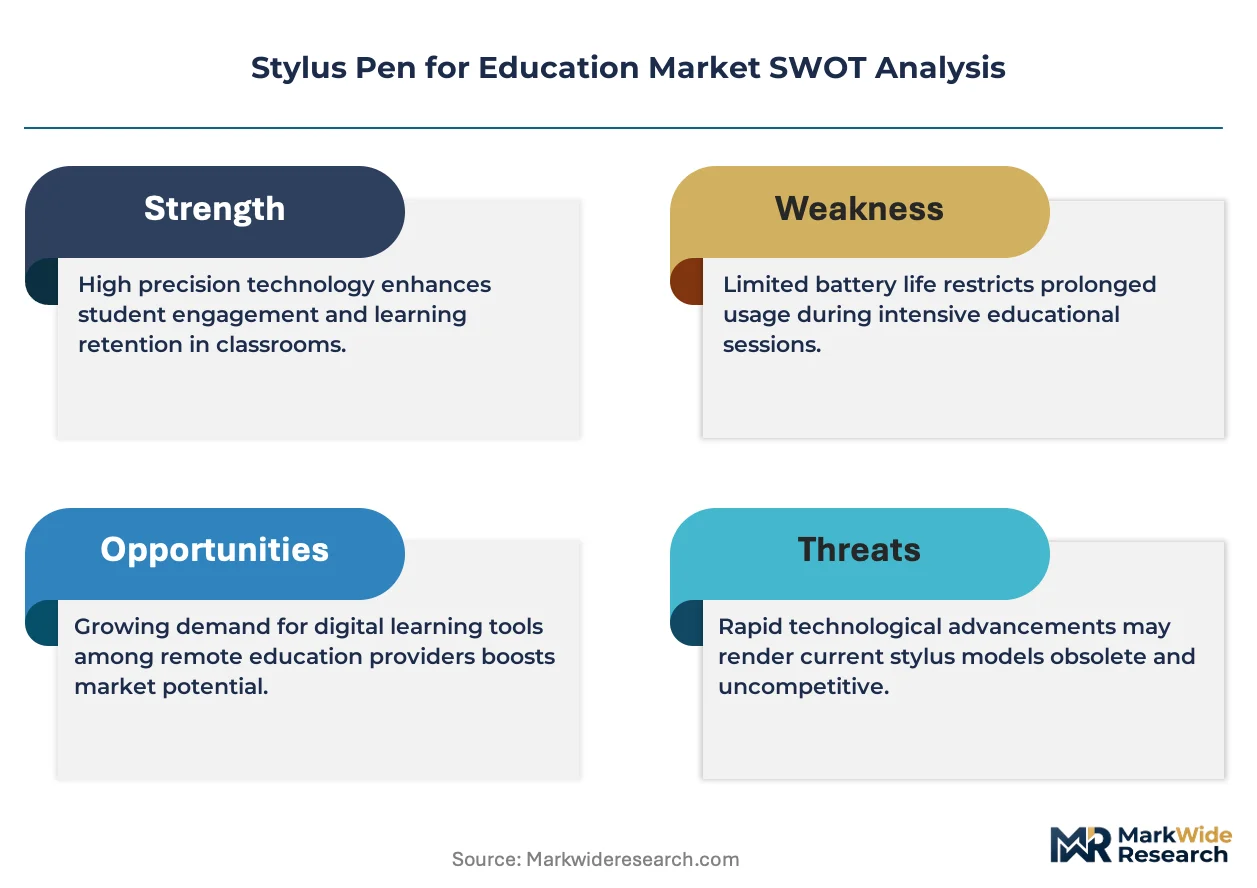
- Neodymium Magnet Supply Concentration:Active stylus assembly depends on rare-earth magnets sourced primarily from Chinese processing facilities, exposing manufacturers to export quota volatility.
- Passive Stylus Substitution:Cost-constrained primary schools in rural districts continue purchasing rubber-tipped capacitive alternatives that satisfy basic touch requirements at one-fifth the unit cost.
- GDPR Data Handling Complexity:Bluetooth-connected pens with onboard storage trigger strict European Union data localization requirements that extend certification timelines by 8-14 months.
Strategic Opportunities
- India Ed-Tech Hardware Gap:Central Board of Secondary Education digitization mandates outpace domestic stylus manufacturing capacity, creating import substitution openings for pressure-sensitive pen suppliers.
- Special Education Accessibility:United States Individuals with Disabilities Education Act compliance is driving demand for adaptive grip stylus designs with programmable shortcut buttons.
- Subscription Platform Integration:E-learning providers are bundling proprietary stylus hardware with annual software licenses, capturing recurring revenue streams that decouple from device replacement cycles.
Industry Challenges
- Firmware Synchronization Complexity:Multi-vendor tablet ecosystems require stylus manufacturers to maintain separate driver certification pipelines for iPadOS, ChromeOS, and Windows Ink platforms simultaneously.
- EMI Compliance Testing Bottlenecks:FCC Part 15 unintentional radiator testing for wireless stylus variants faces 16-22 week queue times at accredited laboratories, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stylus Pen for Education Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Stylus, Passive Stylus, Digital Pen, Graphic Tablet Pen End User: Students, Teachers, Educational Institutions, Online Learners Technology: Capacitive, Pressure Sensitive, Bluetooth Enabled, Optical Application: Note Taking, Digital Art, Annotations, E-Learning |
| Companies Covered | Samsung Electronics Co., Ltd., Huion Technology Corporation, Apple Inc., Adonit, Lenovo Group Limited, Microsoft Corporation, Logitech International S.A., XP-PEN Technology Co., Ltd., Wacom Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stylus Pen for Education Market Emerging Trajectories
Stylus hardware architecture is fragmenting into interoperable component layers that separate digitizer electronics from grip ergonomics and connectivity modules.
Active stylus digitizer chipsets are modularizing into discrete sub-assemblies that OEMs can license from specialized semiconductor foundries rather than designing in-house. K-12 hardware bundlers in Texas and California are adopting these reference designs to accelerate product cycles from 18 months to 9 months. This modularity is compressing R&D capital requirements for mid-tier educational suppliers and enabling faster feature parity with premium alternatives.
CE marking under EU RoHS and REACH directives is tightening hazardous substance thresholds for cadmium and lead content in stylus barrel plastics and circuit board solder joints. German educational procurement authorities now require third-party laboratory documentation verifying compliance with amended Annex XVII restrictions. Manufacturers serving European Union institutional channels are reformulating ABS polymer compounds and transitioning to tin-silver-copper solder alloys to maintain market access.
District-level purchasing committees are consolidating vendor relationships through cooperative procurement agreements that span 40-150 school systems simultaneously. These aggregated buying pools in Florida and Ohio are displacing individual school site-level purchasing autonomy and compressing supplier margins through volume-based pricing tiers. Hardware vendors are responding by dedicating specialized institutional sales teams to cooperative contract negotiation rather than traditional direct-to-school outreach.
Stylus Pen for Education Market Segmentation
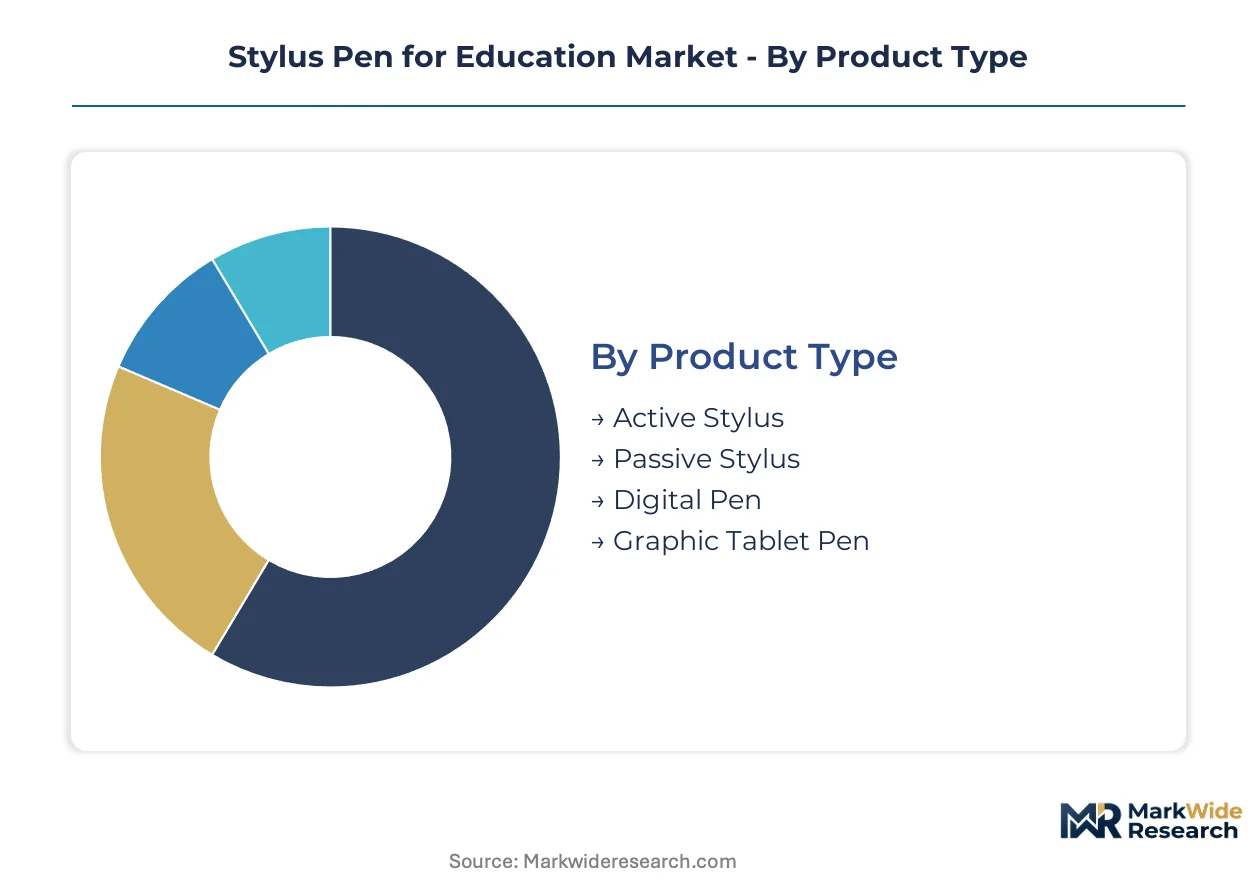
Stylus pen procurement patterns diverge sharply across education verticals, with certification requirements and ergonomic mandates reshaping how districts evaluate hardware tiers. Segmentation clarity enables vendors to align FCC authorization timelines with district funding cycles and curriculum specifications.
Product Type:
Active stylus variants carry the heaviest certification burden, requiring FCC Part 15 unintentional radiator testing and CE marking under EU RoHS and REACH directives, while passive alternatives face minimal regulatory overhead.
- Active Stylus:Electromagnetic digitizer technology with 4,096+ pressure sensitivity levels and palm-rejection algorithms. Demand concentrates in United States K-12 districts deploying ESSER III-funded 1:1 tablet programs where Bluetooth connectivity satisfies interactive hardware bundling requirements.
- Passive Stylus:Rubber-tipped capacitive conductors without internal electronics or power requirements. Rural primary schools in cost-constrained United States districts substitute these at one-fifth the unit cost, bypassing FCC equipment authorization entirely.
- Digital Pen:Self-contained handwriting capture devices with onboard storage and USB transfer capabilities.
- Graphic Tablet Pen:Pressure-sensitive electromagnetic pens designed for tethered use with dedicated digitizer tablets.
Active stylus sits at the top of the volume ranking, with graphic tablet pen climbing the fastest as secondary schools expand digital art curricula.
End User:
Procurement authority and volume scale vary dramatically across end-user tiers, with institutional buyers consolidating purchasing through cooperative agreements while individual learners drive replacement demand.
- Students:Individual purchasers in 1:1 device programs where districts mandate specific stylus compatibility with issued tablets.
- Teachers:Professional-grade hardware seekers requiring tilt recognition and low latency for interactive whiteboard instruction.
- Educational Institutions:Aggregated buyers spanning 40-150 school systems through cooperative procurement agreements in Florida and Ohio, compressing supplier margins through volume-based pricing tiers.
- Online Learners:Distributed purchasers in subscription-based e-learning platforms where hardware bundling deepens attachment rates to annual software licenses.
Educational institutions command the highest absolute volume, with online learners expanding most quickly as remote instruction normalizes.
Technology:
Technology selection determines regulatory pathway complexity, with wireless-enabled variants triggering FCC authorization queues while optical systems avoid electromagnetic compliance testing.
- Capacitive:Passive conductor technology relying on body capacitance to register touch events on tablet displays.
- Pressure Sensitive:Electromagnetic resonance systems measuring tip compression against a digitizer grid, essential for ISO 9241 ergonomic compliance in European procurement specifications.
- Bluetooth Enabled:Wireless active stylus variants with tilt recognition and programmable shortcut buttons, facing 16-22 week FCC Part 15 testing bottlenecks at accredited laboratories.
- Optical:Camera-based tracking systems using patterned paper or surface recognition, circumventing RF emissions testing requirements entirely.
Bluetooth enabled technology leads institutional procurement volume, with pressure sensitive systems gaining share fastest as ergonomic mandates tighten.
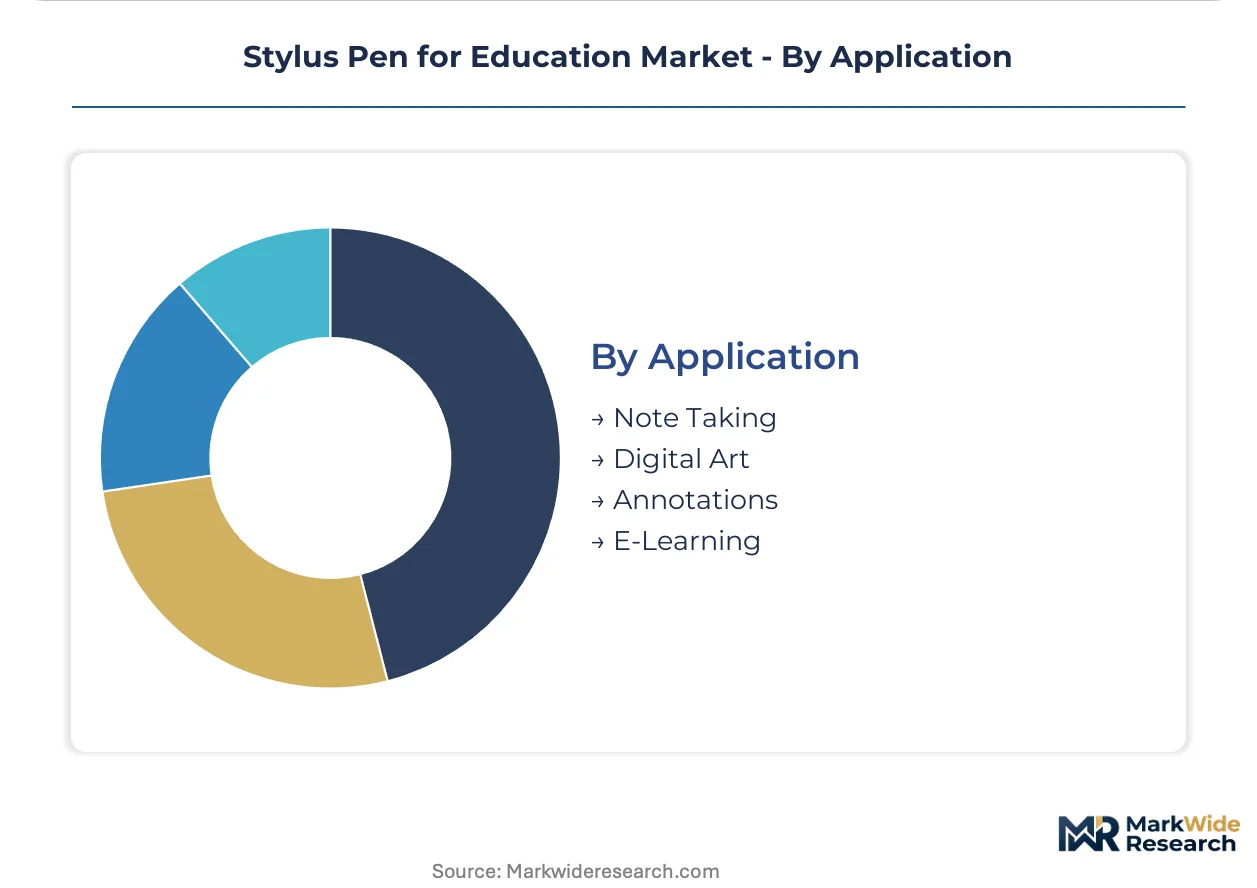
Application:
Application-specific requirements reshape hardware specifications, with digital art curricula demanding pressure sensitivity tiers that note-taking functions do not require.
- Note Taking:Core educational function driving baseline active stylus adoption in United States K-12 tablet programs, where palm-rejection algorithms prevent hand contact interference during extended writing sessions.
- Digital Art:Secondary school graphic design courses in Canada and Australia specify electromagnetic digitizer pens with 4,096+ pressure levels and tilt recognition, creating premium hardware demand.
- Annotations:Teacher-facing markup functions on shared documents and assessment materials.
- E-Learning:Platform-integrated consumption where subscription providers bundle proprietary stylus hardware with annual licenses, capturing recurring revenue streams.
Note taking dominates current volume, with e-learning climbing the fastest as platform integrations deepen hardware attachment rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting stylus pen assembly toward jurisdictions with streamlined electromagnetic compliance pathways, while procurement gravity concentrates in districts with concentrated federal ed-tech funding.
United States
ESSER III fund deployment drives 1:1 tablet program expansion across Texas and California school districts. FCC Part 15 equipment authorization governs Bluetooth-enabled active stylus imports, with 16-22 week testing queues at accredited laboratories. Austin and San Diego hardware bundlers are consolidating cooperative procurement agreements spanning 40-150 school systems simultaneously.
Germany
ISO 9241 ergonomic mandates reshape district-level purchasing specifications for extended student use. CE marking under EU RoHS and REACH directives enforces hazardous substance thresholds in barrel plastics and solder joints. Bavarian educational procurement authorities now require third-party laboratory documentation verifying amended Annex XVII restrictions.
China
Domestic rare-earth processing concentration supplies neodymium magnets essential for active stylus tip assemblies. MIIT electromagnetic compatibility standards govern wireless digitizer emissions for devices targeting institutional export channels. Shenzhen and Dongguan electronics clusters host modular chipset foundries licensing reference designs to mid-tier educational suppliers.
India
Central Board of Secondary Education digitization mandates outpace domestic stylus manufacturing capacity, creating import substitution openings. BIS certification requirements for electronic learning devices extend product registration timelines for foreign suppliers. Karnataka and Telangana ed-tech hardware assembly corridors are attracting contract manufacturers seeking tariff-advantaged production bases.
Canada
Secondary school digital art curricula expansion specifies electromagnetic digitizer pens with 4,096+ pressure sensitivity levels. Health Canada regulates Bluetooth radio frequency emissions under Innovation, Science and Economic Development certification pathways. Ontario and British Columbia school districts are integrating graphic design courses that drive premium hardware procurement.
Stylus Pen for Education Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with ecosystem-integrated technology companies commanding institutional procurement channels while modular component suppliers capture mid-tier educational bundlers. Market structure tilts toward consolidated premium tiers and fragmented entry-level supply, with three archetypes dominating: vertically integrated platform owners, specialized digitizer technology licensors, and price-performance focused hardware assemblers. M&A activity concentrates on chipset module acquisitions, while strategic partnerships between stylus vendors and tablet OEMs lock in compatibility certification pipelines.
Within the platform-integrated tier, Apple Inc. and Microsoft Corporation exemplify ecosystem lock-in strategies that sustain premium positioning across institutional channels. Samsung Electronics Co., Ltd. occupies a position bridging consumer electronics scale with education-specific hardware bundling. XP-PEN Technology Co., Ltd. and Huion Technology Corporation represent the price-performance archetype, competing aggressively on entry-level educational bundle ratios.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Huion Technology Corporation |
| Apple Inc. |
| Adonit |
| Lenovo Group Limited |
| Microsoft Corporation |
| Logitech International S.A. |
| XP-PEN Technology Co., Ltd. |
| Wacom Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Neodymium magnet costs originating from Chinese rare-earth processing facilities cascade through active stylus assembly tiers, compressing margins for electromagnetic digitizer pen manufacturers while amplifying pricing power for vertically integrated suppliers serving United States K-12 ESSER III procurement channels.
Pricing Analysis
Distributor margins for educational hardware bundlers absorb the steepest compression as cooperative procurement agreements spanning 40-150 school systems consolidate purchasing power. Three-tier pricing structure across premium, standard, and economy levels separates Apple ecosystem-locked offerings from Wacom pressure-sensitive alternatives and XP-PEN entry-level bundles. Cost compression in the passive stylus tier intensifies because rural primary schools substitute rubber-tipped capacitive alternatives at one-fifth the unit cost. Online learners in subscription-based e-learning platforms exhibit lowest price sensitivity due to hardware-software bundling, while cost-constrained rural districts display highest sensitivity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Texas and California hardware bundlers consolidating cooperative procurement agreements. Active stylus assembly draws from Chinese rare-earth processing for neodymium magnets, Taiwanese semiconductor foundries for digitizer chipsets, and Malaysian electronics corridors for final assembly. Single-source vulnerability concentrates in Chinese neodymium magnet supply where export quota volatility exposes manufacturers to input disruption. Distribution runs through institutional sales teams negotiating cooperative contracts rather than traditional direct-to-school outreach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where FCC Part 15 testing bottlenecks in United States laboratories create 16-22 week certification delays that European suppliers with CE marking precedence can exploit for competitive timing.
For Market Incumbents: To counter passive stylus substitution in cost-constrained rural districts, Apple and Microsoft should deepen ecosystem lock-in through proprietary stylus-tablet bundling while Wacom expands pressure-sensitive graphic tablet pen capacity in tariff-advantaged Indian assembly corridors. Certification investment in ISO 9241 ergonomic compliance maintains premium positioning against XP-PEN price competition.
For New Entrants and Emerging Players: Capture the India ed-tech hardware gap where Central Board of Secondary Education digitization mandates outpace domestic manufacturing capacity. Special education accessibility under United States Individuals with Disabilities Education Act represents the most penetrable segment, with adaptive grip designs offering programmable shortcut buttons as the specific go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where modular chipset foundries license reference designs that compress R&D capital requirements for mid-tier educational suppliers. Long-term viability centers on acquisition of specialized digitizer technology licensors with FCC certification pipelines locked across iPadOS, ChromeOS, and Windows Ink platforms simultaneously. Monitor EMI compliance testing queue times at accredited laboratories as the inflection indicator for product launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Chipset Licensing | Reference designs from Shenzhen foundries compress R&D cycles from 18 months to 9 months for mid-tier suppliers. |
| Cooperative Procurement Specialization | Dedicated institutional sales teams secure volume-based pricing tiers across 40-150 school system agreements. |
| Ergonomic Certification Investment | ISO 9241 compliance opens European procurement specifications requiring palm-rejection algorithms. |
| Subscription Platform Integration | Hardware bundling with annual software licenses captures recurring revenue decoupled from device replacement. |
| Adaptive Grip Design Development | Programmable shortcut buttons address United States special education accessibility mandates under IDEA. |
Methodological Framework
Direct dialogue with hardware procurement officers at United States school districts, digitizer technology licensors in Shenzhen electronics clusters, educational software platform engineers, and FCC compliance consultants grounded qualitative findings. Secondary validation drew from FCC equipment authorization filings, ESSER III fund deployment disclosures, ISO 9241 ergonomic standard documentation, and CE marking RoHS/REACH directive amendments. Bottom-up demand modeling triangulated against top-down market sizing across product type, end user, technology, and application dimensions.
Bottom-up analysis segmented volume and value outputs by active versus passive stylus variants, student versus institutional procurement authority, Bluetooth-enabled versus pressure-sensitive technology, and note-taking versus digital art applications across the projection horizon. CAGRs derived from enrollment-driven device penetration curves, federal funding cycle phasing, and curriculum digitization mandates. Forecast inputs included cooperative procurement agreement consolidation rates and modular chipset adoption timelines.
Neodymium export quota volatility, FCC testing queue elongation, and GDPR data localization requirement expansion are the dominant revision risks that could compress or extend growth trajectories. Forecasts reflect documented assumptions regarding ESSER fund deployment schedules and curriculum standard adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Continuous Delivery Market
Digital Solutions
Data Integration Market
Digital Solutions
Global Competitive Intelligence Tools Market
Digital Solutions
North America Data Virtualization Market
Digital Solutions
Smart Government Market
Digital Solutions
Voice Picking Headset Market
Digital Solutions
Transit Station Display Board Market
Digital Solutions
Foot Traffic and Customer Location Intelligence Solution Market
Digital Solutions
Computerized Maintenance Management System Market
Digital Solutions
Global Data Catalog Market
Digital Solutions
Global Data Virtualization Market
Digital Solutions
South Africa Digital Twin Market
Digital Solutions
GCC and Africa ICT Market
Digital Solutions
Digital Signage Systems Market
Digital Solutions
Warehouse Management System (WMS) Market
Digital Solutions
Digital BSS Market