
 Data Converter Market | 2026-2036
Data Converter Market Size, Share, and Industry Trends Forecast 2026-2036
Data Converter Market Intelligence
The European Union's RoHS directive, which restricts hazardous substances in electronic equipment, is hardening design requirements for data converter components. Texas Instruments, Inc. leverages its extensive portfolio to serve diverse end-markets from industrial to automotive. Analog Devices, Inc. specializes in high-performance signal processing solutions for critical applications. Infineon Technologies AG competes on its system-level expertise in power management and sensor integration.
A data converter is a semiconductor device that translates real-world analog signals into a digital format or converts digital data back into analog signals. These components are defined by key performance metrics such as resolution in bits, sampling rate, and overall power consumption. Analog-to-Digital Converters represent the largest product type, critical for interfacing with sensors. The telecommunication equipment application shows significant uptake, linked to the deployment of advanced wireless infrastructure.
Compliance with standards from the FCC in the United States for electromagnetic interference and China's GB standards is mandatory for market access. Additionally, ISO 9001 certification is a baseline quality requirement for suppliers engaging with major OEMs. Component selection for design engineers will increasingly balance performance specifications against power efficiency and thermal management constraints.
Market Dynamics
The expansion of 5G wireless infrastructure is the central force shaping the data converter market, compelling higher performance specifications for sampling rates and resolution to manage massive data throughput in base stations. This defines component development roadmaps across the industry.
Growth Catalysts
- 5G Infrastructure Deployment:The rollout of 5G base stations, particularly in China and South Korea, requires high-speed data converters for signal processing, directly stimulating component demand from telecommunication equipment manufacturers.
- Automotive Electrification:Government mandates promoting electric vehicles and advanced driver-assistance systems in Europe and North America increase the need for data converters in battery management systems and sensor fusion applications.
- Industrial Automation:The adoption of smart factories and IoT devices in industrial settings, especially within Germany's manufacturing sector, relies on analog-to-digital converters for interfacing with a multitude of sensors and actuators.
Market Restraints
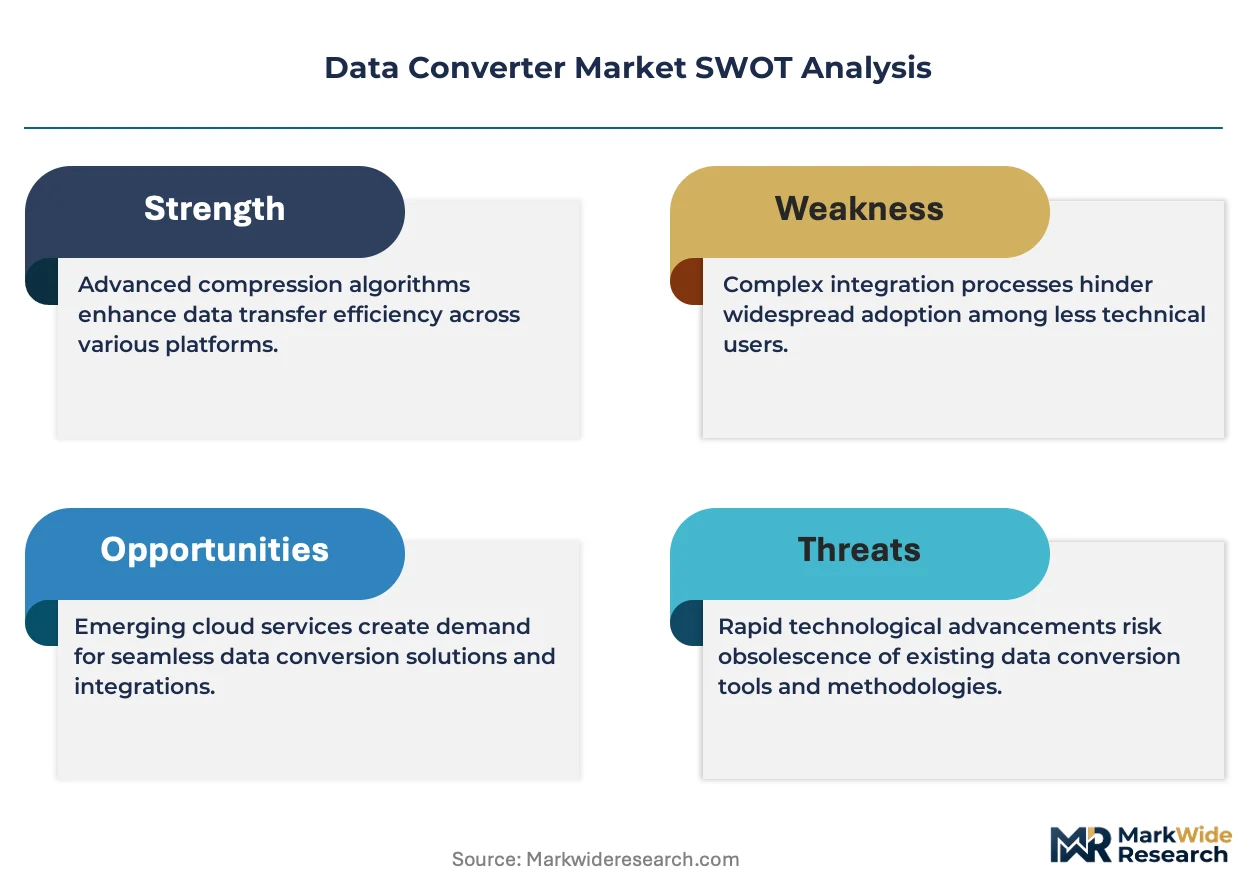
- Power Consumption Constraints:High-speed, high-resolution converters generate significant heat, creating thermal management challenges in densely packed electronic systems like 5G active antenna units, which limits performance scaling.
- Substrate Material Scarcity:The supply of specialized semiconductor substrates, concentrated in a few facilities in Taiwan and Japan, creates vulnerability to disruptions, impacting lead times and production volumes for all manufacturers.
- Stringent EMI Standards:Compliance with electromagnetic interference standards from the FCC in the United States and similar bodies in Europe imposes complex and costly design-for-compliance cycles, delaying product launches.
Strategic Opportunities
- Medical Wearables and Diagnostics:The shift toward remote patient monitoring and point-of-care diagnostics presents an opportunity for low-power, high-precision converters for use in portable medical devices and biosensors.
- EU RoHS Directive Evolution:Upcoming revisions to the EU's RoHS directive create an opportunity for suppliers specializing in converters designed with compliant materials, offering a competitive advantage in the European market.
- Integration with AI Accelerators:Co-packaging data converters with edge AI processing units for applications like smart cameras and autonomous drones offers a path to higher system-level performance and reduced latency.
Industry Challenges
- Mixed-Signal Design Expertise Shortage:A scarcity of engineers with deep expertise in high-frequency mixed-signal IC design is a critical bottleneck, slowing down the development of next-generation data converter architectures.
- System-on-Chip Integration:Integrating high-performance analog data converters onto large digital SoCs without performance degradation from noise and crosstalk remains a significant technical and layout challenge for designers.
- Interoperability Standard Gaps:The lack of fully ratified interoperability standards for emerging high-speed interfaces slows down ecosystem development and creates design uncertainty for both component suppliers and system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Converter Market |
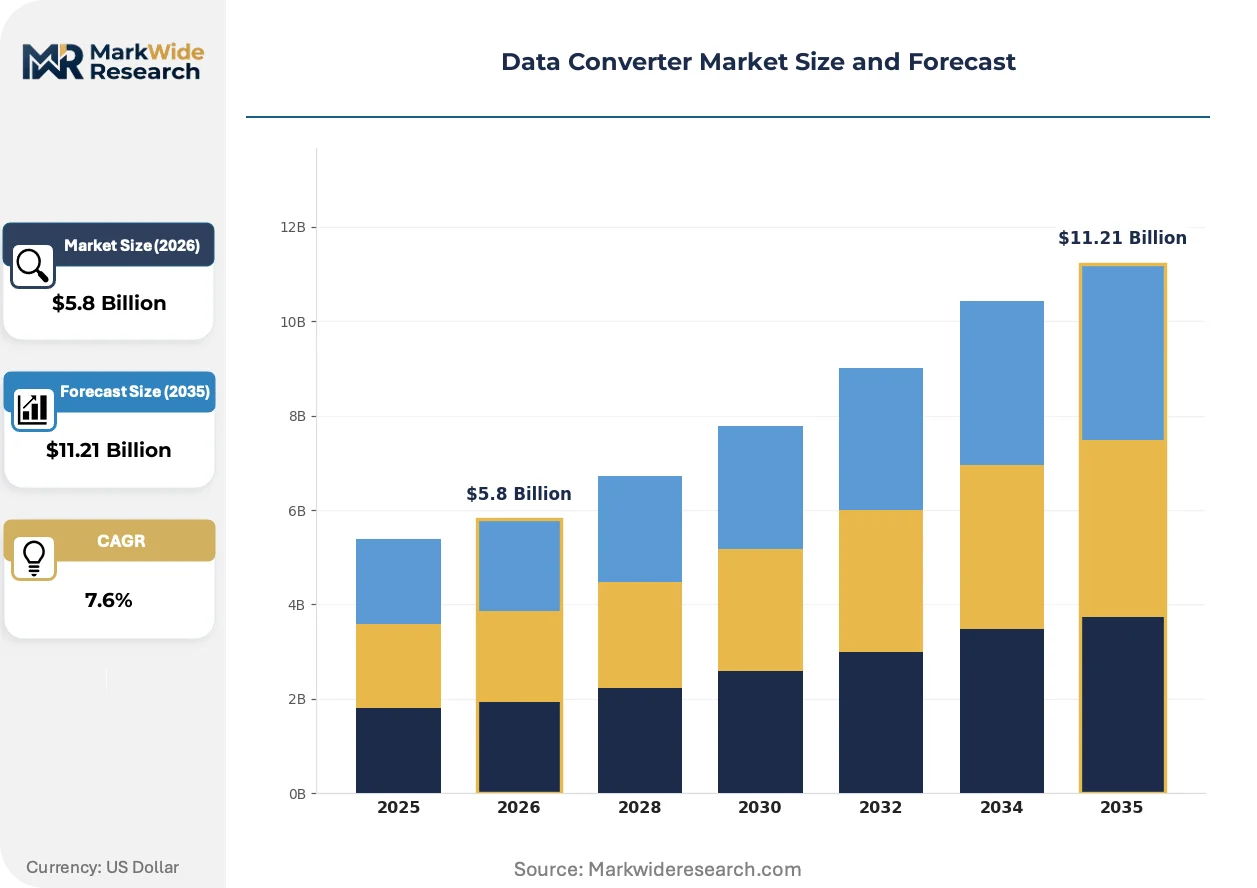
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.21 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog-to-Digital Converter, Digital-to-Analog Converter, Mixed-Signal Converter, Delta-Sigma Converter, Pipeline Converter Technology: Flash, Successive Approximation Register, Sigma-Delta, Folding, Interpolating Application: Telecommunication Equipment, Consumer Electronics, Industrial Control, Instrumentation, Aerospace Systems End User: OEMs, System Integrators, Electronics Manufacturers, Research Laboratories, Defense Contractors |
| Companies Covered | Analog Devices, Inc., Texas Instruments, Inc., Skyworks Solutions, Inc., Infineon Technologies AG, Microchip Technology Incorporated, NXP Semiconductors N.V., STMicroelectronics, Renesas Electronics Corporation, ON Semiconductor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Converter Market Strategic Shifts & Innovations
The dominant trend is the push for higher levels of integration, where data converters are no longer discrete components but are embedded within larger systems-on-a-chip. This shift prioritizes power efficiency and smaller form factors over standalone performance in some applications.
Gallium Nitride (GaN) technology, known for its high power efficiency and switching speeds, is being used in power supply designs for data converter systems. Telecom infrastructure and industrial motor drive manufacturers are adopting GaN to reduce system size and energy loss. This focus on power system efficiency is converging with the signal chain design itself, as optimized power delivery becomes inseparable from achieving high-speed data conversion performance.
China's GB standards for electronic equipment mandate strict limits on electromagnetic emissions and power consumption, influencing component selection for all products sold in the country. This is forcing semiconductor suppliers to design data converters that meet specific regional performance and efficiency profiles, rather than a single global specification. The telecommunication and consumer electronics segments are most affected, requiring design modifications and rigorous testing to secure market access.
Design engineers are increasingly prioritizing system-level integration and pre-validated reference designs over evaluating discrete data converters based on datasheet specifications alone. This trend challenges the traditional component sales model, favoring suppliers who offer comprehensive development kits, software drivers, and application support. This shift is most prominent in the competitive industrial automation and automotive sectors, where time-to-market is a critical factor for OEMs.
Data Converter Market Segmentation
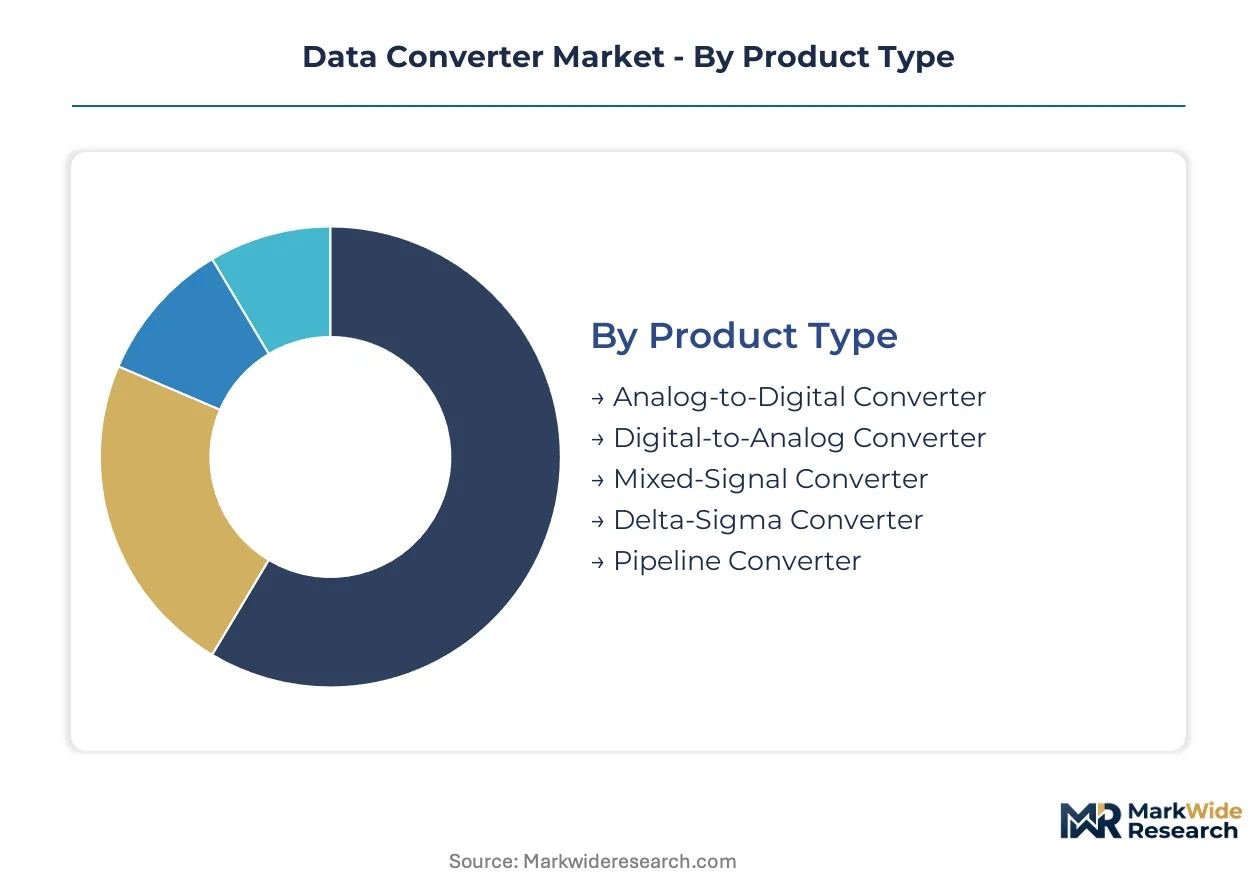
Segmentation provides a critical framework for understanding the diverse requirements and purchasing behaviors within the data converter market. Differentiation across product types, underlying technologies, and target applications directly influences component design and supply chain strategies. End-user segments exhibit distinct procurement cycles and performance priorities, shaping overall market dynamics.
Product Type:
Buyer decisions for data converters fundamentally hinge on the specific signal processing needs of their target system.
- Analog-to-Digital Converter:These devices translate continuous analog signals from the real world into discrete digital data, essential for sensor-based systems. Demand concentrates heavily in telecommunication equipment for 5G base stations, driven by the need to digitize high-frequency radio signals.
- Digital-to-Analog Converter:This product type converts digital data back into analog electrical signals, crucial for driving actuators and displaying visual information. Automotive electrification in Europe and North America significantly drives demand for DACs in motor control and infotainment systems.
- Mixed-Signal Converter:These components integrate both analog and digital functions on a single chip, offering space and power efficiency.
- Delta-Sigma Converter:Known for high resolution and noise shaping, these converters are prevalent in precision measurement and audio applications.
- Pipeline Converter:Offering a balance of speed and resolution, pipeline converters are frequently used in high-speed data acquisition and imaging.
Volume sits with Analog-to-Digital Converters; growth tilts toward Digital-to-Analog Converters due to expanding automotive and industrial needs.
Technology:
The choice of data converter technology directly impacts performance metrics such as speed, resolution, and power consumption.
- Sigma-Delta:These converters achieve high resolution through oversampling and noise shaping, making them suitable for audio, industrial sensors, and medical diagnostic equipment. Deployment in remote patient monitoring devices for medical wearables in Europe drives significant demand for power-efficient solutions.
- Successive Approximation Register:SAR converters offer a good balance of speed and power efficiency, widely adopted in battery-powered devices and industrial control systems. Their compact size and moderate power consumption are critical for IoT devices in Germany's smart factories.
- Flash:Flash converters provide the fastest conversion speeds but consume high power, primarily used in radar and high-frequency communication.
- Folding:This technology reduces the number of comparators compared to flash converters, balancing speed with reduced power consumption.
- Interpolating:Interpolating converters optimize folding architectures for higher speeds and lower power, finding use in advanced imaging applications.
Design complexity varies significantly across these technologies, impacting integration costs and time-to-market for system developers.
Application:
Diverse application requirements dictate the specific performance envelope for data converters, ranging from high-speed to ultra-low power.
- Telecommunication Equipment:This segment demands high-speed, high-resolution data converters for processing massive data throughput in 5G base stations and wireless infrastructure. China and South Korea's aggressive 5G rollouts are the primary drivers for component demand in this sector.
- Industrial Control:Data converters are essential in smart factories and IoT devices for interfacing with a multitude of sensors and actuators, enabling precise process automation. Germany's manufacturing sector relies heavily on these components for advanced robotics and predictive maintenance systems.
- Consumer Electronics:These applications require cost-effective, low-power data converters for smartphones, smart home devices, and wearable technology.
- Instrumentation:High-precision data converters are critical for test and measurement equipment, medical imaging, and scientific research.
- Aerospace Systems:This sector utilizes radiation-hardened, high-reliability data converters for avionics, satellite communication, and defense electronics.
The demand footprint for data converters is expanding across industrial sectors, while telecommunications drives high-performance requirements globally.
End User:
End-user procurement strategies for data converters are shaped by internal design capabilities, integration complexity, and supply chain stability.
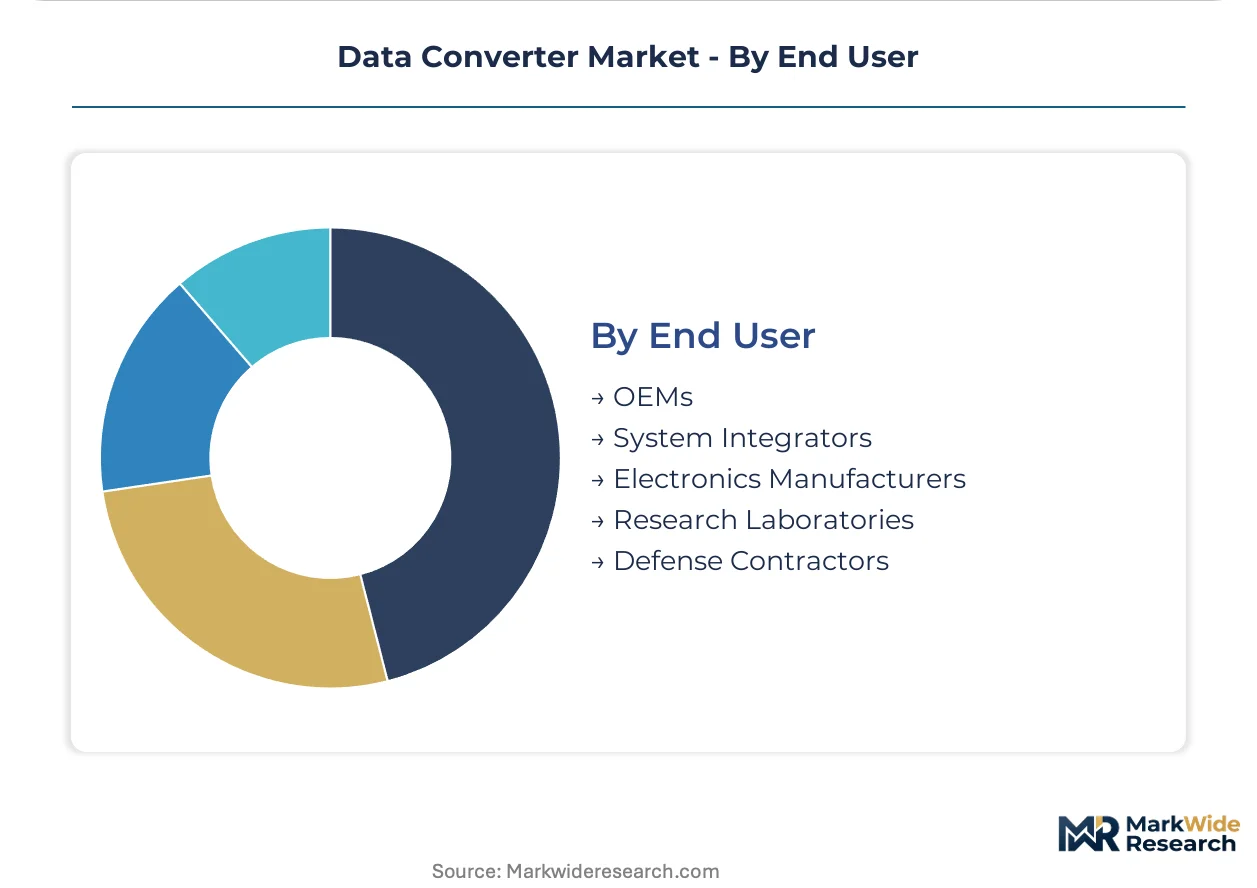
- OEMs:Original Equipment Manufacturers integrate data converters into their final products, prioritizing long-term supply agreements and comprehensive technical support from component suppliers. Major automotive OEMs in Europe require robust, automotive-grade converters for their advanced driver-assistance systems.
- Electronics Manufacturers:These entities, including Contract Manufacturers and Original Design Manufacturers, purchase data converters for assembly into modules or sub-systems for various industries. Asian electronics manufacturing hubs in China and Taiwan represent significant demand for high-volume, cost-optimized components.
- System Integrators:These companies combine various components to create complete solutions, requiring flexible data converter options with strong interoperability.
- Research Laboratories:Academic and corporate research institutions require specialized, high-performance data converters for prototyping and scientific experiments.
- Defense Contractors:This segment demands highly reliable, often custom-designed data converters for military communication, radar, and electronic warfare.
Procurement strategies for data converters are evolving, with major OEMs seeking long-term supply agreements and technical support from suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's advanced manufacturing sector drives demand for high-performance data converters. This city-state's focus on precision engineering and IoT applications fuels the need for sophisticated analog-to-digital and digital-to-analog solutions. The region's strategic location also supports global supply chains for these critical components.
China
5G infrastructure deployment and consumer electronics manufacturing drive substantial demand for data converters. China's GB standards mandate strict performance and emission limits for electronic equipment. The Yangtze River Delta region, particularly Shanghai, is a major hub for semiconductor design and production, attracting significant investment in data converter technology.
United States
The aerospace, defense, and high-performance computing sectors require advanced data converters for critical applications. The FCC's electromagnetic interference standards influence component design and certification processes. Silicon Valley, California, remains a focal point for mixed-signal IC design innovation and product development.
Germany
Industrial automation and automotive electrification projects create strong demand for robust data converters in sensor fusion and motor control. Germany's KBA regulations for automotive electronics ensure high reliability and safety standards. Bavaria's industrial clusters, including Munich, specialize in advanced manufacturing and automotive technology integration.
South Korea
The country's aggressive 5G rollout and leadership in consumer electronics manufacturing necessitate high-speed, high-resolution data converters. South Korea's national standards body sets benchmarks for telecommunication equipment performance. The Seoul Capital Area hosts major electronics manufacturers and semiconductor R&D centers, driving component innovation.
Taiwan
Taiwan's robust semiconductor ecosystem, particularly in foundry services, supports the production of diverse data converter types. The country's industrial policies promote advanced manufacturing and export-oriented electronics. Hsinchu Science Park is a global center for semiconductor fabrication and design, including specialized data converter foundries.
Data Converter Market Key Industry Players
Premium-margin players sit above commodity-margin players across design complexity and performance specifications. The data converter market exhibits a tiered structure, with specialized firms focusing on high-performance applications and larger conglomerates addressing broader industrial needs. Strategic archetypes include integrated device manufacturers, fabless semiconductor companies, and intellectual property providers. Portfolio diversification and strategic partnerships are dominant competitive moves among market participants.
Integrated device manufacturers like Analog Devices, Inc. and Texas Instruments, Inc. exemplify the premium-tier vector, leveraging extensive portfolios and deep technical expertise across diverse end-markets. These companies offer comprehensive solutions for high-performance signal processing and critical applications, anchoring significant market share. NXP Semiconductors N.V., a Dutch-based company, occupies a strong position within the automotive and industrial sectors, reflecting a strategy of focused application leadership and system-level integration. These firms maintain broad product offerings and global distribution networks, supporting complex system designs across various industries. Their market presence is defined by continuous innovation in mixed-signal design.
| Leading Market Players |
|---|
| Analog Devices, Inc. |
| Texas Instruments, Inc. |
| Skyworks Solutions, Inc. |
| Infineon Technologies AG |
| Microchip Technology Incorporated |
| NXP Semiconductors N.V. |
| STMicroelectronics |
| Renesas Electronics Corporation |
| ON Semiconductor Corporation |
| Others |
Cost & Logistics Intelligence
Telecommunication OEMs, particularly those serving 5G infrastructure, drive demand for data converters under long-term supply agreements. This contract-based pricing model prioritizes supply stability and technical support over spot market fluctuations.
Pricing Analysis
Outcome-based pricing, tied to resolution and sampling rate, anchors data converter valuation. Component prices differentiate based on ISO 9001 certification, automotive-grade qualifications, and volume scale, often within a contract-based framework for OEMs. Pricing softness stems from intense competition within the high-volume consumer electronics segment. Aerospace and defense contractors exhibit the lowest price sensitivity, prioritizing reliability and specialized performance.
Supply Chain Analysis
Regional distribution centers and specialized logistics hubs manage the global flow of data converter components. Supply concentrates heavily in Taiwan for foundry services, South Korea for advanced packaging, and Japan for specialized substrates. The industry relies on critical inputs like high-purity silicon and gallium nitride materials. Single-source vulnerability for advanced semiconductor substrates poses a significant structural risk. Distribution runs through direct channels for major OEMs and a network of distributors for smaller system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The data converter market is undergoing a significant technology transition, with System-on-Chip (SoC) integration displacing many standalone converter ICs. This shift demands new strategies for component suppliers and system designers alike.
For Market Incumbents: Acquire mixed-signal design expertise through targeted M&A to counter the critical talent shortage. Incumbents should invest heavily in advanced packaging technologies for seamless co-integration with edge AI processing units. This defends against emerging competitors leveraging system-level integration and mitigates the threat of skill scarcity slowing innovation. Deepening vertical integration into specialized foundry processes also secures critical supply.
For New Entrants and Emerging Players: The price-point gap between premium performance and commodity converters creates opportunities for new entrants. Focus on low-power, high-precision solutions for medical wearables and cost-optimized options for industrial IoT devices. These segments offer penetrable white space, especially in Europe's remote patient monitoring market. Go-to-market strategies should emphasize comprehensive development kits and application-specific reference designs to reduce OEM time-to-market.
For Investors and Strategic Acquirers: The window for entry favors nimble specialists with strong intellectual property in mixed-signal design or GaN power solutions. Long-term viability over the next decade hinges on companies demonstrating expertise in system-level integration and thermal management. Target fabless semiconductor companies with proven track records in high-performance analog-to-digital or digital-to-analog conversion. Increased patent activity in co-packaged analog/digital solutions serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire Mixed-Signal IP Firm | Secures scarce high-frequency design talent, accelerating next-generation data converter development for 5G base stations. |
| Invest in GaN Power Integration | Reduces power consumption and system size, critical for active antenna units in telecommunication equipment. |
| Develop Comprehensive Reference Designs | Lowers time-to-market for OEMs in industrial automation and automotive electrification projects. |
| Expand Low-Power Converter Portfolio | Addresses the growing demand from medical wearables and portable diagnostic devices in Europe. |
| Strengthen Supply Chain Resiliency | Mitigates single-source vulnerability for specialized semiconductor substrates from Taiwan and Japan. |
Research Approach
Document review covered company annual reports, investor presentations, and technical whitepapers, complemented by interviews with industry stakeholders. Primary research included conversations with design engineers, procurement managers at major OEMs, and product line managers from semiconductor firms. Secondary validation drew from FCC filings, EU RoHS directives, China GB standards, and patent databases. This approach ensured bottom-up market sizing and top-down validation.
Historical market data was cross-referenced with expert panel input to establish the forecast framework across the analysis window. Quantitative models projected market growth across product type, technology, application, end-user, and regional regulatory compliance. Compound annual growth rates derived from regression analysis incorporated 5G base station deployment rates and electric vehicle production forecasts. These inputs informed all future projections.
Inputs from public financial disclosures and regulatory databases were available through the study window; gaps in proprietary OEM production plans introduce uncertainty bands. Forecasts reflect these assumptions, acknowledging that geopolitical events impacting substrate supply or rapid shifts in telecommunication standards could revise projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Spain Digital Twin Market
Digital Solutions
Online Home Service Market
Digital Solutions
Part-Time Job Platform Market
Digital Solutions
Smart and Mobile Supply Chain Solutions Market
Digital Solutions
Asia-Pacific Smart Government Market
Digital Solutions
Database Management Platform Market
Digital Solutions
Global Client Virtualization Market
Digital Solutions
Session Replay Software Market
Digital Solutions
Parking Management Systems Market
Digital Solutions
India Digital Twin Market
Digital Solutions
Smart Recording Pen Market
Digital Solutions
Workflow Content Automation (WCA) Market
Digital Solutions
United Kingdom ICT Market
Digital Solutions
US Digital Market
Digital Solutions
Healthcare Video Conferencing Solutions Market
Digital Solutions
Tablet Based E-Detailing Market