
 Global IC Card/Smart Card Market | 2026-2036
Global IC Card/Smart Card Market Size, Share, and Industry Trends Forecast 2026-2036
Global IC Card/Smart Card Market Outlook
Dual-interface chip architecture is fragmenting legacy single-protocol supply chains as issuers demand cards that operate across both contact POS terminals and contactless readers. NXP Semiconductors leverages its secure-element portfolio to anchor European banking certifications. Infineon Technologies sustains manufacturing scale through captive fabs in Germany and Austria. IDEMIA competes on government credential contracts spanning national ID and e-passport programs.
An IC card or smart card embeds a microprocessor or memory chip within a plastic substrate, typically conforming to ISO/IEC 7816 physical and electrical specifications, enabling encrypted data storage and secure transaction authentication for financial, identity, and access applications. Contactless cards lead volume shipments in transit and payment verticals where speed-of-transaction dominates procurement criteria. Microprocessor-based technology captures premium pricing in government and financial services deployments requiring multi-application sandboxing. RFID-enabled smart tags represent the fastest-growing product category as industrial asset-tracking programs replace barcode systems.
FCC Part 15 regulations in the United States govern NFC emission standards, while ETSI and CE marking frameworks in Europe mandate interoperability and security benchmarks for cross-border payment acceptance. India's BIS certification and China's GB/T standards create country-specific compliance layers that foreign suppliers must navigate for market access. Stakeholders must monitor whether regional encryption export controls fragment chip sourcing strategies or consolidate procurement around domestically licensed foundries.
Market Dynamics
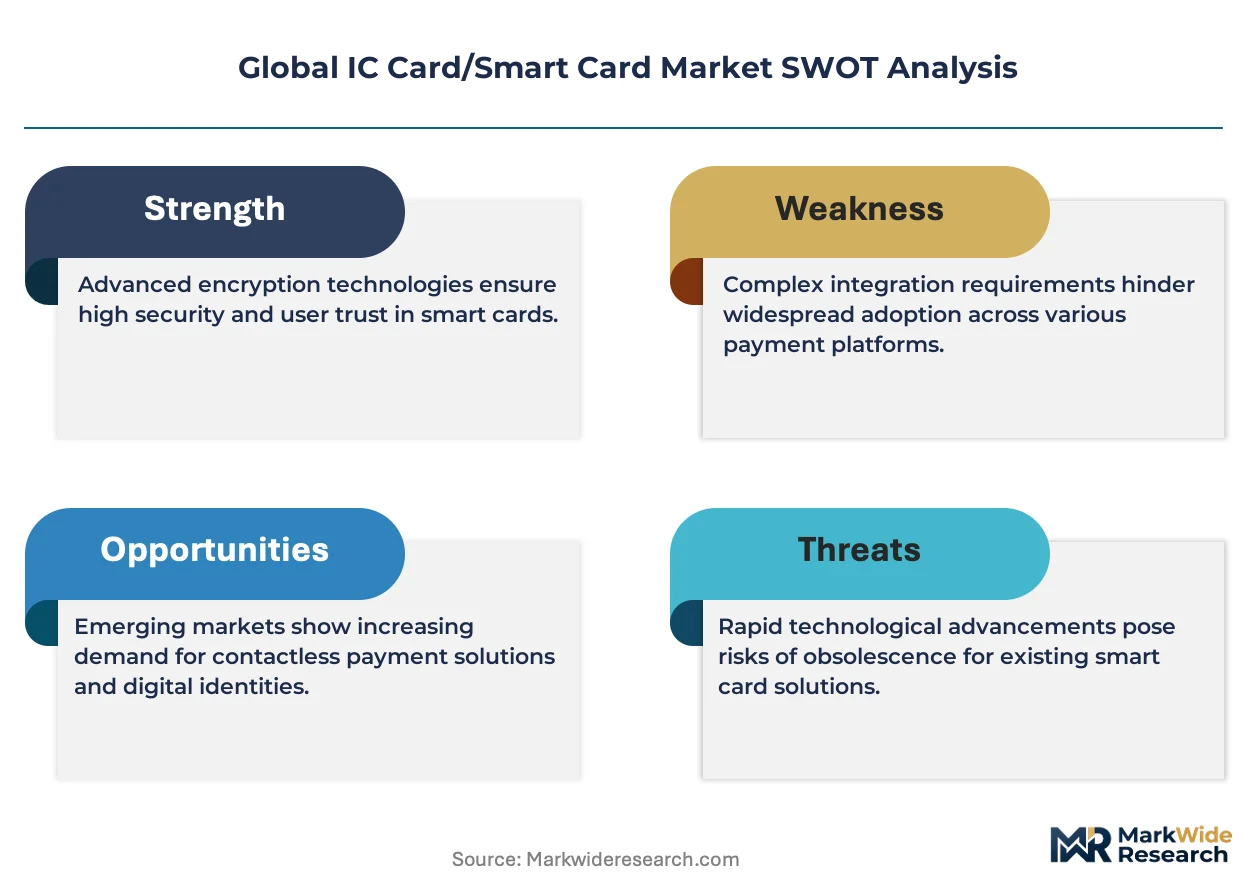
Dual-interface chip migration is fragmenting legacy single-protocol supply chains as issuers demand unified contact and contactless operation, forcing foundries to retool for heterogeneous die architectures.
Growth Catalysts
- EMV Compliance Mandates:PCI-DSS and EMVCo certification requirements in the United States and European Union are compelling card issuers to replace magnetic-stripe portfolios, sustaining replacement-cycle demand.
- Transit Authority Modernization:Urban rail operators in China, Germany, and Brazil are deploying open-loop payment acceptance, requiring contactless card issuance at municipal scale.
- NFC Handset Proliferation:Mobile wallet activation on smartphones is conditioning consumer familiarity with tap-to-pay behavior, reinforcing card-based contactless adoption in retail banking.
Market Restraints
- Silicon Wafer Cost Volatility:300mm wafer pricing fluctuations at foundries in Taiwan and South Korea compress gross margins for secure-element manufacturers.
- Domestic Licensing Requirements:China's GB/T cryptographic standards and SAMR certification create non-tariff barriers that fragment chip sourcing strategies for foreign suppliers.
- Mobile Wallet Substitution:Tokenized smartphone payments embedded in iOS and Android ecosystems threaten physical card volume in premium consumer segments.
Strategic Opportunities
- Industrial Asset-Tracking Expansion:RFID-enabled smart tags are replacing barcode systems in German automotive and Japanese electronics supply chains, opening high-volume industrial contracts.
- India's Digital Identity Stack:The UIDAI Aadhaar program and RBI's push for tokenized card payments create demand for dual-interface credentials in financial inclusion programs.
- Post-Quantum Cryptography Migration:NIST's algorithm standardization timeline is prompting early design wins for quantum-resistant secure elements in government and defense applications.
Industry Challenges
- Certification Timeline Compression:EMVCo and Common Criteria evaluation periods extend 12-18 months, delaying product launches and freezing engineering resources.
- Legacy System Integration Friction:Banks in the United States and Italy face middleware complexity when retrofitting core banking platforms for dual-interface transaction routing.
- Secure-Element Talent Scarcity:Specialized expertise in side-channel attack resistance and fault-injection countermeasures concentrates at a handful of European and Israeli design houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IC Card/Smart Card Market |
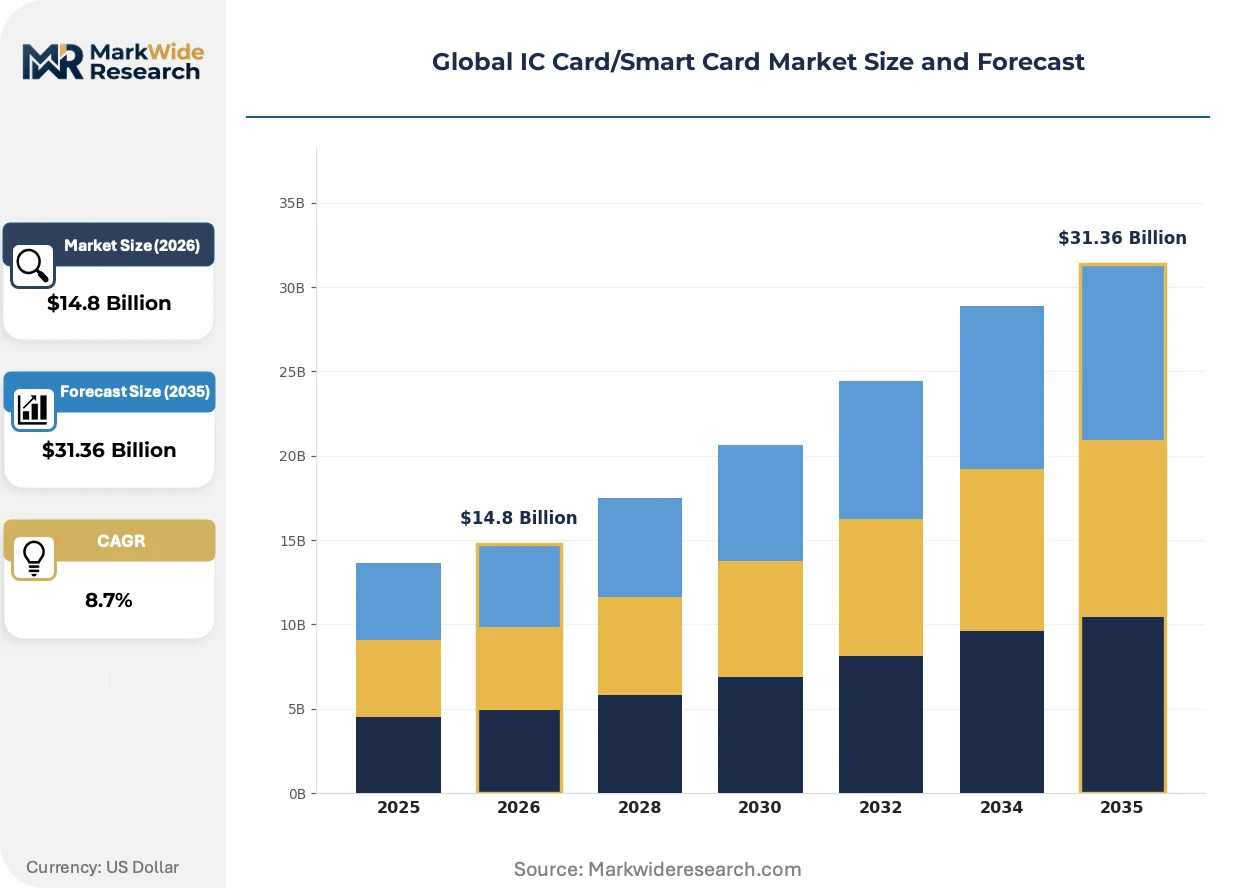
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Cards, Contactless Cards, Dual-Interface Cards, Smart Tags Application: Banking, Transportation, Access Control, Loyalty Programs Technology: RFID, NFC, Magnetic Stripe, Microprocessor End User: Retail, Financial Services, Healthcare, Government |
| Companies Covered | Thales Group, NXP Semiconductors, Infineon Technologies, IDEMIA, Samsung Electronics, STMicroelectronics, Giesecke & Devrient, Microchip Technology, Qualcomm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IC Card/Smart Card Market Strategic Shifts
Chip architecture convergence and regulatory mandates for quantum-resistant encryption are compressing product lifecycles and reshaping procurement specifications across banking and government verticals.
Biometric sensor integration into payment cards is collapsing the distinction between possession-based and inherence-based authentication. Issuers in the Middle East and Nordic markets are piloting fingerprint-activated cards for high-net-worth segments. This convergence is collapsing fraud liability structures and forcing acquirers to retool terminal software for biometric verification workflows.
ETSI's EN 302 636 and the EU Cybersecurity Act are mandating Common Criteria EAL4+ certification for payment applications, elevating compliance costs for non-European suppliers. The European Banking Authority's RTS on SCA is tightening authentication requirements for e-commerce transactions. Contactless card issuers are responding by pre-certifying dual-interface products across multiple national approval schemes to accelerate market entry.
Transit operators are consolidating procurement around open-loop payment acceptance, displacing closed-loop proprietary card systems. Transport for London's model is spreading to São Paulo, Singapore, and Sydney, where municipal agencies now specify EMV-compatible credentials rather than custom transit-only products. This specification shift is most visible in Latin American and Asia-Pacific metro systems seeking interoperability with international tourist payments.
Global IC Card/Smart Card Market Segmentation
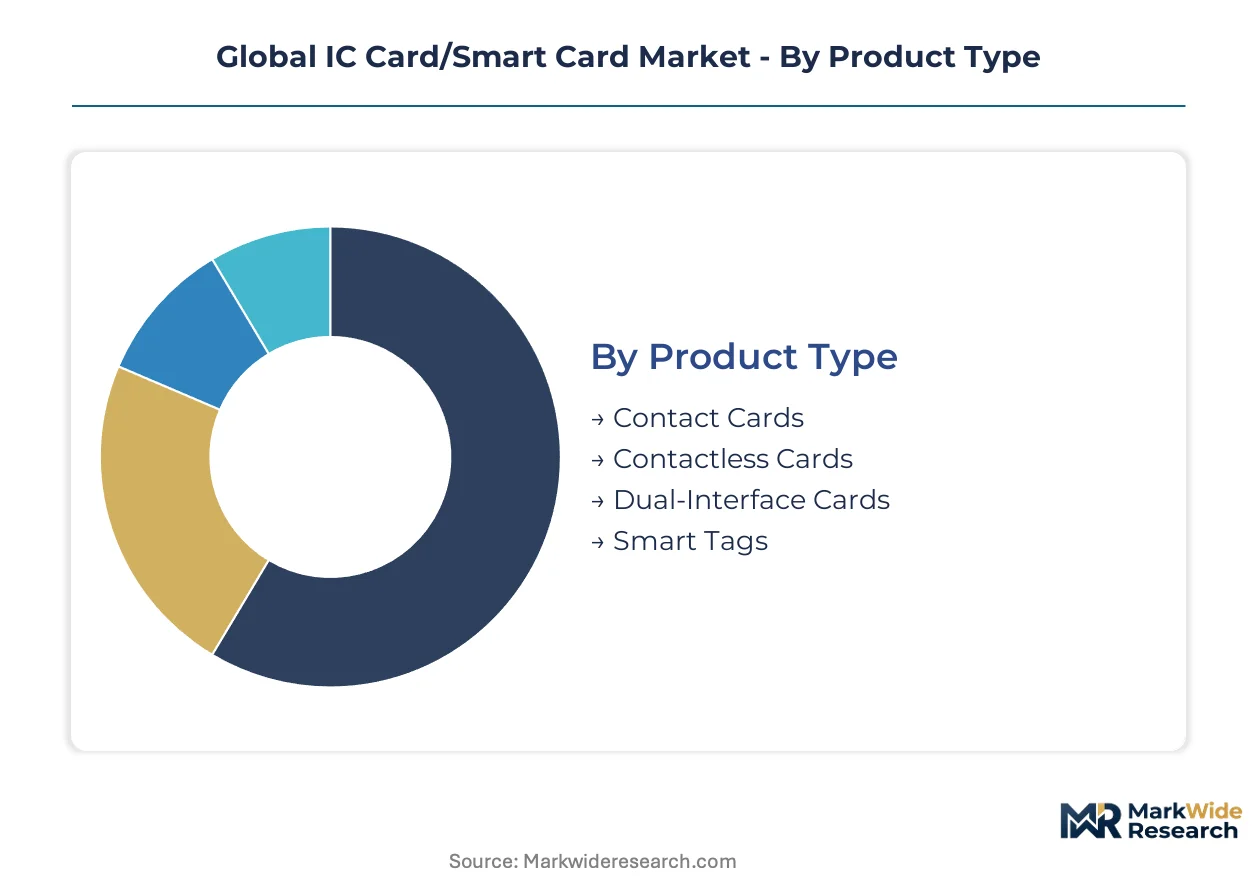
IC card procurement specifications diverge sharply across payment infrastructure, transit authority requirements, and credential security mandates. Segmentation reveals how chip architecture choices and interface protocols align with distinct risk profiles and transaction velocity needs.
Product Type:
Mature contact-based products coexist with emerging dual-interface architectures as issuers balance legacy terminal compatibility against tap-to-pay convenience.
- Contact Cards:Physical gold-plated pads on card surface establish electrical connection with POS terminals through ISO/IEC 7816 protocols. Banking networks in Italy and the United States maintain these for EMV compliance in environments with high terminal replacement costs.
- Contactless Cards:Embedded antenna coils enable 13.56 MHz RF communication with readers at transaction speeds under 500 milliseconds. Transit authorities in São Paulo and Sydney specify these for open-loop fare gates where passenger throughput dictates procurement decisions.
- Dual-Interface Cards:Single chip with both contact pads and contactless antenna. German banks favor these for unified ATM and retail acceptance.
- Smart Tags:Passive RFID labels for industrial asset tracking. Japanese electronics manufacturers deploy these for component-level supply chain visibility.
Contactless cards handle the majority of throughput; dual-interface cards are expanding most quickly on share.
Application:
Cost tier stratification separates high-security government contracts from high-volume retail loyalty programs with minimal encryption requirements.
- Banking:EMVCo-certified secure elements with dynamic data authentication and cryptographic key management. PCI-DSS mandates in the United States and EBA Strong Customer Authentication rules in Europe drive replacement cycles for magnetic-stripe portfolios.
- Transportation:Calypso and MIFARE protocols dominate closed-loop systems; open-loop EMV migration accelerates in Brazil and Singapore. Transport for London's model conditions municipal procurement toward interoperable payment credentials.
- Access Control:DESFire and iCLASS credentials for physical building entry. Corporate campuses in Germany and the United States specify these for multi-site identity federation.
- Loyalty Programs:Low-cost memory cards with static data storage. Retail chains deploy these for points accumulation without transaction authorization requirements.
Banking commands premium pricing per unit; transportation is gaining share fastest as open-loop specifications proliferate.
Technology:
Volume concentration favors established protocols while margin capture shifts toward advanced microprocessor architectures with multi-application sandboxing.
- RFID:Passive backscatter communication across 125 kHz to 960 MHz bands. Industrial asset-tracking programs in German automotive supply chains replace barcode systems with these for real-time location visibility.
- NFC:Short-range 13.56 MHz protocol with active peer-to-peer modes. Mobile wallet activation on smartphones conditions consumer familiarity with tap-to-pay behavior.
- Magnetic Stripe:Legacy iron-oxide tape storage with static account data. Replacement demand concentrates where EMV compliance deadlines have passed.
- Microprocessor:Embedded operating systems with Java Card or MULTOS platforms. Government ID and e-passport programs in China and the United States require these for biometric template storage and digital signature generation.
RFID dominates shipment volumes; microprocessor technology shows the steepest expansion trajectory in value terms.
End User:
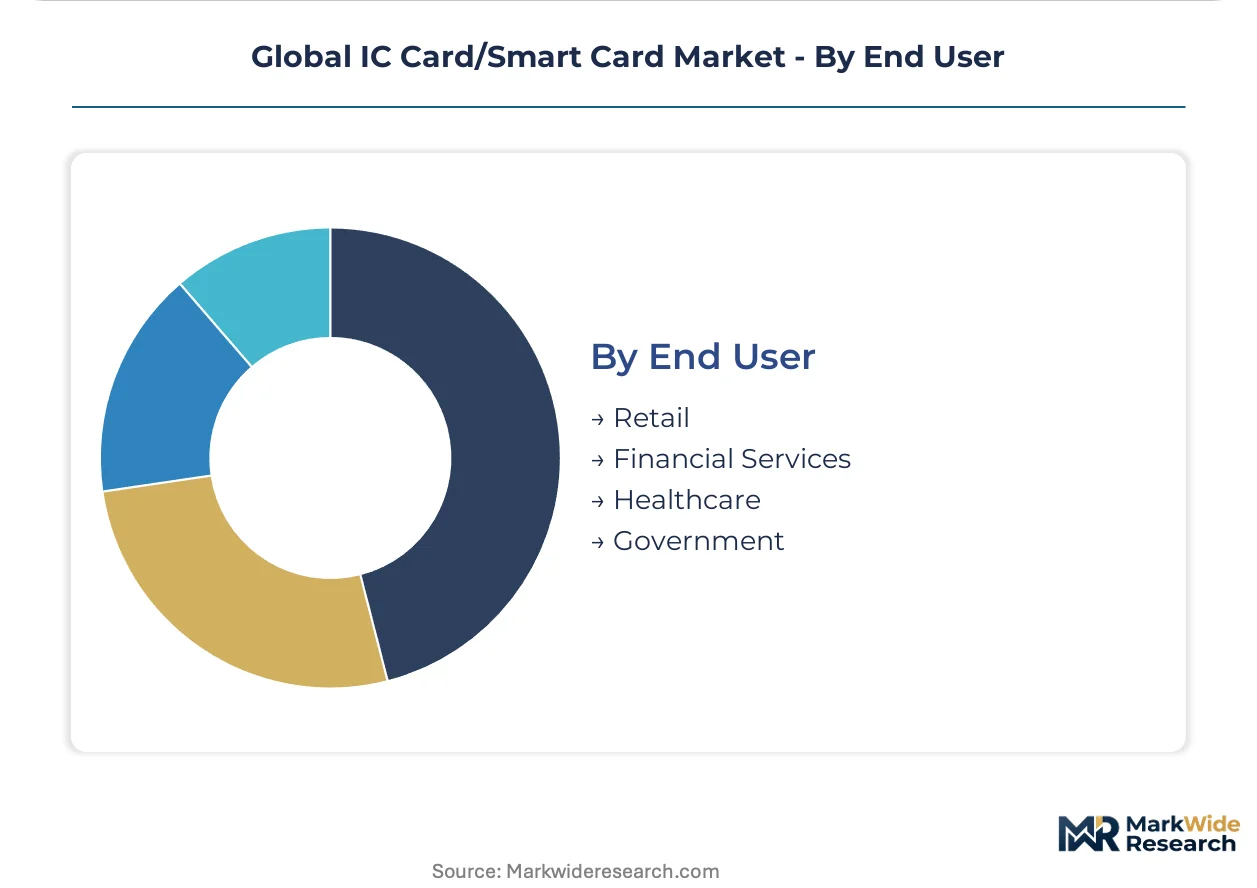
Customer type segmentation reflects divergent certification burdens — financial services demand Common Criteria evaluation while retail prioritizes cost minimization.
- Retail:High-volume, low-margin card issuance for private-label payment and loyalty programs. Merchant acquirers in the United States specify these for cobranded store cards with minimal authentication requirements.
- Financial Services:Dual-interface EMV cards with tokenization support for e-commerce. RBI guidelines in India and PSD2 requirements in Europe mandate strong authentication for online transactions.
- Healthcare:Patient identity cards with insurance eligibility storage. National health systems in Germany deploy these for electronic prescription access.
- Government:National ID, e-passport, and e-driver license credentials with ICAO 9303 compliance. UIDAI Aadhaar specifications in India and REAL ID requirements in the United States drive multi-year procurement cycles.
Retail generates the highest unit volumes; government contracts deliver the longest revenue visibility through multi-year credential modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German secure-element manufacturers export dual-interface chips to banking networks across France, Italy, and Spain. Taiwanese foundries supply wafers to card personalization facilities in Brazil and Mexico. Chinese module assemblers ship contactless products to transit authorities in Southeast Asia.
United States
EMV compliance deadlines and open-loop transit modernization drive secure-element procurement. The Federal Communications Commission governs NFC emission standards under Part 15 rules. New York City and Chicago transit authorities deploy contactless fare systems requiring EMV-compatible credentials.
Germany
Automotive supply chains and federal identity programs anchor domestic demand for microprocessor cards. The Federal Office for Information Security mandates Common Criteria EAL4+ evaluation for government credentials. Bavarian semiconductor fabs produce secure elements for European banking certifications.
China
National ID modernization and mobile payment infrastructure expansion sustain high-volume manufacturing. SAMR certification and GB/T cryptographic standards create compliance barriers for foreign suppliers. Shenzhen and Shanghai host module assembly operations serving domestic transit and banking sectors.
India
UIDAI Aadhaar enrollment and RBI tokenization guidelines propel dual-interface card issuance. BIS certification requirements govern imported secure-element acceptance. Mumbai and Bengaluru concentrate personalization facilities for financial inclusion programs.
Brazil
São Paulo metro open-loop migration and national payment system modernization accelerate contactless adoption. ANVISA regulates health credential formats for patient identity applications. São Paulo state hosts Latin America's largest card personalization cluster serving municipal transit contracts.
Global IC Card/Smart Card Market Competitive Environment
On the supply side, the industry is consolidating around secure-element specialists with captive certification expertise and foundry partnerships. Three archetypes dominate: semiconductor designers with banking security portfolios, diversified electronics conglomerates with government credential divisions, and pure-play card manufacturers with personalization scale. Competitive positioning hinges on EMVCo pre-certification breadth and multi-application Java Card platform licensing.
Within the semiconductor archetype, NXP Semiconductors and Infineon Technologies occupy positions anchored by European banking security certifications. IDEMIA exemplifies the credential-systems tier, leveraging government contract visibility across national ID and e-passport programs. Samsung Electronics represents the diversified conglomerate model, integrating secure-element production with broader consumer electronics manufacturing scale.
| Leading Market Players |
|---|
| Thales Group |
| NXP Semiconductors |
| Infineon Technologies |
| IDEMIA |
| Samsung Electronics |
| STMicroelectronics |
| Giesecke & Devrient |
| Microchip Technology |
| Qualcomm |
| Others |
Value Chain & Pricing Dynamics
Shenzhen's module assembly cluster dictates downstream pricing power through captive access to SAMR-certified secure-element supply. Pricing stratification across the IC card/smart card market traces directly to wafer fabrication concentration and certification tier differentiation.
Pricing Analysis
Single-interface contact cards occupy the economy tier while dual-interface products command mid-market premiums and post-quantum-ready secure elements anchor premium positioning. Three-tier pricing structure across premium, standard, and economy levels reflects Common Criteria EAL4+ certification costs, with German and Austrian foundry output carrying geographic delivery premiums. Cost compression in the contact-card tier is intensifying because Taiwanese 300mm wafer pricing volatility squeezes gross margins. Retail loyalty programs exhibit highest price sensitivity; government e-passport contracts demonstrate lowest sensitivity due to multi-year procurement cycles and security mandates.
Supply Chain Analysis
Export controls on advanced lithography equipment to Chinese fabs limit domestic secure-element production scaling and fragment chip sourcing strategies. Supply concentrates in Taiwan for 300mm wafer fabrication, Germany and Austria for secure-element design, and China for module assembly and card personalization. Raw material dependencies include silicon wafers, gold bonding wire, and epoxy molding compounds. Single-source vulnerability around Taiwanese foundry capacity represents the dominant structural risk. Distribution runs through card personalization bureaus in Brazil, India, and Germany serving regional banking and transit authority procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where EMVCo and Common Criteria certification entrenchment creates formidable switching costs for banking and government customers.
For Market Incumbents: Harden certification portfolio breadth by pre-qualifying dual-interface products across India's BIS, China's SAMR, and ETSI frameworks simultaneously. Deepen backward integration into 300mm wafer supply through long-term offtake agreements with Taiwanese foundries to insulate against silicon cost volatility. Mobile wallet substitution threatens physical card volumes in premium consumer segments; counter with biometric-integrated card pilots in Middle East and Nordic markets. For New Entrants and Emerging Players: Build out industrial asset-tracking specialization targeting German automotive and Japanese electronics supply chains where RFID smart tag adoption outpaces banking card saturation. India's UIDAI Aadhaar-linked financial inclusion programs offer the most penetrable white-space, with dual-interface credential demand outpacing domestic secure-element supply. Pursue licensing partnerships with established Java Card platform holders rather than independent certification investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors secure-element designers with captive government contract visibility and post-quantum cryptography roadmap alignment. Long-term viability hinges on quantum-resistant algorithm standardization timelines extending through the next decade. Target acquisition archetypes: European design houses with side-channel attack resistance expertise and Israeli fault-injection countermeasure specialists. Watch NIST post-quantum algorithm finalization as the signal for accelerated secure-element refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Interface Product Pre-Certification | Accelerates market entry across India's BIS, China's SAMR, and ETSI approval schemes. |
| Post-Quantum Cryptography R&D Investment | Positions secure-element portfolios for NIST algorithm standardization and government design wins. |
| Industrial RFID Tag Capacity Expansion | Captures German automotive supply chain contracts displacing legacy barcode systems. |
| Biometric Sensor Integration Partnership | Enables fingerprint-activated card pilots for Middle East high-net-worth banking segments. |
| Foundry Long-Term Supply Agreement | Locks in Taiwanese 300mm wafer allocation against silicon pricing volatility compression. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with secure-element design engineers, EMVCo certification specialists, transit authority procurement directors, and banking card product managers; and secondary validation against EMVCo certification registries, BIS and SAMR approval databases, ETSI interoperability test reports, and SEC filings from listed semiconductor manufacturers. Bottom-up shipment estimates by product type and application were triangulated against top-down market value reconstruction.
Forecast inputs span contact, contactless, dual-interface, and smart tag product categories across banking, transportation, access control, and government credential applications. Modeled dimensions include interface protocol, chip architecture, certification tier, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis of EMV compliance deadlines and transit modernization procurement waves. Forecast calibration incorporates NFC handset proliferation rates and open-loop payment acceptance expansion timelines.
Stress conditions across silicon wafer pricing bands, certification timeline compression scenarios, and mobile wallet substitution velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EMV migration pace and government credential modernization schedules. Material shifts in NIST post-quantum algorithm standardization timelines or export control expansion to additional lithography equipment categories would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Data As a Service (Daas) Market
Digital Solutions
Media Asset Management (MAM) Solutions Market
Digital Solutions
Digital BSS Market
Digital Solutions
Contact Tracing Application Market
Digital Solutions
Enterprise Asset Management (EAM) Market
Digital Solutions
Express Digitizer Market
Digital Solutions
API Monetization Platform Market
Digital Solutions
Plant Asset Management (PAM) Market
Digital Solutions
Global Tracking As a Service Market
Digital Solutions
Global Advocacy Software Market
Digital Solutions
Crowdsourcing Market
Digital Solutions
Document Case Management (DCM) Market
Digital Solutions
Business Process Management As a Service Market
Digital Solutions
Application Modernization Services Market
Digital Solutions
Web Performance Market
Digital Solutions
Global Cloud OSS BSS Market