
 Global Data Collection and Labeling Market | 2026-2036
Global Data Collection and Labeling Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Collection and Labeling Market Foresight
Subscription-based model-serving layers for continuously refreshed training datasets is shifting how vendors monetize data collection and labeling services. Scale AI leverages its federal and defense sector relationships to sustain high-complexity annotation contracts. Appen Limited anchors its competitive position through a globally distributed crowd workforce spanning multiple continents. Cogito Tech specializes in healthcare-specific labeling protocols that comply with stringent clinical data standards.
Data collection and labeling encompasses the systematic acquisition, categorization, and semantic annotation of raw information—images, text, audio, video, and sensor streams—into structured formats suitable for supervised machine learning, typically involving bounding boxes, transcription, sentiment tags, or LiDAR point-cloud segmentation at precision thresholds of 95% or higher. Image and video data types dominate current volume flows due to computer vision deployment across manufacturing quality control and retail analytics. Automated annotation techniques are displacing manual workflows in high-frequency consumer internet applications, though manual annotation retains premium pricing in medical imaging and legal document review where error tolerance approaches zero.
The EU AI Act imposes mandatory training data documentation requirements that reshape procurement criteria for European enterprise buyers, while FDA guidance on machine learning-based medical devices mandates traceable labeling provenance for clinical algorithm submissions. ISO standards for artificial intelligence data quality are gaining contractual weight in procurement negotiations between technology OEMs and their annotation suppliers. Stakeholders must monitor how regulatory fragmentation between Brussels and Washington creates divergent compliance cost structures that influence vendor selection and geographic service delivery strategies.
Market Dynamics
Autonomous vehicle manufacturers are compressing annotation timelines from months to weeks, forcing data labeling vendors to restructure workforce deployment around continuous model retraining cycles rather than discrete project delivery.
Growth Catalysts
- EU AI Act documentation mandates:European enterprise buyers now require traceable training data provenance, creating procurement pull for vendors with certified audit trails.
- LiDAR point-cloud segmentation:Autonomous vehicle programs in the United States, Germany, and China are driving demand for 3D spatial annotation at sub-centimeter precision thresholds.
- Healthcare algorithm submissions:FDA guidance on machine learning-based medical devices mandates structured labeling protocols, expanding contract volumes for clinical-grade annotation services.
Market Restraints
- Specialized annotator wage inflation:Medical imaging and legal document review require domain-expert labelers, compressing gross margins on high-complexity contracts.
- Platform dependency concentration:Crowd workforce aggregation platforms in the Philippines and Kenya create single-point-of-failure risk for global delivery networks.
- Automated pre-labeling accuracy ceilings:Computer vision models plateau at 85-90% precision on edge cases, requiring costly human-in-the-loop verification.
Strategic Opportunities
- Brazilian agtech satellite imagery:Precision agriculture operators lack localized annotation capacity for crop-disease detection models.
- Synthetic data generation convergence:Neural radiance fields combined with procedural simulation are reducing physical data capture requirements for rare scenario training.
- Japan METI data quality certification:Official recognition programs create preferential vendor status for algorithm exports to Japanese manufacturing OEMs.
Industry Challenges
- Multilingual NLP annotator scarcity:Low-resource language specialists for African and Southeast Asian markets command premium rates and exhibit high turnover.
- ISO 9001 adaptation lag:Annotation vendors struggle to map quality management systems to probabilistic AI data workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Collection and Labeling Market |
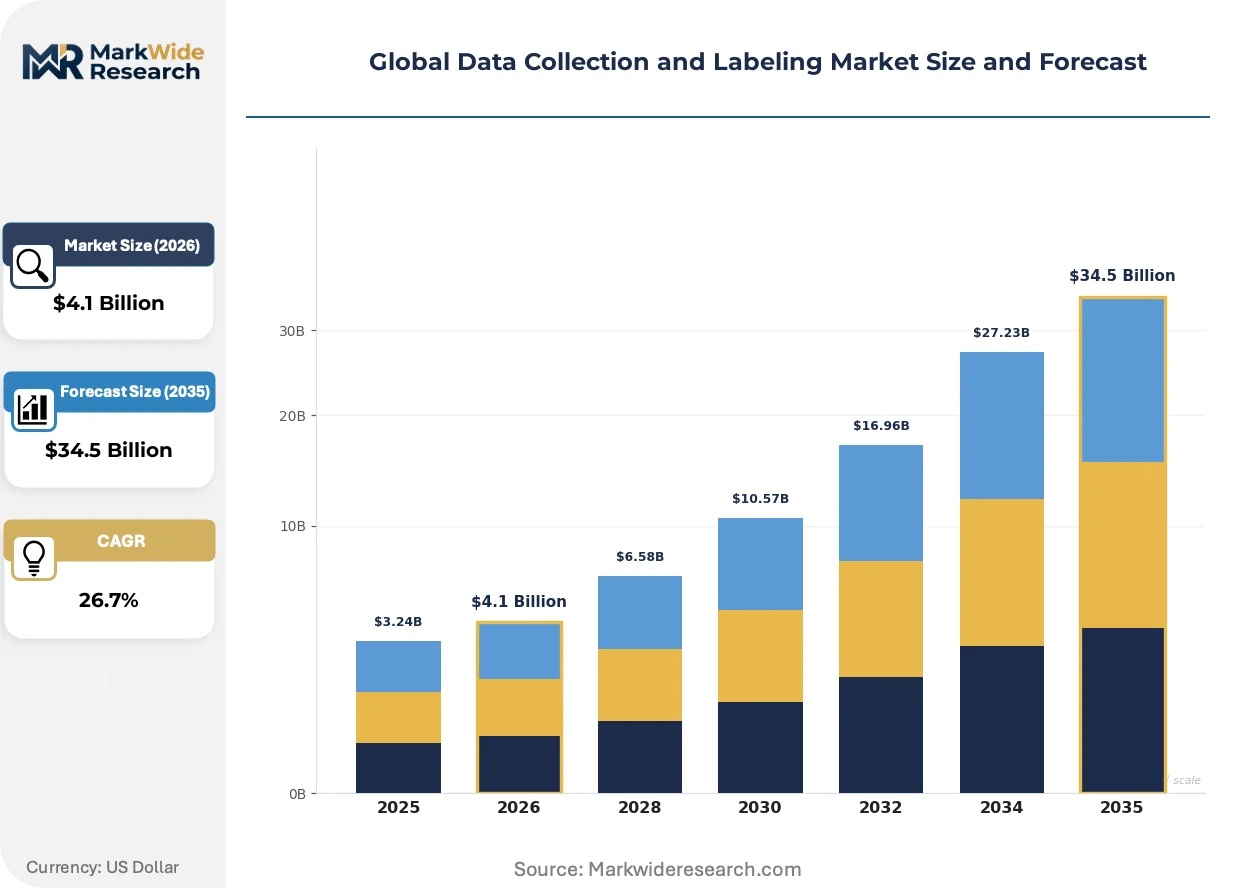
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $34.5 Billion |
| CAGR (2026 – 2036) | 26.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Data Type: Image, Text, Audio, Video, Sensor Data, Satellite Data Labeling Technique: Manual Annotation, Automated Annotation, Semi-Automated Annotation, Synthetic Data Generation, Sensor Fusion, Crowdsourcing Application Area: Computer Vision, Natural Language Processing, Speech Recognition, Autonomous Vehicles, Robotics, Fraud Detection Client Industry: Technology OEMs, Telecom Providers, Financial Institutions, Entertainment Studios, Government Agencies, Academic Organizations |
| Companies Covered | Alegion, Cogito Tech, Appen Limited, iMerit, Encord, Scale AI, CloudFactory Limited, Shaip, Labelbox, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Collection and Labeling Market Shifts & Advancements
Foundation model fine-tuning pipelines are collapsing the traditional boundary between raw data collection and deployment-ready training sets, compressing vendor value-chain positioning.
Active learning frameworks with human-in-the-loop uncertainty sampling are unifying annotation and model training into continuous feedback cycles. Autonomous vehicle developers in California and Bavaria deploy these systems to prioritize edge-case labeling. The technology is unifying quality assurance and dataset curation into single operational layers.
EU AI Act training data documentation requirements are mandating structured provenance records for all high-risk AI system training sets. European enterprise procurement teams now embed audit rights into annotation contracts. Medical device manufacturers submitting to notified bodies face the steepest compliance cost escalations.
Subscription-based dataset refreshing is displacing perpetual-license bulk purchases among consumer internet platforms. San Francisco-based model-serving startups now bundle annotation-as-a-service with inference infrastructure. This pattern is most visible in North American retail analytics and manufacturing quality control deployments.
Global Data Collection and Labeling Market Segmentation
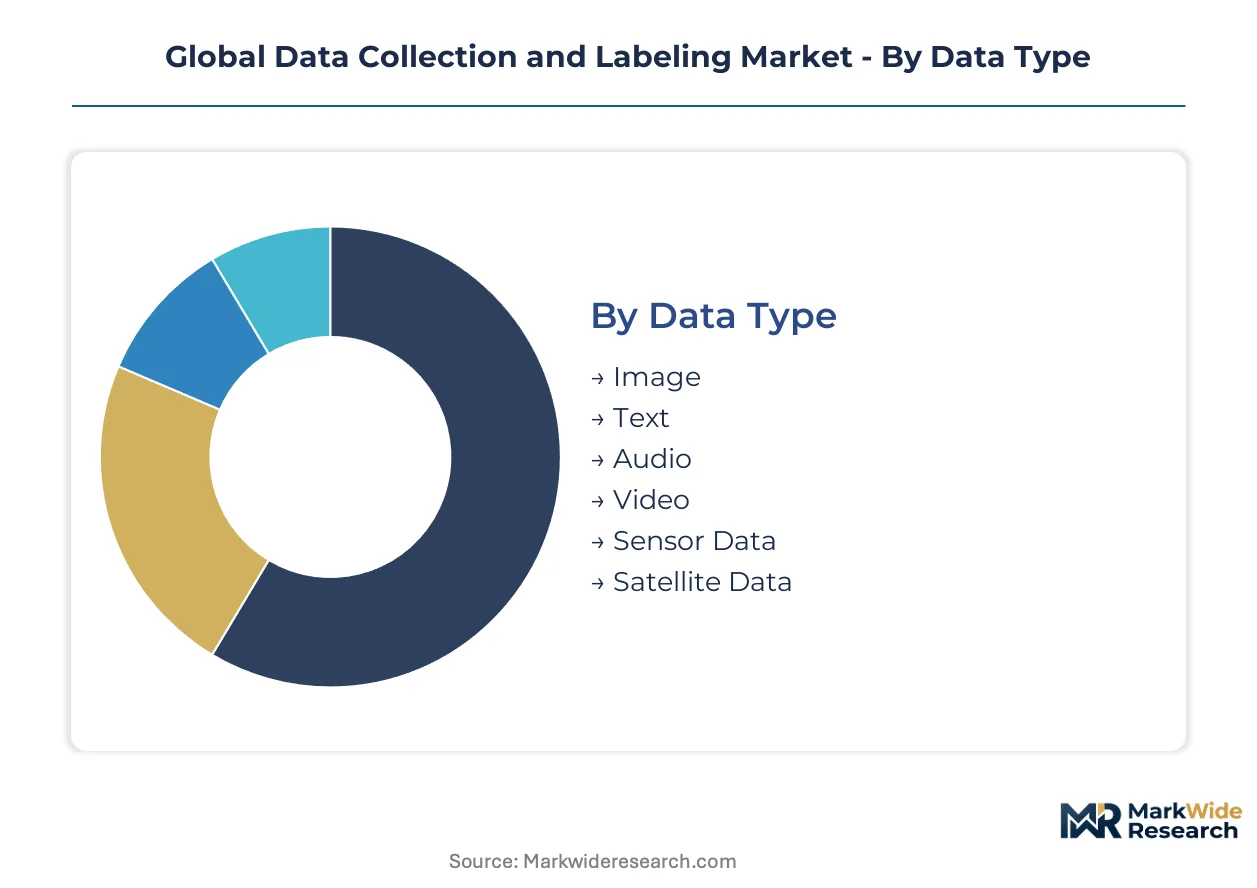
Segmentation in data collection and labeling determines which compliance frameworks apply, which pricing tiers activate, and which vendor capabilities become non-negotiable. Buyers map procurement specifications directly to these dimensions when drafting annotation service agreements.
Data Type:
FDA mandates traceable provenance for medical imaging datasets, while EU AI Act documentation requirements apply differentially based on data modality and risk classification.
- Image:Bounding boxes, segmentation masks, and pixel-level annotations for manufacturing defect detection and retail shelf analytics. San Francisco-based autonomous vehicle developers consume massive volumes for perception model training, with FDA-regulated medical imaging requiring specialist radiologist annotators at premium rates.
- Video:Temporal sequence annotation including object tracking, action recognition, and frame interpolation for motion analysis. German automotive OEMs in Bavaria drive demand for multi-camera synchronization at 30fps minimum, with EU AI Act high-risk system documentation adding contractual overhead.
- Text:Named entity recognition, sentiment classification, and semantic parsing for document intelligence. Financial institutions in New York and London require legal-grade annotation protocols for contract analysis, with GDPR Article 17 deletion rights complicating training set versioning.
- Audio:Speech-to-text transcription, speaker diarization, and acoustic event detection. Call center analytics platforms in India and the Philippines source multilingual transcription for accent-diverse training.
- Sensor Data:Time-series labeling for accelerometer, gyroscope, and IMU streams. Industrial predictive maintenance deployments in Japan and South Korea require vibration pattern annotation aligned with JIS quality standards.
- Satellite Data:Geospatial raster annotation for land use classification and change detection. Brazilian agtech operators lack localized capacity for crop-disease spectral signature labeling.
Image sits at the top of the volume ranking, with Video climbing the fastest.
Labeling Technique:
Cost tiering separates premium human-in-the-loop verification from economy-grade automated pre-labeling, with margin compression most severe at the middle tier.
- Manual Annotation:Domain-expert labelers execute pixel-precise segmentation and clinical-grade medical imaging review. FDA submission pathways for machine learning-based devices mandate this tier for diagnostic algorithms, with specialized annotator wage inflation compressing supplier margins.
- Automated Annotation:Computer vision models generate draft labels for human verification, achieving 85-90% accuracy on standard objects before plateauing on edge cases. Consumer internet platforms in Seattle deploy this tier for high-frequency content moderation at scale.
- Semi-Automated Annotation:Active learning frameworks prioritize uncertain samples for human review, unifying quality assurance and dataset curation. California autonomous vehicle developers deploy continuous retraining cycles through this hybrid approach.
- Synthetic Data Generation:Neural radiance fields and procedural simulation create training scenarios for rare edge cases. Robotics manufacturers reduce physical data capture requirements through synthetic LiDAR point clouds.
- Sensor Fusion:Synchronized annotation across camera, radar, and LiDAR streams for 3D spatial understanding. Sub-centimeter precision thresholds apply for German and Chinese autonomous driving programs.
- Crowdsourcing:Distributed workforce aggregation for high-volume, low-complexity tasks. Platform dependency on Philippine and Kenyan labor markets creates single-point-of-failure risk for global delivery networks.
Automated Annotation dominates transaction volumes, with Synthetic Data Generation expanding most quickly.
Application Area:
Customer type determines whether procurement emphasizes research flexibility or production-grade SLA guarantees.
- Computer Vision:Manufacturing quality control and retail analytics drive current volume flows. ISO standards for artificial intelligence data quality gain contractual weight in technology OEM procurement negotiations.
- Natural Language Processing:Document intelligence and conversational AI require multilingual annotator capacity. Low-resource language specialists for African and Southeast Asian markets command premium rates.
- Speech Recognition:Accent-diverse training data for voice assistants and call center automation. Scarcity of native speakers for underrepresented dialects limits model performance equity.
- Autonomous Vehicles:Timeline compression from months to weeks forces vendor restructuring around continuous model retraining. NHTSA regulatory scrutiny in the United States adds documentation burdens.
- Robotics:Manipulation task annotation and sim-to-real transfer datasets. Synthetic data convergence reduces physical demonstration requirements.
- Fraud Detection:Transaction pattern labeling and anomaly flagging for financial institutions. HIPAA and GDPR constraints apply when behavioral biometrics intersect with personal data.
Computer Vision leads deployment scale, with Autonomous Vehicles gaining share fastest.
Client Industry:
Geographic concentration of demand clusters around regulatory complexity and technology ecosystem maturity.
- Technology OEMs:Vertically integrated annotation procurement for proprietary model development. San Francisco and Seattle clusters anchor North American demand concentration.
- Telecom Providers:Network optimization and customer service automation datasets. 5G infrastructure deployment drives edge computing annotation requirements.
- Financial Institutions:Regulatory compliance documentation for algorithmic decision systems. SEC and FINRA scrutiny elevates audit trail requirements.
- Entertainment Studios:Content moderation and recommendation system training. Subscription-based dataset refreshing displaces perpetual-license bulk purchases.
- Government Agencies:Federal and defense sector contracts sustain high-complexity annotation pipelines. Security clearance requirements limit vendor pools.
- Academic Organizations:Research flexibility prioritizes over production SLAs. Public dataset publication triggers GDPR and institutional review board compliance.
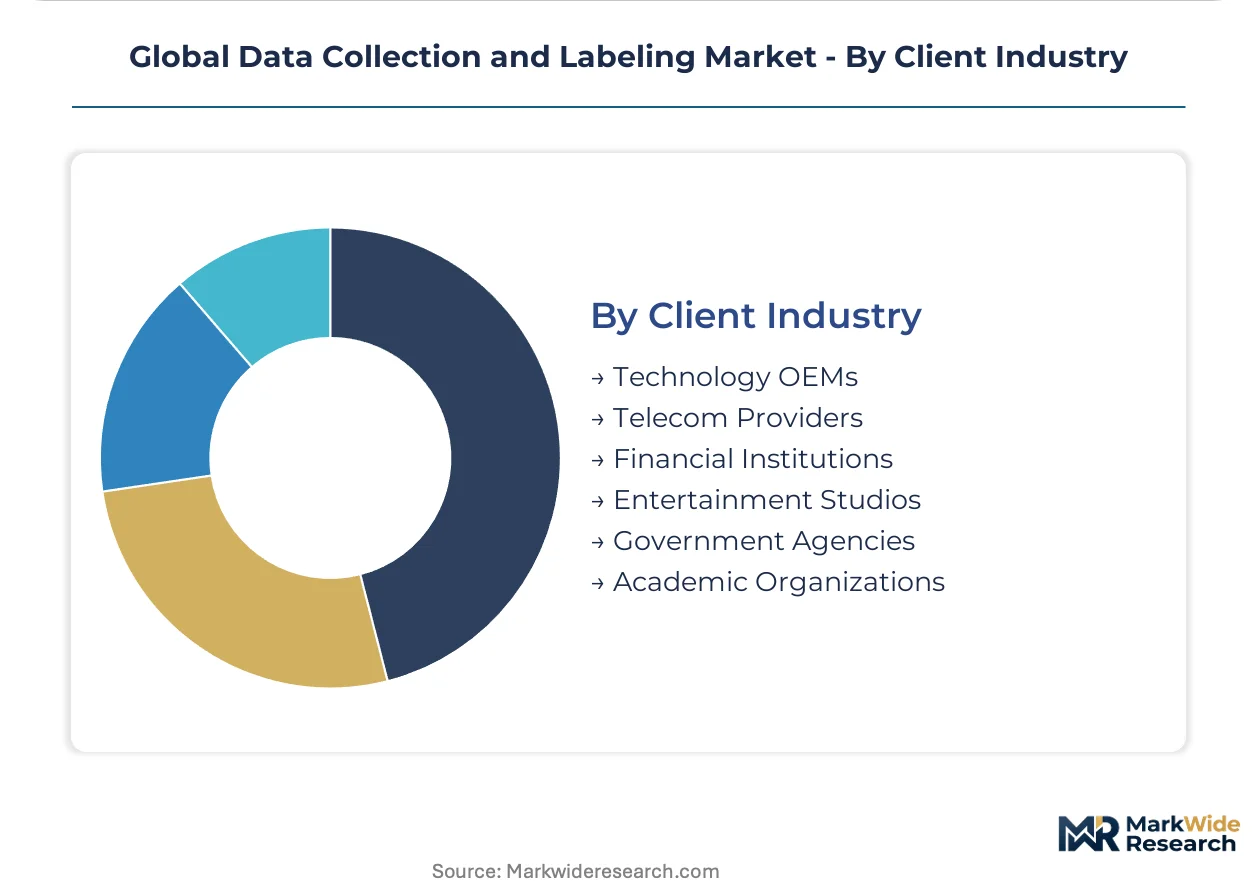
Technology OEMs command the largest contract values, with Government Agencies showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates autonomous vehicle annotation demand while Germany enforces stricter documentation standards under EU AI Act mandates, creating divergent procurement patterns across Atlantic markets.
United States
San Francisco and Seattle technology clusters anchor North American demand for computer vision training datasets, with autonomous vehicle developers compressing annotation timelines from months to weeks. FDA guidance on machine learning-based medical devices mandates traceable labeling provenance for clinical algorithm submissions. Federal and defense sector contracts in Washington DC and Virginia sustain high-complexity annotation pipelines requiring security clearances.
Germany
Bavarian automotive OEMs drive demand for LiDAR point-cloud segmentation at sub-centimeter precision thresholds for autonomous driving programs. EU AI Act documentation requirements impose structured provenance records on high-risk AI system training sets, adding contractual overhead to procurement negotiations. Berlin-based model-serving startups bundle annotation-as-a-service with inference infrastructure for manufacturing quality control deployments.
China
MIIT standards for intelligent vehicle data quality shape domestic annotation procurement specifications for autonomous driving development. Yangtze River Delta technology corridors concentrate computer vision dataset demand for manufacturing defect detection and retail analytics. GB standards compliance creates preferential vendor status for algorithm exports to state-owned manufacturing enterprises.
Japan
METI data quality certification programs establish official recognition frameworks for annotation vendors serving manufacturing OEMs. Industrial predictive maintenance deployments in Nagoya and Osaka require vibration pattern annotation aligned with JIS quality standards. Robotics manufacturers in Tokyo-Yokohama corridors reduce physical data capture requirements through synthetic LiDAR point cloud generation.
Brazil
Precision agriculture operators in São Paulo and Minas Gerais lack localized annotation capacity for crop-disease spectral signature labeling from satellite imagery. ANVISA regulatory pathways for machine learning-based medical devices remain under development, creating uncertainty for clinical-grade annotation procurement. Agtech startups in the Central-West region source remote sensing datasets from international vendors to train detection models.
Global Data Collection and Labeling Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with technology OEMs favoring vertically integrated procurement while government agencies prioritize security-cleared vendors. The vendor base organizes into three strategic archetypes: federal-sector specialists leveraging defense relationships, globally distributed crowd workforce aggregators, and healthcare-focused compliance specialists. M&A activity concentrates on synthetic data generation capabilities, while strategic partnerships dominate the autonomous vehicle annotation vertical.
Within the federal-sector specialist tier, Scale AI exemplifies vendors sustaining high-complexity contracts through security infrastructure investments. Appen Limited represents the globally distributed workforce archetype, spanning multiple continents for high-volume task aggregation. Cogito Tech occupies a position within healthcare-specific labeling, anchoring compliance-oriented procurement for clinical data standards.
| Leading Market Players |
|---|
| Alegion |
| Cogito Tech |
| Appen Limited |
| iMerit |
| Encord |
| Scale AI |
| CloudFactory Limited |
| Shaip |
| Labelbox, Inc. |
| Others |
Supply & Pricing Matrix
Radiologist annotators in India and the Philippines anchor labor-cost differentials that widen pricing-tier spreads between clinical-grade medical imaging contracts and high-volume consumer internet annotation. Specialized domain-expert wage inflation compresses margins at the premium tier while automated pre-labeling erodes price floors in standardized computer vision tasks.
Pricing Analysis
Capacity additions in Kenya and the Philippines are reshaping price floors for crowdsourced annotation tiers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-submission-grade medical imaging from manufacturing quality control and content moderation pools. Price differentiation hinges on certification level—ISO 9001-adapted vendors command 40% premiums—and geographic delivery cost. Cost compression in the standard tier is intensifying because automated pre-labeling accuracy plateaus at 85-90% on edge cases. Consumer internet platforms exhibit highest price sensitivity; clinical algorithm developers show lowest.
Supply Chain Analysis
LiDAR sensor supply rests on German and Chinese automotive component producers. Raw material dependencies include GPU compute clusters from Taiwan, specialized annotation workstations from South Korea, and optical sensor arrays from Japan. Single-source vulnerability concentrates in Philippine crowd-workforce aggregation platforms. Distribution runs through direct enterprise contracts for federal and healthcare sectors, with platform-mediated spot markets serving high-frequency consumer internet demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds on regulatory documentation mandates, with EU AI Act training data provenance requirements creating durable procurement pull for certified vendors.
For Market Incumbents: Lock in federal and defense sector relationships through security clearance infrastructure before emerging synthetic data vendors erode physical annotation demand. Invest in backward integration of synthetic data generation capabilities to defend margin position against neural radiance field convergence. Prioritize ISO 9001 quality management adaptation to capture EU AI Act contract flow.
For New Entrants and Emerging Players: Brazilian agtech operators present an underserved buyer archetype lacking localized satellite imagery annotation capacity for crop-disease detection models. Japanese manufacturing OEMs seeking METI data quality certification offer preferential vendor status for algorithm exports. Position around synthetic data generation convergence to reduce physical data capture requirements and accelerate sales cycles.
For Investors and Strategic Acquirers: Autonomous vehicle manufacturers are the most active acquirer in this space, driven by timeline compression demands and vertical integration imperatives. Long-term viability favors vendors with hybrid human-in-the-loop and synthetic data capabilities over pure-play crowd workforce aggregators. Watch active learning framework adoption rates as inflection indicator for vendor value-chain positioning collapse.
| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Data Generation Capability | Reduces physical LiDAR capture requirements for German and Chinese autonomous driving programs. |
| EU AI Act Compliance Certification | Creates preferential procurement status for European enterprise buyers mandating traceable provenance. |
| Active Learning Framework Deployment | Unifies annotation and model training into continuous feedback cycles for California AV developers. |
| Security Clearance Infrastructure | Limits vendor pools for Washington DC federal and defense sector annotation contracts. |
| Healthcare-Specific Labeling Protocols | Captures FDA-mandated clinical-grade annotation demand for machine learning-based medical devices. |
Research Methodology
Direct dialogue with data operations executives at autonomous vehicle manufacturers, clinical informatics officers at medical device companies, federal procurement officers, crowd workforce platform operators, and AI ethics compliance leads grounded qualitative findings. Secondary validation drew from FDA 510(k) submission databases, EU AI Act implementation guidance, SEC filings of publicly traded annotation vendors, customs records of LiDAR sensor imports, and METI certification registries. Bottom-up contract volume estimates triangulated against top-down technology OEM AI training spend allocations.
Bottom-up modeling of annotation contract volumes by data type, labeling technique, and client industry converged with top-down AI infrastructure investment flow analysis across the projection horizon. Segmentation dimensions included data modality, automation tier, application area, and geographic regulatory cluster. CAGRs derived from vendor revenue trajectory interpolation and buyer procurement cycle compression rates. Synthetic data substitution curves and workforce wage inflation indices served as industry-specific forecast inputs.
Inputs from FDA submission databases and EU notified body guidance were available through the study window; gaps in ANVISA regulatory pathway finalization for Brazilian clinical-grade annotation introduce uncertainty bands around Latin American market sizing. Forecasts reflect assumptions regarding synthetic data accuracy convergence timelines and crowd workforce platform stability. Regulatory fragmentation between Brussels and Washington, automated pre-labeling accuracy ceiling persistence, and specialized annotator turnover rates warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Enterprise Mobility in Energy Sector Market
Digital Solutions
Online Laundry Services Market
Digital Solutions
Global Connected Workplace Market
Digital Solutions
Global Insight As a Service Market
Digital Solutions
Demand Side Platform (DSP) Market
Digital Solutions
UAE Digital Twin Market
Digital Solutions
Sales Acceleration Technology Market
Digital Solutions
Digital Signage Market
Digital Solutions
Farm Management Software Market
Digital Solutions
Asia Pacific B2C Legal Services Market
Digital Solutions
Digital Assistant Market
Digital Solutions
Transport Management System Market
Digital Solutions
Morocco ICT Market
Digital Solutions
Global Cloud POS Market
Digital Solutions
Global Enterprise Mobility Management (EMM) Market
Digital Solutions
APAC Digital Signage Market