
 Enterprise Mobility Market | 2026-2036
Enterprise Mobility Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Mobility Market Intelligence
Platform bundling of endpoint management with identity and security tools is pivoting procurement patterns across enterprise buyers. Microsoft Corporation leverages its cloud ecosystem to anchor integrated mobility suites. VMware, Inc. competes through specialized workspace virtualization layers. BlackBerry Limited differentiates via hardened security modules for regulated industries.
Enterprise mobility encompasses the technologies, policies, and services enabling employees to access corporate data and applications from smartphones, tablets, and laptops outside traditional office perimeters, with core systems requiring AES-256 encryption, certificate-based authentication, and containerized application sandboxes to maintain data integrity across heterogeneous device fleets. Cloud-based deployment now leads volume as organizations retire on-premises infrastructure, while mobile device management captures concentrated margin pools through recurring subscription structures. Communication tools within the application layer are expanding fastest as distributed workforces require persistent collaboration channels.
FDA guidelines for mobile health applications, HIPAA privacy and security rules, and NIST zero-trust architecture standards collectively shape product certification requirements and procurement eligibility across healthcare and federal sectors. The EU AI Act and GDPR cross-border data transfer mechanisms are extending compliance burdens for multinational deployments. Stakeholders must evaluate whether their vendor portfolios satisfy emerging sovereign data residency mandates before committing to long-term platform contracts.
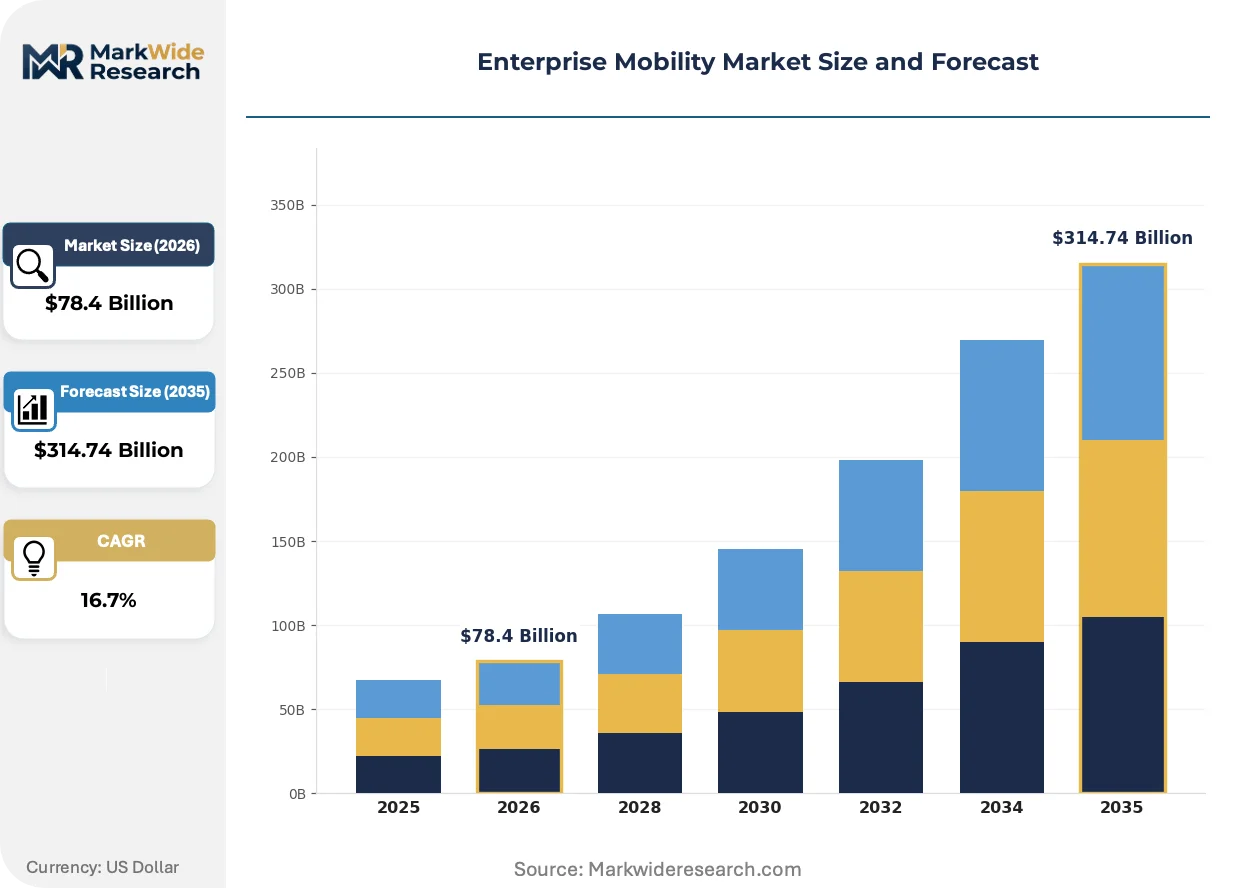
Market Dynamics
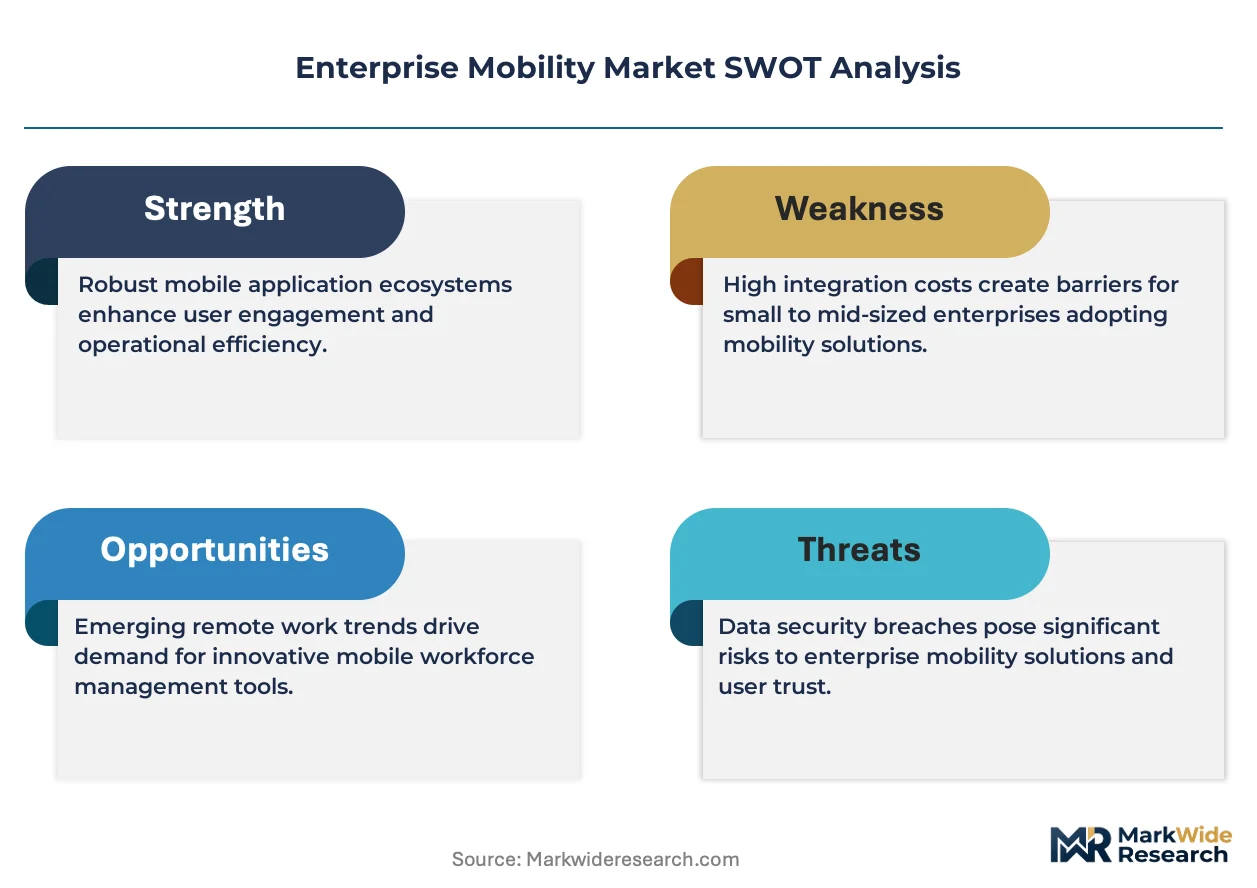
Zero-trust architecture mandates from NIST are forcing enterprise IT departments to rearchitect mobile access frameworks, creating cascading procurement cycles for endpoint security, identity verification, and continuous authentication systems across device fleets.
Growth Catalysts
- NIST Cybersecurity Framework:Federal contractors in the United States must implement continuous device monitoring and certificate-based authentication, expanding addressable market for managed security services.
- Containerization technology:Application sandboxing enables bring-your-own-device policies in financial services without data leakage, reducing hardware refresh costs while maintaining HIPAA and PCI-DSS compliance.
- India:PLI scheme incentives for domestic cloud infrastructure and data center expansion are accelerating regulated sector adoption of sovereign-hosted mobility platforms.
Market Restraints
- Certificate authority concentration:Dependency on a limited pool of trusted root certificate providers creates systemic vulnerability if any major authority experiences compromise or distrust event.
- AES-256 encryption export controls:Cryptographic technology transfer restrictions fragment vendor ability to deploy uniform security stacks across multinational deployments.
- Legacy identity infrastructure:Active Directory dominance in enterprise environments creates integration friction for cloud-native zero-trust architectures, extending deployment timelines.
Strategic Opportunities
- Germany:Industrie 4.0 manufacturing automation and GDPR-compliant edge computing investments create demand for on-premise mobility orchestration platforms with sovereign data controls.
- EU AI Act:Automated decision-making audit requirements for workforce management applications will mandate new logging and explainability features in mobility suites serving European operations.
- 5G private networks:Convergence with ultra-reliable low-latency connectivity enables real-time industrial AR guidance and remote equipment control through hardened mobile endpoints.
Industry Challenges
- Zero-trust architecture expertise:Shortage of engineers capable of implementing continuous authentication pipelines and micro-segmentation policies extends professional services bottlenecks.
- Cross-border data residency:Conflicting sovereignty requirements between GDPR, India's data localization rules, and China's cybersecurity law complicate single-platform global deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Mobility Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $314.74 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Device Management Application: Enterprise Resource Planning, Customer Relationship Management, Business Process Management, Communication Tools End User: SMEs, Large Enterprises, Government, Healthcare Organizations Service Type: Consulting, Implementation, Support & Maintenance, Training |
| Companies Covered | Microsoft Corporation, IBM Corporation, Cisco Systems, Inc., VMware, Inc., Citrix Systems, SAP SE, Broadcom, Inc., BlackBerry Limited, Ivanti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Mobility Market Strategic Shifts & Innovations
Edge-native security architectures are displacing centralized cloud gateways for latency-sensitive applications, while regulatory fragmentation across major economies forces vendors to engineer modular compliance layers rather than uniform global products.
Confidential computing using hardware-based trusted execution environments is decentralizing encryption key management from cloud providers to device-level secure enclaves. Financial services institutions in Germany and the United States are piloting these architectures for high-value transaction authorization. This decentralization reduces attack surface by ensuring sensitive operations execute in hardware-isolated memory regions inaccessible to host operating systems.
GDPR Article 44 cross-border transfer mechanisms and the EU AI Act's risk classification system are imposing documentation burdens on mobility vendors serving European healthcare and public sector clients. Compliance teams must now maintain algorithmic impact assessments and data processing records as auditable artifacts. Vendors are responding by embedding automated compliance telemetry directly into endpoint agents rather than relying on manual attestation.
Subscription fatigue among mid-market buyers is compressing vendor consolidation timelines, with procurement teams demanding unified endpoint management, identity, and security from single platforms rather than best-of-breed point solutions. Value-added resellers and systems integrators in India and the United States are repositioning around outcome-based deployment guarantees. This consolidation pressure is most visible in healthcare, where CIOs prioritize NIST 800-53 alignment over feature breadth.
Enterprise Mobility Market Segmentation
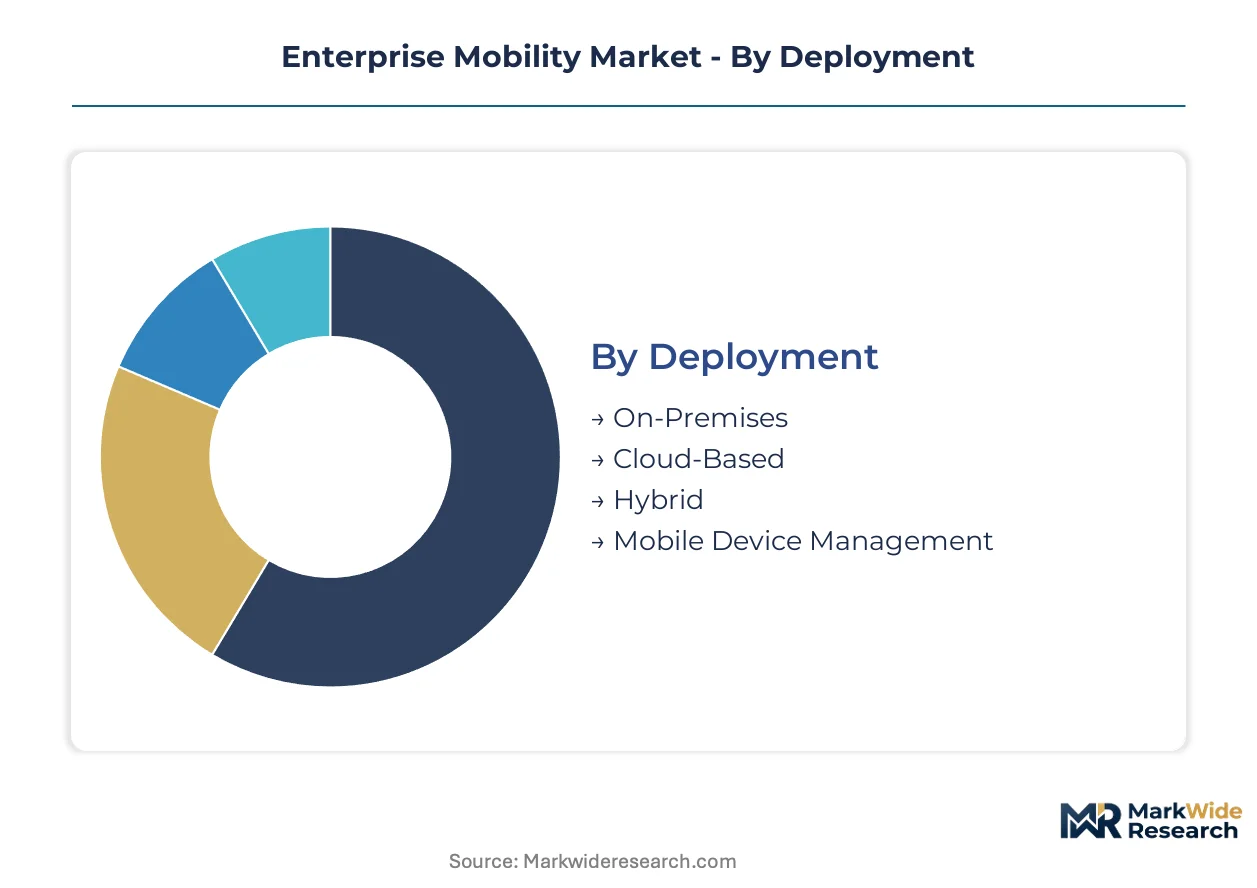
Enterprise mobility procurement patterns diverge sharply across deployment models and organizational scale, with compliance requirements from NIST, HIPAA, and GDPR creating tiered certification burdens that reshape vendor selection criteria. Understanding these segment boundaries clarifies where platform bundling strategies succeed versus where specialized point solutions retain pricing power.
Deployment:
Cloud-based deployments face streamlined SOC 2 and ISO 27001 certification pathways, while on-premises and hybrid architectures must satisfy NIST 800-53 and country-specific data residency audits.
- Cloud-Based:Multi-tenant architectures with centralized patch management and elastic compute scaling. Demand concentrates among mid-market financial services firms in the United States seeking rapid zero-trust implementation without capital expenditure cycles.
- On-Premises:Dedicated infrastructure with full administrative control over encryption key lifecycle and audit logging. German manufacturing conglomerates anchor demand here, driven by Industrie 4.0 sovereignty mandates and GDPR Article 44 transfer restrictions.
- Hybrid:Workload orchestration across private data centers and sovereign cloud regions. India's public sector banks favor this model under RBI data localization guidelines.
- Mobile Device Management:Standalone endpoint control layer with containerized application sandboxing. Healthcare organizations require FDA-aligned validation for clinical workflow integration.
Leading the category by volume: Cloud-Based. Growing fastest: Hybrid.
Application:
Communication tools command premium pricing per seat, while ERP modules face elongated procurement cycles due to SOX compliance and change management overhead.
- Communication Tools:Persistent messaging, video conferencing, and asynchronous collaboration with end-to-end encryption. Distributed technology workforces in India and the United States drive replacement of legacy telephony infrastructure.
- Enterprise Resource Planning:Integrated financial, supply chain, and human capital modules with mobile-responsive interfaces. Large enterprises dominate adoption, constrained by SAP and Oracle ecosystem lock-in during cloud migration.
- Customer Relationship Management:Field sales enablement with offline synchronization and geolocation tracking. Life sciences organizations require 21 CFR Part 11 electronic signature compliance.
- Business Process Management:Workflow automation with mobile task routing and approval hierarchies. Government contractors prioritize FedRAMP-authorized platforms.
Highest margin concentration: Communication Tools. Steepest expansion trajectory: Business Process Management.
End User:
Government and healthcare segments impose mandatory security control frameworks, while commercial buyers optimize for total cost of ownership and integration velocity.
- Government:Classified and unclassified mobility with continuous diagnostics and mitigation. United States federal agencies require FIPS 140-2 validated cryptographic modules.
- Healthcare Organizations:Clinical workflow integration with HIPAA audit logging and FDA 21 CFR Part 11 compliance. Hospital systems prioritize NIST 800-53 moderate security categorization.
- Large Enterprises:Global workforce enablement with multi-region data residency orchestration. Fortune 500 manufacturers in Germany balance GDPR constraints against operational efficiency.
- SMEs:Standardized SaaS consumption with minimal IT overhead. India's services sector accelerates adoption through PLI scheme-supported domestic cloud infrastructure.
Fastest compliance-driven procurement: Healthcare Organizations. Largest addressable expansion: SMEs.
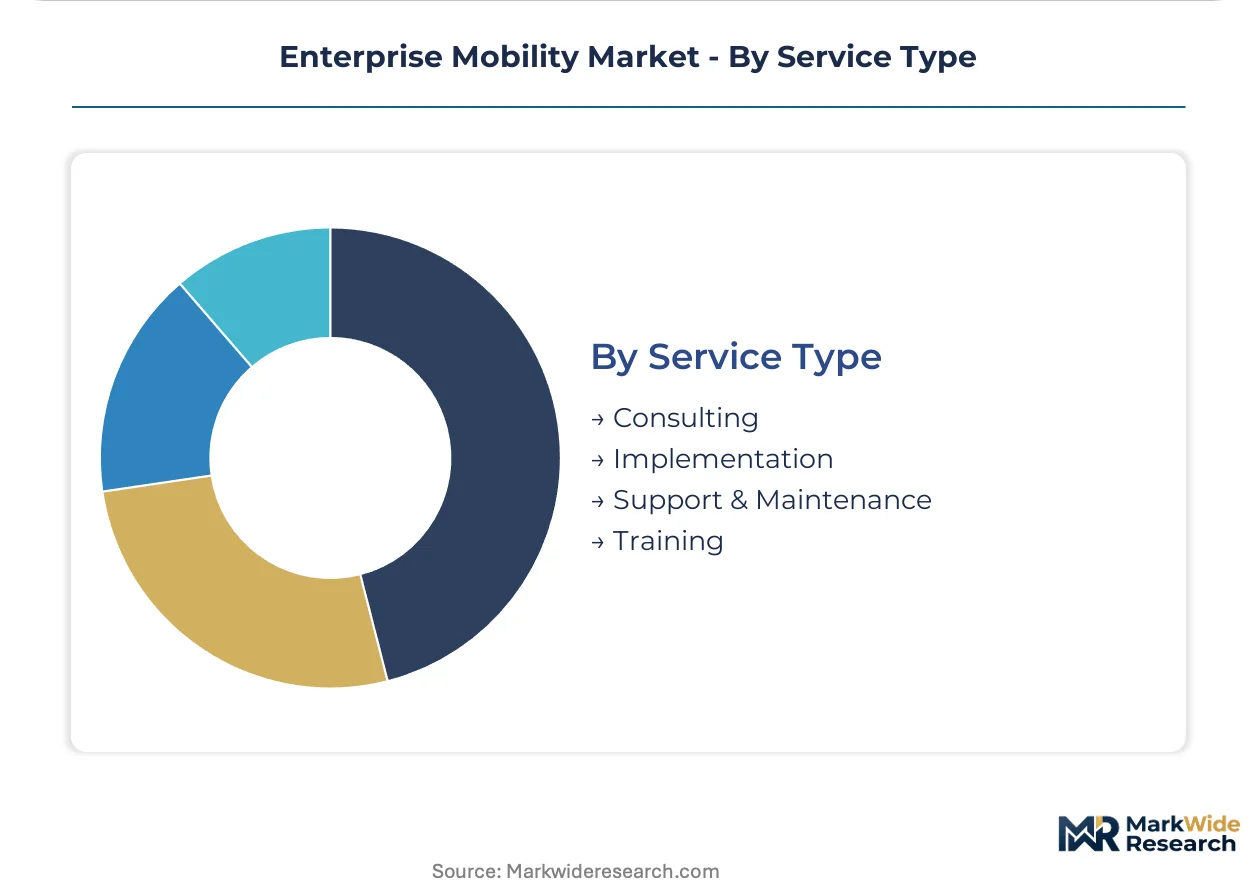
Service Type:
Implementation services capture project-based revenue spikes, while support contracts generate predictable recurring streams with 90%+ renewal rates.
- Implementation:System integration, data migration, and zero-trust architecture deployment. Federal contractors in the United States require cleared personnel for sensitive environment configuration.
- Support & Maintenance:24/7 incident response, patch management, and security advisory. Healthcare organizations mandate four-hour response SLAs for patient-facing systems.
- Consulting:Mobility strategy, compliance gap analysis, and vendor selection advisory. German automotive suppliers engage consultants for EU AI Act readiness assessments.
- Training:Administrator certification and end-user adoption programs. India's IT services firms invest heavily in change management for multinational client deployments.
Revenue concentration peak: Support & Maintenance. Fastest-growing engagement type: Consulting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and Germany's Industrie 4.0 corridors are concentrating enterprise mobility infrastructure investment. Sovereign data mandates and federal procurement requirements are redrawing competitive boundaries across major economies.
United States
Federal contractors drive demand through NIST zero-trust mandates and FIPS 140-2 cryptographic requirements. The Department of Defense's CMMC framework compels continuous device monitoring investments. Northern Virginia's defense corridor hosts concentrated deployment of classified mobility infrastructure.
Germany
Automotive suppliers and Industrie 4.0 manufacturers anchor demand for sovereign-hosted edge platforms. GDPR Article 44 transfer restrictions and BSI technical guidelines enforce data residency compliance. Bavaria's Munich-Stuttgart industrial belt pilots confidential computing for transaction authorization systems.
India
PLI scheme incentives for domestic cloud infrastructure accelerate public sector bank adoption. RBI data localization rules and MeitY cybersecurity frameworks mandate sovereign hosting. Mumbai-Pune and Bengaluru-Hyderabad corridors concentrate IT services firm deployments for multinational clients.
United Kingdom
Financial services institutions in London drive zero-trust architecture procurement for hybrid workforces. NCSC cyber assessment frameworks and FCA operational resilience rules shape vendor selection. The Thames Valley tech cluster hosts concentrated pilot programs for confidential computing endpoints.
Japan
Manufacturing conglomerates demand ultra-reliable mobility platforms for 5G-connected industrial AR. METI's cybersecurity management guidelines and JIS standards enforce rigorous device certification. The Nagoya-Tokyo industrial corridor leads deployment of latency-sensitive remote equipment control systems.
Enterprise Mobility Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Cloud hyperscalers leverage existing enterprise relationships to bundle mobility suites with identity and productivity tools. Specialized workspace virtualization vendors compete through differentiated security modules. Vertical integration into hardware-secured enclaves and strategic partnerships with telecommunications carriers represent dominant competitive moves.
Within the diversified technology tier, Microsoft Corporation and IBM Corporation occupy positions spanning cloud infrastructure through endpoint management. VMware, Inc. exemplifies the specialized virtualization archetype with concentrated workspace solutions. BlackBerry Limited represents the hardened security specialist segment serving regulated industries with sovereign compliance requirements.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Cisco Systems, Inc. |
| VMware, Inc. |
| Citrix Systems |
| SAP SE |
| Broadcom, Inc. |
| BlackBerry Limited |
| Ivanti |
| Others |
Cost & Logistics Intelligence
NIST zero-trust architecture mandates gate qualified supply access and premium-tier pricing power, as federal contractors demand FIPS 140-2 validated cryptographic modules and continuous authentication pipelines that only certified vendors can deliver. This compliance moat separates premium subscription tiers from commoditized endpoint management, with procurement teams paying substantial markups for NIST 800-53 aligned platforms.
Pricing Analysis
Cost-down pressure on mid-market SaaS tiers accelerates because subscription fatigue compresses vendor consolidation timelines, forcing point-solution providers into defensive bundling. Pricing stratifies across FedRAMP-authorized premium suites, SOC 2 validated standard tiers, and stripped-down economy offerings lacking sovereign data controls. Certification grade and after-sales service intensity drive differentiation, with healthcare organizations least price-sensitive due to patient-facing system requirements while Indian SMEs optimize for minimal IT overhead.
Supply Chain Analysis
Reverse-logistics flows for hardware-secured enclaves and confidential computing endpoints concentrate refurbishment expertise in Taiwan, South Korea, and the United States, where semiconductor packaging capabilities support trusted execution environment lifecycle management. Component dependencies center on ARM-based secure processors, hardware security modules, and specialized cryptographic accelerators. Single-source vulnerability in trusted root certificate authorities creates systemic exposure, while distribution runs through hyperscaler marketplaces and value-added resellers with cleared personnel networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where NIST cybersecurity framework mandates erect substantial barrier-to-entry moats, rewarding players with pre-existing federal certifications and punishing those lacking continuous monitoring infrastructure.
For Market Incumbents: Anchor platform consolidation around zero-trust architecture expertise to defend against cloud-native entrants lacking cleared personnel networks. Deepen backward integration into hardware-secured enclaves and captive supply of cryptographic modules. Extend professional services bottlenecks through outcome-based deployment guarantees that lock out competitors. For New Entrants and Emerging Players: EU AI Act automated decision-making audit requirements in Germany open a window for modular compliance layers serving European healthcare and public sector clients. Target India's PLI scheme-supported domestic cloud infrastructure for sovereign-hosted mobility platforms with minimal incumbent presence. Lead with consulting-led engagements for EU AI Act readiness assessments rather than direct platform sales. For Investors and Strategic Acquirers: Consolidation of certificate authority providers is the leading indicator that systemic vulnerability concerns will drive acquisition premiums for diversified trust infrastructure. Long-term viability rests on vendors with embedded automated compliance telemetry rather than manual attestation processes. Monitor subscription renewal rates in healthcare for early signals of platform stickiness versus churn risk.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Certification | FIPS 140-2 validation unlocks federal contractor procurement eligibility and premium pricing tiers. |
| Confidential Computing Hardware Integration | Hardware-based trusted execution environments decentralize encryption key management from cloud providers. |
| Sovereign Cloud Partnership | RBI data localization rules and GDPR Article 44 restrictions mandate domestic infrastructure alliances. |
| Compliance Telemetry Automation | Embedded endpoint agents replace manual attestation for EU AI Act algorithmic impact assessments. |
| Professional Services Capability Buildout | Cleared personnel networks and zero-trust deployment expertise create defensive moats against cloud-native entrants. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across CISOs, federal procurement officers, healthcare CIOs, and systems integration specialists. SEC 10-K disclosures, NIST publications, and EMA regulatory submissions provided validation layers. Bottom-up deployment sizing and top-down market reconstruction were triangulated against hyperscaler capex disclosures and channel partner surveys.
Data-stream reconciliation across deployment models, organization scale, vertical compliance requirements, and regional regulatory clusters shaped the analytical framework throughout the projection horizon. CAGRs derived from elasticity-adjusted adoption curves and replacement cycle analysis. Cloud migration velocity and zero-trust mandate implementation timelines served as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for confidential computing hardware would alter the outlook. Forecasts reflect assumptions around NIST framework adoption rates and sovereign data localization enforcement intensity. Practitioners should monitor certificate authority consolidation events and PLI scheme disbursement patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Thin Client Market
Digital Solutions
Global Digital Art Software Market
Digital Solutions
Automatic Identification and Data Capture Market
Digital Solutions
Core Graphics Market
Digital Solutions
Europe Smart Card Market
Digital Solutions
Content Moderation Services Market
Digital Solutions
AI Infrastructure Solutions Market
Digital Solutions
Contactless Ticketing Ics Market
Digital Solutions
Mock Interview Platforms Market
Digital Solutions
Asia-Pacific Computer Aided Engineering Market
Digital Solutions
Global Enterprise Metadata Management Market
Digital Solutions
Laser Page-Turning Pen Market
Digital Solutions
Global B2B Services Review Platforms Market
Digital Solutions
Utility Bill Management System Market
Digital Solutions
Middle East Smart Card Market
Digital Solutions
Everything As a Service (Xaas) Market