
 Cybersecure Vehicle Control Unit Gateway Systems Market | 2026-2036
Cybersecure Vehicle Control Unit Gateway Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cybersecure Vehicle Control Unit Gateway Systems Market Insights
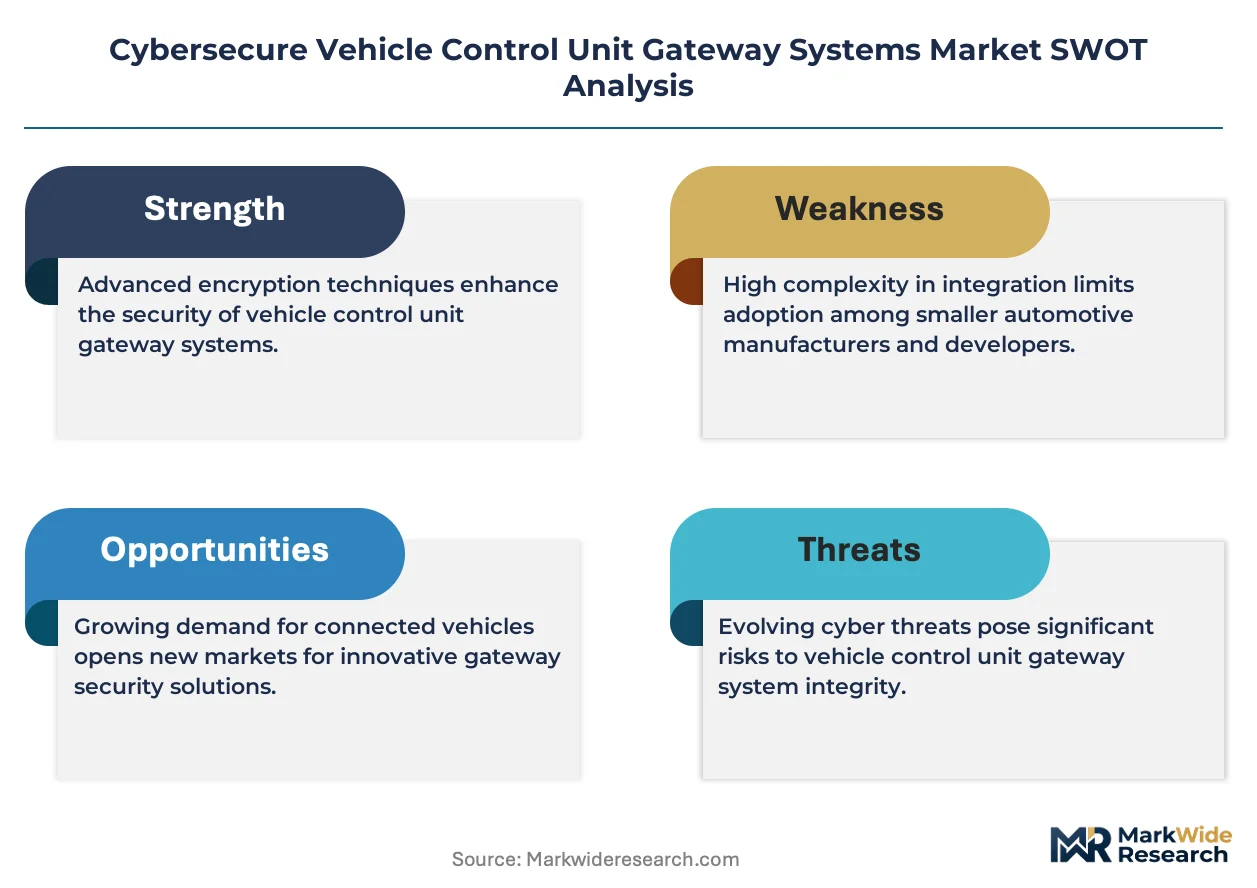
ISO/SAE 21434 certification is collapsing the supplier base for gateway cybersecurity qualification. Robert Bosch leverages its captive semiconductor partnerships to control hardware security module integration at scale. Continental anchors European OEM programs through backward integration into cryptographic firmware stacks. ZF Friedrichshafen competes on domain gateway specialization for electric axle platforms.
Cybersecure vehicle control unit gateway systems are embedded electronic control units that enforce authenticated data routing between vehicle domains using hardware security modules with AES-256 encryption and secure boot protocols, primarily protecting against remote intrusion and unauthorized command injection in connected vehicle architectures. Domain gateway deployments for zonal E/E architectures represent the fastest-expanding segment as automakers consolidate from dozens of discrete ECUs to centralized compute hubs. Embedded gateway units retain the largest installed base but face margin compression as chip shortages ease and commoditization accelerates. Hardware security module technology captures the deepest margin pools due to silicon-level certification requirements and limited qualified foundry capacity.
UN ECE R155 and R156 regulations mandate cybersecurity management systems and software update capabilities for type approval in European markets, directly conditioning gateway design specifications and supplier qualification timelines. The US NHTSA has issued advance notices of proposed rulemaking on vehicle cybersecurity that will extend similar compliance burdens to North American OEM programs. Stakeholders must monitor whether emerging quantum-resistant cryptographic standards from NIST will trigger premature obsolescence cycles for current-generation hardware security modules before design lock points stabilize.
Market Dynamics
Automotive OEMs are consolidating electronic control unit architectures from distributed to zonal gateway designs, compressing supplier qualification timelines and concentrating procurement among semiconductor-integrated tier-1 systems houses.
Growth Catalysts
- UNECE R155 mandate:Cybersecurity management system requirements for type approval force gateway redesigns across European OEM supply chains, expanding qualified supplier addressable market.
- Hardware security module integration:Silicon-level AES-256 encryption and secure boot protocols are becoming baseline specifications for connected vehicle platforms.
- German tier-1 corridor concentration:Stuttgart and Wolfsburg development clusters accelerate domain gateway prototyping cycles for electric axle platforms.
Market Restraints
- Foundry capacity scarcity:Qualified semiconductor fabrication for automotive-grade hardware security modules remains concentrated among TSMC, Samsung, and Intel Foundry Services.
- ISO/SAE 21434 certification costs:Third-party cybersecurity assessment expenses and documentation burdens exclude mid-tier gateway suppliers from OEM qualification pools.
- Commoditization pressure on embedded units:Easing chip shortages expose basic gateway ECUs to price erosion as supply normalizes.
Strategic Opportunities
- Quantum-resistant cryptography transition:NIST post-quantum cryptographic standards create replacement cycles for current-generation hardware security modules before design lock stabilization.
- Software-defined vehicle architectures:Over-the-air update capabilities mandated by UNECE R156 expand recurring revenue potential for gateway firmware maintenance services.
- North American regulatory alignment:NHTSA advance notices on vehicle cybersecurity signal forthcoming compliance burdens similar to European frameworks.
Industry Challenges
- Automotive cybersecurity engineering talent scarcity:Shortage of engineers qualified in both embedded systems and cryptographic protocol implementation extends R&D timelines.
- Legacy vehicle integration complexity:Backward compatibility requirements for CAN-FD and Ethernet gateway protocols constrain architectural freedom in mixed fleet deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cybersecure Vehicle Control Unit Gateway Systems Market |
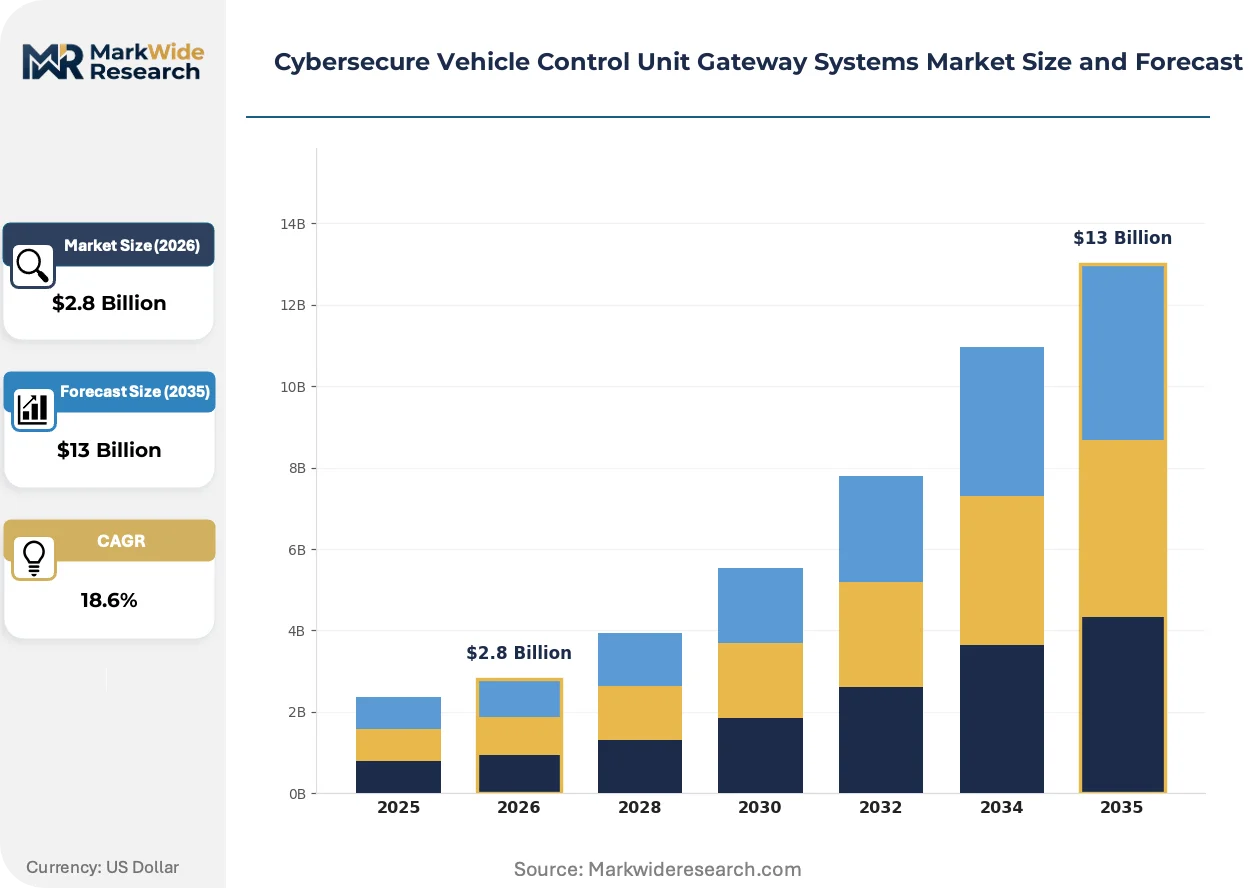
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Gateway, Central Gateway, Domain Gateway, Telematics Gateway Technology: Hardware Security Module, Secure Boot, Intrusion Detection System, Cryptographic Accelerator Application: Advanced Driver Assistance, Fleet Management, Infotainment Security, Vehicle-to-Everything Communication End User: OEMs, Tier-1 Integrators, Aftermarket Suppliers, Autonomous Vehicle Developers |
| Companies Covered | Robert Bosch, Continental, ZF Friedrichshafen, Aptiv, Harman International, DENSO, NXP Semiconductors, Infineon Technologies, Renesas Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cybersecure Vehicle Control Unit Gateway Systems Market Trends and Innovations
Zonal E/E architectures are compressing the gateway supplier base while elevating hardware security module specifications. Three developments are reshaping competitive positioning.
Domain gateway controllers with integrated hardware security modules are supplanting discrete ECU clusters in premium electric vehicle platforms. Luxury and performance OEMs are locking designs eighteen to twenty-four months ahead of volume production. This consolidation is compressing margin pools for standalone gateway suppliers lacking semiconductor partnerships.
UNECE R156 software update mandates are forcing gateway suppliers to embed secure boot and rollback capabilities at silicon level. European type approval authorities are rejecting architectures lacking cryptographic attestation chains. Tier-1 suppliers with captive firmware stacks are capturing specification influence earlier in OEM development cycles.
Automotive procurement teams are consolidating gateway awards to systems houses with end-to-end cybersecurity certification. Direct semiconductor sourcing agreements are replacing modular supplier arrangements. German and US OEM programs show the strongest concentration in single-source domain gateway contracts.
Cybersecure Vehicle Control Unit Gateway Systems Market Segmentation
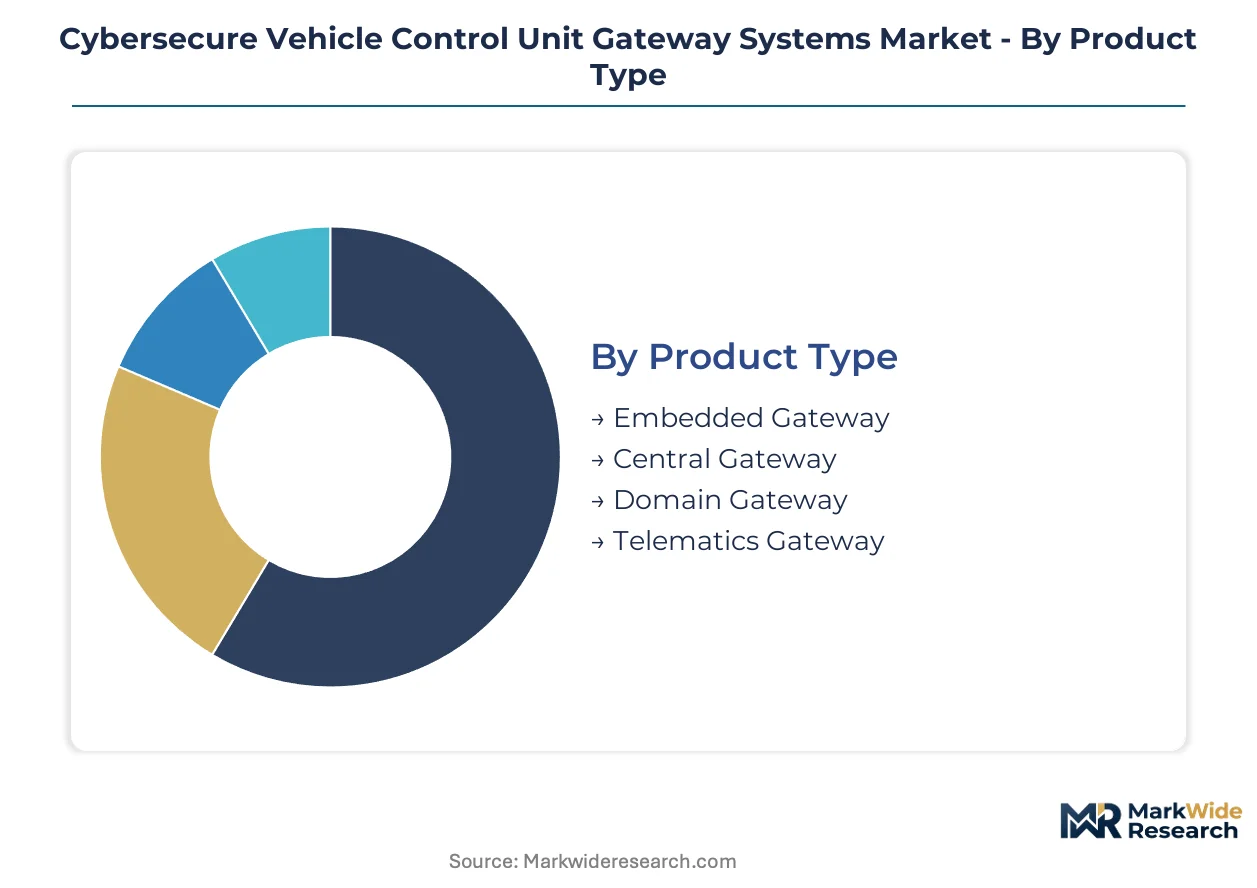
Gateway cybersecurity segmentation reveals where silicon-level certification creates defensible margin pools. Product architecture choices determine supplier qualification barriers, while technology integration depth separates tier-1 systems houses from modular component vendors.
Product Type:
Margin concentration follows the shift from distributed ECU clusters toward centralized compute hubs, with hardware security module integration depth as the primary value driver.
- Domain Gateway:Integrated controllers consolidate multiple vehicle domains through zonal E/E architectures with embedded AES-256 hardware security modules. Demand concentrates in German electric axle platforms where Bosch, Continental, and ZF Friedrichshafen anchor development corridors around Stuttgart and Wolfsburg.
- Central Gateway:High-throughput routing hubs manage cross-domain data flows between powertrain, chassis, and body electronics with secure boot attestation chains. Procurement is shifting toward single-source contracts with semiconductor-integrated tier-1 suppliers as UNECE R156 mandates force earlier design lock decisions.
- Embedded Gateway:Discrete ECU units face margin compression as chip shortages ease and supply normalization accelerates commoditization.
- Telematics Gateway:Cellular-connected modules enable over-the-air firmware updates with cryptographic rollback protection.
The dominant share belongs to Embedded Gateway, while Domain Gateway is closing the gap fastest.
Technology:
Certification scarcity at the silicon foundry level concentrates value capture among suppliers with captive semiconductor partnerships.
- Hardware Security Module:Automotive-grade silicon with AES-256 encryption engines and tamper-resistant key storage requires qualified fabrication at TSMC, Samsung, or Intel Foundry Services. European OEM programs are rejecting architectures lacking cryptographic attestation chains for UNECE R155 type approval.
- Secure Boot:Cryptographic verification protocols ensure firmware integrity from power-on through runtime execution. Implementation demands backward integration into firmware stacks that Continental has anchored through European OEM qualification programs.
- Intrusion Detection System:Real-time monitoring of CAN-FD and Ethernet traffic for anomaly signatures.
- Cryptographic Accelerator:Dedicated silicon for post-quantum algorithm preprocessing as NIST standards mature.
Hardware Security Module commands the deepest margins, though Secure Boot is gaining specification influence fastest in OEM development cycles.
Application:
Functional safety requirements and data throughput demands create divergent certification burdens across use cases.
- Advanced Driver Assistance:Latency-critical sensor fusion gateways require deterministic Ethernet routing with ISO 26262 ASIL-D functional safety qualification. German luxury OEMs are locking designs eighteen to twenty-four months ahead of volume production.
- Vehicle-to-Everything Communication:DSRC and C-V2X protocols demand roadside unit interoperability with standardized security credentials. US NHTSA advance notices signal forthcoming compliance burdens extending European cybersecurity frameworks to North American programs.
- Fleet Management:Telematics aggregation for commercial vehicle operators with standardized OBD-II gateway interfaces.
- Infotainment Security:Consumer-facing content protection with DRM and application sandboxing.
Advanced Driver Assistance retains the largest committed development budgets, while Vehicle-to-Everything Communication is expanding most quickly on regulatory momentum.
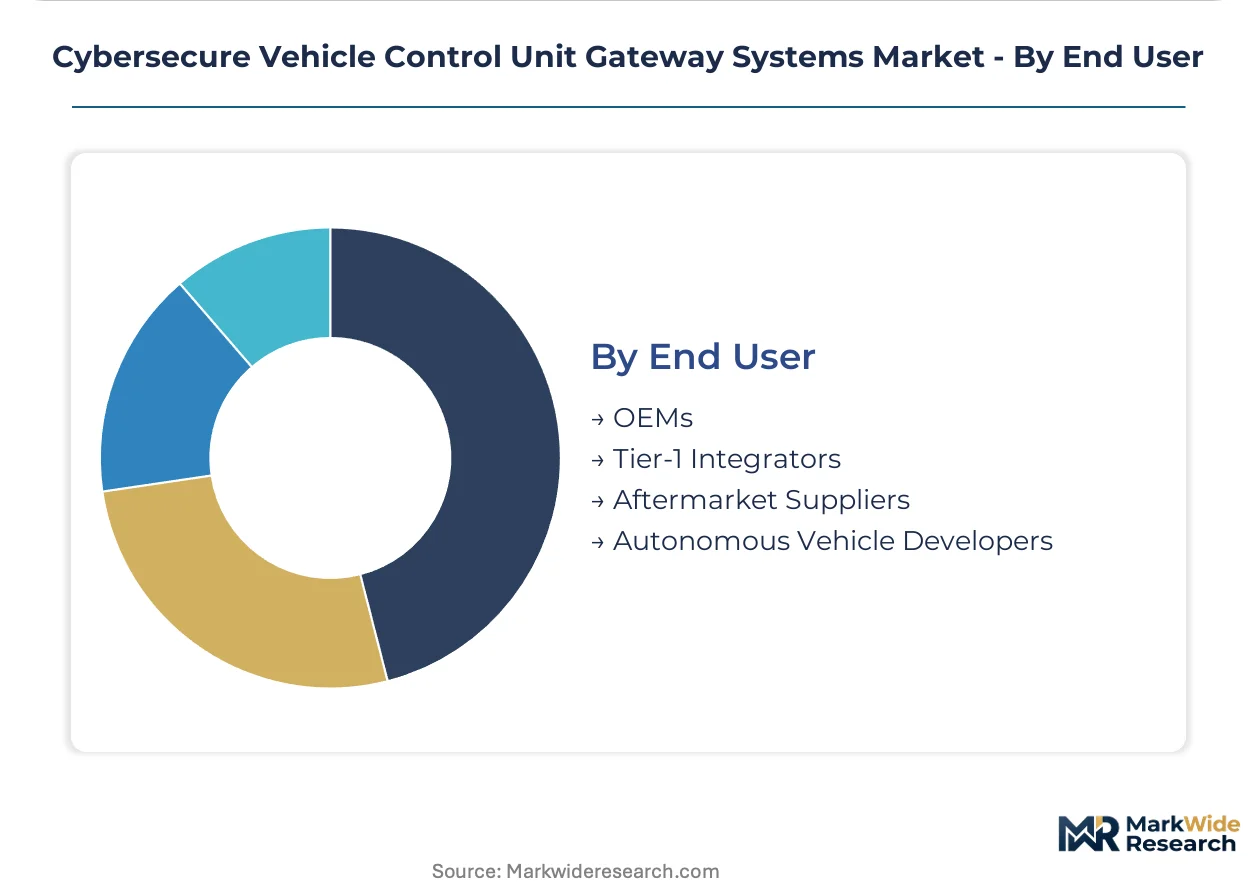
End User:
Procurement authority consolidation is compressing the addressable supplier base as direct semiconductor sourcing agreements replace modular arrangements.
- OEMs:Volkswagen, BMW, and Mercedes-Benz are consolidating gateway awards to systems houses with end-to-end ISO/SAE 21434 certification. Single-source domain gateway contracts now dominate German and US program awards.
- Tier-1 Integrators:Bosch leverages captive semiconductor partnerships to control hardware security module integration at scale across multiple OEM platforms.
- Autonomous Vehicle Developers:Specialized compute architectures with redundant gateway paths for fail-operational performance.
- Aftermarket Suppliers:Retrofit telematics modules for legacy fleet cybersecurity upgrades.
OEMs control the qualification timeline, though Tier-1 Integrators are capturing specification influence earlier in development cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UNECE R155 cybersecurity mandates are redrawing procurement geography across automotive supply chains, concentrating gateway development in jurisdictions with established tier-1 ecosystems and semiconductor fabrication partnerships.
Germany
Volkswagen, BMW, and Mercedes-Benz are consolidating domain gateway awards to systems houses with captive ISO/SAE 21434 certification. KBA type approval authorities enforce cryptographic attestation chains for software update capabilities under UNECE R156. Stuttgart and Wolfsburg development corridors anchor prototyping cycles for electric axle platforms with integrated hardware security modules.
United States
General Motors and Ford are accelerating zonal E/E architecture transitions ahead of anticipated NHTSA cybersecurity rulemaking. Advance notices of proposed rulemaking signal compliance burdens mirroring European frameworks. Michigan and California engineering centers concentrate R&D for deterministic Ethernet routing in autonomous vehicle programs.
China
Domestic OEMs are localizing gateway procurement to escape import dependency for automotive-grade hardware security modules. MIIT cybersecurity standards for connected vehicles mandate encryption capabilities for type approval. Shanghai and Shenzhen semiconductor clusters are qualifying domestic foundry capacity for AES-256 silicon.
Japan
Toyota and Honda are locking domain gateway designs eighteen to twenty-four months ahead of volume production for next-generation electric platforms. METI industrial policy prioritizes cryptographic firmware stack development for automotive applications. Nagoya and Tokyo metropolitan areas concentrate tier-1 engineering resources for ISO 26262 ASIL-D functional safety qualification.
South Korea
Hyundai and Kia are consolidating gateway procurement with semiconductor-integrated suppliers for battery electric vehicle platforms. MFDS alignment with UNECE regulations accelerates cybersecurity management system adoption. Seoul Capital Area development clusters specialize in telematics gateway modules with cellular-connected over-the-air update capabilities.
Cybersecure Vehicle Control Unit Gateway Systems Market Competitive Landscape
Player mix skews toward diversified automotive electronics conglomerates with captive semiconductor partnerships and captive firmware development capabilities. Market structure concentrates procurement authority among three German systems houses controlling Stuttgart and Wolfsburg development corridors. Strategic archetypes separate semiconductor-integrated tier-1 suppliers from modular gateway component vendors and captive semiconductor foundry operators. Dominant competitive moves include backward integration into cryptographic firmware stacks and exclusive foundry capacity reservation for automotive-grade hardware security modules.
Among German-based diversified automotive suppliers, Robert Bosch GmbH, Continental AG, and ZF Friedrichshafen AG exemplify the semiconductor-integrated tier-1 archetype that is capturing single-source domain gateway contracts. Bosch represents systems houses leveraging captive semiconductor partnerships to control hardware security module integration at scale. Continental occupies a position anchored through European OEM qualification programs with backward integration into cryptographic firmware stacks. ZF Friedrichshafen sits within the specialization tier focused on domain gateway architectures for electric axle platforms.
| Leading Market Players |
|---|
| Robert Bosch |
| Continental |
| ZF Friedrichshafen |
| Aptiv |
| Harman International |
| DENSO |
| NXP Semiconductors |
| Infineon Technologies |
| Renesas Electronics |
| Others |
Pricing and Supply Chain Analysis
Automotive-grade silicon foundry utilization rates above ninety percent at TSMC, Samsung, and Intel Foundry Services concentrate hardware security module production in qualified facilities, simultaneously elevating price floors for uncertified gateway suppliers and compressing margins for commoditized embedded ECU tiers lacking cryptographic attestation chains.
Pricing Analysis
Certification level under ISO/SAE 21434 and UNECE R155 type approval creates the primary spread between premium domain gateway contracts and commodity embedded units. Three-tier pricing structure across certified systems houses, qualified modular suppliers, and uncertified component vendors dominates procurement. Cost compression in basic embedded gateways intensifies because chip shortage relief exposes these units to supply normalization and price erosion. Tier-1 integrators with captive semiconductor partnerships exhibit the least price sensitivity, while aftermarket retrofit suppliers face acute margin pressure from OEM single-source consolidation.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports, combined with container availability constraints on Asia-Europe trade lanes, amplify lead time uncertainty for hardware security module shipments from Taiwanese and South Korean foundries. Geographic supply concentration centers on Taiwan, South Korea, and Germany for automotive-grade silicon with AES-256 encryption engines. Raw material dependencies include silicon wafers, cryptographic IP cores, and automotive-grade packaging substrates. Single-source vulnerability at qualified foundries threatens supply continuity for UNECE R156-compliant secure boot architectures. Distribution runs through tier-1 systems houses with direct OEM platform engineering relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from software-defined vehicle architectures that could displace discrete gateway hardware with centralized compute virtualization, requiring proactive silicon-level capability deepening before design lock stabilization.
For Market Incumbents: Compound cryptographic firmware stack depth through backward integration into secure boot and rollback capabilities, neutralizing the threat from modular suppliers lacking UNECE R156 attestation chains. Anchor exclusive foundry capacity reservation at TSMC or Samsung for automotive-grade hardware security modules, securing supply continuity as ISO/SAE 21434 certification timelines compress. Prioritize domain gateway specialization for electric axle platforms where ZF Friedrichshafen has established specification influence.
For New Entrants and Emerging Players: Differentiate on post-quantum cryptographic accelerator preprocessing as NIST standards mature, capturing replacement cycle demand before incumbent hardware security module designs stabilize. Target the Chinese domestic OEM segment where MIIT cybersecurity mandates and localization imperatives create penetrable procurement windows for non-traditional suppliers. Lead with telematics gateway modules featuring cellular-connected over-the-air update capabilities, an application tier with less entrenched tier-1 control.
For Investors and Strategic Acquirers: Semiconductor-captive firmware specialists with ISO 26262 ASIL-D functional safety qualification represent the highest-conviction acquisition archetype for long-term exposure to zonal E/E architecture consolidation. Monitor NHTSA rulemaking finalization as the inflection signal for North American compliance-driven procurement acceleration comparable to European UNECE R155 implementation.
| Strategic Initiative | Industry Significance |
|---|---|
| Hardware Security Module Foundry Partnership | Secures qualified silicon capacity for UNECE R155 cryptographic attestation requirements. |
| Cryptographic Firmware Stack Acquisition | Accelerates backward integration into secure boot capabilities for European OEM programs. |
| Domain Gateway Platform Standardization | Reduces unit costs across electric axle deployments for German premium OEMs. |
| Post-Quantum Cryptography R&D Investment | Positions for NIST-standard replacement cycles before hardware security module design locks. |
| North American Regulatory Compliance Buildout | Captures NHTSA-mandated procurement windows mirroring European cybersecurity frameworks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, automotive production databases, and semiconductor supply disclosures to establish gateway procurement patterns and certification timelines. Primary interviews engaged Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and semiconductor foundry account managers. Secondary validation drew from UNECE R155/R156 implementation guidance, KBA type approval records, IHS Markit vehicle registration data, and SEC filings from automotive electronics conglomerates. Bottom-up unit deployment estimates triangulate against top-down market value reconstruction across the analysis window.
Segmentation dimensions modeled span product architecture, technology integration depth, functional application, and end-user procurement authority, with additional granularity on electric vehicle platform content per vehicle. CAGRs derive from regression-adjusted deployment trajectories incorporating OEM production schedules and regulatory compliance deadlines. Forecast inputs include hardware security module foundry capacity expansion plans and ISO/SAE 21434 certification pipeline visibility.
Material uncertainties — quantum-resistant cryptography standardization timelines, NHTSA rulemaking finalization, and automotive semiconductor demand cyclicality — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and tier-1 supplier consolidation velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Global IoT Digital Forensics Market
Cybersecurity
Europe Cloud DLP Market
Cybersecurity
Global Virtualization Security Market
Cybersecurity
Cloud Siem Market
Cybersecurity
Asia Pacific Cybersecurity Market
Cybersecurity
Finland Cybersecurity Market
Cybersecurity
Nordics Cybersecurity Market
Cybersecurity
Cloud DLP Market
Cybersecurity
Enterprise Network Firewall Market
Cybersecurity
Austria Cybersecurity Market
Cybersecurity
Global Network Security Firewall Market
Cybersecurity
Latin America IoT Security Market
Cybersecurity
Global Network Security Policy Management Market
Cybersecurity
Europe Data Exfiltration Market
Cybersecurity
Operational Technology Security Market
Cybersecurity
Malaysia Cybersecurity Market