
 Super Apps Market | 2026-2036
Super Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Super Apps Market Analytics
Capital intensity divergence between cloud-native infrastructure and legacy mobile stacks is rotating competitive advantage toward players with captive data center capacity. Tencent Holdings Ltd. leverages its WeChat ecosystem to anchor super app functionality across messaging, payments, and mini-programs. Alibaba Group Holding Ltd. sustains merchant density through Taobao and Alipay integration. Grab Holdings Limited competes across Southeast Asia by controlling on-the-ground logistics networks alongside its digital wallet.
Super apps consolidate multiple services—messaging, commerce, payments, and social interaction—within a single mobile interface, typically operating through modular architectures that embed third-party mini-programs via APIs and SDKs. Their primary commercial purpose is maximizing user lifetime value by reducing friction across daily digital transactions. E-commerce and financial services segments generate the deepest margin pools as merchant fees and payment float compound within closed-loop ecosystems. Cloud-based deployment models attract the fastest capacity expansion as hyperscalers offer dedicated sovereign cloud instances for regulated data processing.
China's SAMR enforces anti-monopoly and data security provisions that constrain cross-platform data sharing, while the EU AI Act and GDPR impose algorithmic transparency and consent requirements on European deployments. India's RBI mandates payment aggregator licensing that shapes how PhonePe Pvt Ltd. and competitors structure financial service modules. Stakeholders must monitor whether emerging interoperability mandates in Indonesia and Brazil force platform unbundling or reinforce ecosystem lock-in.
Market Dynamics
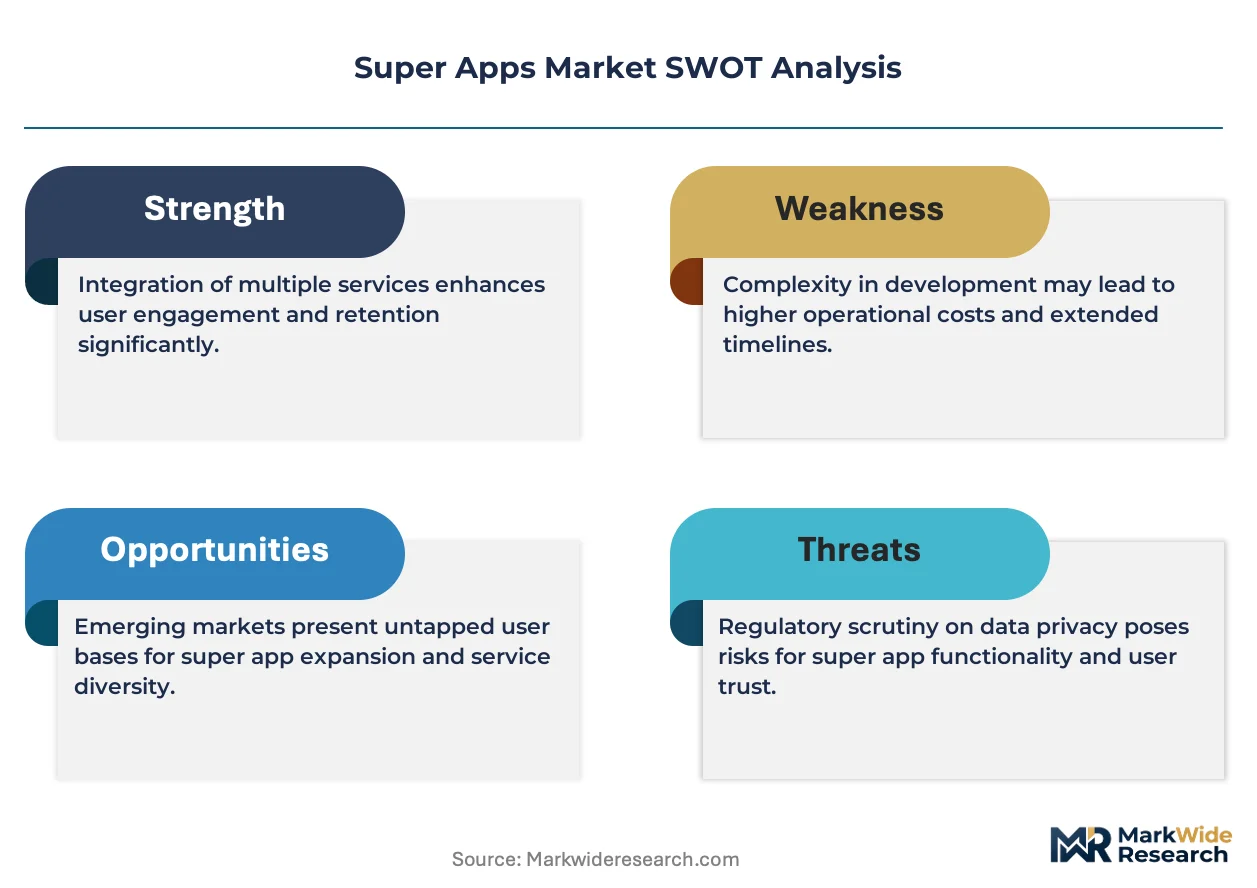
Cloud-native infrastructure investments are fragmenting competitive advantage away from legacy mobile architectures, forcing platforms to rebuild around sovereign data processing capabilities and modular API ecosystems.
Growth Catalysts
- Data Localization Mandates:China's MIIT and SAMR interoperability requirements force platform unbundling that creates new entry points for modular service providers.
- Mini-Program Ecosystems:Embedded third-party applications via standardized SDKs reduce customer acquisition costs while expanding addressable service categories.
- Southeast Asia:Indonesia's retail banking penetration gaps drive demand for integrated financial services within single-platform interfaces.
Market Restraints
- Hyperscaler Concentration:Cloud capacity constraints in regulated jurisdictions limit platform scaling velocity during demand surges.
- Algorithmic Transparency Requirements:The EU AI Act imposes explainability standards that increase compliance engineering overhead for recommendation engines.
- Payment Float Compression:Central bank digital currency pilots in multiple jurisdictions threaten closed-loop payment margin structures.
Strategic Opportunities
- Brazilian Open Finance:Central bank interoperability mandates create white space for foreign platforms to embed credit and insurance modules.
- Edge Computing Convergence:5G network slicing combined with on-device AI inference enables real-time personalization without cloud round-trips.
- Merchant Aggregator Licensing:India's RBI payment aggregator framework rewards compliant platforms with preferential settlement timelines.
Industry Challenges
- Legacy Core Banking Integration:Southeast Asian platforms struggle to reconcile real-time wallet transactions with batch-oriented bank reconciliation systems.
- Cross-Border Data Architecture:Divergent ASEAN data residency rules fragment user profile continuity across national boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Super Apps Market |
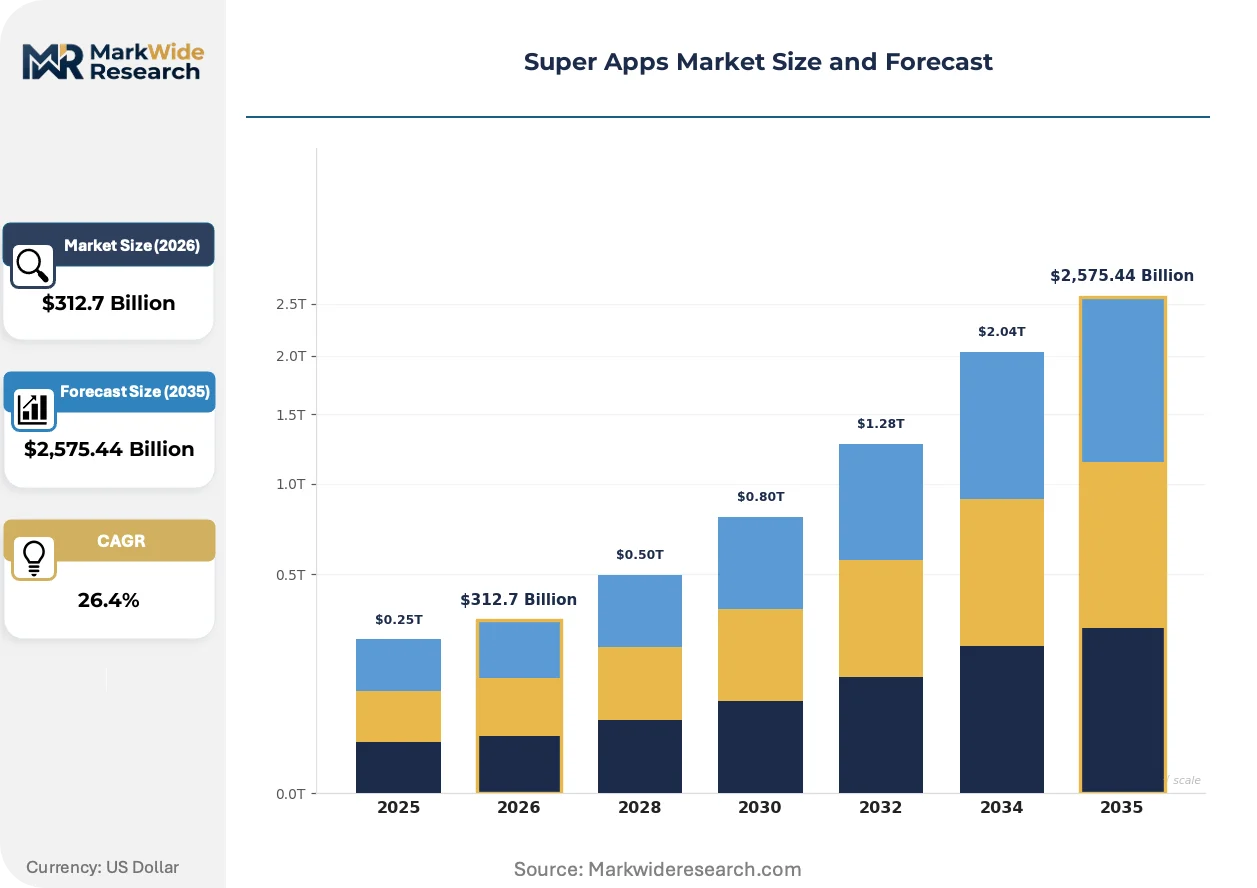
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $2,575.44 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Messaging, E-commerce, Financial Services, Social Media End User: Retail Customers, Businesses, Service Providers, Developers Deployment Model: Cloud-Based, On-Premises, Hybrid, Mobile Feature: Payment Integration, User Analytics, Customization, Third-Party APIs |
| Companies Covered | Alibaba Group Holding Ltd., Meituan, Tencent Holdings Ltd., GoTo Group, MercadoLibre, Ant Group Co., Ltd., Sea Limited, PhonePe Pvt Ltd., Grab Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Super Apps Market Evolving Landscape
Platform architectures are pivoting from monolithic stacks toward composable service layers, with regulatory pressure and infrastructure economics jointly determining which integration patterns survive.
Embedded finance middleware is fragmenting traditional banking relationships by inserting payment, lending, and insurance modules directly into non-financial user journeys. Ride-hailing and delivery platforms in Southeast Asia deploy these tools to capture transaction data that previously flowed through separate banking apps. The structural consequence is compression of standalone fintech customer lifetime value as super apps absorb primary financial touchpoints.
China's SAMR anti-monopoly enforcement constrains cross-platform data sharing, forcing ecosystem operators to rebuild recommendation engines on first-party data alone. Industrial consequence includes higher customer acquisition costs as lookalike audience targeting degrades. Gaming and social commerce verticals within WeChat respond by deepening in-app behavioral tracking to compensate for external data loss.
Merchant onboarding patterns are compressing as platforms compete for supply-side density through instant KYC and automated underwriting. Food delivery aggregators in Indonesia now activate restaurant partners within hours versus days, displacing traditional sales-led acquisition. This behavioral shift concentrates most visibly in high-fragmentation service categories where platform control over supply determines consumer choice architecture.
Super Apps Market Segmentation
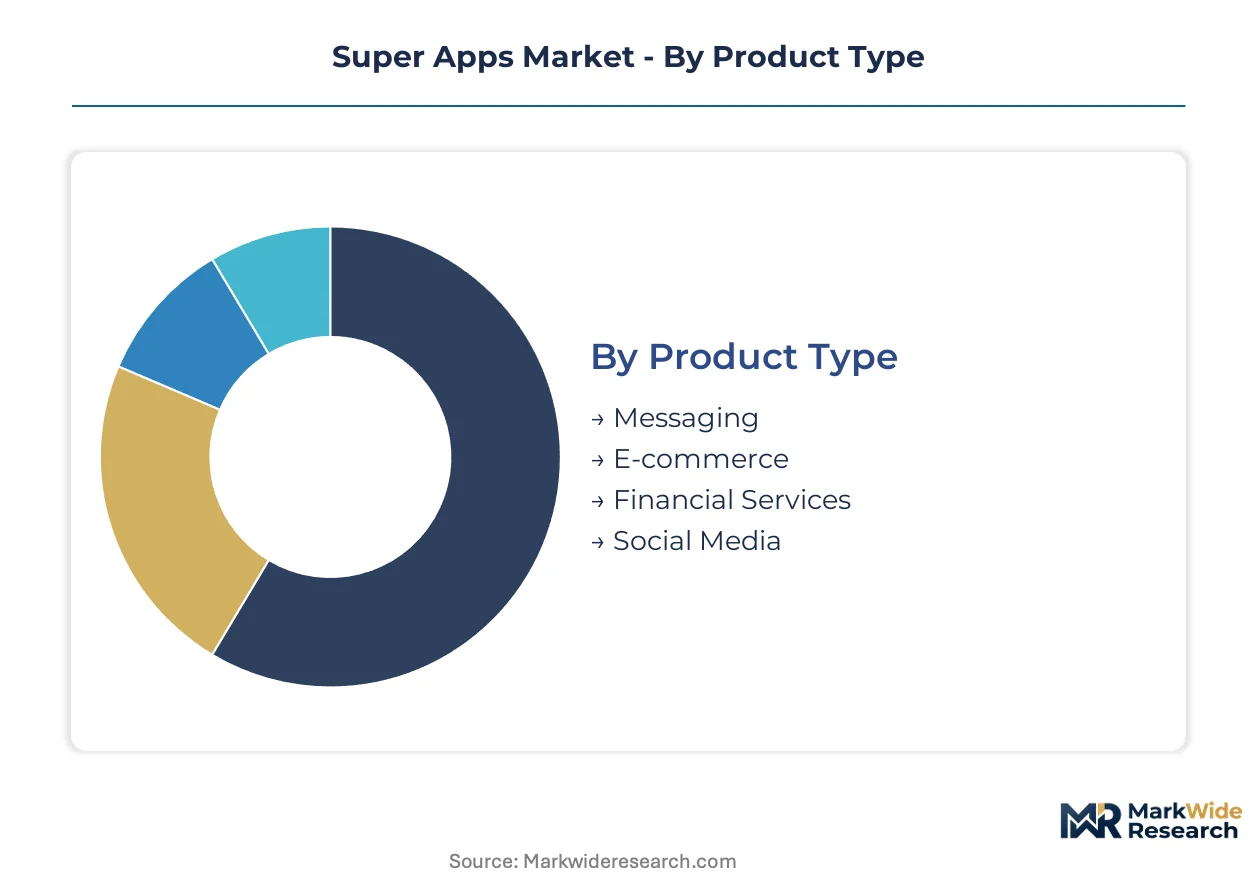
Super apps monetize through differential margin capture across service modules, making segment-level profitability analysis essential for platform architecture decisions. Deployment models and feature stacks determine sovereign compliance costs, while end-user mix shapes customer acquisition economics.
Product Type:
Margin pools concentrate in transaction-heavy modules where payment float and merchant fees compound within closed-loop ecosystems.
- Messaging:Core user engagement layer with embedded mini-program portals. Demand clusters in China and Southeast Asia where WeChat and LINE anchor daily communication habits. Network effects lock in retention but direct monetization remains secondary to ecosystem enablement.
- Financial Services:Highest-margin module combining digital wallets, lending, and insurance distribution. Indonesia's retail banking penetration gaps drive embedded finance adoption through GoPay and OVO integration. Regulatory licensing requirements create moats against unlicensed competitors.
- E-commerce:Merchant density generates transaction fees and advertising inventory. Taobao's integration with Alipay demonstrates closed-loop commerce-payment synergy.
- Social Media:Content feeds drive engagement minutes but monetize indirectly through advertising and live commerce conversion.
Financial Services holds installed capacity. E-commerce is rotating up the share rankings.
End User:
Customer lifetime value spreads widest across retail segments, with enterprise and developer tiers offering lower friction but higher contract values.
- Retail Customers:Primary revenue base for transaction fees and payment float. Southeast Asian urban populations consolidate daily digital activities—ride-hailing, food delivery, bill payments—within single interfaces. India's UPI infrastructure accelerates wallet adoption among price-sensitive users.
- Businesses:Merchant onboarding concentrates in high-fragmentation categories. Indonesian food delivery platforms activate restaurant partners through instant KYC, compressing sales cycles from days to hours.
- Service Providers:Logistics and fulfillment networks require real-time API integration for order routing and inventory synchronization.
- Developers:Mini-program ecosystems reduce customer acquisition costs through standardized SDK deployment. WeChat's developer tools demonstrate platform-scale third-party service embedding.
Retail Customers dominates transaction volume. Businesses is expanding most quickly as merchant acquisition intensifies.
Deployment Model:
Sovereign data processing requirements are fragmenting infrastructure choices across regulated jurisdictions.
- Cloud-Based:Hyperscaler partnerships enable elastic capacity scaling. China's MIIT data localization mandates force dedicated sovereign cloud instances for user data processing. AWS, Azure, and Alibaba Cloud compete for platform workloads.
- Hybrid:Combines edge responsiveness with centralized analytics. 5G network slicing supports real-time personalization without full cloud dependency.
- On-Premises:Legacy financial institutions maintain captive data centers for core banking integration. Southeast Asian platforms struggle with batch-oriented reconciliation systems.
- Mobile:On-device inference reduces latency for biometric authentication and recommendation engines. Edge AI chips enable offline functionality in bandwidth-constrained environments.
Cloud-Based carries current infrastructure investment. Hybrid is climbing the fastest as latency requirements tighten.
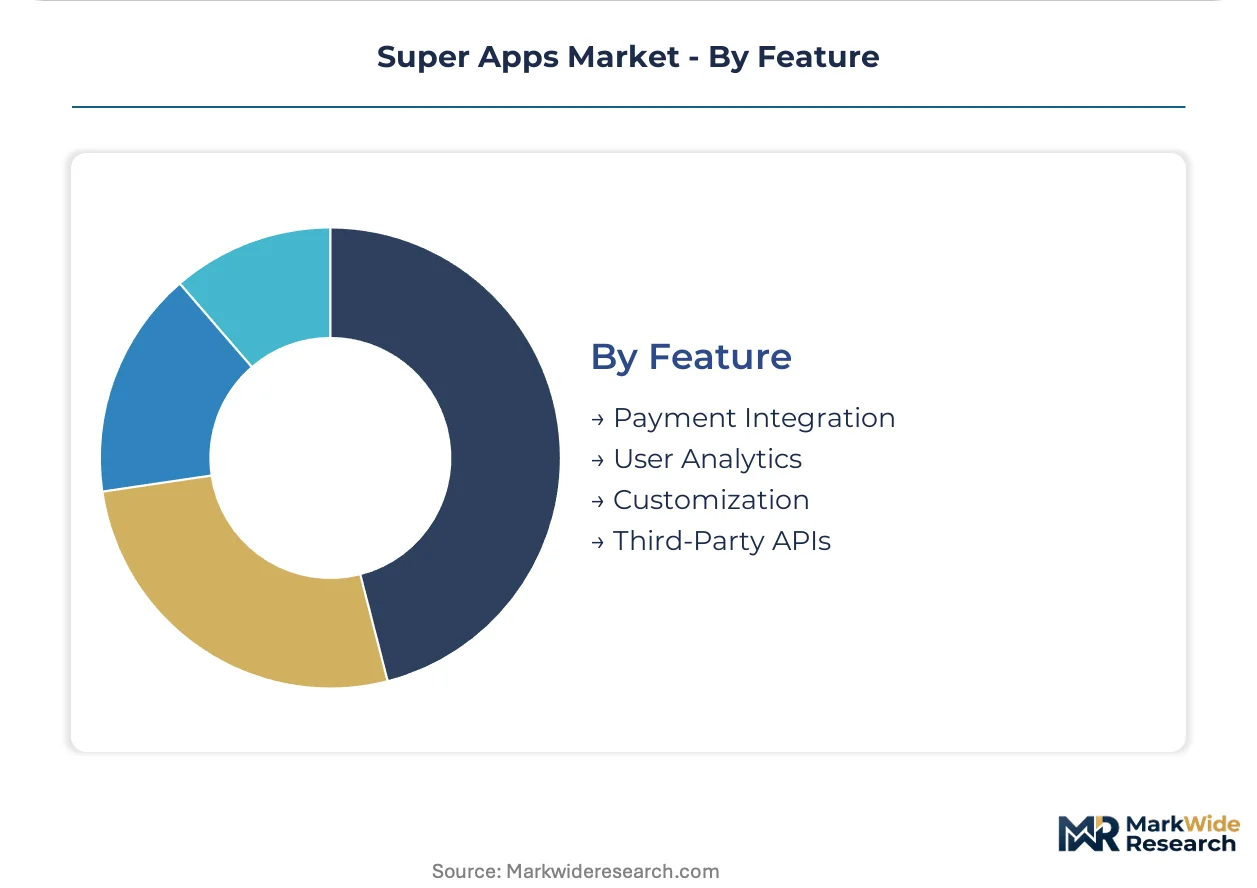
Feature:
Modular capability integration determines platform extensibility and third-party ecosystem depth.
- Payment Integration:Closed-loop wallet architectures capture transaction data and merchant relationships. India's RBI payment aggregator licensing rewards compliant platforms with preferential settlement timelines.
- Third-Party APIs:Standardized interfaces embed external services without native development. Mini-program ecosystems reduce time-to-market for new service categories.
- User Analytics:First-party behavioral tracking compensates for cross-platform data sharing restrictions under China's SAMR enforcement.
- Customization:White-label configurations enable regional adaptation and enterprise deployments. Modular theming supports brand differentiation without core architecture changes.
Payment Integration anchors revenue generation. Third-Party APIs shows the steepest expansion trajectory as ecosystem competition intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in digital services reshape competitive positioning across major economies. Capital flows concentrate where regulatory frameworks permit cross-border data processing and mini-program ecosystem expansion. Platform operators navigate divergent compliance costs while scaling modular service architectures.
China
Domestic platform saturation drives outbound technology licensing and infrastructure exports. MIIT and SAMR enforce data localization mandates that fragment cross-border architecture planning. Shenzhen and Hangzhou anchor super app development clusters where WeChat and Alipay mini-program ecosystems absorb third-party service integration.
Indonesia
Retail banking penetration gaps generate import demand for embedded financial services modules. Bank Indonesia payment system regulations shape wallet licensing requirements for foreign platform entrants. Jakarta and Surabaya concentrate ride-hailing and food delivery platform competition between GoTo Group and Grab Holdings Limited.
India
UPI infrastructure exports create template demand across emerging markets seeking real-time payment interoperability. RBI payment aggregator licensing mandates force modular restructuring of financial service modules. Bangalore and Mumbai host developer ecosystems building mini-program SDKs for platform embedding.
Brazil
Open Finance regulatory frameworks attract foreign platform investment seeking credit and insurance module expansion. Central bank interoperability mandates create entry pathways for super app operators from other geographies. São Paulo anchors fintech-platform convergence where MercadoLibre deepens financial service integration.
Singapore
Regional headquarters functions export compliance architecture and data governance frameworks across Southeast Asian operations. Monetary Authority of Singapore digital banking licenses attract platform operators seeking regulatory credibility. The city-state concentrates venture capital flows and partnership negotiations between Chinese and Southeast Asian platform operators.
Super Apps Market Competitive Landscape
Concentration sits with ecosystem operators possessing captive payment infrastructure and mini-program developer networks. Market structure tilts toward integrated platforms controlling multiple service verticals rather than standalone point solutions. Three archetypes dominate: messaging-origin platforms extending into financial services, e-commerce operators embedding payment loops, and logistics-first players aggregating on-demand services. Competitive moves center on merchant acquisition velocity and sovereign cloud deployment partnerships.
Within the ecosystem-origin tier, Tencent Holdings Ltd. and Alibaba Group Holding Ltd. represent the messaging-to-payments and commerce-to-payments expansion paths respectively. Grab Holdings Limited occupies a position exemplifying logistics-network-first platform development. These three anchors demonstrate how divergent starting points converge on similar modular service architectures through API ecosystem investment.
| Leading Market Players |
|---|
| Alibaba Group Holding Ltd. |
| Meituan |
| Tencent Holdings Ltd. |
| GoTo Group |
| MercadoLibre |
| Ant Group Co., Ltd. |
| Sea Limited |
| PhonePe Pvt Ltd. |
| Grab Holdings Limited |
| Others |
Value Network & Pricing Analysis
China's SAMR data localization mandates gate both cloud infrastructure qualification and sovereign deployment pricing tiers simultaneously, forcing platforms to absorb compliance premiums or segment offerings by data residency tier. This regulatory architecture compresses margins for non-compliant operators while creating pricing power for hyperscalers with captive in-country capacity.
Pricing Analysis
Industrial OEM buyers anchor subscription-tiered SaaS pricing across enterprise deployment modules, with financial services APIs commanding premium positioning over messaging infrastructure. Price differentiation rests on certification depth under India's RBI payment aggregator framework and transaction volume scale across merchant settlement tiers. Cost compression in mid-market cloud instances is intensifying because hyperscaler competition in Jakarta and Singapore is expanding elastic capacity supply. Small and medium merchant segments exhibit highest price sensitivity, while multinational enterprise contracts show lowest elasticity due to compliance bundling requirements.
Supply Chain Analysis
China and India anchor super app development and cloud infrastructure supply, with Singapore concentrating regional headquarters and compliance architecture functions. Raw material dependencies span edge AI chipsets from Taiwan, sovereign cloud server capacity from domestic hyperscalers, and mini-program SDK tooling from Bangalore and Shenzhen developer ecosystems. Single-source vulnerability concentrates in MIIT-certified data center operators where localization mandates restrict vendor choice. Distribution runs through direct hyperscaler partnerships for cloud-based deployments and licensed system integrators for hybrid on-premises configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Super apps constitute a high-growth disruption as central bank digital currency pilots and open finance mandates fragment legacy payment float structures. This regulatory-technological inflection compresses closed-loop margin pools while expanding modular service embedding opportunities.
For Market Incumbents: Consolidate merchant density through instant KYC automation and captive logistics network control in Jakarta and Surabaya. Deepen backward integration into sovereign cloud capacity to defend against hyperscaler pricing power erosion. Prioritize RBI and Bank Indonesia licensing maintenance as regulatory moats against unlicensed wallet competitors. For New Entrants and Emerging Players: Differentiate on embedded finance middleware for Brazilian Open Finance credit and insurance modules where interoperability mandates create white space. Target Indonesian retail banking penetration gaps with ride-hailing origin platforms. Pursue developer ecosystem partnerships rather than native feature builds to compress time-to-market for mini-program deployment. For Investors and Strategic Acquirers: EU AI Act algorithmic transparency requirements reshape the acquisition landscape by elevating compliance engineering capabilities as valuation premiums. Frame long-term viability around platforms with modular API architectures capable of absorbing regulatory fragmentation across ASEAN data residency rules. Monitor central bank digital currency pilot expansion as the signal to watch for payment float compression inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Mini-Program Ecosystem Expansion | Reduces customer acquisition costs through standardized SDK deployment across WeChat and LINE developer networks. |
| Sovereign Cloud Partnership | Secures MIIT-compliant data processing capacity for Chinese user bases against localization mandate penalties. |
| Payment Aggregator Licensing | Unlocks preferential RBI settlement timelines for PhonePe and competitors in Indian financial services modules. |
| Instant KYC Automation | Compresses Indonesian merchant onboarding from days to hours in food delivery platform competition. |
| Edge Computing Convergence | Enables real-time personalization via 5G network slicing without cloud round-trip latency penalties. |
Research Methodology
Cross-validation between primary executive interviews and secondary regulatory filings anchors the qualitative findings across the analysis. Platform strategy leads, cloud infrastructure procurement officers, and regulatory compliance directors at GoTo Group, Grab Holdings, and Tencent Holdings provided operational perspective. Secondary sources include MIIT and SAMR enforcement notices, RBI payment aggregator licensing records, Bank Indonesia payment system regulations, and hyperscaler sovereign cloud capacity disclosures. Bottom-up transaction volume modeling and top-down macroeconomic anchoring complete the triangulation.
Sensitivity analysis frameworks stress-test projections across deployment model adoption curves and regulatory enforcement intensity variations. Segmentation dimensions span product type modules, end-user archetypes, deployment infrastructure choices, and feature integration depth. CAGRs derive from installed base expansion rates and average revenue per user trajectories across financial services and e-commerce margin pools. Mini-program ecosystem velocity and central bank digital currency pilot timelines serve as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained regulatory fragmentation and cloud capacity expansion conditions would require recalibration. Forecasts reflect assumptions regarding interoperability mandate implementation pace and merchant acquisition cost trajectories. Recalibration cycles align with material shifts in data localization enforcement and payment system regulatory frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Quality Process Management Application Market
Digital Solutions
Interactive Kiosk Market
Digital Solutions
Saudi Arabia ICT Market
Digital Solutions
Online Laundry Services Market
Digital Solutions
Europe Electronic Contract Manufacturing and Design Services Market
Digital Solutions
Saudi Arabia Digital Twin Market
Digital Solutions
Digital Signage Services Market
Digital Solutions
Asia-Pacific Multichannel Order Management Market
Digital Solutions
Australia Cloud OSS BSS Market
Digital Solutions
Virtual Hiring Tools Market
Digital Solutions
AI Infrastructure Solutions Market
Digital Solutions
Data Extraction Market
Digital Solutions
Australia Digital Marketing Software Market
Digital Solutions
Digital Manufacturing Software Market
Digital Solutions
Procure-To-Pay Solutions Market
Digital Solutions
Restaurant POS Terminals Market