
 Philippines Data Center Physical Security Market | 2026-2036
Philippines Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Data Center Physical Security Market Insights
Distribution through systems integrators and value-added resellers is fragmenting as end users demand direct vendor relationships for complex multi-layer deployments. Honeywell International Inc. leverages its building automation heritage to bundle environmental and physical security controls. Bosch Sicherheitssysteme GmbH anchors premium surveillance installations through specialized channel partners serving financial institutions. Axis Communications AB competes on open-platform architecture that reduces vendor lock-in for cloud service providers scaling rapidly across the archipelago.
Philippines Data Center Physical Security encompasses perimeter barriers, biometric access control, video surveillance with analytics, and intrusion detection systems engineered to protect critical IT infrastructure from unauthorized physical access. These systems typically integrate IP-based cameras with minimum 4K resolution, multi-factor biometric readers, and centralized physical security information management platforms that correlate events across distributed facilities. Surveillance Systems leads spending as hyperscale operators mandate 24/7 visual coverage with video analytics for behavioral anomaly detection. Access Control grows fastest as facial recognition and palm-vein biometric systems replace legacy card-based entry across new builds in Cavite and Laguna. Managed Services captures expanding margin pools as operators outsource monitoring to specialists rather than staffing in-house security operations centers.
The Department of Information and Communications Technology enforces data center classification standards that prescribe minimum physical security tiers based on facility criticality. BIS and ISO 27001 certification requirements shape procurement specifications, particularly for financial institutions under Bangko Sentral ng Pilipinas oversight. Stakeholders must monitor how the DICT's evolving infrastructure codes and local government permitting for disaster-resilient designs will reshape capital deployment priorities across the Philippine island groups.
Market Dynamics
Cloud service providers are consolidating facility footprints across Luzon while tightening physical security specifications to meet DICT infrastructure codes. This buyer concentration is compressing vendor margins and forcing systems integrators to cede direct relationships to specialized physical security OEMs.
Growth Catalysts
- DICT Cybersecurity Plan:Government mandates for data center classification standards prescribe minimum physical security tiers based on facility criticality. Operators must upgrade perimeter barriers and biometric access controls to achieve compliance certification.
- Hyperscale corridor expansion:Carrier-neutral facilities clustering in Metro Manila's industrial zones demand 24/7 visual coverage with video analytics. These operators specify IP-based cameras with minimum 4K resolution and centralized physical security information management platforms.
- Facial recognition deployment:Palm-vein biometric systems are replacing legacy card-based entry across new builds in Cavite and Laguna. This technology shift reduces tailgating incidents and eliminates credential sharing among contractor workforces.
Market Restraints
- Specialized labor scarcity:Certified technicians capable of integrating multi-factor biometric readers with legacy building management systems command premium wages. Training pipelines for IP-based surveillance analytics remain underdeveloped across Philippine technical institutes.
- Import dependency for sensors:High-resolution thermal cameras and edge-computing video analytics processors ship primarily from East Asian manufacturing hubs. Foreign exchange volatility and port congestion in Manila Bay create input cost instability for local systems integrators.
- Power infrastructure gaps:Unreliable grid supply in secondary island groups outside Luzon forces redundant UPS and generator investments that consume physical security capex budgets. Disaster-resilient designs mandated by local permitting add further construction complexity.
Strategic Opportunities
- Managed security services:Operators are outsourcing 24/7 monitoring to specialists rather than staffing in-house security operations centers. This creates recurring revenue pools for vendors capable of delivering remote video verification and alarm response across distributed archipelago facilities.
- Bangko Sentral ng Pilipinas oversight expansion:Financial institutions face tightening BIS and ISO 27001 certification requirements that shape procurement specifications for physical access controls. Premium surveillance installations serving banking data centers command higher margin profiles than generic commercial deployments.
- Biometric-video convergence:Integration of facial recognition databases with behavioral anomaly detection algorithms enables predictive threat assessment. Cloud service providers scaling rapidly across the archipelago prioritize these unified platforms to reduce vendor lock-in.
Industry Challenges
- Multi-vendor integration complexity:Hyperscale operators demand open-platform architecture that correlates events across perimeter barriers, intrusion detection systems, and environmental controls. Legacy proprietary protocols from building automation heritage systems create interoperability friction during facility retrofits.
- Certification timeline compression:BIS and ISO 27001 audit cycles for financial institution data centers extend 12-18 months. Vendor documentation gaps and witness testing requirements delay revenue recognition for physical security deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Data Center Physical Security Market |
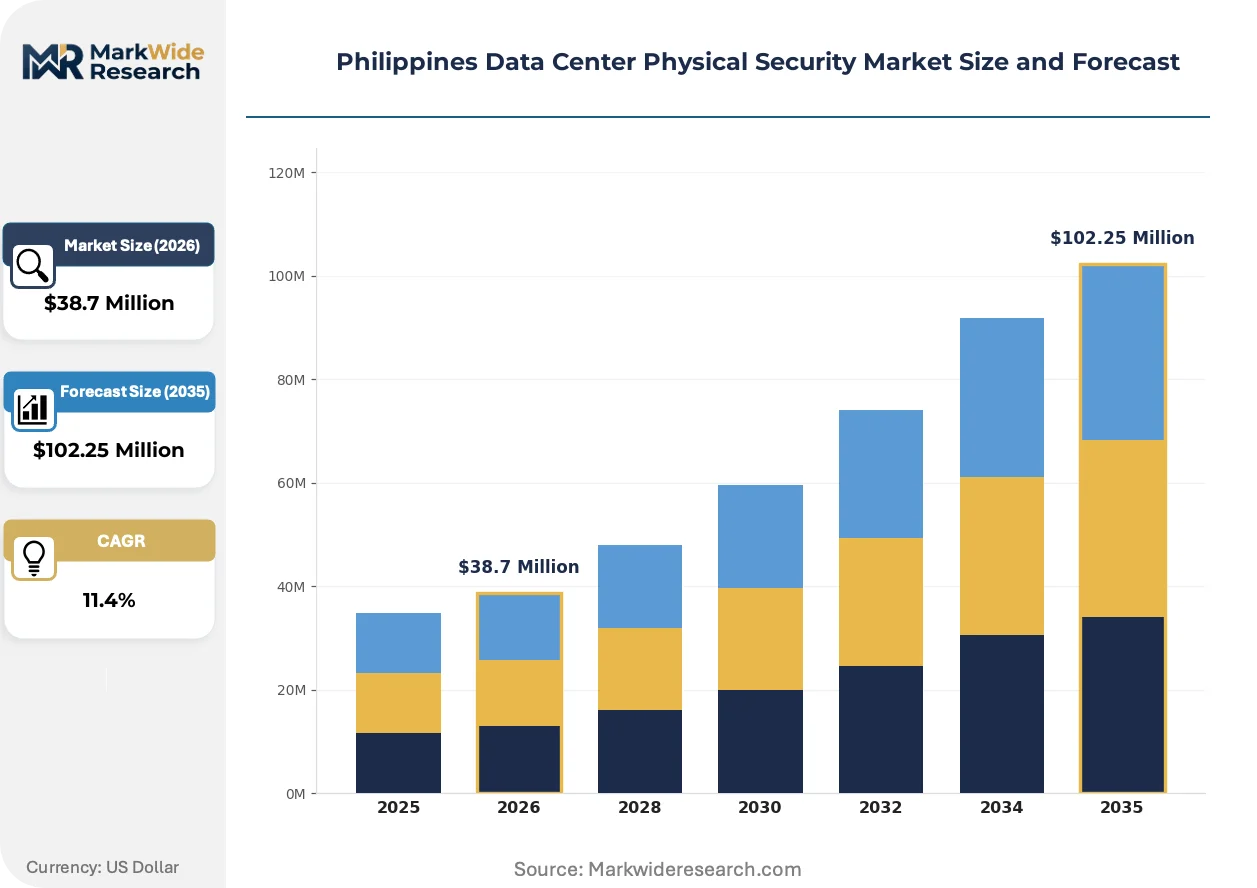
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $102.25 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Security Type: Access Control, Surveillance Systems, Intrusion Detection, Perimeter Security Technology: Video Analytics, Biometric Systems, RFID, Smart Locks End User: Telecommunications, Financial Institutions, Cloud Service Providers, Government Facilities Installation Type: On-Premise, Remote Monitoring, Mobile Integration, Managed Services |
| Companies Covered | Axis Communications AB, ABB Ltd, Bosch Sicherheitssysteme GmbH, Honeywell International Inc., Johnson Controls International plc, Siemens AG, Schneider Electric SE, Cisco Systems Inc., Hangzhou Hikvision Digital Technology Co., Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Data Center Physical Security Market Trends and Innovations
Physical security systems are converging with IT infrastructure management platforms, collapsing the traditional separation between facility operations and cybersecurity teams. This integration is redefining procurement criteria and technical specifications across Philippine data center builds.
Artificial intelligence-powered video analytics now process behavioral patterns in real-time at the network edge, eliminating latency-dependent cloud processing for critical threat detection. Hyperscale operators in Metro Manila's industrial corridors are deploying these systems across 100% of new facility footprints. Static rule-based motion detection is rendering obsolete as machine learning models reduce false alarm rates below 2% in 24/7 operational environments.
The Department of Information and Communications Technology is enforcing progressive data center classification standards that prescribe minimum physical security tiers based on facility criticality. Tier III and Tier IV facilities must demonstrate redundant biometric access controls and 90-day video retention with forensic-grade chain of custody. Financial institutions under Bangko Sentral ng Pilipinas oversight are accelerating compliance investments ahead of announced audit deadline expansions.
Buyer organizations are consolidating vendor relationships and demanding direct OEM engagement for complex multi-layer deployments. Systems integrators and value-added resellers are losing margin to specialized physical security vendors capable of delivering integrated environmental and access control platforms. This channel disintermediation is most visible among cloud service providers scaling facility footprints across Cavite, Laguna, and Bulacan provinces.
Philippines Data Center Physical Security Market Segmentation
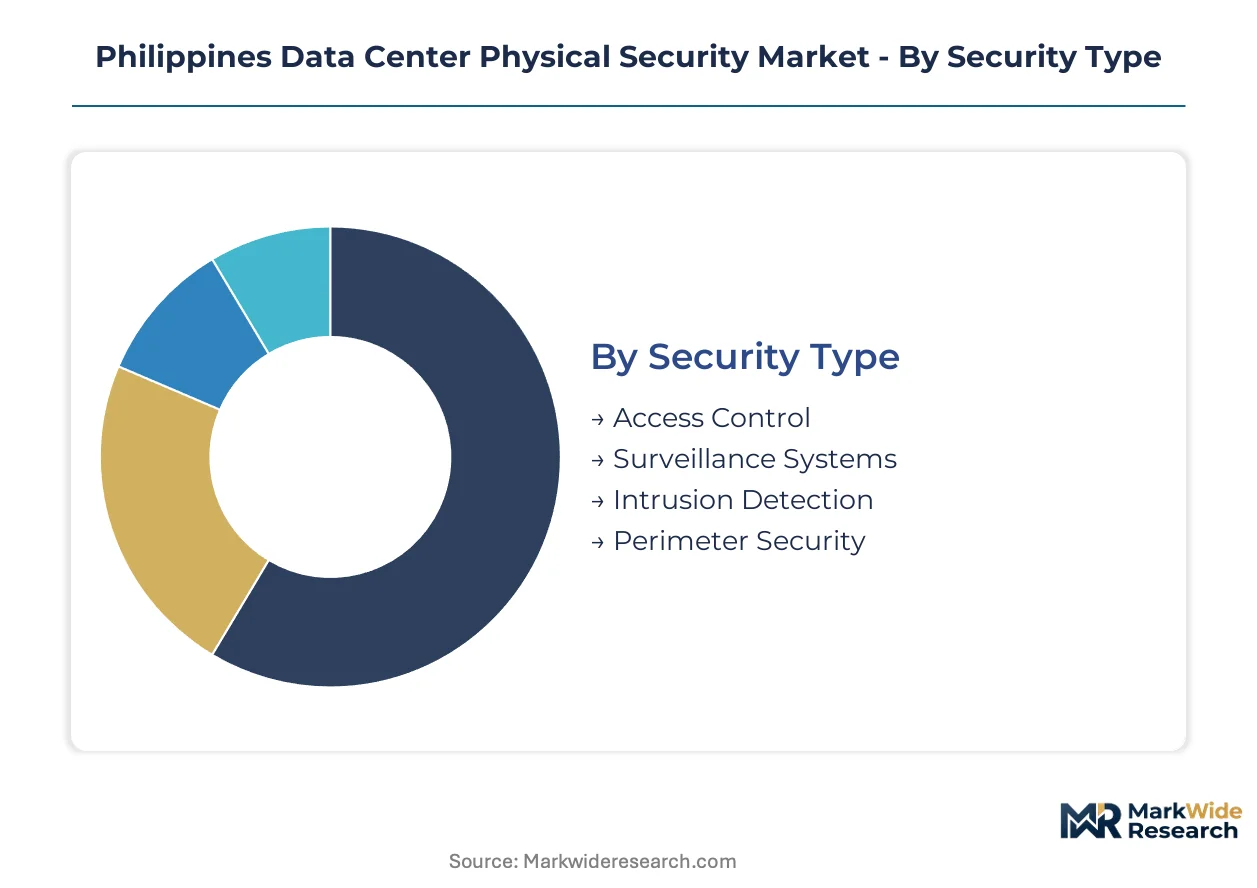
Physical security procurement in Philippine data centers follows distinct technology and service configurations that reflect facility criticality tiers, compliance mandates, and operational scale. Understanding how demand fragments across these dimensions clarifies where vendor resources concentrate and where margin pools shift.
Security Type:
Cost tier differentiation separates budget-conscious retrofits from hyperscale greenfield specifications requiring integrated multi-layer platforms.
- Surveillance Systems:IP-based camera networks with minimum 4K resolution and edge-computing analytics processors deliver 24/7 visual coverage. Hyperscale operators in Metro Manila's industrial corridors mandate these for behavioral anomaly detection with machine learning models that suppress false alarms below operational thresholds.
- Access Control:Multi-factor biometric readers using facial recognition and palm-vein authentication replace legacy card-based entry. New builds in Cavite and Laguna deploy these to eliminate credential sharing and tailgating incidents among contractor workforces.
- Intrusion Detection:Sensor networks combining volumetric, seismic, and fiber-optic cable detection protect server hall perimeters. Financial institutions under Bangko Sentral ng Pilipinas oversight specify these for Tier III and Tier IV certification compliance.
- Perimeter Security:Physical barriers including crash-rated bollards, anti-climb fencing, and vehicle trap systems secure facility exteriors. Provincial deployments outside Luzon prioritize these given extended emergency response times.
Surveillance Systems holds installed capacity. Access Control is rotating up the share rankings.
Technology:
Application maturity varies sharply, with some technologies already standard in new builds while others remain pilot-stage for specialized threat scenarios.
- Biometric Systems:Palm-vein and facial recognition hardware integrated with physical security information management platforms enable centralized credential administration. Cloud service providers scaling across the archipelago prioritize these for reduced vendor lock-in and rapid provisioning.
- Video Analytics:AI-powered behavioral pattern recognition running at the network edge eliminates cloud-processing latency for critical detection. Metro Manila hyperscale facilities deploy these across 100% of new footprints, rendering static motion detection obsolete.
- RFID:Legacy credential technologies persist in brownfield retrofits where biometric upgrade budgets face compression. Government facilities with extended procurement cycles represent residual demand concentration.
- Smart Locks:Network-enabled electromechanical locks with audit trail capabilities serve secondary access points and cabinet-level security. These gain traction in colocation environments requiring granular tenant isolation.
Biometric Systems command premium positioning. Video Analytics is climbing the fastest.
End User:
Customer type determines specification stringency, with financial and cloud sectors driving technology frontier adoption while government and telecom segments lag on refresh cycles.
- Cloud Service Providers:Hyperscale operators consolidating facility footprints across Luzon demand open-platform architecture correlating events across perimeter, access, and environmental controls. Direct OEM relationships displace systems integrator channels for these buyers.
- Financial Institutions:Banks and payment processors face tightening BIS and ISO 27001 certification requirements that shape procurement specifications. Audit cycles extending 12-18 months create documentation and witness testing demands that delay vendor revenue recognition.
- Telecommunications:Carrier-neutral facilities cluster in Metro Manila's hyperscale corridor with standardized security tiers. These operators balance compliance against capex constraints in secondary island groups where grid reliability forces redundant power investments.
- Government Facilities:DICT-mandated classification standards prescribe minimum physical security tiers based on facility criticality. Public procurement timelines and budget approval processes extend deployment schedules versus private sector counterparts.
Cloud Service Providers anchor technology adoption. Financial Institutions are gaining compliance-driven momentum.
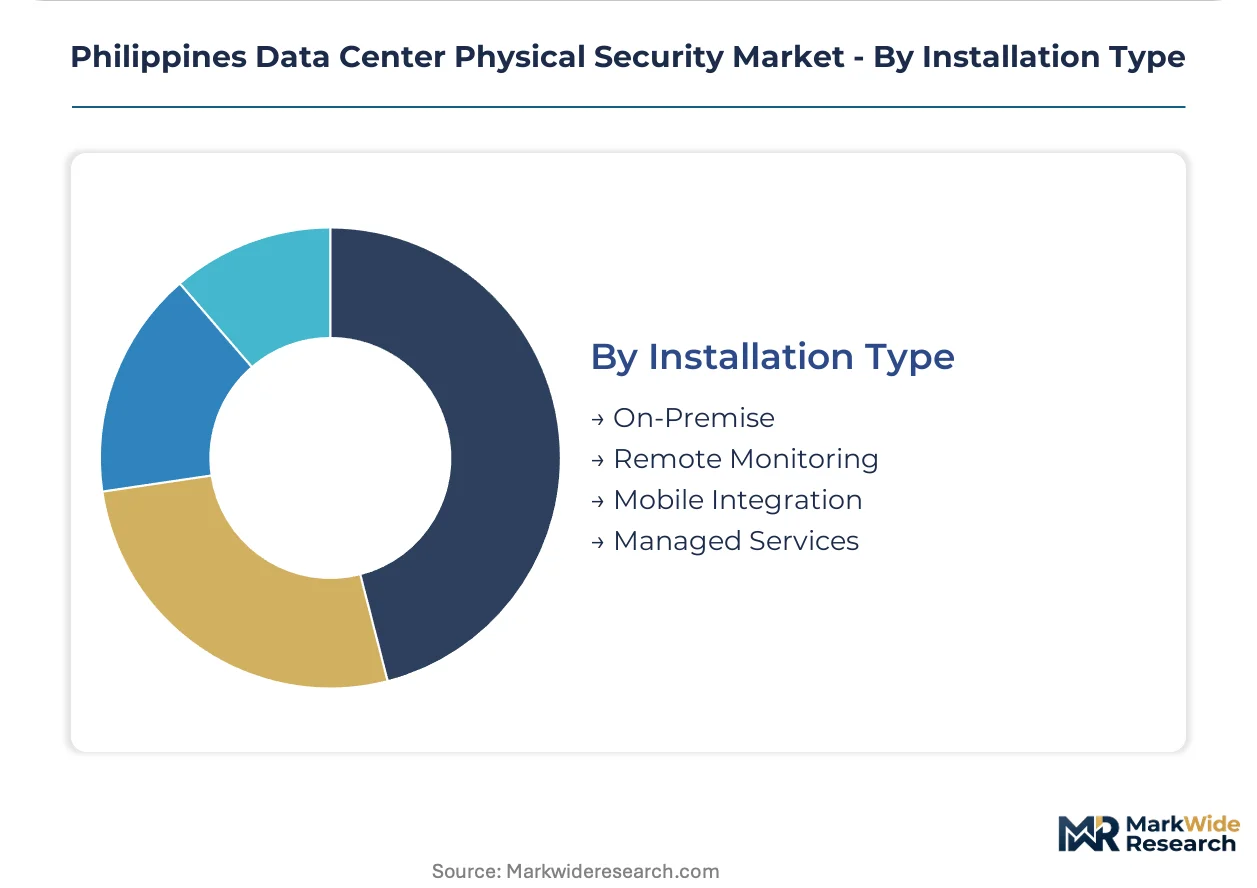
Installation Type:
Supply concentration in managed and remote offerings reflects labor scarcity and the archipelago's geographic complexity.
- Managed Services:Outsourced 24/7 monitoring and alarm response delivered by specialists replaces in-house security operations center staffing. Recurring revenue pools expand for vendors capable of remote video verification across distributed facilities spanning multiple island groups.
- Remote Monitoring:Centralized surveillance oversight with cellular and satellite backhaul connectivity serves secondary locations outside Luzon. These installations address the certified technician shortage that commands premium wages for on-site personnel.
- On-Premise:Traditional staffed security operations with local video walls and guard force deployment persists in Tier IV facilities requiring immediate physical response capability. Capital intensity limits expansion to highest-criticality installations.
- Mobile Integration:Smartphone-enabled credentialing and alert notification extends physical security reach to distributed operations teams. These layers supplement rather than replace hardened infrastructure in regulated environments.
Managed Services captures expanding margin pools. Remote Monitoring is advancing most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Batangas-Manila-Cavite port corridor underwrites Luzon's dominance in Philippine data center infrastructure, with submarine cable landings clustering at landing stations that anchor hyperscale facility placement decisions.
Metro Manila
Carrier-neutral facilities concentrate in Makati, Taguig, and Quezon City industrial zones where DICT-mandated Tier III and Tier IV classifications drive biometric access control deployment. Bangko Sentral ng Pilipinas oversight tightens BIS and ISO 27001 compliance timelines for financial institutions clustering in the Ortigas and Bonifacio Global City corridors.
Cavite
Greenfield hyperscale builds in General Trias and Carmona deploy palm-vein biometric systems replacing legacy card-based entry. The Department of Information and Communications Technology infrastructure codes prescribe redundant perimeter barriers for new facilities within this Southern Luzon manufacturing belt.
Laguna
Calamba and Santa Rosa host cloud service provider expansions demanding 24/7 video analytics with machine learning false alarm suppression. Local government permitting for disaster-resilient designs adds construction complexity to security system integration timelines.
Bulacan
Provincial data center investments in Malolos and Meycauayan prioritize perimeter security given extended emergency response times. Unreliable grid supply forces redundant UPS investments that compete for physical security capex budgets in this Northern Luzon corridor.
Philippines Data Center Physical Security Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying cameras, sensors, and biometric readers. The vendor base organizes around three strategic archetypes: building automation heritage players bundling environmental and physical controls, specialized surveillance OEMs serving premium financial installations, and open-platform architects reducing vendor lock-in for hyperscale operators. Competitive moves concentrate on direct OEM engagement displacing systems integrator channels, and managed security services outsourcing capturing recurring revenue pools.
Among Sweden-based platform architects, Axis Communications AB exemplifies open-platform positioning that reduces interoperability friction for cloud service providers scaling across the archipelago. Bosch Sicherheitssysteme GmbH represents the specialized surveillance tier anchoring premium installations through channel partners. Honeywell International Inc. occupies the building automation convergence position, leveraging heritage controls integration for bundled environmental and physical security deployments.
| Leading Market Players |
|---|
| Axis Communications AB |
| ABB Ltd |
| Bosch Sicherheitssysteme GmbH |
| Honeywell International Inc. |
| Johnson Controls International plc |
| Siemens AG |
| Schneider Electric SE |
| Cisco Systems Inc. |
| Hangzhou Hikvision Digital Technology Co., Ltd |
| Others |
Pricing and Supply Chain Analysis
Manila Bay port congestion and foreign exchange volatility create cost instability that compresses margins for local systems integrators while concentrating pricing power with specialized physical security OEMs capable of direct hyperscale engagement. This logistics chokepoint feeds into a market where procurement choices increasingly favor bundled environmental-access control platforms over discrete component sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates DICT Tier IV-certified installations from Tier II retrofits and generic commercial deployments. Price differentiation hinges on certification grade and after-sales service bundling, with financial institutions under Bangko Sentral ng Pilipinas oversight absorbing premium tiers for audit compliance. Cost compression in the standard tier is intensifying because cloud service providers are consolidating vendor relationships and demanding direct OEM pricing. Government facilities with extended procurement cycles exhibit highest price sensitivity, while hyperscale operators prioritize performance over unit cost.
Supply Chain Analysis
Upstream feedstock for high-resolution thermal cameras and edge-computing video analytics processors draws from South Korea, Japan, and Taiwan manufacturing hubs. Local systems integrators source multi-factor biometric readers and IP-based surveillance hardware from these concentrated supply bases. Single-source vulnerability around specialized sensor fabrication creates exposure to tariff fluctuations and maritime logistics disruptions. Distribution runs through systems integrators and value-added resellers, though this channel is fragmenting as end users demand direct vendor relationships for complex multi-layer deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines data center physical security market rewards vendors who control scarce integration capabilities across biometric-video convergence platforms, while penalizing those dependent on commoditized component resale without certified installation expertise.
For Market Incumbents: Harden defensible positions by acquiring certified technician training pipelines at Philippine technical institutes to lock in labor scarcity premiums. Deepen backward integration into physical security information management software to reduce interoperability friction during hyperscale facility retrofits. Prioritize DICT Tier III and Tier IV pre-certification documentation to compress audit timelines for financial institution deployments. For New Entrants and Emerging Players: Secondary island groups outside Luzon represent the most penetrable entry point, where unreliable grid supply and extended emergency response times create demand for redundant perimeter security and remote monitoring solutions. Managed security services outsourcing in provincial Bulacan and Batangas corridors offers recurring revenue anchoring without hyperscale competitive pressure. Partner with local systems integrators for regulatory navigation rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from building automation heritage conglomerates seeking to divest non-core physical security divisions. Long-term viability rests on exposure to cloud service provider capex cycles and DICT infrastructure code evolution. Watch facial recognition algorithm export control expansions as the critical inflection signal for biometric hardware sourcing strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Managed Security Services Buildout | Outsourced monitoring captures recurring revenue pools as operators abandon in-house security operations centers. |
| Biometric-Video Platform Integration | Unified physical security information management platforms reduce vendor lock-in for Bangko Sentral ng Pilipinas-regulated institutions. |
| Certified Technician Pipeline Investment | Training partnerships with Philippine technical institutes address labor scarcity commanding premium wages. |
| Direct OEM Channel Development | Bypassing systems integrators aligns with cloud service provider procurement consolidation across Luzon. |
| DICT Pre-Certification Documentation | Pre-built audit packages compress 12-18 month BIS and ISO 27001 timelines for financial data center deployments. |
Research Methodology
A standing panel of data center facility managers, physical security systems integrators, DICT compliance officers, and Bangko Sentral ng Pilipinas audit specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from DICT infrastructure code filings, hyperscaler capex disclosures, BIS certification registries, and customs import records for thermal camera and biometric reader shipments. Bottom-up facility deployment tracking and top-down market sizing triangulated volume estimates.
Scenario-bracketing across conservative, baseline, and aggressive adoption curves anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include security type, technology maturity tier, end-user vertical, and installation service configuration. CAGRs were derived from facility pipeline tracking and procurement specification analysis. Forecast inputs incorporated DICT classification standard enforcement timelines and cloud service provider facility footprint expansion plans.
Stress conditions across peso-dollar exchange rate bands, port congestion duration, and grid reliability thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions around regulatory enforcement consistency and hyperscale operator technology refresh cycles. Cross-checking against DICT data center registration databases and Bangko Sentral ng Pilipinas supervised institution audit schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Belgium Data Center Market
Data Center Infrastructure
Data Center Equipment Market
Data Center Infrastructure
Los Angeles Data Center Market
Data Center Infrastructure
Ireland Data Center Physical Security Market
Data Center Infrastructure
Australia Data Center Market
Data Center Infrastructure
India Data Center Power Market
Data Center Infrastructure
Mexico Data Center Market
Data Center Infrastructure
Canada Data Center Power Market
Data Center Infrastructure
Dedicated Server Hosting Market
Data Center Infrastructure
Managed IT Infrastructure Services Market
Data Center Infrastructure
Converged Data Center Infrastructure Market
Data Center Infrastructure
Beijing Data Center Market
Data Center Infrastructure
Global Data Colocation Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
Mumbai Data Center Market
Data Center Infrastructure
Sweden Data Center Construction Market