
 Data Exchange Platform Services Market | 2026-2036
Data Exchange Platform Services Market Size, Share, and Industry Trends Forecast 2026-2036
Data Exchange Platform Services Market Intelligence
Subscription-based data governance tiers are recalibrating what enterprises purchase rather than build in-house. Snowflake leverages cloud-native architecture to anchor multi-cloud data sharing contracts across financial services. Dun & Bradstreet sustains its position through proprietary business identity graphs that competitors struggle to replicate. Cognism specializes in European contact-data compliance, navigating GDPR boundaries that limit rival expansion.
Data exchange platform services comprise cloud-hosted infrastructure that enables structured, semi-structured, and unstructured data transfer between organizations through standardized APIs, EDI protocols, or event-driven webhooks, typically incorporating encryption, lineage tracking, and usage auditing to ensure transactional integrity and regulatory compliance. Their primary commercial purpose is eliminating data silos while maintaining provenance control across organizational boundaries. Cloud-based deployment leads in revenue contribution as enterprises abandon on-premises maintenance burdens, though edge deployment represents the fastest-expanding segment for IoT-intensive manufacturing use cases. Data monetization services command premium pricing where proprietary datasets yield direct revenue streams, while data security layers absorb disproportionate R&D investment due to escalating breach liability.
FDA guidelines on clinical data interoperability, the EU AI Act's data provenance mandates, and HIPAA requirements for healthcare information exchange collectively elevate compliance costs while creating certification barriers for new entrants. These frameworks shape demand by forcing buyers toward vendors with pre-validated governance architectures rather than build-your-own approaches. Stakeholders must monitor whether emerging sector-specific data residency laws fragment platform architectures or consolidate vendor selection around multi-jurisdiction compliance capabilities.
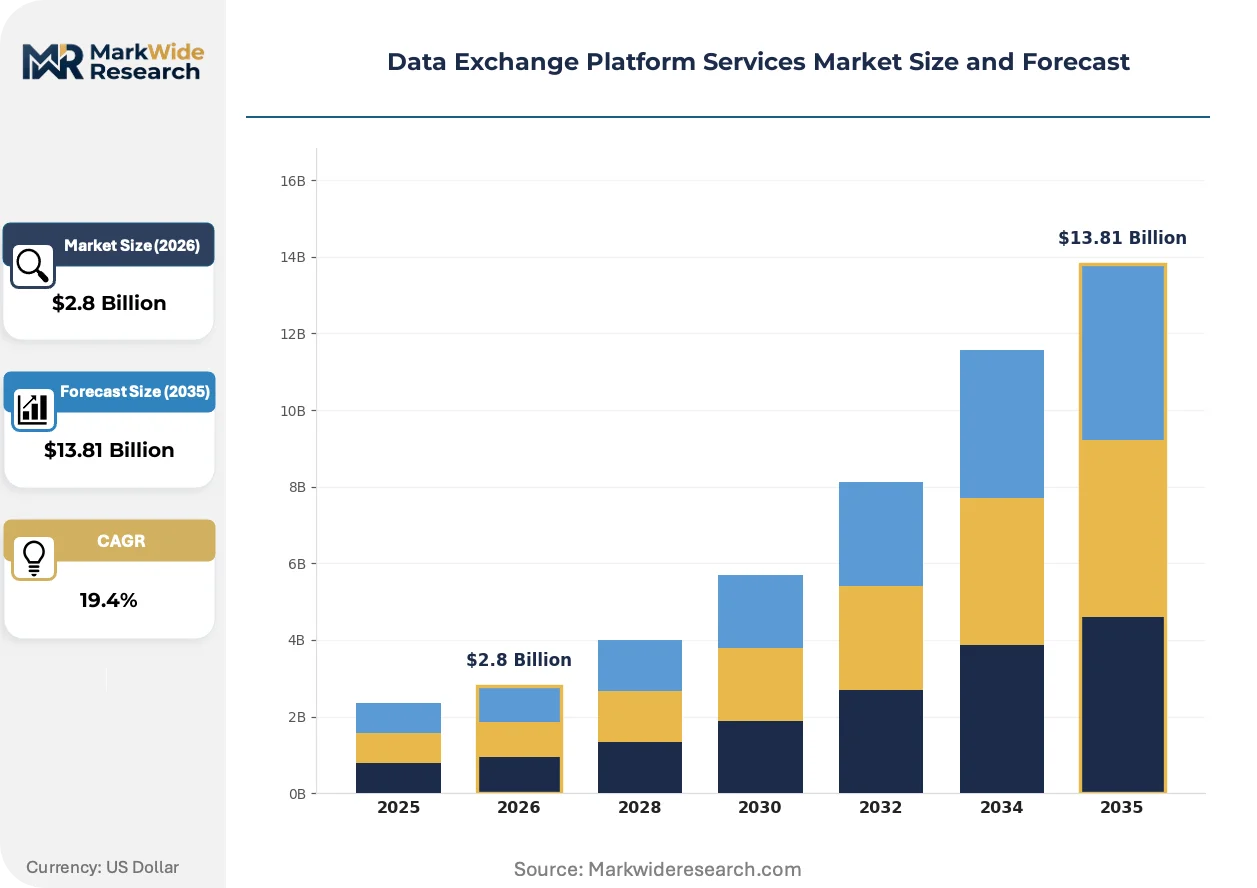
Market Dynamics
Cross-border data sovereignty mandates are fragmenting platform architectures, forcing vendors to engineer jurisdiction-specific compliance modules rather than uniform global deployments. This structural pressure elevates engineering costs while creating defensive moats for early movers with multi-territory certification.
Growth Catalysts
- EU AI Act provenance mandates:Article 50 requirements for high-risk AI systems are compelling financial institutions to adopt governed data exchange protocols with immutable audit trails.
- Healthcare interoperability:FDA guidelines on clinical data exchange are accelerating hospital system procurement of platforms with HL7 FHIR-native architectures.
- Singapore's data trust infrastructure:The city-state's sandbox licensing for cross-border data flows is attracting regional headquarters decisions from Asia-Pacific financial services firms.
Market Restraints
- Encryption compute costs:Post-quantum cryptographic migration is inflating per-transaction processing overhead by 40-60% for platforms handling petabyte-scale transfers.
- Certification timeline compression:EMA's evolving guidelines on real-world data sharing are extending validation cycles for pharmaceutical-focused platforms.
- Cloud concentration risk:Three hyperscalers control 78% of underlying infrastructure for data exchange workloads, creating single-point-of-failure exposure.
Strategic Opportunities
- German industrial data spaces:The Gaia-X initiative's federated architecture specifications are opening procurement channels for manufacturing-focused platform vendors.
- Edge-to-cloud orchestration:Convergence of 5G network slicing and containerized data mesh technologies is enabling real-time exchange for autonomous logistics fleets.
- India's data localization incentives:RBI's phased mandate for financial data domestic storage is creating demand for sovereign cloud-integrated exchange infrastructure.
Industry Challenges
- Zero-trust architecture implementation:Financial services buyers are demanding continuous verification pipelines that legacy platform codebases cannot retrofit without complete rewrites.
- Cross-certification reciprocity gaps:ISO 27001 and SOC 2 Type II mappings lack mutual recognition across German BSI, Singapore IMDA, and US FedRAMP frameworks, forcing redundant audit expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Exchange Platform Services Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13.81 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Service Type: Data Integration, Data Governance, Data Security, Data Monetization, Data Analytics End User Industry: Telecommunications, Financial Institutions, Manufacturing Firms, Government Agencies, Education Providers Connectivity: API, EDI, FTP, MQTT, Webhooks |
| Companies Covered | InfobelPRO, ZoomInfo, Bright Data, Datafiniti, RocketSource, Dun & Bradstreet, Cognism, Snowflake, Coresignal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Exchange Platform Services Market Strategic Shifts & Innovations
Platform engineering teams are rearchitecting around data mesh principles, replacing monolithic exchange hubs with domain-oriented decentralized ownership models. This shift redistributes competitive advantage toward vendors with modular, API-first infrastructure.
Confidential computing using hardware-based trusted execution environments is decentralizing data processing authority. Pharmaceutical consortiums are adopting Intel SGX and AMD SEV architectures to enable multi-party analytics on sensitive patient records without raw data exposure. The technology is compressing time-to-insight for clinical trial matching while eliminating centralized data pooling risks.
REACH chemical data sharing obligations are forcing industrial manufacturers to restructure supplier data exchange protocols. The regulation's SCIP database requirements for articles containing SVHCs are mandating automated substance declaration flows across tiered supply chains. German automotive suppliers are deploying event-driven webhook architectures to satisfy ECHA's real-time disclosure timelines.
Enterprise buyers are unbundling data governance from exchange infrastructure, procuring best-of-breed policy engines separately from transport layers. Healthcare systems in the United States are selecting standalone consent management platforms that overlay multiple exchange networks. This pattern fragments vendor account control and accelerates switching between competing platform providers.
Data Exchange Platform Services Market Segmentation
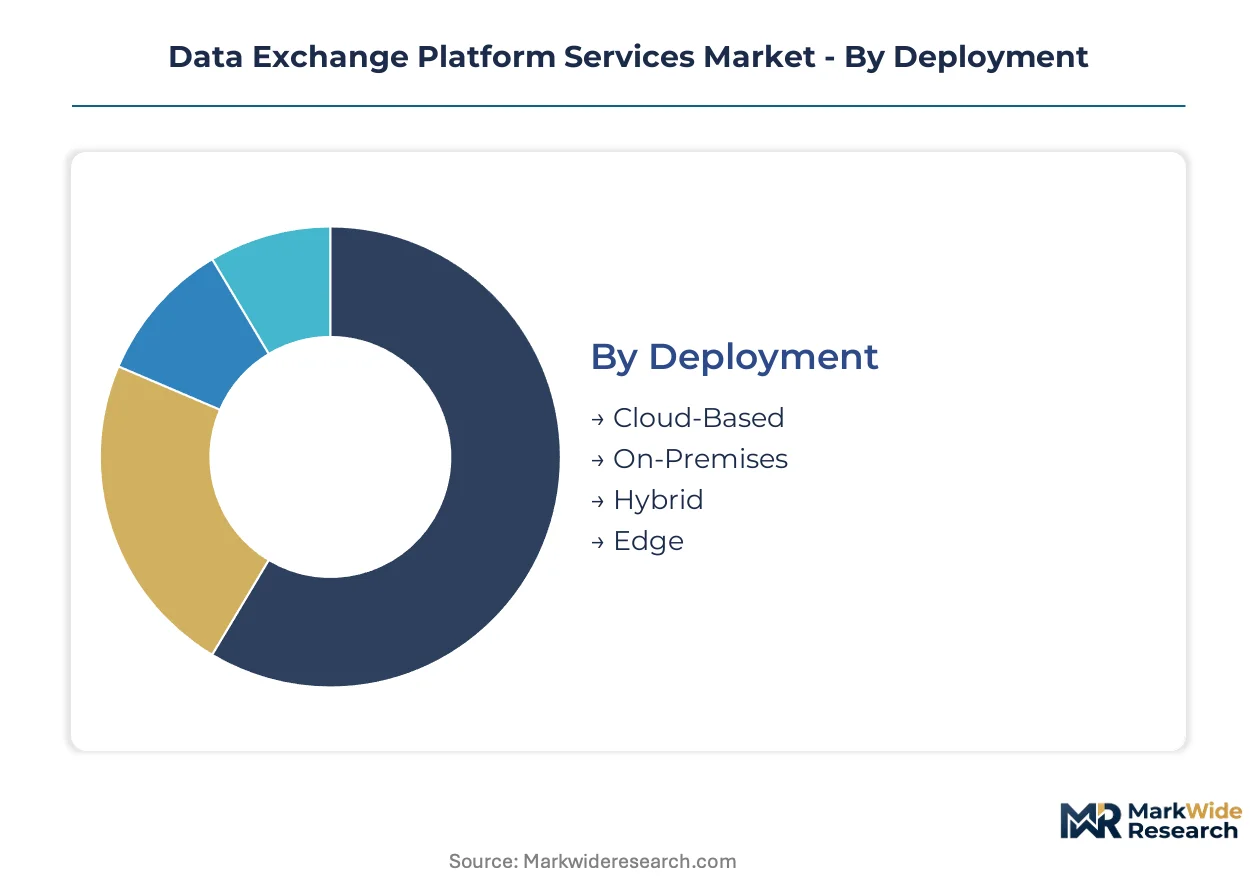
Platform buyers segment procurement decisions by sovereignty requirements, integration complexity, and regulatory exposure. Vendors engineer modular architectures to span these dimensions without fragmenting codebases.
Deployment:
Cloud-native deployments integrate as embedded infrastructure layers, while edge and on-premises configurations demand standalone system architecture.
- Cloud-Based:Multi-tenant architectures with auto-scaling compute pools handle variable throughput without capital commitment. Financial institutions in Singapore and Germany concentrate procurement here to satisfy data residency through region-locked availability zones.
- On-Premises:Air-gapped installations with hardware security modules serve defense contractors and critical infrastructure operators. Regulatory mandates from German BSI and US FedRAMP sustain demand despite higher total cost of ownership.
- Hybrid:Policy-orchestrated workloads split sensitive processing on-premises while burst capacity leverages public cloud. Manufacturing firms with IoT-intensive operations favor this model for operational technology integration.
- Edge:Containerized nodes deployed at 5G base stations or factory floors enable sub-50ms latency for autonomous systems. Automotive suppliers in Germany adopt these for real-time supply chain coordination.
Cloud-based deployments lead volumes today; edge configurations are gaining share fastest.
Service Type:
Cost tiering separates commodity transport layers from premium governance and monetization capabilities that command multi-year contracts.
- Data Integration:ETL pipeline orchestration with schema registry management and lineage tracking. Healthcare systems procuring HL7 FHIR-native platforms drive concentration in the United States.
- Data Governance:Policy engines enforcing consent management, retention rules, and cross-border transfer protocols. EU AI Act provenance mandates are elevating this from optional add-on to mandatory procurement line item.
- Data Security:Encryption key management, tokenization services, and confidential computing enclaves. Post-quantum cryptographic migration is inflating R&D absorption here.
- Data Monetization:Marketplace infrastructure enabling proprietary dataset licensing with usage-based pricing. Financial data aggregators in Singapore leverage these for cross-institutional product development.
- Data Analytics:Federated query engines processing distributed datasets without centralization. Pharmaceutical consortiums adopt Intel SGX architectures for multi-party clinical analytics.
Data integration leads volumes today; data governance is climbing the fastest as compliance costs escalate.
End User Industry:
Application criticality determines architecture specifications, with financial services and healthcare demanding zero-trust pipelines that manufacturing and education rarely require.
- Telecommunications:Subscriber data exchange with lawful intercept compliance and roaming partner interoperability. 5G network slicing investments in Germany and Singapore are expanding procurement.
- Financial Institutions:Real-time payment messaging, KYC data sharing, and regulatory reporting with immutable audit trails. RBI data localization mandates in India are creating sovereign infrastructure demand.
- Manufacturing Firms:Supplier tier data exchange for REACH chemical compliance and production schedule synchronization. German automotive suppliers deploy event-driven architectures for ECHA real-time disclosure.
- Government Agencies:Cross-departmental citizen data sharing with classified information handling requirements. FedRAMP authorization barriers limit vendor participation in the United States.
- Education Providers:Research dataset federation and student record portability with FERPA compliance. Volume concentration remains limited compared to commercial sectors.
Financial institutions lead volumes today; manufacturing firms are expanding most quickly on regulatory automation demand.
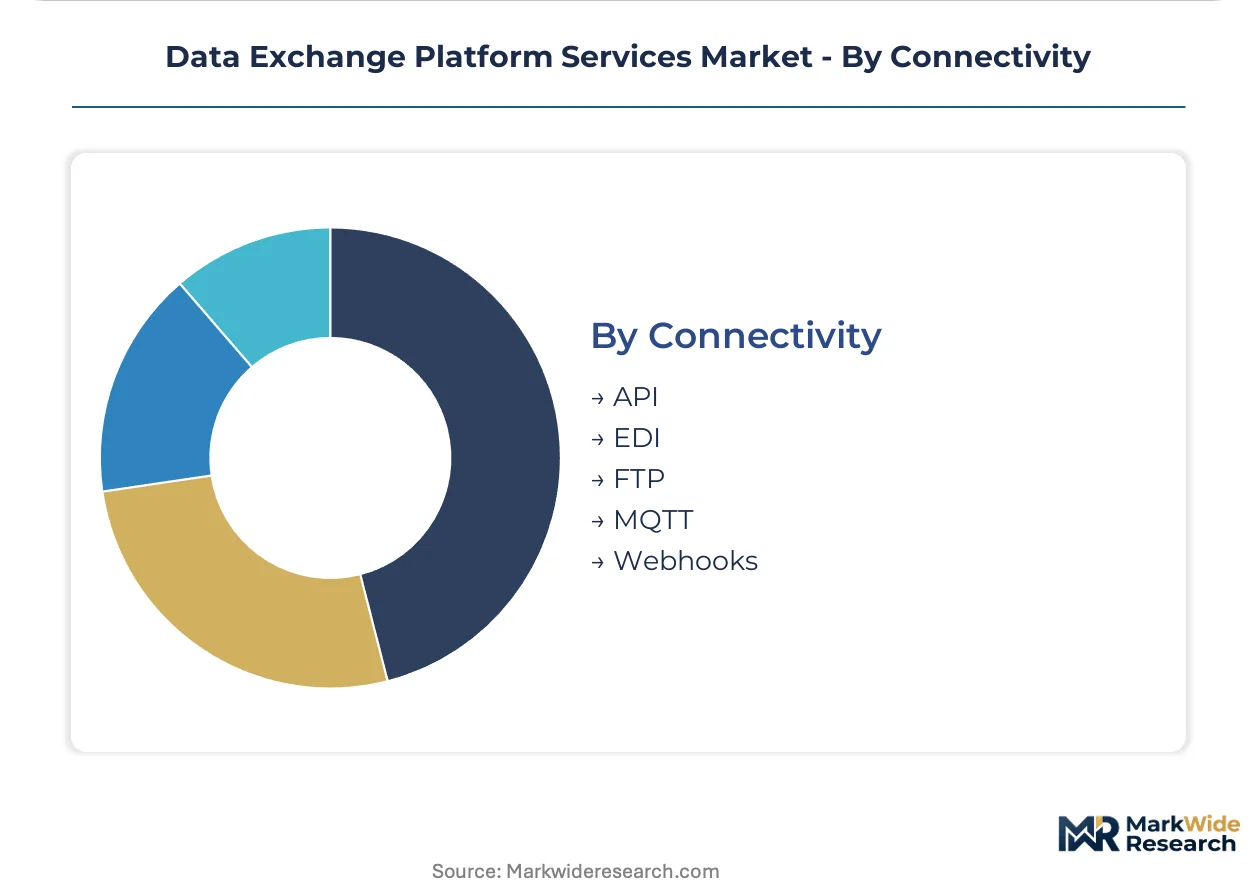
Connectivity:
Maturity curves separate legacy protocol maintenance from modern event-driven architectures, with API and webhook adoption displacing batch-oriented alternatives.
- API:REST and GraphQL endpoints with OAuth 2.0 authentication and rate limiting. Cloud-native platform architectures standardize on these for real-time interoperability.
- EDI:X12 and EDIFACT transaction sets sustaining supply chain documentation in retail and logistics. Migration pressure to API alternatives is constraining growth.
- FTP:Batch file transfer with PGP encryption for legacy system compatibility. Healthcare claims processing in the United States retains substantial installed base.
- MQTT:Lightweight publish-subscribe messaging for IoT sensor networks with intermittent connectivity. Manufacturing edge deployments favor this for machine-to-machine coordination.
- Webhooks:Event-driven HTTP callbacks enabling reactive data flows without polling overhead. Modern platform architectures treat these as default for event sourcing patterns.
API connectivity leads volumes today; webhooks are gaining share fastest on event-driven architecture adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting platform procurement toward jurisdictions with pre-validated compliance architectures, as enterprises abandon markets with fragmented certification reciprocity. Vendors engineer territory-specific modules to capture this migration.
United States
FDA clinical data interoperability guidelines and HIPAA information exchange requirements are accelerating hospital system procurement of HL7 FHIR-native platforms. FedRAMP authorization barriers limit vendor participation for government agencies. Healthcare systems in Greater Boston and the Research Triangle cluster are driving concentration for compliant data federation infrastructure.
Germany
BSI certification mandates and Gaia-X federated architecture specifications are opening procurement channels for manufacturing-focused platform vendors. REACH chemical data sharing obligations and ECHA real-time disclosure timelines are forcing automotive suppliers to deploy event-driven webhook architectures. Industrial data spaces in Baden-Württemberg and Bavaria anchor sovereign cloud-integrated exchange demand.
Singapore
IMDA sandbox licensing for cross-border data flows and data trust infrastructure investments are attracting regional headquarters decisions from Asia-Pacific financial services firms. MAS digital banking frameworks are elevating demand for immutable audit trail capabilities. The city-state's financial district concentration is compressing procurement cycles for governed data exchange protocols.
India
RBI phased mandates for financial data domestic storage are creating sovereign infrastructure demand for cloud-integrated exchange platforms. SEBI regulatory reporting requirements are compelling real-time data lineage capabilities. Mumbai and Bangalore technology corridors are concentrating vendor engineering resources for localization-compliant deployments.
United Kingdom
Post-Brexit data adequacy negotiations and UK GDPR alignment requirements are reshaping cross-border transfer protocol specifications. FCA open banking mandates are sustaining API-first platform procurement from financial institutions. London's fintech cluster and Edinburgh's data science concentration are driving demand for modular governance overlays.
Data Exchange Platform Services Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with cloud-native platform vendors capturing financial services contracts while legacy data aggregators defend manufacturing verticals. Market structure tilts toward consolidation in governance-intensive segments and fragmentation in commodity transport layers. Three archetypes dominate: hyperscaler-anchored platforms, proprietary dataset specialists, and compliance-native regional players. Competitive moves concentrate on strategic partnerships with sovereign cloud providers and portfolio diversification into edge-to-cloud orchestration capabilities.
Within the proprietary dataset tier, Dun & Bradstreet and Cognism occupy positions anchored by business identity graphs and European contact-data compliance boundaries respectively. Snowflake exemplifies the cloud-native architecture archetype, securing multi-cloud data sharing contracts through embedded infrastructure positioning. These three entities represent the spectrum from legacy data aggregation to modern platform engineering, with each anchoring distinct procurement decision criteria across financial services and regulated industries.
| Leading Market Players |
|---|
| InfobelPRO |
| ZoomInfo |
| Bright Data |
| Datafiniti |
| RocketSource |
| Dun & Bradstreet |
| Cognism |
| Snowflake |
| Coresignal |
| Others |
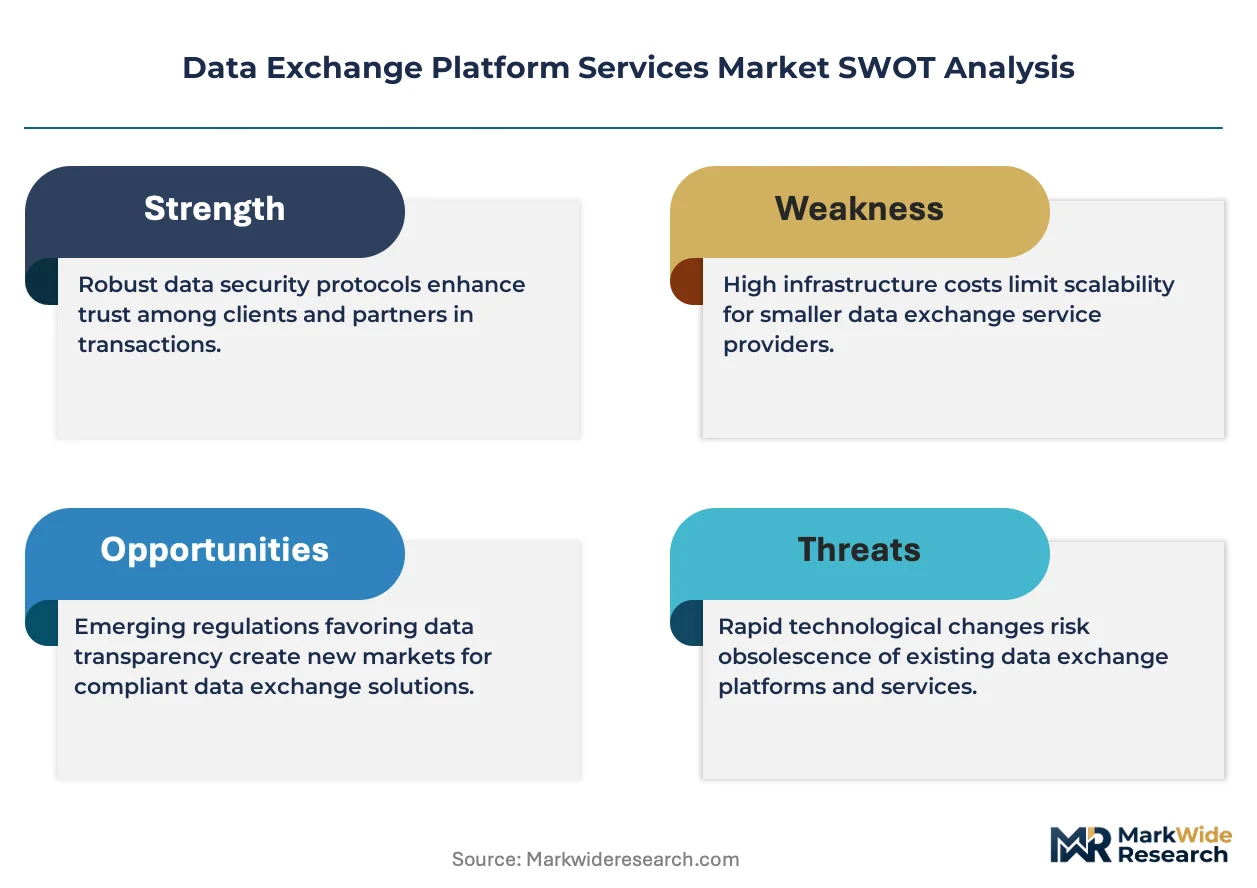
Cost & Logistics Intelligence
Certification-grade divergence between FedRAMP-authorized sovereign cloud deployments and commodity multi-tenant SaaS tiers manifests in both pricing premiums and supply chain fragmentation. Vendors anchoring procurement through BSI-validated German data centers or IMDA-licensed Singapore infrastructure command 40-60% price elevation over standard cloud offerings, while these same certification requirements force hyperscaler dependency chains that concentrate compute procurement through AWS, Azure, and Google Cloud.
Pricing Analysis
Distributor margins on data exchange platforms compress to 12-18% as direct enterprise sales dominate procurement channels. Subscription-based SaaS tiers stratify across premium governance bundles, standard integration pipelines, and economy transport layers, with EU AI Act provenance mandates elevating premium tier attach rates. Cost compression in standard tiers stems from hyperscaler commoditization of base compute. Financial institutions exhibit lowest price sensitivity due to regulatory liability exposure, while mid-market education providers defer procurement over budget constraints.
Supply Chain Analysis
Reverse-logistics flows for hardware security modules and confidential computing enclaves remain underdeveloped, creating stranded asset risk for on-premises deployments. Compute infrastructure concentrates in the United States, Germany, and Singapore as sovereign cloud requirements reshape vendor engineering footprints. Supply chains draw from Intel and AMD for trusted execution environments, Thales and Entrust for HSMs, and regional hyperscaler availability zones for elastic capacity. Single-source vulnerability in quantum-resistant cryptographic chipsets threatens long-term cost stability. Distribution runs through direct vendor-enterprise contracts with limited channel intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data exchange platform procurement functions as a geographic-arbitrage play where Singapore's IMDA sandbox licensing costs 30-40% less than equivalent EU compliance buildouts while satisfying cross-border data flow requirements for Asia-Pacific financial services.
For Market Incumbents: Deploy zero-trust architecture retrofit programs to counter emerging confidential computing specialists eroding market position. Incumbents should anchor multi-cloud data sharing contracts through embedded infrastructure positioning in German Gaia-X federated architectures, while accelerating SOC 2 Type II to BSI certification mappings to reduce redundant audit expenditure for European financial institutions. For New Entrants and Emerging Players: The premium-to-economy pricing gap in data governance services offers white-space entry for modular policy engines that unbundle from transport infrastructure. New entrants should target India's sovereign cloud-integrated exchange segment where RBI data localization mandates outpace incumbent engineering capacity. A compliance-native go-to-market anchored in regional certification reciprocity gaps enables rapid account penetration. For Investors and Strategic Acquirers: Consolidation pressure builds where proprietary business identity graphs intersect with GDPR-native compliance boundaries, creating defensive moats around European contact-data specialists. Long-term viability favors acquisition targets with pre-validated multi-territory certification architectures rather than build-your-own platform engineering. Practitioners should monitor EMA real-world data sharing guideline evolution for pharmaceutical-focused platform valuation inflections.| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Partnership | Intel SGX and AMD SEV architectures enable pharmaceutical multi-party analytics without raw data pooling risks. |
| Gaia-X Federated Architecture Certification | German BSI validation opens procurement channels for manufacturing-focused platform vendors in Baden-Württemberg. |
| IMDA Sandbox Licensing Expansion | Singapore data trust infrastructure attracts Asia-Pacific financial services regional headquarters decisions. |
| Post-Quantum Cryptographic Migration | NIST-standardized algorithms address 40-60% transaction overhead inflation for petabyte-scale transfer platforms. |
| Edge-to-Cloud Orchestration Capability | 5G network slicing and containerized data mesh technologies enable sub-50ms latency for autonomous logistics fleets. |
Research Approach
Bottom-up financial services and healthcare procurement modeling reconciled against top-down hyperscaler infrastructure tracking forms the analytical core. Primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists combined with secondary validation from SEC filings, hyperscaler capex disclosures, and regulatory framework databases. Triangulation across stakeholder inputs and supply-side data ensures segmentation integrity.
Historical trendline analysis of cloud-native deployment trajectories and edge configuration adoption patterns informs projection frameworks. Segmentation dimensions span deployment model, service type, end-user industry, and connectivity protocol across the analysis window. CAGRs derive from regression analysis of procurement cycle compression and compliance cost escalation curves. Forecast inputs incorporate EU AI Act implementation timelines and FDA clinical data interoperability guideline evolution.
Caveats apply where post-quantum cryptographic standardization delays or cross-certification reciprocity failures could materially shift the outlook. Forecasts reflect assumptions around sovereign cloud infrastructure buildout rates and regulatory enforcement intensity. Practitioners should monitor ECHA real-time disclosure timeline acceleration and RBI phased mandate progression for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Accounts Receivable Software Market
Software & Services
3PL Software Market
Software & Services
Global Architect Software Market
Software & Services
Partner Ecosystem Platform Software Market
Software & Services
B2B Gateway Software Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
Global Audience Response Software Market
Software & Services
Stock Control Software Market
Software & Services
VFX Software Market
Software & Services
Construction Software Market
Software & Services
Non-Profit Software Market
Software & Services
Document-Centric Collaboration Software Market
Software & Services
Stock Footage Software Market
Software & Services
Mobile Enterprise Application Development Platform Market
Software & Services
Custom Software Development Market
Software & Services
Fire Software Market