
 Europe Containerized Data Center Market | 2026-2036
Europe Containerized Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Containerized Data Center Market Foresight
Market Context
Multi-source procurement of prefabricated infrastructure is consolidating as enterprises diversify vendor relationships to mitigate supply chain risk. Schneider Electric leverages its European manufacturing footprint to sustain rapid module delivery timelines. Vertiv Holdings Co anchors its position through integrated power and thermal management portfolios. Rittal GmbH & Co. KG specializes in enclosure systems that compete on interoperability with third-party subsystems.
Technical Definition and Segment Structure
Containerized data centers are factory-built, transportable enclosures housing IT equipment, power distribution, and cooling systems in standardized ISO shipping formats, typically rated for rapid deployment within weeks rather than years. Modular data centers lead the product type category due to proven scalability for colocation operators, while liquid cooling segments are gaining share as thermal densities from AI workloads exceed air-cooling thresholds. Edge data centers represent the fastest-growing application as telecommunications firms push latency-sensitive workloads closer to population clusters.
Regulatory Environment and Outlook
EU Green Deal carbon neutrality targets and the CSRD disclosure framework are forcing operators to document lifecycle emissions from module fabrication through decommissioning. CE marking and the F-Gas Regulation constrain refrigerant choices in cooling systems, favoring manufacturers with low-global-warming-potential designs. ECHA chemical registration requirements add compliance layers to imported materials. Stakeholders must monitor whether the EU AI Act's infrastructure transparency rules extend to edge computing nodes housed in containerized formats.
Market Dynamics
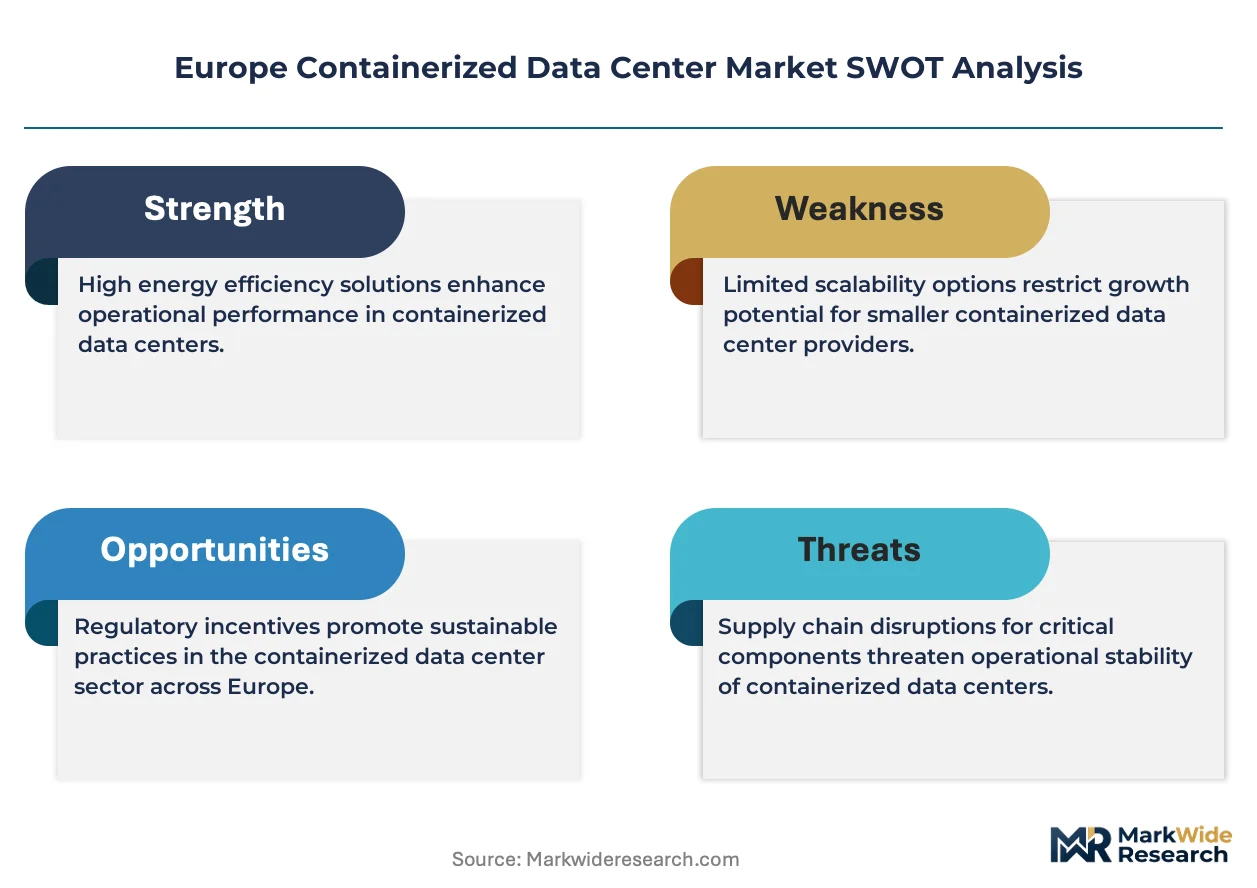
The EU Green Deal and CSRD disclosure mandates are compressing deployment timelines for low-carbon prefabricated infrastructure, forcing operators to document embodied emissions from module fabrication through decommissioning.
Growth Catalysts
- CSRD Reporting Mandates:Operators must disclose lifecycle emissions, creating procurement preference for factory-built modules with verified carbon footprints over traditional construction.
- AI Workload Density:Thermal loads from GPU clusters are exceeding air-cooling thresholds in conventional facilities, pulling liquid-cooled containerized solutions into hyperscale leasing pipelines.
- Edge Computing Expansion:Telecommunications firms in Germany, France, and the Netherlands are deploying latency-sensitive nodes closer to population clusters, accelerating demand for rapid-deployment formats.
Market Restraints
- Steel and Aluminum Input Volatility:Fluctuations in commodity prices for enclosure materials compress margin predictability for module fabricators operating on fixed-price contracts.
- F-Gas Regulation Constraints:The EU F-Gas Regulation restricts refrigerant choices in cooling systems, limiting supplier options for manufacturers without low-global-warming-potential designs.
- Site Preparation Bottlenecks:Grid connection delays and permitting complexity at the municipal level in France and Germany extend effective deployment timelines despite rapid module fabrication.
Strategic Opportunities
- Nordic Expansion:Norway and Sweden offer favorable cooling economics and renewable energy access for operators seeking carbon-neutral hosting capacity outside saturated FLAP markets.
- Waste Heat Recovery Integration:District heating networks in Denmark and Finland present offtake partnerships for thermal output from high-density compute modules.
- EU AI Act Infrastructure Rules:Pending transparency requirements for edge computing nodes could create compliance-driven upgrade cycles for containerized deployments in telecommunications.
Industry Challenges
- Skilled Technician Scarcity:Liquid cooling system installation and maintenance expertise remains concentrated among specialized contractors, constraining deployment velocity.
- Legacy Integration Complexity:Containerized modules must interface with existing building management systems and power distribution architectures, requiring custom engineering.
- CE Marking Timeline Compression:Evolving certification requirements for electrical safety and electromagnetic compatibility extend pre-deployment validation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Containerized Data Center Market |
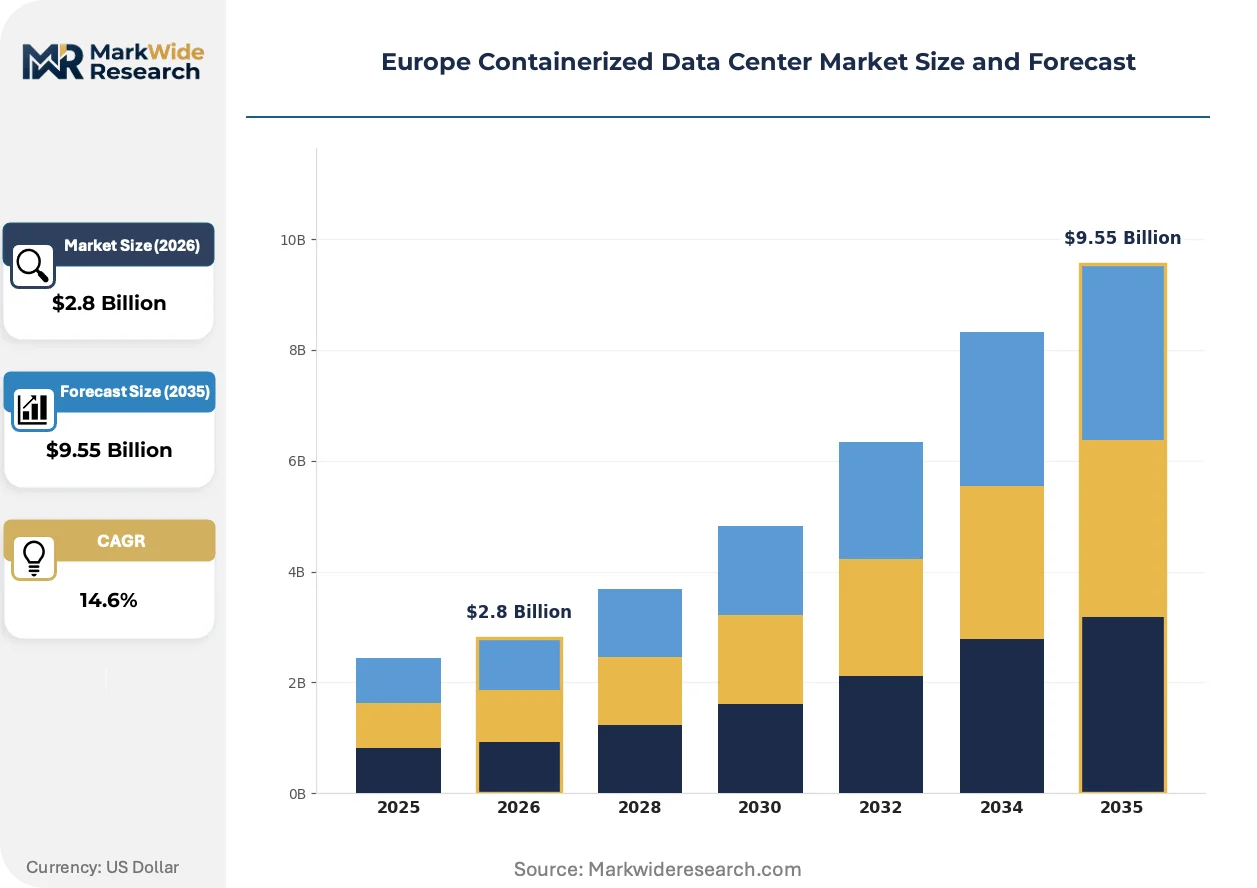
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Data Centers, Portable Data Centers, Hybrid Data Centers, Edge Data Centers Cooling Technology: Air-Cooling, Liquid Cooling, Evaporative Cooling, Immersion Cooling Power Supply: Renewable Energy, Diesel Generators, Fuel Cells, Grid Power End User Industry: Telecommunications, Healthcare, IT & Telecom, Government |
| Companies Covered | Huawei Technologies, Cisco Systems Inc, Schneider Electric, STULZ, Hewlett Packard Enterprise Co, Vertiv Holdings Co, Dell Technologies Inc, ABB, Rittal GmbH & Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Containerized Data Center Market Shifts & Advancements
Digital infrastructure deployment is pivoting from site-built to factory-fabricated models, with automation and sustainability metrics now determining competitive positioning in procurement decisions.
Intelligent power management software is automating load balancing across distributed containerized assets. Colocation operators in the Netherlands are deploying these systems at scale to optimize renewable energy consumption and reduce stranded capacity. The technology is automating operational decisions previously requiring on-site engineering presence, compressing staffing requirements for edge locations.
The EU F-Gas Regulation is accelerating refrigerant transitions in cooling system design. Manufacturers must now certify low-global-warming-potential alternatives or exit the European supply chain. Liquid cooling segments are capturing disproportionate investment as air-cooled architectures face compliance headwinds in Germany and France.
Enterprise buyers are consolidating vendor relationships to reduce supply chain exposure. Multi-source procurement strategies are displacing single-vendor dependencies for critical infrastructure. This concentration is most visible among financial services firms in Frankfurt and Amsterdam, where resilience requirements now mandate qualified secondary suppliers for all prefabricated modules.
Europe Containerized Data Center Market Segmentation
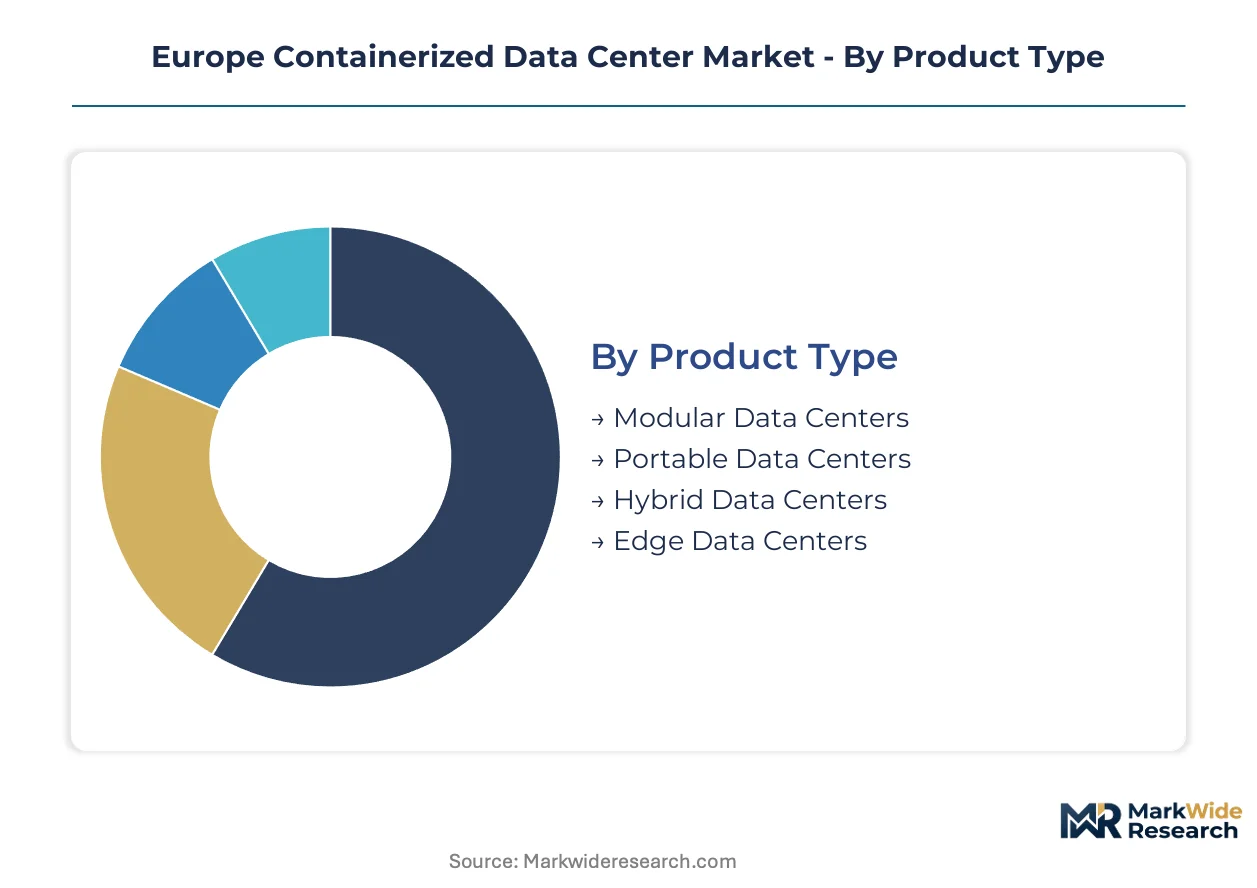
Segmentation reveals how procurement patterns diverge across deployment models and infrastructure specifications. Buyers in Germany, France, and the Netherlands weight cooling density and power resilience differently depending on workload criticality and grid reliability.
Product Type:
Supply concentration among prefabricated module fabricators in Germany and the Netherlands shapes availability and delivery timelines for each format.
- Modular Data Centers:Factory-built units with standardized power and cooling subsystems designed for incremental capacity expansion. Colocation operators in Frankfurt and Amsterdam deploy these for rapid lease-up of hyperscale footprints without long construction cycles.
- Edge Data Centers:Compact, transportable enclosures optimized for sub-10ms latency requirements. Telecommunications firms across Germany and France are installing these at base station aggregation points to support distributed AI inference workloads.
- Portable Data Centers:Self-contained mobile units with integrated generators for temporary or emergency deployment.
- Hybrid Data Centers:Configurations combining containerized modules with on-site built infrastructure for customized scaling.
Modular data centers absorb the bulk of installed capacity; edge data centers are expanding most quickly.
Cooling Technology:
Cost tier differentiation separates established air-cooled designs from emerging liquid and immersion systems requiring specialized installation expertise.
- Liquid Cooling:Direct-to-chip or rear-door heat exchanger architectures handling thermal densities above 50kW per rack. Hyperscale leasing pipelines in the Netherlands and Germany are specifying these for GPU clusters where air cooling fails.
- Air-Cooling:Conventional raised-floor or in-row precision cooling for moderate density loads. Enterprise colocation in France continues specifying these for general-purpose workloads where capital constraints limit infrastructure refresh cycles.
- Immersion Cooling:Dielectric fluid submersion of entire server assemblies for extreme density and noise reduction.
- Evaporative Cooling:Adiabatic or water-assisted systems leveraging ambient wet-bulb conditions for efficiency gains.
Air-cooling retains the largest installed base; liquid cooling is climbing the fastest as AI workload density reshapes procurement specifications.
Power Supply:
Volume concentration among grid-connected deployments in metropolitan FLAP markets contrasts with off-grid and renewable configurations in Nordic expansion zones.
- Grid Power:Utility-fed primary supply with battery or generator backup for Tier III and Tier IV reliability. Frankfurt and Amsterdam operators prioritize grid interconnection for cost predictability despite municipal permitting delays.
- Renewable Energy:Direct power purchase agreements or on-site solar and wind coupled with battery storage. Norway and Sweden are attracting carbon-neutral hosting commitments through hydroelectric and wind access.
- Diesel Generators:Traditional backup power for compliance with uptime institute standards during grid failures.
- Fuel Cells:Hydrogen or natural gas electrochemical generation for extended runtime without fuel logistics.
Grid power dominates current deployments; renewable energy configurations are gaining share fastest as CSRD disclosure mandates pressure Scope 2 emissions reductions.
End User Industry:
Customer type fragmentation separates latency-sensitive telecommunications deployments from compliance-bound healthcare and government specifications.
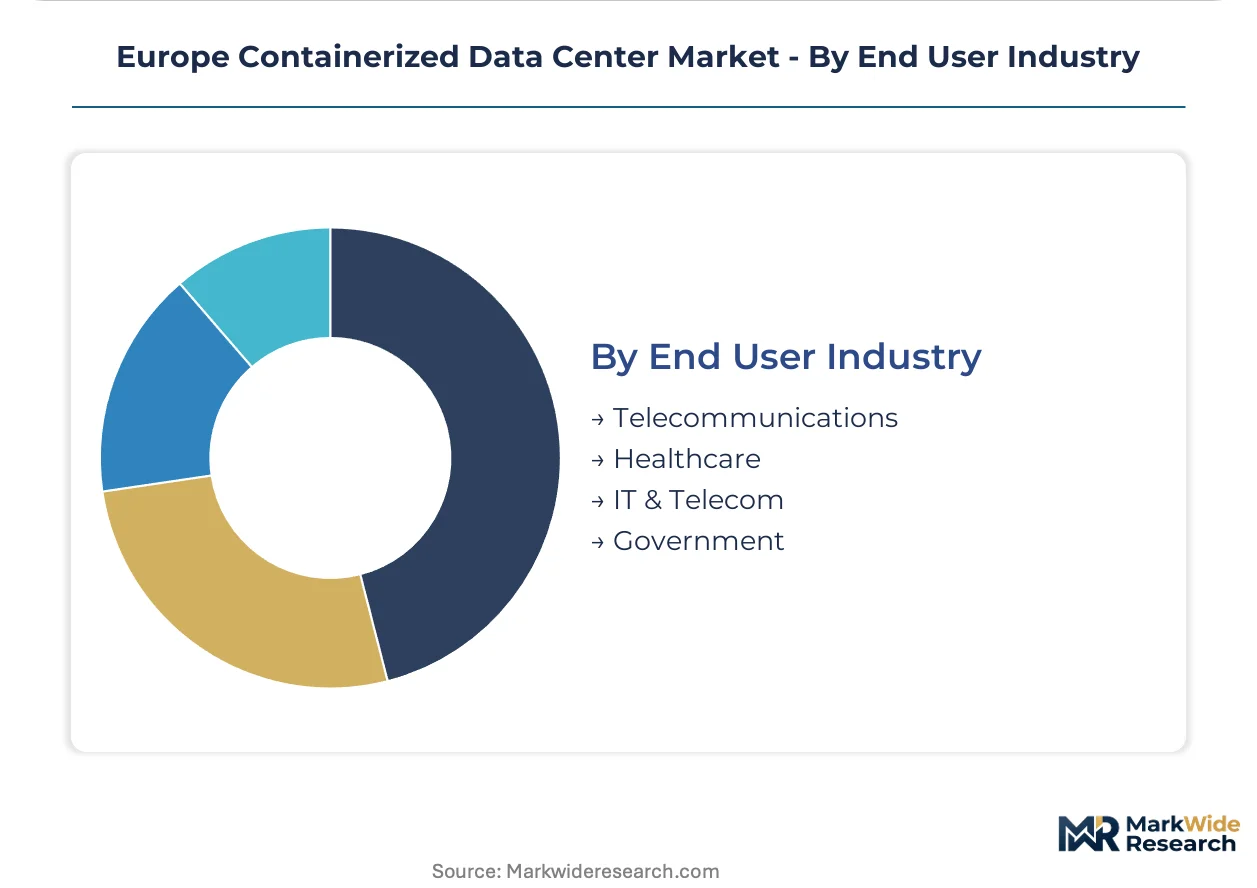
- Telecommunications:Mobile network operators and tower companies deploying edge nodes for 5G core and radio access network virtualization. Deutsche Telekom and Orange are accelerating containerized infrastructure for distributed latency targets.
- IT & Telecom:Cloud service providers and enterprise IT organizations procuring modular capacity for primary and disaster recovery workloads.
- Healthcare:Hospital systems and health data processors requiring localized infrastructure for patient data residency under GDPR and national health regulations.
- Government:Defense and civilian agencies specifying sovereign cloud and tactical deployments with security-hardened enclosures.
IT & Telecom absorbs the bulk of procurement volume; telecommunications is expanding most quickly as 5G standalone core deployment accelerates across Germany and France.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel and aluminum fabrication clusters in Germany's Ruhr region and the Netherlands' Port of Rotterdam anchor the continent's prefabricated module supply chain. These industrial zones feed enclosure manufacturing for rapid-deployment data centers across northern Europe.
Germany
Hyperscale leasing activity in Frankfurt concentrates demand for liquid-cooled containerized modules handling AI workloads. The F-Gas Regulation restricts refrigerant choices in cooling systems, pushing operators toward low-global-warming-potential designs. Bavaria's manufacturing belt hosts enclosure fabricators supplying modular units for colocation expansion.
Netherlands
Amsterdam's dense interconnection ecosystem drives procurement of edge data centers for latency-sensitive financial services workloads. CSRD disclosure mandates pressure operators to document embodied carbon from module fabrication through decommissioning. The Randstad corridor houses integration facilities assembling prefabricated units for rapid site deployment.
France
Paris and Marseille anchor telecommunications-driven edge computing expansion for 5G standalone core virtualization. Municipal permitting complexity extends grid connection timelines despite rapid module fabrication capabilities. Île-de-France hosts systems integrators specializing in hybrid configurations combining containerized modules with on-site infrastructure.
Sweden
Nordic renewable energy access attracts carbon-neutral hosting commitments from cloud operators seeking Scope 2 emissions reductions. District heating networks in Stockholm present waste heat recovery partnerships for thermal output from high-density compute modules. The country's hydroelectric grid supports grid-connected deployments with minimal carbon intensity.
United Kingdom
London's financial services sector drives demand for disaster recovery modules with Tier III reliability specifications. GDPR and national data residency requirements pressure healthcare and government buyers toward sovereign cloud deployments in containerized formats. The Thames Valley corridor hosts integration facilities serving enterprise colocation expansion.
Europe Containerized Data Center Market Competitive Landscape
Global majors compete with regional champions across manufacturing footprint and delivery velocity. The vendor base splits between diversified electrical equipment conglomerates and specialized enclosure fabricators. Two strategic archetypes dominate: integrated power-cooling-module providers and subsystem specialists competing on interoperability. Capacity expansion and strategic partnerships represent the dominant competitive moves as procurement consolidates around qualified secondary suppliers.
Among diversified infrastructure providers, Schneider Electric and Vertiv Holdings Co occupy positions spanning power distribution through thermal management. Rittal GmbH & Co. KG exemplifies the enclosure specialist archetype, competing on subsystem compatibility rather than vertical integration. Huawei Technologies represents the Asian-origin diversified technology conglomerate with European manufacturing presence. These three anchors illustrate how procurement patterns favor either breadth of integrated portfolio or depth of specialized interoperability.
| Leading Market Players |
|---|
| Huawei Technologies |
| Cisco Systems Inc |
| Schneider Electric |
| STULZ |
| Hewlett Packard Enterprise Co |
| Vertiv Holdings Co |
| Dell Technologies Inc |
| ABB |
| Rittal GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
Liquid cooling technician scarcity in Germany's Ruhr region and Bavaria's manufacturing belt compresses installation capacity and widens pricing spreads between premium full-service bundles and unbundled module-only transactions. Labor-cost differentials between these industrial clusters and lower-cost Eastern European integration sites translate directly into tiered service-level pricing across the European market.
Pricing Analysis
Warranty and lifecycle service bundling separates premium-tier offerings from economy configurations where operators assume maintenance risk. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking tier, cooling density specification, and geographic delivery distance from Rotterdam and Hamburg fabrication hubs. Cost compression in standard-tier liquid-cooled modules is intensifying because certified technician pools remain concentrated in Germany and the Netherlands. Financial services firms in Frankfurt and Amsterdam exhibit lowest price sensitivity, prioritizing uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Dual-sourcing mandates from hyperscale colocation operators in Frankfurt and Amsterdam force module fabricators to qualify secondary steel enclosure suppliers beyond Germany's Ruhr concentration. Supply rests on steel and aluminum feedstock from Germany, the Netherlands, and Poland, with cooling subsystem components drawn from Denmark and Sweden. Single-source vulnerability concentrates in specialized liquid cooling heat exchanger fabrication, where Danish and Finnish suppliers dominate. Distribution runs through systems integrators in the Randstad corridor and Bavaria for final assembly and site deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe containerized data center market functions as a cost-of-compliance arena where CSRD disclosure mandates erect substantial documentation barriers that favor incumbent operators with established carbon accounting infrastructure and lifecycle traceability systems.
For Market Incumbents: Extend certification investment into F-Gas Regulation-compliant cooling designs and CE marking pre-validation services to capture procurement preference from disclosure-bound enterprises. Capacity addition in Norway and Sweden secures renewable energy positioning as CSRD pressures intensify Scope 2 reduction commitments. Vertical integration into waste heat recovery partnerships with Nordic district heating networks defends margin position against modular pure-plays lacking thermal offtake capabilities.
For New Entrants and Emerging Players: Launch via direct-to-operator sales models targeting telecommunications edge deployments in France's 5G standalone expansion zones, bypassing established colocation channel control in saturated FLAP markets. White-space concentration sits in liquid-cooled portable configurations for temporary AI training workloads in secondary European cities lacking hyperscale presence. Municipal permitting acceleration services represent the most penetrable value-add layer for entrants lacking manufacturing scale.
For Investors and Strategic Acquirers: The window for entry favors enclosure fabricators with pre-qualified low-global-warming-potential cooling subsystem partnerships and established CE marking pathways. Long-term viability hinges on carbon-neutral hosting commitments from cloud operators extending across the next decade. Monitor F-Gas Regulation amendment timelines as the critical inflection signal for refrigerant transition investment cycles and stranded asset risk in air-cooled module portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| CSRD-Compliant Carbon Accounting Integration | Embodied emissions documentation from module fabrication through decommissioning secures procurement preference among disclosure-bound enterprises in Germany and the Netherlands. |
| Nordic Manufacturing Footprint Expansion | Hydroelectric grid access in Norway and Sweden supports carbon-neutral hosting commitments from hyperscale cloud operators facing Scope 2 reduction mandates. |
| Liquid Cooling Technician Certification Programs | Specialized installation expertise scarcity in Germany constrains deployment velocity, creating competitive advantage for firms with captive training pipelines. |
| Waste Heat Recovery Partnership Development | District heating network integration in Denmark and Finland monetizes thermal output from high-density GPU clusters, differentiating against pure infrastructure plays. |
| Edge Computing Node Compliance Pre-Certification | Pending EU AI Act transparency requirements for telecommunications deployments create upgrade cycle capture opportunity for pre-validated containerized formats. |
Research Methodology
Multi-period observation of hyperscale leasing pipelines, municipal permitting timelines, and cooling technology procurement specifications anchored the trend analysis, supplemented by interviews with colocation operators, telecommunications infrastructure planners, and prefabricated module fabricators. Secondary validation drew from EU regulatory filings, ECHA chemical registration databases, hyperscaler capital expenditure disclosures, and trade flow records for steel and aluminum enclosure materials. Bottom-up unit economics modeling and top-down market sizing triangulation cross-verified volume and value estimates across the analysis window.
Input-output matrices mapped module fabrication capacity, skilled technician availability, and grid interconnection queues against deployment demand projections across the modeling period. Segmentation dimensions included product type, cooling technology architecture, power supply configuration, and end-user industry vertical. CAGRs were derived from logistic adoption curves fitted to historical deployment velocities and regulatory mandate implementation schedules. Forecast inputs incorporated F-Gas Regulation compliance timelines and CSRD disclosure phase-in requirements as structural demand shapers.
Commodity price volatility in steel and aluminum, grid connection permitting delays in France and Germany, and refrigerant technology transition uncertainty are the dominant revision risks to deployment velocity assumptions. Deviation in municipal approval timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
Canada Data Center Construction Market
Data Center Infrastructure
Global Data Center RFID Market
Data Center Infrastructure
Indonesia Data Center Construction Market
Data Center Infrastructure
India Data Center Power Market
Data Center Infrastructure
Singapore Data Center Power Market
Data Center Infrastructure
South Korea Data Center Rack Market
Data Center Infrastructure
Saudi Arabia Data Center Construction Market
Data Center Infrastructure
United Arab Emirates Data Center Power Market
Data Center Infrastructure
Russia Data Center Market
Data Center Infrastructure
Malaysia Data Center Rack Market
Data Center Infrastructure
Russia Data Center Rack Market
Data Center Infrastructure
China Data Center Rack Market
Data Center Infrastructure
Dedicated Server Hosting Market
Data Center Infrastructure
LAMEA Virtual Desktop Infrastructure Market
Data Center Infrastructure
Global Data Center Accelerator Market