
 Custom Software Development Market | 2026-2036
Custom Software Development Market Size, Share, and Industry Trends Forecast 2026-2036
Custom Software Development Market Intelligence
Platform licensing revenue is rewriting margin distribution across the custom software value chain. Accenture leverages its cloud migration practice to capture recurring architecture engagements. Tata Consultancy Services anchors large-scale healthcare and finance transformation programs across North America and Europe. IBM competes through hybrid cloud and AI-infused development tooling that extends enterprise retention.
Custom software development encompasses the design, engineering, testing, and deployment of purpose-built applications using specified programming languages, frameworks, and architectural patterns to meet unique operational requirements. The practice integrates front-end interfaces, back-end services, database schemas, and API layers into cohesive systems that automate workflows, process transactions, or analyze proprietary data. Agile and DevOps development models now dominate delivery structures, displacing rigid waterfall approaches in time-sensitive industries. Cloud deployment types absorb the fastest-growing share of new engagements, while on-premise installations persist in regulated finance and defense segments where data sovereignty controls access.
US HIPAA security rules, EU GDPR data-processing requirements, and India BIS IT service standards collectively elevate compliance costs and technical specifications for cross-border delivery. FDA software-as-medical-device guidance and SEC cybersecurity disclosure rules in the United States further tighten validation protocols for healthcare and finance applications. Stakeholders must monitor regulatory divergence between jurisdictions to avoid architecture lock-in that complicates future geographic expansion.
Market Dynamics
Cloud-first mandates from EU GDPR and US HIPAA compliance frameworks are compressing procurement cycles and forcing architectural standardization across healthcare, finance, and defense verticals.
Growth Catalysts
- HIPAA Security Rule enforcement:US healthcare providers must replace legacy on-premise systems with auditable cloud architectures, creating sustained demand for compliant custom platforms.
- DevOps automation tooling:Continuous integration pipelines reduce deployment friction, accelerating release velocity for time-sensitive financial trading applications.
- India's BIS IT service standards:Certification requirements for cross-border delivery hubs elevate quality benchmarks, attracting Fortune 500 outsourcing contracts to Bangalore and Hyderabad clusters.
Market Restraints
- Specialized talent scarcity:Shortage of certified cloud architects and security engineers in Germany and the United States inflates project staffing costs by 30-40%.
- Input cost volatility:Enterprise software licensing fees for middleware and database engines fluctuate with vendor consolidation, compressing gross margins for fixed-price contracts.
- Regulatory fragmentation:Divergent FDA software-as-medical-device guidance and EU MDR requirements force redundant validation cycles for healthcare applications targeting both markets.
Strategic Opportunities
- Underpenetrated German Mittelstand:Mid-sized industrial manufacturers lack bespoke ERP integrations for Industry 4.0 connectivity, representing white space for specialized developers.
- EU AI Act compliance tooling:Mandated risk classification and documentation requirements for high-risk AI systems create attach-rate opportunities for governance platforms.
- Edge-to-cloud convergence:Integration of containerized microservices with 5G-enabled industrial IoT gateways opens new deployment architectures for manufacturing automation.
Industry Challenges
- Legacy system entanglement:Financial institutions running COBOL core banking platforms face decade-long migration timelines that stall greenfield custom development budgets.
- Certification bottlenecks:SOC 2 Type II and ISO 27001 audit queues extend sales cycles by 6-9 months for security-sensitive government contracts.
- Intellectual property disputes:Open-source license contamination in code repositories triggers indemnification conflicts between clients and development vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Custom Software Development Market |
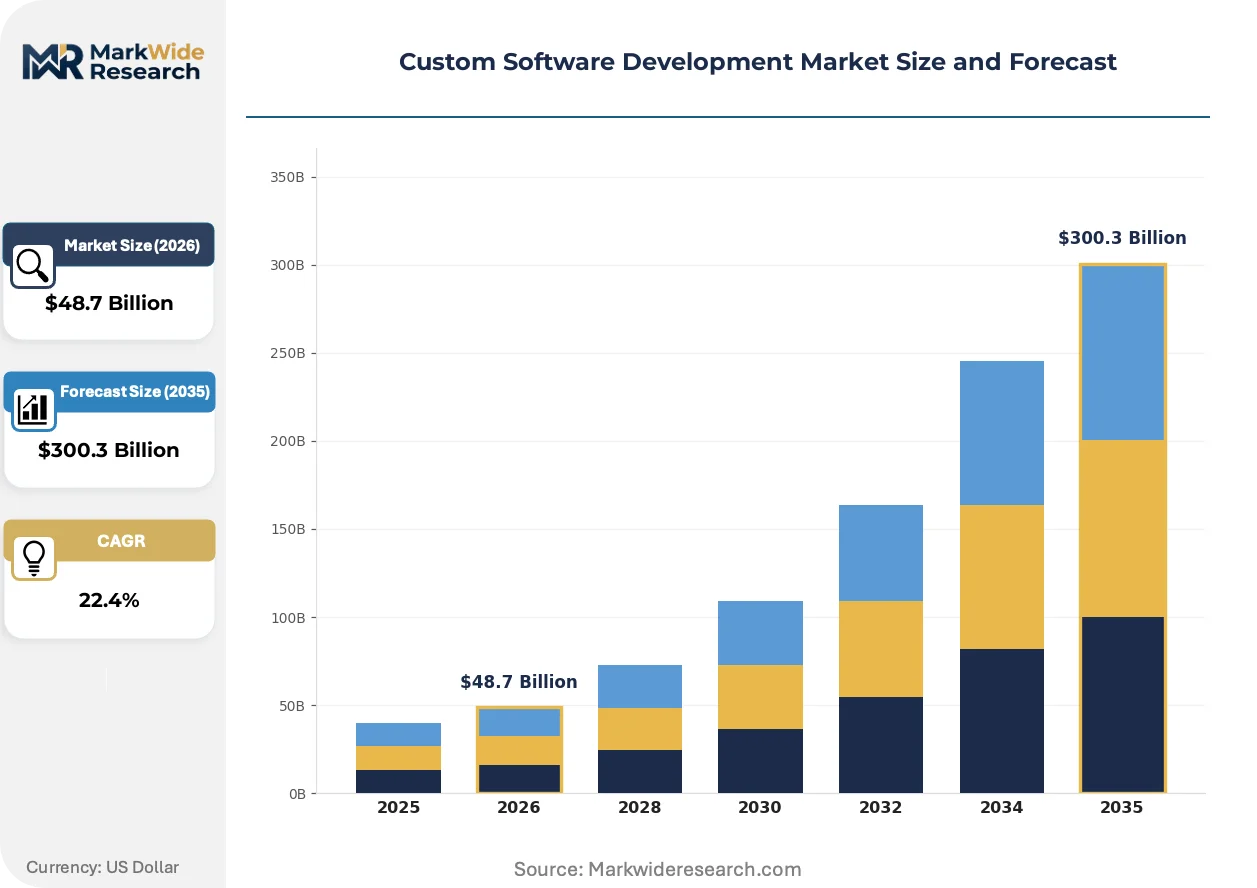
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $300.3 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Development Model: Agile, Waterfall, DevOps, Outsourced Target Industry: Healthcare, Retail, Finance, Education Technology Stack: Javascript, Python, Java, Ruby Deployment Type: Cloud, On-Premise, Hybrid, Mobile |
| Companies Covered | Accenture, Cognizant, Tata Consultancy Services, Infosys, Capgemini, Wipro, IBM, HCL Technologies, DXC Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Custom Software Development Market Strategic Shifts & Innovations
Generative AI coding assistants and low-code platforms are compressing traditional development timelines while forcing established vendors to reposition service offerings around architecture governance and integration complexity.
Platform engineering is hybridizing internal developer experience tooling with self-service infrastructure provisioning. Large enterprises in the United States and Germany are consolidating fragmented CI/CD pipelines into unified control planes. This convergence is compressing vendor fragmentation and favoring providers with upstream control over both tooling and managed services.
GDPR Article 32 security-of-processing requirements now mandate encryption-by-default and breach-notification automation for all customer-facing applications. EU supervisory authorities are imposing fines that reach 4% of global turnover, forcing procurement teams to embed privacy-by-design clauses into every statement of work. Healthcare and fintech segments in France and the Netherlands are responding by pre-qualifying vendors through centralized national procurement frameworks.
Enterprise buyers are unbundling long-term managed services from initial development contracts, compressing vendor lock-in and accelerating switching cycles. Systems integrators now face annual recompetition for maintenance and support work that previously ran 5-7 years. This pattern is most visible in the United Kingdom and Nordic markets, where public-sector procurement frameworks mandate competitive rebidding at 24-month intervals.
Custom Software Development Market Segmentation
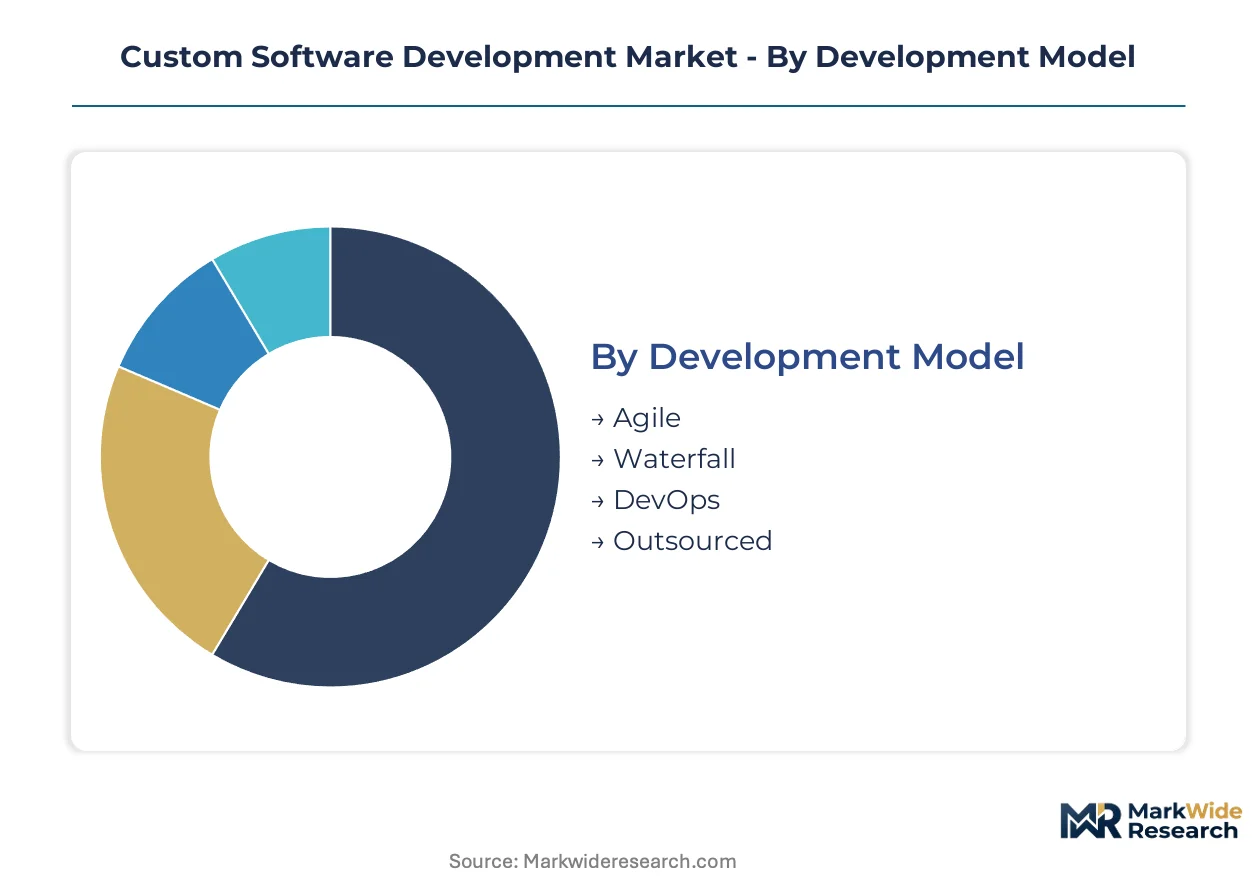
Segmentation in custom software development reveals divergent procurement rhythms across delivery methodologies and infrastructure choices. Healthcare and finance buyers demand validated, slower-cycle deployments while retail and education segments compress vendor selection timelines. Understanding these velocity differences enables suppliers to align pipeline management with segment-specific sales cycles.
Development Model:
Agile iterations compress delivery timelines to 2-4 week sprints, while Waterfall engagements lock requirements for 12-18 month build phases. DevOps pipelines and outsourced arrangements occupy intermediate positions with distinct contracting structures.
- Agile:Iterative sprint-based delivery with continuous stakeholder feedback loops. US healthcare providers deploying patient portals favor two-week release cycles to accommodate FDA software-as-medical-device validation checkpoints.
- DevOps:Integrated development-operations pipelines automating build, test, and deployment stages. German automotive suppliers leverage continuous integration to synchronize embedded software releases with manufacturing line updates.
- Waterfall:Sequential phase-gate methodology with frozen requirements after initial specification. Defense contractors in the United States maintain this model for security-cleared systems with immutable compliance baselines.
- Outsourced:Third-party delivery through offshore or nearshore development centers. Indian BIS-certified hubs in Bangalore and Hyderabad capture Fortune 500 contracts requiring 24/7 coverage.
Waterfall anchors the volume base in regulated verticals while DevOps gains share at the steepest rate across cloud-native enterprises.
Target Industry:
Cost tier stratification separates compliance-heavy healthcare and finance engagements from retail and education projects with lighter validation burdens.
- Healthcare:HIPAA-compliant systems for patient data management, clinical workflows, and telemedicine platforms. US providers replacing legacy on-premise infrastructure drive sustained demand for auditable cloud architectures.
- Finance:Trading systems, risk engines, and customer-facing banking applications. SEC cybersecurity disclosure rules extend procurement cycles for US institutions seeking SOC 2 Type II certification.
- Retail:E-commerce platforms, inventory management, and customer analytics tools. Seasonal demand spikes around holiday periods compress development windows for European omnichannel merchants.
- Education:Learning management systems, student information platforms, and assessment tools. Budget constraints in public districts favor modular, subscription-based procurement over custom builds.
Finance generates the highest contract values per engagement while retail exhibits the most compressed vendor selection timelines.
Technology Stack:
Maturity curves separate established enterprise languages from rapidly evolving frameworks preferred by venture-backed startups.
- Java:Enterprise-grade object-oriented language with extensive library ecosystems. German Mittelstand manufacturers rely on Java backends for Industry 4.0 ERP integrations requiring decade-long support horizons.
- Python:Interpreted language dominant in data science, machine learning, and automation workflows. EU AI Act compliance tooling in France and the Netherlands increasingly specifies Python for risk classification pipelines.
- Javascript:Ubiquitous front-end runtime with Node.js server-side extensions. Real-time trading dashboards in US finance favor Javascript for sub-second DOM updates.
- Ruby:Dynamic language emphasizing developer productivity and convention-over-configuration. Early-stage SaaS ventures in India select Ruby for rapid prototype-to-production cycles.
Java sustains the largest installed base among Fortune 500 enterprises while Python expands most quickly in AI-infused application development.
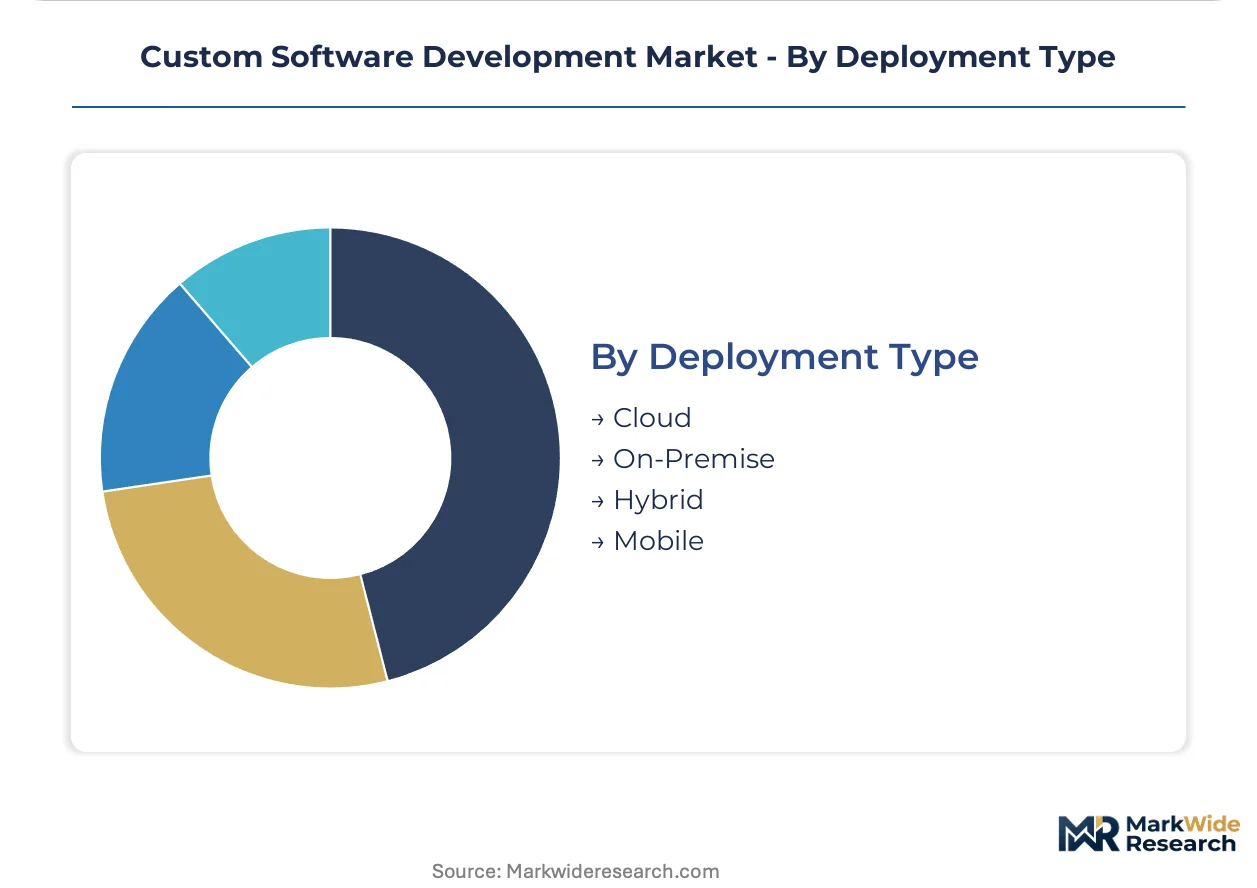
Deployment Type:
Margin profiles diverge sharply between capital-intensive on-premise installations and recurring-revenue cloud managed services.
- Cloud:Public, private, or multi-tenant infrastructure delivered as managed services. GDPR Article 32 encryption mandates accelerate EU healthcare migration to ISO 27001-certified cloud environments.
- Hybrid:Workload distribution across on-premise and cloud resources with unified orchestration. German automotive OEMs deploy hybrid architectures to keep proprietary design data local while leveraging cloud compute for simulation.
- On-Premise:Self-managed infrastructure within client-controlled data centers. US defense agencies mandate on-premise deployment for classified systems under ITAR export control regulations.
- Mobile:Native iOS/Android or cross-platform applications with offline synchronization capabilities. Indian fintech startups prioritize mobile-first deployment to capture underbanked rural populations.
Cloud deployment captures the majority of new contract value while hybrid configurations climb fastest among industrial manufacturers balancing sovereignty with scalability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US healthcare providers exhibit the lowest price elasticity, absorbing 30-40% staffing cost premiums for HIPAA-certified architects. German Mittelstand manufacturers and Indian offshore buyers operate at the highest elasticity, squeezing vendor margins through competitive rebidding.
United States
FDA software-as-medical-device guidance and SEC cybersecurity disclosure rules drive compliance-heavy procurement. HIPAA Security Rule enforcement compels cloud migration from legacy on-premise systems. The Boston-Cambridge corridor anchors healthcare AI development, while New York and Chicago financial centers sustain trading platform demand.
Germany
EU AI Act risk classification mandates and GDPR Article 32 encryption requirements elevate technical specifications. Industry 4.0 connectivity gaps in mid-sized industrial manufacturers create bespoke ERP integration opportunities. Baden-Württemberg automotive clusters and Bavarian industrial hubs deploy hybrid architectures balancing data sovereignty with cloud scalability.
India
BIS IT service standards certification attracts Fortune 500 outsourcing contracts demanding 24/7 coverage. RBI and SEBI data localization norms reshape financial services delivery structures. Bangalore and Hyderabad development centers capture cross-border engagements, while Mumbai and Pune serve domestic enterprise modernization.
United Kingdom
Public-sector procurement frameworks mandate competitive rebidding at 24-month intervals, compressing vendor lock-in. NHS digital transformation programs sustain patient portal and telemedicine platform demand. London financial services and Manchester public-sector clusters drive distinct procurement rhythms.
France
CNIL enforcement of GDPR breach-notification automation elevates privacy-by-design contract clauses. ANSM medical device software guidance tightens validation protocols for healthcare applications. Paris fintech and Lyon industrial software clusters respond through centralized national procurement pre-qualification frameworks.
Custom Software Development Market Key Industry Players
Global systems integrators and offshore-centric delivery specialists split the market along compliance-complexity and cost-optimization vectors. Tier-one consultancies capture multi-year transformation programs with recurring architecture governance revenue. Boutique firms penetrate mid-market verticals through specialized domain expertise. Dominant competitive moves include cloud migration practice buildouts and DevOps automation tooling acquisitions.
Within the premium-tier integration segment, Accenture exemplifies the cloud-first transformation archetype through recurring architecture engagements. Tata Consultancy Services anchors large-scale healthcare and finance programs across North America and Europe. IBM occupies a hybrid positioning, competing through AI-infused development tooling that extends enterprise retention cycles.
| Leading Market Players |
|---|
| Accenture |
| Cognizant |
| Tata Consultancy Services |
| Infosys |
| Capgemini |
| Wipro |
| IBM |
| HCL Technologies |
| DXC Technology |
| Others |
Cost & Logistics Intelligence
Single-source dependency on certified cloud architects in Germany and the United States compresses margin structures while amplifying pricing tier spreads between HIPAA-validated engagements and commodity development contracts. This talent chokepoint forces procurement teams to accept 30-40% staffing premiums for compliance-heavy healthcare platforms while squeezing vendor margins through competitive rebidding in offshore delivery clusters.
Pricing Analysis
Recurring architecture governance revenue drives lifetime value differentiation between initial development contracts and multi-year managed service engagements. Three-tier pricing structure across premium, standard, and economy levels separates HIPAA-certified healthcare platforms from mid-market ERP integrations and commodity offshore development. Cost compression in the standard tier intensifies because Indian BIS-certified hubs attract Fortune 500 contracts through aggressive competitive rebidding. US healthcare providers exhibit the lowest price sensitivity, absorbing certified architect premiums, while German Mittelstand manufacturers operate at the highest elasticity.
Supply Chain Analysis
Accenture, Tata Consultancy Services, and IBM concentrate delivery capacity across North American and European enterprise accounts. India, Germany, and the United States anchor geographic supply concentration for cross-border development hubs, onshore compliance specialists, and hybrid cloud architects. Talent pipelines draw from computer science graduates in Bangalore, certified security engineers in Berlin, and FDA-experienced developers in Boston-Cambridge. Single-source vulnerability in certified cloud architecture talent triggers project delays when SOC 2 Type II audit queues extend sales cycles. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and national procurement frameworks in France and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection centers on unified control planes consolidating fragmented CI/CD pipelines, with interoperability mandates from EU AI Act risk classification reshaping vendor selection criteria.
For Market Incumbents: Insulate recurring revenue streams by embedding proprietary DevOps tooling into client infrastructure, creating switching costs that outlast initial contract terms. Acquire specialized compliance automation vendors to capture EU AI Act documentation requirements before boutique competitors consolidate this attach-rate opportunity. Vertical integration into managed cloud services offsets margin pressure from fixed-price development contracts.
For New Entrants and Emerging Players: German Mittelstand manufacturers lack bespoke ERP integrations for Industry 4.0 connectivity, representing immediate white-space opportunity. Target mid-sized industrial automation buyers in Baden-Württemberg and Bavaria through hybrid architecture specialization balancing data sovereignty with cloud scalability. Lead generation through Industry 4.0 consortium partnerships accelerates trust-building with risk-averse procurement committees.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platforms with upstream control over both tooling and managed services. Long-term viability over the next decade hinges on recurring architecture governance revenue rather than project-based development fees. Acquisition target archetype: boutique firms with certified healthcare or finance domain expertise and established FDA or SEC compliance track records. Watch for inflection when national procurement frameworks in France and the Netherlands accelerate vendor pre-qualification velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies fragmented CI/CD pipelines into control planes that compress vendor switching. |
| Acquisition of Specialist Firm | Captures EU AI Act compliance tooling attach-rates before boutique consolidation. |
| Geographic Expansion | Targets underpenetrated German Mittelstand ERP integration gaps for Industry 4.0 connectivity. |
| Strategic Partnership | Embeds DevOps automation into client infrastructure through Industry 4.0 consortium alliances. |
| Product Launch | Introduces HIPAA-validated cloud architectures that command 30-40% staffing premiums. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and national procurement framework databases to validate market sizing and growth trajectory assumptions. Primary interviews engaged CTOs at US healthcare providers, IT procurement officers at German automotive OEMs, platform engineers at Indian development centers, and integration specialists at European systems integrators. Bottom-up triangulation across project pipeline data and top-down validation through regulatory filing analysis ensures segmentation accuracy across deployment models and vertical applications.
Forecast inputs include cloud migration velocity, compliance certification queue lengths, and DevOps tooling adoption curves across the projection horizon. Segmentation dimensions modeled encompass development methodology, target industry vertical, technology stack maturity, deployment architecture, organization size tier, and regional regulatory cluster. CAGRs derive from trend extrapolation of historical contract value data adjusted for enforcement timelines of HIPAA Security Rule, EU AI Act, and GDPR Article 32 mandates.
The forecast holds incumbent behavior within observed patterns; aggressive platform consolidation moves by hyperscaler-backed entrants would shift outcomes beyond projected ranges. Quarterly review of SOC 2 Type II audit queue lengths, national procurement framework vendor pre-qualification velocity, and certified architect salary inflation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Server Virtualization Software Market
Software & Services
Theatrical Distribution Software Market
Software & Services
Subscription Management Software Market
Software & Services
Personal Budgeting Software Market
Software & Services
Global Handyman Software Market
Software & Services
Referral Marketing Software Market
Software & Services
Broadcast Scheduling Software Market
Software & Services
VFX Software Market
Software & Services
Relational Database Management System Market
Software & Services
North America Servicenow Store Apps Market
Software & Services
Global Open API Market
Software & Services
HR Management Software (Personnel and Organization) Market
Software & Services
Construction Jobsite Management Software Market
Software & Services
Global Webinar Software Market
Software & Services
Ecommerce Inventory Management Software Market
Software & Services
Global Online Expense Management Software Market