
 Global Sales Enablement Platform Market | 2026-2036
Global Sales Enablement Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sales Enablement Platform Market Foresight
Platform licensing revenue is reconfiguring how vendors capture lifetime value from enterprise relationships. Seismic leverages extensive content personalization engines to dominate complex B2B sales cycles. Highspot sustains differentiation through AI-driven revenue intelligence that tightens marketing-sales alignment. Outreach anchors its position inside the workflow layer, embedding enablement directly within seller communication channels.
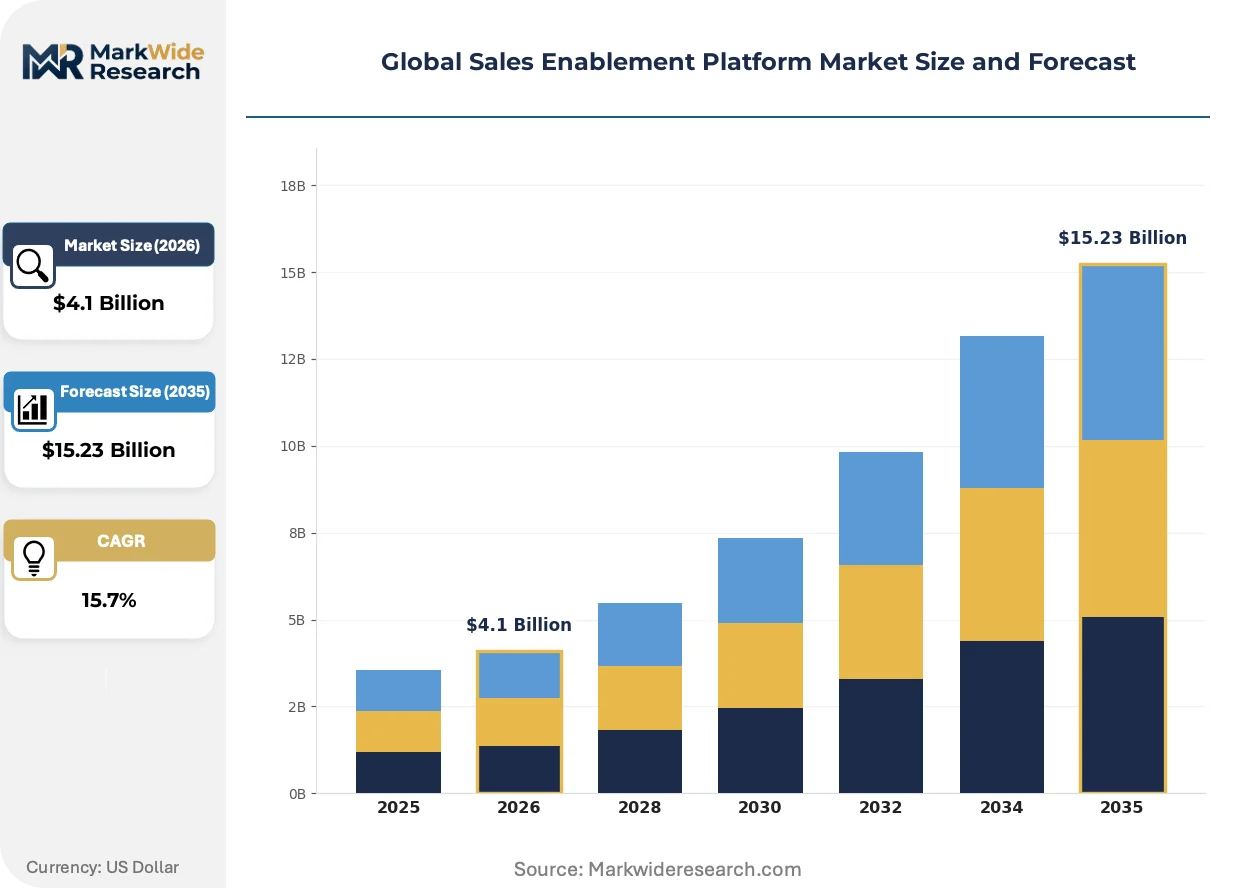
A sales enablement platform integrates content management, training delivery, analytics, and CRM connectivity into a unified system that orchestrates seller activities and measures revenue outcomes. These platforms typically deploy via multi-tenant cloud architecture with API-first design to ensure real-time data synchronization across enterprise software stacks. Cloud-based and SaaS deployment models command the dominant share of new bookings as IT departments prioritize subscription economics over capital-intensive on-premise installations. Content management and analytics modules represent the fastest-expanding solution areas, driven by C-suite pressure to attribute sales outcomes to specific enablement interventions rather than intuition-based coaching.
GDPR in Europe and state-level privacy statutes in the United States constrain how buyer interaction data flows through analytics pipelines, forcing vendors to architect regional data residency options. The EU AI Act introduces additional compliance layers for automated coaching recommendations and predictive scoring embedded within these platforms. Financial services regulators including SEC and FINRA in the United States impose record-keeping and supervision requirements that shape how communication tools within enablement suites capture and archive seller-buyer interactions. Stakeholders must evaluate whether their vendor's regulatory roadmap keeps pace with evolving AI governance and sector-specific supervision mandates before committing to long-term platform contracts.
Market Dynamics
AI-embedded coaching modules are compressing sales cycle timelines while forcing vendors to rearchitect data pipelines for real-time personalization at enterprise scale.
Growth Catalysts
- EU AI Act compliance mandates:Financial services firms across Germany and France are procuring platforms with built-in algorithmic audit trails to satisfy automated decision-making transparency requirements.
- Cloud migration deadlines:Fortune 500 IT departments are retiring on-premise sales infrastructure, creating replacement demand for API-first SaaS architectures with native CRM synchronization.
- SEC and FINRA record-keeping rules:US wealth management firms require communication capture and archival capabilities that only integrated enablement suites can provide.
Market Restraints
- GDPR data residency costs:Vendors must maintain separate EU-hosted infrastructure, inflating operational overhead and complicating single-tenant pricing models.
- Legacy CRM entrenchment:Deep Salesforce and Microsoft Dynamics deployments create switching friction that extends sales cycles and elevates customer acquisition costs.
- AI talent scarcity:Machine learning engineers with sales domain expertise command premium compensation, constraining vendor R&D velocity.
Strategic Opportunities
- Japan's financial sector digitization:METI-backed initiatives are accelerating advisor platform adoption among regional banks with limited existing sales technology.
- Conversational AI and revenue intelligence fusion:Vendors integrating real-time call transcription with predictive scoring can displace point-solution providers in mid-market accounts.
- India's BFSI expansion:RBI supervision guidelines and SEBI distribution norms are creating compliance-driven demand among mutual fund and insurance distributors.
Industry Challenges
- Cross-functional enablement alignment:Marketing and sales operations teams maintain conflicting KPIs, complicating platform configuration and user adoption metrics.
- Content personalization at scale:Maintaining brand compliance while allowing field-level customization requires governance workflows that most enterprises have not operationalized.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sales Enablement Platform Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $15.23 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Solution Offering: Content Management, Training & Coaching, Analytics & Reporting, CRM Integration, Communication Tools Application: Lead Generation, Customer Onboarding, Sales Training, Performance Tracking, Deal Management End User: Technology Providers, Consultancy Firms, Financial Services, Manufacturing Companies, Telecommunications |
| Companies Covered | Seismic, Highspot, Showpad, MindTickle, Outreach, SalesLoft, Bigtincan, Mediafly, Allego, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sales Enablement Platform Market Shifts & Advancements
Generative AI is rewriting how sales content gets produced, distributed, and optimized, collapsing the gap between marketing creation and field consumption.
Real-time conversation intelligence is digitizing seller-buyer interactions into structured data streams. Enterprise software buyers in the United States are deploying these tools across inside sales teams within ninety-day implementation windows. The technology is digitizing coaching from episodic manager reviews into continuous, algorithmically-triggered skill interventions.
The EU AI Act's risk classification framework is forcing vendors to document training data provenance and model performance benchmarks for automated coaching recommendations. Platform providers serving European financial services must now maintain algorithmic impact assessments as standard contract deliverables. German and French procurement teams are prioritizing vendors with pre-certified conformity assessment procedures.
Subscription-based pricing for enablement modules is displacing perpetual licensing in enterprise negotiations. Mid-market buyers in the United Kingdom and Australia are demanding consumption-aligned metrics tied to active seller seats rather than total employee counts. This shift compresses vendor revenue recognition timelines while accelerating platform refresh cycles.
Global Sales Enablement Platform Market Segmentation
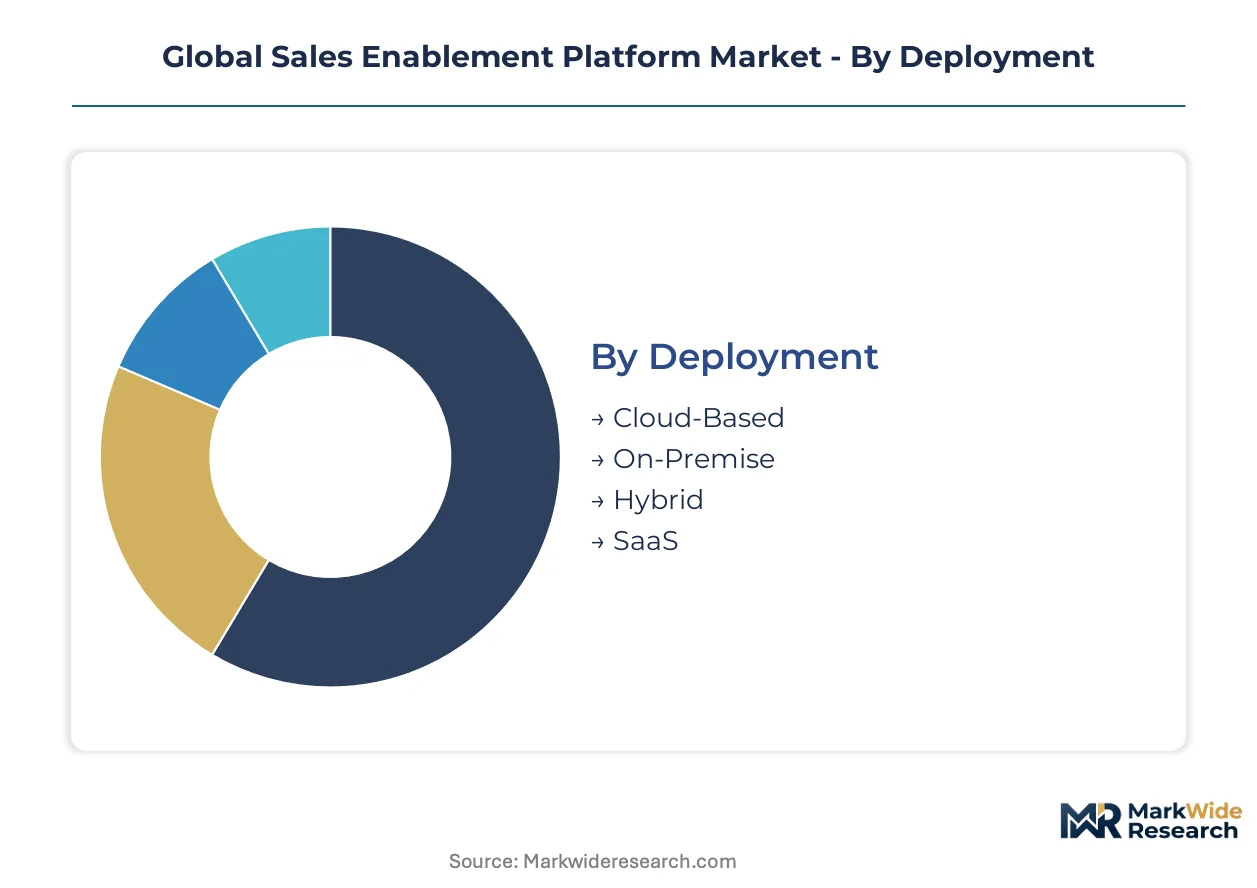
Sales enablement platforms fragment across deployment architectures, solution modules, use cases, and buyer industries. Procurement teams evaluate segments based on integration complexity, compliance requirements, and revenue attribution capabilities.
Deployment:
Mature cloud configurations dominate enterprise procurement while hybrid architectures address transitional compliance needs.
- Cloud-Based:Multi-tenant architectures with API-first design synchronize real-time data across enterprise software stacks. Fortune 500 IT departments in the United States prioritize these configurations to retire capital-intensive infrastructure and align with subscription economics.
- SaaS:Subscription delivery models compress vendor revenue recognition timelines while accelerating platform refresh cycles. Mid-market buyers in the United Kingdom and Australia demand consumption-aligned metrics tied to active seller seats rather than total employee counts.
- On-Premise:Legacy installations persist in highly regulated environments requiring localized data sovereignty.
- Hybrid:Split architectures accommodate EU data residency mandates while maintaining core cloud functionality.
Cloud-Based handles the majority of throughput; SaaS is expanding most quickly on share.
Solution Offering:
Revenue attribution pressure concentrates demand in modules that connect enablement interventions to closed-won outcomes.
- Content Management:Centralized repositories with field-level customization workflows balance brand compliance against personalization needs. C-suite pressure to attribute sales outcomes to specific interventions drives fastest expansion in this category.
- Analytics & Reporting:Real-time dashboards pipeline seller activity data into predictive scoring models. Financial services firms deploy these tools to satisfy SEC and FINRA supervision requirements for advisor productivity measurement.
- Training & Coaching:AI-embedded modules compress sales cycle timelines through algorithmically-triggered skill interventions.
- CRM Integration:Native synchronization with Salesforce and Microsoft Dynamics reduces switching friction in entrenched enterprise environments.
- Communication Tools:Conversation capture and archival capabilities address record-keeping mandates in wealth management and insurance distribution.
Content Management captures the largest deployment footprint; Analytics & Reporting is climbing the fastest on commercial momentum.
Application:
Use case prioritization reflects organizational maturity in sales operations and revenue operations alignment.
- Deal Management:Pipeline orchestration tools integrate content, coaching, and forecasting into unified seller workflows. Complex B2B sales cycles in technology and manufacturing verticals concentrate demand here.
- Sales Training:Continuous skill development platforms digitize coaching from episodic manager reviews into real-time interventions. Ninety-day implementation windows are standard for inside sales teams in the United States.
- Lead Generation:Prospecting automation connects marketing-qualified leads to enablement content sequences.
- Customer Onboarding:Post-sale enablement reduces churn through structured adoption pathways.
- Performance Tracking:Individual and team metrics feed into compensation and promotion decisions.
Deal Management anchors enterprise procurement value; Sales Training is gaining share fastest as AI coaching modules mature.
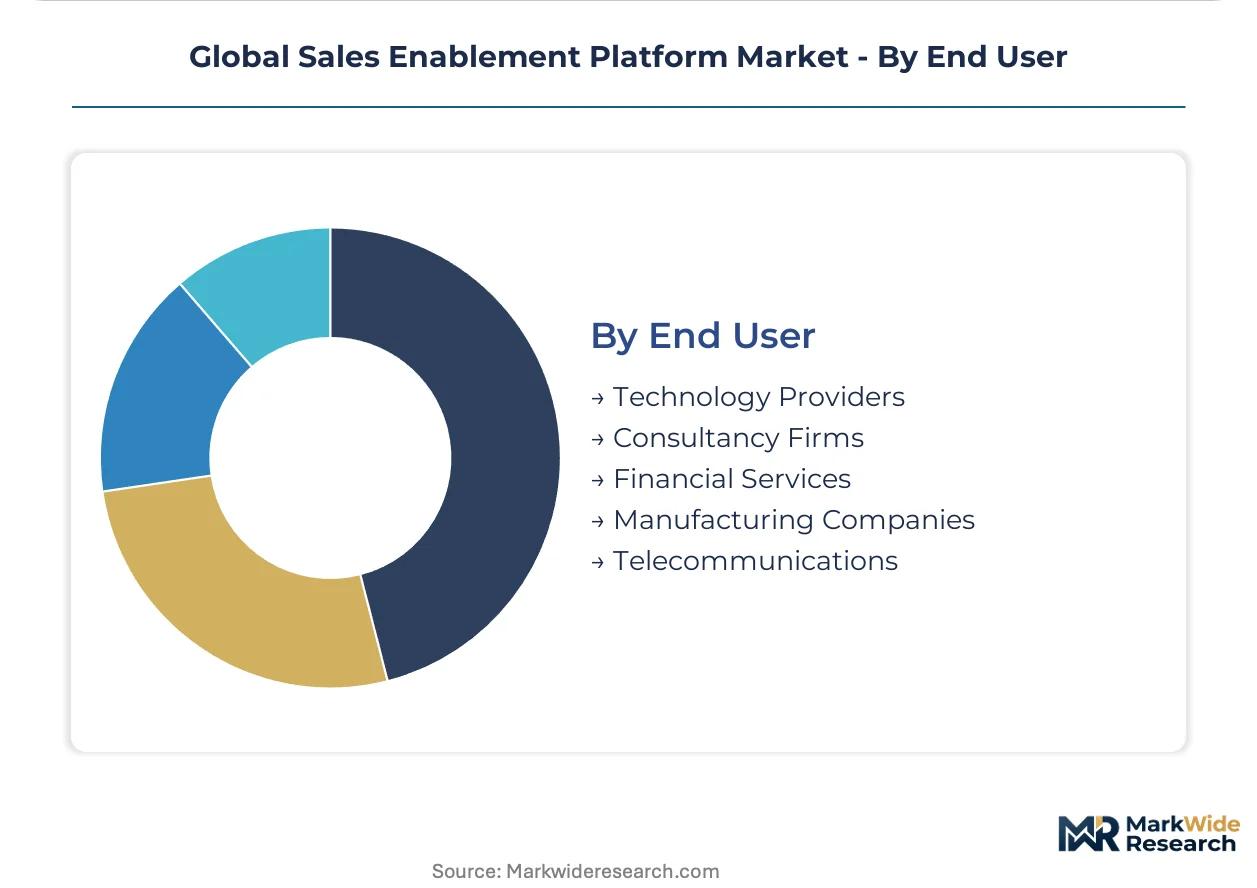
End User:
Industry-specific compliance requirements reshape platform configuration and vendor selection criteria.
- Financial Services:Wealth management and insurance distributors require communication capture, algorithmic audit trails, and automated decision-making transparency. SEC, FINRA, and EU AI Act compliance mandates drive replacement of legacy supervision infrastructure.
- Technology Providers:SaaS vendors with complex product portfolios leverage extensive content personalization engines to accelerate enterprise sales cycles.
- Consultancy Firms:Knowledge-intensive selling demands rapid content customization for proposal development and client presentations.
- Manufacturing Companies:Long sales cycles with technical specifications require structured deal management and stakeholder alignment tools.
- Telecommunications:High-velocity inside sales operations prioritize real-time conversation intelligence and predictive scoring.
Financial Services commands the deepest compliance-driven investment; Technology Providers are scaling fastest on cloud-native adoption patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform engineering talent and enterprise software procurement budgets concentrate heavily in the United States, with secondary development clusters emerging across Western Europe and select Asia-Pacific financial centers.
United States
Fortune 500 sales organizations drive SaaS penetration deepest here, with cloud migration mandates accelerating replacement of on-premise infrastructure. SEC and FINRA record-keeping rules shape wealth management procurement decisions. The San Francisco Bay Area and Greater Boston anchor vendor R&D operations and enterprise customer concentration.
Germany
Financial services firms across Frankfurt and Munich prioritize algorithmic audit trails for automated coaching recommendations. The EU AI Act's risk classification framework forces vendors to document training data provenance. Baden-Württemberg's industrial Mittelstand generates demand for deal management tools in complex B2B manufacturing sales.
United Kingdom
Mid-market buyers in London and the Southeast demand consumption-aligned pricing tied to active seller seats rather than total employee counts. GDPR compliance costs inflate operational overhead for vendors maintaining EU-hosted infrastructure. The City's wealth management sector requires communication capture capabilities meeting FCA supervision guidelines.
Japan
METI-backed digitization initiatives accelerate advisor platform adoption among regional banks with limited existing sales technology. Financial sector regulators impose record-keeping requirements that favor integrated enablement suites. Tokyo's insurance distribution sector generates compliance-driven demand for structured onboarding and performance tracking modules.
India
RBI supervision guidelines and SEBI distribution norms create compliance-driven demand among mutual fund and insurance distributors in Mumbai and Delhi-NCR. SaaS deployment models gain traction as IT departments prioritize subscription economics. Bangalore's technology services sector employs enablement platforms to accelerate enterprise sales cycles for offshore delivery contracts.
Global Sales Enablement Platform Market Competitive Landscape
Content-centric specialists and workflow-embedded platforms split the market between marketing-sales alignment tools and communication-layer solutions. The vendor base organizes around three strategic archetypes: extensive personalization engines, AI-driven revenue intelligence providers, and seller workflow integrators. Dominant competitive moves include API-first architecture investments to reduce CRM switching friction and generative AI module development to compress content production cycles.
Within the personalization-engine tier, Seismic and Highspot exemplify divergent approaches to complex B2B sales enablement. Seismic occupies a position emphasizing content personalization at enterprise scale, while Highspot anchors revenue intelligence capabilities that tighten marketing-sales alignment. Outreach sits within the workflow-embedded archetype, representing vendors that embed enablement directly within seller communication channels rather than as standalone systems.
| Leading Market Players |
|---|
| Seismic |
| Highspot |
| Showpad |
| MindTickle |
| Outreach |
| SalesLoft |
| Bigtincan |
| Mediafly |
| Allego |
| Others |
Supply & Pricing Matrix
EU data residency mandates as a regulatory chokepoint determine both pricing tier spreads and supply chain shape by forcing vendors to maintain parallel infrastructure stacks across jurisdictions, inflating operational overhead while segmenting procurement options by compliance tier.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across automated coaching modules, separating premium certified offerings from standard uncertified alternatives. Price differentiation rests on algorithmic audit trail completeness and regional data hosting guarantees. Cost compression in mid-market SaaS tiers is intensifying because buyers demand seat-based consumption metrics rather than enterprise-wide licensing. Regional banks in Japan exhibit highest price sensitivity; Fortune 500 technology providers show least.
Supply Chain Analysis
Extended payment terms from hyperscaler cloud providers now anchor vendor working capital requirements, compressing cash conversion cycles for platform developers. Engineering talent concentrates in the United States, India, and Germany. Cloud compute and API infrastructure draw from Amazon Web Services, Microsoft Azure, and Google Cloud Platform. Single-source vulnerability in AI model training data creates concentration risk. Distribution runs through direct enterprise sales teams and strategic systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sales enablement platforms sit at a platform-economics inflection where API-first interoperability with Salesforce and Microsoft ecosystems determines competitive survival, not standalone feature depth.
For Market Incumbents: Pre-empt workflow-embedded competitors by deepening native CRM synchronization beyond basic API connections to real-time bi-directional data streaming. Acquire conversational AI specialists before mid-market entrants consolidate this capability. Vertical integration into proprietary large language model training reduces dependency on third-party AI infrastructure. For New Entrants and Emerging Players: Regional banks in Japan with METI digitization mandates but limited legacy sales technology represent the most penetrable entry point. India's mutual fund distributors facing SEBI compliance deadlines offer secondary white-space. A compliance-first go-to-market positioning against EU AI Act requirements differentiates against established vendors. For Investors and Strategic Acquirers: The EU AI Act's full enforcement timeline reshapes the acquisition landscape by privileging vendors with pre-certified conformity assessment procedures. Viable targets combine workflow-embedded architecture with financial services compliance depth. Watch for algorithmic audit trail standardization across German and French procurement teams as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Salesforce and Microsoft Dynamics synchronization reduces switching friction in entrenched enterprise environments. |
| Acquisition of Specialist Firm | Conversational AI providers with real-time transcription capabilities accelerate revenue intelligence module deployment. |
| Geographic Expansion | EU-hosted infrastructure investments satisfy GDPR residency mandates for German and French financial services procurement. |
| Product Launch | Generative AI content modules collapse production cycles between marketing creation and field seller consumption. |
| Strategic Partnership | Systems integrator alliances extend reach into mid-market accounts lacking dedicated sales operations teams. |
Research Methodology
Initial hypotheses were tested against primary input from chief revenue officers, sales operations directors, IT procurement officers, and platform integration specialists and refined through secondary validation against SEC filings, hyperscaler capex disclosures, App Annie enterprise software rankings, and EU regulatory filing databases. Bottom-up vendor revenue estimates triangulated against top-down enterprise software spending allocations.
Demand-supply balance across deployment models, solution modules, organization size tiers, and vertical compliance requirements anchored the analytical framework. CAGRs were derived from segment-level growth rate reconciliation. Forecast inputs included cloud migration deadline schedules from Fortune 500 IT departments and AI Act implementation timelines across European financial centers.
Stress conditions across cloud infrastructure cost inflation, AI talent compensation escalation, and regulatory enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about CRM entrenchment persistence and compliance-driven replacement cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Procurement Software Market
Software & Services
Enterprise Intellectual Property (IP) Management Software Market
Software & Services
DevOps Market
Software & Services
Global Maintenance Management Software Market
Software & Services
Global Web Scraper Software Market
Software & Services
Movie Editing Software Market
Software & Services
Scanning and Migration Software Market
Software & Services
Construction Suites Software Market
Software & Services
Landing Page Creation Software Market
Software & Services
Patent Management Software Market
Software & Services
Self-Storage Software Market
Software & Services
Stock Control Software Market
Software & Services
Desktop Hypervisor Market
Software & Services
Automotive Digital Retailing Software Market
Software & Services
Electronic Batch Records Market
Software & Services
Asia-Pacific IT Services Market