
 Fire Software Market | 2026-2036
Fire Software Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Software Market Insights
Platform licensing revenue is reconfiguring margin pools away from perpetual desktop licenses toward recurring SaaS arrangements. Tyler Technologies leverages deep municipal ERP integration to anchor its position in government agency deployments. ESO Solutions sustains dominance in incident reporting through specialized data analytics architecture. Vector Solutions competes aggressively on mobile-first training and compliance modules for firefighter management.
Fire software encompasses digital platforms that manage emergency response workflows, asset tracking, personnel certification, and real-time incident command through cloud-native architectures with API interoperability and NFPA 1401-compliant data logging. Cloud-based solutions now capture the fastest expansion as fire departments abandon on-premise server maintenance, while SaaS deployment models concentrate recurring revenue streams and reduce total cost of ownership for budget-constrained municipal buyers. Desktop software retains residual share in rural jurisdictions with limited broadband infrastructure, though hybrid architectures are bridging this gap.
NFPA standards, ISO 9001 certification frameworks, and the U.S. SAFER grant program collectively shape procurement specifications and federal funding eligibility for fire software acquisitions. The U.S. Federal Communications Commission mandates interoperable communications protocols that directly influence platform design requirements for multi-agency incident response. Stakeholders must monitor evolving cybersecurity mandates for critical infrastructure software and assess whether their architecture accommodates emerging mutual-aid data-sharing protocols before competitive displacement accelerates.
Market Dynamics
Municipal fire departments are abandoning perpetual licensing for cloud-native SaaS platforms, compressing vendor revenue cycles while embedding NFPA 1401-compliant data logging as a non-negotiable procurement specification.
Growth Catalysts
- NFPA 1401 Compliance Mandates:U.S. fire departments face tightened incident documentation standards, forcing platform upgrades and expanding addressable market for certified vendors.
- Federal Grant Funding:The U.S. SAFER grant program specifically earmarks capital for digital command and personnel management systems, accelerating municipal procurement timelines.
- Broadband Infrastructure Expansion:Rural jurisdictions in Australia and Germany are gaining fiber and 5G access, dissolving the technical barrier that previously constrained cloud deployment outside urban cores.
Market Restraints
- Budget Fragmentation:Municipal procurement cycles stretch 18-36 months across volunteer departments in the U.S. Midwest, freezing mid-market vendor pipelines.
- Cybersecurity Certification Costs:FedRAMP and StateRAMP compliance for cloud platforms serving government agencies demands six-figure audit investments that exclude smaller software vendors.
- Legacy Data Migration Complexity:Decades of paper-based incident logs and non-standard digital formats in German fire departments create integration friction that prolongs deployment timelines.
Strategic Opportunities
- Interoperable Mutual-Aid Networks:Multi-jurisdictional data-sharing protocols in California and Victoria, Australia create demand for API-first platforms that transcend municipal boundaries.
- AI-Enabled Predictive Analytics:Convergence of machine learning with NFPA-compliant incident databases enables fire risk scoring for insurance underwriters and urban planners as adjacent revenue streams.
- Mobile-First Training Modules:Firefighter certification tracking via smartphone applications penetrates volunteer-heavy regions in Queensland and Bavaria where desktop access remains sporadic.
Industry Challenges
- Cybersecurity Talent Scarcity:Municipal IT departments lack personnel to manage zero-trust architectures and endpoint detection for cloud-connected emergency response systems.
- ISO 9001 Certification Timelines:Vendors face 12-18 month approval cycles to meet quality management standards required by German and Australian government tenders, delaying market entry.
- Legacy Radio System Integration:P25 and TETRA communication infrastructures in U.S. and European fire departments resist seamless API connectivity, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Software Market |
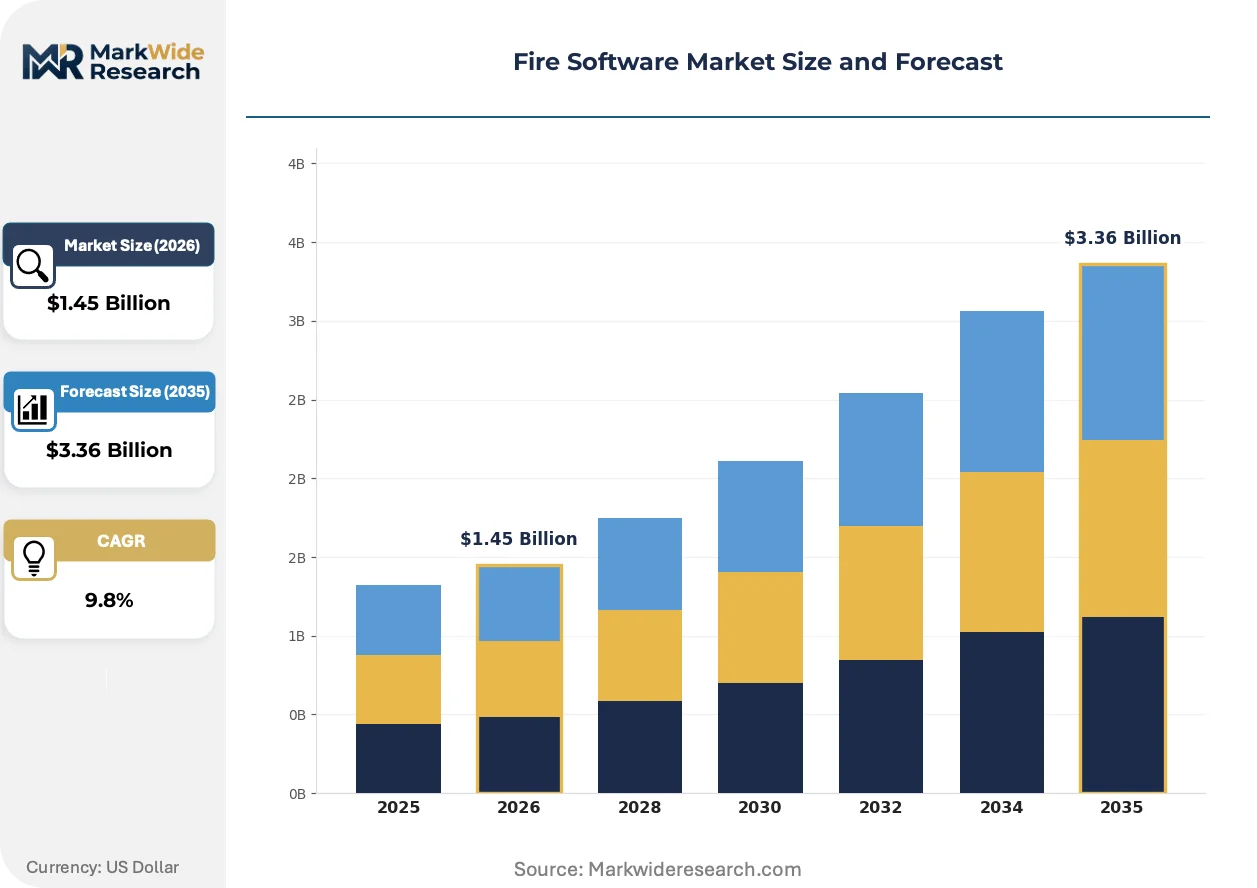
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $3.36 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Firefighter Management, Incident Reporting, Risk Assessment, Resource Allocation Type: Cloud-Based Solutions, Mobile Applications, Desktop Software, Open Source Tools Deployment: On-Premise, Hybrid, SaaS, Virtual Solutions End User: Government Agencies, Insurance Firms, Private Fire Departments, Educational Institutions |
| Companies Covered | Tyler Technologies, ESO Solutions, Vector Solutions, ImageTrend, firecloud365, Accela, CivicPlus, FirePrograms Software, StationSmarts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Software Market Trends and Innovations
Fire software architectures are converging around real-time data fusion, embedding incident command with asset tracking and personnel certification in unified platforms that compress response coordination from minutes to seconds.
Edge computing is hybridizing with centralized cloud processing to enable split-second decision support at incident scenes. Fire departments in Texas and New South Wales deploy ruggedized tablets that process thermal imaging and hazardous material databases locally, then synchronize with command centers upon network restoration. This architecture is hybridizing vendor business models, forcing simultaneous investment in lightweight edge software and heavy cloud infrastructure.
The U.S. Federal Communications Commission mandates interoperable communications protocols under FirstNet authority, compelling platform redesign for multi-agency incident response. Equipment manufacturers must certify devices for Band 14 LTE access, reshaping procurement specifications for command vehicles and mobile data terminals. California and Florida departments lead compliance adoption, creating specification templates that cascade to smaller jurisdictions.
Subscription pricing now dominates municipal procurement, displacing perpetual licenses with annual SaaS arrangements that bundle maintenance, updates, and cybersecurity monitoring. German cities including Munich and Hamburg negotiate multi-year enterprise agreements that consolidate training, incident reporting, and asset management under single-vendor contracts. This consolidation concentrates vendor selection power with procurement officers rather than operational chiefs.
Fire Software Market Segmentation
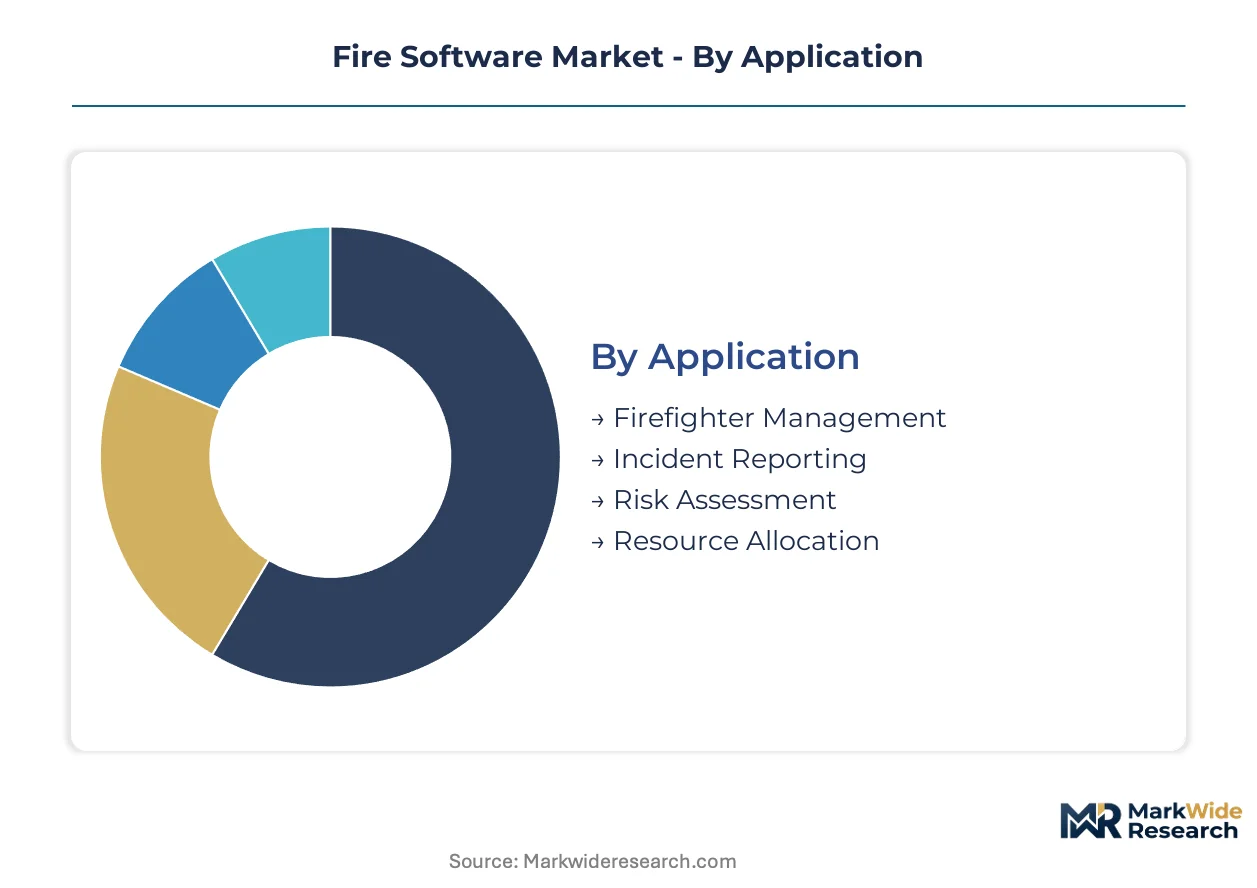
Fire software procurement diverges sharply across operational contexts, with municipal command centers prioritizing real-time interoperability while volunteer departments optimize for mobile accessibility and minimal infrastructure. Understanding these segment boundaries clarifies where platform architectures must flex versus where standardization dominates.
Application:
Use-case intensity varies from life-critical incident command to administrative compliance tracking, creating divergent performance thresholds and integration requirements across functional modules.
- Firefighter Management:Personnel certification tracking, shift scheduling, and training compliance modules integrate with NFPA 1401 data standards. Demand concentrates in U.S. municipal departments consolidating fragmented volunteer rosters under unified digital systems, driven by SAFER grant eligibility requirements that mandate documented workforce analytics.
- Incident Reporting:Real-time documentation platforms capture apparatus deployment, casualty tracking, and property damage assessments through cloud-native architectures with API interoperability. German fire departments in Bavaria and North Rhine-Westphalia are deploying these systems fastest, constrained by legacy paper-log migration complexity that prolongs implementation timelines.
- Risk Assessment:Predictive analytics engines score structural fire probability and hazardous material exposure for urban planning and insurance underwriting.
- Resource Allocation:Dynamic dispatch algorithms optimize apparatus positioning based on incident frequency heatmaps and mutual-aid network availability.
The dominant share belongs to Incident Reporting, while Firefighter Management is closing the gap fastest.
Type:
Technical architecture choices determine total cost of ownership and deployment feasibility across broadband-constrained rural jurisdictions versus fiber-connected urban centers.
- Cloud-Based Solutions:Centralized SaaS platforms eliminate on-premise server maintenance while embedding automated cybersecurity patching and NFPA-compliant data logging. Australian fire services in Victoria and New South Wales are expanding these deployments fastest, enabled by federal broadband infrastructure investments dissolving previous connectivity barriers.
- Mobile Applications:Smartphone-native interfaces deliver incident command, thermal imaging integration, and hazardous material database access through ruggedized edge devices. Texas fire departments deploy these for split-second scene decision support, with local processing that synchronizes to command centers upon network restoration.
- Desktop Software:Perpetual-license platforms persist in Midwest U.S. volunteer departments with limited IT staffing and unreliable internet connectivity.
- Open Source Tools:Community-developed alternatives attract budget-constrained educational institutions and small private departments seeking customization without licensing fees.
Cloud-Based Solutions command the largest installed base, though Mobile Applications are expanding most quickly as edge computing capabilities mature.
Deployment:
Infrastructure ownership models reflect municipal risk tolerance for data sovereignty versus operational agility, with cybersecurity certification costs filtering vendor participation.
- SaaS:Fully managed subscription arrangements bundle maintenance, updates, and FedRAMP-compliant security monitoring into predictable annual expenditures. German cities including Munich and Hamburg negotiate multi-year enterprise agreements consolidating training, incident reporting, and asset management under single-vendor contracts.
- Hybrid:Split architectures process sensitive personnel data on-premise while routing incident analytics through cloud pipelines. U.S. departments in California and Florida favor this model to satisfy mutual-aid data-sharing protocols without exposing internal systems.
- On-Premise:Self-hosted servers retain residual share in jurisdictions with strict data residency mandates or chronic connectivity failures.
- Virtual Solutions:Containerized deployments abstract hardware dependencies for rapid scaling during multi-agency emergency responses.
SaaS holds the dominant position, while Hybrid deployments are gaining share fastest as zero-trust security architectures mature.
End User:
Procurement authority and funding mechanisms diverge across public-sector appropriations, insurance risk engineering budgets, and institutional training allocations.
- Government Agencies:Municipal fire departments drive volume through federal grant programs and ISO certification requirements that specify digital command platform functionality. U.S. agencies anchor this segment, with procurement cycles stretching 18-36 months across volunteer-heavy Midwest jurisdictions.
- Insurance Firms:Underwriters deploy fire risk scoring algorithms to refine property premiums and catastrophe modeling. Demand clusters in Australia and Germany where regulatory frameworks encourage predictive analytics integration with building code enforcement.
- Private Fire Departments:Industrial site protection teams at chemical plants and logistics hubs purchase specialized hazardous material response modules.
- Educational Institutions:Fire academies and training centers license certification tracking platforms for curriculum management and student progress analytics.
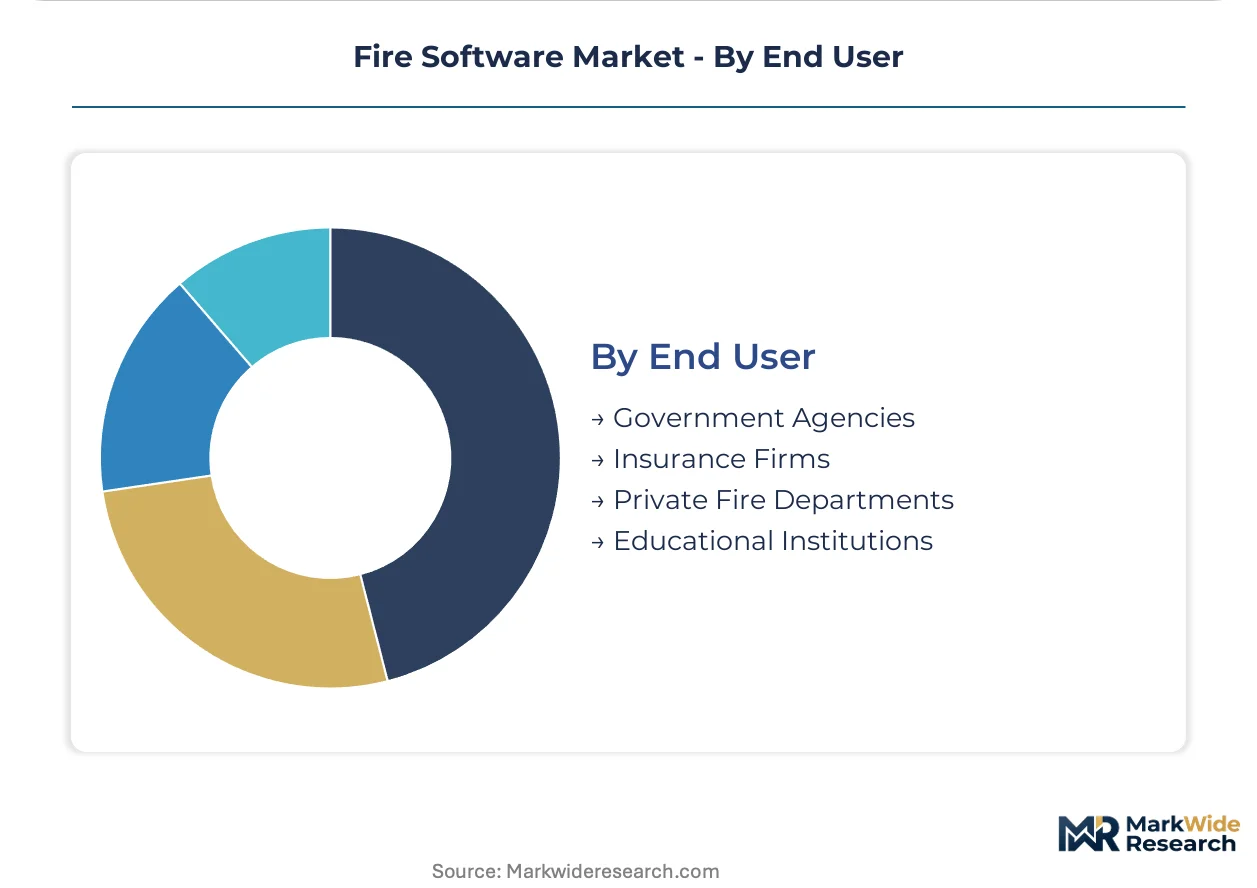
Government Agencies account for the dominant share, while Insurance Firms are climbing the fastest as AI-enabled risk analytics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement elasticity varies sharply across jurisdictions. German cities absorb premium SaaS pricing with minimal friction, while Midwest U.S. volunteer departments stretch 18-36 month cycles over modest five-figure budgets. Australian federal broadband investments dissolve prior connectivity barriers fastest.
United States
The SAFER grant program channels federal capital toward digital command platforms, compressing procurement timelines for NFPA 1401-compliant vendors. FCC FirstNet mandates reshape multi-agency interoperability specifications. California and Florida departments lead Band 14 LTE certification, creating specification templates that cascade to smaller jurisdictions.
Germany
Bavaria and North Rhine-Westphalia fire services deploy incident reporting systems fastest despite legacy paper-log migration friction. ISO 9001 certification requirements filter vendor participation in government tenders. Munich and Hamburg negotiate multi-year enterprise agreements consolidating training, reporting, and asset management under single-vendor SaaS contracts.
Australia
Federal broadband infrastructure investments dissolve previous connectivity barriers in Victoria and New South Wales, accelerating cloud-native deployments. Queensland volunteer-heavy regions drive mobile-first certification tracking via smartphone applications. The country's national emergency management framework encourages predictive analytics integration with building code enforcement.
Canada
Provincial procurement frameworks in Ontario and British Columbia emphasize FedRAMP-aligned cybersecurity certification for cloud platforms serving government agencies. Health Canada guidelines influence data residency requirements for personnel records. Prairie volunteer departments retain hybrid architectures to satisfy mutual-aid protocols without exposing internal systems.
Fire Software Market Competitive Landscape
Municipal ERP integrators and specialized incident reporting architects split the market between platform consolidation and functional depth. The vendor base concentrates around three strategic archetypes: government software generalists with deep ERP integration, vertical specialists with NFPA-compliant data architectures, and mobile-first training platforms targeting volunteer-heavy jurisdictions. Dominant competitive moves include strategic partnerships with broadband infrastructure providers and portfolio diversification into predictive analytics for insurance underwriters.
Within the government software generalist tier, Tyler Technologies exemplifies deep municipal ERP anchoring, while ESO Solutions occupies a position as the vertical specialist archetype in incident reporting. Vector Solutions represents the mobile-first training platform model competing aggressively on firefighter certification modules.
| Leading Market Players |
|---|
| Tyler Technologies |
| ESO Solutions |
| Vector Solutions |
| ImageTrend |
| firecloud365 |
| Accela |
| CivicPlus |
| FirePrograms Software |
| StationSmarts |
| Others |
Pricing and Supply Chain Analysis
Munich and Hamburg anchor European SaaS capacity for municipal fire software, with their enterprise procurement offices concentrating vendor selection power and compressing price negotiation cycles for multi-year training and incident reporting bundles. This geographic concentration of buyer sophistication feeds downstream into pricing structures that stratify across federal compliance tiers, mobile deployment complexity, and cybersecurity certification levels.
Pricing Analysis
Post-deployment service revenue and extended cybersecurity monitoring contracts anchor lifetime value in municipal fire software procurement. Three-tier pricing structure across premium, standard, and economy levels segments by NFPA 1401 certification grade and FedRAMP authorization status, with premium tiers bundling real-time mutual-aid interoperability. Cost compression in mid-market SaaS offerings is intensifying because volunteer-heavy jurisdictions in Queensland and the U.S. Midwest demand smartphone-native alternatives at lower per-seat rates. Government agencies with SAFER grant eligibility show least price sensitivity, while private industrial fire departments exhibit highest cost consciousness.
Supply Chain Analysis
Contract manufacturing for ruggedized mobile hardware concentrates with EMS providers in Taiwan, China, and South Korea who assemble thermal imaging tablets and Band 14 LTE terminals. Software development draws from cloud infrastructure providers in the United States, Ireland, and Germany hosting FedRAMP-authorized data centers. Single-source vulnerability persists in specialized P25 radio middleware components. Distribution runs through municipal procurement cooperatives and federal grant administration channels rather than direct vendor sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from AI-native incident analytics platforms that bypass traditional NFPA-compliant data architectures, forcing defensive repositioning around data moats and certification barriers.
For Market Incumbents: Insulate core incident reporting revenue by deepening integration with Tyler Technologies-style municipal ERP systems and accelerating FedRAMP StateRAMP dual certification to exclude undercapitalized challengers. Threat from horizontal AI platforms entering predictive risk scoring demands proprietary data network effects as the primary defensive lever. For New Entrants and Emerging Players: Build out mobile-first training modules for volunteer-heavy regions in Queensland and Bavaria where desktop infrastructure remains sporadic and incumbent penetration is weakest. White-space sits in AI-enabled fire risk scoring for Australian insurance underwriters integrated with national building code enforcement frameworks. Go-to-market through federal broadband infrastructure partnerships dissolves connectivity barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because NFPA 1401 compliance mandates and ISO 9001 certification timelines create structural barriers that concentrate vendor selection power with established platforms. Acquisition targets with existing FedRAMP authorization and mutual-aid network API deployments offer fastest path to municipal wallet share. Signal to watch is SAFER grant allocation shifts toward cybersecurity-hardened command platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates incident reporting, asset tracking, and personnel certification under unified NFPA 1401-compliant architectures. |
| Strategic Partnership | Broadband infrastructure alliances in Victoria and New South Wales dissolve rural connectivity barriers for cloud deployment. |
| Acquisition of Specialist Firm | AI-native risk scoring capabilities penetrate insurance underwriter budgets adjacent to municipal fire department procurement. |
| Geographic Expansion | Bavaria and North Rhine-Westphalia offer fastest incident reporting adoption despite legacy paper-log migration friction. |
| Product Launch | Edge-computing tablets with thermal imaging integration address Texas fire department split-second scene decision requirements. |
Research Methodology
A standing panel of fire chiefs, municipal IT procurement officers, NFPA standards committee members, and cloud platform integration specialists provided ongoing calibration against secondary validation from SEC filings of government software vendors, FCC FirstNet deployment databases, SAFER grant award records, and ISO 9001 certification registries. Bottom-up triangulation across departmental deployment timelines and top-down vendor revenue segmentation anchored market sizing.
Scenario-bracketing around federal grant funding volatility, broadband infrastructure buildout pace, and cybersecurity mandate enforcement intensity shaped projections across the analysis window. Segmentation dimensions modeled include deployment architecture, department size tier, volunteer versus career staffing ratio, and regional regulatory cluster. CAGRs derived from fitted adoption curves cross-referenced against historical municipal software procurement cycle data and cloud migration elasticity estimates for public safety agencies.
Stress conditions across SAFER grant appropriation levels, FedRAMP audit backlogs, and mutual-aid protocol standardization timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about certification timeline stickiness and cloud connectivity diffusion. Quarterly review of federal grant award velocity and state-level cybersecurity procurement mandates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Equity Management Software Market
Software & Services
Global Kiosk Software Market
Software & Services
Intellectual Property Software Market
Software & Services
MRP Software Market
Software & Services
Software-Defined Machine Market
Software & Services
Global Script Writing Software Market
Software & Services
Medical E-Commerce Software Market
Software & Services
Global Open API Market
Software & Services
Global Quantum Computing Software Market
Software & Services
SAP HANA and S4HANA Market
Software & Services
ID Photo Software Market
Software & Services
Global Municipal Software Market
Software & Services
Geophysical Software Service Market
Software & Services
Global Janitorial Software Market
Software & Services
Sales Training Software Market
Software & Services
Global Pre-Employment Testing Software Market