
 Mobile Enterprise Application Development Platform Market | 2026-2036
Mobile Enterprise Application Development Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Enterprise Application Development Platform Market Outlook
Enterprise software procurement is tilting toward cloud-native delivery models as IT departments abandon perpetual licensing. Microsoft Corporation leverages its Azure ecosystem to anchor platform subscriptions within Fortune 500 accounts. SAP SE competes through deep ERP integration that sustains renewal rates among manufacturing clients. Oracle Corporation dominates database-centric deployments where in-house development teams require managed runtime environments.
A mobile enterprise application development platform constitutes an integrated software environment enabling the design, testing, deployment, and management of business applications across iOS, Android, and progressive web interfaces, typically incorporating visual development interfaces, backend connectors, and over-the-air update mechanisms. Low-code platforms lead current deployment volumes by compressing time-to-market for internal workflow tools, while no-code solutions represent the fastest-expanding segment as citizen developers in retail and healthcare bypass formal IT queues. Hybrid cloud deployment models capture widening margin pools by addressing data residency requirements without sacrificing elastic scaling.
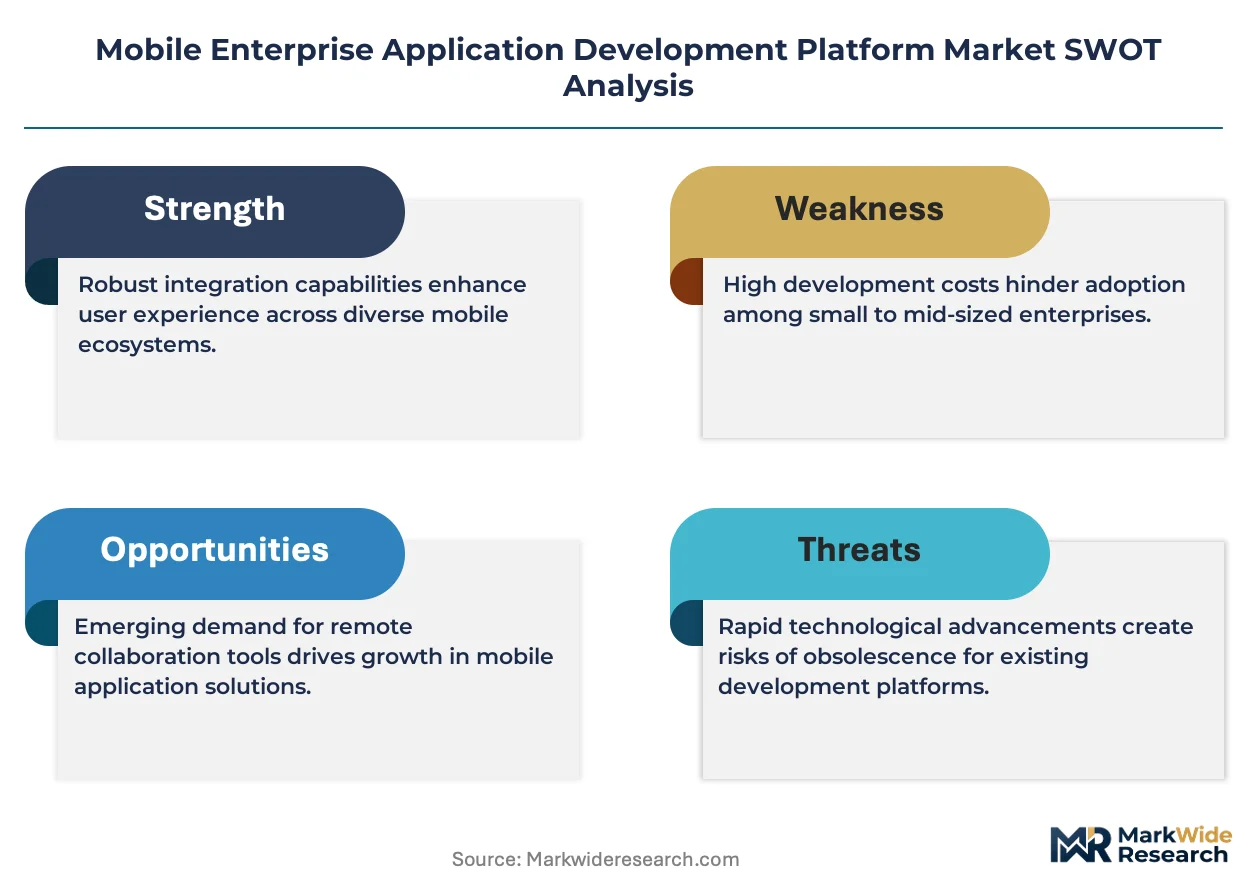
FDA guidelines on mobile health software, EU GDPR cross-border transfer protocols, and India's BIS cloud security standards collectively elevate compliance costs for platform vendors seeking multi-territory certification. HIPAA-aligned encryption mandates in US healthcare verticals restrict vendor selection to architectures with audited key management. Stakeholders must monitor how fragmented sovereignty requirements reshape platform architecture roadmaps and partner qualification criteria.
Market Dynamics
Financial services firms now mandate sub-90-day application deployment cycles, forcing platform vendors to compress provisioning pipelines and pre-certify compliance modules for HIPAA and GDPR alignment.
Growth Catalysts
- EU GDPR cross-border protocols:Mandatory data residency controls drive enterprise procurement of hybrid cloud deployment models with sovereign infrastructure options.
- Healthcare workflow digitization:FDA mobile health software guidelines accelerate platform adoption for clinical trial data capture and remote patient monitoring interfaces.
- India's BIS cloud security standards:Government-mandated encryption tiers create certified vendor lists that streamline public sector procurement decisions.
Market Restraints
- Multi-territory certification costs:Fragmented sovereignty requirements between EU, US, and India force vendors to maintain parallel compliance architectures.
- Specialized mobile security talent scarcity:Shortage of engineers with runtime hardening and key management expertise inflates implementation timelines.
- Legacy ERP integration complexity:Deep coupling with SAP and Oracle systems creates switching friction that extends sales cycles.
Strategic Opportunities
- Germany's Industrie 4.0 manufacturing mandates:Factory floor mobile applications for predictive maintenance remain underpenetrated among mid-tier automotive suppliers.
- Edge-to-cloud runtime convergence:5G private networks and containerized microservices enable millisecond-latency industrial control applications.
- India's PLI scheme for IT hardware:Local data center infrastructure incentives reduce latency for domestic financial services deployments.
Industry Challenges
- Citizen developer governance gaps:No-code adoption by retail and healthcare business units outpaces IT security review capacity.
- Cross-platform testing matrix expansion:Fragmentation across iOS, Android, and progressive web interfaces multiplies QA resource requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Enterprise Application Development Platform Market |
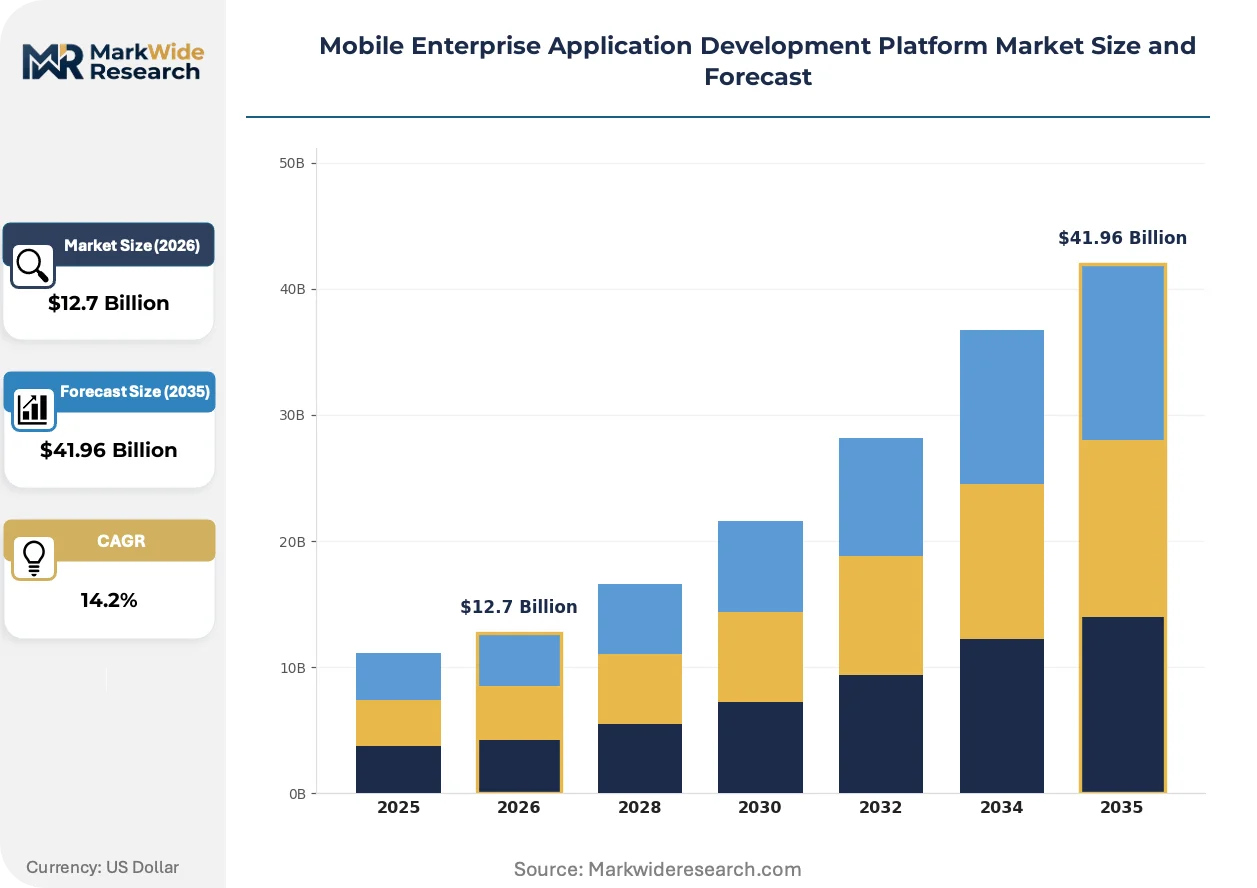
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $41.96 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Code Platforms, No-Code Solutions, Traditional Development Tools, Cloud-Based Services Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Large Enterprises, SMBs, Government Organizations, Educational Institutions Industry Vertical: Healthcare, Retail, Finance, Manufacturing |
| Companies Covered | Microsoft Corporation, SAP SE, Oracle Corporation, IBM Corporation, Salesforce, Inc., Adobe Systems, Inc., Apple, Inc., Google LLC, OutSystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Enterprise Application Development Platform Market Strategic Shifts
Platform architecture is fragmenting across three vectors: runtime environment heterogeneity, compliance automation embedding, and procurement model unbundling. Vendors must now engineer for sovereignty-first deployment while abstracting complexity from line-of-business developers.
Containerized microservices paired with serverless functions are hybridizing traditional mobile backend architectures. Manufacturing clients in Germany adopt these patterns fastest, collapsing six-month integration projects into weeks. The approach compresses vendor switching costs while enabling granular scaling of compute-intensive analytics modules.
EU AI Act risk classification rules now govern automated decision-making in financial services mobile applications. Platform vendors must embed algorithmic audit trails and human-in-the-loop overrides. US healthcare verticals face parallel FDA scrutiny on diagnostic software, driving consolidation around pre-validated component libraries.
Subscription unbundling now separates runtime fees from development seat licenses. Retail and healthcare buyers in the United States negotiate consumption-based pricing that ties platform costs to active monthly users. Procurement teams favor this structure for seasonal workforce applications where perpetual licensing created stranded capacity.
Mobile Enterprise Application Development Platform Market Segmentation
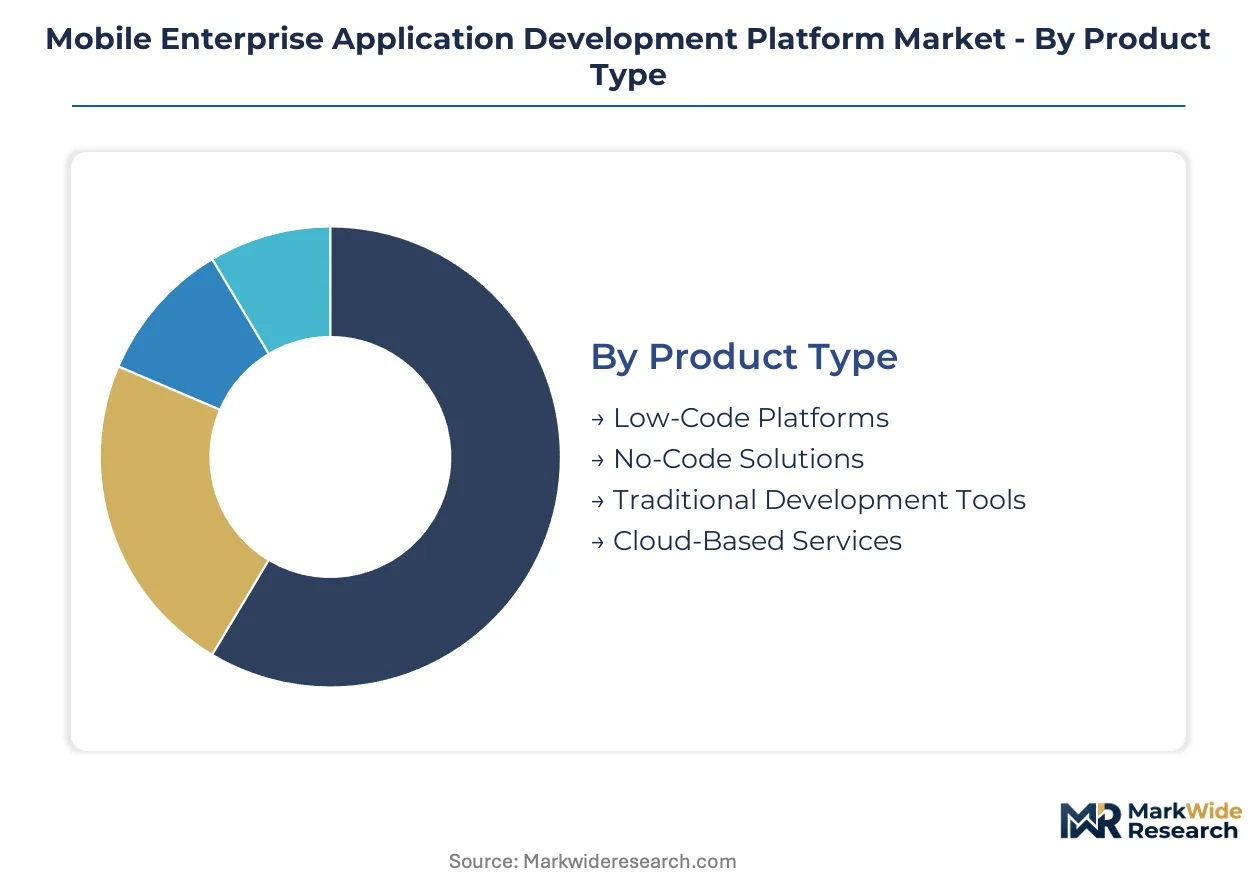
Segmentation in the mobile enterprise application development platform market reveals distinct procurement patterns across technical maturity, compliance posture, and organizational scale. Platform vendors must architect modular pricing and deployment options that map to these divergent buyer requirements rather than forcing uniform adoption.
Product Type:
Cost tier differentiation separates citizen developer tools from professional engineering environments, with pricing elasticity varying by seat volume and runtime consumption.
- Low-Code Platforms:Visual development interfaces with pre-built connectors compress application delivery timelines for internal workflow tools. Financial services firms in the United States now mandate sub-90-day deployment cycles, making these platforms the default procurement choice for compliance-heavy verticals.
- No-Code Solutions:Drag-and-drop interfaces enable business unit personnel to bypass formal IT queues entirely. Retail and healthcare citizen developers in India are expanding most quickly here, though governance gaps create security review backlogs that constrain enterprise rollout velocity.
- Traditional Development Tools:Native SDKs and IDE-based environments retain dominance among Oracle and SAP-integrated manufacturing systems requiring deep runtime customization.
- Cloud-Based Services:Managed backend infrastructure abstracts scaling complexity for variable-load applications, with Germany's automotive suppliers driving sovereign deployment demand.
Low-Code Platforms hold installed capacity. No-Code Solutions is rotating up the share rankings.
Deployment Model:
Application sensitivity to data residency requirements and latency constraints determines architecture selection across regulated industries.
- Hybrid Cloud:Sovereign infrastructure options paired with elastic burst capacity address EU GDPR cross-border protocols and India's BIS encryption mandates simultaneously. Manufacturing clients in Germany adopt containerized microservices on these patterns fastest, collapsing integration timelines from months to weeks.
- Public Cloud:Shared infrastructure delivers lowest unit economics for seasonal workforce applications where consumption-based pricing aligns cost with active monthly users.
- Private Cloud:Dedicated single-tenant environments satisfy HIPAA-aligned encryption mandates in US healthcare verticals requiring audited key management.
- On-Premises:Air-gapped runtime persists in defense and critical infrastructure sectors where network segmentation overrides cloud agility benefits.
Hybrid Cloud holds installed capacity. Public Cloud is rotating up the share rankings.
End User:
Customer type dictates sales cycle length, with procurement complexity scaling nonlinearly against organizational IT maturity.
- Large Enterprises:Fortune 500 accounts negotiate enterprise-wide platform subscriptions anchored within existing cloud ecosystems, with Microsoft Azure and SAP ERP integration sustaining renewal rates. These buyers demand pre-certified compliance modules for HIPAA and GDPR alignment.
- SMBs:Mid-market adopters prioritize consumption-based pricing that eliminates stranded capacity from perpetual licensing. India's PLI scheme for IT hardware reduces domestic latency for financial services deployments in this segment.
- Government Organizations:Public sector procurement in India follows BIS-certified vendor lists, while EU institutions require algorithmic audit trails under AI Act risk classification rules.
- Educational Institutions:Budget-constrained buyers favor no-code solutions for administrative automation, with seasonal enrollment driving variable user licensing.
Large Enterprises holds installed capacity. SMBs is rotating up the share rankings.
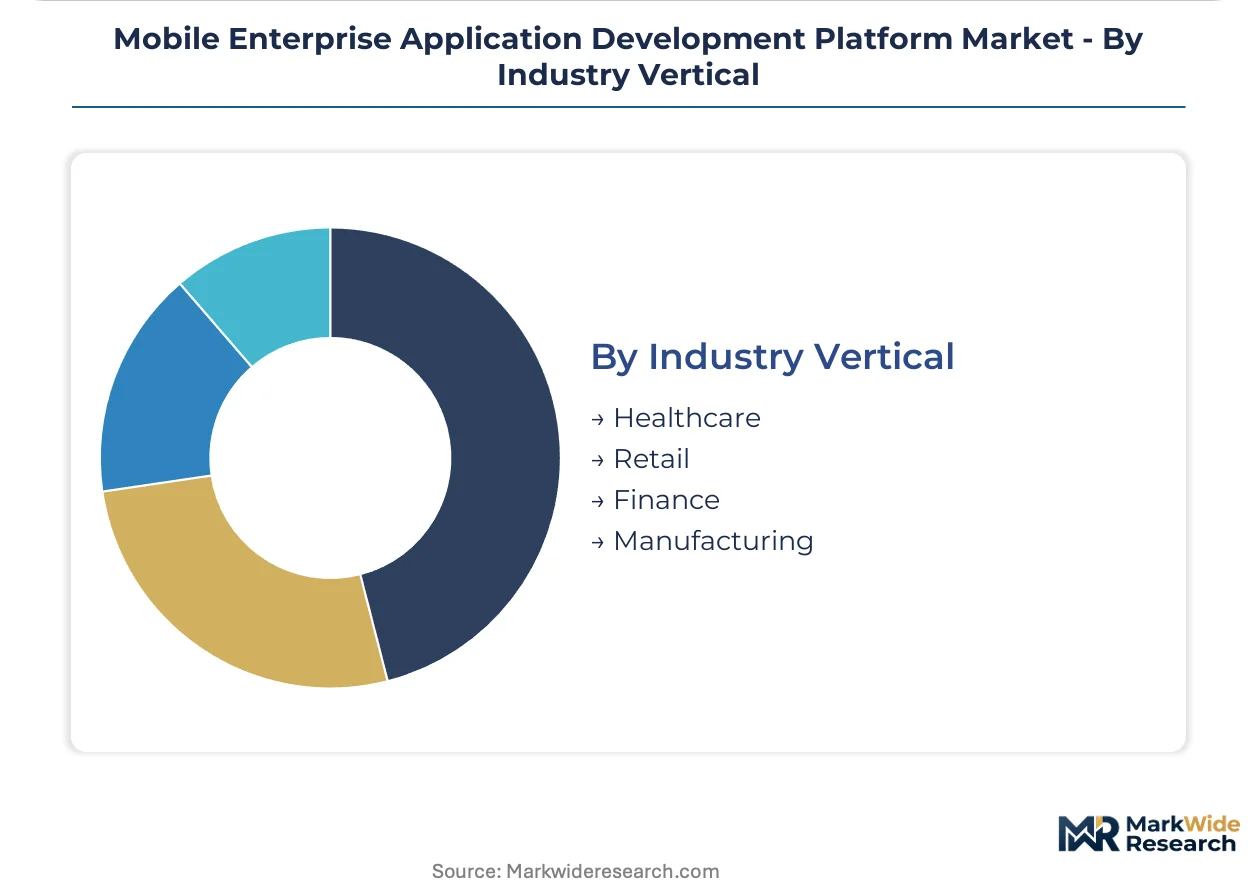
Industry Vertical:
Vertical-specific regulatory density shapes platform feature roadmaps and partner qualification criteria.
- Healthcare:FDA mobile health software guidelines and HIPAA encryption mandates restrict vendor selection to architectures with audited key management. Remote patient monitoring interfaces and clinical trial data capture are accelerating platform adoption here.
- Finance:EU AI Act risk classification rules govern automated decision-making in mobile applications, requiring human-in-the-loop overrides. Sub-90-day deployment mandates compress vendor provisioning pipelines.
- Manufacturing:Germany's Industrie 4.0 mandates drive factory floor mobile applications for predictive maintenance, with 5G private networks enabling millisecond-latency industrial control.
- Retail:Seasonal workforce fluctuations favor unbundled subscription models separating runtime fees from development seat licenses, with citizen developer governance gaps creating security review bottlenecks.
Finance holds installed capacity. Healthcare is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for IT hardware and Germany's Industrie 4.0 mandates are accelerating sovereign infrastructure investments. EU GDPR cross-border protocols and FDA mobile health guidelines reshape procurement criteria across major economies.
United States
Financial services firms in New York and Chicago now mandate sub-90-day application deployment cycles. HIPAA-aligned encryption mandates restrict vendor selection to architectures with audited key management. The Boston-Cambridge corridor concentrates healthcare platform deployments for clinical trial data capture.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg adopt factory floor mobile applications for predictive maintenance. EU GDPR cross-border protocols drive hybrid cloud procurement with sovereign infrastructure options. Stuttgart's manufacturing cluster leads 5G private network deployments for millisecond-latency industrial control.
India
Retail and healthcare citizen developers in Maharashtra and Karnataka expand no-code adoption fastest. BIS cloud security standards create certified vendor lists streamlining public sector procurement. Mumbai's financial services sector drives consumption-based pricing negotiations for seasonal workforce applications.
United Kingdom
London-based enterprises anchor platform subscriptions within existing cloud ecosystems. EU AI Act risk classification rules govern automated decision-making in financial services mobile applications. The Thames Valley corridor concentrates fintech platform deployments requiring algorithmic audit trails.
Japan
Manufacturing clients in the Chubu region around Nagoya adopt containerized microservices patterns fastest. METI industrial digitization programs compress integration timelines for legacy ERP systems. Osaka's automotive electronics cluster drives demand for runtime hardening expertise.
Mobile Enterprise Application Development Platform Market Competitive Environment
On the supply side, the industry is consolidating around cloud ecosystem anchors and ERP-integrated specialists. Tiered competitive dynamics separate hyperscale platform vendors from vertical-focused low-code specialists and open-source runtime providers. Strategic moves center on compliance module pre-certification and consumption-based pricing unbundling.
Within the ecosystem-anchored tier, Microsoft Corporation and SAP SE exemplify divergent competitive positions. Microsoft leverages its Azure cloud infrastructure to anchor enterprise subscriptions within Fortune 500 accounts. SAP competes through deep ERP integration that sustains renewal rates among manufacturing clients requiring legacy system connectivity. Oracle Corporation occupies a position among database-centric deployment specialists serving in-house development teams.
| Leading Market Players |
|---|
| Microsoft Corporation |
| SAP SE |
| Oracle Corporation |
| IBM Corporation |
| Salesforce, Inc. |
| Adobe Systems, Inc. |
| Apple, Inc. |
| Google LLC |
| OutSystems |
| Others |
Value Chain & Pricing Dynamics
Bavaria's sovereign cloud infrastructure cluster anchors European platform capacity, concentrating runtime hardening expertise among a tight vendor base that commands premium pricing for GDPR-aligned deployment modules. Downstream buyers in financial services absorb these premiums as non-negotiable compliance costs, while mid-market adopters in India negotiate consumption-based alternatives that compress vendor margins.
Pricing Analysis
Certification level creates the primary spread between platform tiers, with FDA-grade healthcare modules and EU AI Act-compliant financial services runtimes commanding substantial premiums over standard enterprise licenses. Subscription unbundling now separates per-seat development licenses from consumption-based runtime fees, with seasonal workforce applications in US retail driving the fastest adoption of variable pricing. Pricing pressure stems from open-source runtime alternatives commoditizing basic backend infrastructure. SMBs in India exhibit highest price sensitivity, while Fortune 500 accounts anchored in Azure ecosystems show lowest elasticity.
Supply Chain Analysis
Export controls on advanced encryption technologies limit flows of key management hardware and sovereign cloud infrastructure components between the United States, European Union, and China. Platform vendors source runtime environments from certified data centers in Germany, India, and Singapore, with containerized microservices architectures drawing from open-source orchestration layers. Single-source vulnerability concentrates in specialized mobile security engineering talent pools centered on Stuttgart and Bangalore. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Runtime hardening specialists with cross-border certification expertise represent the scarcest capability layer in this market, constraining vendor expansion velocity and inflating implementation timelines for regulated deployments.
For Market Incumbents: Entrench platform stickiness through deep ERP integration with SAP and Oracle manufacturing systems, extending renewal cycles beyond typical SaaS churn windows. Invest in pre-certified compliance modules for HIPAA and EU AI Act alignment to neutralize emerging low-code specialists. Vertical integration into sovereign cloud infrastructure in Germany and India defends margin position against hyperscaler marketplace disintermediation. For New Entrants and Emerging Players: Establish a beachhead in India's mid-tier financial services segment, where BIS certification requirements have created authorized vendor lists with limited incumbent penetration. Target no-code governance tooling as the most underdefended layer, with retail and healthcare citizen developers outpacing IT security review capacity. Lead with consumption-based pricing that eliminates stranded capacity objections from seasonal workforce buyers. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-automation play because regulatory fragmentation across EU, US, and Indian jurisdictions perpetuates demand for pre-certified platform architectures. Acquisition targets should display vertical-specific certification depth rather than horizontal scale. Watch FDA guidance expansion into diagnostic AI and EU AI Act enforcement intensity as inflection signals for platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Module Pre-Certification | FDA and EU AI Act alignment reduces sales cycles for healthcare and financial services procurement teams. |
| Sovereign Cloud Infrastructure Expansion | Germany's Industrie 4.0 mandates and India's PLI scheme create localized runtime capacity with data residency guarantees. |
| Consumption-Based Pricing Unbundling | Separating runtime fees from development seats aligns platform costs with seasonal workforce applications in US retail. |
| No-Code Governance Tooling Launch | Security review automation addresses citizen developer adoption gaps in healthcare and retail business units. |
| ERP Integration Specialist Acquisition | Deep SAP and Oracle connectivity sustains renewal rates among manufacturing clients with legacy system dependencies. |
Study Parameters
The analysis maps low-code platforms, no-code solutions, traditional development tools, and cloud-based services, each validated through CTOs, IT procurement officers, platform engineers, and integration specialists. Primary interviews with these stakeholders combined with secondary validation against SEC filings, hyperscaler capex disclosures, App Annie mobile deployment data, and BIS-certified vendor registries. Bottom-up segment sizing triangulates against top-down market envelope checks.
Assumptions held fixed include regulatory enforcement intensity for EU AI Act and FDA mobile health guidelines, while cloud adoption curves and citizen developer penetration rates were varied across scenarios. The projection horizon models deployment model, organization size, vertical industry, and integration complexity as core segmentation dimensions. CAGRs derive from elasticity-adjusted adoption curves and replacement cycle analysis for legacy ERP-integrated systems.
Stress conditions across GDPR cross-border protocol enforcement, BIS certification timeline delays, and mobile security talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Material shifts in FDA diagnostic software jurisdiction expansion or EU AI Act risk classification granularity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Sports Facility Scheduling and Management Software Market
Software & Services
Global Thermal Analysis Software Market
Software & Services
Global Calendar Scheduling Software Market
Software & Services
Global Corporate Wellness Software Market
Software & Services
Storyboarding Software Market
Software & Services
Global Enterprise Architecture Tools Market
Software & Services
Procurement Software Market
Software & Services
Global Invoice Automation Software Market
Software & Services
Content As a Service (Caas) Market
Software & Services
Global Electrical Computer-Aided Design (ECAD) Market
Software & Services
Gym Motion Tracking Software Market
Software & Services
PLM Software Market
Software & Services
Global Funeral Home Software Market
Software & Services
Media Editing App Market
Software & Services
Camera Tracking Software Market
Software & Services
Global Charity Accounting Software Market