
 Non-Profit Software Market | 2026-2036
Non-Profit Software Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Profit Software Market Analytics
Faith-based organizations are unwinding the historical dominance of secular charities in software procurement, as congregations and religious ministries digitize tithing, volunteer coordination, and member outreach at accelerated rates. Salesforce leverages its CRM architecture to anchor enterprise-grade donor engagement across multi-site ministries. Blackbaud sustains deep vertical specialization in advancement and alumni management for higher-education affiliated nonprofits. Bloomerang competes on usability-driven conversion, occupying the mid-market tier where smaller development teams prioritize intuitive interfaces over configurable complexity.
Non-profit software encompasses purpose-built applications for constituent relationship management, fundraising automation, grant lifecycle tracking, and program outcome measurement, typically delivered through multi-tenant cloud architectures with role-based access controls and audit-ready reporting modules. The software type dimension shows donor management platforms maturing while grant management solutions capture expanding margin pools as federal and foundation compliance requirements tighten. Cloud-based deployment now leads volume uptake though hybrid configurations persist among organizations with legacy on-premise accounting systems and heightened data residency concerns.
The Federal Trade Commission and state attorneys general enforce donor privacy and charitable solicitation regulations that elevate compliance functionality to a purchase prerequisite, while the IRS mandates standardized Form 990 disclosures that shape reporting module design. GDPR and emerging state-level privacy statutes in California and Virginia impose cross-border data handling protocols on international nonprofits operating dual-jurisdiction programs. Stakeholders must monitor whether emerging AI-driven personalization tools trigger new consent and algorithmic transparency obligations before embedding them into donor outreach workflows.
Market Dynamics
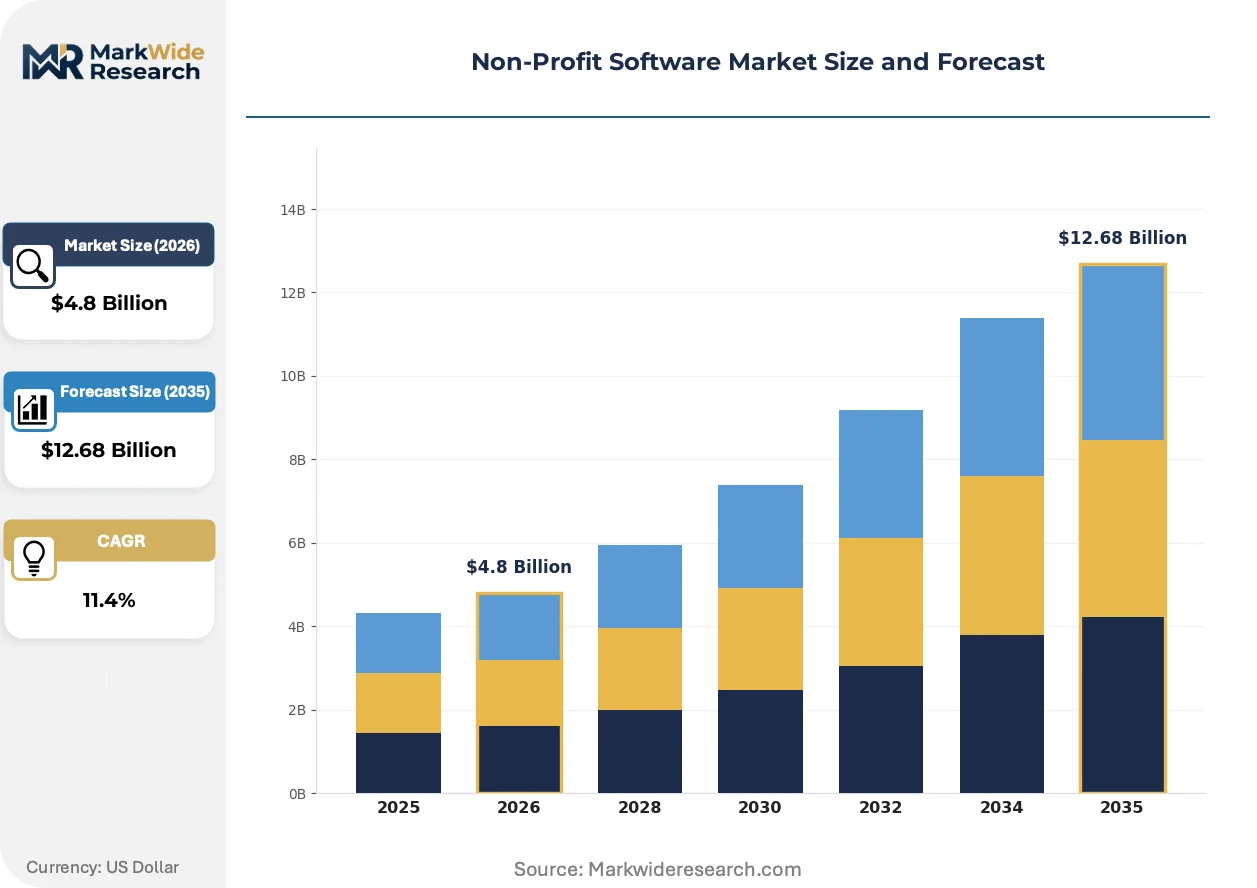
Cloud migration mandates from data protection authorities are compressing procurement cycles and forcing legacy system replacements across charitable and faith-based organizations alike. This regulatory pressure is reshaping vendor selection criteria toward audit-ready architectures and cross-border data compliance.
Growth Catalysts
- GDPR and State Privacy Statutes:California's CCPA and Virginia's CDPA impose data handling protocols that drive demand for compliant donor management platforms. International nonprofits operating dual-jurisdiction programs must upgrade systems to avoid penalties.
- Faith-Based Digitization:Congregations and religious ministries are accelerating software adoption for tithing automation, volunteer coordination, and member outreach, outpacing traditional charitable entities in procurement velocity.
- Federal Compliance Requirements:The IRS mandates standardized Form 990 disclosures that shape reporting module design, compelling nonprofits to replace manual processes with automated audit trails.
Market Restraints
- Legacy System Entrenchment:Organizations with decades-old on-premise accounting systems face high switching costs and data migration risks that delay cloud transitions.
- IT Talent Scarcity:Smaller development teams at mid-market nonprofits lack specialized skills for API integration and security configuration, constraining implementation depth.
- Data Residency Requirements:Heightened concerns over cross-border data storage limit vendor options for organizations serving sensitive populations or operating in restrictive jurisdictions.
Strategic Opportunities
- Grant Management Automation:Federal and foundation compliance requirements are tightening, expanding margin pools for solutions that automate lifecycle tracking and outcome reporting.
- AI-Driven Personalization:Emerging tools for donor outreach workflows present white space, though stakeholders must first navigate consent and algorithmic transparency obligations under developing regulatory frameworks.
- Hybrid Deployment Models:Organizations with residual on-premise infrastructure seek bridge architectures that preserve legacy investments while enabling cloud scalability.
Industry Challenges
- Integration Complexity:Nonprofits struggle to synchronize new donor management platforms with existing financial systems, CRM databases, and email marketing tools without disrupting operations.
- Compliance Timeline Pressure:The FTC and state attorneys general enforce donor privacy and charitable solicitation regulations that elevate functionality to a purchase prerequisite, shortening evaluation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Profit Software Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Fundraising, Donor Management, Grant Management, Event Management Deployment Model: On-Premise, Cloud-Based, Hybrid, Open Source End User: Charities, Foundations, Advocacy Groups, Community Organizations Functionality: Accounting, Reporting, Communication, Volunteer Management |
| Companies Covered | Blackbaud, Salesforce, Bloomerang, Microsoft, Oracle NetSuite, DonorPerfect, Neon One, Bonterra, Pushpay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Profit Software Market Evolving Landscape
Artificial intelligence capabilities are fragmenting competitive positioning across vendor tiers, with enterprise platforms embedding predictive analytics while mid-market providers emphasize usability over configurable complexity.
Machine learning for donor propensity scoring is bifurcating the competitive landscape. Large ministries and multi-site faith organizations deploy predictive models to optimize major gift cultivation and reduce donor attrition. This capability compression is widening the functionality gap between enterprise-grade platforms and usability-focused alternatives.
GDPR enforcement actions by European data protection authorities are accelerating cross-border compliance investments. The regulation's extraterritorial reach forces international nonprofits to implement data localization and consent management architectures. Faith-based organizations with European congregations face the steepest adaptation costs.
Subscription pricing for constituent management tools is displacing perpetual license models among development offices. Smaller nonprofits favor predictable operational expenditures over capital-intensive upfront purchases. The United States exhibits the fastest transition pace due to higher nonprofit density and digital procurement maturity.
Non-Profit Software Market Segmentation
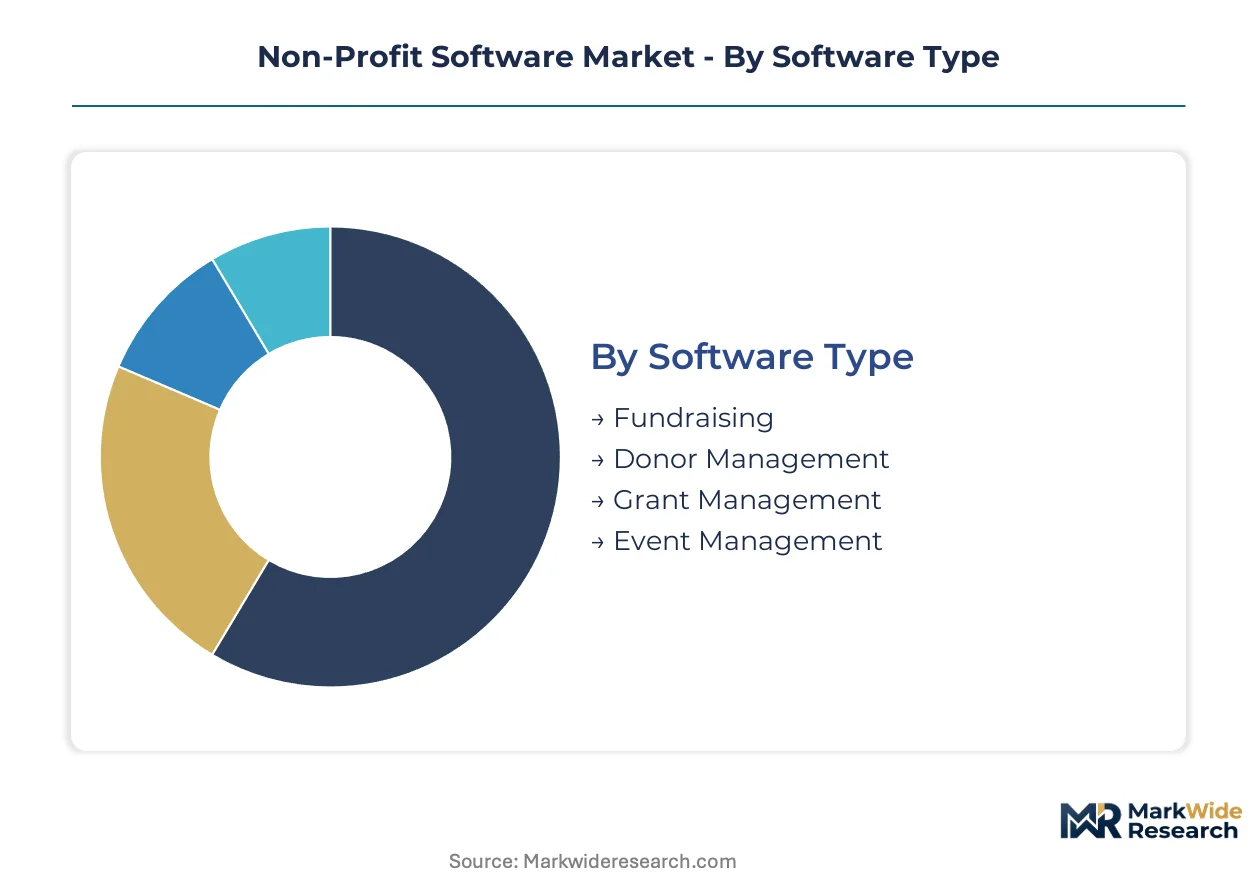
Segmentation in non-profit software reveals how procurement priorities diverge across organizational maturity, technical infrastructure, and regulatory exposure. Vendors must align product architecture with these fault lines to avoid misaligned development investments.
Software Type:
Grant Management faces acute substitution pressure from horizontal project management tools adapted for compliance workflows, while Donor Management maintains defensive moats through CRM integration depth.
- Fundraising:Platforms automate campaign orchestration, peer-to-peer solicitation, and recurring gift processing. Demand concentrates in mid-sized charities replacing manual spreadsheets, driven by FTC donor privacy enforcement requiring audit trails.
- Donor Management:Systems centralize constituent profiles, interaction histories, and segmentation logic. Faith-based organizations in the United States anchor demand, accelerating procurement to digitize tithing and member outreach workflows.
- Grant Management:Lifecycle tracking modules span proposal development, award compliance, and outcome reporting. Federal reporting mandates shape feature roadmaps.
- Event Management:Tools coordinate registration, ticketing, and post-event engagement for galas and peer-to-peer campaigns. Hybrid event formats persist post-pandemic.
Donor Management anchors the volume base while Grant Management gains share at the steepest rate.
Deployment Model:
Cost tier differentiation separates enterprise buyers with compliance budgets from resource-constrained organizations seeking operational expenditure predictability.
- Cloud-Based:Multi-tenant architectures with role-based access controls and automatic updates. GDPR and state privacy statutes in California and Virginia compress procurement cycles as organizations replace legacy systems.
- Hybrid:Bridge configurations preserve on-premise accounting investments while enabling cloud scalability for donor-facing functions. Organizations with decades-old financial systems dominate this tier.
- On-Premise:Single-tenant installations with full data residency control. Heightened concerns over cross-border storage sustain residual demand.
- Open Source:Community-maintained codebases with customizable modules. Developer-scarce mid-market nonprofits limit penetration.
Cloud-Based deployments command the majority position while Hybrid configurations expand most quickly among organizations with residual legacy infrastructure.
End User:
Customer type segmentation tracks how mission focus shapes functionality requirements and procurement sophistication.
- Charities:Direct-service organizations managing individual donors and program delivery. IRS Form 990 automation drives replacement demand.
- Foundations:Grant-making institutions requiring outbound portfolio management and recipient monitoring. Compliance-heavy reporting modules dominate selection criteria.
- Advocacy Groups:Organizations mobilizing grassroots action and legislative engagement. Communication and volunteer coordination tools rank highest.
- Community Organizations:Localized entities with limited technical staff. Usability-driven conversion supersedes configurable complexity.
Charities sustain the broadest installed base while Foundations exhibit the steepest expansion trajectory as compliance requirements tighten.
Functionality:
Maturity gradients separate established modules from emerging capabilities where vendor positioning remains unsettled.
- Reporting:Audit-ready modules generating IRS Form 990 disclosures and foundation outcome metrics. Standardized disclosure mandates cement this as a purchase prerequisite.
- Communication:Email marketing, SMS outreach, and social integration tools. AI-driven personalization presents white space though consent obligations remain unresolved.
- Accounting:Fund-specific ledger management and restricted revenue tracking. Integration complexity with legacy systems constrains implementation depth.
- Volunteer Management:Scheduling, hour tracking, and engagement tools. Faith-based digitization accelerates adoption for ministry coordination.
Reporting functionality anchors procurement decisions while Communication tools climb the fastest as engagement channel diversification intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development for charitable and faith-based organizations concentrates heavily in the United States, where nonprofit density and venture capital availability sustain the deepest vendor ecosystem. Secondary development clusters operate in the United Kingdom and Germany, though these markets serve narrower compliance and data residency requirements.
United States
Domestic nonprofit density exceeds 1.5 million registered entities, generating concentrated demand for donor management and grant lifecycle platforms. The FTC enforces donor privacy regulations that compress procurement cycles and mandate audit-ready reporting architectures. Austin and Boston anchor rival development clusters, with Salesforce and Blackbaud maintaining headquarters operations that shape product roadmaps for faith-based digitization and higher-education advancement.
United Kingdom
Charity Commission registration requirements and GDPR extraterritorial reach drive demand for consent management and cross-border data handling capabilities. The Information Commissioner's Office enforces strict breach notification protocols that elevate security functionality in vendor selection. London's fintech corridor hosts emerging grant management specialists serving dual-UK-EU nonprofit operations.
Germany
Data localization preferences and the Federal Data Protection Act sustain residual demand for on-premise and hybrid deployment configurations. German charitable foundations manage substantial endowment portfolios requiring specialized compliance reporting for tax-advantaged status. Berlin's SaaS startup ecosystem produces mid-market alternatives emphasizing usability over enterprise complexity.
Canada
Charities Directorate reporting mandates and provincial privacy statutes in British Columbia and Alberta shape functionality requirements for Canadian nonprofits. The Canada Revenue Agency's T3010 disclosure obligations parallel IRS Form 990 automation needs. Toronto's technology corridor hosts regional headquarters for US-based vendors adapting products for bilingual and multi-currency operations.
Australia
ACNC governance standards and the Privacy Act's notifiable data breach scheme accelerate cloud migration among Australian charities and religious organizations. Deductible gift recipient status management requires specialized reporting modules. Sydney and Melbourne concentrate domestic software development serving Asia-Pacific nonprofit operations with heightened data residency concerns.
Non-Profit Software Market Competitive Landscape
Concentration sits with vertically specialized platforms and horizontal CRM incumbents that have adapted donor engagement modules for nonprofit workflows. The vendor base separates into three strategic archetypes: enterprise-grade suites with deep integration capabilities, mid-market usability specialists, and faith-focused vertical solutions. Competitive moves center on API ecosystem expansion and compliance automation partnerships that reduce implementation friction for resource-constrained development offices.
Within the enterprise platform tier, Salesforce anchors donor relationship management through CRM architecture adapted for multi-site ministries and university advancement offices. Blackbaud occupies the specialized vertical position with advancement and alumni management systems for higher-education affiliated nonprofits. Bloomerang represents the mid-market usability archetype, competing on intuitive interfaces that reduce training burdens for smaller development teams with limited technical staff.
| Leading Market Players |
|---|
| Blackbaud |
| Salesforce |
| Bloomerang |
| Microsoft |
| Oracle NetSuite |
| DonorPerfect |
| Neon One |
| Bonterra |
| Pushpay |
| Others |
Value Network & Pricing Analysis
GDPR extraterritorial enforcement and state-level privacy statutes in California and Virginia simultaneously gate vendor qualification and stratify pricing tiers across the non-profit software market. Organizations operating dual-jurisdiction programs face compliance premiums that compress procurement budgets for smaller charities while expanding margin pools for audit-ready architectures.
Pricing Analysis
GDPR and state privacy statutes dictate the pricing tier structure across cloud-based donor management and grant lifecycle platforms. Subscription SaaS models dominate deployment, with three-tier pricing structure across premium, standard, and economy levels anchored to compliance certification depth and API integration complexity. Price differentiation rests on automated audit trail generation and cross-border data residency controls. Pricing pressure stems from mid-market usability specialists competing on intuitive interfaces that reduce implementation friction. Faith-based organizations with limited technical staff exhibit highest price sensitivity, while multi-site ministries and university advancement offices demonstrate lowest sensitivity due to compliance mandate rigidity.
Supply Chain Analysis
Container availability constraints on trans-Pacific trade lanes from Shanghai and Busan to Long Beach and Seattle elevate inbound logistics costs for hardware-dependent hybrid deployment configurations. Software development concentrates in the United States, the United Kingdom, and Germany, with Austin, Boston, and London anchoring rival engineering clusters. Cloud infrastructure draws from hyperscaler data center networks across Virginia, Oregon, and Frankfurt. Single-source vulnerability sits with API ecosystem dependencies for financial system integration. Distribution runs through direct vendor sales organizations and value-added reseller networks serving regional nonprofit associations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-profit software represents a service-attach opportunity where implementation consulting and ongoing compliance monitoring subscriptions expand faster than core platform licensing. Recurring revenue from automated Form 990 preparation and GDPR consent management audits now exceeds perpetual license attach rates.
For Market Incumbents: Fortify vertical integration into grant management automation and faith-based digitization workflows to defend against mid-market usability specialists eroding share. Deepen API ecosystem partnerships with legacy accounting system vendors to reduce switching cost friction. Invest in AI-driven personalization modules before algorithmic transparency obligations harden into purchase prerequisites.
For New Entrants and Emerging Players: Anchor in community organizations and localized charities where usability-driven conversion supersedes configurable complexity requirements. Target foundations with tightening federal compliance mandates as the most penetrable segment. Pursue channel partnerships with nonprofit association networks as the primary go-to-market angle.
For Investors and Strategic Acquirers: Emerging AI consent and algorithmic transparency obligations under developing regulatory frameworks reshape the acquisition landscape toward compliance-automation capabilities. Long-term viability favors platforms with audit-ready architectures and cross-border data handling protocols. Target mid-market specialists with hybrid deployment expertise bridging legacy on-premise investments. Watch FTC enforcement actions on donor privacy as the signal indicating accelerated replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API ecosystem expansion reduces implementation friction for resource-constrained development offices. |
| Strategic Partnership | Compliance automation alliances with nonprofit associations accelerate mid-market penetration. |
| Product Launch | AI-driven personalization modules capture white space before algorithmic transparency obligations mature. |
| Acquisition of Specialist Firm | Grant management automation targets expand margin pools as federal reporting mandates tighten. |
| Geographic Expansion | European data localization capabilities address GDPR extraterritorial reach for international nonprofits. |
Research Methodology
Initial hypotheses were tested against primary input from nonprofit CIOs, development directors, foundation grant officers, and compliance officers at faith-based organizations and refined through secondary validation. CTOs at mid-market charities, IT procurement officers at multi-site ministries, platform engineers at cloud-native vendors, and integration specialists serving hybrid deployment configurations contributed structured interviews. Secondary sources encompassed IRS Form 990 filing databases, state attorney general charitable solicitation registries, GDPR enforcement action records from European data protection authorities, and SEC filings from publicly traded software vendors. Bottom-up sizing of deployment volumes triangulated against top-down expenditure estimates from nonprofit sector economic surveys.
Variance decomposition across software type, deployment model, end user category, and functionality maturity shaped the analytical framework over the projection horizon. Segmentation dimensions modeled encompassed donor management versus grant management platforms, cloud-based versus hybrid versus on-premise configurations, charities versus foundations versus advocacy groups, and reporting versus communication versus accounting versus volunteer management capabilities. CAGRs were derived from trend extrapolation moderated by regulatory inflection timing and technology adoption S-curve positioning. Forecast inputs incorporated faith-based digitization velocity and federal compliance mandate expansion trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement intensity and stable nonprofit sector funding levels; material deviation would warrant model refresh. Forecasts reflect documented base-case assumptions regarding cloud migration pace and AI adoption timelines. Sudden shifts in FTC enforcement posture, state privacy statute expansion, or hyperscaler pricing restructuring could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global SAP S-4HANA Application Market
Software & Services
Neurodiverse Workforce Productivity Tools Market
Software & Services
Global Job Evaluation Software Market
Software & Services
Saas for Spa Management Market
Software & Services
Dental Practice Management Software Market
Software & Services
Employee Engagement Solutions Market
Software & Services
Global Club Management Software Market
Software & Services
Global Charity Accounting Software Market
Software & Services
Global Meeting Room Booking System Software Market
Software & Services
Global Permit Management Software Market
Software & Services
UK Point of Sale Software Market
Software & Services
Team Collaboration Tools Market
Software & Services
Software-Defined Machine Market
Software & Services
HACCP Software Market
Software & Services
Global Nosql Software Market
Software & Services
Life Sciences Software Market