
 Global Architect Software Market | 2026-2036
Global Architect Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Architect Software Market Foresight
ISO 19650 certification for building information management is reorganizing competitive access across the Global Architect Software Market. Autodesk Inc. leverages its Revit ecosystem to anchor North American design workflows. Nemetschek Group differentiates through an open BIM philosophy that sustains interoperability across its brand portfolio. Bentley Systems, Incorporated dominates infrastructure-focused digital twin deployments with deep civil engineering integration.
Architect software encompasses computer-aided design platforms, parametric modeling engines, and collaborative project environments that process geometric data, material specifications, and structural simulations into construction-ready documentation. Building Information Modeling segments lead value capture through federated data models that unify multidisciplinary workflows, while Cloud-Based deployment modes represent the fastest-expanding structural category as distributed project teams demand real-time synchronization. Rendering Software occupies concentrated margin pools where visualization quality directly influences client approval cycles and competitive bidding outcomes.
REACH chemical transparency rules and the EU AI Act's risk classification framework are reshaping material database compliance and automated design validation protocols across European deployments. The EPA's ENERGY STAR certification requirements and evolving ASHRAE standards in the United States mandate integrated energy performance analytics within design platforms. Stakeholders must monitor how converging sustainability disclosure rules and emerging AI governance standards will redefine software capability requirements and procurement criteria across major construction markets.
Market Dynamics
ISO 19650 certification mandates are compressing competitive access across the Global Architect Software Market, forcing vendors to restructure data governance capabilities or exit federated BIM workflows entirely.
Growth Catalysts
- EU Green Deal building performance standards:Tightened energy modeling compliance requirements in Germany, France, and Italy are accelerating procurement of simulation-integrated design platforms.
- KfW sustainable building funding:Germany's federal development bank program ties loan eligibility to certified energy performance documentation, directly stimulating architect software upgrades.
- Cloud-based deployment modes:Distributed project teams across commercial construction sectors demand real-time synchronization capabilities that legacy on-premise installations cannot deliver.
Market Restraints
- High switching costs:Established BIM ecosystems lock design firms into proprietary data formats, creating structural friction against platform migration.
- Talent scarcity in computational design:The shortage of professionals skilled in parametric modeling and generative algorithms constrains adoption velocity among mid-sized practices.
- Interoperability gaps:Persistent data exchange failures between structural engineering and MEP disciplines force redundant manual reconciliation workflows.
Strategic Opportunities
- India's Smart Cities Mission:Urban infrastructure digitization mandates create demand for BIM-enabled planning tools across municipal authorities and large developers.
- EU AI Act risk classification:Automated design validation protocols for high-risk building systems open specialized compliance software segments.
- Digital twin convergence with IoT:Integration of real-time sensor data into as-built models enables new facility management service revenue streams.
Industry Challenges
- ISO 19650 certification timelines:Extended audit and documentation requirements delay go-to-market for new market entrants.
- Legacy CAD migration complexity:Decades of 2D drawing archives require costly digitization and semantic enrichment to participate in federated BIM workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Architect Software Market |
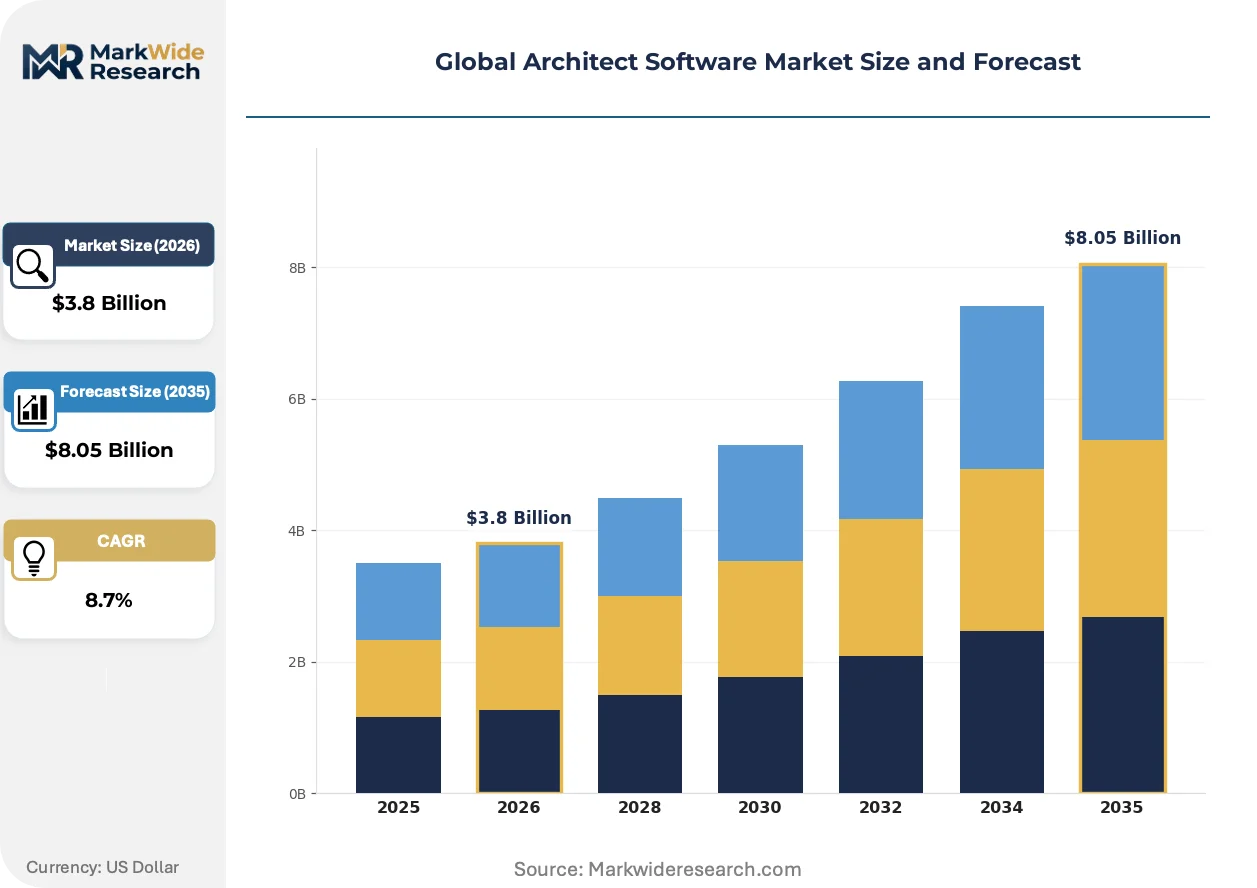
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Building Information Modeling, CAD, Rendering Software, Project Management Tools, Estimation Software, Visualization Software Deployment Mode: On-Premises, Cloud-Based, Hybrid, SaaS, Web-Based End User: Architectural Firms, Real Estate Developers, Construction Consultants, Urban Planners, Engineering Companies Application: Design & Drafting, Visualization, Project Collaboration, Cost Estimation, Building Analysis, Documentation |
| Companies Covered | Autodesk Inc., Nemetschek Group, Bentley Systems, Incorporated, Trimble Inc., Dassault Systèmes, Hexagon AB, AVEVA Group plc, Siemens Digital Industries Software, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Architect Software Market Shifts & Advancements
Generative design algorithms and real-time rendering engines are redrawing capability boundaries across architect software categories, compressing traditional competitive moats.
AI-assisted generative design is fragmenting established workflows by automating optioneering tasks previously requiring senior architect judgment. Mid-sized commercial practices in the United States and United Kingdom are adopting these tools fastest, lured by compressed schematic design phases. The technology is fragmenting value capture away from traditional hourly billing models toward outcome-based fee structures.
REACH chemical transparency rules are forcing material database providers to restructure supply chain disclosure protocols. Manufacturers serving European markets must now document substance composition through full product lifecycles. German and French architect software deployments are prioritizing integrated environmental product declaration libraries to preempt compliance gaps.
Subscription pricing models are displacing perpetual licenses across professional design software. Small and mid-sized architecture practices in Spain, Australia, and South Korea are driving this transition, prioritizing predictable cash flows over capital expenditure avoidance. The shift is most visible in rendering and visualization segments where GPU-intensive cloud processing eliminates hardware investment barriers.
Global Architect Software Market Segmentation
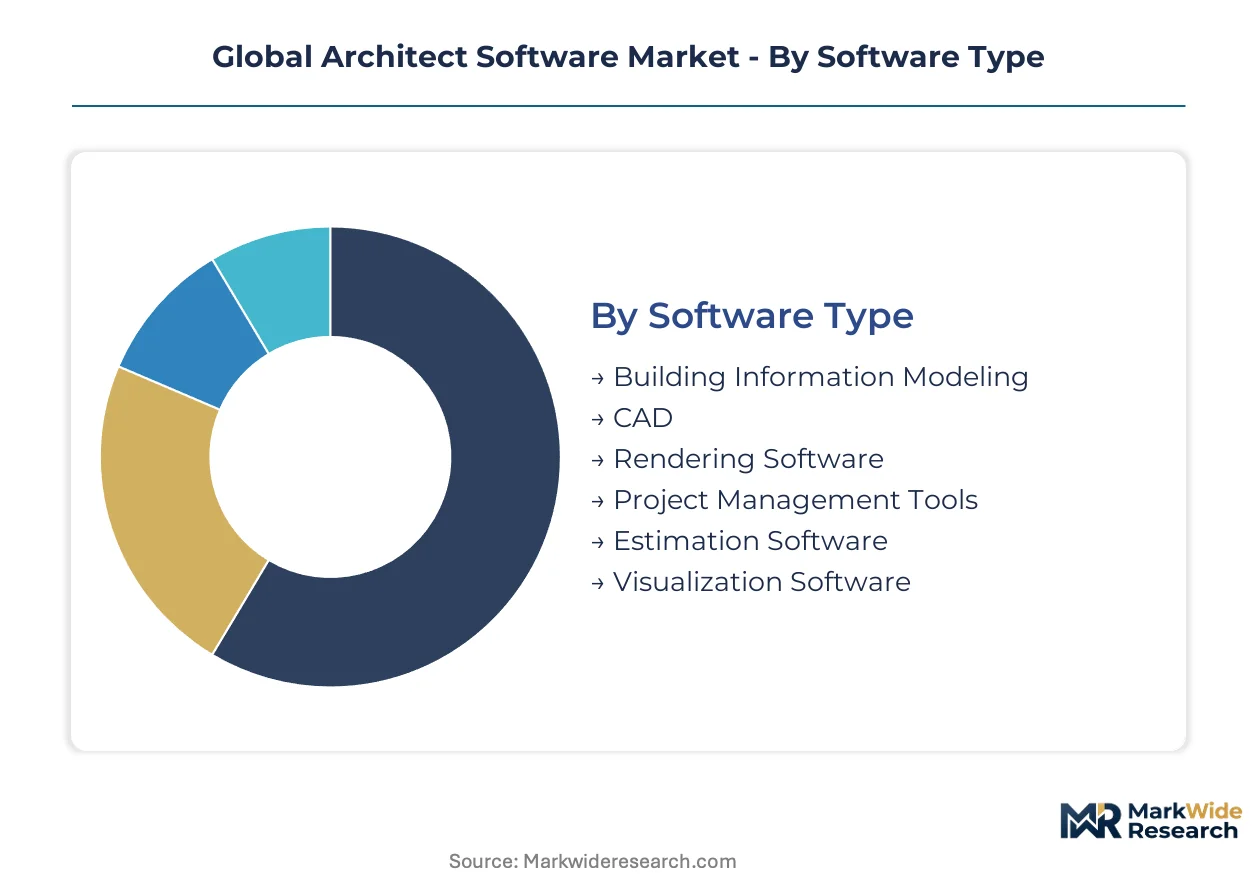
Segmentation in architect software reveals how procurement criteria diverge across buyer sophistication tiers and project complexity thresholds. Technical requirements for federated BIM workflows differ fundamentally from visualization-focused purchases, creating distinct competitive arenas with minimal vendor overlap.
Software Type:
Building Information Modeling dominates procurement in Germany and France where EU Green Deal compliance mandates energy modeling integration; CAD and rendering tools retain strongholds in price-sensitive domestic markets across Spain and Italy.
- Building Information Modeling:Federated data models unify structural, MEP, and architectural disciplines through ISO 19650-compliant data governance. German KfW funding requirements and French RE2020 regulations concentrate demand among mid-sized firms retrofitting legacy workflows.
- CAD:Legacy 2D drafting platforms persist in municipal infrastructure and small commercial renovations where BIM overhead exceeds project value. Italian and Spanish practices maintain installed bases despite interoperability pressures from prime contractors.
- Rendering Software:GPU-intensive visualization engines compress client approval cycles in competitive bidding scenarios.
- Project Management Tools:Schedule and resource coordination modules integrate with design platforms through open APIs.
- Estimation Software:Quantity take-off automation links geometric models to cost databases for tender documentation.
- Visualization Software:Real-time engines serve virtual reality walkthroughs and marketing deliverables for developer clients.
Building Information Modeling holds the largest share; momentum sits with Rendering Software as real-time engines displace offline processing.
Deployment Mode:
Cost tier stratification separates capital-intensive on-premise installations from operational-expense SaaS models favored by mid-sized practices managing cash flow volatility.
- Cloud-Based:Distributed project teams synchronize models through browser-accessible platforms eliminating hardware procurement cycles. Australian and South Korean practices lead adoption where remote collaboration spans multiple time zones.
- SaaS:Subscription pricing eliminates upfront license costs while embedding automatic updates and security patches. Small architectural firms in Spain and Portugal prioritize predictable monthly expenditures over perpetual ownership.
- On-Premises:Air-gapped installations persist in defense and critical infrastructure sectors with data sovereignty requirements.
- Hybrid:Mixed deployments balance sensitive IP on local servers with collaborative coordination in cloud environments.
- Web-Based:Lightweight clients enable field access on mobile devices for construction administration tasks.
On-Premises retains entrenched positions in regulated sectors; Cloud-Based deployment is climbing the fastest as distributed teams become standard.
End User:
Customer type determines feature prioritization, with engineering companies demanding structural simulation depth while real estate developers prioritize visualization speed and marketing output quality.
- Architectural Firms:Design practices require comprehensive toolchains spanning schematic design through construction documentation. German and UK mid-sized firms drive BIM adoption as ISO 19650 certification becomes mandatory for public sector work.
- Real Estate Developers:Proptech divisions and development arms purchase visualization-heavy suites for investor presentations and pre-sales marketing. Dubai and Singapore developers commission digital twin integrations for luxury residential positioning.
- Construction Consultants:Quantity surveyors and project managers seek estimation and scheduling modules with design platform connectivity.
- Urban Planners:Municipal authorities and master planning consultants require GIS integration and large-site coordination capabilities.
- Engineering Companies:Structural and MEP specialists demand analytical simulation depth and code compliance automation.
Architectural Firms constitute the core installed base; Real Estate Developers are gaining share fastest as proptech investment expands.
Application:
Maturity gradients separate established design and drafting functions from emerging AI-assisted building analysis where automated code checking and generative optioneering reshape workflow economics.
- Design & Drafting:Core geometric modeling and documentation production remains the primary procurement trigger across all buyer segments. French and Japanese practices maintain rigorous drafting standards that resist full automation.
- Building Analysis:Energy performance simulation, structural calculation, and code compliance checking integrate with design models for real-time feedback. EU Green Deal enforcement in Germany and Netherlands accelerates procurement of simulation-integrated platforms.
- Visualization:Rendering and virtual reality output for client communication and marketing materials.
- Project Collaboration:Multi-stakeholder coordination through model sharing and clash detection workflows.
- Cost Estimation:Automated quantity extraction linked to pricing databases for tender preparation.
- Documentation:Drawing production, specification writing, and submittal package assembly.
Design & Drafting commands the dominant revenue pool; Building Analysis shows the steepest expansion trajectory as sustainability compliance tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial construction teams and architectural design firms concentrate procurement across Germany, the United States, and Japan where regulatory mandates and funding programs reshape software requirements. Mid-sized practices in these markets face the steepest compliance deadlines for energy modeling and federated BIM workflows.
Germany
KfW development bank funding ties sustainable building loans to certified energy performance documentation, forcing architect software upgrades among mid-sized firms. The EU Green Deal's building performance standards tighten compliance windows through 2025. Munich and Frankfurt design clusters lead BIM adoption velocity as ISO 19650 certification becomes mandatory for public sector contracts.
United States
Commercial developers in Texas and Florida prioritize visualization speed for competitive bidding cycles, while California practices face ASHRAE standard updates mandating integrated energy analytics. EPA ENERGY STAR certification requirements filter into procurement criteria for design platforms. The Pacific Northwest and Northeast corridors show strongest cloud-based deployment adoption among distributed project teams.
Japan
METI building efficiency standards and JIS certification protocols drive simulation-integrated platform procurement among large architectural conglomerates. Tokyo and Osaka design hubs concentrate demand for parametric modeling capabilities. The country's aging infrastructure renewal programs create openings for digital twin integrations in facility management workflows.
United Kingdom
ISO 19650 certification deadlines for public sector work compress competitive access, forcing mid-sized London and Manchester practices to restructure data governance capabilities. The Building Safety Regulator's gateway compliance requirements extend software capability mandates beyond design into construction documentation. Birmingham's commercial renovation market sustains legacy CAD installed bases where BIM overhead exceeds project value.
Australia
Remote collaboration across multiple time zones accelerates cloud-based deployment among Sydney and Melbourne architectural practices. State-level building code updates in New South Wales and Victoria integrate energy performance simulation requirements. The country's Smart Cities program creates municipal demand for BIM-enabled planning tools in urban infrastructure digitization.
Global Architect Software Market Competitive Landscape
Player mix skews toward integrated platform providers with established BIM ecosystems and specialized infrastructure engineering vendors with deep civil simulation capabilities. The competitive structure consolidates around three tiers: full-stack design suites anchoring large commercial workflows, open-architecture specialists prioritizing interoperability, and point-solution providers in visualization and cost estimation. Dominant competitive moves include strategic partnerships with cloud infrastructure providers and portfolio diversification into facility management services.
Within the integrated platform tier, Autodesk Inc. and Nemetschek Group occupy positions representing contrasting philosophies on data governance and ecosystem openness. Bentley Systems, Incorporated anchors the infrastructure-specialist vector with civil engineering integration capabilities. These three entities exemplify how vendor archetypes align with distinct buyer segments—commercial architectural practices, multidisciplinary design firms, and heavy infrastructure project consortia—creating minimal direct overlap in competitive contests.
| Leading Market Players |
|---|
| Autodesk Inc. |
| Nemetschek Group |
| Bentley Systems, Incorporated |
| Trimble Inc. |
| Dassault Systèmes |
| Hexagon AB |
| AVEVA Group plc |
| Siemens Digital Industries Software |
| Oracle Corporation |
| Others |
Supply & Pricing Matrix
Cloud-based SaaS substitution for perpetual licensing redraws both vendor revenue geography and customer procurement economics, compressing upfront capital requirements while elongating vendor cash conversion cycles across German, Japanese, and Australian markets.
Pricing Analysis
Cost-plus contracts with annual CPI indexation dominate enterprise procurement in Germany and the United States. Three-tier pricing structure across premium, standard, and economy levels separates ISO 19650-certified suites from visualization-only tools and entry-level CAD platforms. Pricing pressure stems from mid-sized Spanish and Portuguese practices migrating to SaaS tiers with stripped feature sets. Small architectural firms show highest price sensitivity; infrastructure engineering consortia demonstrate lowest.
Supply Chain Analysis
Just-in-time deployment via browser-accessible platforms eliminates inventory holding entirely, though strategic stockpiling of GPU compute capacity secures rendering performance during peak bidding cycles. Software development concentrates in the United States, Germany, and Japan; cloud infrastructure draws from hyperscaler networks anchored in Ireland, Singapore, and Virginia. Single-source vulnerability sits with Autodesk's proprietary data formats. Distribution runs through direct vendor sales, value-added resellers, and systems integrators serving AEC verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
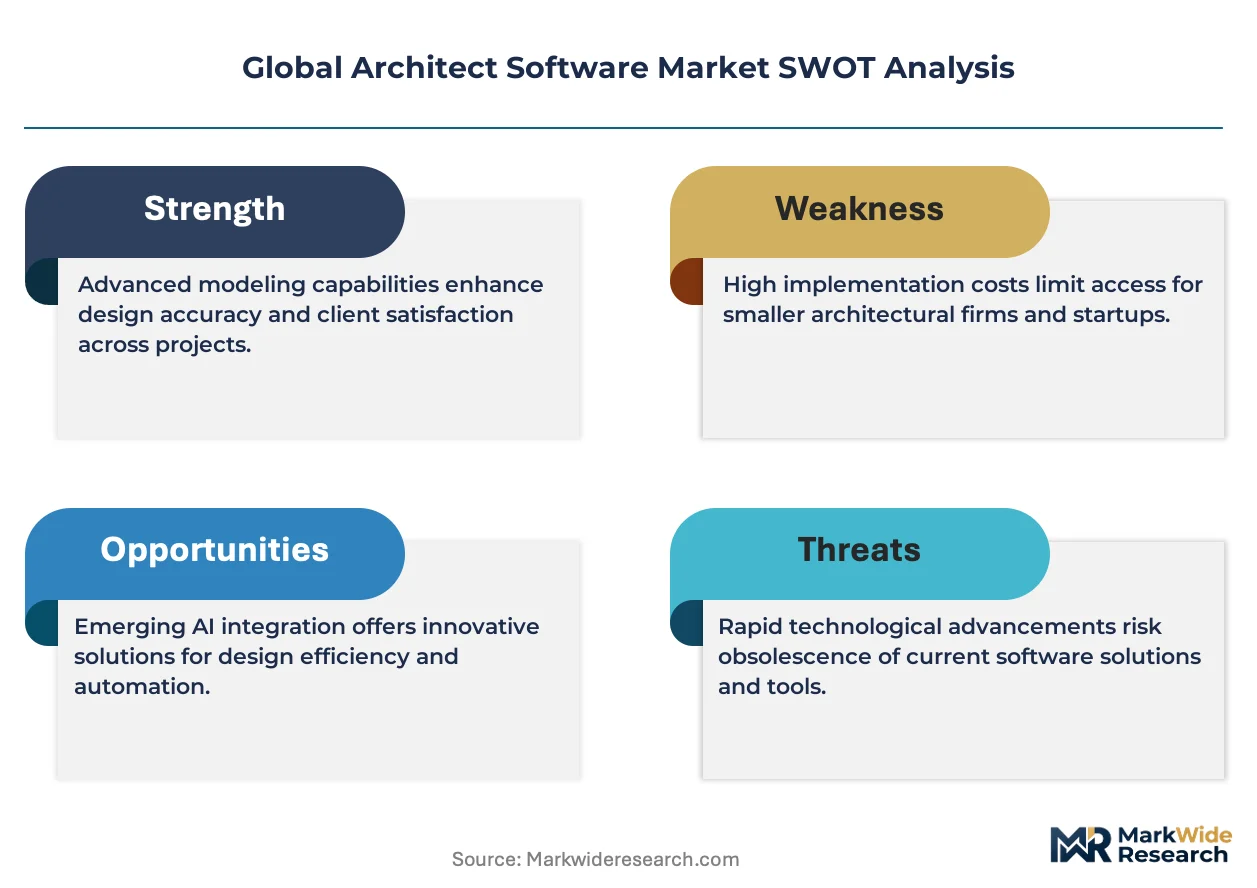
ISO 19650 certification bottlenecks and parametric modeling talent shortages constrain expansion velocity, privileging vendors with established training ecosystems and accredited implementation partners.
For Market Incumbents: Consolidate data governance capabilities around federated BIM workflows to lock in switching costs against open-source interoperability initiatives. Deepen vertical integration into facility management services, capturing digital twin revenue streams as Japanese infrastructure renewal programs accelerate. Anchor channel control through certified implementation partner networks in Germany and the United Kingdom.
For New Entrants and Emerging Players: Lead with AI-assisted generative design modules targeting mid-sized United States and United Kingdom commercial practices seeking compressed schematic phases. India's Smart Cities Mission offers the most penetrable geography, with municipal authorities lacking legacy CAD migration burdens. Pursue outcome-based fee structures that align vendor compensation with client project wins.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed visualization specialists holding concentrated developer relationships in Dubai and Singapore. Long-term viability hinges on convergence with IoT-enabled facility management platforms. Watch for KfW funding program expansions beyond Germany as the signal indicating accelerated procurement cycles across European sustainable building markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies structural, MEP, and architectural disciplines through ISO 19650-compliant data governance. |
| Acquisition of Specialist Firm | Captures generative design capabilities or real-time rendering engines from fragmented visualization vendors. |
| Strategic Partnership | Secures hyperscaler cloud infrastructure for GPU-intensive rendering workloads in Australian and South Korean markets. |
| Geographic Expansion | Targets India's Smart Cities Mission with BIM-enabled planning tools for municipal infrastructure digitization. |
| Product Launch | Introduces automated design validation protocols aligned with EU AI Act risk classification requirements. |
Research Methodology
Initial hypotheses were tested against primary input from chief technology officers at architectural firms, IT procurement officers at real estate developers, platform engineers at software vendors, and integration specialists at construction consultancies, then refined through secondary validation against SEC filings, hyperscaler capex disclosures, EU regulatory filings, and construction industry trade association reports. Bottom-up sizing of deployment modes and end-user segments triangulated against top-down market value estimates.
Variance decomposition across the projection horizon isolates drivers by software type, deployment complexity, organization size tier, and regional regulatory cluster. CAGRs derive from segment-level growth rate synthesis and cross-validation against adoption curve modeling. Industry-specific forecast inputs include KfW funding disbursement trajectories and ISO 19650 certification penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or cloud infrastructure cost stability would require recalibration. Forecasts reflect documented assumptions regarding interoperability standard adoption and parametric design talent pipeline expansion. Revision becomes warranted when EU AI Act implementation timelines cross enforcement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Translation Software Market
Software & Services
Construction Suites Software Market
Software & Services
United States Contract Lifecycle Management Software Market
Software & Services
Global Janitorial Software Market
Software & Services
Vending Software Market
Software & Services
Global Thermal Analysis Software Market
Software & Services
HCS Software and Services Market
Software & Services
Global Driving School Software Market
Software & Services
Global Referral Software Market
Software & Services
Client Virtualization Software Market
Software & Services
Collaborative Authoring Tools Market
Software & Services
Global Press Release Distribution Software Market
Software & Services
Paraphrasing Tools Market
Software & Services
Software Publishers Market
Software & Services
Indonesia Big Data Analytics Software Market
Software & Services
Enterprise Resource Planning (ERP) Software Market