
 Big Data Analytics in Automotive Market | 2026-2036
Big Data Analytics in Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Big Data Analytics in Automotive Market Analysis
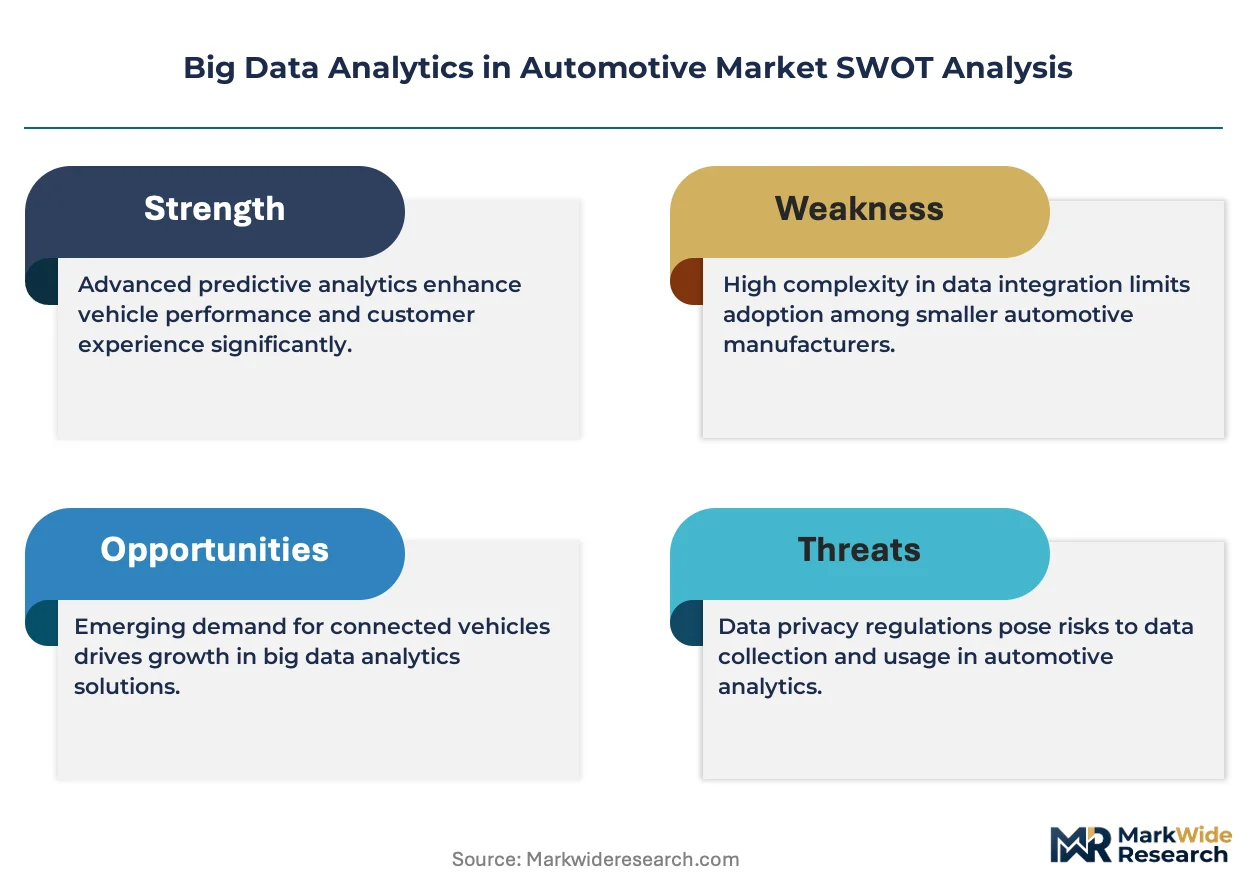
Subscription-based predictive maintenance platforms is repositioning how automotive data monetization works. Microsoft Corporation leverages its Azure cloud infrastructure to anchor fleet analytics services across multiple OEM partnerships. IBM Corporation sustains competitive relevance through specialized data mining tools tailored for automotive quality control. Bosch dominates edge-computing deployments that process vehicle sensor streams before cloud transmission.
Big Data Analytics in Automotive encompasses the collection, processing, and algorithmic interpretation of multi-structured vehicle-generated datasets—including CAN bus signals, LiDAR point clouds, and telematics time-series—using distributed computing architectures to enable real-time operational decisions. Its primary commercial purpose centers on converting raw vehicular data into actionable intelligence for safety optimization, cost reduction, and revenue generation across mobility ecosystems. Predictive Maintenance leads application adoption because OEMs prioritize uptime guarantees in commercial fleet contracts. Machine Learning functionality captures expanding margin pools as automakers demand autonomous algorithm training pipelines. Streaming Data types grow fastest where connected vehicle penetration enables continuous rather than batch processing architectures.
The EU AI Act imposes conformity requirements on automated decision systems in vehicles, while GDPR restricts cross-border transfer of driver biometric data collected through cabin analytics. NHTSA in the United States mandates event data recorder standards that shape what vehicle telemetry gets captured and retained. Stakeholders must monitor divergent regulatory timelines between jurisdictions to avoid compliance fragmentation in globally deployed analytics platforms.
Market Dynamics
Fleet operators now mandate uptime guarantees that force OEMs to embed predictive algorithms directly into vehicle architectures, compressing the timeline between sensor data generation and maintenance action.
Growth Catalysts
- EU AI Act Conformity Requirements:Automated decision systems in commercial vehicles must demonstrate algorithmic transparency, creating standardized demand for interpretable machine learning pipelines that OEMs must procure.
- Edge Computing Hardware Maturation:Automotive-grade processors capable of real-time inference at the vehicle level eliminate latency constraints that previously bottlenecked predictive maintenance deployment.
- Germany Automotive Cluster Density:Stuttgart and Munich host concentrated engineering talent pools that accelerate analytics platform development and validation cycles for European OEMs.
Market Restraints
- GDPR Cross-Border Data Friction:Biometric cabin data collected through driver monitoring systems faces transfer restrictions that fragment cloud analytics architectures across jurisdictions.
- Silicon Supply Concentration:Advanced driver-assistance system chips rely on fabrication capacity concentrated in Taiwan, exposing analytics hardware roadmaps to geopolitical supply disruption.
- LiDAR Point Cloud Processing Costs:Autonomous perception stacks generate petabyte-scale datasets that strain storage and compute budgets for mid-tier OEMs.
Strategic Opportunities
- India Connected Vehicle Penetration Gap:Telematics adoption in commercial fleets remains below 15 percent, creating first-mover advantage for analytics providers establishing localized cloud infrastructure.
- CAN Bus to 5G Telemetry Convergence:Streaming protocols that merge legacy vehicle networks with cellular connectivity enable continuous rather than batch analytics for aftermarket service providers.
- NHTSA Event Data Recorder Mandates:Standardized telemetry capture requirements in the United States create compliant data lakes that insurers can access for usage-based pricing models.
Industry Challenges
- Automotive Data Engineering Talent Scarcity:The intersection of embedded systems expertise and machine learning operations remains underpopulated, elongating platform deployment timelines.
- ISO 26262 Functional Safety Certification:Analytics algorithms that influence vehicle control decisions must complete ASIL-D validation processes that extend development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Big Data Analytics in Automotive Market |
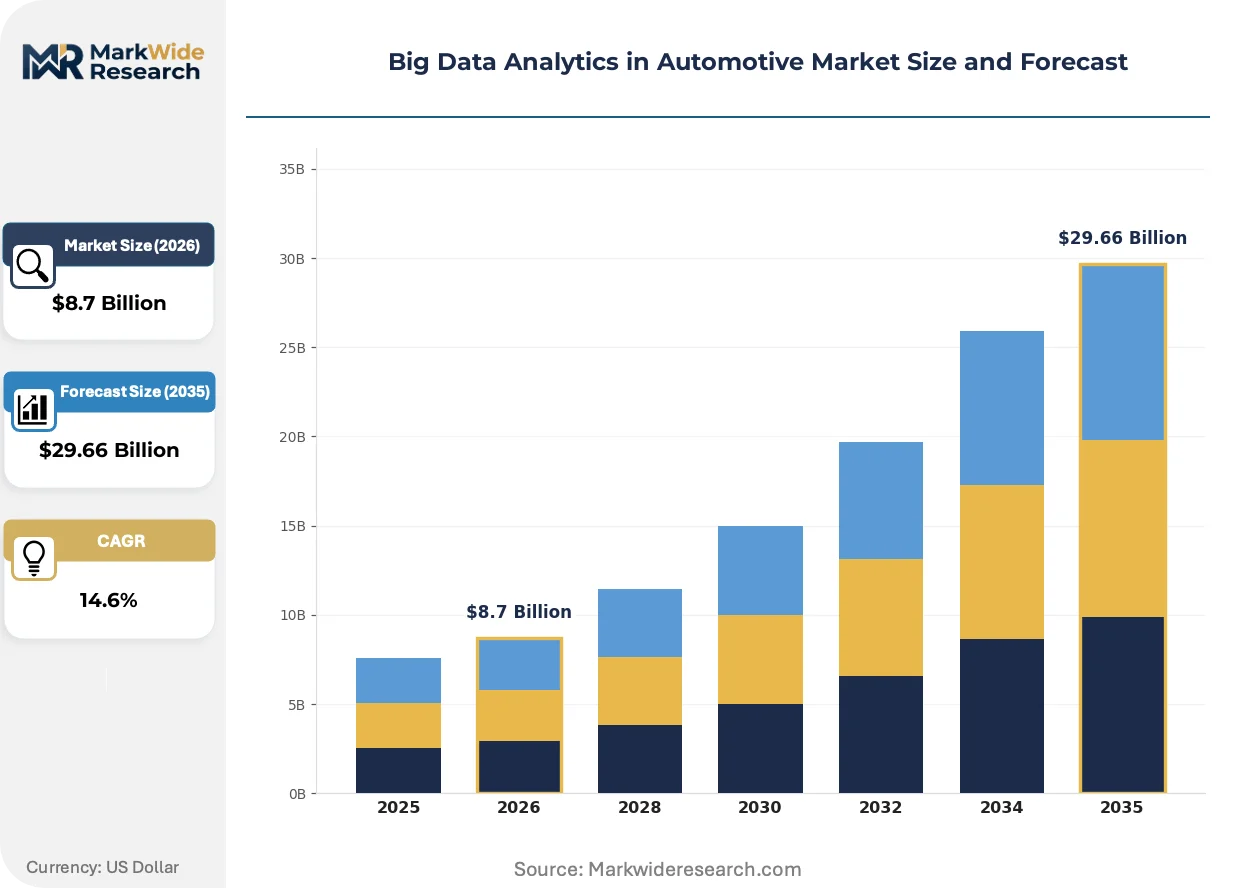
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Predictive Maintenance, Fleet Management, Traffic Management, Risk Assessment Data Type: Structured Data, Unstructured Data, Time-Series Data, Streaming Data Functionality: Data Visualization, Data Mining, Machine Learning, Reporting Deployment: On-Premises, Hybrid, Public Cloud, Private Cloud |
| Companies Covered | IBM Corporation, Microsoft Corporation, SAP SE, SAS Institute Inc, Oracle, Amazon Web Services, Reply SpA, Continental AG, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Big Data Analytics in Automotive Market Emerging Trajectories
Federated learning architectures are redistributing where model training occurs, shifting computation from centralized clouds toward distributed vehicle fleets that retain data locality.
Digital twin technology is electrifying how OEMs simulate powertrain degradation before physical failure occurs. BMW and Mercedes-Benz deploy virtual engine replicas that ingest real-world telemetry to forecast component replacement windows. This capability compresses warranty reserve requirements while repositioning aftermarket parts suppliers around predictive inventory positioning.
The EU AI Act's risk-based classification system imposes documentation burdens on high-risk automated driving functions. Tier-1 suppliers must now maintain algorithmic audit trails that trace decision pathways through neural network layers. German regulators at KBA are piloting conformity assessment procedures that will likely export across EEA member states.
Fleet procurement departments now unbundle telematics hardware from analytics software subscriptions. Large logistics operators in the United States negotiate directly with Microsoft Azure and AWS for cloud compute, bypassing OEM data platform markups. This disintermediation concentrates buying power among operators with 10,000-plus vehicle fleets while pressuring traditional supplier margins.
Big Data Analytics in Automotive Market Segmentation
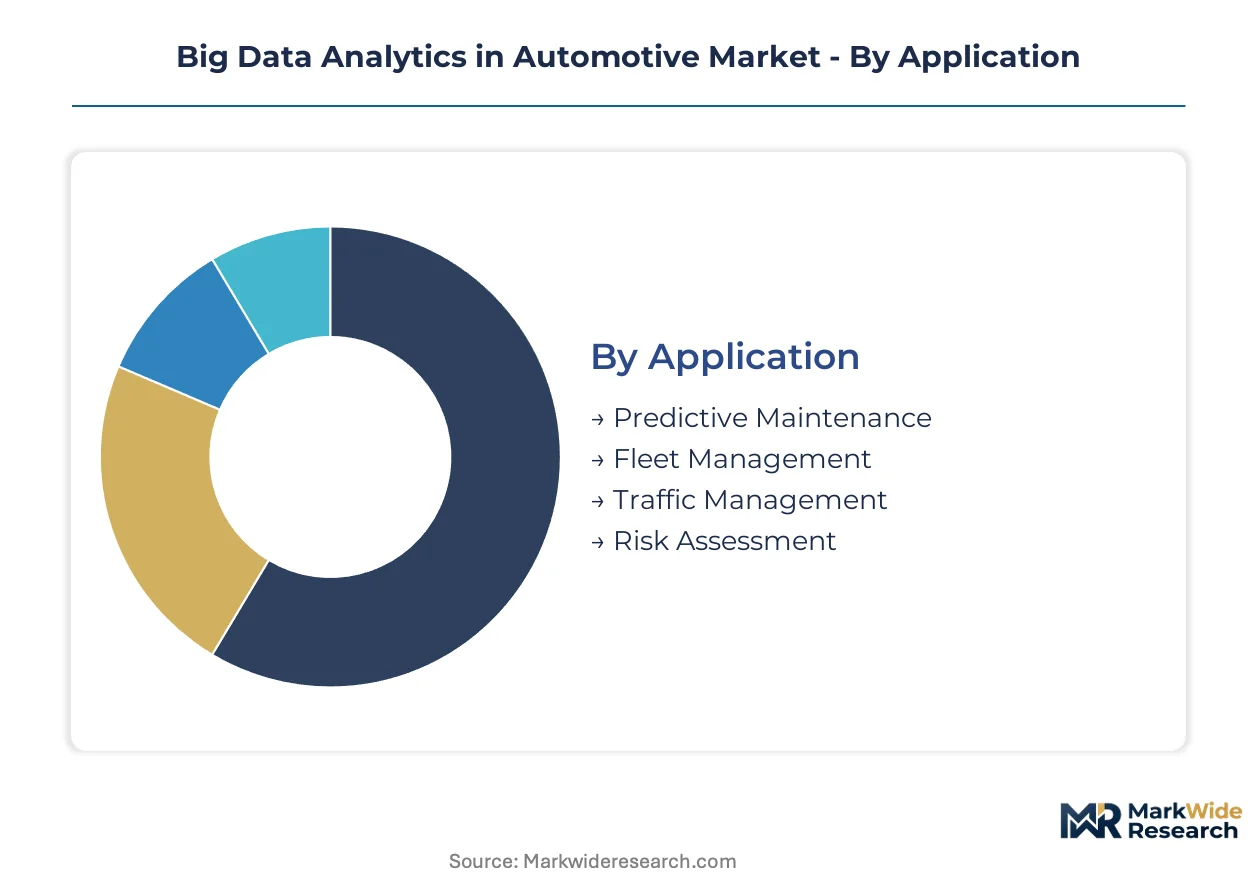
Segmentation in automotive big data analytics reveals how value pools concentrate across distinct technical architectures and operational use cases. OEM procurement patterns diverge sharply between real-time edge deployments and centralized cloud analytics, while regulatory pressures reshape data type preferences across jurisdictions.
Application:
Functional purpose determines hardware specifications, algorithmic complexity, and integration depth with vehicle control systems.
- Predictive Maintenance:Algorithms process CAN bus signals and vibration telemetry to forecast component degradation before failure triggers downtime. Commercial fleet operators in Germany mandate uptime guarantees that embed these systems directly into powertrain control modules, compressing maintenance response windows.
- Fleet Management:Aggregates telematics across thousands of vehicles to optimize routing, fuel consumption, and asset utilization through centralized dashboards. Logistics operators with 10,000-plus vehicle counts negotiate direct cloud compute contracts, bypassing OEM platform markups and concentrating buying power.
- Traffic Management:Municipal and highway authorities ingest anonymized vehicle flow data to adjust signal timing and congestion pricing.
- Risk Assessment:Insurers analyze driving behavior telemetry to calibrate usage-based premium models under NHTSA event data recorder mandates.
Predictive Maintenance leads on scale; Fleet Management leads on momentum.
Data Type:
Storage economics and processing latency tradeoffs shape which data formats dominate specific automotive workflows.
- Streaming Data:Continuous ingestion from connected vehicle sensors enables real-time inference without batch processing delays. Edge computing maturation in Stuttgart and Munich automotive clusters accelerates deployment architectures that retain data locality while minimizing cloud transmission costs.
- Time-Series Data:Sequential telemetry logs capture temporal patterns in battery performance, brake wear, and thermal cycling. German OEMs prioritize this format for warranty reserve forecasting and supplier quality audits.
- Structured Data:Relational databases organize vehicle identification, maintenance records, and compliance documentation.
- Unstructured Data:LiDAR point clouds and cabin camera feeds require specialized compression and annotation pipelines.
Time-Series Data anchors current infrastructure investment; Streaming Data gains share fastest as 5G vehicle connectivity expands.
Functionality:
Capability depth separates commodity visualization tools from premium algorithmic platforms that command recurring subscription revenue.
- Machine Learning:Neural network training pipelines for autonomous perception and predictive algorithms demand specialized MLOps infrastructure. The EU AI Act imposes conformity documentation burdens on high-risk automated driving functions, extending validation cycles and favoring suppliers with established regulatory pathways.
- Data Mining:Pattern recognition across quality control databases identifies defect correlations that escape human inspection. Bosch leverages edge-deployed mining tools to filter sensor streams before cloud transmission, reducing bandwidth costs.
- Data Visualization:Dashboard interfaces translate complex telemetry into actionable maintenance alerts for fleet technicians.
- Reporting:Standardized compliance documentation satisfies GDPR data portability requirements and insurer audit protocols.
Machine Learning commands premium pricing; Data Mining delivers margin stability through embedded hardware integration.
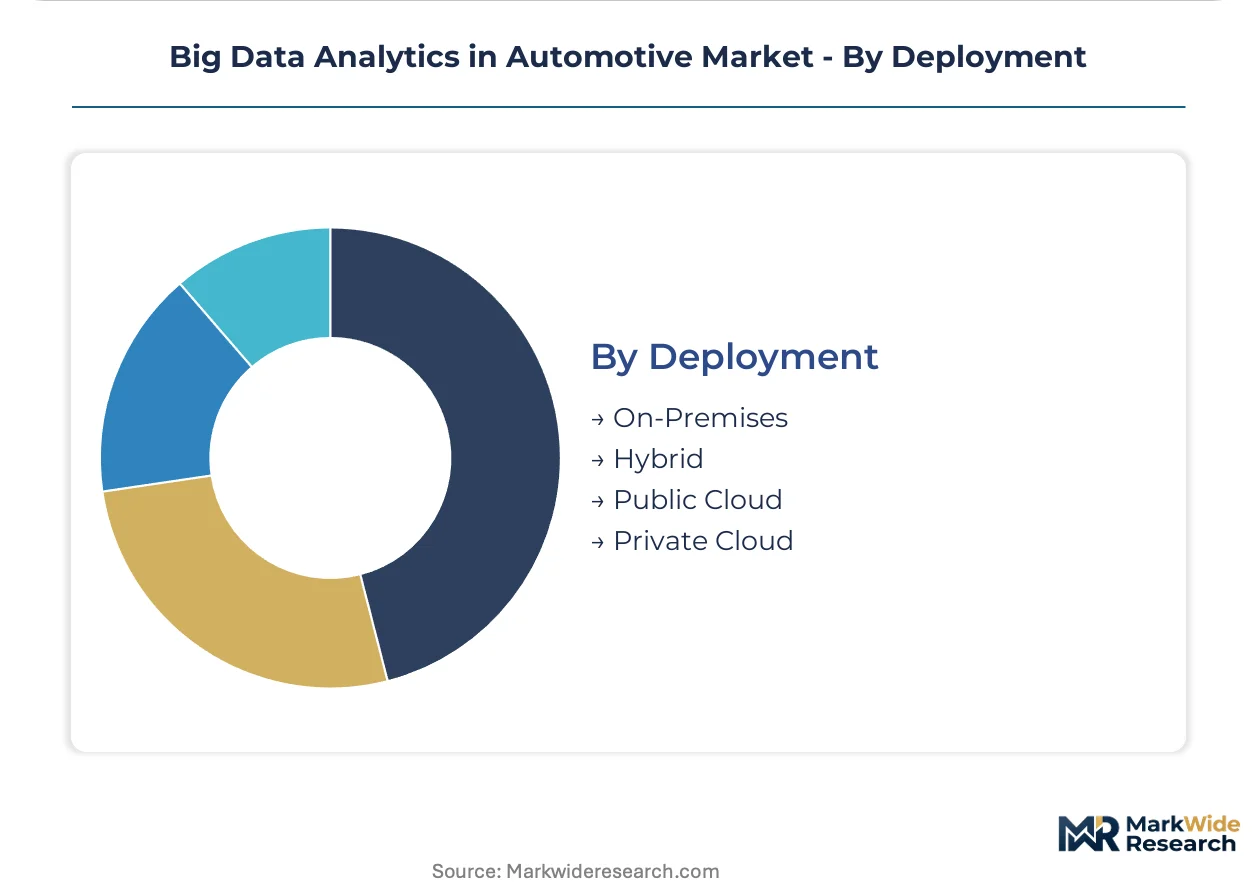
Deployment:
Architecture choice reflects data sovereignty requirements, latency constraints, and existing IT infrastructure amortization.
- Hybrid:Combines edge preprocessing for latency-sensitive inference with cloud aggregation for fleet-level analytics. GDPR cross-border transfer restrictions on biometric cabin data fragment architectures, making hybrid models the default for European OEMs serving multiple jurisdictions.
- Public Cloud:Microsoft Azure and AWS anchor scalable compute for fleet operators with variable demand patterns. Large logistics providers unbundle telematics hardware to negotiate direct cloud contracts, disintermediating traditional supplier margins.
- Private Cloud:Dedicated infrastructure satisfies defense and government fleet security requirements.
- On-Premises:Legacy installations persist where air-gapped networks satisfy national security vehicle programs.
Hybrid deployment captures the steepest expansion trajectory; Public Cloud retains volume concentration among commercial fleet segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing analytics platform development toward jurisdictions with clearer AI conformity pathways. Germany's KBA procedures and the EU AI Act's risk-based framework attract engineering investment that bypasses fragmented compliance costs elsewhere.
Germany
Stuttgart and Munich automotive clusters concentrate predictive maintenance R&D for BMW, Mercedes-Benz, and Porsche. KBA pilots algorithmic audit trail requirements that Tier-1 suppliers must satisfy for automated driving functions. Bosch anchors edge-computing deployments across Baden-Württemberg engineering corridors.
United States
NHTSA event data recorder mandates create standardized telemetry lakes that insurers access for usage-based pricing models. Fleet operators with 10,000-plus vehicle counts negotiate direct Azure and AWS contracts, disintermediating OEM platform markups. Michigan and California host competing autonomous perception training clusters.
China
MIIT connected vehicle standards accelerate domestic telematics adoption above 60 percent penetration in commercial fleets. Dual carbon goals pressure OEMs to deploy battery degradation analytics for warranty reserve optimization. Yangtze River Delta cities anchor LiDAR point cloud processing infrastructure.
India
Commercial fleet telematics penetration remains below 15 percent, creating first-mover advantage for cloud infrastructure localization. PLI scheme incentives for automotive electronics attract edge-computing hardware assembly. Maharashtra and Karnataka host emerging analytics validation centers for export-oriented suppliers.
Japan
METI data governance guidelines shape how Toyota and Honda structure cross-border driver biometric flows. JIS standards for vehicle-to-infrastructure communication create compliant streaming protocols for traffic management analytics. Nagoya and Tokyo metropolitan corridors concentrate quality control data mining operations.
Big Data Analytics in Automotive Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with cloud hyperscalers capturing recurring subscription revenue while hardware-integrated vendors retain embedded system margins. The vendor base concentrates around three strategic archetypes: cloud infrastructure providers with automotive-specific service layers, industrial conglomerates with edge-computing hardware portfolios, and specialized analytics software houses with regulatory compliance expertise. M&A activity targets MLOps capabilities that accelerate ISO 26262 certification timelines, while strategic partnerships between OEMs and cloud providers disintermediate traditional Tier-1 data platform margins.
Among cloud-centric service providers, Microsoft Corporation exemplifies the platform-architecture archetype through Azure-based fleet analytics. IBM Corporation occupies a position within specialized data mining and interpretable machine learning pipelines. Bosch represents the edge-computing hardware integrator segment with vehicle-level preprocessing capabilities that reduce transmission costs.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| SAP SE |
| SAS Institute Inc |
| Oracle |
| Amazon Web Services |
| Reply SpA |
| Continental AG |
| Bosch |
| Others |
Supply Flow & Price Mechanics
Cloud-hyperscaler partnerships with sovereign wealth-backed automotive ventures concentrate procurement leverage among fleet operators with 10,000-plus vehicle counts, compressing Tier-1 supplier margins while anchoring subscription pricing discipline across European and North American deployments.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for predictive maintenance platforms as Bosch and Continental expand edge-computing hardware production. Three-tier pricing structure across premium, standard, and economy levels segments buyers by fleet scale and algorithmic complexity, with ISO 26262 ASIL-D certification commanding substantial premiums. Cost compression in standard-tier offerings is intensifying because fleet operators negotiate direct Azure and AWS contracts, bypassing OEM platform markups. Small commercial fleets with under 500 vehicles exhibit highest price sensitivity, while logistics operators with transcontinental networks accept premium pricing for uptime guarantees.
Supply Chain Analysis
ISO 26262 functional safety certification gates Tier-1 supplier qualification, elongating vendor onboarding timelines by 18-24 months for analytics algorithms influencing vehicle control decisions. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, with automotive-grade inference processors drawing from TSMC and Samsung foundry capacity. Raw material dependencies span silicon wafers, rare-earth magnetics for LiDAR assemblies, and cobalt-lithium battery chemistries for electric vehicle telemetry systems. Single-source vulnerability in Taiwan-based advanced node production exposes hardware roadmaps to geopolitical disruption. Distribution runs through OEM-anchored Tier-1 channels, direct cloud provider contracting, and aftermarket telematics installers serving fragmented commercial fleet segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with regulatory mandates across the EU AI Act and NHTSA data recorder standards generating recurring compliance expenditure that sustains platform subscription revenues.
For Market Incumbents: Acquire MLOps specialist firms with established ISO 26262 certification pathways to compress algorithm validation timelines. Consolidate edge-computing hardware portfolios around automotive-grade inference processors to defend against cloud-hyperscaler disintermediation. Invest in interpretable machine learning pipelines that satisfy EU AI Act conformity documentation burdens before KBA audit trail requirements harden. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels bypass OEM procurement gatekeepers and capture margin pools from logistics operators negotiating direct cloud contracts. Target India's sub-15-percent commercial fleet telematics penetration, where localized cloud infrastructure investment creates first-mover positioning. Anchor go-to-market around CAN Bus to 5G telemetry convergence for aftermarket service providers seeking continuous streaming architectures. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier analytics software houses with regulatory compliance expertise but limited MLOps scale. Long-term viability centers on recurring subscription revenue durability across 5-10 year fleet management contracts. Watch for inflection when KBA algorithmic audit trail requirements export across EEA member states, triggering consolidation demand for conformity-ready platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Hardware Scale-Up | Bosch's Baden-Württemberg deployments reduce cloud transmission costs for Stuttgart OEM clusters. |
| Federated Learning Platform Development | Retains data locality for GDPR-compliant biometric cabin analytics across German fleets. |
| Direct Cloud Provider Contracting | Microsoft Azure partnerships with US logistics operators disintermediate traditional Tier-1 margins. |
| ISO 26262 Certification Investment | ASIL-D validation accelerates OEM procurement approval for safety-critical predictive algorithms. |
| India Cloud Infrastructure Localization | Maharashtra and Karnataka assembly positions capture PLI scheme incentives for automotive electronics. |
Methodological Framework
Multiple input streams — primary interviews with Tier 1 supplier procurement leads, OEM platform engineers, and aftermarket distributors; secondary validation through vehicle production databases, IHS Markit registration data, SEC hyperscaler capex disclosures, and EU regulatory filings — were reconciled through bottom-up and top-down triangulation to construct segment-level estimates.
Historical growth trajectories were cross-referenced against panel input from automotive data engineering specialists to anchor projections across the analysis window. Segmentation dimensions modeled include application type, data format, functional capability, and deployment architecture, with vehicle class and regional production cluster as automotive-specific stratifiers. CAGRs were derived from fitted trend extrapolation adjusted for regulatory mandate implementation timelines and connected vehicle penetration curves.
The model assumes a particular technology adoption path; alternative pathways for autonomous perception stack deployment would alter the outlook for LiDAR point cloud processing demand and associated storage economics. Forecasts reflect assumptions regarding EU AI Act enforcement consistency, Taiwan semiconductor supply continuity, and 5G vehicle connectivity rollout pace. A model refresh is warranted upon material change in KBA algorithmic audit trail standardization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Customer Experience Analytics Market
Analytics
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market
Analytics
Data Analytics Outsourcing Market
Analytics
Big Data Analytics Market
Analytics
UK Video Analytics Market
Analytics
Data Visualization Market
Analytics
Spend Analytics Software Market
Analytics
Procurement Analytics Market
Analytics
BI and Analytics Market
Analytics
Prescriptive Analytics Market
Analytics
Predictive and Prescriptive Analytics Market
Analytics
Global in-Store Analytics Market
Analytics
Asia-Pacific Edge Analytics Market
Analytics
Data Preparation Market
Analytics
Online Analytical Processing Market
Analytics
App Analytics Market