
 Global Accounts Receivable Software Market | 2026-2036
Global Accounts Receivable Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Accounts Receivable Software Market Foresight
Market Context with Strategic Players
North American SaaS infrastructure is recalibrating around embedded finance capabilities, forcing legacy receivables vendors to accelerate platform modernization. SAP SE leverages deep ERP integration to dominate enterprise deployments across manufacturing and wholesale distribution. Oracle Corporation anchors its position through database-layer connectivity that reduces reconciliation latency for large corporations. HighRadius Corporation specializes in AI-driven cash application, competing aggressively with cloud-native challengers in the mid-market segment.
Technical Definition and Structural Segments
Accounts receivable software automates invoice-to-cash workflows, encompassing credit decisioning, billing orchestration, payment matching, and collections management through configurable rule engines and API-based bank connectivity. Its primary commercial purpose is to compress cash conversion cycles and reduce bad debt exposure for B2B and B2C sellers. Cloud-based deployment leads volume growth as accounting firms and service providers abandon on-premises maintenance burdens, while payment processing solutions capture disproportionate margin pools due to interchange and float revenue attachment. Collection automation represents the fastest-expanding solution type, driven by labor cost pressures in retail and manufacturing customer segments.
Regulatory Frame and Forward-Looking Close
The US Federal Reserve's FedNow instant payment rails, the EU's PSD3 open finance framework, and ISO 20022 migration mandates across SWIFT and regional clearing systems are reshaping product roadmaps and compliance certification requirements. GDPR in Europe and state-level data privacy laws in California and Virginia constrain cross-border receivables data architecture, elevating regional hosting premiums. Stakeholders must monitor central bank digital currency pilots and real-time payment interoperability standards as these will determine which platforms achieve lock-in versus commoditization.
Market Dynamics
The migration toward ISO 20022 payment messaging standards is forcing enterprise finance teams to rebuild reconciliation engines, compressing vendor upgrade cycles and redistributing competitive advantage toward platforms with native API architectures.
Growth Catalysts
- FedNow instant payment rails:The US Federal Reserve's real-time settlement infrastructure eliminates batch-processing delays, compelling mid-market enterprises to replace legacy lockbox systems with automated cash application modules.
- Healthcare labor cost pressures:Hospital systems and physician groups deploy collection automation to reduce administrative headcount dedicated to patient billing follow-up and insurance denial management.
- AI-driven cash application:Machine learning models trained on remittance patterns now match payments to invoices with minimal human intervention, shrinking days sales outstanding for wholesale distributors.
Market Restraints
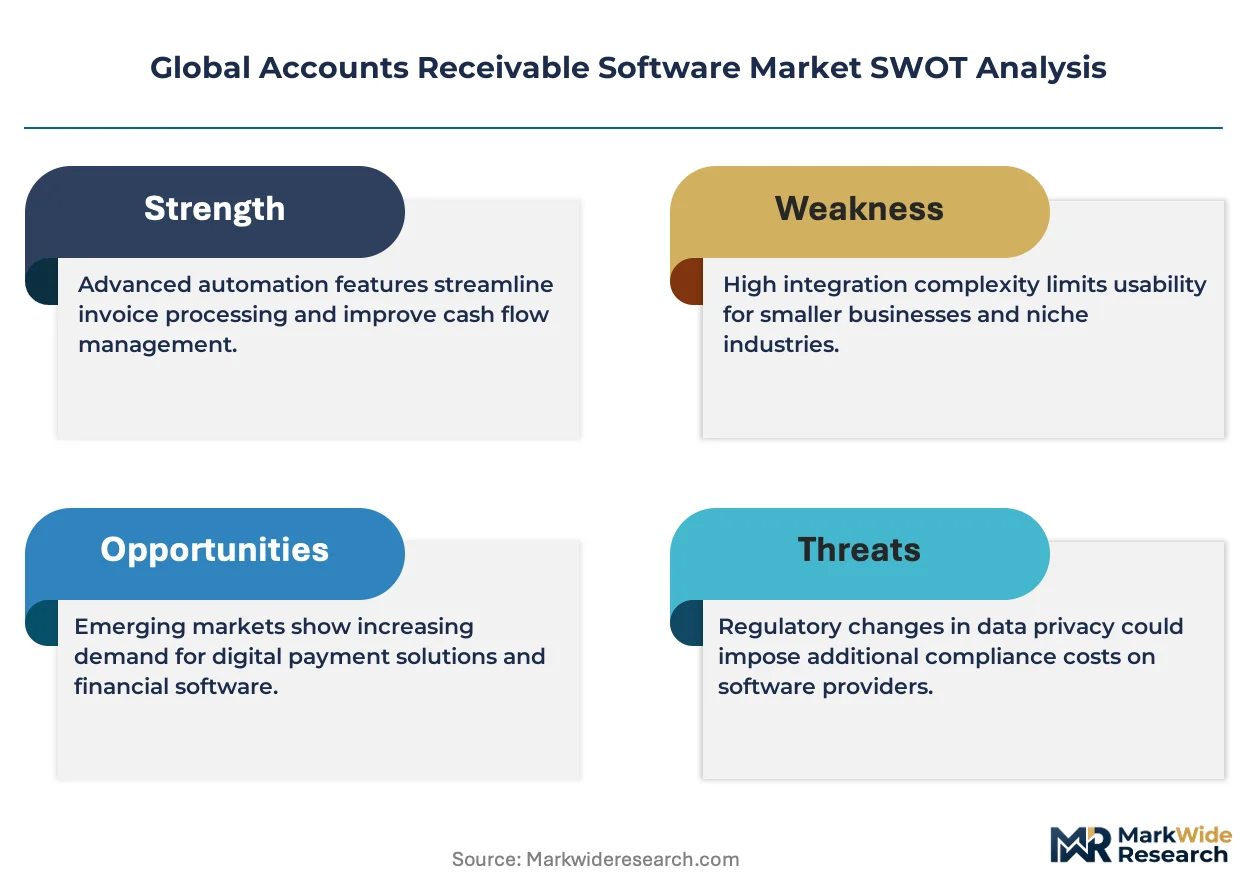
- Cloud infrastructure concentration:Hyperscale provider dominance in data center regions creates single-point-of-failure risk for SaaS receivables platforms serving regulated industries.
- Interoperability friction:Incomplete ISO 20022 adoption across correspondent banking networks forces expensive dual-format message maintenance during multi-year transition windows.
- GDPR compliance premiums:European data residency mandates require redundant hosting infrastructure, elevating total cost of ownership for cross-border receivables operations.
Strategic Opportunities
- Central bank digital currency pilots:Programmable settlement tokens in wholesale CBDC experiments promise atomic invoice-payment matching, eliminating reconciliation lag entirely.
- Embedded finance penetration:Vertical SaaS providers in construction and logistics integrate receivables financing at the point of invoice generation, capturing lending margin pools.
- India's account aggregator framework:RBI-mandated financial data consent architecture enables alternative credit scoring for SME receivables financing outside traditional banking channels.
Industry Challenges
- Legacy ERP integration complexity:On-premises SAP and Oracle instances require custom middleware development, extending implementation timelines and inflating professional services costs.
- ISO 20022 certification bottlenecks:SWIFT message format validation and regional clearing system accreditation create multi-quarter delays for product release schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Accounts Receivable Software Market |
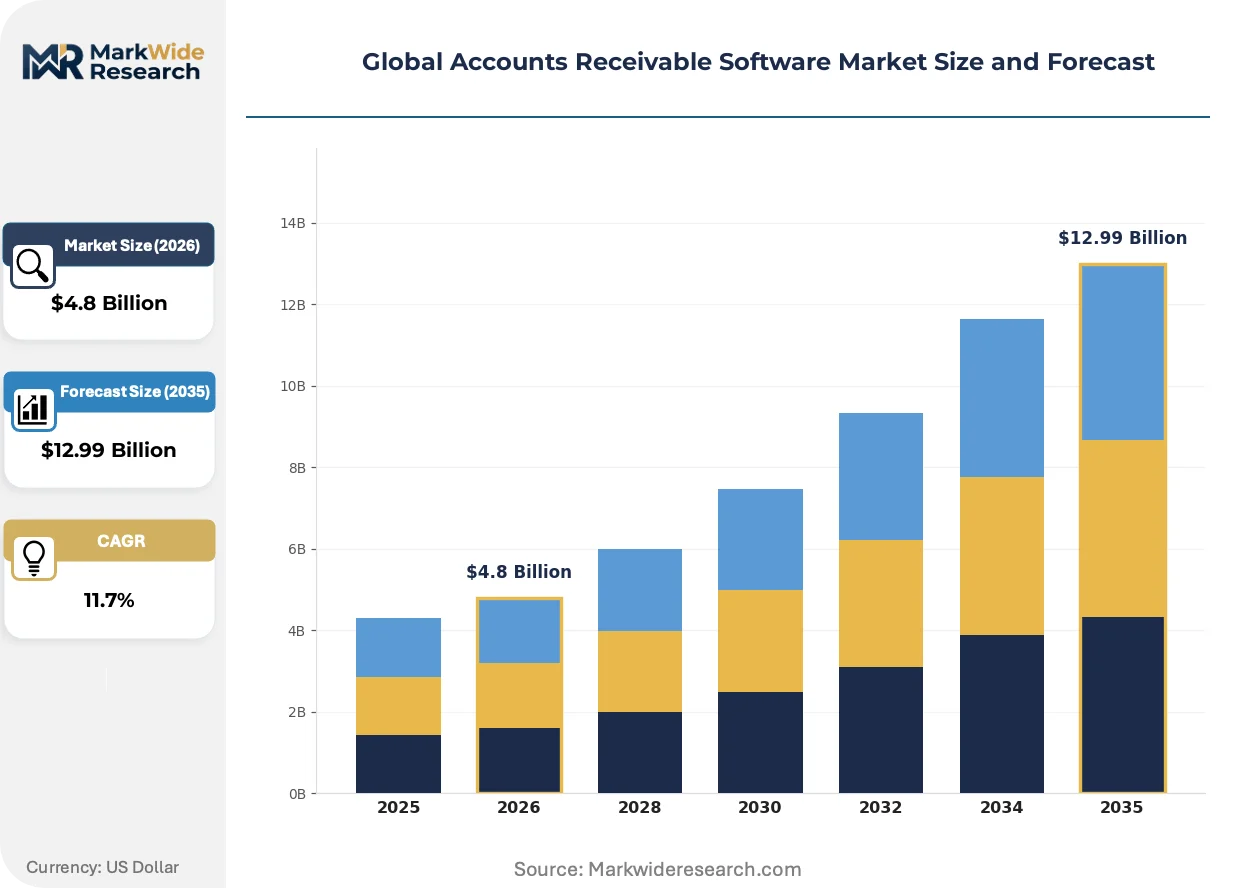
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Solution Type: Invoice Management, Payment Processing, Credit Management, Collection Automation, Reporting & Analytics Application: Small & Medium Enterprises, Large Corporations, Financial Institutions, Non-Profit Organizations, Public Sector Customer Type: Accounting Firms, Retailers, Manufacturing Plants, Service Providers, Wholesale Distributors |
| Companies Covered | SAP SE, Oracle Corporation, BlackLine Inc., HighRadius Corporation, The Sage Group plc, Workday, Inc., Quadient SA, Billtrust, Versapay Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Accounts Receivable Software Market Shifts & Advancements
Real-time payment infrastructure and machine learning convergence are collapsing the invoice-to-cash timeline from weeks to minutes, redefining working capital optimization as a competitive weapon rather than back-office efficiency.
Machine learning models for predictive payment timing are absorbing historical behavioral data from enterprise resource planning systems to forecast customer remittance dates with precision. Mid-market manufacturers and distributors adopt these tools aggressively to optimize liquidity forecasting. The technology is absorbing judgment-based credit decisioning, displacing static scoring models with dynamic risk pricing.
Europe's PSD3 open finance framework mandates account-to-account payment initiation through standardized APIs, bypassing card networks entirely. This regulatory architecture fragments payment acceptance economics and forces receivables platforms to support multi-rail orchestration. Corporate treasury departments in Germany and France accelerate vendor selection processes to meet compliance deadlines.
Subscription billing models in software and business services compress invoice generation cycles from monthly to usage-based micro-billing. Finance teams abandon periodic statement reconciliation in favor of continuous ledger matching against streaming transaction data. This behavioral shift is most visible among SaaS providers serving developer tools and cloud infrastructure segments.
Global Accounts Receivable Software Market Segmentation
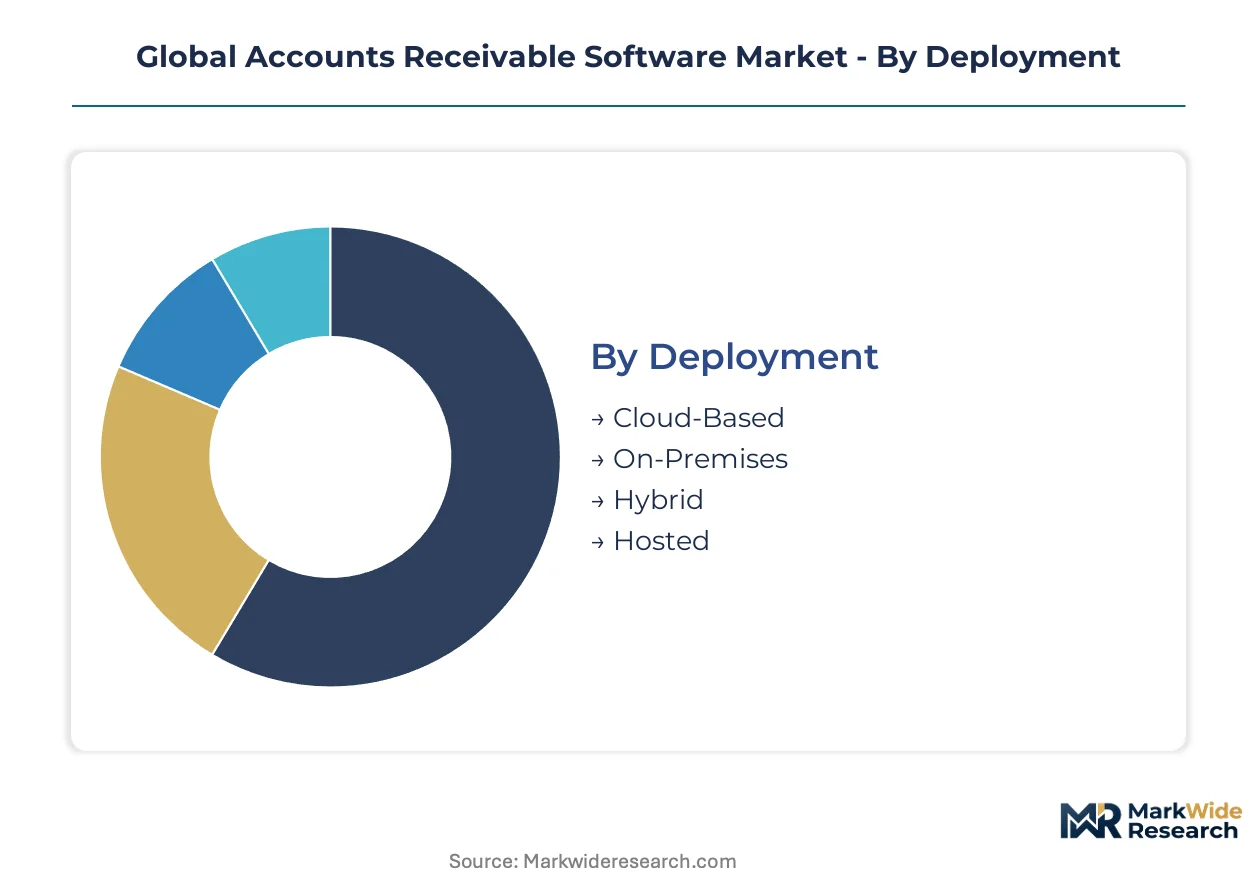
Segmentation in accounts receivable software reveals divergent technology adoption patterns across infrastructure maturity, customer scale, and industry verticals. Deployment architecture choices directly determine integration complexity, compliance posture, and total cost of ownership for finance teams.
Deployment:
Cloud-native architectures dominate new procurement as finance teams abandon data center maintenance burdens.
- Cloud-Based:Multi-tenant SaaS platforms with API-first bank connectivity and automatic compliance patching. Demand concentrates among mid-market retailers and wholesale distributors seeking rapid FedNow integration without infrastructure overhead.
- On-Premises:Legacy ERP-embedded instances requiring dedicated hardware and manual upgrade cycles. Large German manufacturers and Japanese automotive suppliers retain these deployments due to proprietary data sovereignty requirements and deep SAP customizations.
- Hybrid:Sensitive credit data remains on-site while payment processing shifts to cloud rails. US healthcare systems favor this architecture to isolate patient billing records from third-party infrastructure.
- Hosted:Single-tenant cloud deployments with dedicated virtual infrastructure managed by vendors. French and Italian public sector entities specify hosted arrangements to satisfy CNIL and national cybersecurity agency audit requirements.
Mature deployment sits with On-Premises. Newer deployment is concentrated in Cloud-Based.
Solution Type:
Functional modules compete for budget priority based on measurable working capital impact.
- Collection Automation:AI-driven dunning workflows, predictive delinquency scoring, and automated payment plan negotiation. Hospital systems and physician groups in the United States deploy these tools aggressively to reduce administrative headcount dedicated to patient billing follow-up.
- Payment Processing:Multi-rail orchestration spanning ACH, wire, card, and instant payment networks. Wholesale distributors capture disproportionate margin pools through interchange revenue sharing and float optimization.
- Invoice Management:Electronic invoice generation, delivery tracking, and dispute workflow management. German automotive suppliers leverage these platforms to comply with e-invoicing mandates from federal procurement offices.
- Credit Management:Dynamic scoring models, exposure monitoring, and automated credit limit adjustments. Indian NBFCs integrate RBI account aggregator data to score SME receivables outside traditional banking channels.
- Reporting & Analytics:Real-time dashboards for days sales outstanding, aging analysis, and cash forecasting. Treasury departments at Singaporean commodity traders demand these capabilities for multi-currency liquidity management.
Collection Automation commands the steepest expansion trajectory as labor cost pressures intensify across retail and healthcare segments.
Application:
Customer scale determines feature complexity, implementation timeline, and vendor selection criteria.
- Large Corporations:Global treasury platforms requiring multi-entity consolidation, intercompany netting, and jurisdictional tax compliance. Swiss pharmaceutical giants and Dutch energy traders anchor demand for these enterprise-grade deployments.
- Small & Medium Enterprises:Lightweight SaaS tools with pre-built accounting software connectors and self-service configuration. Australian professional services firms and Canadian construction subcontractors adopt these solutions to replace spreadsheet-based tracking.
- Financial Institutions:White-labeled receivables financing platforms and supply chain finance orchestration. Brazilian banks deploy these modules to compete with fintech lenders in SME working capital markets.
- Public Sector:Procurement-to-payment transparency tools with audit trail requirements and citizen-facing payment portals. UK local authorities and Scandinavian municipal governments mandate these capabilities for taxpayer fund stewardship.
- Non-Profit Organizations:Donor pledge management and grant receivables tracking with restricted fund accounting. US universities and international NGOs utilize these specialized modules for complex funding source segregation.
Financial Institutions generate the highest per-customer revenue concentration. SME adoption is climbing the fastest as vertical SaaS bundles reduce procurement friction.
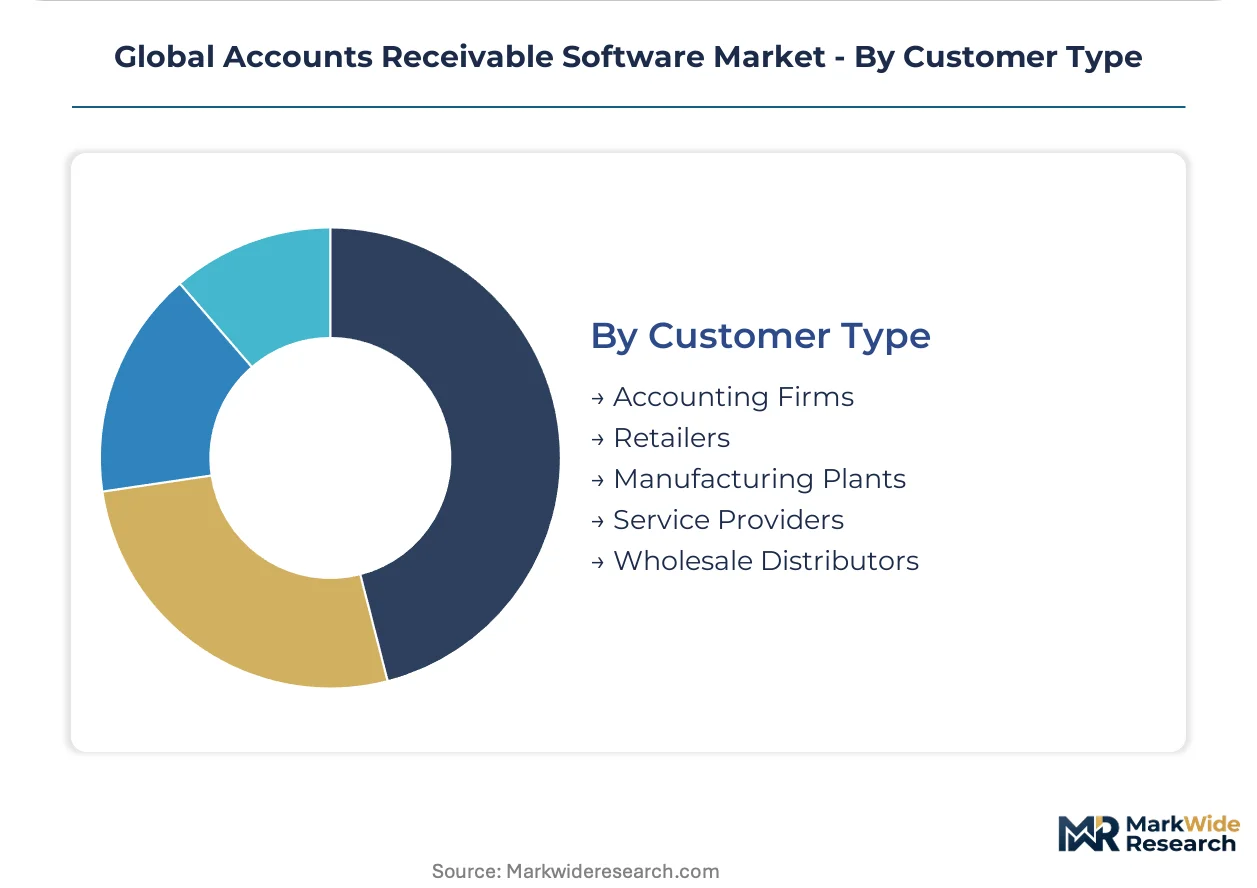
Customer Type:
Industry verticals impose distinct workflow requirements and compliance constraints on platform design.
- Accounting Firms:Multi-client practice management with consolidated billing and automated time capture. UK mid-tier firms and Australian regional practices specify these tools for audit and advisory service monetization.
- Wholesale Distributors:High-volume invoice matching against purchase orders and shipment confirmations. US industrial distributors and German steel traders prioritize cash application accuracy to minimize deduction disputes.
- Manufacturing Plants:Complex milestone billing tied to production completion and quality acceptance gates. Japanese precision equipment makers and Italian machinery builders require these capabilities for project-based revenue recognition.
- Service Providers:Subscription and usage-based billing with automated renewal management. Indian IT services exporters and Irish cloud consultancies leverage these platforms for recurring revenue optimization.
- Retailers:Omnichannel payment reconciliation across POS, e-commerce, and marketplace transactions. French luxury brands and South Korean department stores demand real-time visibility into fragmented payment flows.
Accounting firms represent the most mature vertical penetration. Retailers are gaining share fastest as omnichannel complexity outpaces legacy reconciliation capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's venture capital density and Wall Street's payment infrastructure investments anchor United States demand for receivables automation platforms. Cloud data center clusters in Northern Virginia and financial technology corridors in New York City concentrate vendor development and enterprise procurement decisions.
United States
Mid-market SaaS penetration and FedNow real-time payment adoption drive procurement velocity among healthcare systems and wholesale distributors. The Federal Reserve's instant settlement infrastructure eliminates batch-processing delays for treasury departments. Dallas-Fort Worth hospital networks deploy collection automation to reduce administrative headcount dedicated to patient billing follow-up.
Germany
E-invoicing mandates from federal procurement offices and deep SAP ERP customizations sustain on-premises deployment preferences among automotive suppliers. The EU's PSD3 open finance framework mandates account-to-account payment initiation through standardized APIs. Stuttgart's precision equipment makers require complex milestone billing tied to production completion and quality acceptance gates.
India
RBI-mandated account aggregator frameworks enable alternative credit scoring for SME receivables financing outside traditional banking channels. The central bank's financial data consent architecture fragments traditional lending economics. Bangalore's IT services exporters leverage subscription billing platforms for recurring revenue optimization.
United Kingdom
Mid-tier accounting firms specify multi-client practice management tools for audit and advisory service monetization. GDPR compliance premiums elevate regional hosting costs for cross-border receivables operations. London's commodity traders demand real-time dashboards for multi-currency liquidity management and days sales outstanding tracking.
Japan
Proprietary data sovereignty requirements and deep ERP customizations sustain legacy on-premises deployments among precision equipment manufacturers. METI industrial policy emphasizes supply chain finance digitization for SME working capital access. Nagoya's automotive suppliers retain hybrid architectures to isolate sensitive credit data from third-party infrastructure.
Global Accounts Receivable Software Market Competitive Landscape
Global majors compete with regional champions across ERP integration depth and payment rail connectivity. The vendor base stratifies between consolidated enterprise platforms and specialized cloud-native challengers. Three archetypes dominate: ERP-embedded incumbents with database-layer dominance, AI-driven cash application specialists, and vertical SaaS bundlers capturing mid-market procurement friction. M&A activity concentrates on API-first architectures and FedNow certification capabilities.
Within the enterprise integration tier, SAP SE and Oracle Corporation exemplify ERP-anchored positioning through deep manufacturing and wholesale distribution penetration. HighRadius Corporation occupies a specialist position in AI-driven cash application, competing aggressively with cloud-native challengers for mid-market segment share.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| BlackLine Inc. |
| HighRadius Corporation |
| The Sage Group plc |
| Workday, Inc. |
| Quadient SA |
| Billtrust |
| Versapay Corporation |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up cloud-native specialists concentrate platform development in Northern Virginia data center clusters, compressing infrastructure costs while extracting SaaS margin premiums through FedNow certification scarcity. This ownership pattern tightens pricing discipline across mid-market deployment tiers as vendors recoup integration investments through multi-year subscription lock-in.
Pricing Analysis
Warranty and service bundling separates enterprise-grade implementations from self-service tiers, with FedNow certification support and dedicated customer success managers reserved for premium contracts. Pricing stratifies across premium, standard, and economy tiers based on API call volume entitlements and ISO 20022 message format coverage. Cost compression in the standard tier is intensifying because hyperscale infrastructure providers command escalating compute premiums. Small and medium enterprises exhibit the highest price sensitivity, while large corporations absorb premium pricing for SAP and Oracle database-layer integration.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud infrastructure concentrated in the United States, Ireland, and Singapore for primary data center regions. Platform development draws from specialized machine learning engineering talent pools, ISO 20022 certification consultancies, and API-first banking connectivity providers. Tariff exposure on cross-border data transfer infrastructure elevates total cost of ownership for European deployments under GDPR residency mandates. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and vertical SaaS bundlers serving construction and healthcare segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where platform providers pursue downstream control over payment rail connectivity to capture interchange revenue and float optimization. Winners will anchor receivables automation at the database layer rather than application layer.
For Market Incumbents: To counter cloud-native challengers with native API architectures, SAP and Oracle must accelerate FedNow certification timelines and deepen embedded finance partnerships with regional banks. Prioritize backward integration into real-time payment infrastructure to defend reconciliation latency advantages.
For New Entrants and Emerging Players: Capture white-space opportunity in India's account aggregator-enabled SME receivables financing and US healthcare collection automation for mid-market hospital systems. Penetrate through vertical SaaS bundling with pre-built EHR and ERP connectors rather than horizontal platform positioning.
For Investors and Strategic Acquirers: ISO 20022 certification completion by regional clearing systems is the leading indicator that platform commoditization pressure will intensify, favoring acquisition targets with proprietary data assets or captive banking relationships. Target AI-driven cash application specialists with demonstrated DSO reduction metrics for large wholesale distributors.
| Strategic Initiative | Industry Significance |
|---|---|
| FedNow Certification Investment | Unlocks real-time settlement revenue streams for treasury departments replacing legacy lockbox systems. |
| ISO 20022 Native Architecture | Eliminates dual-format message maintenance costs during multi-year correspondent banking transitions. |
| Embedded Finance Integration | Captures lending margin pools at invoice generation for construction and logistics verticals. |
| Healthcare Collection Automation | Reduces administrative headcount dedicated to patient billing follow-up and insurance denial management. |
| AI-Driven Cash Application | Shrinks days sales outstanding for wholesale distributors through machine learning remittance matching. |
Research Methodology
Multi-period observation of SaaS procurement velocity, FedNow adoption curves, and ISO 20022 migration timelines anchored the trend analysis, supplemented by interviews with CFOs at mid-market manufacturers, treasury directors at wholesale distributors, IT procurement officers at hospital systems, and integration specialists at systems integrators. Secondary validation drew from SEC 10-K filings of publicly traded software vendors, Federal Reserve payment system disclosures, SWIFT message format documentation, and EU PSD3 regulatory texts. Bottom-up deployment modeling triangulated against top-down enterprise software spending forecasts.
Input-output matrices mapped cloud-based versus on-premises deployment penetration, solution type budget allocation, and customer scale adoption patterns across the projection horizon. Segmentation dimensions modeled encompassed deployment architecture, organization size, industry vertical, integration complexity, and regional regulatory framework. CAGRs were derived from trend extrapolation of vendor revenue disclosures and enterprise procurement survey data, with specific weighting applied to AI cash application adoption rates and real-time payment infrastructure investment cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to central bank digital currency pilot outcomes and open finance API standardization fragmentation. Forecasts reflect documented assumptions about regulatory compliance timelines and technology substitution elasticities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Driver and Staff Management Software Market
Software & Services
IT Services Market
Software & Services
Mobile Application Development Market
Software & Services
Global Franchise Management Software Market
Software & Services
Hadoop Market
Software & Services
Push Notifications Software Market
Software & Services
Europe Integration Platform As a Service Market
Software & Services
Enterprise Intellectual Property (IP) Management Software Market
Software & Services
Global Process Mining Software Market
Software & Services
Transient Analysis Software Market
Software & Services
In-Memory Data Grids Software Market
Software & Services
Employee Advocacy Software Market
Software & Services
Aviation Software Market
Software & Services
Staffing Agency Software Market
Software & Services
Global Landscape Software Market
Software & Services
Global Recreation Management Software Market