
 VFX Software Market | 2026-2036
VFX Software Market Size, Share, and Industry Trends Forecast 2026-2036
VFX Software Market Outlook
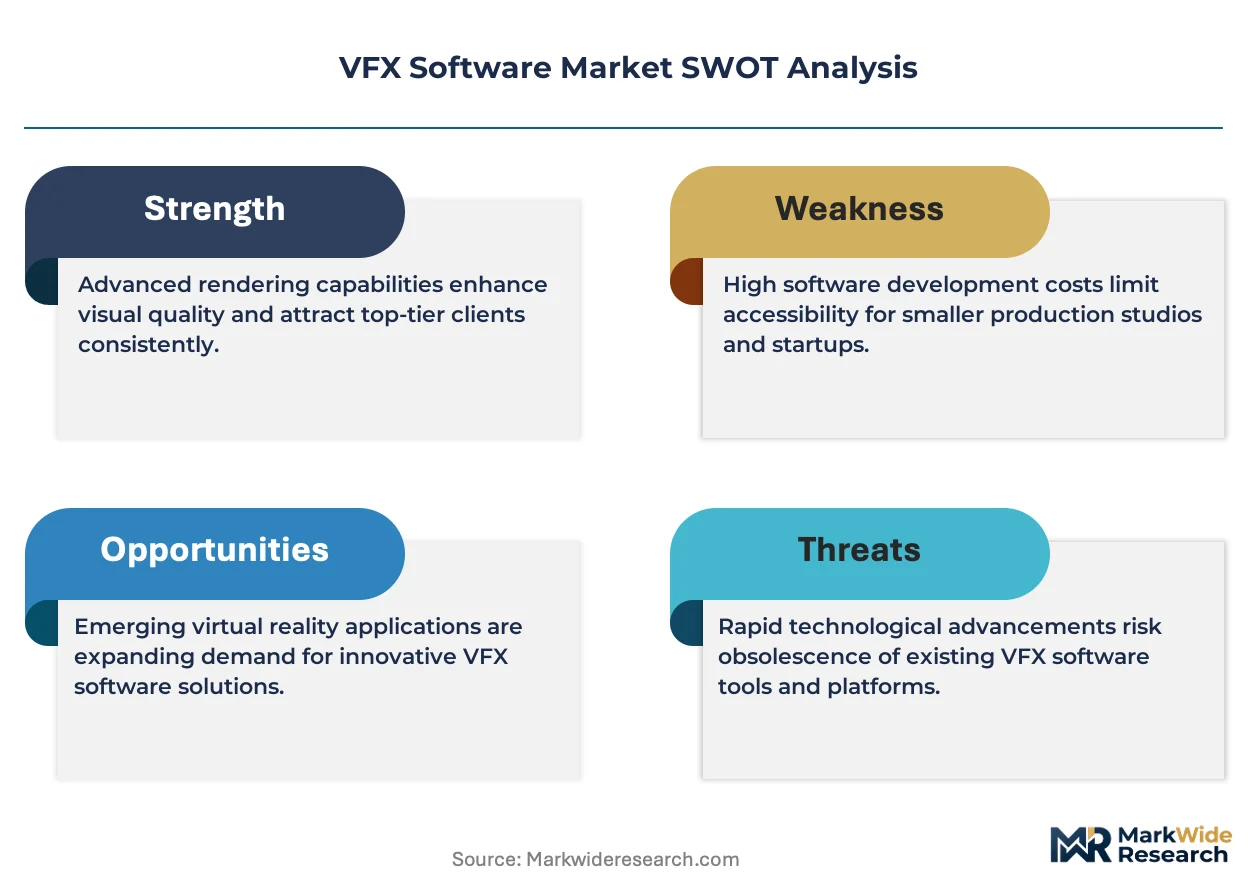
ISO/IEC 27001 certification for cloud-based asset pipelines is bifurcating vendor eligibility between enterprise-grade suppliers and smaller toolmakers. Autodesk leverages its Maya and Flame ecosystems to anchor studio relationships across feature film and broadcast verticals. SideFX differentiates through Houdini's procedural architecture, which dominates effects-heavy productions requiring simulation scalability.
VFX software encompasses digital tools for image manipulation, compositing, animation, and rendering used in motion picture, television, and interactive media production. These systems process high-dynamic-range imagery through node-based or layer-based workflows, with real-time GPU acceleration now matching offline CPU quality for many deliverables. Compositing software and 3D rendering technology lead current revenue pools, while virtual reality tools represent the fastest-expanding segment as location-based entertainment and immersive advertising gain traction. Motion graphics software occupies a mature niche with stable margins, whereas animation software faces margin pressure from open-source alternatives and subscription pricing models.
FCC content guidelines for broadcast standards and MPAA rating compliance frameworks shape rendering fidelity requirements and delivery specifications for US-targeted productions. GDPR and EU AI Act provisions increasingly govern cloud-based rendering farms processing European creator data, forcing architecture decisions about data residency and algorithmic transparency. Stakeholders must monitor whether real-time engine consolidation alters procurement patterns away from perpetual licenses toward integrated platform subscriptions.
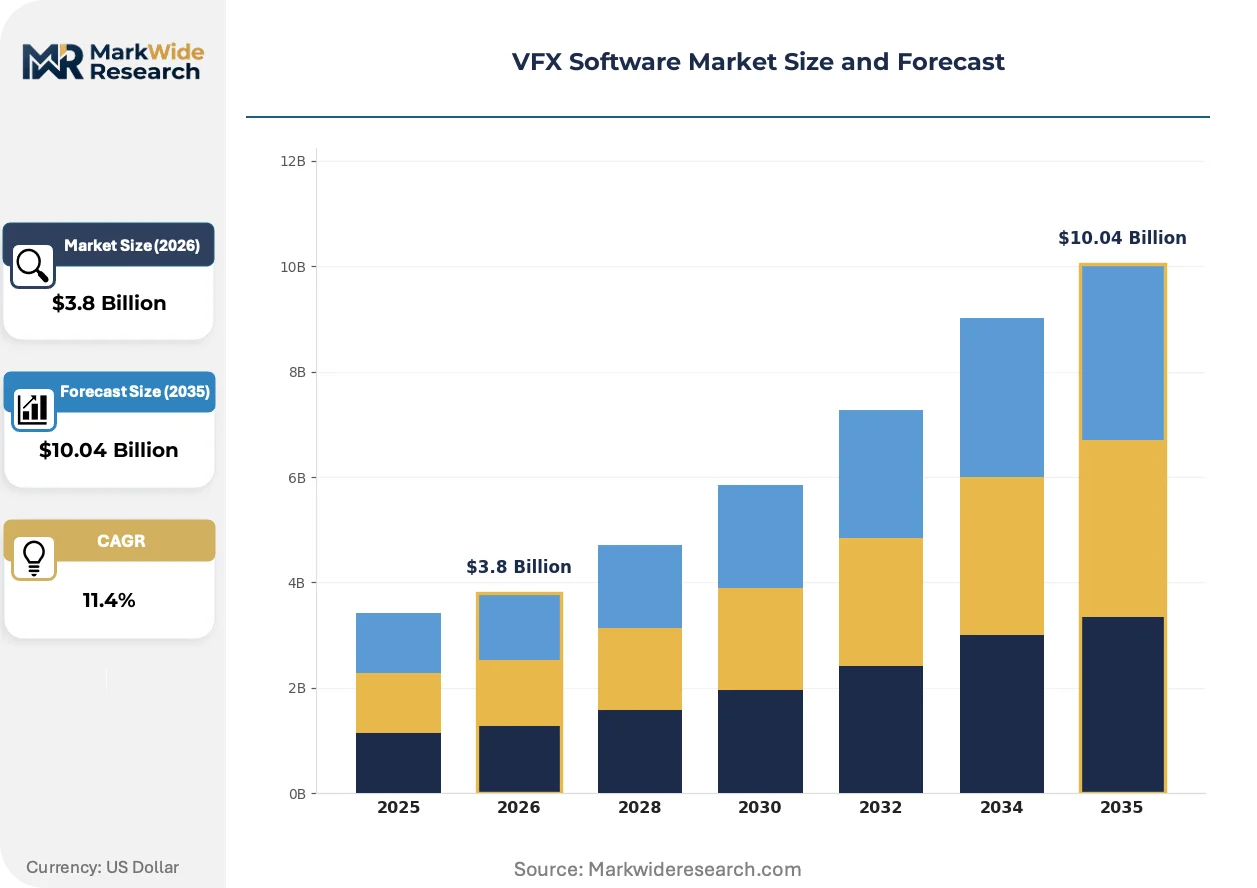
Market Dynamics
Real-time rendering engines are compressing production timelines for episodic television, forcing studios to retool pipeline architectures away from traditional offline CPU farms toward GPU-accelerated workflows.
Growth Catalysts
- Streaming platform content budgets:Netflix, Amazon Prime Video, and Disney+ are commissioning original productions with VFX-heavy specifications that exceed traditional broadcast thresholds.
- ISO/IEC 27001 certification requirements:Cloud-based asset pipelines now mandate enterprise-grade security standards, filtering vendor pools toward established platform providers.
- Procedural simulation scalability:Houdini's node-based architecture enables effects teams to iterate complex physics simulations without rebuilding scene graphs from scratch.
Market Restraints
- GPU hardware cost volatility:NVIDIA datacenter chip shortages inflate render farm capital expenditure by 40-60% for mid-sized facilities.
- Los Angeles-Vancouver production cluster concentration:Talent and infrastructure overdependence on two metropolitan corridors creates geographic vulnerability to labor disruptions.
- Open-source substitution pressure:Blender's feature parity gains erode pricing power for entry-level 3D modeling and animation tools.
Strategic Opportunities
- Location-based entertainment VR:Immersive theme park attractions and retail installations require real-time VFX pipelines with lower latency tolerances than film production.
- EU AI Act algorithmic transparency mandates:Cloud rendering providers can differentiate through auditable processing logs for European creator data.
- USD (Universal Scene Description) pipeline convergence:Interoperability between Maya, Houdini, and Unreal Engine collapses handoff friction between departments.
Industry Challenges
- Real-time engine integration complexity:Legacy Flame and Nuke compositing workflows require expensive bridge development to ingest Unreal Engine outputs.
- ISO 27001 compliance timeline compression:Smaller toolmakers face 18-24 month certification windows that delay cloud service launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VFX Software Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compositing Software, Animation Software, Motion Graphics Software, Video Editing Software End User: Film Studios, Advertising Agencies, Gaming Companies, Educational Institutions Technology: 2D Animation, 3D Rendering, Augmented Reality, Virtual Reality Application: Feature Films, Television, Commercials, Online Content |
| Companies Covered | Autodesk, Adobe, SideFX, Maxon Computer, The Foundry Visionmongers Limited, Chaos Software, Blackmagic Design Pty. Ltd., Epic Games, Unity Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VFX Software Market Strategic Shifts
GPU-accelerated real-time engines are rewriting cost structures for episodic production, collapsing the historical separation between previsualization and final pixel delivery.
Unreal Engine 5's Nanite virtualized geometry and Lumen dynamic lighting are displacing traditional offline raytracing for background plates and environment work in television series. Showrunners at Paramount+ and HBO Max are mandating real-time dailies reviews that previously required overnight CPU farm renders. This compression is eliminating the "temp final" quality tier that dominated streaming workflows through 2022.
GDPR Article 44 transfer mechanism enforcement and the EU AI Act's risk classification framework are forcing cloud rendering providers to architect region-locked compute nodes. Studios processing European creator data must demonstrate data residency through contractual and technical controls. France's CNIL and Germany's DPA authorities are auditing pipeline vendors for algorithmic decision transparency in automated rotoscoping and match-moving services.
Perpetual license procurement is giving way to integrated platform subscriptions that bundle rendering credits, asset storage, and collaboration tools. Mid-sized post-production houses in Vancouver and London are consolidating vendor relationships around Autodesk's Media & Entertainment Collection and Foundry's Nuke Studio ecosystem. This bundling reduces procurement overhead but locks facilities into upgrade cycles timed to platform roadmaps rather than project requirements.
VFX Software Market Segmentation
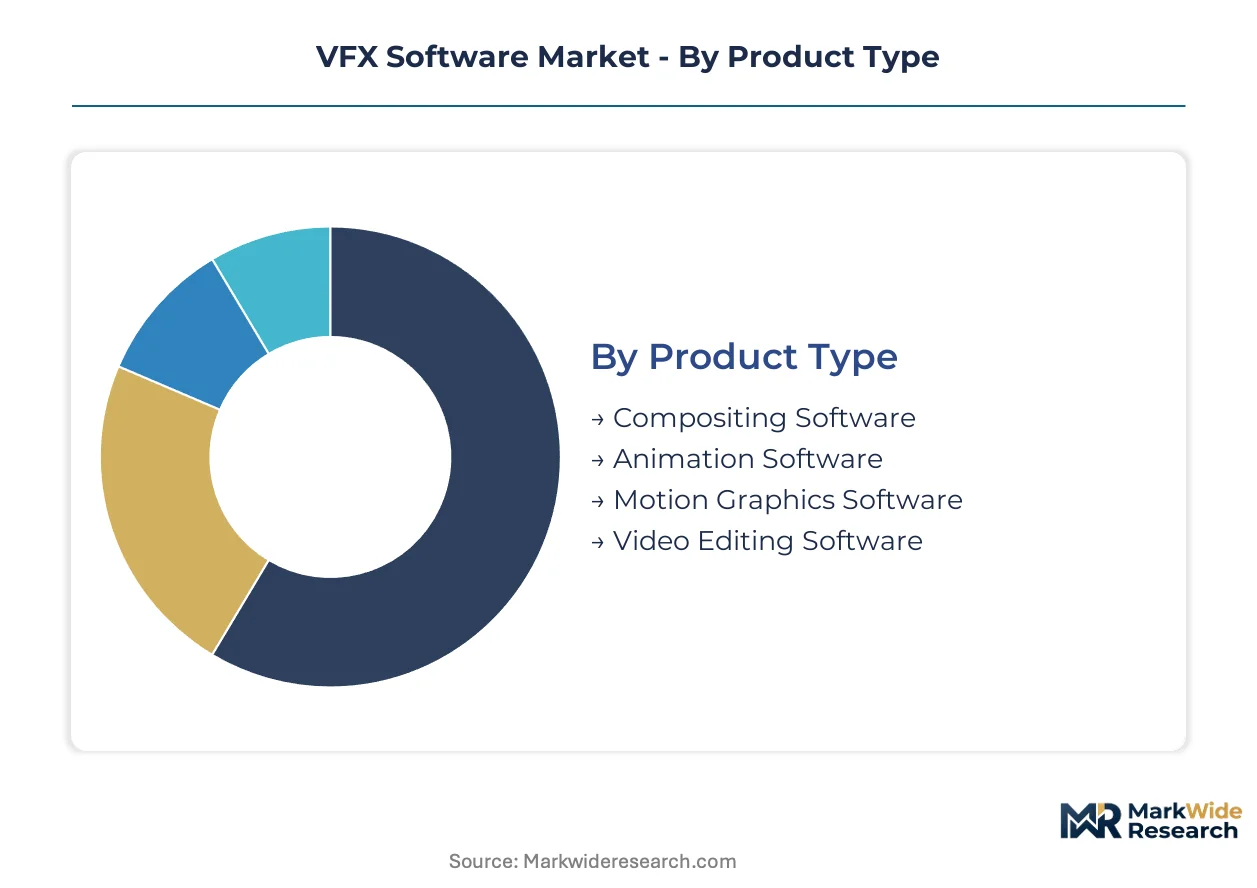
VFX software segmentation reveals how pipeline requirements diverge across production scales and delivery formats. Understanding these divides exposes where procurement budgets concentrate and which tool categories face substitution pressure.
Product Type:
Compositing software demand clusters in Los Angeles and Vancouver facilities serving streaming platform originals, while animation software procurement spreads across mid-sized studios in Mumbai and London seeking cost efficiency.
- Compositing Software:Node-based and layer-based systems process high-dynamic-range imagery for final pixel delivery. Los Angeles post-houses serving Netflix and Disney+ specifications drive premium licensing, with ISO 27001 certification filtering vendor pools toward enterprise-grade suppliers.
- Animation Software:Rigging and keyframe tools face margin compression from Blender's open-source feature parity. Educational institutions in India and Southeast Asia increasingly deploy no-cost alternatives, eroding entry-level pricing power for proprietary suites.
- Motion Graphics Software:Broadcast packaging and title design tools occupy stable-margin niches with predictable upgrade cycles.
- Video Editing Software:Timeline-based cutting systems integrate increasingly with real-time engines for dailies workflows.
Compositing software holds the largest share; momentum sits with animation software as procedural tools displace traditional keyframe approaches.
End User:
Film studios command the highest per-seat licensing values, while advertising agencies prioritize rapid turnaround tools over simulation depth.
- Film Studios:Major motion picture facilities in Los Angeles, London, and Wellington deploy full Autodesk and Foundry stacks with perpetual licenses transitioning to subscription bundles. Real-time engine integration now mandates GPU-accelerated pipeline retooling.
- Advertising Agencies:Commercial production houses in New York and São Paulo favor motion graphics suites with template libraries for compressed delivery schedules.
- Gaming Companies:Real-time engine convergence drives these users toward Unreal Engine and Unity pipelines that bridge cinematic and interactive deliverables.
- Educational Institutions:Training programs in Vancouver, Mumbai, and Berlin shape future talent preferences through curriculum-standard software choices.
Film studios dominate procurement value; gaming companies are climbing fastest as in-engine cinematics blur traditional VFX boundaries.
Technology:
3D rendering commands capital-intensive infrastructure investments, while virtual reality tools attract location-based entertainment spending.
- 2D Animation:Traditional cel and vector-based tools persist in television series production with lower hardware barriers.
- 3D Rendering:CPU and GPU-accelerated engines process photorealistic imagery for feature film delivery. NVIDIA datacenter chip shortages inflate render farm expenditure by 40-60% for mid-sized facilities in Vancouver and London.
- Augmented Reality:Mobile-first overlay tools serve retail and marketing applications with lighter pipeline requirements.
- Virtual Reality:Six-degrees-of-freedom systems require sub-20ms latency tolerances for theme park installations in Orlando and Dubai.
3D rendering anchors revenue pools; virtual reality shows the steepest expansion trajectory as immersive advertising and location-based entertainment gain traction.
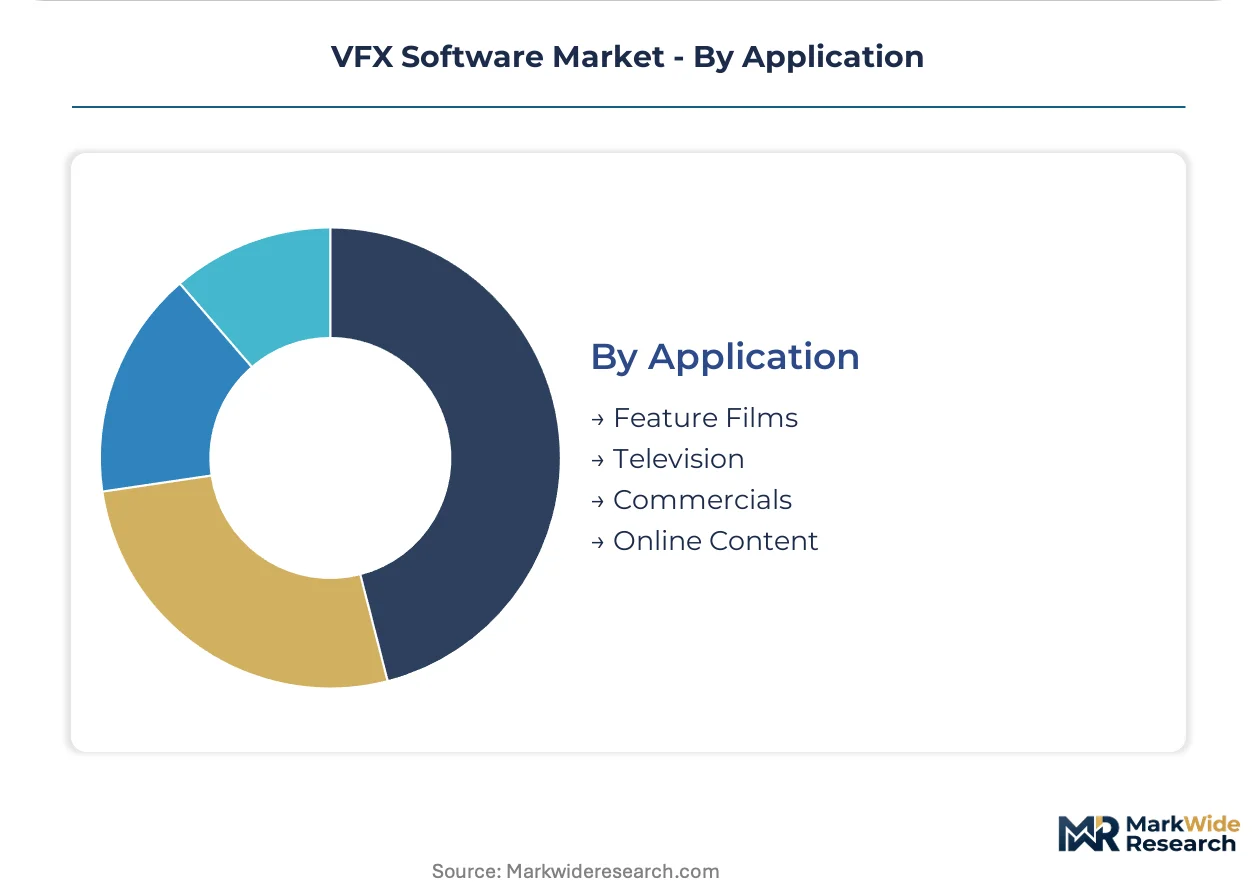
Application:
Television production timelines compress most aggressively under streaming platform volume demands, while feature films retain longer development cycles.
- Feature Films:Theatrical releases in the United States and China sustain the highest fidelity requirements and longest software development partnerships.
- Television:Episodic series at Paramount+ and HBO Max now mandate real-time dailies, collapsing the historical separation between previsualization and final pixel delivery.
- Commercials:Advertising content in major metropolitan markets prioritizes rapid iteration over simulation complexity.
- Online Content:Creator economy productions on YouTube and TikTok drive demand for accessible, subscription-priced tools with lower learning curves.
Television captures the fastest volume expansion; feature films retain the highest per-project software expenditure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC content guidelines and IRA production tax incentives are reshaping facility investment patterns across major production corridors. National regulators are mandating data residency and security certifications that filter vendor eligibility by geography.
United States
Streaming platform original productions at Netflix, Disney+, and Amazon Prime Video drive Los Angeles facility expansion. FCC broadcast standards and MPAA rating compliance frameworks mandate specific rendering fidelity thresholds. California and New York post-houses command premium licensing values for feature film and episodic work.
United Kingdom
London facilities serve as European production hubs for major motion picture franchises and high-end television series. GDPR Article 44 transfer mechanisms and the EU AI Act's risk classification framework enforce data residency requirements for cloud rendering. Soho post-production clusters face escalating certification costs for ISO 27001 compliance.
Canada
Provincial tax credits in British Columbia and Ontario attract streaming platform volume production from US-based content owners. The Canadian Radio-television and Telecommunications Commission maintains broadcast technical standards that align with US FCC specifications. Vancouver production clusters now rival Los Angeles for episodic television VFX shot volume.
India
Mumbai and Hyderabad facilities leverage cost arbitrage for roto-animation and match-moving services on Western productions. The country's national media regulator enforces content certification requirements that shape delivery specifications for domestic theatrical releases. Bengaluru emerging technology corridors incubate real-time engine talent pipelines for gaming and interactive media.
Germany
Berlin and Munich post-houses specialize in automotive advertising and high-end commercial work with compressed delivery schedules. The Federal Network Agency and national data protection authority audit cloud rendering providers for GDPR compliance and algorithmic transparency. Bavaria film fund incentives attract international co-productions requiring German facility participation.
VFX Software Market Competitive Environment
Player mix skews toward diversified platform providers with cross-vertical software ecosystems. Market structure concentrates around three to five dominant vendors controlling compositing, animation, and rendering verticals. Strategic archetypes include full-stack platform bundlers, procedural simulation specialists, and real-time engine disruptors. Competitive moves center on subscription bundling and cloud rendering credit integration.
Among North American platform providers, Autodesk and Adobe occupy positions as full-stack ecosystem anchors. SideFX represents the procedural simulation specialist archetype through its node-based architecture dominance. European specialist The Foundry Visionmongers Limited exemplifies the premium compositing tier with facility-grade tool positioning.
| Leading Market Players |
|---|
| Autodesk |
| Adobe |
| SideFX |
| Maxon Computer |
| The Foundry Visionmongers Limited |
| Chaos Software |
| Blackmagic Design Pty. Ltd. |
| Epic Games |
| Unity Technologies |
| Others |
Value Chain & Pricing Dynamics
GPU-accelerated render engines displacing CPU-based offline pipelines simultaneously concentrate licensing spend in Los Angeles and Vancouver production clusters while compressing per-shot economics for mid-tier facilities. This substitution dynamic rewards vendors with integrated platform subscriptions that bundle compute credits, asset storage, and collaboration tools, eroding standalone perpetual license pricing power.
Pricing Analysis
Cost-plus contracts with NVIDIA datacenter chip indexation dominate render farm procurement for Vancouver and London post-houses. Three-tier pricing structure across enterprise-grade certified, professional standard, and educational economy levels segments buyers by ISO 27001 compliance requirements and volume scale. Pricing pressure stems from Blender's open-source feature parity eroding entry-level animation tool margins. Educational institutions in Mumbai and Southeast Asia exhibit highest price sensitivity, while Los Angeles film studios serving Netflix and Disney+ specifications show lowest.
Supply Chain Analysis
Inbound logistics costs for NVIDIA H100 and A100 datacenter GPUs through Los Angeles and Vancouver ports face container availability constraints on Asia-Pacific trade lanes. Hardware supply concentrates in Taiwan, South Korea, and the United States, with software licensing anchored in California, London, and Toronto. Component dependencies span NVIDIA silicon, cloud compute infrastructure, and enterprise storage arrays. Single-source vulnerability around NVIDIA datacenter GPU allocation creates procurement bottlenecks. Distribution runs through direct vendor relationships with major post-production houses and reseller channels serving mid-tier facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story built on regulatory entrenchment. ISO 27001 certification requirements create 18-24 month compliance windows that filter vendor pools toward established platform providers with existing enterprise security infrastructure.
For Market Incumbents: Compound subscription bundling advantages by integrating rendering credits, asset storage, and real-time engine collaboration tools into unified platform offerings. Deepen certification moats through proactive GDPR Article 44 and EU AI Act compliance architecture for European creator data processing. Defend against open-source substitution pressure by anchoring studio relationships through pipeline interoperability investments and curriculum-standard educational licensing.
For New Entrants and Emerging Players: Anchor in location-based entertainment VR pipelines where sub-20ms latency tolerances and immersive theme park installations in Orlando and Dubai create specialized requirements underserved by film-centric incumbents. Target mid-sized post-houses in Berlin and São Paulo seeking cost-efficient real-time dailies workflows without full Autodesk or Foundry stack investments. Pursue go-to-market partnerships with regional cloud rendering providers offering ISO 27001-certified infrastructure.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors procedural simulation specialists with node-based architecture dominance and established studio relationships. Long-term viability hinges on platform subscription retention rates and real-time engine integration depth rather than perpetual license renewal cycles. Monitor Unreal Engine and Unity pipeline convergence as inflection signal for vendor displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | USD pipeline convergence between Maya, Houdini, and Unreal Engine collapses departmental handoff friction. |
| Certification Investment | ISO 27001 compliance architecture filters cloud rendering vendor eligibility toward enterprise-grade suppliers. |
| Strategic Partnership | Streaming platform original production mandates at Netflix and Disney+ anchor long-term licensing commitments. |
| Geographic Expansion | Vancouver and London facility clusters rival Los Angeles for episodic television VFX shot volume. |
| Acquisition of Specialist Firm | Procedural simulation capabilities in Houdini node-based architecture dominate effects-heavy production scalability. |
Study Parameters
A spread of perspectives from VFX pipeline supervisors, post-production facility CTOs, streaming platform content executives, and cloud rendering procurement leads converged on the working assumptions. Primary interviews combined with secondary validation from SEC filings of publicly traded software vendors, hyperscaler capex disclosures, and industry trade publications including Autodesk and Adobe financial statements. Bottom-up facility licensing estimates triangulated against top-down streaming platform content budget allocations.
Segmentation dimensions modeled span product type, end user archetype, technology deployment, and application format across the projection horizon. CAGRs derived from facility expansion trajectories in Los Angeles, Vancouver, and London correlated with streaming platform original production commissioning rates. Real-time engine adoption curves and GPU hardware procurement cycles informed technology transition assumptions. Regional regulatory frameworks including GDPR Article 44 and EU AI Act provisions shaped European market sizing.
Material uncertainties — NVIDIA datacenter chip allocation constraints, labor disruption in Los Angeles-Vancouver corridors, and open-source feature parity acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about streaming platform content budget sustainability and real-time engine quality parity thresholds. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Semiconductor Fabrication Software Market
Software & Services
File Sharing Software Market
Software & Services
Global Disclosure Management Software Market
Software & Services
Middle East HR Payroll Software Market
Software & Services
Latin America Human Resource (HR) Technology Market
Software & Services
Software As a Service (Saas) Market
Software & Services
3D Animation Software Market
Software & Services
Disk Space Analyzer Software Market
Software & Services
Mainframe Software Market
Software & Services
Global Localization Software Market
Software & Services
Personal Budgeting Software Market
Software & Services
Global Catalog Management Systems Market
Software & Services
US Enterprise Legal Management Software Market
Software & Services
Global Data Governance Software Market
Software & Services
Multiphysics Software Market
Software & Services
Global Managed File Transfer (MFT) Software and Service Market