
 Construction Software Market | 2026-2036
Construction Software Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Software Market Analysis
The EU Green Deal's building performance standards is restructuring procurement priorities across European construction firms, forcing digitization of energy compliance tracking and carbon reporting workflows. Procore leverages its cloud-native architecture to sustain dominance in North American mid-market contracting. Autodesk Build anchors its position through deep integration with design-to-construction workflows, while Fieldwire competes aggressively on field-task mobility for specialty trade contractors.
Construction software encompasses digital platforms that coordinate project planning, resource allocation, cost control, and field execution through centralized data architectures, typically deployed via cloud infrastructure with API connectivity to BIM and ERP systems. Cloud-based deployment leads solution uptake as general contractors abandon on-premise maintenance burdens, though hybrid configurations retain share among security-sensitive infrastructure operators. Project management solutions capture the largest margin pool by bundling scheduling, document control, and financial tracking into unified subscriptions.
FDA oversight intersects indirectly where construction software manages pharmaceutical facility builds, while OSHA recordkeeping mandates shape field-safety module demand and EPA environmental reporting requirements drive compliance feature development. The EU AI Act will soon classify certain automated scheduling algorithms as high-risk, demanding audit trails that reshape product roadmaps. Stakeholders must monitor how evolving building codes across multiple jurisdictions force platform vendors to embed localized compliance engines or cede share to regional specialists.
Market Dynamics
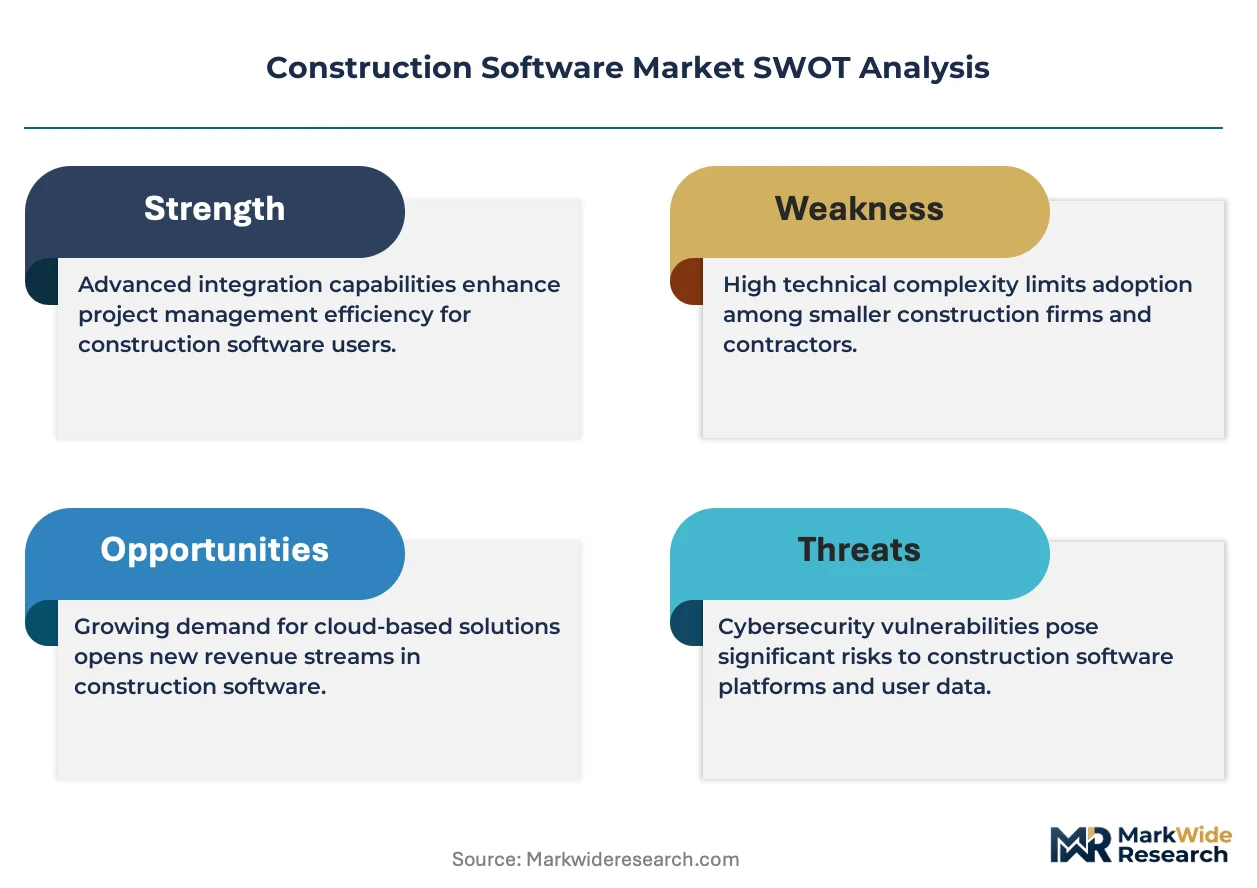
Cloud migration among general contractors is compressing deployment cycles and forcing legacy vendors to rearchitect pricing models around subscription consumption rather than perpetual licenses.
Growth Catalysts
- Federal infrastructure investment:United States public works agencies are mandating digital project tracking for stimulus-funded contracts, pulling mid-tier contractors into integrated platforms.
- EU Green Deal building performance standards:Energy compliance tracking requirements are digitizing carbon reporting workflows across European construction firms.
- API-native architectures:Open integration protocols are collapsing data silos between BIM, ERP, and field execution systems, accelerating platform consolidation.
Market Restraints
- Specialized labor scarcity:Shortage of construction technologists capable of configuring advanced scheduling algorithms limits enterprise rollout velocity.
- Cybersecurity liability concentration:Cloud-hosted project data creates single-point-of-failure exposure that delays adoption among critical infrastructure operators.
- Fragmented subcontractor digitization:Specialty trades with thin margins resist software procurement, breaking data continuity across project phases.
Strategic Opportunities
- India urban infrastructure buildout:Smart city mandates and PLI scheme incentives for construction technology are opening greenfield deployment opportunities.
- Predictive analytics convergence:Machine learning models trained on historical project data are enabling risk-adjusted bidding tools for general contractors.
- Mobile-first field execution:Smartphone penetration among trade laborers is creating channel innovation for task-level workflow applications.
Industry Challenges
- Interoperability certification delays:ISO 19650 compliance timelines stretch 18-24 months, freezing procurement decisions for owners requiring certified data handover.
- Change management intensity:Field supervisor resistance to digital reporting protocols demands dedicated training investment that erodes SaaS margins.
- Legacy ERP integration complexity:Custom middleware development for on-premise accounting systems consumes implementation resources and extends payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Software Market |
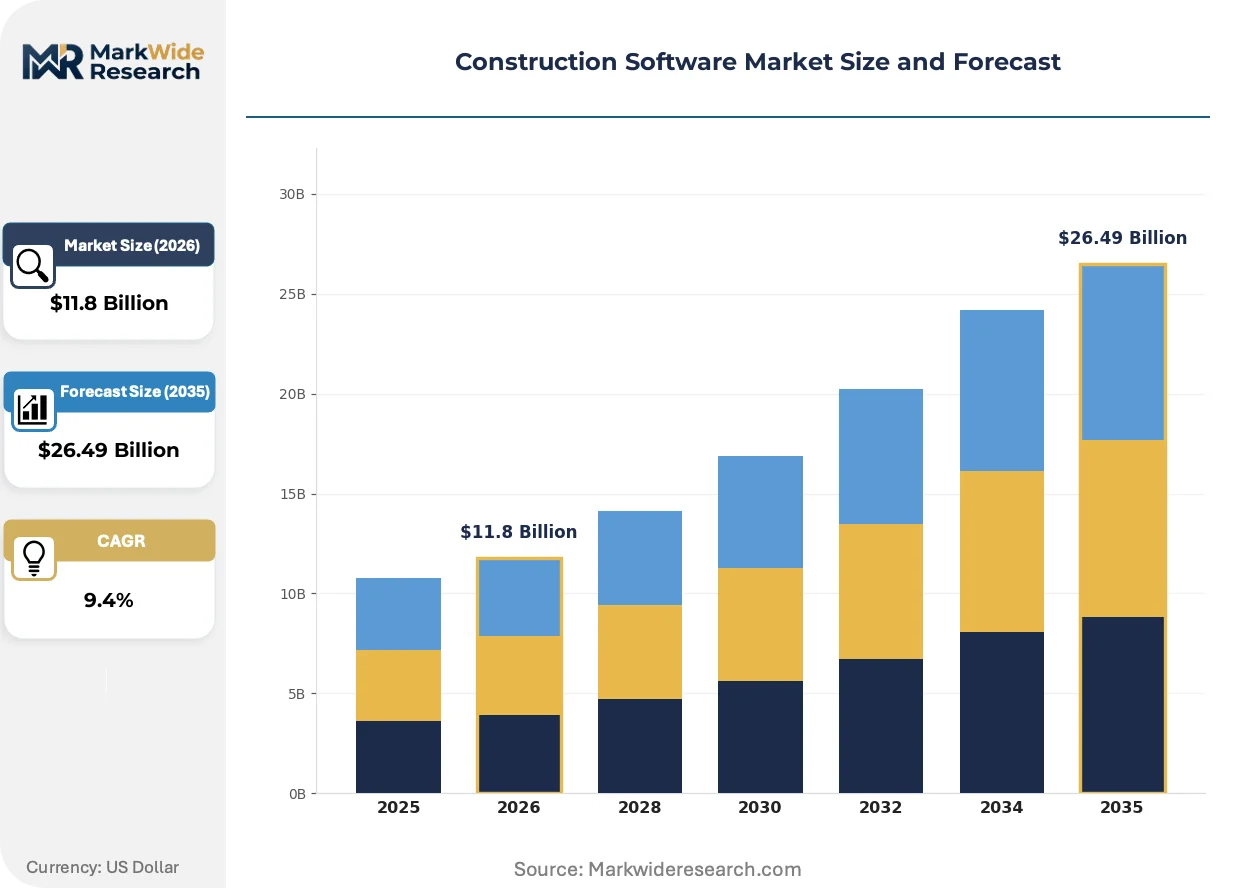
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $26.49 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premise, Cloud-based, Hybrid, Remote Solution: Project Management, Cost Estimation, Scheduling, Collaboration End User: Contractors, Engineers, Architects, Project Managers Application: Residential, Commercial, Infrastructure, Industrial |
| Companies Covered | Fieldwire, e-Builder, Procore, InEight, BuildOps, Autodesk Build, INGENIOUS.BUILD, Jonas Construction Software, Buildertrend, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Software Market Emerging Trajectories
Construction software is pivoting from document repositories toward real-time coordination engines that compress decision latency between field and office.
Digital twin platforms are unifying sensor feeds from equipment, materials, and labor location tracking into live project simulations. Large general contractors in the United States are deploying these systems on mega-projects exceeding $500 million contract value. This unification is collapsing the feedback loop between as-planned and as-built conditions, compressing rework cycles from weeks to hours.
The EU AI Act's high-risk classification for automated scheduling algorithms is mandating audit trail capabilities that reshape product roadmaps. Vendors must embed explainable decision logging that satisfies conformity assessment requirements. European infrastructure operators are prioritizing platforms with pre-certified algorithmic transparency modules.
Subscription fatigue among specialty trade contractors is fragmenting purchasing authority toward project-level procurement. General contractors are responding by unbundling enterprise licenses into consumption-based field tools. This pattern is most visible in United States commercial construction, where superintendent-led software selection is displacing corporate IT standardization.
Construction Software Market Segmentation
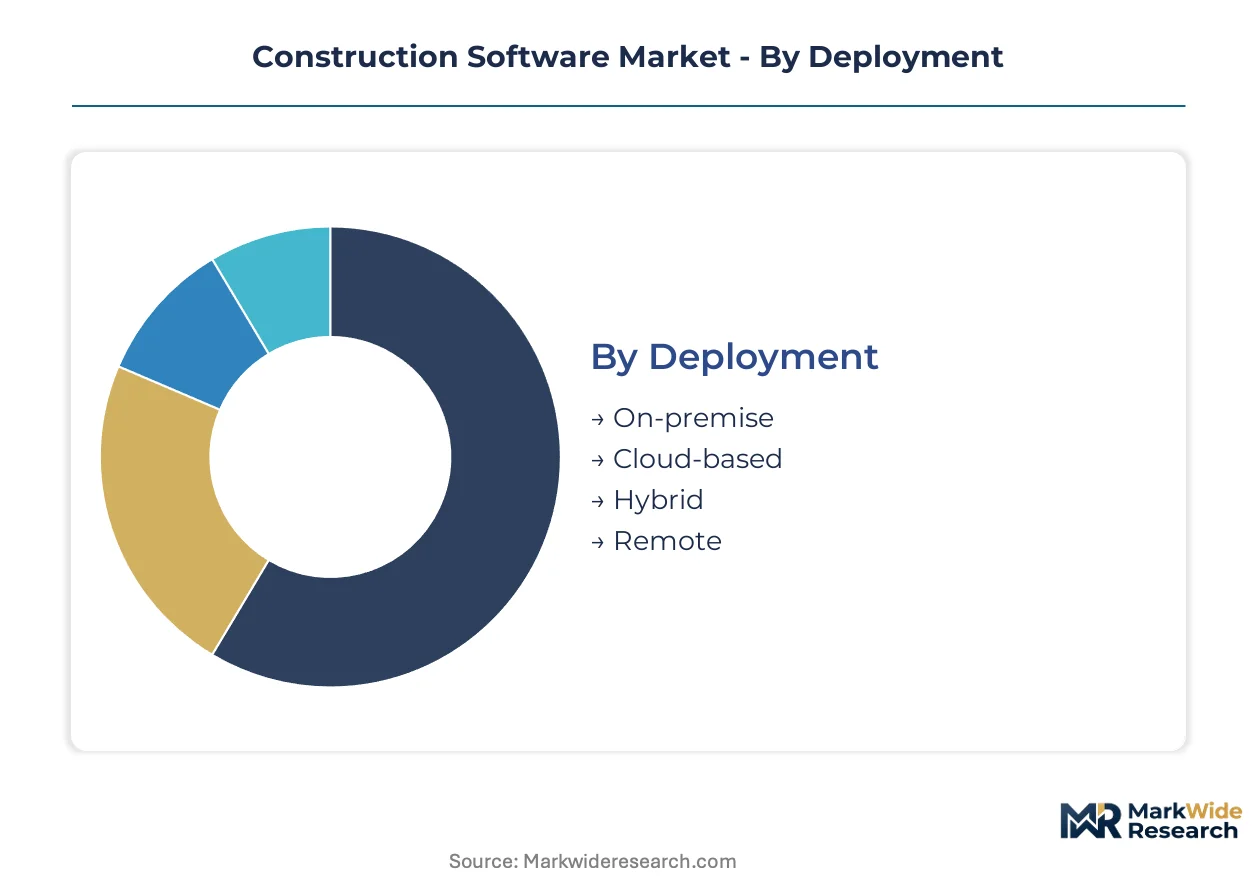
Construction software vendors structure product portfolios around four intersecting dimensions that determine pricing architecture, implementation complexity, and renewal economics. Deployment mode dictates infrastructure investment and security posture. Solution type shapes margin profiles through module bundling. End-user role determines interface design priorities. Application vertical governs compliance engine requirements and sales cycle length.
Deployment:
Purchasing organizations sort into four camps based on data sovereignty tolerance, legacy system entanglement, and IT staffing levels.
- Cloud-based:Multi-tenant SaaS architectures eliminate server maintenance burdens and compress implementation timelines from quarters to weeks. General contractors in the United States with dispersed project portfolios favor this model for centralized visibility across state lines. Subscription economics align vendor incentives with customer success metrics.
- Hybrid:Sensitive financial data remains on-premise while field coordination tools sync through cloud gateways. Infrastructure operators with FERC-regulated assets or defense-adjacent contracts mandate this configuration for audit trail compartmentalization.
- On-premise:Perpetual licensing persists among security-sensitive operators requiring air-gapped environments. Nuclear facility constructors and certain classified federal contractors maintain this stance despite higher total cost of ownership.
- Remote:Edge-deployed instances serve projects with intermittent connectivity—mining operations, remote pipeline construction, offshore wind installations. Synchronization protocols queue transactions for batch upload when bandwidth permits.
Volume sits with Cloud-based deployments; growth tilts toward Hybrid configurations as critical infrastructure operators modernize without surrendering data control.
Solution:
Module selection reflects organizational maturity and the balance between standardization needs versus specialized workflow requirements.
- Project Management:Unified platforms bundle document control, RFIs, submittals, and financial tracking into subscription tiers. Large general contractors consolidate here to replace fragmented point solutions. Bundling captures the largest recurring revenue pool and highest switching costs.
- Scheduling:Critical path optimization with resource leveling algorithms drives adoption on complex multi-prime projects. European infrastructure operators now demand EU AI Act-compliant audit trails for automated scheduling decisions.
- Cost Estimation:Quantity takeoff integration with historical cost databases supports bid preparation. Specialty trade contractors with thin margins depend on accuracy here to avoid catastrophic underbidding.
- Collaboration:Model coordination and clash detection tools bridge design and construction phases. Architects and engineers deploy these for ISO 19650-compliant data handover to construction teams.
Revenue concentrates in Project Management; steepest expansion trajectory belongs to Scheduling as AI compliance requirements reshape procurement criteria.
End User:
Role-based differentiation determines interface complexity, mobile emphasis, and training burden.
- Contractors:Field-first interfaces with offline functionality dominate procurement criteria. Superintendents prioritize task-level workflow tools over enterprise dashboards.
- Project Managers:Cross-functional coordination demands span scheduling, cost control, and stakeholder communication. This role drives platform consolidation decisions.
- Engineers:Technical specification management and design integration shape purchasing. Structural and MEP engineers require deep BIM connectivity.
- Architects:Design intent preservation through construction drives interest in model-based collaboration tools. Smaller practices resist enterprise licensing economics.
User volume clusters with Contractors; fastest share gains accrue to Project Managers as general contractors flatten organizational hierarchies.
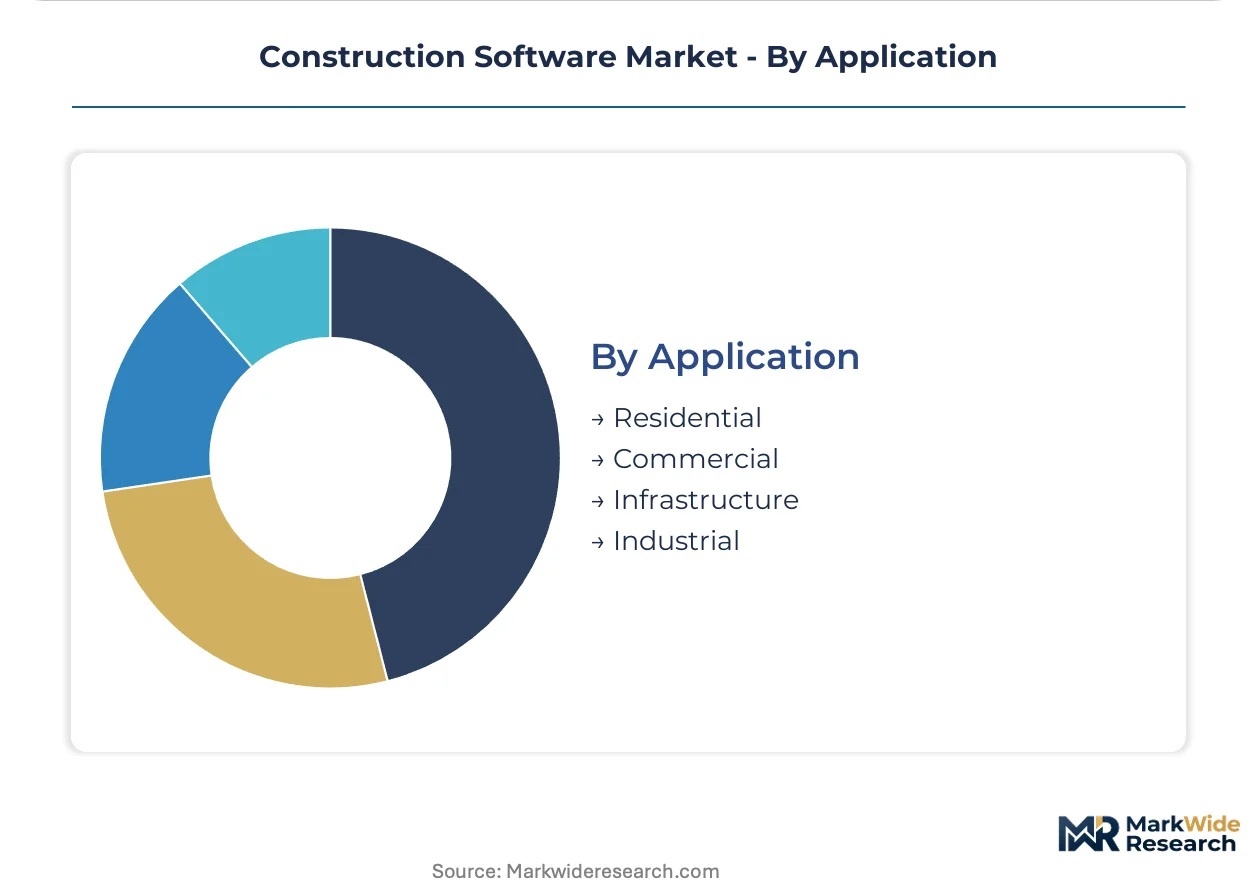
Application:
Vertical specialization governs compliance engine requirements and sales cycle economics.
- Commercial:Office, retail, and hospitality projects generate consistent demand for tenant improvement workflows and lease-integrated project tracking. United States metropolitan construction volumes concentrate here.
- Infrastructure:Transportation, water, and energy projects carry extended timelines, public funding compliance, and stringent safety documentation. Federal stimulus programs in the United States accelerate digitization mandates.
- Residential:Production homebuilders and multifamily developers prioritize speed-to-market tools with supply chain integration. Margin compression limits software spend per unit.
- Industrial:Manufacturing facilities, data centers, and pharmaceutical plants demand cleanroom protocols, FDA-aligned documentation, and specialized MEP coordination. Validation requirements extend implementation cycles.
Project value concentrates in Infrastructure; Commercial applications expand most quickly as private development recovers and institutional investors deploy capital.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley and Seattle anchor North American construction software development, hosting engineering hubs that supply cloud-native platforms to contractors nationwide. Federal infrastructure stimulus and EU Green Deal mandates are pulling procurement decisions toward compliance-embedded solutions across multiple jurisdictions.
United States
General contractors in Texas and Florida are consolidating field operations onto unified project management platforms as federal stimulus mandates digital tracking for public works contracts. OSHA recordkeeping requirements shape safety module procurement across commercial and infrastructure segments. The Pacific Northwest corridor hosts development centers supplying API-native architectures to mid-market contractors nationwide.
Germany
Infrastructure operators in Bavaria and North Rhine-Westphalia prioritize hybrid deployment models that satisfy audit compartmentalization requirements under national security protocols. The EU AI Act's high-risk classification for automated scheduling algorithms is mandating explainable decision logging in procurement criteria. Stuttgart's engineering clusters are driving BIM-to-construction workflow integration for industrial facility builds.
India
Smart city mandates in Maharashtra and Karnataka are opening greenfield deployment opportunities for mobile-first field execution tools among urban infrastructure contractors. The PLI scheme incentives for construction technology are accelerating local software development. Delhi-NCR's commercial construction boom is pulling mid-tier developers into cloud-based project coordination platforms.
United Arab Emirates
Mega-project developers in Dubai and Abu Dhabi are deploying digital twin platforms on contracts exceeding $500 million, unifying sensor feeds from equipment and labor tracking. MOHAP facility construction requirements are shaping compliance module specifications for pharmaceutical and healthcare builds. The Saudi border corridor is extending demand for remote-deployed edge instances serving intermittent connectivity environments.
United Kingdom
Commercial developers in London and the Southeast are unbundling enterprise licenses into consumption-based field tools as superintendent-led procurement displaces corporate IT standardization. Building Safety Regulator mandates are digitizing compliance handover workflows for high-rise residential projects. Manchester's infrastructure renewal programs are pulling mid-market contractors into ISO 19650-certified collaboration platforms.
Construction Software Market Vendor Landscape
Premium-margin players sit above commodity-margin players across deployment architecture sophistication, with cloud-native platforms commanding subscription premiums over legacy on-premise installations. The vendor base stratifies into three tiers: design-to-construction integrators anchoring enterprise accounts, field-task mobility specialists capturing specialty trade contractors, and mid-market project management generalists. Consolidation pressure is intensifying as API-native architectures collapse data silos and force point-solution obsolescence. Dominant competitive moves include strategic partnerships with BIM and ERP incumbents, plus geographic expansion through localized compliance engine development.
Within the cloud-native platform tier, Procore Technologies Inc. and Autodesk Build occupy positions exemplifying design-to-construction workflow integration, while Fieldwire represents the field-task mobility archetype targeting specialty trade contractors with smartphone-first interfaces. These three companies anchor distinct strategic vectors that competitors must match or circumvent.
| Leading Market Players |
|---|
| Fieldwire |
| e-Builder |
| Procore |
| InEight |
| BuildOps |
| Autodesk Build |
| INGENIOUS.BUILD |
| Jonas Construction Software |
| Buildertrend |
| Others |
Supply Flow & Price Mechanics
Cloud-native platform migration is simultaneously collapsing implementation costs for buyers and concentrating vendor pricing power among API-architecture leaders with proven compliance modules. This technology shift rewards scale economies in software development while squeezing margins for legacy on-premise installers unable to rearchitect subscription models.
Pricing Analysis
Value-based pricing anchored to project outcome metrics—on-time delivery rates, rework reduction percentages, and compliance audit pass rates—dominates enterprise procurement negotiations. Pricing stratifies across premium, standard, and economy tiers based on API integration depth and EU AI Act certification status. Cost compression in the mid-market tier is intensifying because general contractors unbundle enterprise licenses into consumption-based field tools. Specialty trade contractors exhibit acute price sensitivity, while infrastructure operators with federal compliance mandates demonstrate inelastic demand for certified audit-trail modules.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud infrastructure providers—AWS, Microsoft Azure, and Google Cloud—hosting the majority of multi-tenant SaaS deployments for North American and European contractors. Software development draws from engineering talent pools concentrated in the United States, India, and Germany, with API middleware components sourced from specialized integration vendors. Regulatory restriction risk looms as the EU AI Act mandates algorithmic transparency certifications that freeze procurement decisions for uncertified platforms. Distribution runs through direct enterprise sales teams and systems integrators with vertical construction expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction software capacity is supply-constrained by the scarcity of construction technologists capable of configuring advanced scheduling algorithms, propping vendor pricing power and extending implementation backlogs.
For Market Incumbents: Deepen API-native architecture investments to collapse data silos between BIM and ERP systems before emerging cloud-native challengers achieve interoperability parity. Acquire specialized field-task mobility developers to preempt unbundling threats from superintendent-led procurement patterns. Prioritize EU AI Act compliance certification to capture European infrastructure operators mandating explainable decision logging. For New Entrants and Emerging Players: Specialty trade contractors with thin margins and smartphone-first workflow needs represent the most penetrable buyer archetype underserved by enterprise-focused incumbents. Target mobile-first field execution tools with offline functionality for remote pipeline and mining operations in the United Arab Emirates and Saudi border corridors. Pursue project-level procurement channels through superintendent relationships rather than corporate IT gatekeepers. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid-deployment specialists given critical infrastructure operators modernizing without surrendering data control under FERC and national security protocols. Long-term viability favors vendors with pre-certified compliance engines across multiple jurisdictions. Monitor ISO 19650 certification timelines as an inflection indicator—delays freeze procurement decisions and concentrate share among certified platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-native architectures collapse data silos between BIM, ERP, and field execution systems. |
| Acquisition of Specialist Firm | Field-task mobility developers preempt unbundling threats from superintendent-led procurement. |
| Geographic Expansion | Localized compliance engine development captures EU Green Deal and EU AI Act mandates. |
| Product Launch | Digital twin platforms unify sensor feeds for contracts exceeding $500 million in the UAE. |
| Strategic Partnership | BIM and ERP incumbent alliances accelerate design-to-construction workflow consolidation. |
Methodological Framework
SEC filings, hyperscaler capex disclosures, and construction technology trade publications formed the secondary backbone, cross-referenced with primary interviews involving CTOs at general contracting firms, IT procurement officers at infrastructure operators, platform engineers at software vendors, and integration specialists deploying API middleware. Bottom-up sizing of deployment mode, solution type, end-user role, and application vertical segments was triangulated against top-down macroeconomic indicators across the analysis window.
Historical trendline analysis of cloud adoption rates, subscription pricing migration, and compliance module attachment informed the analytical framework. Segmentation dimensions modeled include deployment architecture, organization size, vertical specialization, integration complexity, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for EU AI Act implementation timelines and federal infrastructure stimulus disbursement patterns.
Revisions become necessary when EU AI Act enforcement timelines accelerate, federal infrastructure funding allocations shift, or cybersecurity liability frameworks harden against cloud-hosted project data. Forecasts reflect documented assumptions about technology adoption curves and regulatory compliance costs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Grant Management Software Market
Software & Services
Global Recreation Management Software Market
Software & Services
Global Subscription Billing Software Market
Software & Services
Global Employee Engagement and Feedback Software Market
Software & Services
Digital Onboarding Platform Market
Software & Services
Office Productivity Software Market
Software & Services
Investor Relations (IR) Website Builder Software Market
Software & Services
PCB Layout Software Market
Software & Services
Global Online Form Builder Software Market
Software & Services
Exploration and Production (E&P) Software Market
Software & Services
Latin America Cloud Workforce Management Software Market
Software & Services
Global OEE Software Market
Software & Services
Feedback Management Software Market
Software & Services
Predictive Dialer Software Market
Software & Services
Intellectual Property Software Market
Software & Services
Global Time and Attendance Management Software Market