
 Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market | 2026-2036
Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market Size, Share, and Industry Trends Forecast 2026-2036
Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market Analytics
Enterprise distribution channels for programmable networking infrastructure is reconfiguring around cloud-native procurement models. Cisco Systems leverages its installed base of routing hardware to push subscription-based SDN controllers into Fortune 500 accounts. Nokia anchors its competitive position through deep vertical integration with telecom-specific orchestration stacks. Huawei Technologies dominates emerging market deployments where cost-sensitive carriers prioritize open-source control plane alternatives.
Software Defined Networking and Network Function Virtualization decouple network control logic from proprietary hardware through centralized, programmable controllers and virtualized network functions running on commodity servers. OpenFlow protocol specifications enable direct manipulation of forwarding tables across multi-vendor switches, replacing manual CLI configuration with automated policy enforcement. The control plane segment captures premium margin pools as orchestration software becomes the strategic bottleneck in telco cloud transformations. Hybrid cloud deployments are expanding fastest among enterprises seeking to bridge on-premises legacy gear with public cloud network overlays. Managed service providers represent an underdeveloped channel where VMware NSX and Cisco ACI expertise commands pricing power.
FCC open internet rules and NIST cybersecurity frameworks shape how U.S. carriers architect virtualized core networks, mandating traceability and access controls that favor audited SDN platforms. ETSI NFV standards and EU GDPR data-localization requirements drive European operators toward sovereign cloud deployments with embedded compliance tooling. Stakeholders must monitor how 3GPP release timelines synchronize with containerized network function maturity to time infrastructure refresh cycles.
Market Dynamics
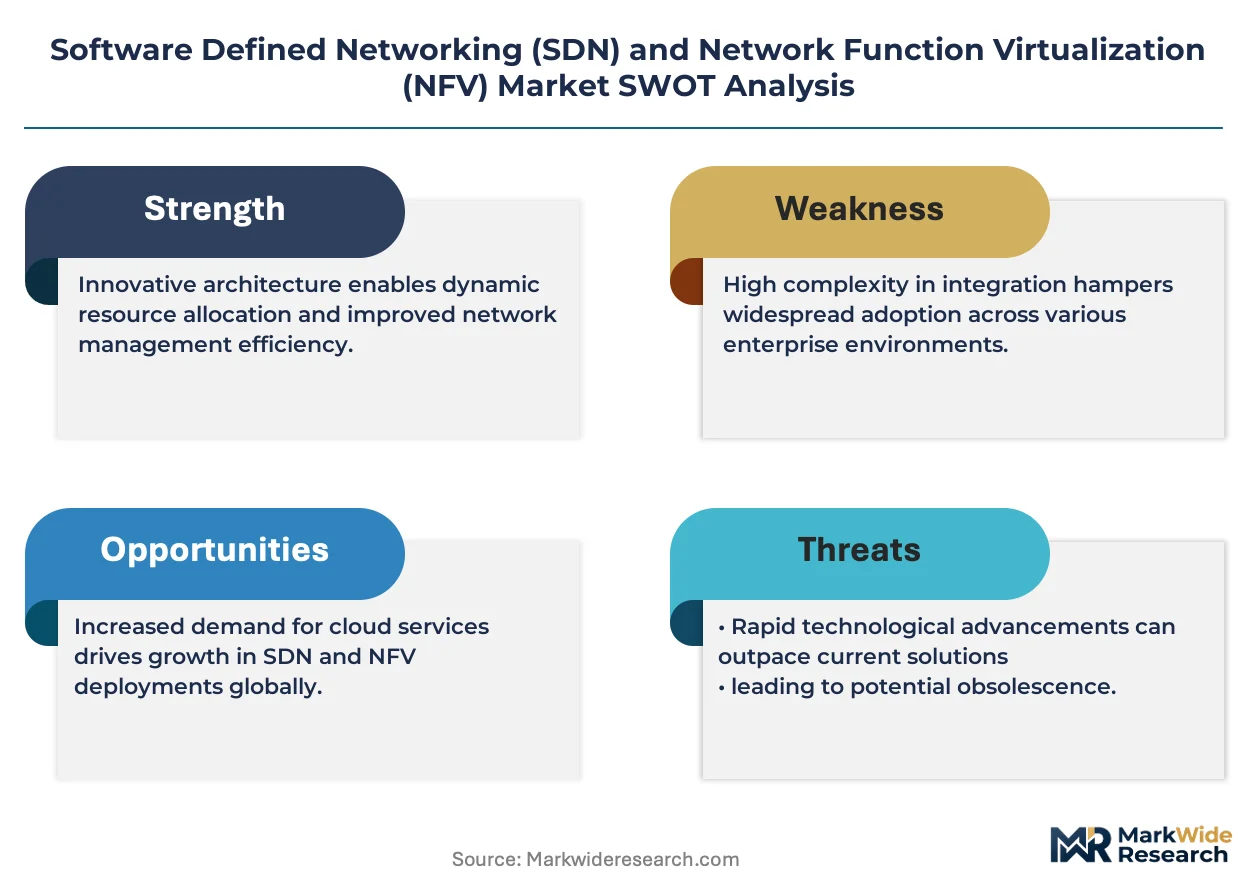
Telecom operators are dismantling hardware-centric network architectures in favor of software-defined control planes that centralize policy enforcement and slash provisioning cycles from weeks to minutes.
Growth Catalysts
- EU AI Act compliance mandates:European carriers are virtualizing core functions to embed auditable decision trails and automated governance into network operations.
- Cloud hyperscaler infrastructure buildouts:Amazon Web Services, Microsoft Azure, and Google Cloud are deploying programmable networking fabrics across their data center footprints to optimize east-west traffic.
- Open-source control plane alternatives:ONOS and OpenDaylight adoption in cost-sensitive emerging markets is accelerating disaggregation of routing software from proprietary silicon.
Market Restraints
- Specialized engineering talent scarcity:The shallow pool of engineers proficient in both legacy MPLS protocols and Kubernetes-orchestrated container networking constrains deployment velocity.
- Optical transport hardware concentration:Dependence on a limited set of coherent DSP suppliers creates vulnerability in 400G/800G wavelength deployment timelines.
- FCC open internet traceability requirements:Mandatory logging and access control specifications add architectural complexity that slows virtualized core rollouts.
Strategic Opportunities
- India's sovereign cloud mandate:TRAI data-localization directives are compelling domestic carriers to deploy compliant NFV infrastructure with embedded encryption and geographic fencing.
- Edge computing convergence:Synchronization of containerized network functions with 5G MEC nodes creates new monetization paths for low-latency enterprise services.
- Managed SD-WAN channel expansion:Service providers lacking in-house VMware NSX or Cisco ACI expertise represent an underdeveloped resale avenue commanding premium implementation fees.
Industry Challenges
- Multi-vendor interoperability certification:ETSI NFV compliance testing cycles average 18-24 months, delaying revenue recognition for new virtualized network function releases.
- Technical debt in legacy OSS/BSS integration:Bridging decades-old billing and provisioning systems with cloud-native orchestration APIs requires expensive custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market |
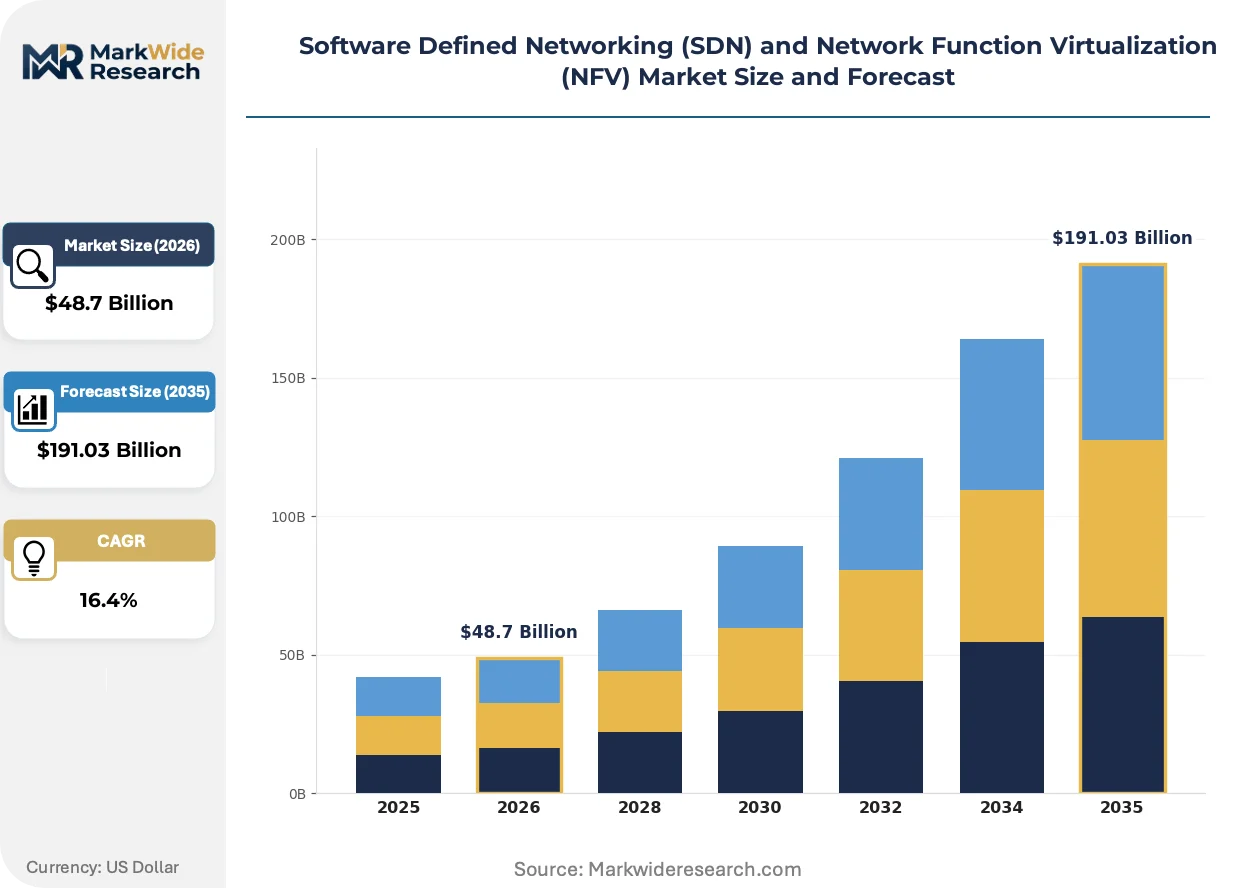
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $191.03 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Control Plane, Data Plane, Application Plane, Virtualization Software Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-premises End User: Telecom Providers, Enterprises, Government Agencies, Managed Service Providers Technology: OpenFlow, Microsoft Azure, Cisco ACI, VMware NSX |
| Companies Covered | Hewlett Packard Enterprise, Nokia, Cisco Systems, Intel Corporation, IBM, VMware, Huawei Technologies, Arista Networks, Juniper Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market Evolving Landscape
Intent-based networking systems are supplanting imperative configuration models, compressing operational complexity into declarative policy statements that autonomous controllers translate into device-level instructions.
Cloud-native network functions packaged as microservices are digitizing how mobile core elements scale horizontally across distributed Kubernetes clusters. Tier-1 operators in Germany and South Korea are migrating packet core components to containerized architectures that instantiate on demand rather than provisioning fixed appliances. This shift is digitizing capital allocation patterns, transforming network infrastructure from depreciating hardware assets into elastic software subscriptions.
ETSI NFV Release 4 specifications are mandating enhanced platform awareness and hardware acceleration abstraction layers that complicate vendor certification pathways. European operators must now demonstrate compliance with both ETSI standards and EU GDPR data-localization requirements before deploying virtualized subscriber databases. The control plane segment bears the heaviest compliance burden, forcing orchestration vendors to embed sovereign cloud tooling directly into their management stacks.
Enterprise procurement of networking infrastructure is consolidating around cloud-native consumption models that bundle software licenses with managed operations. Fortune 500 technology buyers are displacing traditional resale channels with direct hyperscaler marketplaces and carrier-integrated service wraps. This reconfiguration is most pronounced in the United States, where FCC regulatory clarity on virtualized network security has accelerated carrier willingness to assume operational responsibility for enterprise edge deployments.
Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market Segmentation
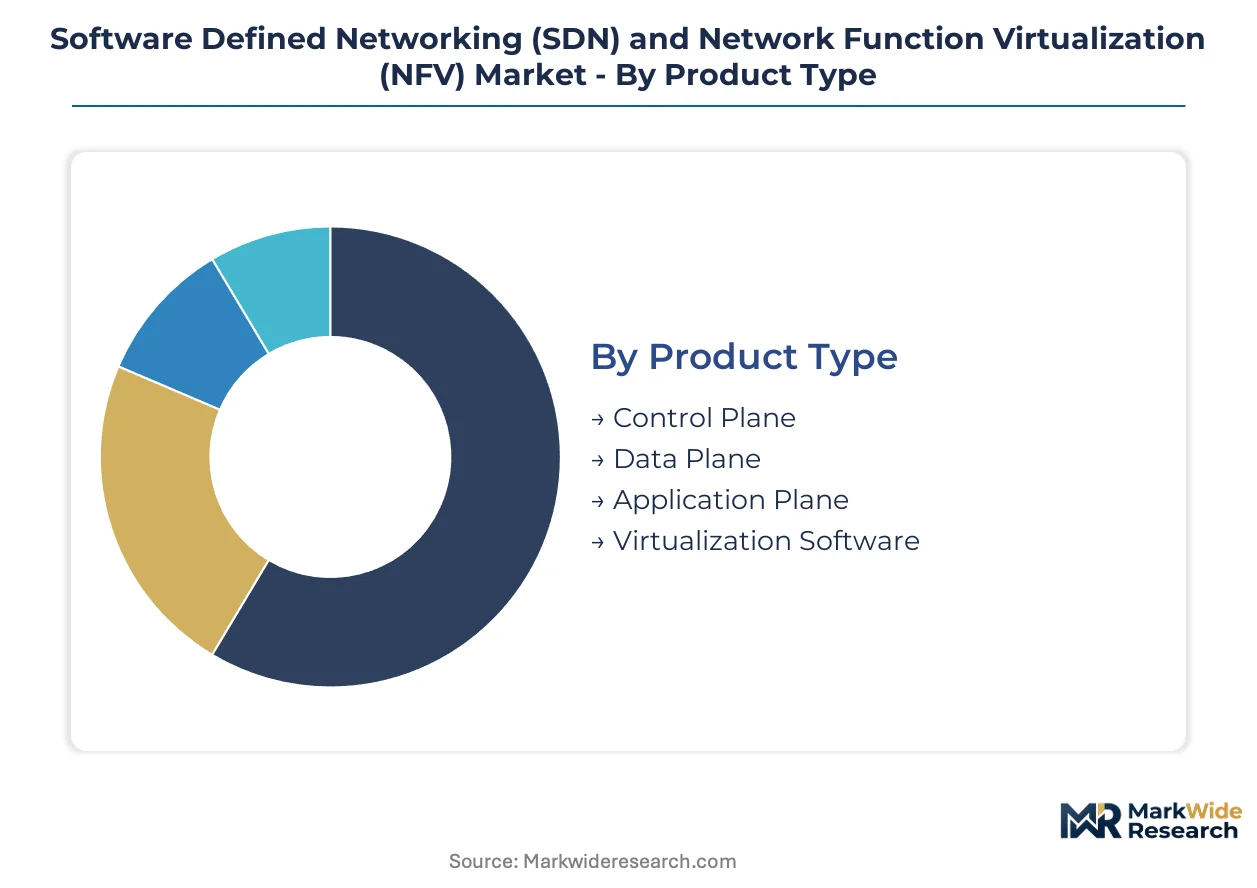
SDN and NFV segmentation reveals how control plane abstraction, deployment flexibility, and orchestration protocols create distinct value pools for telecom operators, cloud hyperscalers, and enterprise IT architects. Each dimension carries different margin structures, compliance burdens, and vendor lock-in risks that shape procurement strategies.
Product Type:
Use-case spectrum spans centralized policy engines, packet forwarding substrates, programmable service layers, and hypervisor-based abstraction stacks.
- Control Plane:Centralized controllers like ONOS and OpenDaylight abstract routing decisions from underlying silicon, enabling automated path computation across multi-vendor environments. Telecom operators in Germany and South Korea deploy these to compress provisioning cycles from weeks to minutes for 5G core virtualization. The dominant share belongs to Control Plane, while Application Plane is closing the gap fastest.
- Data Plane:Programmable forwarding elements execute match-action rules pushed by controllers, with merchant silicon from Broadcom and Intel displacing custom ASICs in cost-sensitive deployments. Cloud hyperscalers favor this segment for east-west traffic optimization within data center fabrics.
- Application Plane:Network-aware software services including load balancers, firewalls, and intrusion detection systems that consume controller APIs for dynamic policy adaptation.
- Virtualization Software:Hypervisors and container runtimes that abstract compute, storage, and networking resources into elastic pools for network function instantiation.
Control Plane commands premium pricing as the strategic bottleneck in telco cloud transformations, while Virtualization Software faces commoditization pressure from open-source alternatives.
Deployment Model:
Cost tier differentiation separates capital-intensive owned infrastructure from operational expenditure models with varying sovereignty and latency trade-offs.
- Hybrid Cloud:Bridges on-premises legacy gear with public cloud network overlays, enabling burst capacity and disaster recovery without full migration. Enterprises in regulated sectors favor this model to satisfy data-localization requirements while accessing elastic compute.
- Public Cloud:Amazon Web Services, Microsoft Azure, and Google Cloud deploy programmable networking fabrics across their data center footprints, offering SDN-as-a-service with consumption-based billing.
- Private Cloud:Dedicated infrastructure with single-tenant isolation, preferred by government agencies and financial institutions for classified or sensitive workloads.
- On-premises:Traditional owned-and-operated deployments retaining full hardware control, declining fastest as virtualization matures but persisting in latency-critical industrial applications.
Hybrid Cloud expansion outpaces other models as enterprises seek to preserve existing investments while capturing cloud agility.
End User:
Customer type determines solution complexity, with telecom providers demanding carrier-grade reliability and enterprises prioritizing rapid service instantiation.
- Telecom Providers:Tier-1 and Tier-2 carriers virtualizing mobile packet core, radio access networks, and subscriber management systems to reduce hardware dependency and accelerate service launches. India's TRAI data-localization directives are compelling domestic carriers toward compliant NFV infrastructure.
- Enterprises:Fortune 500 technology buyers displacing traditional resale channels with direct hyperscaler marketplaces and carrier-integrated service wraps for branch connectivity and data center interconnection.
- Government Agencies:Sovereign cloud deployments with embedded encryption, geographic fencing, and FedRAMP or equivalent certification requirements.
- Managed Service Providers:Underdeveloped channel where VMware NSX and Cisco ACI expertise commands premium implementation fees, representing resale avenue for vendors lacking direct enterprise relationships.
Telecom Providers anchor procurement volume, though Enterprises are gaining share fastest as cloud-native consumption models penetrate Fortune 500 accounts.
Technology:
Protocol and platform maturity creates divergent vendor ecosystems with varying degrees of standardization and proprietary extension.
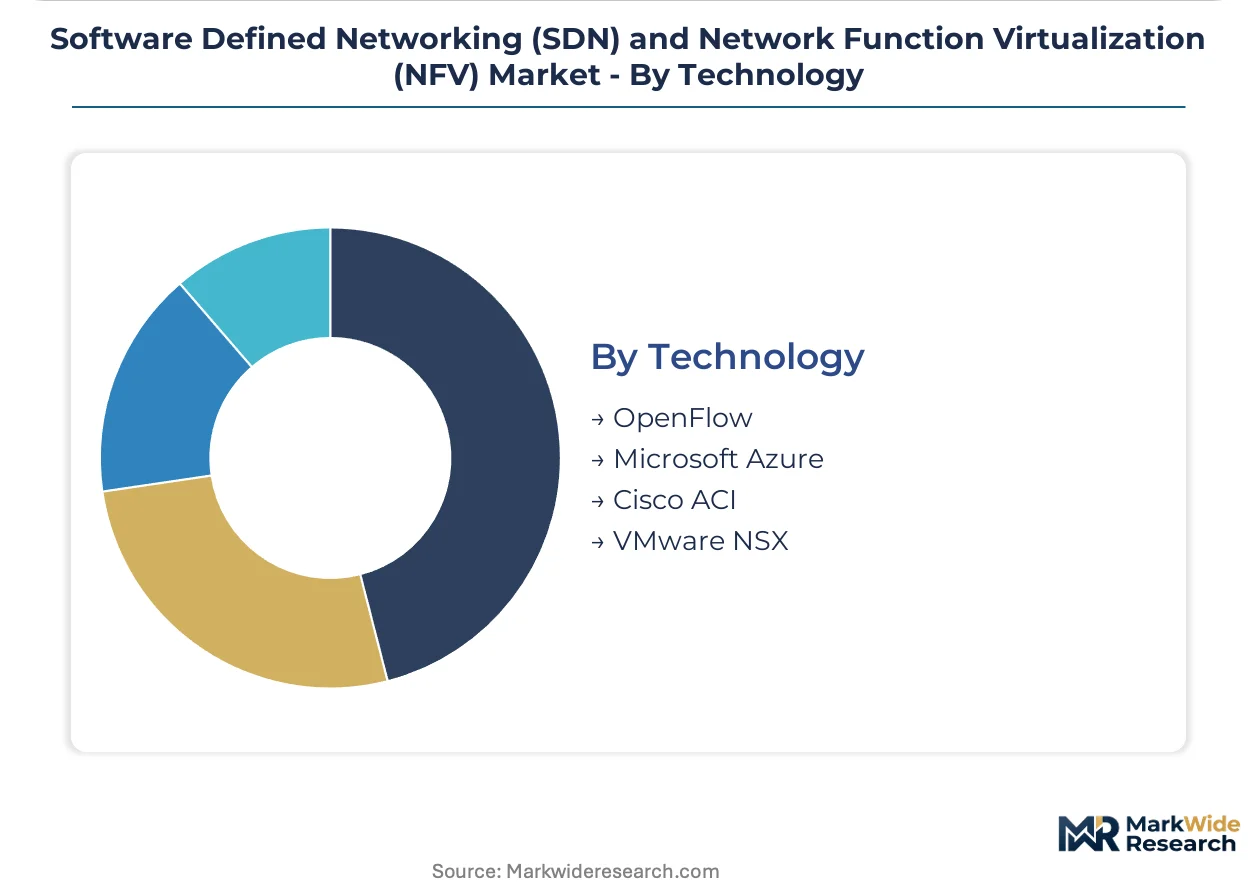
- OpenFlow:Open protocol specifications enabling direct manipulation of forwarding tables across multi-vendor switches, replacing manual CLI configuration with automated policy enforcement. ONOS and OpenDaylight adoption in cost-sensitive emerging markets accelerates disaggregation of routing software from proprietary silicon.
- VMware NSX:Network virtualization platform delivering micro-segmentation and overlay networking for multi-cloud environments, deeply integrated with vSphere and Tanzu container platforms.
- Cisco ACI:Policy-driven data center fabric with application-centric infrastructure, leveraging Cisco's installed base of routing hardware to push subscription-based controllers.
- Microsoft Azure:Native cloud networking services including Virtual WAN, ExpressRoute, and Azure Firewall, consumed through hyperscaler marketplaces with integrated billing.
OpenFlow maintains leadership in service provider disaggregation initiatives, while VMware NSX climbs fastest in enterprise multi-cloud deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where hyperscaler infrastructure buildouts absorb premium SDN controllers, while European operators face compliance-driven cost compression under GDPR and EU AI Act mandates.
United States
Cloud hyperscalers Amazon Web Services, Microsoft Azure, and Google Cloud drive programmable networking fabric deployment across data center footprints. FCC open internet rules and NIST cybersecurity frameworks mandate traceability and access controls that favor audited SDN platforms. Northern Virginia's data center corridor anchors east-west traffic optimization investments.
Germany
Deutsche Telekom and Vodafone Germany accelerate 5G core virtualization to compress provisioning cycles from weeks to minutes. ETSI NFV standards and EU GDPR data-localization requirements push operators toward sovereign cloud deployments with embedded compliance tooling. Munich and Frankfurt host Tier-1 carrier labs migrating packet core components to containerized architectures.
India
Domestic carriers deploy NFV infrastructure to satisfy TRAI data-localization directives with embedded encryption and geographic fencing. BIS certification requirements and the PLI scheme for telecom equipment manufacturing incentivize local assembly of virtualized network functions. Bengaluru and Hyderabad concentrate engineering talent for Kubernetes-orchestrated container networking.
South Korea
SK Telecom and KT Corporation synchronize containerized network functions with 5G MEC nodes for low-latency enterprise services. The Ministry of Science and ICT backs 5G network slicing investments that depend on software-defined control planes. Seoul's Digital Media City clusters vendors developing cloud-native network function microservices.
United Kingdom
BT Group and Vodafone UK dismantle hardware-centric architectures in favor of centralized policy enforcement engines. Post-Brexit regulatory divergence from EU frameworks creates uncertainty around data sovereignty requirements for virtualized subscriber databases. London's Tech City hosts managed service providers commanding premium fees for VMware NSX and Cisco ACI expertise.
Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying merchant silicon and orchestration modules. The vendor base stratifies across three tiers: legacy networking incumbents with installed hardware bases, cloud-native software vendors, and open-source control plane alternatives. Dominant competitive moves include backward integration into merchant silicon supply and strategic partnerships bridging legacy OSS/BSS with cloud-native orchestration APIs.
Within the platform integrator tier, Cisco Systems and Nokia exemplify divergent pathways—Cisco leverages its routing hardware installed base to push subscription-based controllers, while Nokia anchors through telecom-specific orchestration stacks. VMware occupies a position representing the cloud-native software archetype with its NSX network virtualization platform. Among emerging market specialists, Huawei Technologies exemplifies cost-driven deployment models where open-source control plane alternatives disaggregate routing software from proprietary silicon.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise |
| Nokia |
| Cisco Systems |
| Intel Corporation |
| IBM |
| VMware |
| Huawei Technologies |
| Arista Networks |
| Juniper Networks |
| Others |
Value Network & Pricing Analysis
Merchant silicon fabrication concentration in Taiwan and South Korea funnels margin capture toward coherent DSP suppliers, while orchestration software vendors downstream extract premium pricing from telecom operators seeking carrier-grade NFV certification.
Pricing Analysis
Configured-to-order SDN controllers command 40-60% premiums over standard subscription tiers due to ETSI NFV compliance testing requirements and embedded sovereign cloud tooling. Three-tier pricing structure across premium orchestration stacks, standard virtualization software, and open-source control plane alternatives stratifies the market by certification grade and after-sales support bundling. Cost compression in the standard tier intensifies because VMware NSX and Cisco ACI expertise scarcity allows managed service providers to capture implementation fees. Enterprise buyers show highest price sensitivity, while government agencies absorbing FedRAMP-certified deployments exhibit lowest elasticity.
Supply Chain Analysis
US Commerce Department export controls on advanced networking ASICs and coherent DSPs constrain flows to Chinese equipment vendors, fragmenting vendor procurement strategies. Supply draws from Taiwan for merchant silicon, South Korea for memory components, and the United States for specialized orchestration software. Single-source vulnerability concentrates in 400G/800G optical transport hardware where Broadcom and Intel dominate merchant silicon supply. Distribution runs through direct hyperscaler marketplaces and carrier-integrated service wraps, displacing traditional resale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SDN and NFV adoption sits in early-cycle expansion as containerized network function maturity synchronizes with 5G core virtualization timelines, compressing provisioning cycles from weeks to minutes for Tier-1 operators.
For Market Incumbents: Entrench position by backward integration into merchant silicon supply chains and captive development of Kubernetes-orchestrated container networking talent pools. Cisco Systems and Nokia must defend against open-source control plane alternatives by embedding compliance tooling directly into orchestration stacks, neutralizing the cost advantage of ONOS and OpenDaylight deployments in emerging markets. For New Entrants and Emerging Players: Build out managed SD-WAN expertise to capture premium implementation fees from service providers lacking in-house VMware NSX or Cisco ACI capabilities. India's TRAI data-localization directives create the most penetrable geography, where domestic carriers require compliant NFV infrastructure with embedded encryption and geographic fencing. Partner with systems integrators possessing existing Fortune 500 relationships to bypass direct enterprise sales cycles. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native network function specialists with proven ETSI NFV Release 4 certification pathways and sovereign cloud deployment track records. Long-term viability over the next decade hinges on orchestration software becoming the strategic bottleneck in telco cloud transformations. Monitor 3GPP release timeline synchronization with containerized network function maturity as the inflection signal for infrastructure refresh cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| ETSI NFV Compliance Certification | Deutsche Telekom and Vodafone Germany mandate this for 5G core vendor selection, compressing procurement cycles. |
| Kubernetes-Orchestrated Container Networking | SK Telecom and KT Corporation deploy this architecture to synchronize network functions with 5G MEC nodes. |
| Sovereign Cloud Tooling Integration | European operators embed this to satisfy EU GDPR data-localization and EU AI Act audit trail requirements. |
| Merchant Silicon Supply Agreement | Cloud hyperscalers secure this to optimize east-west traffic within Northern Virginia data center corridors. |
| Managed SD-WAN Channel Partnership | Service providers lacking Cisco ACI expertise capture premium fees through this resale avenue. |
Research Methodology
Cross-validation between primary interviews with network architects, telco cloud transformation officers, and hyperscaler infrastructure planners anchors the qualitative findings against secondary validation from SEC filings, ETSI NFV specification documents, hyperscaler capex disclosures, and TRAI regulatory circulars. Bottom-up sizing of control plane, data plane, and virtualization software segments triangulates with top-down cross-checks against carrier-reported virtualization spend and enterprise SD-WAN procurement data.
Calibration against historical adoption curves for MPLS-to-SDN migration and VM-to-container transitions shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, deployment model, end user, and technology protocol maturity, with regional regulatory cluster as the industry-specific overlay. CAGRs derive from elasticity-adjusted penetration rates and infrastructure refresh cycle timing, incorporating 3GPP release synchronization and containerized network function commercial availability as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by open-source control plane consortia or Chinese equipment vendors circumventing export controls would shift outcomes. Material shifts in FCC open internet traceability requirements, ETSI NFV certification timelines, or TRAI data-localization enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
China Data Center Networking Market
Data Center and Networking
5G Edge Cloud Network and Services Market
Data Center and Networking
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market
Data Center and Networking
Virtual Networking Market
Data Center and Networking
Ethernet Transceivers Market
Data Center and Networking
Network Slicing Market
Data Center and Networking
Service Provider Router Market
Data Center and Networking
South America Data Center Networking Market
Data Center and Networking
Ireland Data Center Networking Market
Data Center and Networking
Global Data Lakes Market
Data Center and Networking
Enterprise Network Infrastructure Market
Data Center and Networking
Singapore Data Center Networking Market
Data Center and Networking
Nosql Market
Data Center and Networking
Sweden Data Center Networking Market
Data Center and Networking
Saudi Arabia Data Center Networking Market
Data Center and Networking
Middle East Data Center Server Market