
 Dedicated Internet Access Market | 2026-2036
Dedicated Internet Access Market Size, Share, and Industry Trends Forecast 2026-2036
Dedicated Internet Access Market Outlook
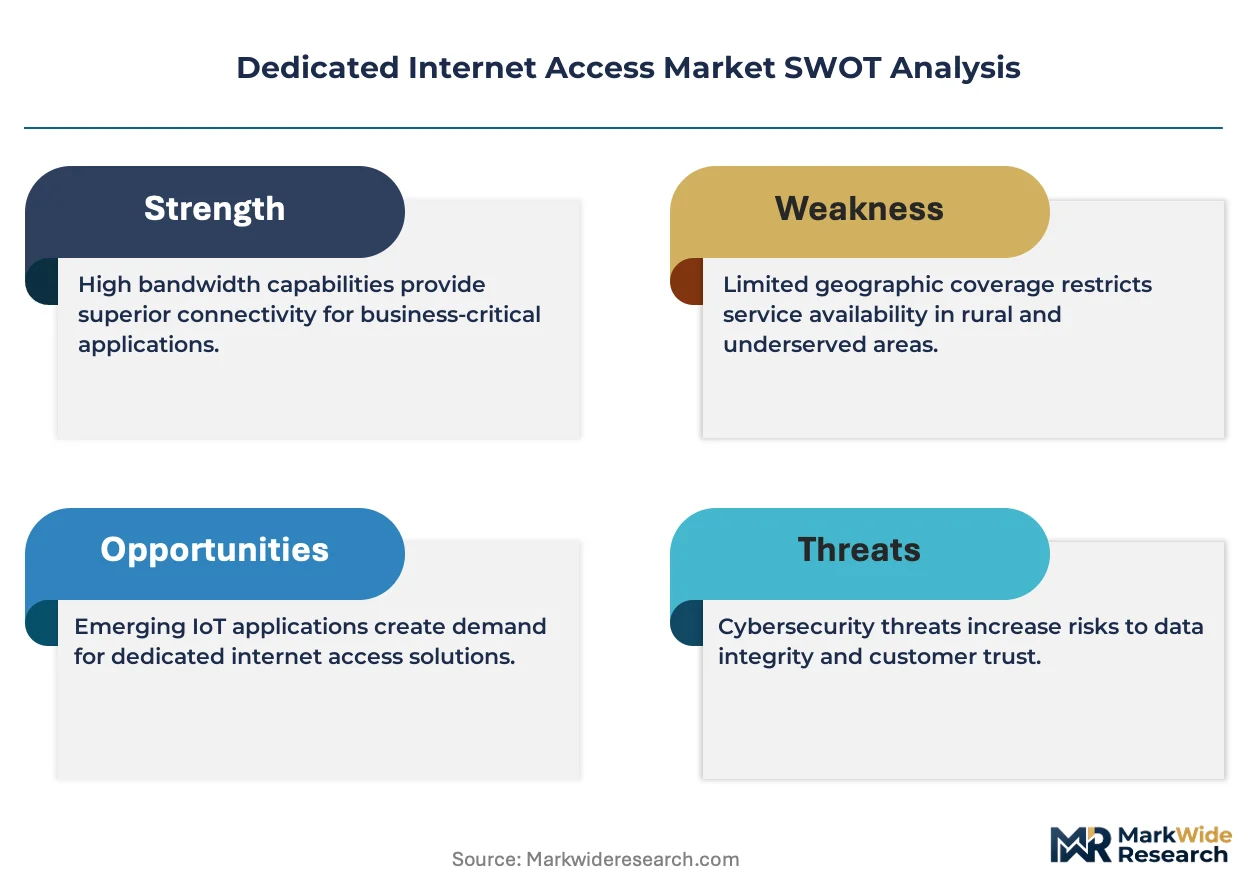
Software-defined WAN orchestration is pivoting how carriers bundle Dedicated Internet Access with managed security and application-aware routing. AT&T Inc. leverages its fiber depth and FirstNet spectrum position to anchor government and public safety contracts. Lumen Technologies, Inc. specializes in low-latency routes linking financial exchanges across North America and Europe. Zayo Group Holdings, Inc. controls one of the densest dark fiber footprints, allowing custom wavelength and dedicated access configurations that competitors struggle to replicate.
Dedicated Internet Access denotes a symmetric, uncontended connectivity service with guaranteed bandwidth, service-level agreements defining latency and uptime, and static IP addressing for mission-critical operations. Fiber deployments achieve sub-10 millisecond latency within metro rings, supporting high-frequency trading, telemedicine imaging, and real-time manufacturing control systems. Ethernet service types now dominate new enterprise installations due to simpler provisioning and native cloud interconnection compatibility. Wireless technology segments gain traction in remote mining and energy extraction sites where trenching fiber remains economically prohibitive. Hybrid deployment models concentrate margin pools as customers retain on-premises security appliances while bursting compute workloads into cloud regions.
The FCC governs business data service pricing and infrastructure access in the United States, while Ofcom regulates wholesale leased line markets in the United Kingdom, and Germany's Bundesnetzagentur enforces symmetric connectivity mandates for critical infrastructure operators. These frameworks determine whether competitive carriers can lease incumbent fiber at regulated rates, directly shaping market entry costs and end-user pricing tiers. Stakeholders must monitor spectrum auction outcomes and open access fiber mandates as wireless and alternative last-mile technologies threaten to displace traditional copper and fiber dedicated circuits in secondary markets.
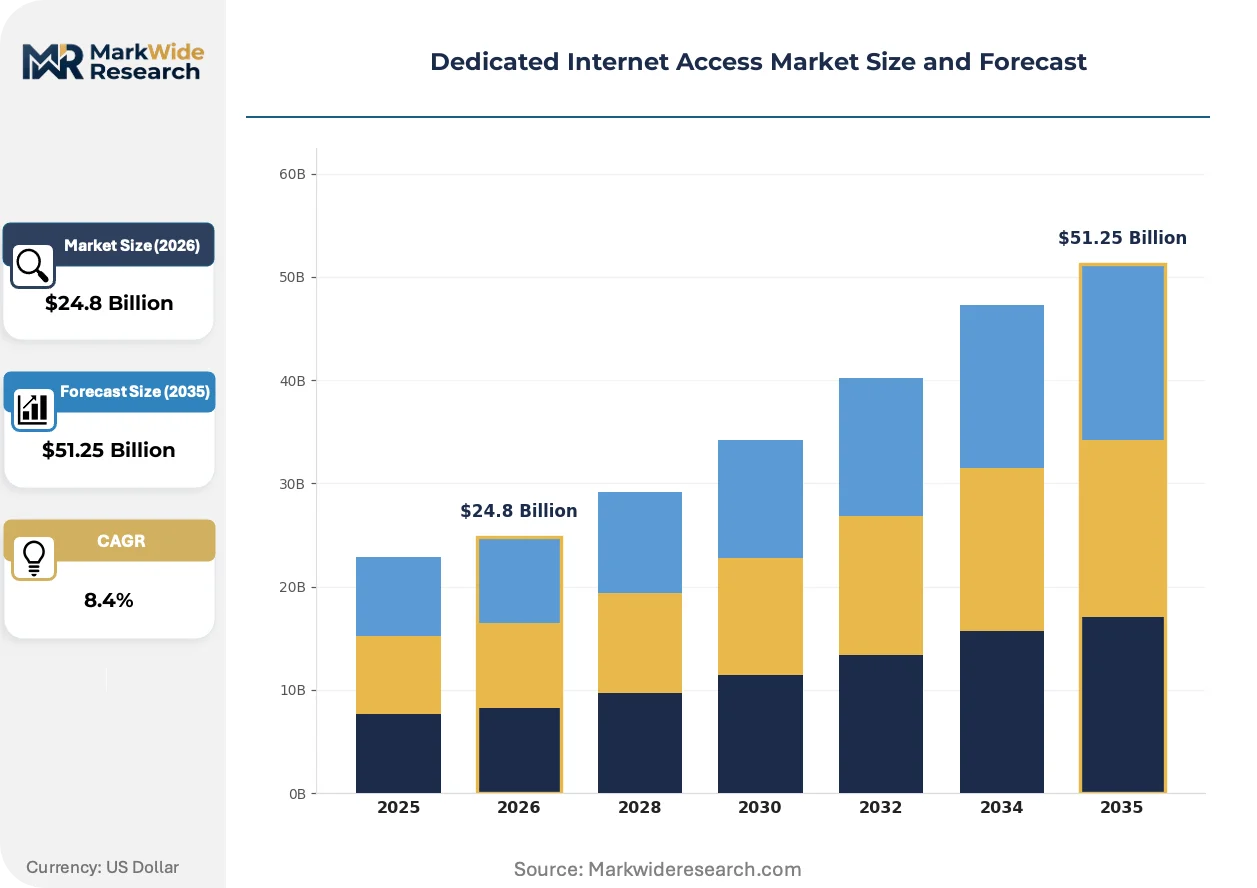
Market Dynamics
Software-defined orchestration is compressing provisioning cycles from weeks to hours, forcing carriers to restructure service bundles around programmable bandwidth rather than static circuit contracts. This shift rewards fiber-dense operators with API-ready infrastructure while marginalizing legacy copper-dependent providers.
Growth Catalysts
- FCC Business Data Service Reforms:Competitive carriers in the United States gain regulated access to incumbent fiber at wholesale rates, lowering market entry barriers for alternative providers serving enterprise clusters.
- Industrial Automation Demand:Manufacturing control systems in Germany's Ruhr Valley and Bavaria require symmetric sub-10 millisecond connectivity, pulling dedicated fiber deeper into plant floor environments.
- Cloud Trading Infrastructure Migration:Financial services firms are relocating matching engines and co-location facilities to hyperscale cloud regions, demanding uncontended low-latency pipes with guaranteed jitter specifications.
Market Restraints
- Fiber Trenching Economics:Remote mining and energy extraction sites face capital-intensive last-mile construction where bedrock terrain and permit timelines stretch deployment schedules.
- Incumbent Last-Mile Concentration:Local exchange carriers in secondary U.S. markets retain control over conduit and pole attachment rights, constraining competitive overbuild economics.
- Copper Network Sunset Complexity:Enterprises with embedded T1 and DS3 circuits encounter forced migration timelines as carriers depreciate legacy switching equipment.
Strategic Opportunities
- Wireless Backhaul Expansion:Fixed wireless access using millimeter-wave spectrum offers dedicated-equivalent performance for industrial parks in Poland and Czech Republic where fiber lateral builds remain uneconomic.
- Managed Security Bundling:Carriers can capture margin pools by integrating SASE stacks with raw bandwidth, addressing enterprise demand for converged network and security policy enforcement.
- Ofcom's Dark Fiber Consultation:Proposed open-access mandates in the United Kingdom would force infrastructure unbundling, creating wholesale arbitrage positions for agile service providers.
Industry Challenges
- Fiber Splicing Technician Scarcity:Deployment velocity constraints emerge as specialized fusion splicing and OTDR certification skills concentrate with aging union workforces in Midwestern U.S. states.
- Multi-Cloud Interconnection Complexity:Enterprises struggle to maintain consistent policy frameworks across AWS Direct Connect, Azure ExpressRoute, and Google Cloud Interconnect circuits with differing SLA structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dedicated Internet Access Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Leased Line, Ethernet, MPLS, Fiber Optic End User: Enterprises, Educational Institutions, Government, Healthcare Facilities Deployment: On-Premises, Cloud, Hybrid, Remote Technology: DSL, Fiber, Satellite, Wireless |
| Companies Covered | Lumen Technologies, Inc., BT Group plc, AT&T Inc., Zayo Group Holdings, Inc., NTT Communications Corporation, Verizon Communications Inc., Charter Communications, Inc., Cox Communications, Inc., Comcast Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dedicated Internet Access Market Strategic Shifts
Programmable infrastructure is dissolving the boundary between transport and compute, enabling carriers to sell latency-tiered connectivity as a metered utility rather than a fixed pipe commitment.
Network function virtualization is converging with dedicated access circuits, allowing enterprises to instantiate virtual CPE and security functions at carrier edge nodes without on-premises hardware. Manufacturing and healthcare buyers in the United States and Germany are piloting these deployments to compress branch office footprints. This convergence is collapsing the traditional demarcation between WAN transport and premises equipment markets.
The FCC's Infrastructure Investment and Jobs Act implementation is mandating broadband labeling standards that expose hidden fees and actual throughput metrics to business buyers. Carrier pricing transparency is accelerating procurement cycle compression as enterprises benchmark competing quotes against standardized disclosure templates. Financial services and government verticals in the United States are leveraging these disclosures to renegotiate multi-year contracts.
Consumption-based billing models are displacing traditional term commitments with minimum revenue guarantees, aligning carrier incentives with actual traffic growth rather than port reservation. Channel partners and systems integrators are capturing advisory roles as enterprises navigate burst pricing and commit-tier optimization. This behavioral shift is most pronounced among SaaS-dependent mid-market firms in the United Kingdom and Netherlands seeking to align connectivity costs with cloud spend patterns.
Dedicated Internet Access Market Segmentation
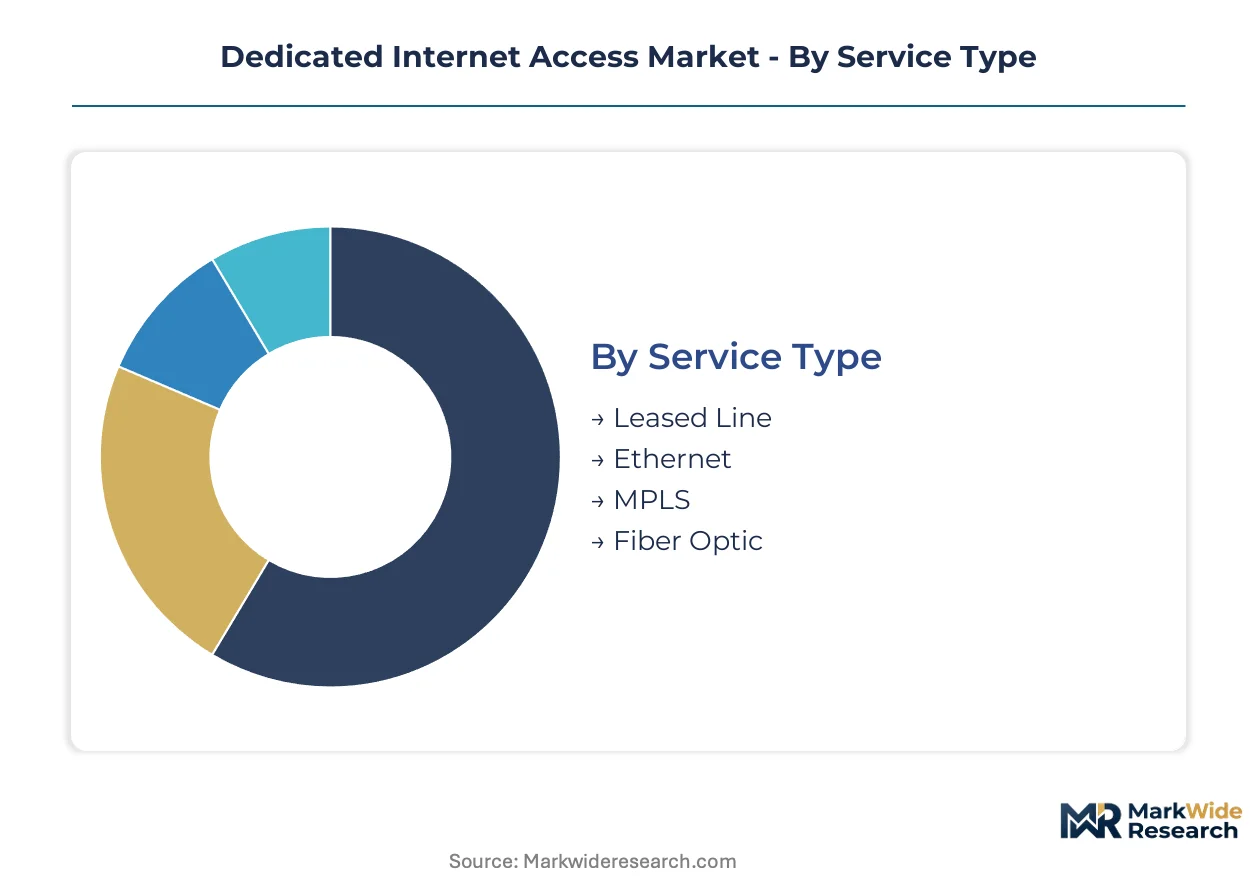
Dedicated Internet Access procurement decisions hinge on matching latency requirements, security postures, and workload distribution models to specific service architectures. Segmentation reveals where carriers capture premium pricing versus commodity volume plays.
Service Type:
Standalone dedicated circuits dominate mission-critical installations, while Ethernet-over-fiber bundles increasingly embed within broader managed service portfolios.
- Leased Line:Traditional copper or fiber TDM circuits deliver symmetric bandwidth with legally enforceable SLAs. Financial exchanges in Frankfurt and Chicago maintain these for regulatory audit trails despite higher per-megabit costs.
- Ethernet:Native packet-based provisioning enables rapid cloud interconnection through standardized handoffs. Enterprise demand concentrates in London and Amsterdam where multi-cloud architectures require consistent Layer 2 connectivity into AWS, Azure, and Google Cloud regions.
- MPLS:Label-switched paths prioritize traffic engineering for multi-site corporations with legacy QoS requirements. Manufacturing conglomerates along Germany's Rhine-Ruhr corridor retain these for brownfield plant networks.
- Fiber Optic:Dark fiber and lit wavelength services offer maximum control over routing and latency. High-frequency trading firms lease specific fiber pairs between matching engines to guarantee microsecond-level path consistency.
Volume placements concentrate in Ethernet; the faster expansion belongs to Fiber Optic.
End User:
Customer-type segmentation exposes divergent buying behaviors across procurement sophistication and compliance burden.
- Enterprises:Multinational corporations negotiate global master service agreements with committed volume tiers. Technology and financial services verticals in the United States drive demand for API-driven bandwidth scaling.
- Educational Institutions:Universities and research consortia require high-capacity pipes for distributed computing and massive dataset transfer. CERN and national laboratory networks in Switzerland and France anchor procurement clusters.
- Government:Public sector contracts mandate certified secure facilities and cleared personnel for installation. FirstNet deployments in the United States specify dedicated fiber with priority routing for emergency services.
- Healthcare Facilities:Hospital systems and diagnostic imaging centers need uncontended bandwidth for telemedicine and picture archiving systems. Germany's university hospital networks enforce symmetric connectivity for real-time surgical consultation.
Government contracts deliver the most stable revenue streams; healthcare is climbing the fastest as telemedicine infrastructure mandates expand.
Deployment:
Architecture choices reflect enterprise cloud maturity and data sovereignty requirements.
- On-Premises:Traditional demarcation at customer premises with owned CPE and security appliances. Defense contractors and classified facilities in the United States mandate this for air-gapped operational technology networks.
- Cloud:Direct connectivity into hyperscale regions bypassing public internet exchange points. SaaS-dependent firms in the Netherlands and Ireland prioritize these for latency-sensitive application delivery.
- Hybrid:Split traffic engineering retaining sensitive workloads on-premises while bursting to cloud. German automotive manufacturers favor this for protecting proprietary design data while leveraging cloud simulation.
- Remote:Satellite and fixed wireless solutions serving extraction sites and maritime platforms. North Sea oil installations and Australian mining camps drive specialized procurement.
Hybrid architectures capture the largest deployment share; cloud-native connectivity is expanding most quickly.
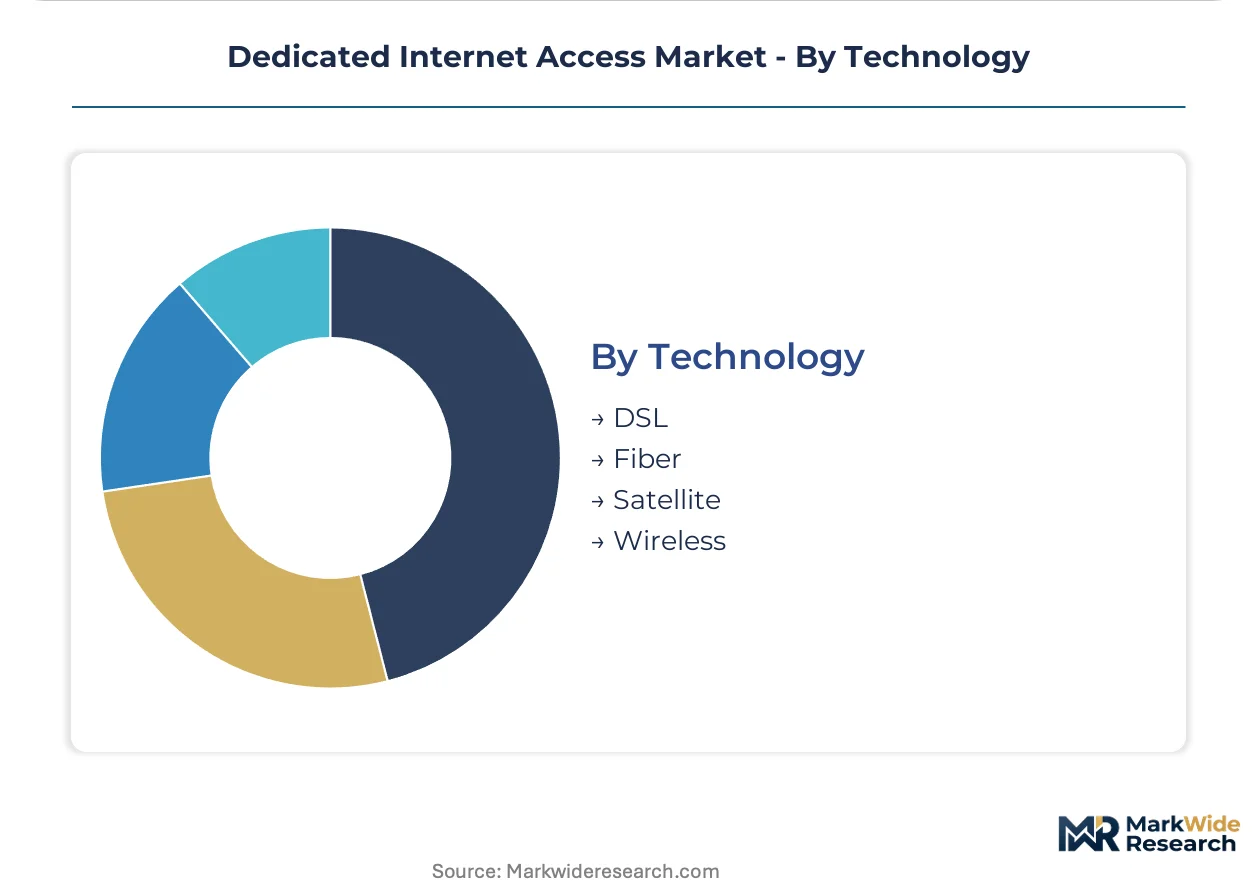
Technology:
Physical layer selection determines reach, latency floor, and total cost of ownership across geographic constraints.
- DSL:Copper-based symmetric services over existing telephone infrastructure. Small and medium enterprises in secondary UK markets retain these where fiber overbuild remains uneconomic.
- Fiber:Single-mode and multimode deployments achieving sub-millisecond latency within metro rings. Dense urban corridors in Tokyo, Singapore, and New York anchor global fiber concentration.
- Satellite:Geostationary and low-earth orbit constellations serving mobility and extreme remote applications. Maritime shipping lanes and polar research stations constitute primary demand nodes.
- Wireless:Millimeter-wave and sub-6GHz fixed wireless for rapid industrial park deployment. Polish and Czech manufacturing zones adopt these to circumvent fiber trenching delays.
Fiber commands the dominant technology share; wireless is gaining share fastest as spectrum allocation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt anchors the world's densest concentration of dedicated internet access infrastructure, hosting matching engines for Eurex and Deutsche Börse that demand sub-10 millisecond latency. The city's fiber density and regulatory environment for financial services connectivity establish the benchmark for symmetric uncontended service deployment.
United States
Financial services firms in Chicago and New York drive demand for low-latency routes between exchanges and cloud regions. The FCC's business data service reforms grant competitive carriers regulated wholesale access to incumbent fiber, lowering entry barriers in enterprise clusters. Chicago's Aurora data center corridor concentrates matching engine co-location facilities requiring dedicated wavelength services.
Germany
Industrial automation clusters in the Ruhr Valley and Bavaria mandate symmetric connectivity for real-time manufacturing control systems. The Bundesnetzagentur enforces strict latency and uptime standards for critical infrastructure operators. Munich's automotive technology corridor hosts BMW and Siemens facilities deploying dedicated fiber for digital twin simulations.
United Kingdom
London's financial district generates concentrated demand for Ethernet services into AWS, Azure, and Google Cloud regions. Ofcom regulates wholesale leased line markets and consults on dark fiber unbundling mandates. The Docklands area maintains one of Europe's densest concentrations of trading infrastructure requiring uncontended circuits.
Japan
Tokyo's financial technology sector and Osaka's manufacturing hubs require dedicated access for high-frequency trading and industrial IoT applications. METI promotes fiber deployment standards for smart factory connectivity. The Tokyo-Osaka fiber corridor serves as the primary low-latency route for domestic financial data transmission.
Singapore
Maritime shipping lanes and regional headquarters operations generate demand for satellite-backup dedicated circuits with guaranteed availability. The Infocomm Media Development Authority licenses submarine cable landing stations and promotes data center interconnectivity standards. The Jurong industrial estate concentrates petrochemical and precision manufacturing facilities requiring redundant fiber access.
Dedicated Internet Access Market Competitive Environment
Capital-heavy fiber infrastructure owners compete with asset-light service integrators for enterprise connectivity contracts. The market structure concentrates around tier-one carriers with dense metro fiber footprints and national-scale alternative providers with specialized route control. Three archetypes dominate: incumbent telecommunications operators with legacy copper and fiber plant, pure-play fiber infrastructure specialists with dark fiber assets, and cable operators leveraging hybrid fiber-coaxial upgrades. Competitive dynamics center on M&A activity to acquire fiber density and strategic partnerships with hyperscale cloud providers for direct interconnection.
Among infrastructure-heavy operators, Lumen Technologies, Inc., Zayo Group Holdings, Inc., and AT&T Inc. exemplify contrasting strategic positions. Lumen occupies the low-latency specialist archetype with controlled routes linking financial exchanges. Zayo represents the fiber-density aggregator model through extensive dark fiber holdings enabling custom wavelength configurations. AT&T anchors the integrated incumbent position combining wireless spectrum, fiber depth, and government contract relationships. Each structure reflects different capital allocation priorities between organic buildouts and acquisition-led expansion.
| Leading Market Players |
|---|
| Lumen Technologies, Inc. |
| BT Group plc |
| AT&T Inc. |
| Zayo Group Holdings, Inc. |
| NTT Communications Corporation |
| Verizon Communications Inc. |
| Charter Communications, Inc. |
| Cox Communications, Inc. |
| Comcast Corporation |
| Others |
Value Chain & Pricing Dynamics
Software-defined orchestration compresses provisioning cycles from weeks to hours, simultaneously collapsing cost structures for fiber-dense operators while marginalizing legacy copper-dependent providers who cannot match API-ready infrastructure economics. This production-method transition concentrates pricing power with carriers owning programmable metro rings and dark fiber assets, forcing commodity circuit vendors toward managed service bundling to defend margin pools.
Pricing Analysis
Latency-tiered service guarantees anchor value-based pricing, with financial exchanges in Frankfurt and Chicago paying premiums for sub-10 millisecond symmetric connectivity with enforceable uptime SLAs. Three-tier pricing structure across premium wavelength services, standard Ethernet bundles, and economy copper circuits reflects differentiation by certification grade and geographic fiber density. Pricing pressure stems from competitive wholesale access reforms enabling alternative carriers to lease incumbent fiber at regulated rates. Mid-market enterprises in secondary U.S. markets exhibit highest price sensitivity, while government and financial services verticals prioritize uptime guarantees over per-megabit cost.
Supply Chain Analysis
Dual-sourcing requirements from hyperscale cloud providers and defense contractors mandate multi-supplier qualification for fiber optic cable, optical transceivers, and fusion splicing equipment. Supply concentrates in the United States, Germany, and Japan for specialized single-mode fiber and precision optical components. Raw material dependencies span high-purity silica glass, rare-earth doping elements for amplifiers, and indium phosphide for high-speed transceivers. Single-source vulnerability in specialized fusion splicing technician certification constrains deployment velocity. Distribution runs through carrier-direct procurement for lit services and dark fiber leasing, with systems integrators capturing advisory roles in hybrid deployment configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dedicated Internet Access Market is becoming a vertical-integration race as carriers pursue backward integration into dark fiber ownership and submarine cable landing rights to escape regulated wholesale pricing tiers.
For Market Incumbents: Cement fiber density advantages through strategic acquisitions of metro dark fiber rings in Chicago, Frankfurt, and London financial corridors. Prioritize API-ready orchestration platforms that expose programmable bandwidth to enterprise procurement systems, defending against asset-light service integrators capturing mid-market share through SASE bundling.
For New Entrants and Emerging Players: Begin with fixed wireless access deployments in Polish and Czech industrial parks where fiber trenching economics remain prohibitive. Target manufacturing automation clusters requiring symmetric connectivity with rapid deployment timelines that incumbent carriers cannot match. Pursue direct interconnection partnerships with hyperscale cloud regions as the primary go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in infrastructure rollup transactions as private equity consolidates fragmented metro fiber assets. Long-term viability hinges on securing routes with irreplaceable latency characteristics linking financial exchanges. The signal to watch is spectrum auction outcomes for millimeter-wave bands that could displace dedicated fiber in secondary markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Dark Fiber Acquisition | Secures irreplaceable low-latency routes between Eurex and Deutsche Börse matching engines. |
| API-First Orchestration Platform | Enables enterprise self-service bandwidth scaling that compresses provisioning cycles to hours. |
| SASE Stack Integration | Captures security policy enforcement margins alongside raw connectivity in hybrid deployments. |
| Cloud Interconnection Partnership | Establishes direct on-ramps into AWS, Azure, and Google Cloud regions for latency-sensitive workloads. |
| Fixed Wireless Spectrum Positioning | Creates dedicated-equivalent performance for industrial parks where fiber trenching remains uneconomic. |
Study Parameters
Independent corroboration across carrier network planning executives, enterprise IT procurement officers, and fiber infrastructure asset managers underwrites the qualitative findings in this study. Primary fieldwork encompassed interviews with hyperscale cloud interconnection specialists, financial services technology leads, and regulatory affairs directors at competitive carriers. Secondary validation drew from FCC business data service filings, Ofcom wholesale market reviews, Bundesnetzagentur infrastructure mandates, and SEC disclosures from publicly traded fiber operators. Bottom-up deployment tracking across metro fiber rings triangulates against top-down carrier revenue segmentation.
Rate-of-change decomposition across the projection horizon segments volume and value by service architecture, deployment model, and end-user vertical. The analytical framework models Ethernet, MPLS, fiber optic wavelength, and leased line service types alongside on-premises, cloud, hybrid, and remote deployment configurations. CAGRs derive from carrier capex trajectory analysis, cloud region expansion timelines, and industrial automation connectivity mandates. Forecast inputs include FCC infrastructure investment disbursement schedules and European Commission digital sovereignty funding allocations.
Spectrum reallocation decisions, submarine cable landing license delays, and fiber splicing technician labor pool constraints are the dominant revision risks. Forecasts reflect assumptions regarding wholesale access pricing stability and hyperscale cloud region buildout cadence. Deviation in millimeter-wave spectrum allocation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Data Center Servers Market
Data Center and Networking
United Kingdom Data Center Networking Market
Data Center and Networking
Network Connectivity Tester Market
Data Center and Networking
Denmark Data Center Networking Market
Data Center and Networking
Mobile Data Market
Data Center and Networking
Wide Area Network Optimization Market
Data Center and Networking
Network Virtualization Software Market
Data Center and Networking
Global Cloud Content Delivery Network Market
Data Center and Networking
Enterprise Network Infrastructure Market
Data Center and Networking
Ireland Data Center Networking Market
Data Center and Networking
Global Content Delivery Network (CDN) Software Market
Data Center and Networking
Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market
Data Center and Networking
Automotive Data Management Market
Data Center and Networking
Broadband Network Gateway Market
Data Center and Networking
Global Mobile Content Delivery Network Market
Data Center and Networking
Europe Data Center Networking Market