
 Telematics in Automotive Market | 2026-2036
Telematics in Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Telematics in Automotive Market Insights
Automotive-grade connectivity certification is unwinding legacy aftermarket telematics into integrated OEM platforms. Robert Bosch GmbH leverages its sensor-to-cloud vertical stack to dominate embedded control unit supply. Continental AG anchors European production with manufacturing scale across multiple assembly corridors. Qualcomm Technologies, Inc. competes on chipset integration, extending its position into automotive 5G modems.
Telematics in Automotive denotes the integrated use of GPS, cellular, and onboard diagnostics hardware to transmit vehicle location, performance, and driver behavior data to remote servers for fleet optimization, insurance risk scoring, and predictive maintenance. The system architecture typically requires CAN bus integration, OBD-II port compatibility, and sub-100ms latency for real-time alerts. Fleet Management applications lead installed base volume, while Insurance Telematics represents the fastest-growing margin pool as usage-based pricing models penetrate commercial auto lines. OEMs capture the highest value per unit through embedded factory installations, whereas Aftermarket Providers compete on retrofit speed and multi-brand compatibility.
The National Highway Traffic Safety Administration shapes US market access through crash notification mandates and cybersecurity guidelines for connected vehicles. The European Commission's GDPR and EU AI Act constrain how driver behavior data is stored, processed, and monetized across member states. China's MIIT enforces GB standards for vehicle-network security, creating separate certification pathways for foreign suppliers. Stakeholders must decide whether to pursue platform consolidation or maintain modular interoperability as regulatory fragmentation deepens.
Market Dynamics
OEM embedded telematics platforms are displacing aftermarket hardware as vehicle-network security mandates harden CAN bus access requirements and factory-installed modems achieve price parity with retrofit units.
Growth Catalysts
- Fleet electrification mandates:California's Advanced Clean Trucks regulation and the EU's CO2 standards for heavy-duty vehicles are compelling logistics operators to deploy battery-electric fleets with integrated energy monitoring and route optimization systems.
- Cellular-V2X spectrum allocation:The FCC's 5.9 GHz band reconfiguration and corresponding EU harmonization are accelerating chipset refresh cycles that embed dual-mode 4G/5G connectivity as standard.
- Usage-based insurance penetration:Commercial auto underwriters in Germany and the United Kingdom are pricing driver behavior data into risk models, pulling telematics adoption through premium incentives rather than hardware subsidies.
Market Restraints
- Semiconductor supply concentration:Automotive-grade modem SoC fabrication concentrates at TSMC and Samsung foundries, creating 26-40 week lead time volatility for control unit suppliers.
- GDPR data localization:The European Commission's cross-border data transfer restrictions impose redundant server infrastructure costs on fleet operators running multi-country routes.
- Legacy fleet replacement inertia:Small commercial fleets with 8-15 year vehicle replacement cycles delay telematics adoption until natural turnover occurs.
Strategic Opportunities
- Predictive maintenance convergence:Integration of tire pressure, brake wear, and battery health sensors into unified diagnostic streams opens subscription revenue pools for component suppliers.
- India's PLI scheme for automotive electronics:The production-linked incentive framework is attracting module assembly investments that could serve domestic commercial vehicle demand and export markets.
- China's MIIT cybersecurity certification:Foreign suppliers completing GB standard compliance gain access to the world's largest connected vehicle deployment pipeline through joint venture partnerships.
Industry Challenges
- Embedded software talent scarcity:Functional safety engineering for ISO 26262-compliant telematics stacks commands 40% salary premiums over consumer IoT roles, constraining supplier scaling.
- Multi-protocol integration complexity:Fleet operators demand seamless data handoff between OEM embedded systems, aftermarket devices, and third-party fleet management platforms.
- Homologation timeline compression:The EU AI Act's risk classification for driver monitoring systems extends type-approval cycles by 8-14 months for computer vision-enabled cabin analytics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telematics in Automotive Market |
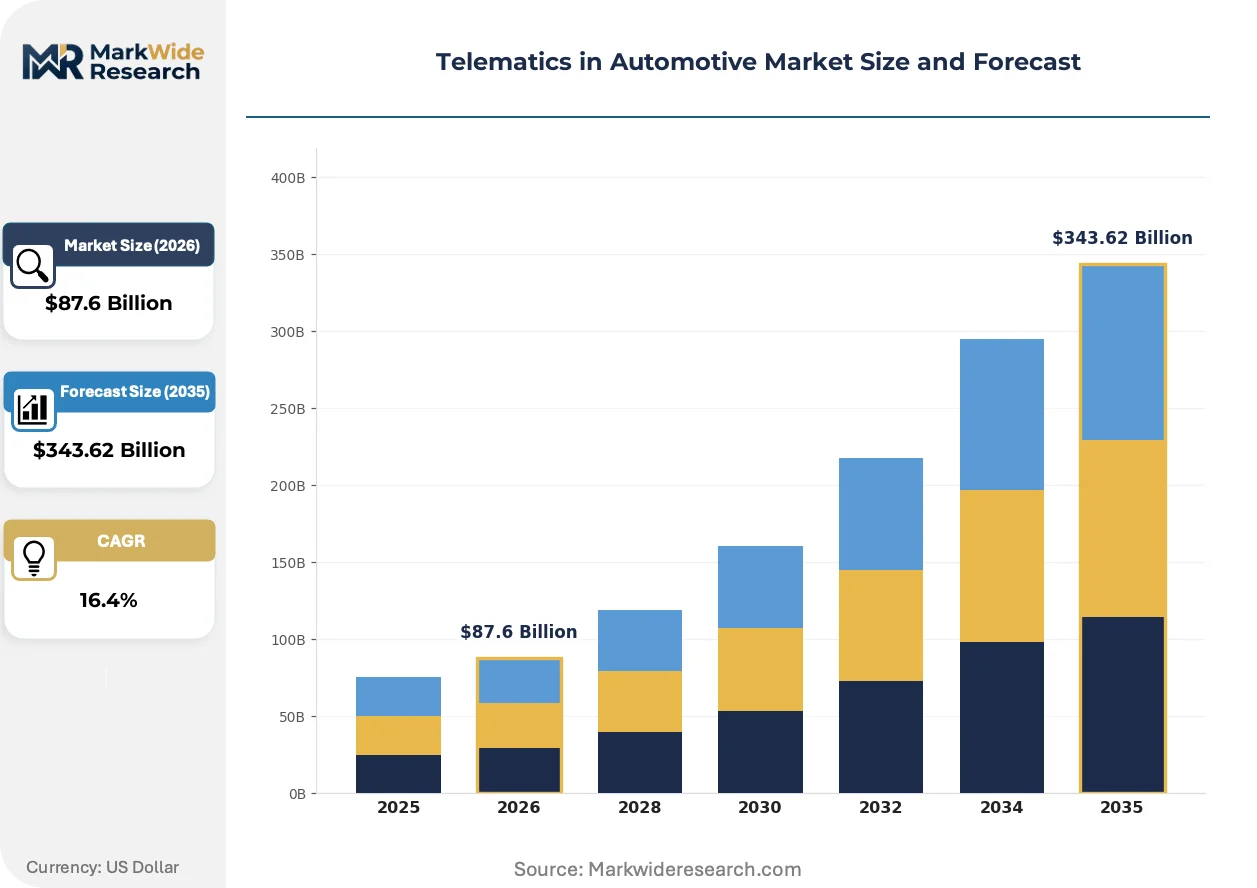
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $343.62 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, GSM, RFID, Wi-Fi Application: Fleet Management, Insurance Telematics, Navigation, Vehicle Diagnostics End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Logistics Companies Feature: Real-time Tracking, Vehicle Monitoring, Driver Behavior Analysis, Emergency Assistance |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, LG Electronics, HARMAN International, Verizon Connect, Geotab, Trimble Inc., Qualcomm Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telematics in Automotive Market Trends and Innovations
Edge computing architectures and AI inference on vehicle gateways are redistributing data processing loads between onboard systems and cloud platforms, altering hardware specifications and supplier value capture.
Automotive 5G modems with integrated C-V2X stacks are bifurcating the connectivity hardware market. Premium passenger vehicles and heavy-duty trucks adopt dual-SIM redundant architectures for mission-critical applications. Mid-market segments retain 4G fallback to contain bill-of-materials costs. This split is compressing single-mode modem supplier margins while rewarding chipset vendors with software-defined radio capabilities.
The EU AI Act's prohibited-practice rules for biometric identification in vehicles are forcing cabin monitoring system redesigns. Manufacturers must deploy gaze-tracking and drowsiness detection without facial recognition data retention. German luxury OEMs are responding with on-device inference architectures that process video streams locally and transmit only anonymized alert flags.
Commercial fleet buyers are consolidating vendor relationships around full-stack providers capable of hardware, connectivity, and analytics subscriptions. Single-point solution vendors lose procurement access at fleets above 500 vehicles. This concentration is most visible in North American long-haul trucking, where top-20 for-hire carriers now specify telematics through exclusive master service agreements rather than regional equipment tenders.
Telematics in Automotive Market Segmentation
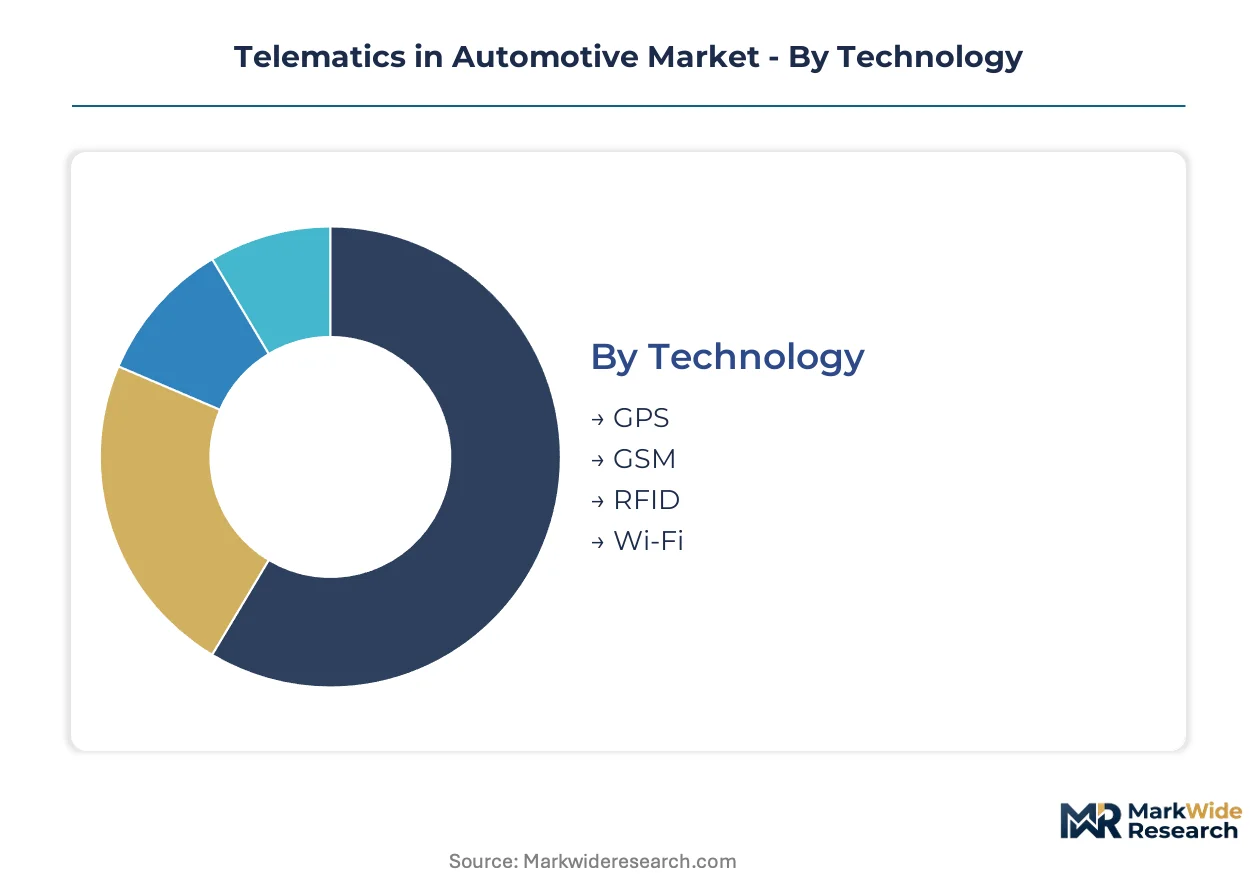
Telematics market segmentation reveals how value migrates from hardware commoditization toward software-defined service layers. Distinct margin pools form around real-time data processing capabilities and regulatory-compliant data architectures.
Technology:
GSM and GPS combinations command the highest attachment rates in factory-installed systems, while emerging protocols compete on latency reduction and spectrum efficiency.
- GPS:Satellite positioning infrastructure delivers sub-5 meter accuracy for location-based services. Fleet operators in Germany and the United States prioritize GPS-dominant architectures for cross-border route optimization under divergent data localization regimes.
- GSM:Cellular modems using 2G/3G fallback remain prevalent in cost-sensitive commercial vehicle segments. Logistics companies running mixed-age fleets in India leverage GSM's broader coverage footprint where 4G penetration remains uneven.
- RFID:Short-range identification enables automated toll collection and secure facility access. Manufacturing clusters in Japan deploy RFID-integrated telematics for just-in-time parts tracking between tier-1 suppliers and assembly plants.
- Wi-Fi:Local wireless connectivity supports high-bandwidth software updates and in-cabin hotspot services. Premium passenger vehicles in South Korea integrate Wi-Fi 6E for low-latency infotainment streaming.
GPS holds installed capacity. Wi-Fi is rotating up the share rankings.
Application:
Fleet Management absorbs the largest hardware shipment volumes, though Insurance Telematics generates superior recurring revenue per deployed unit.
- Fleet Management:Real-time vehicle tracking, fuel consumption monitoring, and route optimization dominate commercial vehicle procurement specifications. California's Advanced Clean Trucks regulation pushes logistics operators toward integrated energy management dashboards.
- Insurance Telematics:Usage-based pricing models quantify driver risk through acceleration, braking, and cornering telemetry. Commercial auto underwriters in the United Kingdom price behavior data directly into premium calculations.
- Navigation:Turn-by-turn guidance with traffic-aware routing remains standard in passenger vehicle infotainment stacks. Japanese OEMs embed navigation with VICS integration for real-time congestion avoidance.
- Vehicle Diagnostics:Predictive maintenance alerts leverage OBD-II data streams to flag component degradation before failure. German commercial vehicle manufacturers bundle diagnostic subscriptions with powertrain warranty extensions.
Fleet Management holds installed capacity. Insurance Telematics is rotating up the share rankings.
End User:
OEMs capture value through embedded factory installations, while Aftermarket Providers serve replacement cycles and multi-brand fleet heterogeneity.
- OEMs:Factory-integrated telematics modules achieve hardware cost parity with retrofit units while locking in service subscription revenue. European passenger vehicle manufacturers embed modems as standard equipment to satisfy EU eCall mandates.
- Aftermarket Providers:Plug-and-play OBD-II devices serve legacy fleet vehicles and owner-operated trucks outside OEM service networks. Installation speed and cross-brand compatibility determine procurement decisions.
- Tier-1 Suppliers:Component manufacturers supply control units, antennas, and sensor arrays to vehicle assembly lines. Robert Bosch GmbH and Continental AG dominate European supply corridors.
- Logistics Companies:Fleet operators specify telematics through master service agreements consolidating hardware, connectivity, and analytics. Top-20 North American for-hire carriers now demand single-vendor accountability.
OEMs hold installed capacity. Logistics Companies is rotating up the share rankings.
Feature:
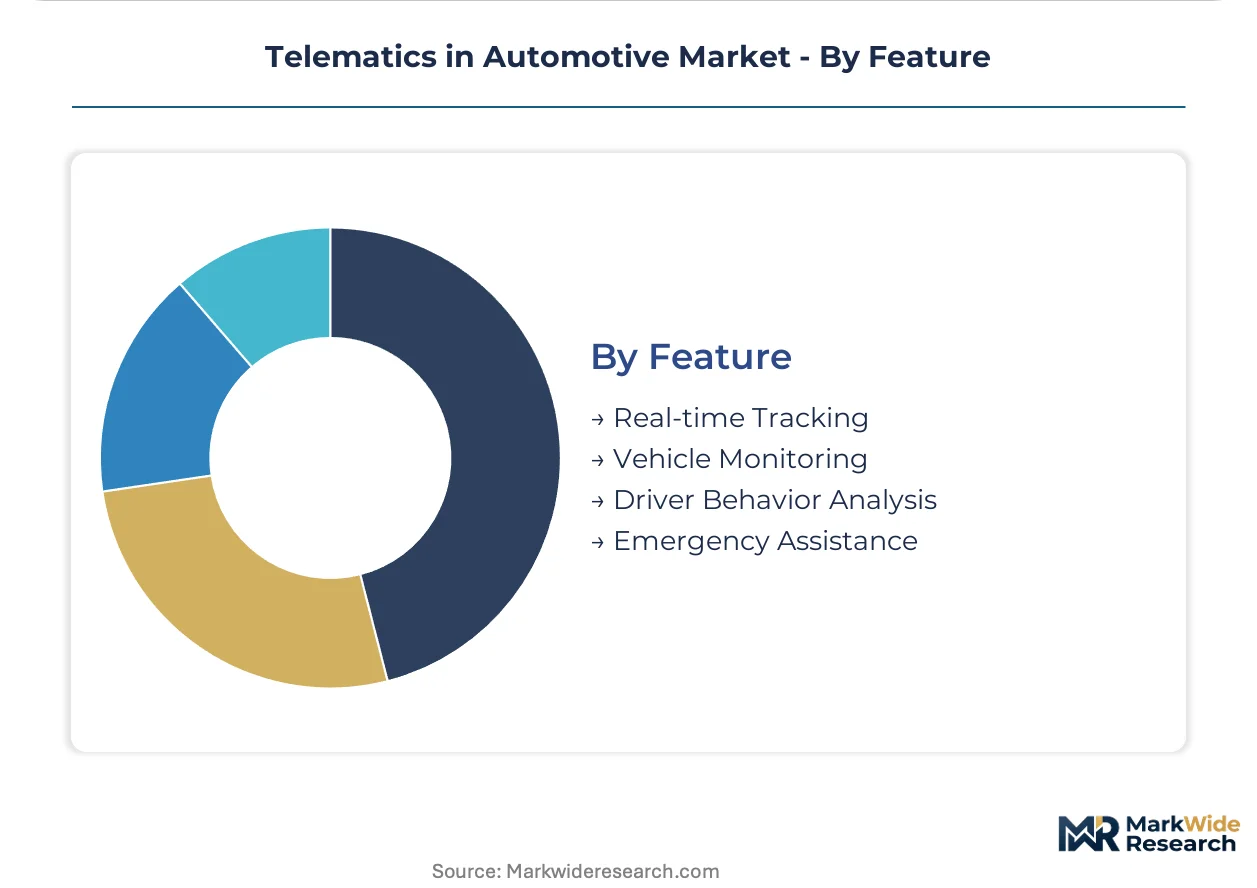
Real-time Tracking and Driver Behavior Analysis concentrate subscription revenue, while Emergency Assistance satisfies regulatory mandates with thinner margins.
- Real-time Tracking:Sub-100ms location updates enable dynamic dispatch and geofenced alert generation. Indian commercial vehicle operators deploy tracking to optimize load matching across fragmented long-haul markets.
- Driver Behavior Analysis:Acceleration, braking, and cornering metrics feed risk scoring algorithms and coaching programs. GDPR constraints in France and Germany force on-device processing to avoid biometric data retention.
- Vehicle Monitoring:Engine temperature, tire pressure, and battery health telemetry support predictive maintenance workflows. Brazil's ANVISA-aligned commercial fleet regulations mandate monitoring for refrigerated transport.
- Emergency Assistance:Automatic crash notification and stolen vehicle tracking satisfy regulatory baselines. EU eCall requirements standardize this feature across new vehicle registrations.
Real-time Tracking holds installed capacity. Driver Behavior Analysis is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modem SoC fabrication concentrates at TSMC and Samsung foundries, creating supply bottlenecks that favor countries with established automotive electronics corridors and regulatory clarity on connected vehicle deployment.
United States
Fleet electrification mandates and long-haul trucking digitization drive telematics demand. The FCC's 5.9 GHz band reconfiguration for C-V2X accelerates chipset refresh cycles. Michigan's automotive engineering clusters host embedded control unit development for Detroit Three OEMs.
Germany
Commercial auto underwriters price driver behavior data into risk models, pulling adoption through premium incentives. The EU AI Act's biometric identification rules force cabin monitoring redesigns. Stuttgart and Munich anchor tier-1 supplier density for factory-installed telematics modules.
China
The world's largest connected vehicle deployment pipeline creates module demand at scale. MIIT enforces GB standards for vehicle-network security, requiring separate certification pathways. Yangtze River Delta joint ventures integrate foreign supplier technology into domestic OEM platforms.
India
Fragmented long-haul markets drive load-matching optimization through real-time tracking. The PLI scheme for automotive electronics attracts module assembly investments. Tamil Nadu and Karnataka commercial vehicle corridors deploy GSM-dominant architectures where 4G penetration remains uneven.
United Kingdom
Usage-based insurance penetration advances fastest in commercial auto lines. GDPR cross-border data transfer restrictions impose redundant server infrastructure on multi-country fleet operators. Midlands logistics hubs consolidate vendor relationships around full-stack telematics providers.
Telematics in Automotive Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where premium embedded systems coexist with price-sensitive aftermarket retrofit units. Consolidation pressures intensify as fleet operators above 500 vehicles demand single-vendor accountability through exclusive master service agreements. Three archetypes dominate: sensor-to-cloud vertical integrators, chipset-focused connectivity specialists, and modular aftermarket platform providers. Competitive moves center on backward integration into semiconductor sourcing and strategic partnerships to secure 5G modem allocation.
Among European-based tier-1 suppliers, Robert Bosch GmbH and Continental AG exemplify the vertical integration archetype with captive control unit manufacturing. Qualcomm Technologies, Inc. occupies the chipset specialization tier, extending from consumer electronics into automotive 5G modems. Denso Corporation represents the Asia-Pacific manufacturing scale position, serving both embedded OEM channels and aftermarket retrofit demand through modular platform architectures.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| LG Electronics |
| HARMAN International |
| Verizon Connect |
| Geotab |
| Trimble Inc. |
| Qualcomm Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
Automotive-grade 5G modem substitution for legacy 4G chipsets redraws procurement geography toward TSMC and Samsung foundries while compressing hardware margins through dual-SIM redundancy requirements. Tier-1 suppliers pass foundry allocation premiums downstream, forcing fleet operators into longer master service agreements to lock component supply.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for cabin monitoring systems, separating GDPR-compliant on-device inference architectures from cloud-dependent alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks certification complexity: premium tiers absorb ISO 26262 functional safety engineering premiums, while economy tiers compete on GSM fallback compatibility. Pricing pressure stems from semiconductor supply concentration, with modem SoC fabrication bottlenecks squeezing control unit margins. Small commercial fleets with 8-15 year replacement cycles exhibit highest price sensitivity, whereas top-20 North American for-hire carriers prioritize single-vendor accountability over unit cost.
Supply Chain Analysis
Taiwan Strait transit risk concentrates automotive-grade modem SoC supply, with TSMC and Samsung foundries anchoring 5G chipset fabrication. The telematics hardware stack draws from South Korean memory components, German sensor arrays, and Chinese PCB assembly capacity. Single-source vulnerability in foundry allocation creates 26-40 week lead time volatility for control unit suppliers. Distribution runs through tier-1 supplier direct OEM channels, aftermarket distributor networks, and fleet operator master service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The telematics market enters a cyclical recovery phase as fleet electrification mandates force replacement cycles in commercial vehicle segments. California's Advanced Clean Trucks regulation and corresponding EU CO2 standards for heavy-duty vehicles create synchronized demand pull across North America and Europe.
For Market Incumbents: Consolidate around sensor-to-cloud vertical stacks to defend against Qualcomm's chipset integration push and modular aftermarket platform erosion. Robert Bosch GmbH and Continental AG should deepen backward integration into semiconductor sourcing to secure 5G modem allocation. Captive control unit manufacturing and exclusive master service agreements with top-20 for-hire carriers lock in procurement access above 500-vehicle fleet thresholds.
For New Entrants and Emerging Players: Anchor in India's PLI scheme for automotive electronics to exploit fragmented long-haul markets with GSM-dominant architectures where 4G penetration remains uneven. Tamil Nadu and Karnataka commercial vehicle corridors offer white-space deployment for load-matching optimization platforms. Partner with domestic module assemblers to serve export markets through cost-sensitive retrofit channels.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed aftermarket telematics providers facing OEM embedded platform displacement. Five-to-ten year viability hinges on software-defined service layer migration and predictive maintenance subscription revenue pools. Watch Cellular-V2X spectrum harmonization between FCC and EU frameworks as inflection indicator for chipset refresh cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEM embedded telematics modules achieve hardware cost parity with retrofit units through factory integration. |
| Battery Supply Agreement | Fleet electrification mandates compel logistics operators to deploy integrated energy monitoring with route optimization. |
| Software-Defined Vehicle Investment | Edge computing architectures redistribute data processing loads between onboard systems and cloud platforms. |
| Geographic Manufacturing Footprint | India's PLI scheme attracts module assembly investments serving domestic demand and export markets. |
| Charging Infrastructure Partnership | Commercial fleet electrification requires telematics-integrated energy management dashboards for route planning. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, tier-1 supplier procurement leads, aftermarket distribution channel heads, and fleet operator technology officers. Secondary validation drew from vehicle production databases, IHS Markit registration data, FCC spectrum allocation filings, and EU regulatory impact assessments. Bottom-up unit economics triangulated against top-down market sizing across technology, application, end user, and feature segmentation dimensions.
Across the analysis window, the forecasting framework modeled vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs derived from installed base turnover rates, regulatory mandate timelines, and insurance telematics penetration curves. Forecast inputs incorporated Cellular-V2X spectrum harmonization progress, GDPR data localization infrastructure costs, and MIIT cybersecurity certification completion rates for foreign suppliers.
Decision-makers should treat outputs as directional under base assumptions of sustained fleet electrification mandates and semiconductor supply normalization; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU AI Act enforcement timelines and China GB standard compliance pathways evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Mobile Resource Management (MRM) Market
Telematics and Infotainment
Europe Vehicle Remote Diagnostic Market
Telematics and Infotainment
Dashboard Camera Market
Telematics and Infotainment
Automotive Dashboard Camera Market
Telematics and Infotainment
Boat and Ship Telematics Market
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
Telematics Market
Telematics and Infotainment
In-Car Infotainment Market
Telematics and Infotainment
Global in Dash Navigation System Market
Telematics and Infotainment
Vehicle-To-Infrastructure (V2I) Communication Market
Telematics and Infotainment
In-Vehicle Infotainment Systems Market
Telematics and Infotainment
Global 5G in Automotives Market
Telematics and Infotainment
Internet of Things Vehicle-To-Vehicle Communication Market
Telematics and Infotainment
Fleet Telematics System Market
Telematics and Infotainment
In Vehicle Infotainment Market
Telematics and Infotainment
Asia-Pacific Connected Cars Market