
 Asia-Pacific Automotive Telematics Market | 2026-2036
Asia-Pacific Automotive Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automotive Telematics Market Analytics
India's AIS-140 mandate is consolidating the cost-of-entry calculus for aftermarket telematics providers across the region. Continental AG leverages its embedded systems expertise to anchor OEM supply relationships in Japan and South Korea. Robert Bosch GmbH competes through R&D intensity in V2X communication modules. Tata Consultancy Services Ltd sustains its position via software integration capabilities for fleet management platforms serving domestic logistics networks.
Asia-Pacific automotive telematics encompasses GPS-enabled hardware and software systems that transmit vehicle location, performance metrics, and driver behavior data through cellular or satellite networks to centralized management platforms. These systems typically integrate onboard diagnostic ports, accelerometers, and wireless modems operating across 2G through 5G frequency bands to enable real-time fleet oversight, usage-based insurance pricing, and predictive maintenance scheduling. Fleet Management dominates current revenue pools across the region as logistics operators prioritize fuel optimization and route efficiency, while V2X Communication represents the fastest-expanding segment as Chinese and Japanese regulators push cooperative intelligent transport standards. Insurance Telematics occupies a narrower but high-margin niche where data granularity directly determines premium pricing accuracy for commercial vehicle underwriters.
Japan's METI and India's Ministry of Road Transport shape product standards through connected-vehicle mandates and safety certification requirements, while China's MIIT enforces GB-standard compliance for data localization in automotive networks. Australia's TGA-equivalent transport safety frameworks and South Korea's MFDS-aligned automotive cybersecurity protocols further fragment market access rules across the region. Stakeholders must monitor divergence between China's data-sovereignty requirements and ASEAN's emerging cross-border fleet data reciprocity negotiations to determine platform architecture investments.
Market Dynamics
India's AIS-140 mandate and China's GB-standard data localization rules are compressing platform architecture decisions for telematics providers across the Asia-Pacific region, forcing simultaneous compliance with divergent sovereign data regimes.
Growth Catalysts
- AIS-140 Compliance Deadline:India's Ministry of Road Transport mandates GPS-enabled panic buttons and real-time tracking for all public transport vehicles, creating immediate hardware replacement cycles across state bus fleets and commercial operators.
- Connected-Vehicle Corridors:China's MIIT has designated cooperative intelligent transport system (C-ITS) pilot zones spanning Shanghai, Beijing, and Shenzhen, accelerating V2X module deployment.
- Fleet Operator Consolidation:Southeast Asian logistics networks are centralizing procurement of fuel optimization platforms, concentrating demand among regional 3PL providers serving cross-border ASEAN trade routes.
Market Restraints
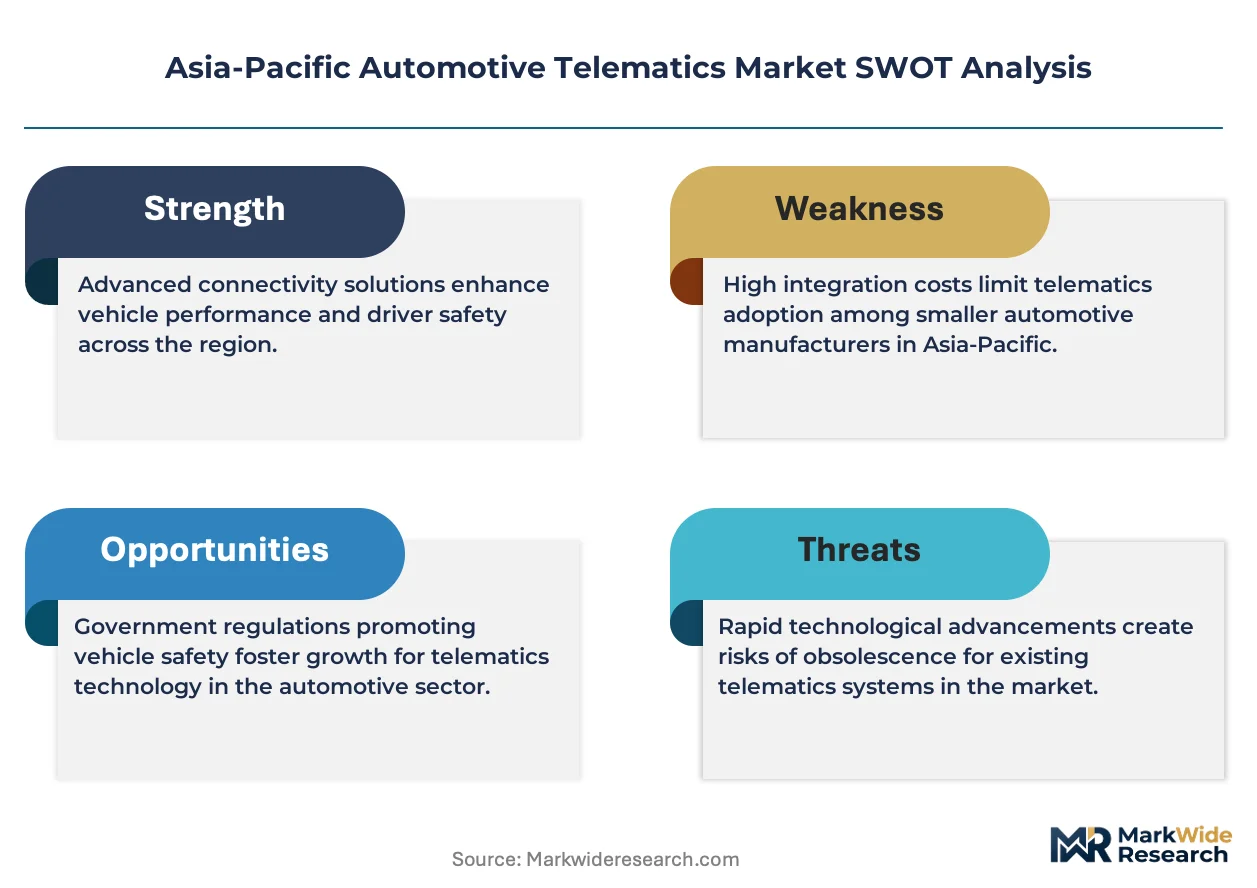
- Semiconductor Supply Concentration:Cellular modem chipsets for automotive-grade telematics units rely on concentrated foundry capacity in Taiwan and South Korea, exposing module assemblers to allocation volatility.
- Data Sovereignty Fragmentation:China's GB/T 32960 standard requires in-country server localization, while India's draft data protection framework imposes divergent cross-border transfer restrictions, multiplying compliance architecture costs.
- 2G Network Sunsetting:Thailand and Indonesia's scheduled 2G shutdowns strand legacy hardware installed across aging commercial fleets, compressing replacement timelines for cost-sensitive owner-operators.
Strategic Opportunities
- Usage-Based Insurance Penetration:Australia's transport safety frameworks now recognize telematics-derived driver scores for commercial vehicle premium calculations, opening a high-margin data services channel.
- Predictive Maintenance Convergence:Onboard diagnostic data streams are converging with AI-driven failure prediction models, enabling Japanese OEMs to monetize subscription-based fleet health monitoring.
- Rural Fleet Digitization:India's state-level logistics modernization schemes target unconnected agricultural and last-mile delivery vehicles across Uttar Pradesh and Maharashtra, representing greenfield hardware deployment.
Industry Challenges
- Embedded Software Talent Scarcity:V2X protocol stack development requires specialized automotive cybersecurity engineers, with South Korea's MFDS-aligned certification programs failing to produce sufficient qualified candidates.
- Multi-Standard Integration Complexity:Fleet management platforms must simultaneously support Japan's METI C-ITS specifications, China's LTE-V2X protocols, and India's AIS-140 message formats, fragmenting R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automotive Telematics Market |
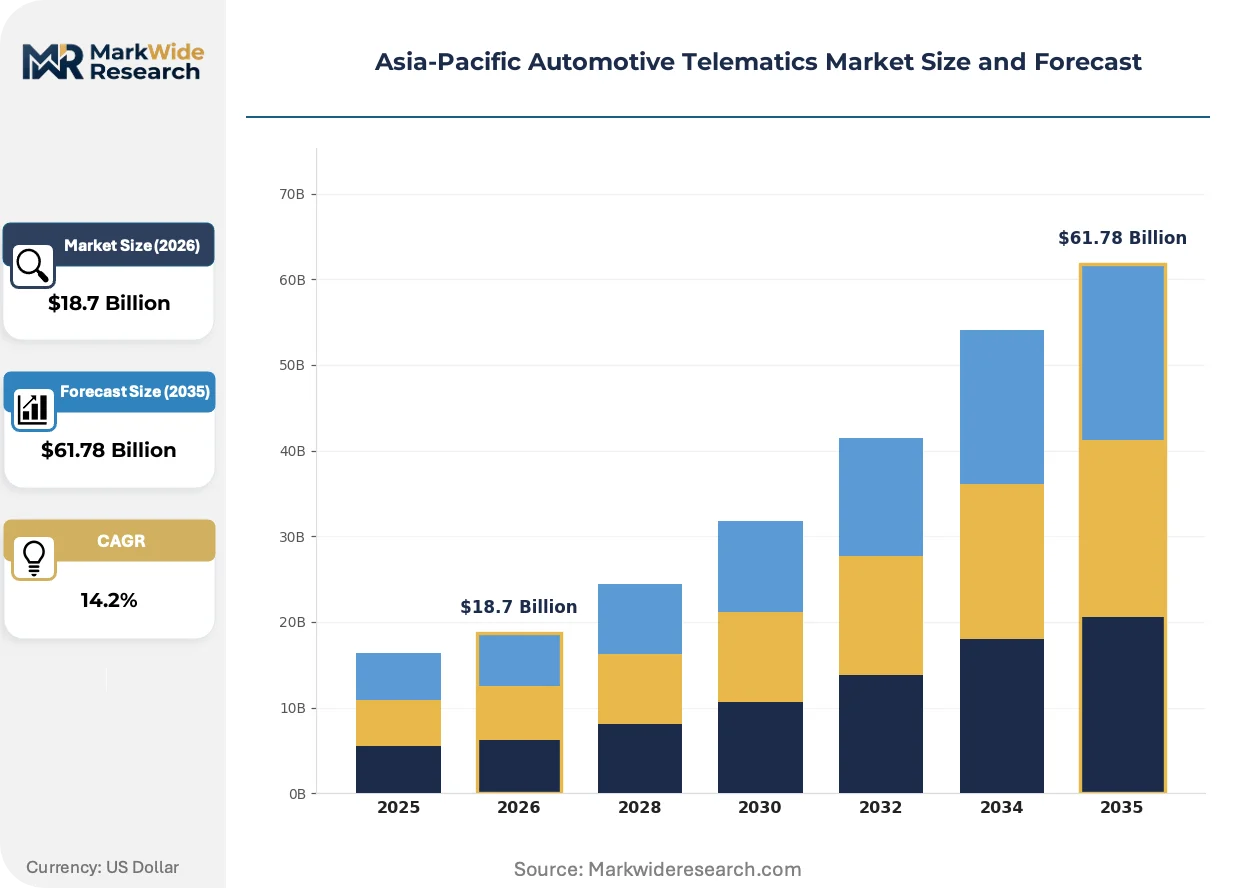
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fleet Management, Insurance Telematics, Navigation Systems, V2X Communication Application: Remote Diagnostics, Driver Behavior Monitoring, Vehicle Tracking, Emergency Services Technology: GPS, Cellular, Bluetooth, Satellite End User: OEMs, Fleet Operators, Insurance Companies, Aftermarket Providers |
| Companies Covered | MiX Telematics Ltd, Trimble Inc., Tata Consultancy Services Ltd, Tech Mahindra Limited, HARMAN International, Continental AG, Robert Bosch GmbH, Geotab, TomTom Telematics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automotive Telematics Market Evolving Landscape
Edge computing architectures and satellite-backup connectivity are redistributing data processing loads across the Asia-Pacific telematics stack, reducing latency-critical application dependence on cellular infrastructure.
Cellular V2X (C-V2X) modules are converging with 5G network slicing capabilities to enable sub-10-millisecond latency for collision avoidance applications. Japanese commercial vehicle OEMs are adopting these integrated units fastest, with METI safety certification timelines compressing from 18 to 12 months for compliant designs. This convergence is displacing earlier DSRC-only architectures in cooperative intelligent transport deployments.
China's MIIT enforcement of GB/T 32960.3 data localization standards requires all connected vehicle telemetry to route through domestically certified cloud infrastructure. Automotive telematics providers must now maintain separate platform instances for Chinese fleet data, fragmenting their regional architecture investments. Domestic logistics operators in the Yangtze River Delta are responding by consolidating procurement with state-affiliated platform vendors.
Fleet procurement teams across Southeast Asia are unbundling hardware acquisition from software subscription commitments, compressing vendor lock-in periods from multi-year to annual terms. This pattern disrupts traditional bundled pricing models and favors modular platform providers with API-first architectures. Indonesian mining and plantation fleet operators exhibit the strongest preference for this disaggregated purchasing structure.
Asia-Pacific Automotive Telematics Market Segmentation
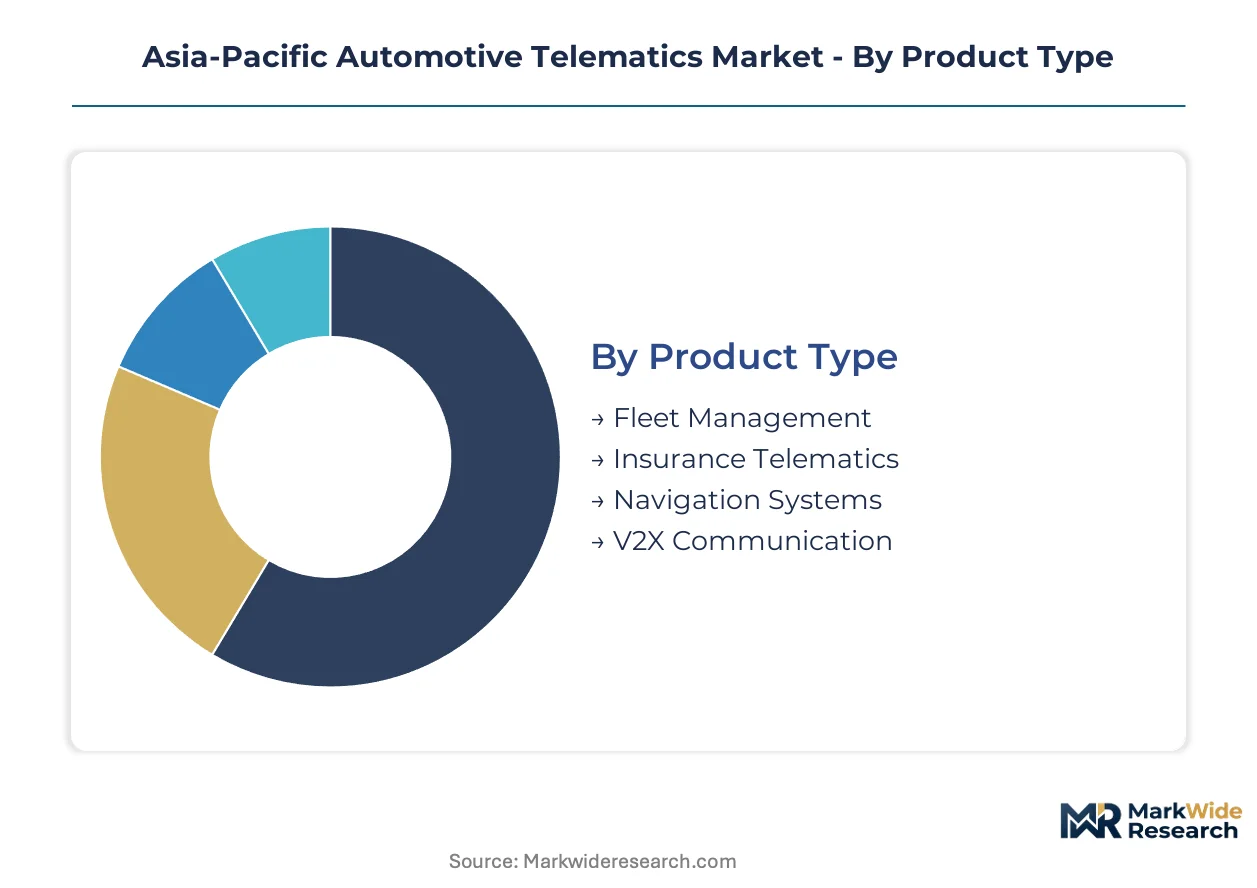
Asia-Pacific telematics providers architect platform investments around four intersecting dimensions: hardware-software integration depth, real-time application requirements, connectivity reliability thresholds, and procurement authority concentration. Each segmentation axis carries distinct margin profiles and compliance burdens across India's AIS-140 corridors, China's GB-standard zones, and ASEAN cross-border logistics networks.
Product Type:
Standalone aftermarket units dominate cost-sensitive deployments, while embedded OEM-integrated systems anchor long-term subscription revenue in Japanese and South Korean vehicle programs.
- Fleet Management:Integrated hardware-software platforms combining GPS modems, onboard diagnostic interfaces, and cloud dashboards for fuel optimization and route planning. Demand concentrates among Southeast Asian 3PL operators serving cross-border ASEAN trade corridors, where fuel costs consume 35-45% of operating budgets and real-time visibility justifies hardware expenditure.
- V2X Communication:Cellular and DSRC modules enabling vehicle-to-vehicle and vehicle-to-infrastructure data exchange for collision avoidance and traffic signal prioritization. China's MIIT-designated C-ITS pilot zones in Shanghai, Beijing, and Shenzhen are absorbing module volumes fastest, with METI safety certification timelines compressing for compliant Japanese commercial vehicle designs.
- Insurance Telematics:Usage-based pricing platforms aggregating accelerometer data, GPS traces, and engine diagnostics to generate driver risk scores. Australia's transport safety frameworks now recognize these scores for commercial vehicle premium calculations.
- Navigation Systems:Embedded and portable units providing real-time routing with traffic overlay. Indian state bus fleets and last-mile delivery operators in Uttar Pradesh and Maharashtra drive replacement cycles as 2G networks sunset.
Fleet Management leads volumes today; V2X Communication is gaining share fastest.
Application:
Functional requirements diverge sharply between safety-critical real-time systems and retrospective analytics platforms, with latency tolerance determining connectivity technology selection.
- Remote Diagnostics:Continuous monitoring of engine performance, battery health, and component wear through OBD-II data streams. Japanese OEMs are monetizing subscription-based fleet health monitoring by converging these streams with AI-driven failure prediction models.
- Vehicle Tracking:Location-based services for asset recovery, route verification, and geofence enforcement. India's AIS-140 mandate for public transport panic buttons and real-time tracking has triggered immediate hardware replacement cycles across state bus corporations.
- Driver Behavior Monitoring:Accelerometer-based detection of harsh braking, acceleration, and cornering events for safety coaching and insurance scoring. Australian commercial underwriters now accept telematics-derived scores for premium adjustments.
- Emergency Services:Automatic collision notification and manual panic button systems transmitting location to first responders. Regulatory mandates in India and proposed frameworks across ASEAN are embedding these as baseline requirements.
Vehicle Tracking commands the largest installed base; Remote Diagnostics is climbing the fastest as predictive maintenance subscriptions penetrate Japanese commercial fleets.
Technology:
Connectivity modality selection hinges on coverage gaps, latency requirements, and sovereign data routing constraints across the region's fragmented telecommunications infrastructure.
- Cellular:4G LTE and emerging 5G modules supporting real-time data transmission with network-slicing capabilities for sub-10-millisecond latency. China's LTE-V2X protocols and Japan's METI C-ITS specifications are driving converged module development.
- GPS:Satellite positioning systems providing location accuracy for tracking and navigation applications. Remains the foundational layer across all product types, with multi-constellation support becoming standard.
- Bluetooth:Short-range wireless for smartphone pairing and in-cabin device integration. Enables low-cost driver identification and trip logging for insurance telematics.
- Satellite:Backup connectivity for remote areas beyond cellular coverage, particularly relevant for Indonesian mining and plantation fleets operating in Kalimantan and Papua.
Cellular dominates connectivity spend; Satellite is expanding most quickly as fleet digitization penetrates Indonesia's remote extraction and agricultural operations.
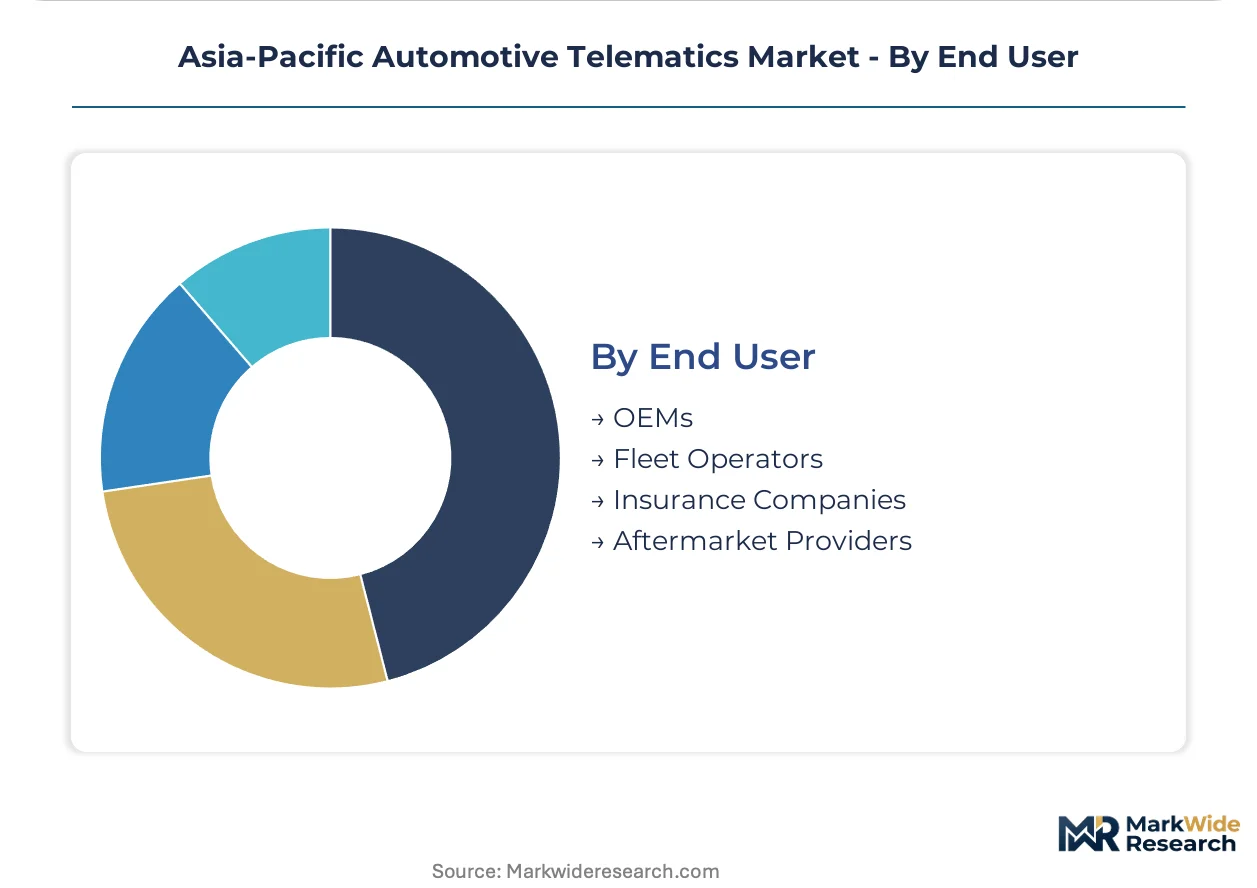
End User:
Procurement authority is fragmenting as Southeast Asian fleet operators unbundle hardware acquisition from software subscriptions, compressing vendor lock-in periods.
- Fleet Operators:Logistics companies, ride-hailing platforms, and public transport authorities purchasing integrated platforms. Indonesian mining and plantation operators exhibit strongest preference for disaggregated hardware-software purchasing.
- OEMs:Vehicle manufacturers embedding telematics at production for warranty management and connected services. Japanese commercial vehicle OEMs are fastest adopters of integrated C-V2X modules.
- Insurance Companies:Underwriters deploying usage-based pricing programs for commercial vehicle portfolios. Australian transport safety frameworks now explicitly recognize telematics-derived driver scores.
- Aftermarket Providers:Independent installers serving cost-sensitive owner-operators and retrofit mandates. India's AIS-140 compliance deadline has compressed replacement timelines for state bus fleets.
Fleet Operators represent the largest addressable spend; Insurance Companies are gaining share fastest as usage-based pricing penetrates Australian commercial vehicle underwriting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's embedded software engineering workforce anchors the region's telematics platform development, while China's hardware manufacturing clusters and Japan's automotive cybersecurity specialists complete the talent triangle shaping competitive positioning across the Asia-Pacific market.
China
Domestic logistics operators in the Yangtze River Delta are consolidating procurement with state-affiliated platform vendors. MIIT enforcement of GB/T 32960.3 data localization standards requires separate cloud infrastructure for Chinese fleet data. Shanghai, Beijing, and Shenzhen absorb module volumes fastest as C-ITS pilot zones accelerate V2X deployment.
India
State bus corporations across Uttar Pradesh and Maharashtra are executing immediate hardware replacement cycles. The Ministry of Road Transport's AIS-140 mandate mandates GPS-enabled panic buttons and real-time tracking for all public transport vehicles. Last-mile delivery operators in Delhi-NCR and Bangalore drive aftermarket unit demand as 2G networks sunset.
Japan
Commercial vehicle OEMs are fastest adopters of integrated C-V2X modules with subscription-based fleet health monitoring. METI safety certification timelines compressed from 18 to 12 months for compliant designs. Nagoya and Tokyo anchor cooperative intelligent transport system deployments with embedded OEM-integrated systems.
Australia
Commercial underwriters now accept telematics-derived driver scores for premium adjustments under transport safety frameworks. Usage-based insurance penetration opens high-margin data services channels. Mining and long-haul logistics corridors across Western Australia and Queensland drive satellite-backup connectivity demand.
Indonesia
Mining and plantation fleet operators in Kalimantan and Papua exhibit strongest preference for disaggregated hardware-software purchasing. Scheduled 2G shutdowns strand legacy hardware across aging commercial fleets. Jakarta-based logistics networks are unbundling procurement commitments from multi-year to annual terms.
Asia-Pacific Automotive Telematics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware fabrication, software integration, and platform orchestration layers. The vendor base stratifies into three tiers: global automotive suppliers with embedded systems expertise, IT services conglomerates with fleet management software capabilities, and telematics-native specialists with modular API-first architectures. Dominant competitive moves include strategic partnerships between hardware manufacturers and cloud platform providers, plus geographic expansion through regulatory compliance bundling.
Within the automotive supplier tier, Continental AG and Robert Bosch GmbH exemplify embedded systems and V2X communication module development. Among IT services providers, Tata Consultancy Services Ltd anchors software integration capabilities for domestic logistics networks. These three entities represent distinct archetypes: German engineering conglomerates with OEM supply relationships, and Indian technology services firms with fleet platform specialization.
| Leading Market Players |
|---|
| MiX Telematics Ltd |
| Trimble Inc. |
| Tata Consultancy Services Ltd |
| Tech Mahindra Limited |
| HARMAN International |
| Continental AG |
| Robert Bosch GmbH |
| Geotab |
| TomTom Telematics |
| Others |
Value Network & Pricing Analysis
Backward integration into cellular modem chipset fabrication anchors both supply security and pricing power for tier-one module assemblers serving Japanese and South Korean OEM programs. This captive production capability insulates vendors from Taiwan foundry allocation volatility while supporting premium-tier pricing for automotive-grade telematics units.
Pricing Analysis
The bundled-vs-unbundled service split separates legacy multi-year commitments from emerging annual subscription terms. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales service intensity. Cost compression in economy-tier aftermarket units intensifies because Indonesian mining operators aggressively disaggregate hardware from software procurement. Fleet operators exhibit highest price sensitivity; Japanese commercial vehicle OEMs demonstrate lowest sensitivity due to embedded integration requirements.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for cellular modem chipsets, exposing module assemblers to foundry allocation volatility. Raw material dependencies include automotive-grade semiconductors, GPS receiver components, and lithium-ion power cells. Tariff exposure across ASEAN cross-border logistics routes compounds supply chain risk. Distribution runs through state-affiliated platform vendors in China and independent aftermarket installers in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Asia-Pacific automotive telematics rests on software subscription scaling and predictive maintenance premium-tier adoption. Cost-down drivers include edge computing architectures reducing cellular data transmission volumes.
For Market Incumbents: Deploy certification bundling as a defensive lever against modular API-first specialists. Consolidate OEM supply relationships through METI-aligned C-ITS specification compliance. Anchor position in China's GB-standard zones by maintaining separate in-country cloud infrastructure. Deepen software integration capabilities to offset hardware commoditization pressure.
For New Entrants and Emerging Players: AI-driven failure prediction models offer technology-first wedge into Japanese commercial fleet health monitoring subscriptions. Target rural agricultural vehicle digitization across Uttar Pradesh and Maharashtra as the most penetrable geography. Pursue white-label platform partnerships with Indonesian plantation operators seeking disaggregated procurement structures.
For Investors and Strategic Acquirers: Roll-up economics work for modular API-first specialists because fleet procurement unbundling fragments vendor relationships and compresses lock-in periods. Five-to-ten-year viability favors platform orchestrators with cross-border ASEAN compliance capabilities. Monitor divergence between China's data-sovereignty requirements and ASEAN reciprocity negotiations as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | METI C-ITS and China's LTE-V2X protocol convergence reduces multi-standard R&D fragmentation for module developers. |
| Software-Defined Vehicle Investment | Japanese OEMs monetize subscription-based fleet health monitoring through OBD-II data stream integration. |
| Geographic Manufacturing Footprint | India's embedded software engineering workforce anchors regional platform development cost advantages. |
| Strategic Partnership | State-affiliated cloud vendors in Yangtze River Delta consolidate procurement for GB/T 32960.3 compliance. |
| Acquisition of Specialist Firm | V2X cybersecurity engineering talent scarcity in South Korea drives targeted capability consolidation. |
Research Methodology
Direct dialogue with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distribution channel heads, and fleet operations managers grounded qualitative findings. Secondary validation drew from MIIT GB-standard filings, METI safety certification timelines, AIS-140 compliance documentation, and ASEAN customs trade data. Bottom-up unit economics triangulated against top-down regional demand aggregation.
Segmentation outputs across product type, application, technology, and end-user dimensions calibrated penetration curves over the projection horizon. CAGRs derived from installed base replacement cycles, regulatory mandate deadlines, and fleet operator procurement intention surveys. V2X module deployment trajectories in C-ITS pilot zones and insurance telematics adoption curves in Australia informed scenario weightings.
The model holds under stable sovereign data regime enforcement; deviation in cross-border fleet data reciprocity agreements or accelerated 2G network sunsetting would shift replacement timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Japan Commercial Telematics Market
Telematics and Infotainment
In-Car Infotainment Market
Telematics and Infotainment
Global Car GPS Navigation System Market
Telematics and Infotainment
5G V2X Communications Market
Telematics and Infotainment
In-Taxi Digital Signage Market
Telematics and Infotainment
Automotive Data Monetization Market
Telematics and Infotainment
In-Vehicle Infotainment Systems Market
Telematics and Infotainment
Motorcycle Infotainment System Market
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
Automotive Navigation Solutions Market
Telematics and Infotainment
GPS Tracker Market
Telematics and Infotainment
V2X Communication Module Market
Telematics and Infotainment
Park Assist Camera Market
Telematics and Infotainment
Internet of Things Vehicle-To-Vehicle Communication Market
Telematics and Infotainment
Automotive Human Machine Interface (HMI) Market
Telematics and Infotainment
In Car Infotainment System Market