
 North America Dashboard Camera Market | 2026-2036
North America Dashboard Camera Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dashboard Camera Market Analytics
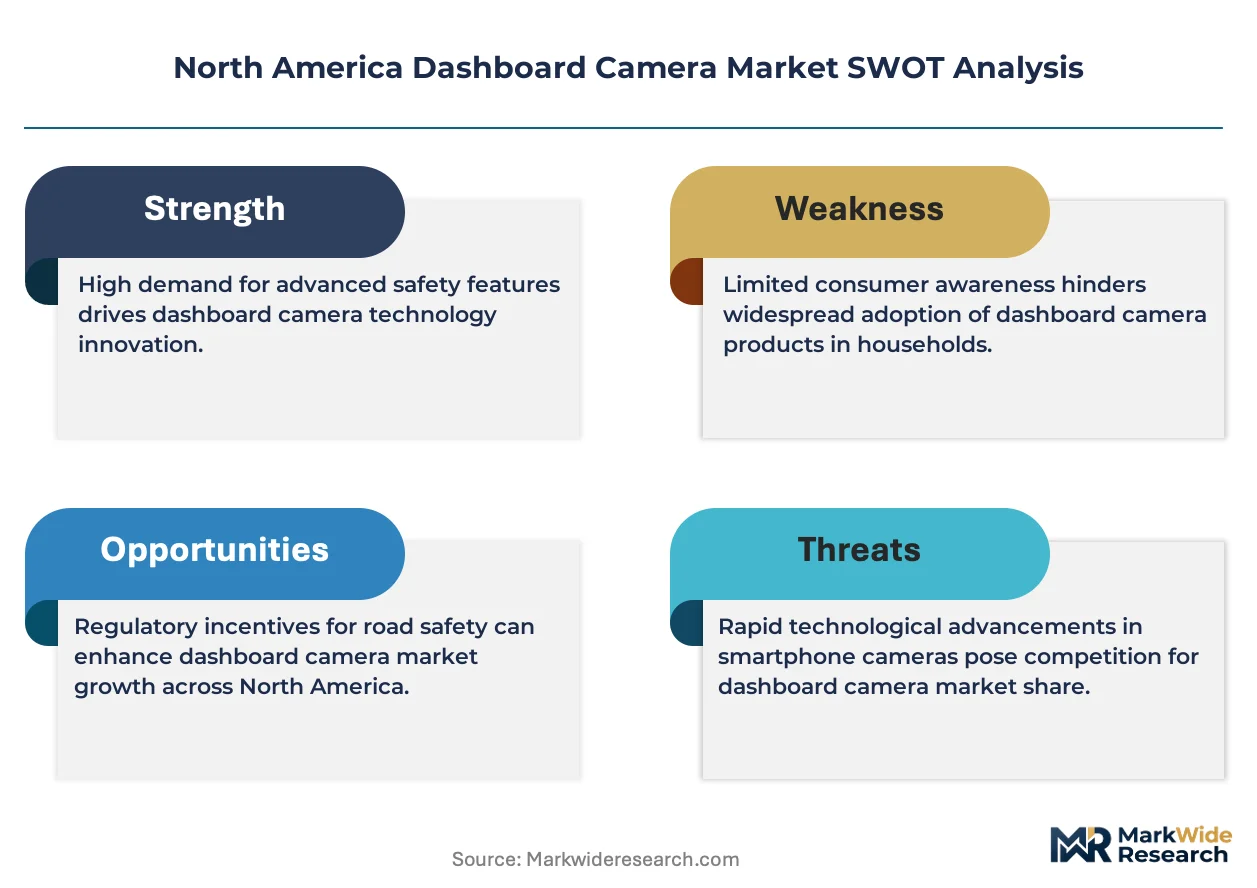
Cloud-connected video storage and over-the-air firmware updates are restructuring what fleet managers purchase, shifting transactions from one-time hardware sales to recurring service relationships. Garmin Ltd leverages its aviation-grade GPS heritage to anchor premium positioning in law enforcement channels. Nextbase competes through direct-to-consumer online retail dominance in the United States and Canada. Thinkware Corporation specializes in thermal management engineering for extreme-climate reliability across northern tier states.
A dashboard camera is a windshield-mounted digital video recorder capturing continuous forward-facing and cabin footage, typically recording at 1080p to 4K resolution with looped storage on microSD or solid-state media, designed to document traffic incidents, driver behavior, and vehicle surroundings for insurance, legal, or operational review. Smart cameras with AI-powered incident detection and cloud connectivity represent the fastest-expanding segment as commercial fleets prioritize real-time risk analytics over passive recording. Dual lens cameras sustain premium margin pools by combining forward and interior views in single-unit deployments favored by ride-sharing services and school transportation operators. Standard cameras occupy mature, price-sensitive demand among individual consumers purchasing through automotive dealer channels.
The National Highway Traffic Safety Administration influences crash-test documentation standards that shape product certification requirements for OEM-integrated units, while the Federal Communications Commission governs wireless transmission protocols for Wi-Fi and cellular-connected devices. State-level insurance commissioners in California, Texas, and Florida increasingly reference dashcam footage in fault determination frameworks, creating compliance incentives for commercial operators. Stakeholders must monitor evolving privacy litigation around cabin-facing recordings and the patchwork of state wiretapping consent laws that could restrict audio capture functionality without clear policy architecture.
Market Dynamics
Fleet operators across the United States and Canada are abandoning passive recording hardware in favor of cloud-integrated video analytics platforms that transform dashcams from evidence archives into real-time risk management infrastructure.
Growth Catalysts
- NHTSA ADAS compatibility guidelines:Federal mandates for advanced driver assistance system integration are compelling commercial vehicle operators to upgrade legacy units, creating replacement demand cycles across interstate trucking corridors.
- Ride-sharing liability frameworks:Transportation network companies operating in California and Texas now mandate dual-lens cabin documentation, accelerating adoption among gig economy drivers seeking platform compliance.
- AI-powered incident detection:Machine learning algorithms processing edge-computed video streams enable automatic collision alerts and driver behavior scoring, shifting purchasing criteria from resolution specs to analytics capability.
Market Restraints
- Semiconductor supply concentration:Image sensor fabrication depends on a limited supplier base concentrated in East Asian foundries, exposing North American assemblers to lead time volatility and allocation constraints.
- Lithium-ion thermal limitations:Battery-dependent parking mode operation faces reliability degradation in Arizona and Nevada desert conditions, restricting 24-hour surveillance functionality without hardwire installation.
- State wiretapping consent fragmentation:Audio recording functionality encounters legal friction in two-party consent jurisdictions like Illinois and Pennsylvania, forcing firmware disablement or compliance complexity.
Strategic Opportunities
- Canadian prairie commercial fleets:Saskatchewan and Manitoba agricultural logistics operators remain underpenetrated by cloud-connected platforms, presenting first-mover expansion potential for integrated telematics providers.
- School transportation mandate alignment:State-level pupil transportation safety regulations in Florida and Georgia are incorporating video documentation requirements, opening institutional procurement channels distinct from consumer retail.
- 5G-V2X convergence:Cellular vehicle-to-everything communication modules integrated with dashcam hardware enable real-time hazard broadcasting, creating premium tier differentiation for early adopters in connected vehicle corridors.
Industry Challenges
- Embedded systems cybersecurity certification:Fleet procurement departments now require UL 2900 or IEC 62443 compliance documentation, extending vendor qualification timelines and raising engineering overhead for smaller manufacturers.
- Legacy fleet management platform integration:API incompatibility between proprietary video management systems and established telematics dashboards forces costly middleware development or customer IT burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dashboard Camera Market |
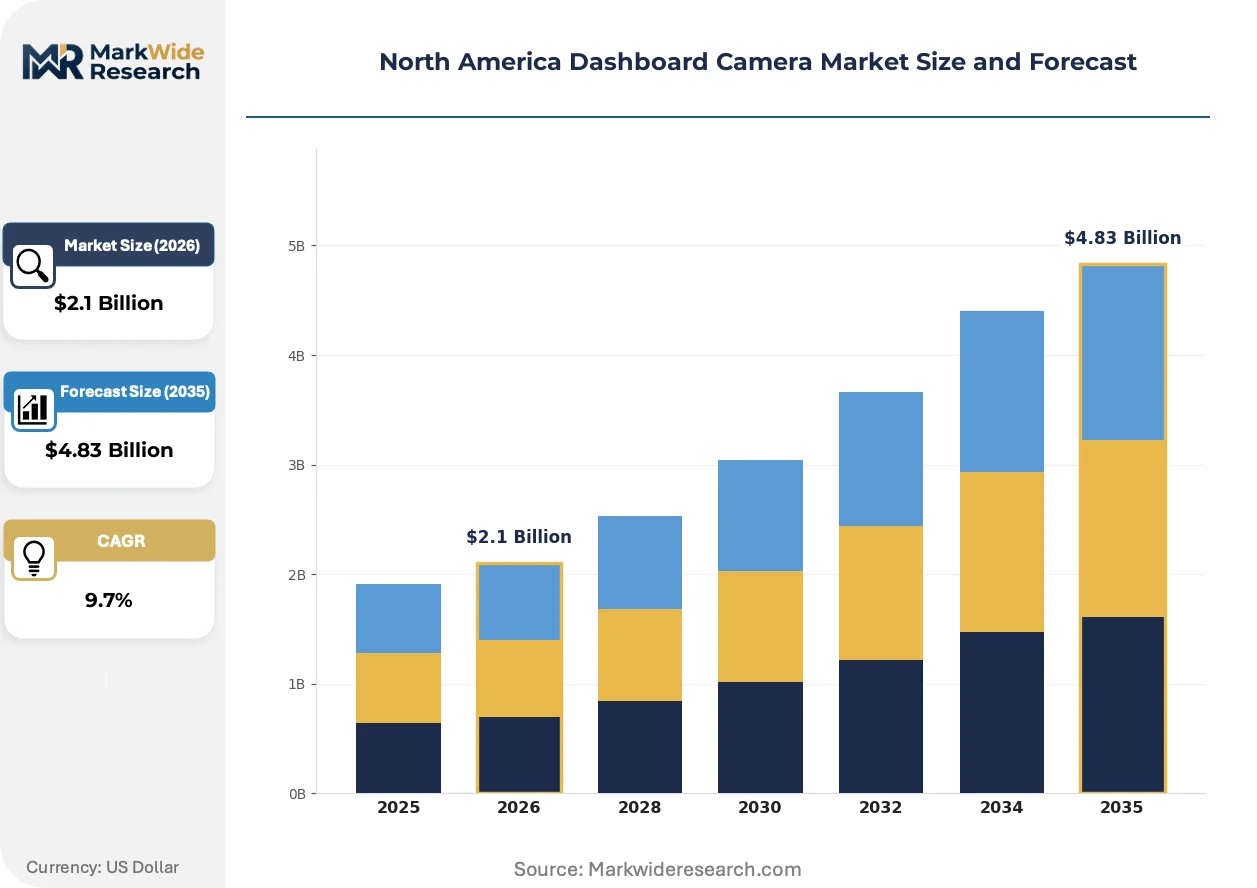
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.83 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cameras, Smart Cameras, 360-Degree Cameras, Dual Lens Cameras End User: Individual Consumers, Fleet Owners, Ride-Sharing Services, Law Enforcement Technology: Night Vision, GPS Integration, Wi-Fi Connectivity, G-Sensor Technology Distribution Channel: Online Retail, Specialty Stores, Automotive Dealers, Wholesale Distributors |
| Companies Covered | Garmin Ltd, Nextbase, Thinkware Corporation, Panasonic Holdings Corporation, LG Innotek, Waylens Inc., Harman International Industries Inc., BlackVue (Pittasoft), Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dashboard Camera Market Evolving Landscape
Video data architectures are pivoting from localized storage to distributed cloud pipelines, restructuring how hardware vendors monetize customer relationships and how fleet managers access operational intelligence.
Edge AI processors from Qualcomm and Ambarella are unifying sensor fusion capabilities—combining radar, GPS, and accelerometer inputs with visual data—within single system-on-chip designs. Commercial fleet operators in Texas logistics hubs are deploying these consolidated units to eliminate separate telematics hardware, collapsing installation complexity and maintenance overhead while enabling sub-second incident classification.
NHTSA's evolving crash-test documentation standards now reference video evidence protocols, compelling OEM-integrated dashcam suppliers to pursue formal certification pathways previously reserved for passive safety systems. Tier-1 automotive suppliers serving Detroit manufacturers are reconfiguring production lines to accommodate these documentation requirements, with compliance timelines compressing from 18-month cycles to 9-month validation windows.
Fleet procurement departments are consolidating vendor relationships around full-stack video-telematics platforms, displacing the historical pattern of sourcing cameras, cellular modems, and fleet software from separate suppliers. This concentration is most visible among California-based last-mile delivery operators managing thousand-vehicle deployments, where unified data lakes now outweigh hardware cost minimization in sourcing decisions.
North America Dashboard Camera Market Segmentation
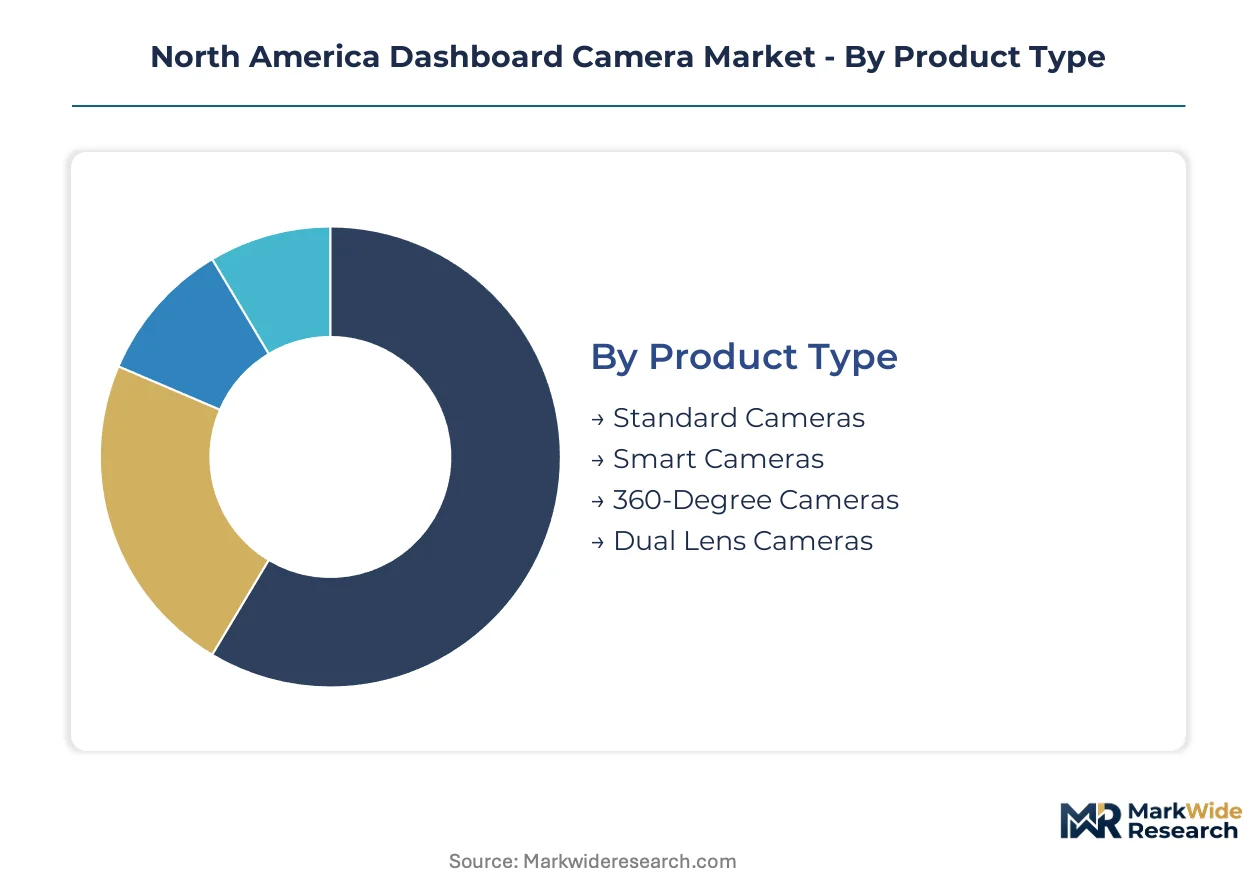
Dashboard camera purchasing patterns fragment sharply across hardware sophistication, operational purpose, and connectivity requirements. Fleet procurement departments weight cloud analytics and telematics integration far differently than individual consumers prioritizing price points. Understanding these divergent selection criteria exposes where margin pools concentrate and which specification trajectories command R&D investment.
Product Type:
Resolution thresholds and lens architecture differentiate hardware tiers, with processing capability and sensor fusion determining functional ceiling rather than recording quality alone.
- Smart Cameras:Edge AI processors enable real-time incident classification and driver behavior scoring without cloud dependency. California last-mile delivery fleets and Texas logistics operators deploy these units to collapse separate telematics hardware and reduce installation complexity.
- Dual Lens Cameras:Forward-facing and cabin-view sensors unified in single housings capture simultaneous road and occupant footage. Ride-sharing platforms operating in California and Texas mandate this configuration for liability documentation, creating compliance-driven procurement at premium price points.
- Standard Cameras:1080p loop recording on microSD cards serves price-sensitive individual purchasers through automotive dealer channels.
- 360-Degree Cameras:Multi-sensor spherical coverage eliminates blind spots for high-value cargo transport and armored vehicle operators.
Mature deployment sits with Standard Cameras. Newer deployment is concentrated in Smart Cameras.
End User:
Purchasing authority and operational scale reshape vendor engagement models, from retail packaging for consumers to API integration requirements for enterprise fleets.
- Fleet Owners:Thousand-vehicle operators in California and Texas corridors negotiate unified video-telematics platforms. Consolidated data lakes now outweigh hardware cost minimization in sourcing decisions, with procurement departments requiring UL 2900 cybersecurity certification.
- Ride-Sharing Services:Platform-mandated dual-lens documentation drives gig economy driver adoption. Transportation network companies embed hardware requirements in driver agreements, shifting compliance burden to individual operators.
- Individual Consumers:Post-purchase installation through automotive dealer channels dominates this price-sensitive segment.
- Law Enforcement:Evidence chain-of-custody requirements demand aviation-grade GPS timestamping and tamper-evident sealing.
Volume concentration rests with Individual Consumers. Margin expansion is steepest among Fleet Owners.
Technology:
Sensor fusion and wireless protocols determine integration depth with existing vehicle systems and fleet management infrastructure.
- GPS Integration:Aviation-grade timestamping and geolocation tagging anchor evidence admissibility standards. Law enforcement channels and commercial liability frameworks in Florida and Georgia require this capability for fault determination documentation.
- Wi-Fi Connectivity:Over-the-air firmware updates and smartphone-based footage retrieval reduce fleet IT burden. Individual consumers and small fleet operators favor this over cellular-connected alternatives to avoid recurring service fees.
- Night Vision:Infrared illumination and low-light sensor sensitivity enable incident documentation in unlit parking environments and overnight trucking corridors.
- G-Sensor Technology:Accelerometer-triggered emergency recording protects collision footage from loop overwrite during impact events.
Baseline specification centers on G-Sensor Technology. Capability differentiation is climbing the fastest around GPS Integration.
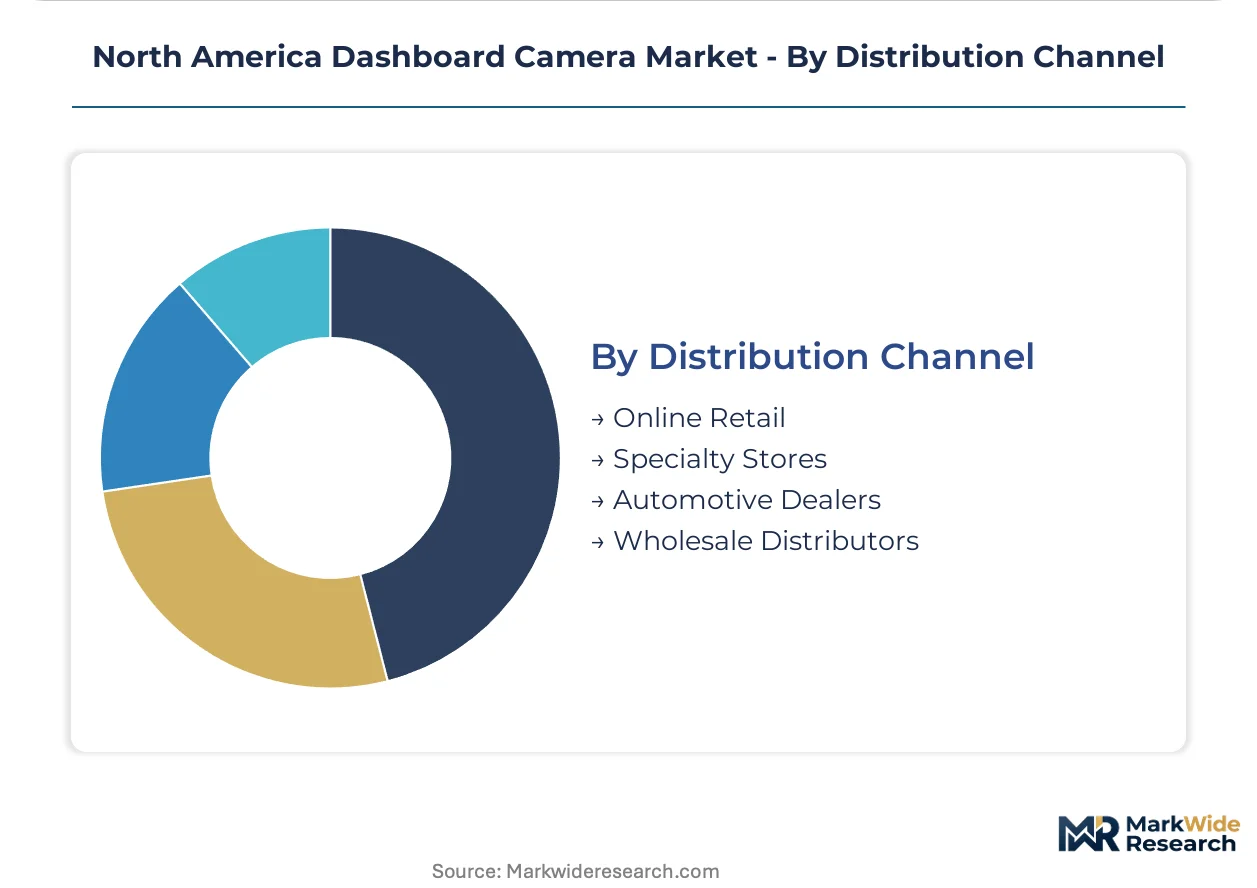
Distribution Channel:
Channel selection reflects buyer technical sophistication, installation capability, and preference for bundled services versus transactional hardware acquisition.
- Online Retail:Direct-to-consumer platforms dominate individual purchaser acquisition in the United States and Canada. Specification comparison tools and user review aggregation reduce information asymmetry for unassisted buying decisions.
- Automotive Dealers:Point-of-sale attachment to new vehicle purchases captures consumers prioritizing professional installation. This channel serves buyers lacking technical confidence for self-installation of hardwire kits.
- Specialty Stores:Hands-on demonstration and immediate technical support attract enthusiasts seeking premium specifications.
- Wholesale Distributors:Volume pricing and logistics integration serve regional fleet service providers and installation networks.
Transaction volume flows through Online Retail. Enterprise procurement is consolidating around Wholesale Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North American demand concentrates in the United States while Canadian commercial fleets and Mexican logistics corridors absorb distinct hardware tiers. Production and assembly remain concentrated in East Asian foundries, creating import dependency for image sensors and edge processors.
United States
California last-mile delivery operators and Texas logistics hubs drive cloud-connected platform adoption. NHTSA guidelines on advanced driver assistance system compatibility reshape hardware certification requirements. Fleet procurement departments in Los Angeles and Dallas-Fort Worth now mandate UL 2900 cybersecurity documentation.
Canada
Saskatchewan and Manitoba agricultural logistics operators present underpenetrated demand for integrated telematics solutions. Health Canada regulates wireless transmission protocols for cellular-connected devices crossing provincial borders. Thinkware Corporation's thermal engineering targets extreme-climate reliability across Prairie Provinces.
Mexico
Cross-border trucking corridors connecting Nuevo León and Tamaulipas to Texas generate dual-lens documentation demand for liability protection. Mexican federal transportation safety regulations increasingly reference video evidence standards. Manufacturing clusters in Guadalajara assemble components for North American distribution.
North America Dashboard Camera Market Competitive Landscape
Top-tier vendors anchor aviation-grade GPS and law enforcement channels, while mid-tier specialists compete through direct-to-consumer retail and thermal engineering. The vendor base stratifies across premium positioning for evidence-grade hardware, volume-driven online retail, and climate-specialized reliability engineering. Three archetypes dominate: GPS heritage players, direct-to-consumer platforms, and thermal management specialists. Consolidation pressure intensifies through API integration requirements and cybersecurity certification overhead.
Within the GPS-heritage tier, Garmin Ltd exemplifies premium positioning anchored in aviation-grade timestamping capabilities. Nextbase occupies the direct-to-consumer vector through online retail dominance in the United States and Canada. Thinkware Corporation represents the climate-specialist archetype, with engineering focus on extreme-temperature reliability across northern tier states.
| Leading Market Players |
|---|
| Garmin Ltd |
| Nextbase |
| Thinkware Corporation |
| Panasonic Holdings Corporation |
| LG Innotek |
| Waylens Inc. |
| Harman International Industries Inc. |
| BlackVue (Pittasoft) |
| Honeywell International Inc. |
| Others |
Value Network & Pricing Analysis
DRAM spot price indices cascading through bill-of-materials structures differentiate margin pools across hardware tiers, with memory cost volatility compressing standard camera pricing while AI-enabled units capture service-recurring premiums.
Pricing Analysis
Margin tightening in standard 1080p units reflects image sensor commoditization and East Asian foundry overcapacity. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and analytics capability, with UL 2900 cybersecurity documentation commanding substantial premiums. Cost-down pressure on entry-level hardware accelerates because fleet procurement departments consolidate around unified video-telematics platforms. Individual consumers exhibit highest price sensitivity, while law enforcement channels show minimal elasticity for aviation-grade GPS timestamping.
Supply Chain Analysis
Reverse logistics flows for warranty returns and firmware-obsolete units concentrate refurbishment activity in Guadalajara assembly clusters. Image sensor fabrication draws from Taiwan and South Korea, with edge AI processors sourced from USA-based Qualcomm and Ambarella designs. Lithium-ion battery cells, microSD controllers, and thermal management substrates anchor raw material dependencies. Single-source vulnerability in advanced CMOS foundry capacity exposes North American assemblers to allocation constraints. Distribution runs through wholesale distributors serving fleet installation networks, supplemented by direct-to-consumer online retail for individual purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cybersecurity certification overhead and API integration complexity are forcing sub-scale vendors toward exit or acquisition, consolidating procurement influence around full-stack platform providers.
For Market Incumbents: Lock in fleet procurement relationships through UL 2900 and IEC 62443 compliance documentation, extending vendor qualification timelines that disadvantage smaller competitors. Deepen backward integration into edge AI processor supply through strategic partnerships with Qualcomm and Ambarella, reducing exposure to foundry allocation volatility. Prioritize unified data lake architectures that collapse separate telematics hardware, reinforcing switching costs among California and Texas logistics operators. For New Entrants and Emerging Players: Begin with Saskatchewan and Manitoba agricultural logistics corridors, where cloud-connected platform penetration remains underdeveloped and first-mover expansion potential sits with integrated telematics providers. Target school transportation procurement channels in Florida and Georgia, where state-level pupil safety regulations are incorporating video documentation requirements outside competitive retail saturation. Pursue direct-to-fleet sales models bypassing established distributor relationships through API-native platform designs. For Investors and Strategic Acquirers: Distressed-cycle entries favor thermal engineering specialists with extreme-climate reliability credentials in northern tier states and Prairie Provinces. Long-term viability hinges on recurring service revenue attachment rates rather than transactional hardware margins. Monitor NHTSA crash-test documentation standard evolution as inflection indicator for OEM-integrated unit certification timelines and Tier-1 supplier qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified video-telematics data lakes displace separate hardware sourcing for California last-mile fleets. |
| Certification Investment | UL 2900 cybersecurity documentation extends vendor qualification timelines, filtering sub-scale competitors. |
| Geographic Expansion | Canadian prairie agricultural logistics corridors present underpenetrated demand for cloud-connected platforms. |
| Acquisition of Specialist Firm | Thermal engineering capabilities anchor extreme-climate reliability positioning across northern tier states. |
| Strategic Partnership | Edge AI processor alliances with Qualcomm reduce foundry allocation exposure for North American assemblers. |
Research Methodology
Multi-period observation of fleet procurement patterns, NHTSA regulatory filings, and image sensor foundry capacity utilization anchored the trend analysis, supplemented by interviews with fleet operations directors, Tier-1 automotive supplier procurement managers, cloud platform engineers, and insurance claims specialists. Secondary validation drew from FCC equipment authorization databases, SEC 10-K filings of listed component suppliers, customs import records for imaging semiconductors, and vehicle production databases. Bottom-up unit shipment estimates triangulated against top-down service revenue projections.
Segment-weighting approaches distributed value across smart cameras, dual lens configurations, standard units, and 360-degree systems, with technology dimensions spanning GPS integration, Wi-Fi connectivity, night vision capability, and G-sensor implementation. End-user segmentation captured fleet owners, ride-sharing services, individual consumers, and law enforcement channels. CAGRs derived from logistic diffusion curves fitted to fleet replacement cycles and regulatory compliance timelines, incorporating edge AI processor cost trajectories and cellular data plan pricing elasticity.
Underlying measurement precision varies by segment; fleet procurement data carries tighter precision than individual consumer estimates given consolidated purchasing visibility. Forecasts reflect assumptions around NHTSA ADAS compatibility guideline implementation pace, semiconductor supply normalization, and state wiretapping consent law evolution. Practitioners should monitor foundry capacity allocation announcements, cybersecurity certification requirement expansion, and 5G-V2X module integration timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Global Car Digital Cockpit Market
Telematics and Infotainment
Global Vehicle Fleet Communication Market
Telematics and Infotainment
Motorcycle Infotainment System Market
Telematics and Infotainment
Global Automotive Infotainment System Market
Telematics and Infotainment
Automotive Infotainment Market
Telematics and Infotainment
In Vehicle Infotainment Market
Telematics and Infotainment
Automotive Navigation Solutions Market
Telematics and Infotainment
Automotive Wi-Fi Router Market
Telematics and Infotainment
Mobile Resource Management (MRM) Market
Telematics and Infotainment
Global 5G in Automotives Market
Telematics and Infotainment
Global Carpool-As-A-Service Market
Telematics and Infotainment
Telematics Market
Telematics and Infotainment
Vehicle Digital Cockpit Market
Telematics and Infotainment
Japan Commercial Telematics Market
Telematics and Infotainment
Europe Automotive Navigation System Market
Telematics and Infotainment
APAC Telematics Market