
 Advanced Traveller Information System Market | 2026-2036
Advanced Traveller Information System Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Traveller Information System Market Analysis
Silicon carbide is hardening as the preferred substrate for roadside edge-computing nodes, cutting thermal management costs against legacy silicon designs. Siemens AG anchors European deployments with integrated traffic-management stacks. Garmin Ltd. leverages consumer GPS heritage to compete in fleet-dashboard segments. Kapsch TrafficCom specializes in toll-collector-to-traveller data pipelines across Alpine corridor projects.
Advanced Traveller Information Systems fuse real-time sensor feeds, predictive algorithms, and multimodal scheduling engines to deliver dynamic routing guidance across road, rail, and shared-mobility networks. These platforms typically process sub-100-millisecond latency updates from loop detectors, floating car data, and connected-vehicle broadcasts to synchronize arrival estimates across operator dashboards and personal devices. Cloud-based installation architectures now lead procurement among mid-size municipalities seeking elastic compute without capital-heavy server farms. IoT Devices as a technology layer represents the fastest-expanding segment, driven by falling cellular-module costs and V2X radio mandates in several jurisdictions.
The U.S. DOT's ITS Joint Program Office, the EU's delegated acts under the Intelligent Transport Systems Directive, and Japan's METI connected-vehicle roadmaps collectively shape certification requirements for cross-border data interoperability and cybersecurity hardening. China's MIIT GB standards for vehicular communication impose domestic encryption protocols that fragment vendor access for non-local suppliers. Stakeholders must weigh regional compliance divergence against the economies of unified software stacks.
Market Dynamics
V2X radio mandates and edge-computing hardware economics are compressing deployment timelines for municipal procurement of real-time traveller information platforms. Cloud-native architectures displace on-premise server installations as operating authorities prioritize elastic compute over capital-intensive infrastructure.
Growth Catalysts
- EU Green Deal Delegated Acts:Member states must deploy emissions-linked routing algorithms for multimodal trip planning across urban transit networks. This creates procurement pull for integrated traffic-management stacks.
- Silicon Carbide Substrates:Roadside edge-computing nodes now deploy wide-bandgap semiconductors that cut thermal management costs by half against legacy silicon designs. Municipal budgets redirect savings toward sensor density expansion.
- Seoul-Singapore Metro Integration:Dense bus-rail corridors in these cities demonstrate measurable ridership retention when real-time arrival estimates synchronize across operator dashboards and passenger devices.
Market Restraints
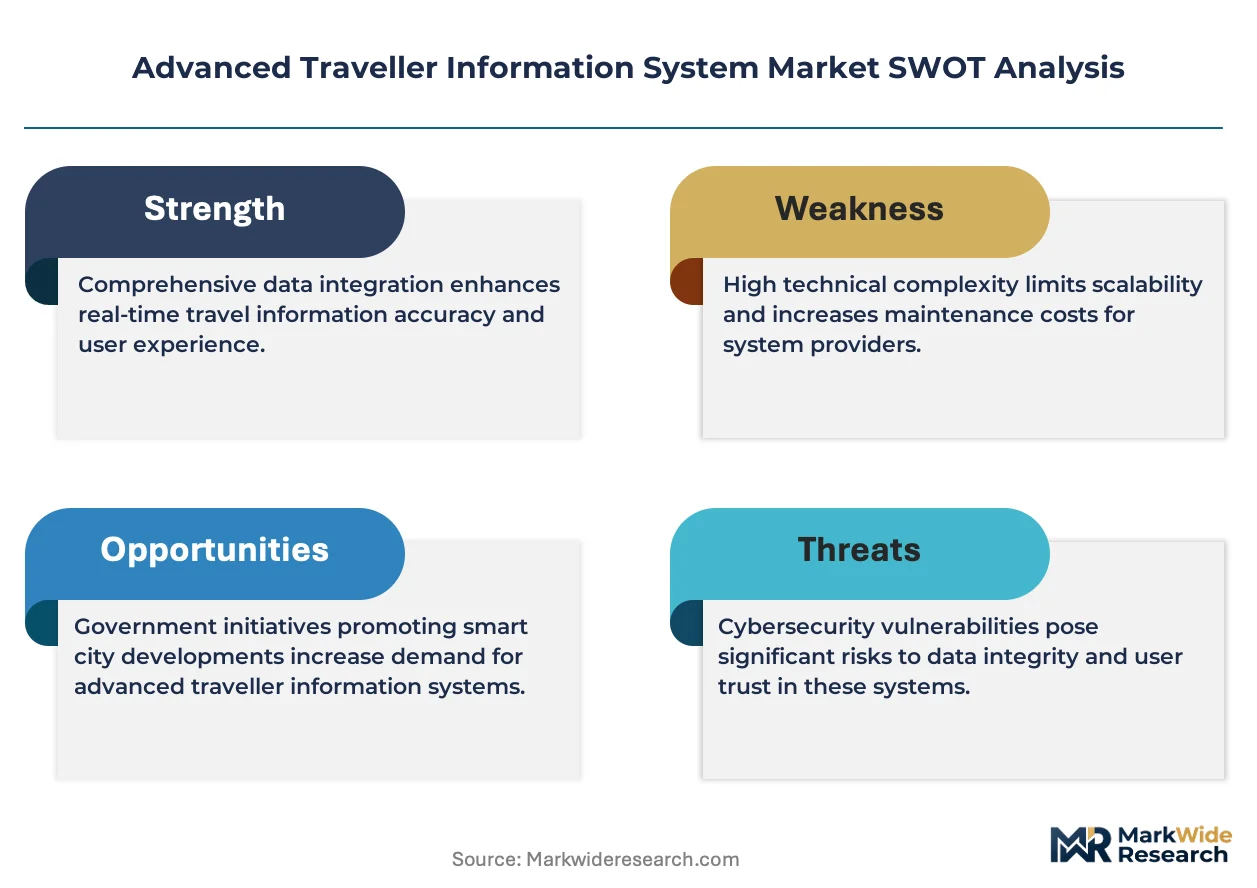
- MIIT GB Encryption Fragmentation:China's domestic vehicular communication standards impose non-interoperable encryption protocols that lock out non-local suppliers from connected-vehicle data pipelines.
- Cellular Module Supply Concentration:IoT device manufacturing depends on concentrated substrate fabrication capacity in East Asian foundries, exposing procurement timelines to geopolitical disruption.
- Legacy Loop Detector Sunk Costs:Municipalities with extensive inductive-loop installations face stranded asset risk when migrating to camera-and-lidar sensor fusion architectures.
Strategic Opportunities
- India's Smart Cities Mission:Underpenetrated Tier-2 municipal markets seek cloud-based traveller information deployments without upfront server capital, creating SaaS entry points for mid-size platform vendors.
- V2X-to-Transit Convergence:Dedicated short-range communications radio is integrating with automated vehicle location systems, enabling priority signal preemption for buses that cuts dwell time at intersections.
- Alpine Corridor Data Monetization:Toll-collector-to-traveller data pipelines in Switzerland and Austria demonstrate revenue models where congestion pricing feeds subsidize free routing app provision.
Industry Challenges
- Cybersecurity Certification Timelines:Cross-border data interoperability under the U.S. DOT ITS Joint Program Office and EU Intelligent Transport Systems Directive requires parallel security hardening audits that extend procurement cycles by 8-14 months.
- Multimodal API Integration Complexity:Transit agencies struggle to harmonize legacy GTFS feeds with real-time floating car data and connected-vehicle broadcasts within sub-100-millisecond latency windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Traveller Information System Market |
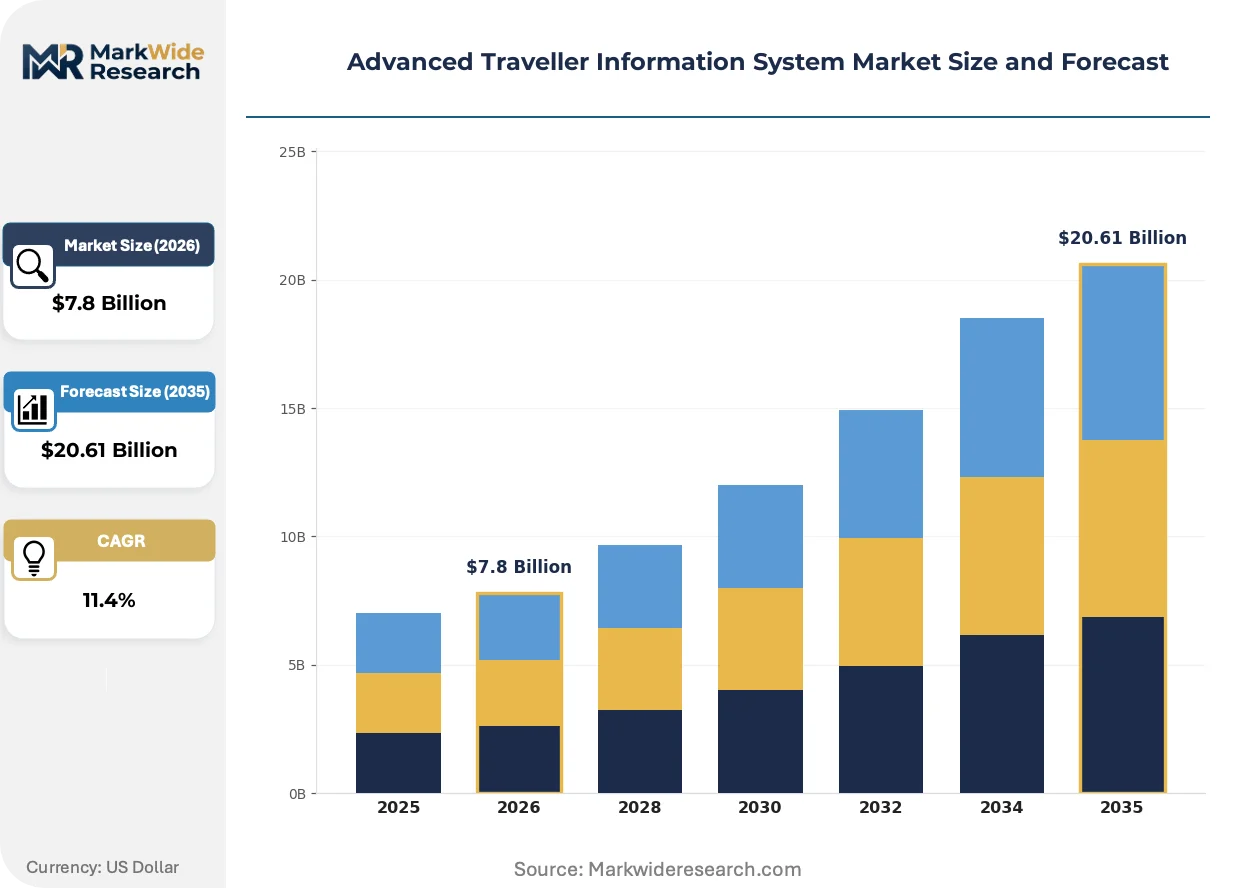
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Real-Time Data, Route Optimization, Passenger Advisory, Mobility Management Installation: Cloud-Based, On-Premise, Hybrid, Third-Party Integration End User: Transportation Authorities, Municipalities, Commercial Operators, Tourists Technology: GPS Tracking, Mobile Apps, IoT Devices, Data Analytics |
| Companies Covered | Garmin Ltd., Cubic Corporation, Siemens AG, Q-Free ASA, Iteris Inc., TomTom International, Kapsch TrafficCom, HERE Technologies, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Traveller Information System Market Emerging Trajectories
Edge intelligence and predictive routing algorithms are compressing the latency window for traveller information delivery from seconds to milliseconds. Three convergent developments reshape platform architecture and procurement criteria.
Silicon carbide power electronics is integrating into roadside edge-computing enclosures, enabling passive cooling designs that eliminate fan maintenance and extend mean-time-between-failures in harsh roadside environments. European traffic-management authorities are specifying SiC-based nodes for Alpine tunnel projects where thermal cycling stress degrades conventional silicon. The technology is integrating thermal resilience with compute density, allowing single-enclosure processing of video, radar, and V2X feeds that previously required distributed server racks.
The EU's delegated acts under the Intelligent Transport Systems Directive mandate real-time emissions data integration into routing algorithms by 2027. This forces platform vendors to ingest fuel-consumption models and electric-vehicle charging station availability alongside conventional congestion metrics. Fleet operators in Germany and the Netherlands are pre-emptively retrofitting dashboard systems to capture CO2-per-kilometer calculations that will become compulsory for contract compliance with public-sector logistics tenders.
Municipal procurement offices are unbundling hardware ownership from software licensing, favoring subscription-based platform access that transfers sensor maintenance and algorithm update liability to vendors. French and Italian regional transport authorities now structure 7-10 year service contracts with uptime guarantees replacing traditional capital purchase models. This shift concentrates vendor risk in operational performance rather than equipment delivery, squeezing margins for hardware-centric suppliers while rewarding cloud-native platform operators with recurring revenue visibility.
Advanced Traveller Information System Market Segmentation
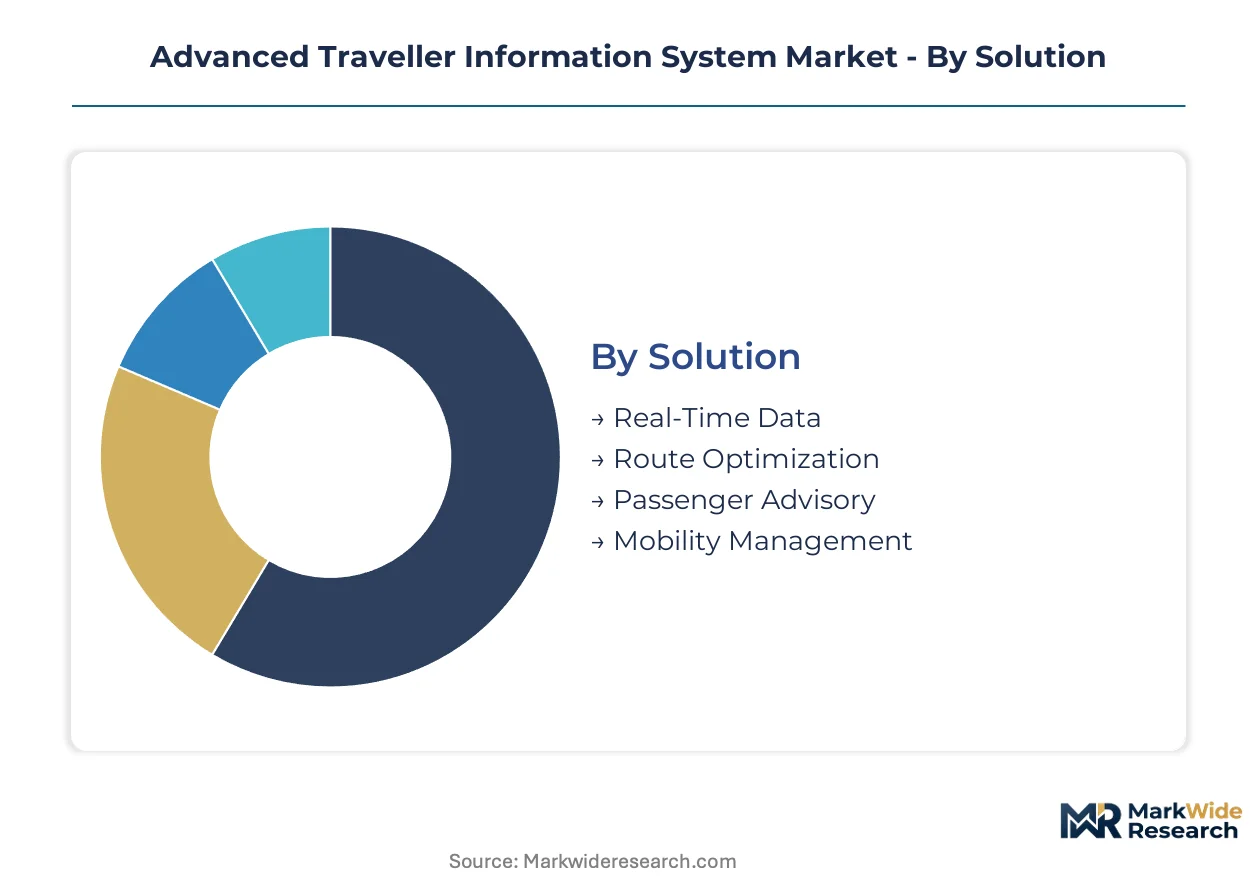
Segmentation in advanced traveller information systems reveals how procurement priorities diverge across infrastructure ownership models, technology readiness, and operator scale. Vendors must align solution architecture with specific deployment constraints rather than pursuing universal platform designs.
Solution:
Supply concentration in integrated traffic-management stacks favors vendors with bundled algorithm portfolios over point-solution specialists.
- Real-Time Data:Sub-100-millisecond latency processing of loop detector, floating car, and V2X feeds synchronizes arrival estimates across operator dashboards. Seoul and Singapore transit agencies anchor procurement for multimodal synchronization in dense metro-bus corridors.
- Route Optimization:Predictive algorithms ingest congestion patterns, incident reports, and weather overlays to generate dynamic path recommendations. EU Green Deal delegated acts mandate emissions-linked routing for public-sector logistics tenders in Germany and the Netherlands.
- Passenger Advisory:Disruption alerts and platform changes push to personal devices via cellular and DSRC broadcasts.
- Mobility Management:Aggregates shared-micromobility, ride-hail, and transit schedules into unified trip planners.
Real-Time Data absorbs the bulk of installed capacity; Route Optimization is expanding most quickly.
Installation:
Cost tier separation between capital-intensive ownership and operational expenditure models reshapes municipal procurement timelines.
- Cloud-Based:Elastic compute architectures eliminate server farm capital for mid-size municipalities. French and Italian regional transport authorities now structure 7-10 year service contracts with uptime guarantees replacing traditional purchase models.
- On-Premise:Dedicated hardware installations persist in jurisdictions with data sovereignty requirements or limited connectivity.
- Hybrid:Edge-computing nodes handle latency-critical processing while cloud layers manage archival analytics.
- Third-Party Integration:API-first architectures embed traveller information into existing municipal IT stacks.
Cloud-Based deployments capture the majority of new procurement; Hybrid installations are climbing the fastest as edge-computing hardware economics improve.
End User:
Application intensity varies sharply between regulatory-mandated public deployments and discretionary commercial investments.
- Transportation Authorities:State and provincial agencies specify cross-modal interoperability standards. U.S. DOT ITS Joint Program Office certification requirements parallel EU Intelligent Transport Systems Directive security hardening audits.
- Municipalities:Urban procurement offices prioritize subscription-based platform access that transfers sensor maintenance liability to vendors.
- Commercial Operators:Fleet dashboard retrofits for CO2-per-kilometer tracking anticipate compulsory contract compliance.
- Tourists:Free routing app provision in Alpine corridor projects demonstrates congestion pricing subsidy models.
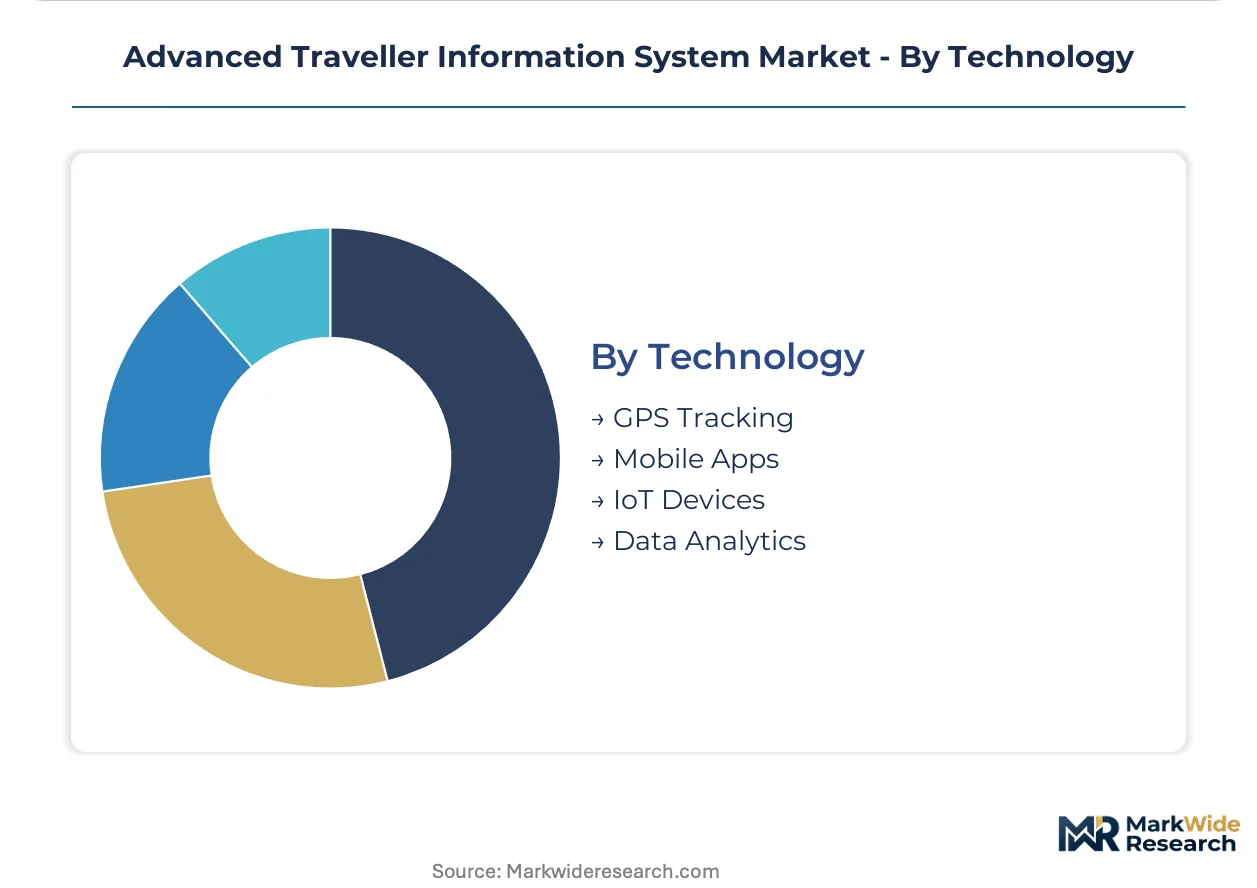
Transportation Authorities account for the largest share of platform revenue; Commercial Operators are gaining share fastest as fleet compliance deadlines approach.
Technology:
Customer type differentiation separates infrastructure-scale deployments from consumer-facing service layers.
- GPS Tracking:Satellite positioning heritage from consumer navigation devices migrates into fleet-dashboard segments. Garmin Ltd. leverages this trajectory against specialized traffic-management vendors.
- Mobile Apps:Personal device delivery of multimodal trip plans reaches highest penetration in East Asian megacities with dense metro-bus integration.
- IoT Devices:Cellular-module cost declines and V2X radio mandates drive the steepest expansion trajectory across several jurisdictions.
- Data Analytics:Predictive demand forecasting and ridership retention modeling support operator resource allocation.
IoT Devices absorb the bulk of technology-layer investment; Mobile Apps are expanding most quickly in underpenetrated Tier-2 municipal markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian megacities generate the densest procurement pull for multimodal traveller information platforms, while European regulatory mandates accelerate emissions-linked routing deployments. National standards divergence fragments vendor access in key growth corridors.
United States
The U.S. DOT ITS Joint Program Office certifies cross-border data interoperability standards that synchronize real-time feeds across state transportation authorities. Municipal procurement in California and Texas prioritizes cloud-native architectures with uptime-guaranteed service contracts. The Pacific Northwest corridor demonstrates integrated bus-rail priority signal preemption using DSRC radio integration.
Germany
Fleet operators retrofit dashboard systems to capture CO2-per-kilometer calculations ahead of compulsory public-sector logistics tender requirements. The KBA enforces cybersecurity hardening audits that extend platform certification timelines. Bavarian regional transport authorities structure 7-10 year subscription contracts transferring sensor maintenance liability to vendors.
China
MIIT GB standards impose domestic encryption protocols on vehicular communication networks that lock non-local suppliers from connected-vehicle data pipelines. Tier-2 municipal markets under the Smart Cities Mission seek elastic compute deployments without upfront server capital. Yangtze River Delta cities deploy the highest sensor density per kilometer of managed roadway.
Singapore
Dense metro-bus integration anchors ridership retention metrics when real-time arrival estimates synchronize across operator dashboards and passenger devices. The Land Transport Authority mandates multimodal trip planning APIs that ingest shared-micromobility and ride-hail schedules. Urban procurement offices specify sub-100-millisecond latency processing for disruption alerts.
Switzerland
Alpine corridor toll-collector-to-traveller data pipelines demonstrate revenue models where congestion pricing feeds subsidize free routing app provision. Swissmedic-equivalent transport certification bodies specify silicon carbide-based edge-computing nodes for tunnel thermal resilience. The Eidgenössische Technische Hochschule cluster advances predictive algorithm development for dynamic path recommendations.
Advanced Traveller Information System Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated traffic-management stack vendors capturing procurement preference over point-solution specialists. The vendor base organizes around three strategic archetypes: heritage navigation device manufacturers pivoting into fleet dashboards, European industrial conglomerates bundling traffic-management software with infrastructure hardware, and Alpine corridor specialists monetizing toll-data pipelines. Dominant competitive moves include cloud-native platform unbundling from hardware ownership and 7-10 year service contract structures that transfer operational risk to vendors.
Within the industrial conglomerate tier, Siemens AG anchors European deployments with bundled algorithm portfolios. Garmin Ltd. occupies a position exemplifying heritage consumer GPS manufacturers migrating into commercial fleet segments. Kapsch TrafficCom represents the corridor-specialist archetype, with its corporate structure signaling Austrian origins and toll-system integration expertise.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Cubic Corporation |
| Siemens AG |
| Q-Free ASA |
| Iteris Inc. |
| TomTom International |
| Kapsch TrafficCom |
| HERE Technologies |
| Thales Group |
| Others |
Supply Flow & Price Mechanics
Captive silicon carbide substrate production anchors pricing power for roadside edge-computing node vendors, locking in thermal management cost advantages that subscription-based service contracts struggle to erode. Municipal procurement offices in France and Italy now unbundle hardware ownership from software licensing, transferring sensor maintenance liability to vendors through 7-10 year uptime-guaranteed structures.
Pricing Analysis
High-volume cloud-native deployments trade margin for recurring revenue visibility, while premium on-premise installations retain pricing power through data sovereignty compliance. Price differentiation hinges on certification tier—EU ITS Directive security hardening audits versus baseline municipal specs—and after-sales bundling of algorithm updates. Pricing pressure stems from cellular module cost declines commoditizing IoT device layers. Tier-2 municipal buyers in India exhibit acute price sensitivity; Alpine corridor operators absorbing congestion pricing subsidies show lowest elasticity.
Supply Chain Analysis
Silicon carbide wafer supply rests on Japanese and German specialty substrate producers, with Taiwanese foundries handling backend packaging for V2X radio modules. Raw material dependencies span wide-bandgap semiconductor ingots, automotive-grade cellular modems, and hardened enclosure alloys. Single-source vulnerability concentrates in East Asian loop detector replacement cycles. Distribution runs through systems integrators bundling traffic-management stacks for European regional transport authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Advanced Traveller Information System Market sits in a hardware-to-cloud transition, with silicon carbide edge nodes displacing legacy silicon designs and subscription service contracts replacing capital purchase models.
For Market Incumbents: Anchor market position through backward integration into silicon carbide substrate supply, securing thermal management cost advantages against modular competitors. Prioritize certification investment for EU ITS Directive delegated acts ahead of emissions-linked routing mandates. Defend against cloud-native SaaS entrants by emphasizing sub-100-millisecond latency guarantees that elastic compute architectures struggle to match. For New Entrants and Emerging Players: Tier-2 Indian municipalities under the Smart Cities Mission represent the most penetrable buyer archetype, seeking elastic deployments without upfront server capital. Target hybrid edge-cloud architectures as the fastest-climbing installation segment. Pursue go-to-market partnerships with regional systems integrators holding existing municipal IT relationships rather than direct procurement contests. For Investors and Strategic Acquirers: Exit pathways concentrate in corridor-specialist acquisitions by industrial conglomerates seeking toll-data pipeline monetization expertise. Long-term viability favors vendors with recurring revenue visibility from 7-10 year service contracts over hardware-centric suppliers exposed to commoditization. Watch V2X radio mandate enforcement velocity across EU member states as the key inflection signal for platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | French regional transport authorities now structure subscription contracts replacing traditional capital purchases. |
| Silicon Carbide Node Deployment | Swiss Alpine tunnel projects specify SiC-based enclosures for thermal resilience against conventional silicon degradation. |
| V2X Radio Integration | Pacific Northwest corridor demonstrates bus-rail priority signal preemption using DSRC radio integration. |
| Emissions-Linked Routing Certification | German fleet operators retrofit dashboards to capture CO2-per-kilometer calculations ahead of compulsory tender requirements. |
| Tier-2 Municipal SaaS Entry | Indian Smart Cities Mission creates procurement pull for mid-size vendors offering elastic compute without server capital. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving traffic management authority procurement officers, ITS platform engineering leads, municipal CIOs, and toll-system operators. U.S. DOT ITS Joint Program Office certification databases, EU delegated acts documentation, MIIT GB standard filings, and municipal RFP archives supplied quantitative anchors. Bottom-up sensor deployment tallies triangulated against top-down infrastructure spend estimates across the analysis window.
Granularity-level modeling tracked solution type, installation architecture, end-user category, and technology layer at the country-city corridor level. Deployment timelines, regulatory mandate enforcement schedules, and cellular module cost curves fed segment-specific growth trajectories. CAGRs derived from elasticity-adjusted procurement forecasts across cloud-native, hybrid, and on-premise installation models.
Revisions become necessary when V2X radio mandate delays, cellular supply disruptions, or cybersecurity certification timeline extensions materialize. Forecasts reflect documented assumptions regarding municipal budget cycles and silicon carbide foundry capacity expansion. A small set of named triggers—EU Green Deal delegated act enforcement velocity, MIIT GB standard fragmentation persistence, and Tier-2 Indian municipal digitalization pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Marine Telematics Market
Telematics and Infotainment
Internet of Cars Market
Telematics and Infotainment
Video Telematics Market
Telematics and Infotainment
In-Cabin Lighting-Climate-Audio Synchronized Experience Systems Market
Telematics and Infotainment
Global Automotive Navigation System Market
Telematics and Infotainment
North America Electronic Toll Collection (ETC) Market
Telematics and Infotainment
Intelligent Transport Systems (ITS) Market
Telematics and Infotainment
Fleet Telematics System Market
Telematics and Infotainment
Global Car Sharing Telematics Market
Telematics and Infotainment
Telematics Control Unit Market
Telematics and Infotainment
Europe Automotive Telematics Market
Telematics and Infotainment
5G V2X Communications Market
Telematics and Infotainment
Commercial Telematics Market
Telematics and Infotainment
Electric Vehicle Telematics Market
Telematics and Infotainment
Telematics and Connectivity Control Unit Systems Market
Telematics and Infotainment
In-Taxi Digital Signage Market