
 Europe Commercial Vehicle Telematics Market | 2026-2036
Europe Commercial Vehicle Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Commercial Vehicle Telematics Market Foresight
Mid-sized logistics fleets are redrawing procurement priorities across Europe. Masternaut leverages cloud-native architecture to serve this expanding buyer segment. Targa Telematics anchors its position through embedded OEM partnerships with Italian and German truck manufacturers. Webfleet Solutions dominates the aftermarket channel with extensive service coverage across Benelux and Iberia.
Europe commercial vehicle telematics encompasses integrated hardware-software systems that capture vehicle location, engine diagnostics, and driver behavior data via CAN bus interfaces and cellular modems. These systems enable fleet operators to optimize fuel consumption, enforce driving hour compliance, and schedule predictive maintenance based on real-time engine fault codes. Fleet Management solutions lead in revenue contribution due to recurring SaaS subscription models, while Driver Behavior Monitoring exhibits the fastest expansion as insurers and regulators tie premium calculations to telematics-verified safety scores. Cloud Computing infrastructure underpins margin pools, with platform providers capturing value through data monetization and API ecosystem expansion.
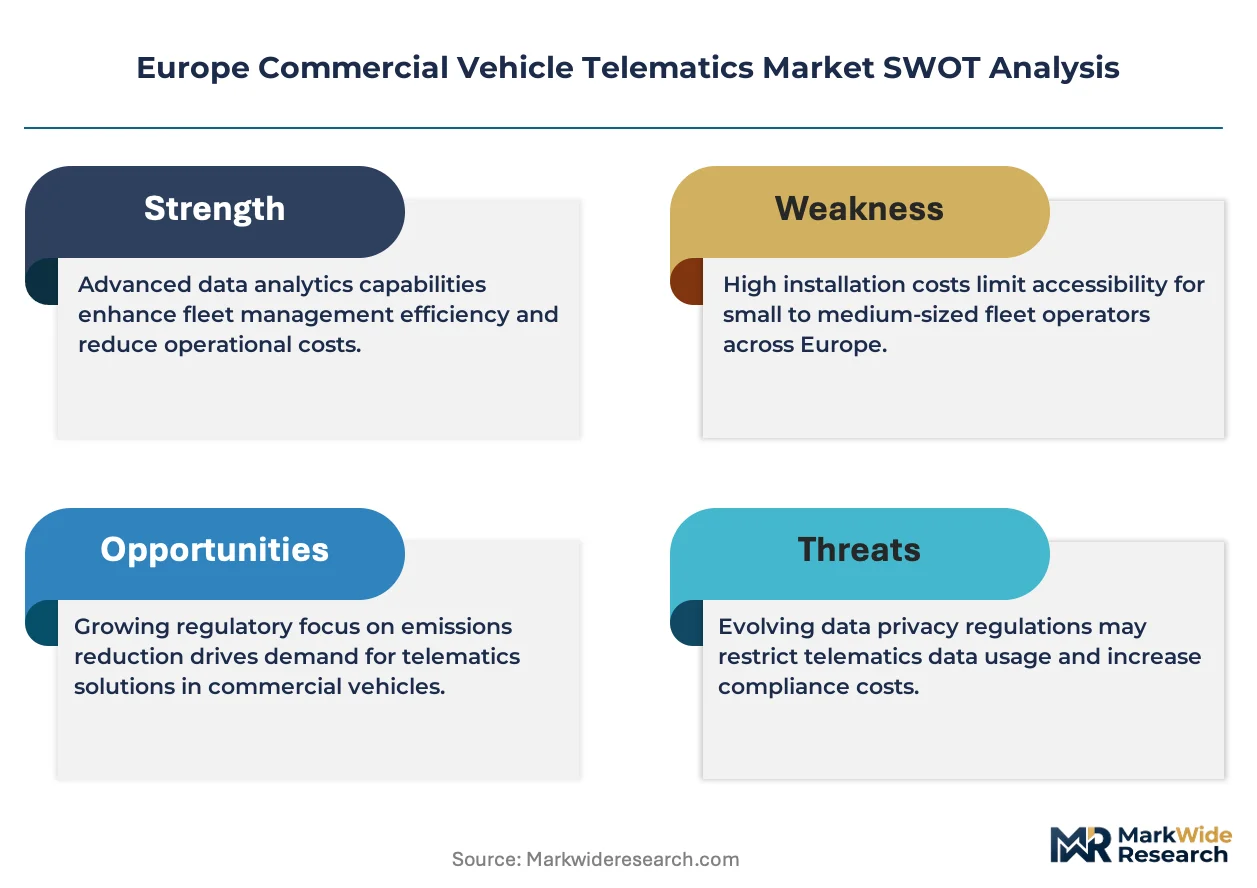
The EU Green Deal mandates CO2 emission tracking for heavy-duty vehicles, enforced through the European Commission's Mobility Package regulations. EMA guidelines on driver working time validation intersect with national transport authority enforcement across France, Germany, and Poland. The EU AI Act introduces algorithmic transparency requirements for automated driver scoring systems. Stakeholders must monitor how upcoming CSRD disclosure rules expand telematics data into corporate sustainability reporting obligations.
Market Dynamics
The EU Green Deal's CO2 emission tracking mandate is compressing fleet operator technology refresh cycles across Europe. Hardware-software integration requirements are forcing telematics providers to reconfigure platform architectures ahead of 2027 enforcement deadlines.
Growth Catalysts
- EMA Working Time Validation:Cross-border enforcement across France, Germany, and Poland mandates digital tachograph integration with telematics platforms for driver hour compliance.
- Embedded 5G Connectivity:Real-time CAN bus data streaming enables predictive maintenance scheduling based on engine fault code patterns.
- Benelux Logistics Corridors:Dense freight flows connecting Rotterdam, Antwerp, and Lille concentrate demand for fleet optimization tools among mid-sized operators.
Market Restraints
- Semiconductor Supply Concentration:Cellular modem chip sourcing remains concentrated among Asian foundries, creating input cost volatility for hardware manufacturers.
- GDPR Data Localization:Cross-border fleet data storage requirements impose architectural constraints on cloud-native platform providers.
- Aftermarket Installation Costs:Retrofit complexity for legacy diesel fleets without OEM-embedded telematics creates adoption friction among smaller operators.
Strategic Opportunities
- CSRD Disclosure Alignment:Corporate sustainability reporting rules expand telematics data into Scope 3 emissions verification for logistics procurement departments.
- Usage-Based Insurance:Safety score monetization through telematics-verified driver behavior creates new revenue pools for platform providers.
- Eastern European Fleet Penetration:Underpenetrated Polish and Romanian trucking markets present white space for aftermarket channel expansion.
Industry Challenges
- EU AI Act Algorithmic Transparency:Automated driver scoring systems face validation requirements that extend product development timelines.
- Legacy Fleet Integration:Heterogeneous vehicle age profiles across European fleets complicate standardized deployment of CAN bus interfaces.
- Cybersecurity Certification:UNECE R155 vehicle cybersecurity regulations impose testing burdens on telematics hardware suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Commercial Vehicle Telematics Market |
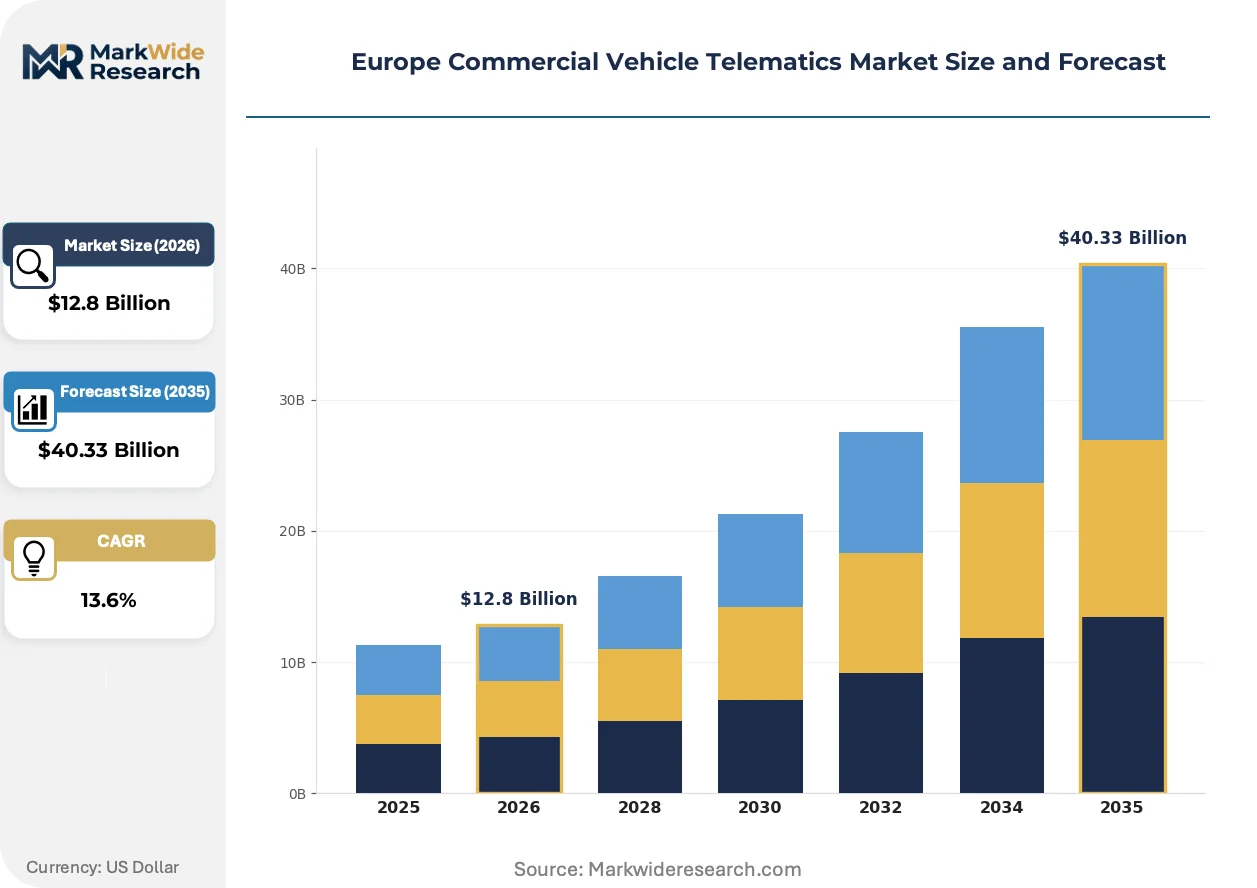
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $40.33 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fleet Management, Driver Behavior Monitoring, Route Optimization, Maintenance Management Technology: GPS Tracking, Wireless Communication, On-Board Diagnostics, Cloud Computing End User: Logistics Providers, Construction Companies, Public Transport Operators, Delivery Services Application: Real-Time Tracking, Data Analytics, Vehicle Performance Monitoring, Compliance Management |
| Companies Covered | Volvo Trucks, Masternaut, Targa Telematics, Lytx, ABAX, Webfleet Solutions, Trimble, Fleetmatics, Verizon Connect, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Commercial Vehicle Telematics Market Shifts & Advancements
Edge computing architectures are displacing centralized cloud processing for latency-sensitive fleet applications. Platform providers are reconfiguring data pipelines to accommodate real-time decision requirements at the vehicle level.
Cellular Vehicle-to-Everything (C-V2X) modules are miniaturizing to single-chip form factors that integrate directly into OEM telematics control units. German and Italian truck manufacturers are adopting these consolidated designs for 2026 model year platforms. The compression of hardware footprints is enabling dual-mode connectivity that switches between cellular and direct short-range communication without separate antenna arrays.
The EU AI Act's risk-based classification system is imposing documentation requirements on automated driver scoring algorithms. Fleet management software vendors must maintain technical files demonstrating bias testing and human oversight protocols. Driver Behavior Monitoring solutions face the steepest compliance burdens as insurers tie premium calculations to algorithmic outputs.
Mid-sized logistics operators are consolidating vendor relationships around integrated platform providers rather than point solutions. The shift compresses procurement cycles from multi-year hardware refresh schedules toward continuous SaaS subscription models. This pattern is most visible in the Netherlands and Belgium where fleet sizes between 50 and 200 vehicles dominate the addressable market.
Europe Commercial Vehicle Telematics Market Segmentation
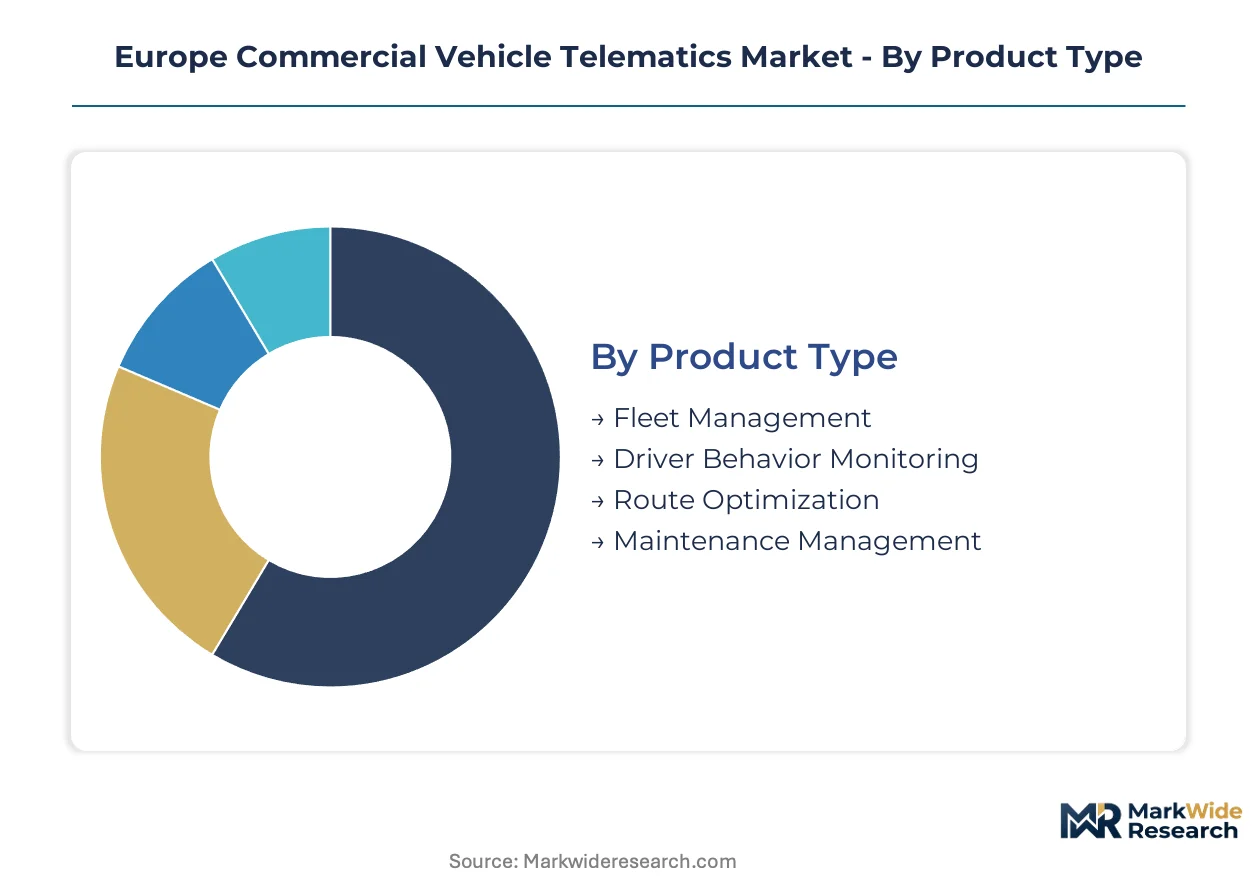
European fleet operators select telematics configurations based on regulatory compliance burdens and route density patterns. Segmentation reveals how embedded OEM partnerships diverge from aftermarket channels across hardware-software combinations.
Product Type:
Fleet Management solutions flow primarily through SaaS subscription channels, while Driver Behavior Monitoring penetrates via insurer partnerships and compliance bundling.
- Fleet Management:Integrated hardware-software systems capture vehicle location, fuel consumption, and engine diagnostics through CAN bus interfaces. Demand concentrates among mid-sized logistics operators in the Netherlands and Belgium seeking EU Green Deal emissions compliance.
- Driver Behavior Monitoring:Telematics platforms algorithmically score acceleration, braking, and cornering patterns for safety verification. German and Polish fleets adopt these systems to satisfy EMA working time validation and usage-based insurance requirements.
- Route Optimization:Real-time traffic integration with delivery scheduling reduces empty mileage for last-mile operators.
- Maintenance Management:Predictive algorithms process engine fault codes to schedule service intervals before breakdown.
By volume, Fleet Management leads. By growth pace, Driver Behavior Monitoring is expanding most quickly.
Technology:
Technology selection tracks cost tier differentiation, with premium deployments embedding multiple sensor modalities and economy tiers relying on single-source positioning.
- GPS Tracking:Satellite positioning modules provide location telemetry with meter-level accuracy for asset recovery and geofencing enforcement. Adoption saturates among construction equipment renters in France and Spain seeking theft prevention.
- Cloud Computing:Centralized data architectures enable API ecosystem expansion and third-party analytics integration. Benelux logistics corridors drive concentration here, as dense freight flows justify real-time platform investments.
- Wireless Communication:Cellular modems transmit vehicle data to fleet management portals.
- On-Board Diagnostics:OBD-II and heavy-duty J1939 interfaces extract engine performance parameters.
Cloud Computing commands the largest revenue share. GPS Tracking delivers the steepest expansion trajectory in aftermarket retrofit installations.
End User:
Customer type segmentation maps to application maturity, with logistics providers running the most sophisticated multi-modal deployments and public transport operators trailing in connected fleet adoption.
- Logistics Providers:Full-stack telematics integration spans route planning, driver compliance, and emissions reporting. Rotterdam-Antwerp-Lille freight corridors generate concentrated demand for 50-200 vehicle fleets.
- Public Transport Operators:Municipal bus and tram fleets deploy location tracking and passenger counting systems. Italian and German urban networks lead adoption driven by service reliability mandates.
- Construction Companies:Equipment telematics tracks engine hours and unauthorized use for yellow iron assets.
- Delivery Services:Last-mile van fleets prioritize real-time customer notification and proof-of-delivery capture.
Logistics Providers anchor volume. Delivery Services are climbing the fastest as e-commerce fulfillment networks expand.
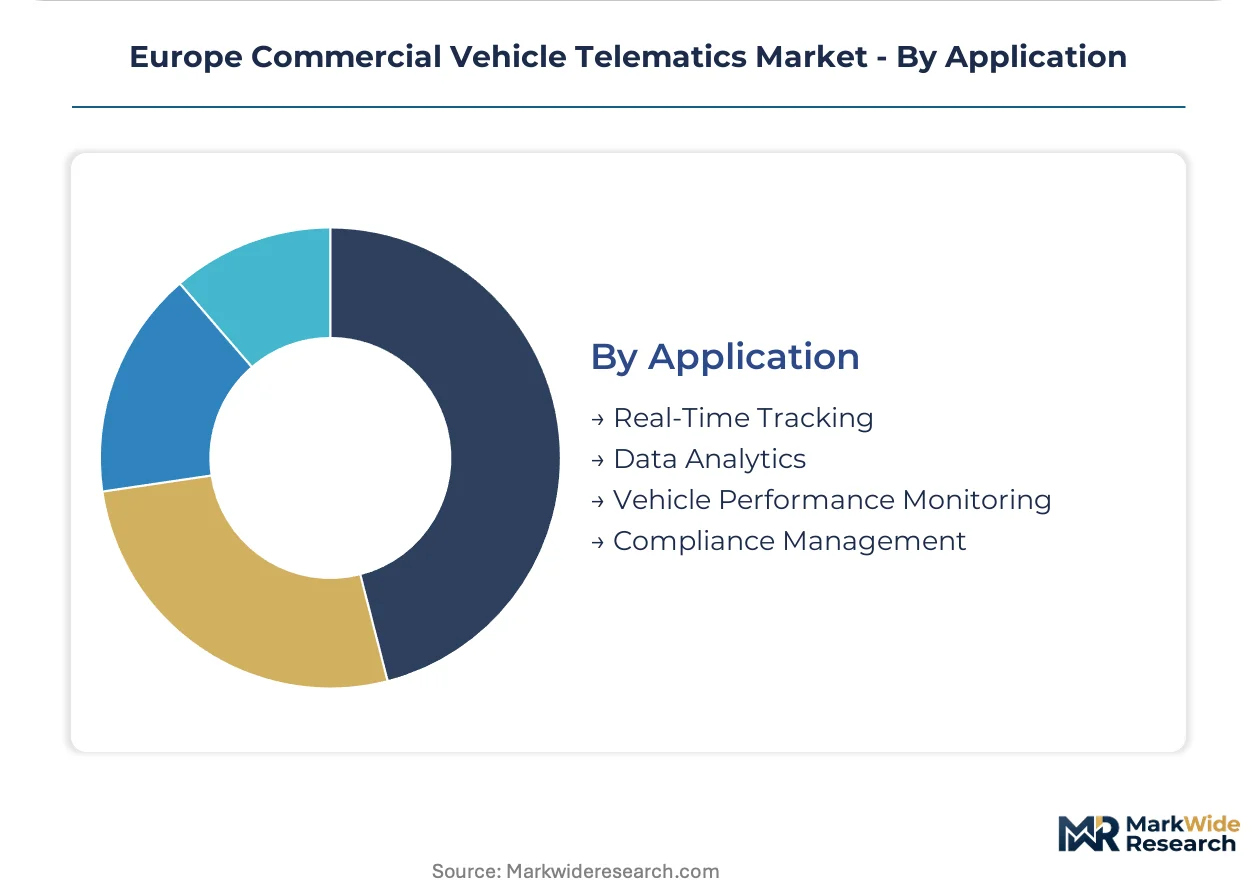
Application:
Application segmentation reflects margin pool distribution, with data-intensive analytics commanding premium pricing and basic tracking functions commoditizing.
- Real-Time Tracking:Continuous location updates enable dispatch optimization and theft recovery for high-value cargo. Polish and Romanian trucking markets show rising penetration as fleet digitization accelerates.
- Data Analytics:Aggregated telematics feeds power fuel efficiency benchmarking and driver performance league tables. German fleet operators invest here to satisfy CSRD disclosure requirements for Scope 3 emissions verification.
- Vehicle Performance Monitoring:Engine health dashboards display fault codes and maintenance alerts.
- Compliance Management:Automated tachograph integration enforces driving hour regulations across cross-border routes.
Real-Time Tracking leads by installation base. Data Analytics is gaining share fastest as sustainability reporting obligations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freight flows from Rotterdam through Antwerp to Lille concentrate telematics demand across the Netherlands, Belgium, and northern France. German logistics operators export fleet optimization services eastward into Polish and Romanian markets.
Germany
KBA enforcement of EU Green Deal CO2 tracking compresses fleet technology refresh cycles among heavy-duty operators. The EU AI Act imposes algorithmic transparency requirements on automated driver scoring systems deployed by domestic platforms. Munich and Stuttgart anchor embedded OEM partnerships where truck manufacturers integrate telematics control units into 2026 model year production.
Netherlands
Rotterdam port logistics generates dense demand for real-time cargo tracking among 50-200 vehicle mid-sized fleets. GDPR data localization rules constrain cloud-native platform architectures serving cross-border operators. The Randstad corridor concentrates SaaS subscription growth as logistics providers consolidate vendor relationships around integrated platforms.
Belgium
Antwerp's chemical and container freight flows drive predictive maintenance adoption for high-asset-utilization fleets. EMA working time validation requirements mandate digital tachograph integration with telematics platforms on France-Germany cross-border routes. Flemish logistics clusters around Ghent and Leuven exhibit fastest uptake of usage-based insurance tied to telematics-verified safety scores.
France
Paris-based fleet operators face ANSM and CNIL oversight intersecting with EU AI Act automated decision-making disclosures. The country's national transport authority enforces driving hour compliance across routes into Germany and Spain. Île-de-France and Hauts-de-France logistics hubs prioritize CSRD-aligned emissions reporting for Scope 3 verification in procurement contracts.
Poland
Underpenetrated trucking markets between Warsaw and Kraków present aftermarket channel expansion opportunities for retrofit hardware providers. National transport authority enforcement of EMA guidelines accelerates digital tachograph adoption among cross-border operators. Silesian industrial corridors generate emerging demand for construction equipment telematics tracking engine hours and unauthorized use.
Europe Commercial Vehicle Telematics Market Competitive Landscape
Listed leaders compete with private specialists across embedded OEM and aftermarket channel strategies. The vendor base fragments across hardware manufacturers, SaaS platform providers, and insurer-aligned data analytics firms. Three archetypes dominate: truck OEMs with captive telematics units, independent cloud-native platform specialists, and mobile network operator-backed fleet management divisions. M&A activity concentrates on acquiring API ecosystem capabilities, while geographic expansion targets Eastern European white space.
Within the independent platform tier, Masternaut and Webfleet Solutions exemplify cloud-native architecture approaches serving mid-sized logistics fleets. Targa Telematics occupies a position among embedded specialists through partnerships with Italian and German truck manufacturers. These three entities represent divergent channel strategies—aftermarket SaaS subscriptions, OEM-integrated hardware-software bundles, and insurer-partnered safety scoring platforms—without any single archetype commanding majority position.
| Leading Market Players |
|---|
| Volvo Trucks |
| Masternaut |
| Targa Telematics |
| Lytx |
| ABAX |
| Webfleet Solutions |
| Trimble |
| Fleetmatics |
| Verizon Connect |
| Others |
Supply & Pricing Matrix
UNECE R155 vehicle cybersecurity certification gates hardware supplier qualification while simultaneously stratifying pricing tiers across embedded and aftermarket channels. Fleet operators in Germany and the Netherlands face divergent cost structures depending on whether telematics units ship factory-installed or require retrofit installation.
Pricing Analysis
Next-generation 5G-enabled telematics hardware commands premium positioning over 4G legacy units and emerging satellite-backup configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in economy-tier cellular modems is intensifying because Asian foundry capacity expansion outpaces European demand growth. Mid-sized logistics fleets with 50-200 vehicles exhibit highest price sensitivity, while heavy-duty operators under EU Green Deal mandates absorb premium pricing for compliance-embedded systems.
Supply Chain Analysis
Taiwan Strait shipping lanes bottleneck cellular modem chip delivery schedules for European hardware assemblers. Semiconductor fabrication concentrates in Taiwan, South Korea, and mainland China, while final system integration localizes in Germany, Poland, and the Czech Republic. Raw material dependencies span silicon wafers, rare-earth magnets for antenna assemblies, and lithium cells for backup power. Single-source vulnerability in baseband processor sourcing exposes vendors to geopolitical disruption. Distribution runs through Tier 1 automotive suppliers and direct OEM procurement channels into captive telematics units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal enforcement deadlines compress fleet technology refresh cycles into a narrow adoption window, creating concentrated growth inflection for compliant platform providers. The regulatory mandate reconfigures procurement priorities across mid-sized logistics operators.
For Market Incumbents: Compound cloud-native architecture advantages through API ecosystem expansion targeting insurer data partnerships. Deepen embedded OEM relationships with Italian and German truck manufacturers before 2026 model year platform lock-in. Counter aftermarket price erosion by bundling predictive maintenance algorithms with hardware subscriptions. For New Entrants and Emerging Players: Lead with usage-based insurance integration as the go-to-market wedge into Polish and Romanian aftermarket white space. Target underpenetrated 50-vehicle construction fleets in Silesian industrial corridors with equipment-focused telematics tracking engine hours and unauthorized use. Differentiate through GDPR-compliant edge computing architectures that minimize cross-border data transfer exposure. For Investors and Strategic Acquirers: EU AI Act algorithmic transparency requirements reshape the acquisition landscape toward vendors with pre-validated driver scoring documentation. Long-term viability hinges on SaaS recurring revenue density rather than hardware shipment volume. Monitor EMA working time validation enforcement intensity across France-Germany-Poland corridors as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded OEM Partnership Expansion | Locks in 2026 model year platform integration with German and Italian truck manufacturers. |
| API Ecosystem Development | Enables insurer data monetization through telematics-verified safety score distribution. |
| Edge Computing Architecture Migration | Addresses GDPR localization constraints while reducing cloud infrastructure latency. |
| Eastern European Channel Buildout | Captures aftermarket retrofit demand in underpenetrated Polish and Romanian trucking markets. |
| CSRD Reporting Integration | Positions telematics data as Scope 3 emissions verification for logistics procurement departments. |
Research Methodology
A standing panel of fleet operations directors, telematics platform product managers, insurer risk analytics leads, and EU regulatory affairs specialists provided ongoing calibration throughout the study period. Primary interviews with these practitioners combined with secondary validation against EMA enforcement bulletins, KBA type-approval databases, EU Green Deal implementation guidance, and customs trade data for cellular modem imports. Bottom-up fleet penetration modeling triangulated against top-down market sizing from automotive production registrations.
Consistency checks validated volume and value outputs against external benchmarks including vehicle registration databases and SaaS subscription disclosure patterns. The analytical framework segmented across hardware-software configuration, fleet size tier, regulatory compliance burden, and geographic corridor density throughout the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in comparable fleet technology categories. Industry-specific forecast inputs incorporated digital tachograph integration mandates and 5G network rollout timelines.
Underlying assumptions cover EMA enforcement intensity, semiconductor supply normalization, and GDPR interpretation stability, with deviation risk concentrated in EU AI Act implementation timing and geopolitical disruption to Asian foundry output. Practitioners should keep alternative scenarios live as CSRD disclosure scope expansion and carbon border adjustment mechanisms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Global Intelligent Transportation System (ITS) Market
Telematics and Infotainment
Automotive Data Monetization Market
Telematics and Infotainment
V2X Communication Module Market
Telematics and Infotainment
Motorcycle Infotainment System Market
Telematics and Infotainment
Commercial Vehicle Telematics Market
Telematics and Infotainment
Europe Automotive Navigation System Market
Telematics and Infotainment
Telematics Market
Telematics and Infotainment
Dashboard Camera Market
Telematics and Infotainment
Europe Vehicle Remote Diagnostic Market
Telematics and Infotainment
Automotive Dashboard Camera Market
Telematics and Infotainment
Park Assist Camera Market
Telematics and Infotainment
In Car Infotainment System Market
Telematics and Infotainment
In Vehicle Infotainment Market
Telematics and Infotainment
Global Automotive Infotainment System Market
Telematics and Infotainment
Vehicle to Vehicle (V2V) Communication Market
Telematics and Infotainment
APAC Internet of Cars Market