
 Automotive Dashboard Camera Market | 2026-2036
Automotive Dashboard Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Dashboard Camera Market Analysis
Fleet operator procurement consolidation is recalibrating volume concentration toward large commercial buyers with standardized telematics requirements. Garmin Ltd leverages its aviation-derived GPS architecture to anchor premium positioning in North American fleet channels. Panasonic Corporation dominates OEM supply relationships through captive manufacturing scale and direct vehicle platform integration. Thinkware Corporation specializes in Korean domestic market distribution while extending its cloud-connected service layer into European insurance partnerships.
An automotive dashboard camera is a windshield-mounted digital video recorder capturing forward-facing and cabin footage with loop storage, G-sensor event locking, and typically 1080p to 4K resolution at 30-60 frames per second; its primary function is to provide objective collision evidence, driver behavior documentation, and automated incident alerts for liability reduction and fleet risk management. Single-channel devices still occupy the highest shipment volumes due to cost-sensitive individual buyers, though multi-channel configurations integrating cabin and rear views are capturing margin pools from commercial fleets requiring comprehensive coverage. GPS-enabled technology leads attach rates as insurers and fleet operators demand geospatial correlation with video evidence, while 4K resolution remains a premium tier where memory cost and processing overhead limit mass penetration.
NHTSA event data recorder guidelines, EU GDPR provisions on biometric and location data processing, and China's MIIT connected vehicle security standards collectively shape product architecture, data governance obligations, and cross-border market access requirements for dashboard camera manufacturers. GDPR's strict consent and retention protocols force European vendors to engineer localized storage and encryption capabilities that increase bill-of-materials complexity. Stakeholders must monitor whether emerging EU type-approval frameworks for intelligent transport systems will mandate dashboard cameras as standard equipment, fundamentally shifting volume from aftermarket replacement to factory-installed base.
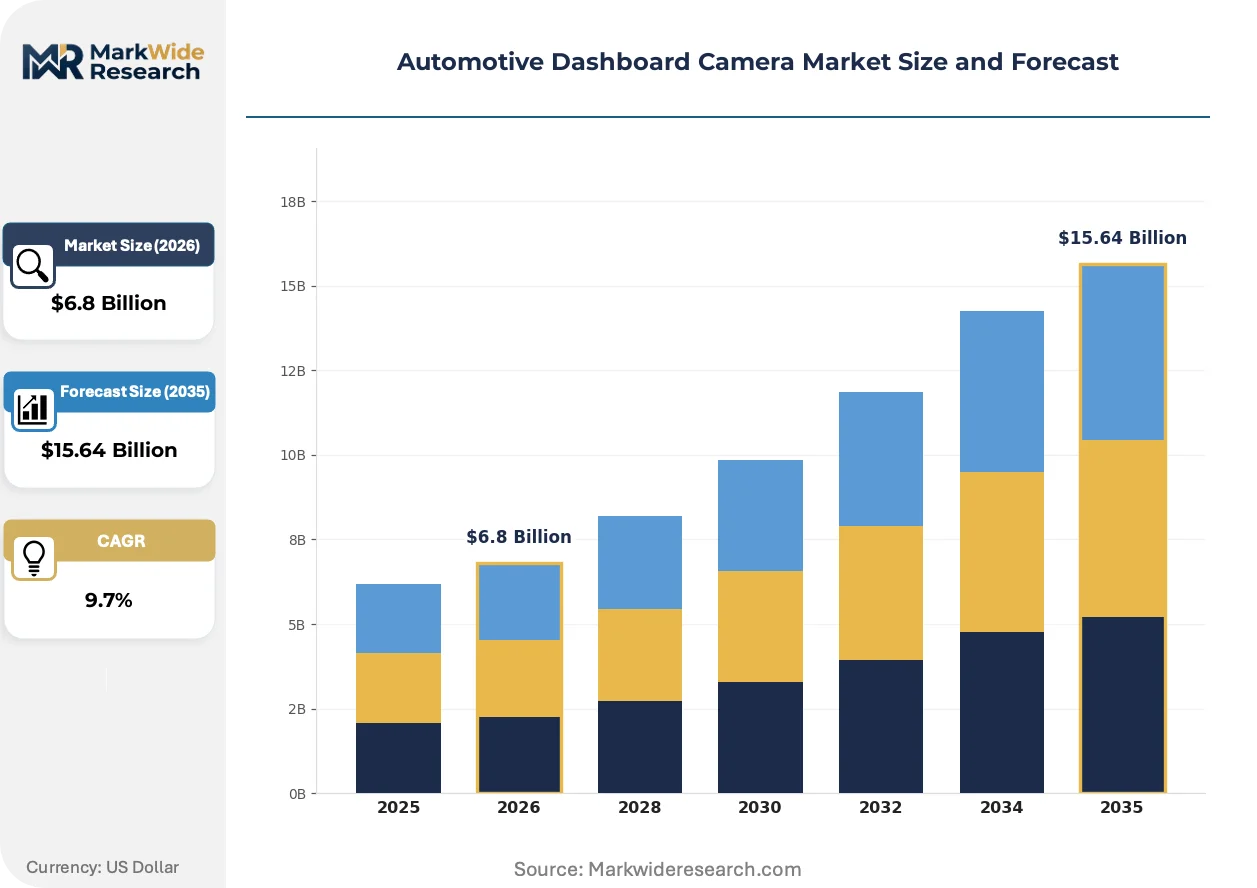
Market Dynamics
Fleet telematics integration is compressing procurement cycles and forcing dashboard camera vendors to embed cellular connectivity and cloud APIs as baseline capabilities rather than premium add-ons.
Growth Catalysts
- EU Intelligent Transport Systems Mandates:Emerging type-approval frameworks for commercial vehicle safety equipment are creating regulatory pull for factory-installed event recording systems.
- Chinese OEM Factory Embedding:Domestic automakers and ride-hailing platforms in China are pre-installing dual-channel cameras at vehicle assembly, eliminating aftermarket installation friction.
- 4K Sensor Cost Curves:CMOS image sensor foundry scale is reducing bill-of-materials premiums for high-resolution capture, enabling margin expansion in premium fleet segments.
Market Restraints
- NAND Flash Supply Concentration:Memory module sourcing depends on Korean and Taiwanese foundry output, exposing vendors to input cost volatility during supply shocks.
- GDPR Data Localization Burden:EU biometric and geospatial data retention rules force European deployments to engineer encrypted edge storage, adding hardware complexity.
- Smartphone Dash Cam Apps:Software-based alternatives using mobile device cameras threaten low-end single-channel aftermarket volume in price-sensitive consumer segments.
Strategic Opportunities
- India Commercial Fleet Underpenetration:Long-haul trucking and logistics operators in India lack systematic video telematics adoption, creating first-mover channel establishment potential.
- ADAS Sensor Fusion Convergence:Integration of dash cam video streams with radar and lidar perception stacks enables unified driver monitoring for autonomous vehicle development programs.
- Usage-Based Insurance Partnerships:European insurers are piloting connected camera data for dynamic premium pricing, opening B2B2C distribution through underwriting channels.
Industry Challenges
- Embedded Software Talent Scarcity:Vendors struggle to recruit firmware engineers capable of optimizing real-time video encoding for thermal-constrained automotive environments.
- OEM Integration Timelines:Factory installation requires 24-36 month platform validation cycles, compressing revenue recognition windows for new product generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Dashboard Camera Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.64 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Channel, Multi Channel, Rear View, 360-Degree Technology: HD, 4K, Night Vision, GPS Enabled End User: OEMs, Fleet Operators, Individual Customers, Insurance Companies Distribution Channel: Online Retail, Offline Retail, Direct Sales, Subscription Services |
| Companies Covered | Pittasoft Co., Ltd., Vantrue Technology Co., Ltd., Garmin Ltd, Samsung Electronics Co., Ltd., VIOFO Ltd., Nextbase Global Ltd, Panasonic Corporation, BlackVue, Thinkware Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Dashboard Camera Market Emerging Trajectories
Edge AI inference is migrating from cloud servers to camera hardware, enabling real-time incident detection without cellular latency and reshaping how fleet operators configure alert thresholds.
On-device neural processing units are decentralizing video analytics execution from centralized fleet management platforms. Logistics operators with dispersed vehicle networks are deploying these chips to trigger event locks within milliseconds of collision detection. This architecture is decentralizing data transmission costs and reducing dependence on continuous connectivity.
China's MIIT connected vehicle security standards are mandating cryptographic authentication for over-the-air firmware updates in dashboard cameras. Manufacturers must now embed hardware security modules and certificate management infrastructure. Commercial vehicle platforms in China are responding by consolidating supplier relationships around vendors with established automotive cybersecurity certifications.
Fleet procurement departments are consolidating vendor relationships and demanding outcome-based contracts tying camera system fees to measurable collision frequency reduction. Third-party fleet management platforms are displacing direct OEM relationships as the primary purchasing channel. This pattern is most visible in North American long-haul trucking where large operators negotiate enterprise-wide telematics agreements.
Automotive Dashboard Camera Market Segmentation
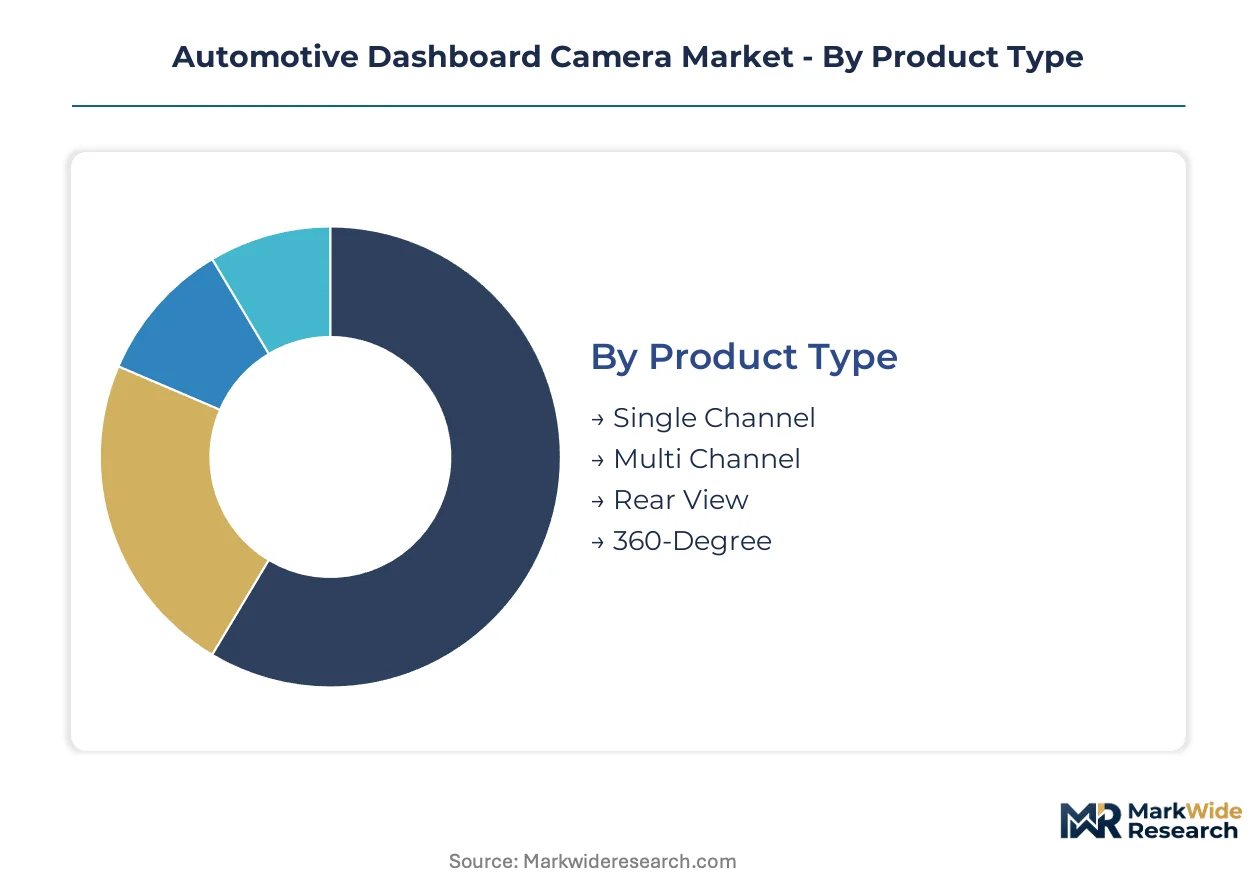
Segmentation in automotive dashboard cameras reveals how procurement patterns diverge between cost-sensitive individual buyers and enterprise fleets demanding integrated telematics. Product architecture and distribution channel choices directly determine margin capture and customer lifetime value across these divergent buyer profiles.
Product Type:
Upgrade cycles in this category accelerate as fleet operators replace single-channel units with multi-channel configurations to satisfy comprehensive coverage mandates from insurers and safety regulators.
- Single Channel:Forward-facing devices with 1080p recording and loop storage dominate individual consumer purchases through retail channels. Cost engineering pressures limit attach rates for premium features in this tier.
- Multi Channel:Dual-lens systems capturing cabin and forward views command fleet procurement preference where driver behavior monitoring and collision evidence requirements converge. North American long-haul trucking operators specify these configurations in enterprise telematics tenders.
- Rear View:Supplementary rear-facing modules integrate with existing front units to close coverage gaps in parking incidents and rear-end collisions. Aftermarket installation friction limits adoption outside factory-embedded deployments.
- 360-Degree:Multi-sensor panoramic capture systems serve premium vehicle platforms and autonomous development programs requiring complete environmental recording. Sensor fusion complexity and calibration overhead restrict volume to specialized applications.
Single Channel sits at the top of the volume ranking, with Multi Channel climbing the fastest.
Technology:
Cost tier differentiation in imaging technology separates premium fleet deployments from economy individual purchases, with sensor specifications determining archival utility and insurance admissibility.
- HD:1080p resolution at 30 frames per second remains the baseline specification for price-sensitive consumer segments. Memory cost efficiency and broad device compatibility sustain this technology's position in high-volume markets.
- 4K:Ultra-high-definition capture enables license plate readability at extended distances and supports forensic zoom requirements in commercial liability disputes. CMOS sensor foundry scale is compressing bill-of-materials premiums for fleet-specified installations.
- Night Vision:Infrared illumination and low-light sensor optimization address critical evidence gaps in dusk and nighttime incidents. Commercial operators in northern latitudes specify this capability for winter darkness coverage.
- GPS Enabled:Geospatial metadata embedding correlates video timestamps with precise location coordinates for fleet route verification and accident reconstruction. Insurers mandate this technology for usage-based premium programs.
HD maintains volume leadership, while GPS Enabled gains share fastest as telematics integration becomes standard practice.
End User:
Application-specific requirements reshape product specifications, with enterprise buyers demanding cloud connectivity and API integration that individual consumers rarely utilize.
- OEMs:Factory installation at vehicle assembly requires 24-36 month platform validation cycles and automotive-grade component qualification. Chinese domestic automakers are embedding dual-channel systems at the production line to eliminate aftermarket friction.
- Fleet Operators:Enterprise procurement of connected dash cam systems with cellular uplink and centralized fleet management platform integration. Telematics providers are consolidating camera vendors into bundled service agreements.
- Individual Customers:Retail purchasers prioritizing cost minimization and simple installation over advanced connectivity features. Smartphone dash cam applications threaten this segment's low-end volume.
- Insurance Companies:Underwriting channel partnerships distributing connected cameras to policyholders for dynamic premium pricing and claims verification. European pilot programs are expanding this B2B2C distribution model.
Fleet Operators anchor current volume concentration, with Insurance Companies expanding most quickly through underwriting channel partnerships.
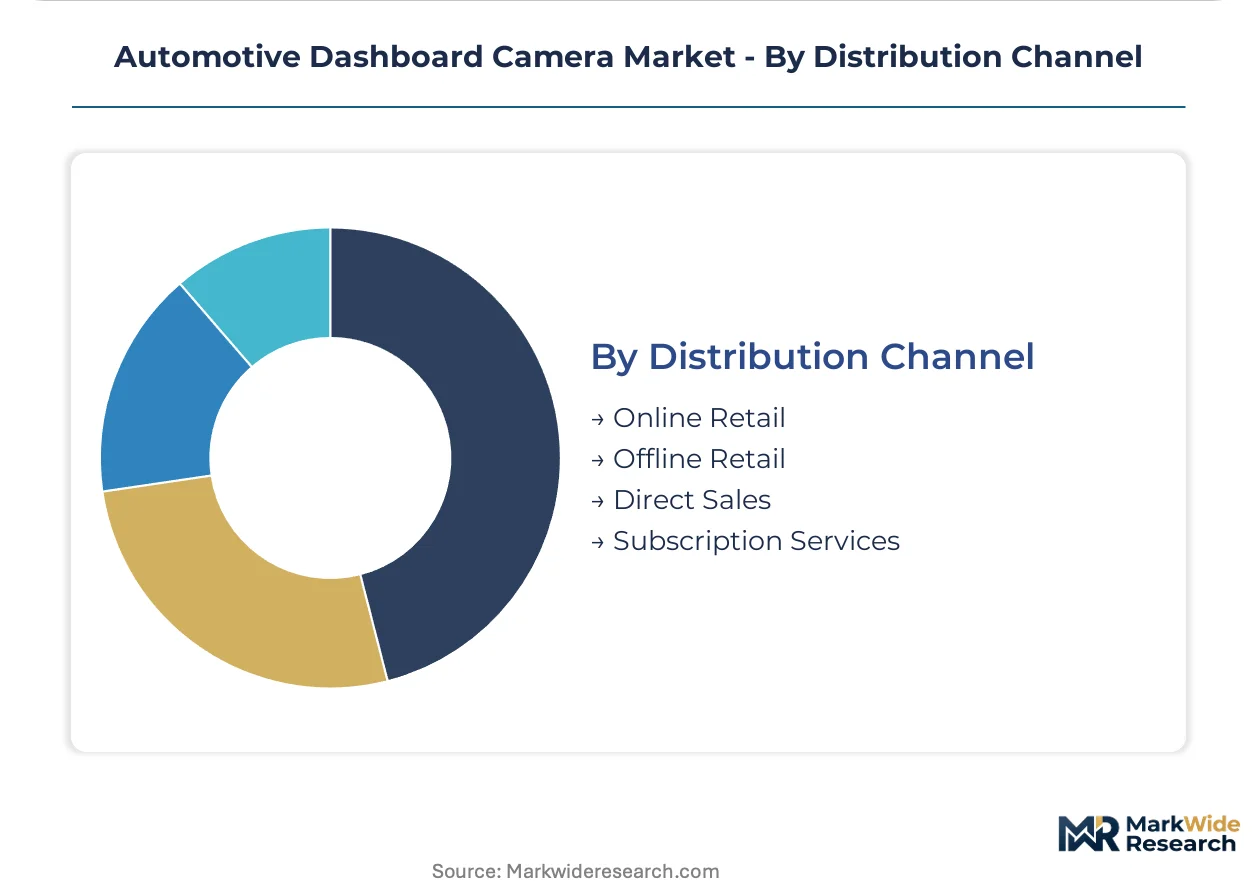
Distribution Channel:
Customer type determines channel preference, with enterprise procurement consolidating through direct vendor relationships while individuals fragment across retail touchpoints.
- Online Retail:E-commerce platforms serving individual buyers with comparison shopping and installation tutorial resources. Return rates exceed offline channels due to compatibility confusion and mounting difficulty.
- Offline Retail:Electronics retailers and automotive aftermarket specialists providing hands-on product demonstration and installation services. Staff expertise gaps limit upselling of connected features.
- Direct Sales:Enterprise account teams negotiating multi-year telematics agreements with fleet procurement departments. Outcome-based contracts tying fees to collision frequency reduction are emerging in North American trucking.
- Subscription Services:Recurring-revenue models bundling hardware, cellular connectivity, and cloud storage for commercial operators. Third-party fleet management platforms are displacing direct OEM relationships as primary purchasing channels.
Online Retail leads transaction volume, with Subscription Services gaining share fastest as fleet operators shift toward operational expenditure models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's factory-embedding surge contrasts with the United States' fleet telematics consolidation, revealing divergent pathways for dashboard camera penetration. Germany anchors European regulatory momentum through GDPR-compliant architectures. South Korea and Japan supply critical sensor and memory components while building distinct domestic demand profiles.
United States
Long-haul trucking fleets and ride-share operators drive enterprise procurement of connected dual-channel systems. NHTSA event data recorder guidelines shape product specifications for commercial vehicle deployments. Detroit-area automotive suppliers integrate camera modules into factory telematics stacks for domestic OEM programs.
China
Domestic automakers and Didi-style ride-hailing platforms embed dashboard cameras at assembly lines, eliminating aftermarket friction. MIIT connected vehicle security standards mandate cryptographic authentication for over-the-air firmware updates. Shenzhen hardware clusters manufacture AI-enabled edge processing units for both local consumption and export markets.
Germany
Commercial fleets and insurance partnerships propel demand for GDPR-compliant recording systems with encrypted edge storage. EU intelligent transport systems frameworks under development may mandate factory-installed event recording for commercial vehicles. Stuttgart automotive engineering centers validate camera integration for premium vehicle platforms.
South Korea
Memory module supply concentration and domestic fleet digitization create dual demand channels. MFDS-equivalent automotive safety frameworks influence component qualification standards. Seoul metropolitan area logistics operators pilot cloud-connected camera systems for delivery fleet optimization.
Japan
Precision sensor manufacturing and aging driver safety programs sustain market development. METI industrial standards guide automotive electronics certification processes. Nagoya automotive supplier corridors refine camera-to-vehicle network integration for next-generation mobility platforms.
Automotive Dashboard Camera Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Electronics conglomerates leverage captive semiconductor supply and automotive customer relationships. Pure-play vendors concentrate on firmware optimization and cloud service differentiation. Scale-driven consolidation and telematics platform partnerships represent the dominant competitive vectors reshaping vendor rankings.
Among Asia-Pacific component and systems suppliers, Pittasoft Co., Ltd., Samsung Electronics Co., Ltd., and Thinkware Corporation exemplify distinct strategic postures. Pittasoft anchors Korean pure-play specialization. Samsung Electronics occupies a diversified conglomerate position spanning memory supply through system integration. Thinkware represents mid-tier vendors extending service-layer capabilities into insurance and fleet channels.
| Leading Market Players |
|---|
| Pittasoft Co., Ltd. |
| Vantrue Technology Co., Ltd. |
| Garmin Ltd |
| Samsung Electronics Co., Ltd. |
| VIOFO Ltd. |
| Nextbase Global Ltd |
| Panasonic Corporation |
| BlackVue |
| Thinkware Corporation |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up fleet telematics specialists anchor supply discipline through captive manufacturing relationships in Shenzhen and Taipei, compressing component procurement costs while enforcing subscription-tier pricing that separates enterprise fleet deployments from retail consumer tiers.
Pricing Analysis
Capacity additions in Chinese CMOS sensor foundries are reshaping price floors for 4K imaging modules, enabling margin expansion in premium fleet segments while cost compression intensifies in single-channel consumer tiers. Three-tier pricing structure across premium, standard, and economy levels separates GPS-enabled multi-channel fleet systems from basic HD retail units, with certification grade for NHTSA event data recorder compliance commanding substantial premiums. Pricing pressure stems from smartphone dash cam applications threatening low-end aftermarket volume. Individual customers exhibit highest price sensitivity, while fleet operators prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Workforce availability constraints in Korean and Taiwanese NAND flash foundries limit memory module expansion despite fleet demand acceleration. Component sourcing draws from China for CMOS sensors and edge AI processors, South Korea for memory modules, and Taiwan for semiconductor packaging. Raw material dependencies include silicon wafers, rare earth elements for optical components, and lithium for backup battery cells. Single-source vulnerability concentrates in Korean NAND flash supply. Distribution runs through third-party fleet management platforms consolidating enterprise procurement and e-commerce channels fragmenting retail volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
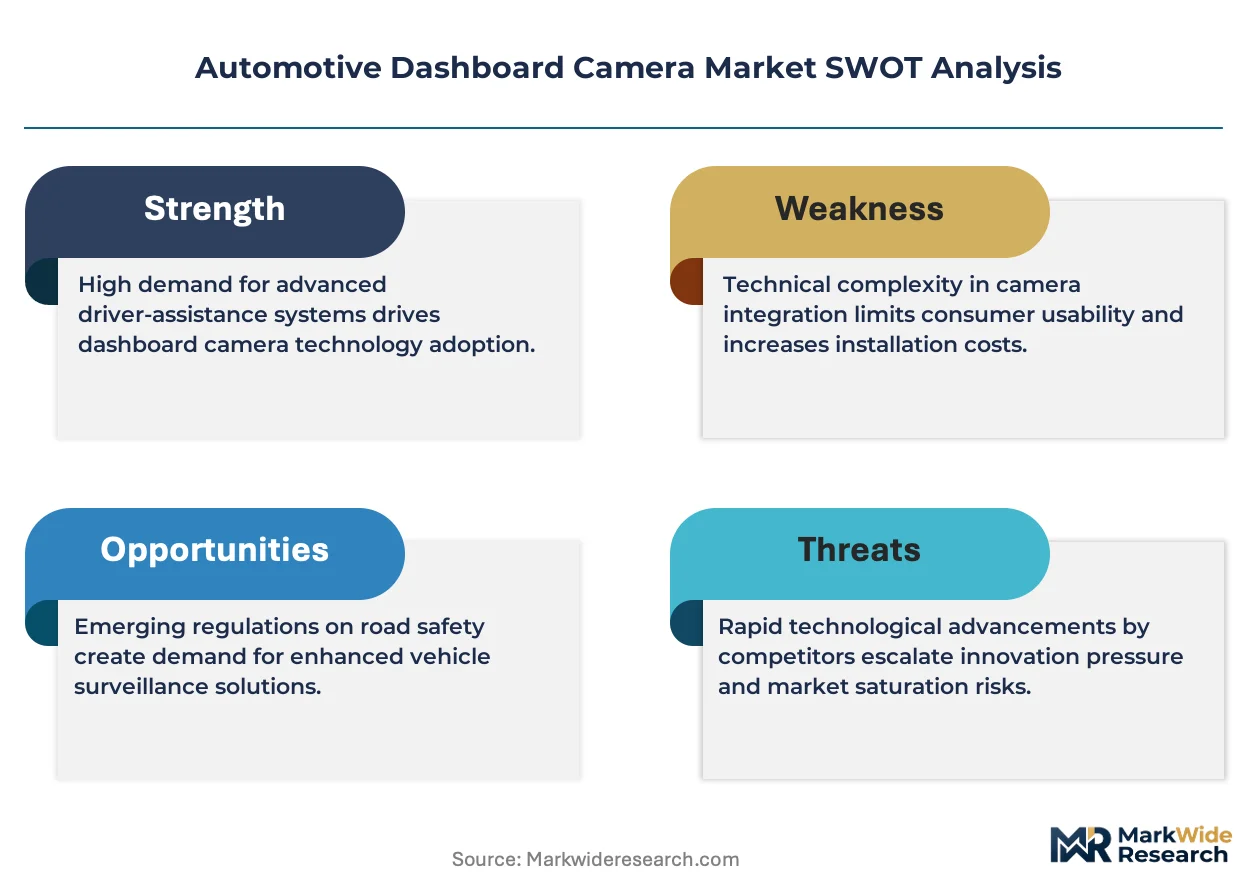
Analyst Recommendations
This market operates as a regulatory compounder where EU intelligent transport systems mandates and NHTSA event data recorder guidelines create structural demand pull independent of economic cycles.
For Market Incumbents: To counter smartphone dash cam applications eroding retail price floors, deepen backward integration into CMOS sensor supply through strategic foundry partnerships in China and accelerate certification investment for EU type-approval frameworks mandating factory-installed event recording systems. For New Entrants and Emerging Players: Begin with India's underpenetrated long-haul trucking sector, where systematic video telematics adoption remains nascent among logistics operators, deploying usage-based insurance partnerships as the primary go-to-market channel to bypass established fleet management platform gatekeepers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier pure-play firmware specialists lacking cloud service differentiation, with long-term viability hinging on embedded software talent retention; monitor EU type-approval framework finalization timing as the critical inflection signal shifting volume from aftermarket replacement to factory-installed base.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Processor Integration | Enables real-time incident detection without cellular latency for dispersed fleet networks. |
| GDPR-Compliant Architecture Deployment | Satisfies EU biometric data retention rules through encrypted edge storage engineering. |
| Telematics Platform Partnership | Secures enterprise procurement channel access as third-party platforms displace direct OEM relationships. |
| Automotive Cybersecurity Certification | Meets China's MIIT cryptographic authentication mandates for over-the-air firmware updates. |
| Insurance Underwriter Alliance | Opens B2B2C distribution through European dynamic premium pricing pilot programs. |
Methodological Framework
Multiple input streams — fleet operator procurement directors, Tier 1 supplier platform engineers, aftermarket distributor operations heads, and insurance underwriting specialists — were reconciled with secondary validation from vehicle production databases, IHS Markit registration data, NHTSA guideline documentation, and EU regulatory framework publications, employing bottom-up shipment volume builds and top-down market sizing triangulation.
Historical volume trajectories were cross-referenced against expert panel assessments across product type, technology tier, end user category, and distribution channel dimensions over the projection horizon, with CAGRs derived from regression analysis of telematics adoption curves and OEM embedding timelines, incorporating fleet management platform consolidation patterns and sensor cost curve assumptions as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including potential EU mandate acceleration beyond current framework timelines and geopolitical disruption to Taiwan semiconductor supply. Forecasts reflect documented assumptions regarding fleet telematics penetration rates and OEM embedding decisions. Practitioners should monitor EU type-approval framework publication timing and NAND flash supply allocation shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Automotive Human Machine Interface (HMI) Market
Telematics and Infotainment
North America Dashboard Camera Market
Telematics and Infotainment
Europe Automotive Navigation System Market
Telematics and Infotainment
Automotive Personal Navigation Systems Market
Telematics and Infotainment
Automotive Navigation & Infotainment Systems Market
Telematics and Infotainment
Global Car Digital Cockpit Market
Telematics and Infotainment
Fleet Telematics System Market
Telematics and Infotainment
Global Carpool-As-A-Service Market
Telematics and Infotainment
India Connected Car Market
Telematics and Infotainment
Car DVR Market
Telematics and Infotainment
Next Generation in-Vehicle Networking (IVN) Market
Telematics and Infotainment
Automotive Navigation Solutions Market
Telematics and Infotainment
Automotive Infotainment Market
Telematics and Infotainment
Telematics-Linked Fleet Battery Health Management Systems Market
Telematics and Infotainment
Advanced Traveller Information System Market
Telematics and Infotainment
North America Automotive Infotainment System Market