
 Dairy Desserts Market | 2026-2036
Dairy Desserts Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Desserts Market Analysis
Single-serve portion bundling is repositioning buyer choice across retail and food service channels, replacing bulk formats with modular multi-packs that reduce waste and improve margin capture. Unilever leverages its frozen dessert portfolio breadth to control shelf-space negotiations in European supermarkets. Nestle anchors premium ice cream positioning through R&D intensity in reduced-sugar formulations. General Mills competes in the North American pudding segment through brand strength in comfort-food positioning.
Dairy desserts comprise processed milk-based formulations—typically containing minimum milk fat thresholds, stabilizers, and sweeteners—that undergo pasteurization, homogenization, and controlled-temperature setting to deliver chilled or frozen finished products for direct consumption. Ice cream leads product type value generation due to established premium-tier pricing and flavor innovation pipelines, while yogurt segments extend fastest through functional positioning around protein and gut-health claims. Distribution through supermarkets still captures the largest margin pools, though online retail segments are deepening penetration in urban markets with cold-chain reliability improvements.
EFSA governs additive and labeling standards for dairy desserts sold across EU member states, while FDA enforces Grade A Pasteurized Milk Ordinance provisions affecting cross-border ingredient sourcing into the United States. India's FSSAI mandates specific milk-solid-not-fat thresholds for frozen dessert classifications, shaping how Fonterra and Danone formulate export-ready products for that market. Stakeholders must monitor evolving clean-label enforcement thresholds and cold-chain infrastructure gaps before committing capacity expansion decisions.
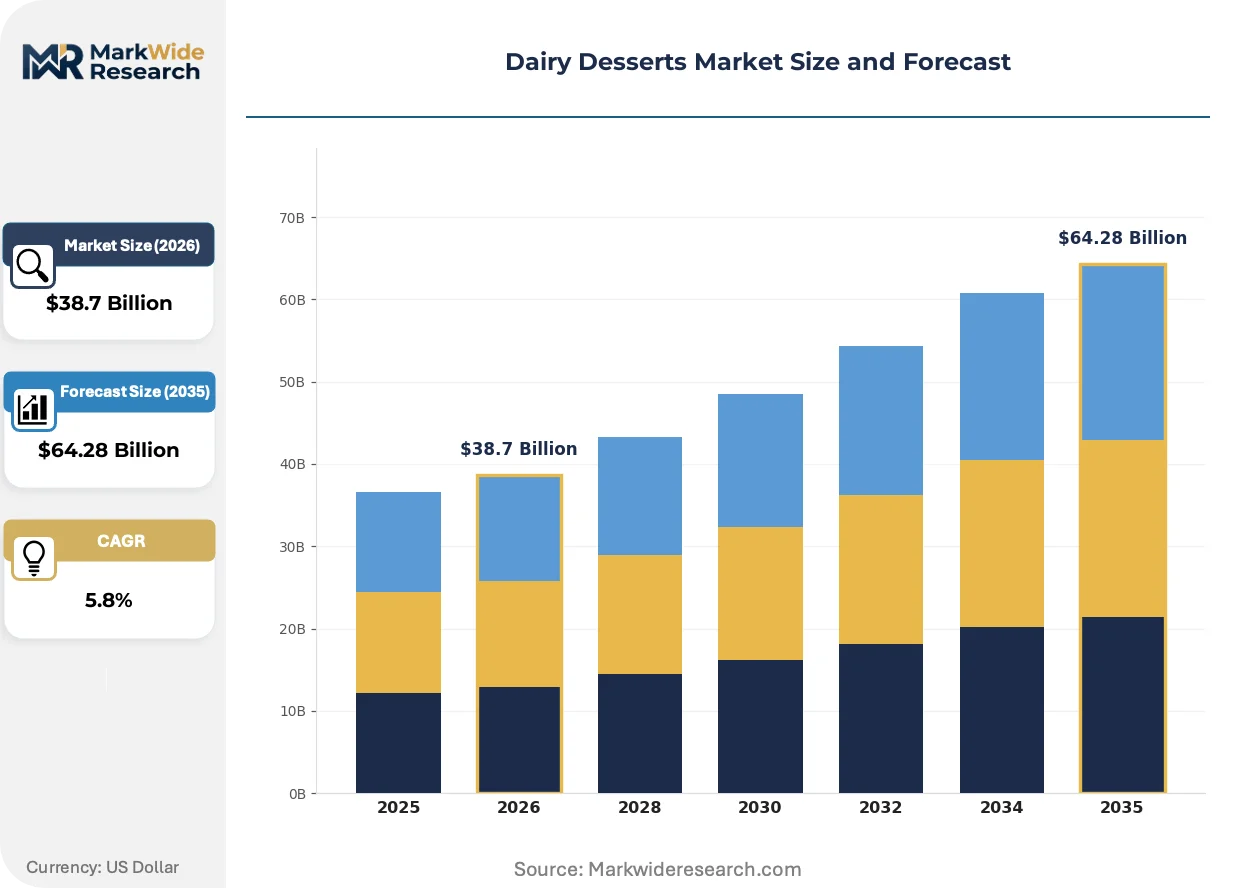
Market Dynamics
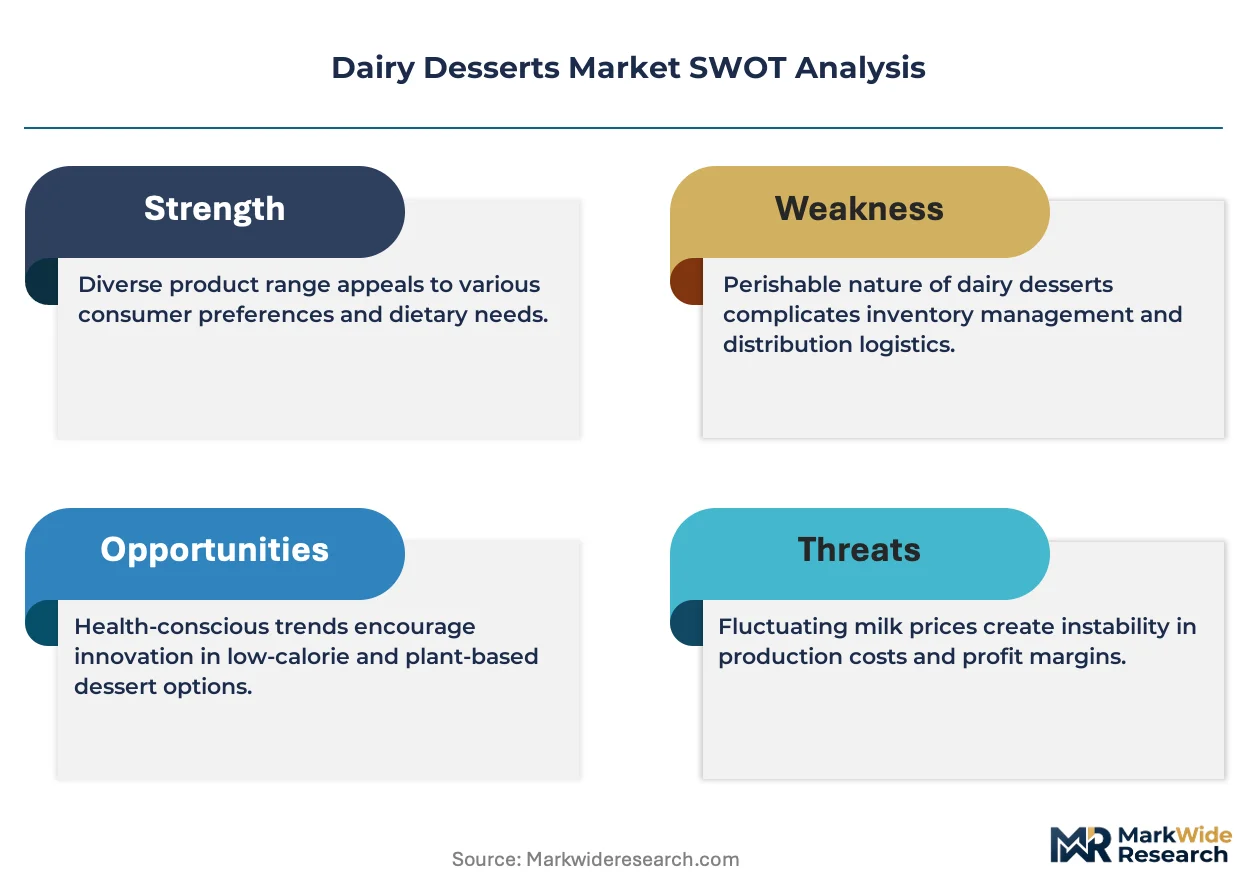
Clean-label ingredient mandates under EFSA and the EU Green Deal are forcing dairy dessert manufacturers to reformulate stabilizer systems and sweetener portfolios, compressing R&D timelines while elevating compliance costs across European production networks.
Growth Catalysts
- Urban Quick-Service Expansion:Bakery chains and QSR operators in India are scaling chilled dairy dessert procurement, creating pull-through demand for portion-controlled formats with extended ambient stability.
- EU Green Deal Alignment:Sustainability-linked financing incentives are accelerating plant-based dairy dessert line extensions as manufacturers seek Scope 3 emission reductions in ingredient sourcing.
- Cold-Chain Infrastructure:Investments in refrigerated last-mile logistics across Southeast Asian urban corridors are unlocking frozen dessert distribution previously constrained by temperature excursion risks.
Market Restraints
- Milk Fat Price Volatility:Global butterfat supply tightness driven by New Zealand and EU production fluctuations is compressing margin structures for premium ice cream formulations.
- Stabilizer Sourcing Concentration:Carrageenan and guar gum supply chains concentrate in South Asian processing hubs, exposing manufacturers to monsoon-dependent harvest variability and export licensing delays.
- FSSAI Classification Rigidity:India's frozen dessert versus ice cream legal distinctions based on milk-solid-not-fat thresholds block formulation flexibility for exporters targeting hybrid positioning.
Strategic Opportunities
- Functional Yogurt White Space:Protein-fortified and gut-health positioned chilled desserts remain underpenetrated in Middle Eastern markets where ambient dairy traditions dominate consumption patterns.
- Direct-to-Consumer Subscription:Cold-chain reliable metro corridors in Brazil and Mexico enable recurring delivery models for premium gelato and artisan ice cream bypassing traditional retail slotting fees.
- Precision Fermentation Inputs:Lab-derived dairy proteins are converging with traditional dessert processing, offering pathway to animal-free claims without sensory compromise in frozen applications.
Industry Challenges
- Clean-Label Reformulation Expertise:Shortage of food technologists skilled in natural stabilizer system design is extending product development cycles as brands phase out synthetic additives under EFSA scrutiny.
- Multi-Temperature Distribution Complexity:Retailers are demanding simultaneous supply of frozen, chilled, and ambient dairy desserts, forcing logistics providers to reconfigure fleet assets and warehouse zoning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Desserts Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yogurt, Pudding, Ice Cream, Cheesecake End User: Retail Customers, Food Service, Bakeries, Catering Services Ingredient Type: Milk, Cream, Sugar, Natural Flavoring Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores |
| Companies Covered | Unilever, Lactalis, Nestle, Arla Foods, Fonterra, Danone, Mondelez International, Kraft Heinz, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Desserts Market Emerging Trajectories
Reformulation priorities are pivoting around texture engineering and sweetness modulation as manufacturers balance regulatory compliance with sensory performance in reduced-sugar and clean-label launches.
High-pressure processing technology is converging with conventional pasteurization in chilled dairy dessert manufacturing, extending shelf life without thermal degradation of protein structures. European premium brands are adopting HPP for refrigerated mousse and custard lines, enabling 60-day coded life without chemical preservatives. This convergence is compressing the competitive window between artisan fresh positioning and mass-market distribution reach.
EFSA's evolving additive authorization timelines under the 2023 flavoring substance re-evaluation program are forcing manufacturers to accelerate natural flavor sourcing transitions ahead of sunset dates for synthetic vanillin and fruit ester compounds. The industrial consequence is supply contract restructuring with botanical extract suppliers in Madagascar and Indonesia. Ice cream and frozen dessert categories face the steepest compliance curves given flavor intensity requirements in low-temperature consumption.
Single-serve multi-pack formats are displacing bulk family-size containers across European and North American retail channels as household size compression and impulse consumption patterns reshape purchase behavior. Supermarkets are reallocating freezer door facings to modular 4-6 count offerings with premium price-per-liter positioning. France and Germany demonstrate the most advanced format rotation, with private-label entrants capturing shelf space previously held by 1.5-liter tubs.
Dairy Desserts Market Segmentation
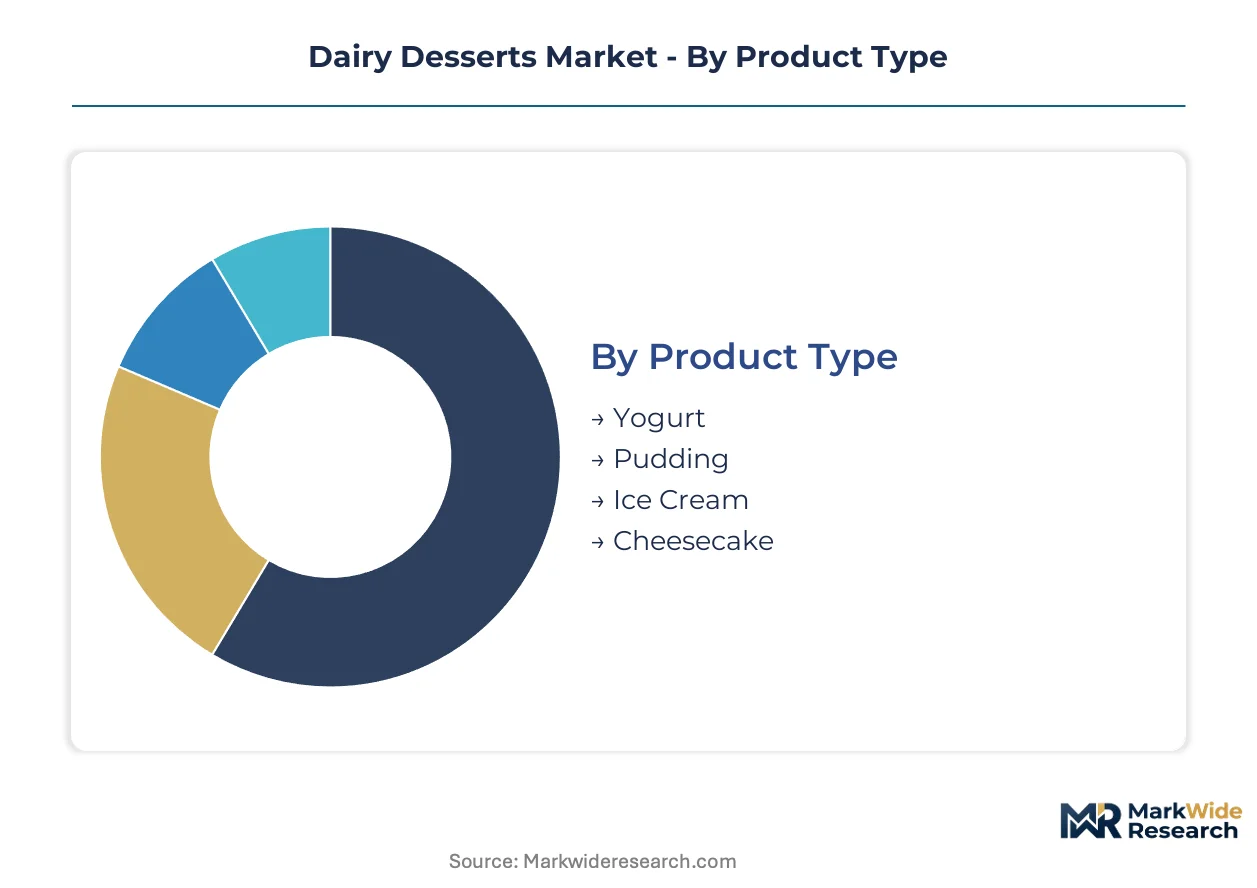
Dairy desserts segment across four interlocking dimensions that determine margin capture and cold-chain investment intensity. Product type and distribution channel choices dictate manufacturing asset configuration, while end-user targeting shapes portion architecture and formulation stability requirements.
Product Type:
Standalone consumption formats dominate retail freezer cases, while embedded dessert components integrate into multi-item food service platters and bakery finished goods.
- Ice Cream:Frozen emulsions requiring minimum milk fat thresholds and controlled overrun rates anchor premium pricing tiers in European and North American retail. Demand concentrates in single-serve multi-pack formats as French and German supermarkets reallocate freezer door facings away from bulk family tubs.
- Yogurt:Cultured dairy bases with live probiotic positioning command functional premium pricing through protein fortification and gut-health claims. Urban Indian bakery chains and quick-service restaurants are scaling procurement of portion-controlled chilled formats with extended ambient stability for out-of-home consumption.
- Pudding:Starch-thickened or egg-based custards serve comfort-food positioning in North American retail channels with reduced-sugar formulation pipelines accelerating.
- Cheesecake:Cream cheese-based formulations span frozen retail sleeves and food service dessert platters, with texture engineering critical for thaw-stable slice integrity.
Volume placements concentrate in ice cream; the faster expansion belongs to yogurt.
End User:
Cost tier differentiation separates commodity procurement at scale from artisan positioning with premium slotting allowances.
- Retail Customers:Individual purchasers selecting single-serve or family formats through supermarket freezer aisles and online platforms with cold-chain reliability requirements. E-commerce penetration deepens in Brazilian and Mexican metro corridors where subscription models bypass traditional retail slotting fees.
- Food Service:Quick-service restaurant operators and institutional feeders sourcing portion-controlled desserts with consistent portion weights and thaw-stable performance. Indian urban QSR expansion is pulling demand for ambient-stable chilled formats.
- Bakeries:Artisan and chain operators integrating dairy desserts as finished components or co-branded offerings, requiring formulation compatibility with ambient display cases.
- Catering Services:Event and institutional feeders demanding bulk formats with extended holding stability and transport resilience for off-premise service.
Margin capture peaks in food service; the steepest volume climb occurs in retail e-commerce channels.
Ingredient Type:
Supply concentration geography determines formulation flexibility under divergent regulatory thresholds for milk-solid-not-fat content.
- Milk:Fluid and condensed dairy bases standardized for protein and fat content, with Fonterra and Danone adjusting export formulations to meet India's FSSAI frozen dessert classification rigidity.
- Cream:High-butterfat inputs compressing margin structures during New Zealand and EU production fluctuations, forcing premium ice cream manufacturers into forward contracting.
- Sugar:Sweetener portfolios undergoing forced reformulation under EFSA clean-label mandates, with natural alternatives replacing synthetic compounds ahead of sunset dates.
- Natural Flavoring:Botanical extracts from Madagascar and Indonesia restructuring supply contracts as EFSA's flavoring substance re-evaluation program accelerates natural sourcing transitions.
Input cost volatility concentrates in cream; the most rapid specification change is occurring in natural flavoring.
Distribution Channel:
Customer type separation between planned pantry stock-up and impulse convenience purchase dictates packaging format and temperature protocol.
- Supermarkets:Multi-temperature zone retailers demanding simultaneous frozen, chilled, and ambient dairy dessert supply, forcing logistics reconfiguration of fleet assets and warehouse zoning.
- Online Retail:Direct-to-consumer platforms requiring last-mile cold-chain reliability investments across Southeast Asian urban corridors previously constrained by temperature excursion risks.
- Specialty Stores:Premium gelato and artisan ice cream boutiques in European city centers with high-pressure processing adoption for extended shelf-life refrigerated lines.
- Convenience Stores:Impulse-oriented freezer facings for single-serve formats with premium price-per-liter positioning in high-footfall urban locations.
Revenue concentration remains in supermarkets; the fastest share gain is occurring in online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in New Zealand and the European Union supply butterfat and milk solids to consumption markets where urbanization and quick-service expansion are reshaping demand patterns. India imports significant volumes while building domestic chilled-dairy infrastructure. Brazil and the United States anchor Americas consumption with divergent regulatory frameworks.
United States
Quick-service restaurant chains and institutional food service operators drive portion-controlled dessert procurement, with cold-chain reliability improvements enabling expanded distribution. FDA enforces Grade A Pasteurized Milk Ordinance provisions governing cross-border ingredient sourcing and pasteurization standards. The Midwest dairy belt surrounding Wisconsin and Minnesota supplies milk solids to frozen dessert manufacturers operating in Chicago and Minneapolis-Saint Paul industrial corridors.
Germany
Supermarket freezer door reallocation toward single-serve multi-packs is displacing bulk family tubs in retail channels. EFSA and EU Green Deal mandates are accelerating natural stabilizer and flavor transitions ahead of synthetic additive sunset dates. The North Rhine-Westphalia industrial cluster around Cologne and Düsseldorf hosts reformulation R&D facilities serving pan-European clean-label compliance requirements.
India
Urban bakery chains and quick-service restaurants are scaling chilled dairy dessert procurement with extended ambient stability requirements. FSSAI mandates specific milk-solid-not-fat thresholds that block formulation flexibility for frozen dessert versus ice cream classifications. The Mumbai-Pune corridor in Maharashtra and the Delhi-NCR region concentrate cold-chain infrastructure investments and food service operator headquarters.
Brazil
Direct-to-consumer subscription models for premium gelato are bypassing traditional retail slotting fees in São Paulo and Rio de Janeiro metro corridors. Cold-chain reliability improvements in refrigerated last-mile logistics are unlocking distribution previously constrained by temperature excursion risks. The São Paulo state industrial belt anchors dairy processing capacity serving Southeast Brazil's urban consumption concentration.
New Zealand
Global butterfat supply tightness driven by production fluctuations is compressing margin structures for premium ice cream formulations dependent on high-fat inputs. Fonterra adjusts export formulations to meet destination market regulatory thresholds including India's FSSAI classifications. The Canterbury Plains dairy farming region and Waikato processing hub supply international markets with standardized milk protein and fat fractions.
Dairy Desserts Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The structure concentrates around multinational packaged food groups with frozen and chilled dessert portfolio breadth, while regional dairy cooperatives and private-label manufacturers occupy mid-tier volume positions. Strategic archetypes include conglomerate portfolio managers, dairy cooperative processors, and ingredient technology suppliers. Dominant competitive moves center on clean-label reformulation partnerships and cold-chain logistics alliances.
Within the conglomerate tier, Unilever, Nestle, and General Mills occupy positions defined by portfolio breadth and brand architecture scale. Unilever represents the frozen dessert portfolio manager archetype with European supermarket shelf-space negotiation leverage. Nestle exemplifies premium ice cream positioning through reduced-sugar formulation R&D intensity. General Mills anchors North American pudding segment presence through comfort-food brand positioning. These entities sit within a competitive structure where R&D scale and distribution network control determine tier placement.
| Leading Market Players |
|---|
| Unilever |
| Lactalis |
| Nestle |
| Arla Foods |
| Fonterra |
| Danone |
| Mondelez International |
| Kraft Heinz |
| General Mills |
| Others |
Supply Flow & Price Mechanics
EFSA's clean-label additive sunset dates are forcing European manufacturers into rapid natural stabilizer and flavor sourcing transitions, compressing procurement timelines while elevating input costs as Madagascar vanilla and Indonesian botanical extract contracts reprice under supply contract restructuring.
Pricing Analysis
Margin tightening in premium ice cream reflects New Zealand and EU butterfat supply tightness, with Fonterra's production fluctuations forcing forward contracting at elevated levels. Three-tier pricing structure across premium, standard, and economy levels separates HPP-enabled refrigerated mousse lines from conventional frozen formats and private-label commodity tubs. Cost compression in food service channels accelerates as Indian QSR operators consolidate procurement around portion-controlled formats with extended ambient stability specifications. Retail customers demonstrate highest price sensitivity through private-label share gains in French and German supermarkets, while specialty gelato boutiques maintain lowest sensitivity through artisan positioning.
Supply Chain Analysis
Direct-to-food-service channels handle scaled procurement from Indian urban bakery chains and QSR operators, while supermarket multi-temperature distribution demands simultaneous frozen, chilled, and ambient supply. Manufacturing concentrates in New Zealand's Canterbury Plains and Waikato hub for butterfat and milk protein fractions, India's Maharashtra and Delhi-NCR corridors for cold-chain infrastructure, and Germany's North Rhine-Westphalia cluster for reformulation R&D. Raw material dependencies center on South Asian carrageenan and guar gum harvests, Madagascar vanilla botanical extracts, and EU-sourced milk solids. Monsoon-dependent harvest variability in South Asian processing hubs creates single-source vulnerability for natural stabilizer inputs. Distribution runs through refrigerated last-mile logistics investments across Southeast Asian urban corridors and Brazilian metro subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA's evolving additive authorization timelines under the flavoring substance re-evaluation program erect a compliance moat that rewards early natural sourcing transitions and punishes laggards with stranded synthetic inventory.
For Market Incumbents: To counter private-label encroachment in European supermarkets, Unilever and Nestle should deepen backward integration into Madagascar vanilla extraction and Indonesian botanical supply partnerships, while accelerating HPP technology deployment across refrigerated mousse and custard lines to extend shelf-life differentiation without chemical preservatives.
For New Entrants and Emerging Players: EU Green Deal sustainability-linked financing incentives in Europe open a window for precision fermentation-derived dairy protein positioning, with white space concentrating in Middle Eastern functional yogurt markets where protein-fortified chilled desserts remain underpenetrated against ambient dairy traditions.
For Investors and Strategic Acquirers: The window for entry favors cold-chain logistics specialists with Southeast Asian last-mile capabilities, with long-term viability hinging on India's FSSAI classification rigidity resolving to permit hybrid frozen dessert formulations; the signal to watch is Fonterra's export formulation adjustments to Indian milk-solid-not-fat thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Partnership | EFSA's additive sunset dates force natural stabilizer system redesign ahead of synthetic compound phase-outs. |
| Cold-Chain Infrastructure Expansion | Refrigerated last-mile investments in São Paulo and Mumbai unlock subscription models bypassing retail slotting fees. |
| Precision Fermentation Integration | Lab-derived dairy proteins enable animal-free claims without sensory compromise in premium frozen applications. |
| Portion-Controlled Format Development | Single-serve multi-packs displace bulk tubs in French and German supermarkets as household sizes compress. |
| High-Pressure Processing Adoption | HPP technology extends refrigerated mousse shelf life to 60 days without thermal protein degradation. |
Methodological Framework
Trade databases, EFSA regulatory filings, and customs import records formed the secondary backbone, supplemented by primary interviews with dairy dessert R&D directors, cold-chain logistics operators, European supermarket category buyers, and Indian QSR procurement heads. Bottom-up and top-down triangulation validated volume estimates across product type and distribution channel segments.
Bottom-up modeling built from individual country consumption patterns and production capacity, while top-down analysis cross-checked against aggregate dairy processing output and ingredient trade flows. Segmentation dimensions included product type, end-user archetype, ingredient sourcing geography, and distribution channel temperature protocol. CAGRs derived from regression analysis against urbanization rates, quick-service restaurant expansion, and cold-chain infrastructure investment indices.
The model assumes a particular technology adoption path for high-pressure processing; alternative pathways for thermal pasteurization retention would alter the outlook for clean-label shelf-life extension. Forecasts reflect assumptions about EFSA enforcement timelines, New Zealand butterfat production stability, and Indian FSSAI classification evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Processed Superfruits Market
Processed Foods
Fermented Food and Drinks Market
Processed Foods
Low Fat Pasta Market
Processed Foods
Processed Cashew Market
Processed Foods
Sugar-Free Ice Cream Market
Processed Foods
Global Malted Milk Market
Processed Foods
Spray Cheese Market
Processed Foods
Africa Soup Market
Processed Foods
Soup Market
Processed Foods
Ice Cream Parlor Market
Processed Foods
Europe Processed Egg Market
Processed Foods
Global Dried Processed Food Market
Processed Foods
Low Fat Chicken Soup Market
Processed Foods
US Processed Pumpkin Market
Processed Foods
India Spray Dried Food Market
Processed Foods
Processed Vegetable Market