
 Low Fat Pasta Market | 2026-2036
Low Fat Pasta Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Pasta Market Analytics
Subscription-based replenishment services for low fat pasta is consolidating around direct-to-consumer nutrition platforms. Barilla G. e R. Fratelli S.p.A. leverages its Mediterranean supply chain to anchor premium whole wheat positioning. Nestlé S.A. sustains R&D intensity across plant-based protein fortification. Banza competes through chickpea-derived formulations that occupy the legume-based segment.
Low fat pasta comprises durum wheat semolina or alternative flour bases processed to achieve reduced lipid content, typically below 2 grams per serving through modified extrusion temperatures and precise moisture control during drying. The primary commercial purpose centers on delivering familiar pasta functionality for calorie-restricted and cardiovascular-conscious diets. Legume-based types lead structural growth as protein density commands shelf space premiums, while dried form dominates manufacturing scale and logistics efficiency. Health-conscious consumers represent the deepest margin pool through willingness to pay for certified nutritional claims.
FDA nutritional labeling requirements and USDA organic certification standards shape product development timelines and ingredient sourcing transparency across North American distribution. EFSA health claim regulations in Europe enforce stricter evidentiary thresholds for low fat positioning on packaging. Stakeholders must monitor evolving protein fortification standards and clean-label enforcement intensity to maintain formulation compliance and retail access.
Market Dynamics
FDA nutritional labeling requirements are compressing formulation timelines while durum wheat supply concentration in Italian processing clusters creates sourcing bottlenecks for North American retail expansion.
Growth Catalysts
- EFSA health claim regulations:Stricter evidentiary thresholds in Europe are forcing manufacturers to invest in clinical validation, elevating certified low fat products above commodity positioning.
- Chickpea flour extrusion technology:Modified screw profiles and lower-temperature processing enable legume-based pasta to achieve al dente texture parity with durum wheat, unlocking protein-fortified shelf space premiums.
- Italy's Emilia-Romagna cluster:Concentrated durum wheat innovation infrastructure and Mediterranean diet heritage positioning anchor premium whole wheat supply chains for export markets.
Market Restraints
- Semolina price volatility:Climate-driven durum wheat yield fluctuations in Canadian prairies and North American plains create input cost instability for traditional low fat pasta formulations.
- Clean-label enforcement intensity:USDA organic certification standards and FDA disclosure requirements extend product development timelines by 8-14 months for reformulated SKUs.
- Fresh pasta substitution:Refrigerated pasta segments with shorter ingredient lists capture health-conscious consumers seeking minimal processing over shelf-stable low fat alternatives.
Strategic Opportunities
- Direct-to-consumer nutrition platforms:Subscription-based replenishment services bypass retail slotting fees and capture recurring revenue from calorie-restricted diet adherents.
- Plant-based protein fortification:Pea protein and lentil flour integration responds to flexitarian demand while meeting FDA protein content claims for qualified health positioning.
- USDA BioPreferred program:Federal procurement preferences for biobased products create institutional channel access for pasta manufacturers with certified sustainable packaging.
Industry Challenges
- Extrusion engineering talent scarcity:Specialized expertise in low-moisture, low-temperature drying protocols for alternative flour matrices commands premium compensation and constrains scale-up velocity.
- Dual certification complexity:Simultaneous pursuit of FDA nutritional labeling compliance and USDA organic standards requires parallel documentation streams that extend time-to-shelf.
- Legacy equipment retrofitting:Converting traditional durum wheat extrusion lines for chickpea and lentil flour processing demands screw geometry modifications and cooling system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Pasta Market |
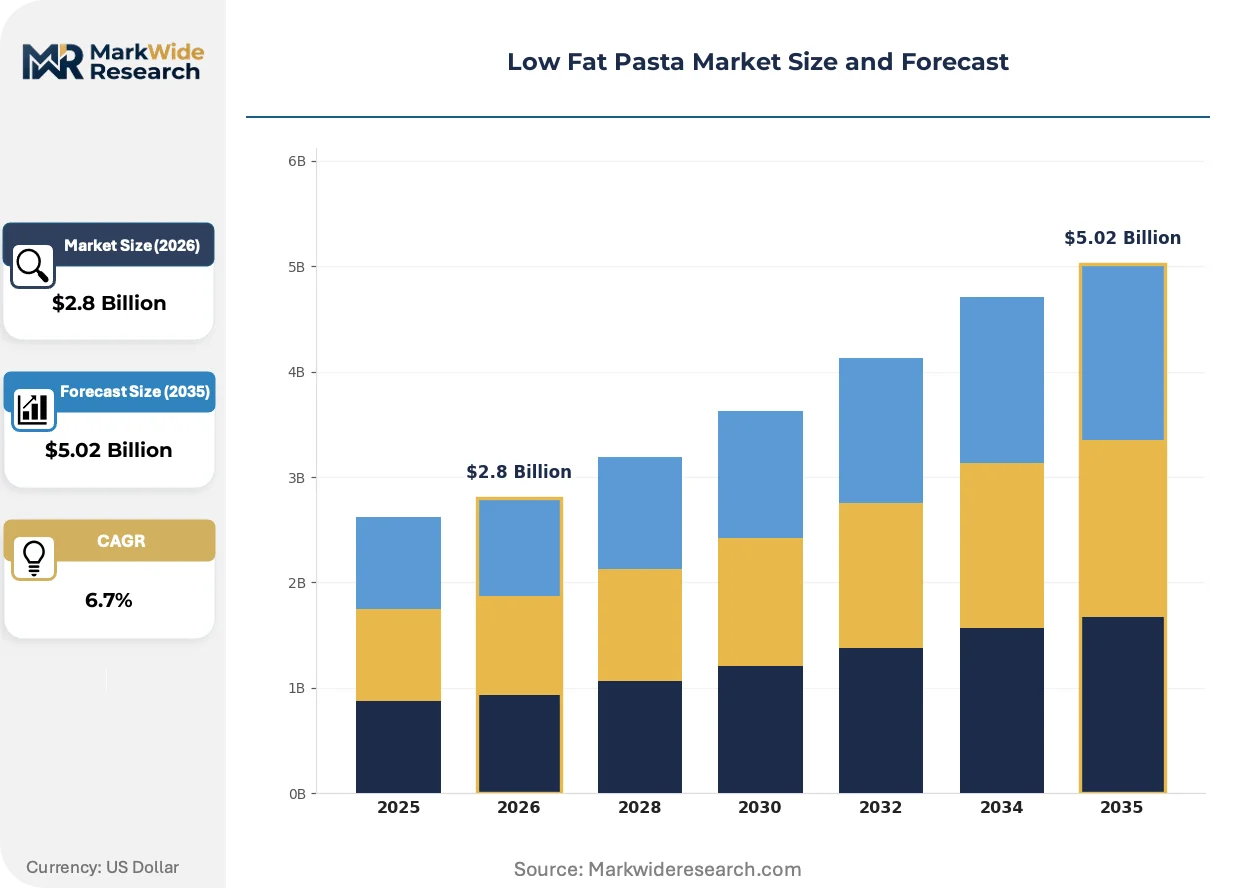
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Whole Wheat, Legume-Based, Spinach, Zucchini Form: Dried, Fresh, Frozen, Ready-to-Cook Packaging Type: Bags, Boxes, Cups, Pouches Customer Type: Health-Conscious Consumers, Fitness Enthusiasts, Restaurants, Grocery Stores |
| Companies Covered | Barilla G. e R. Fratelli S.p.A., Ebro Foods, S.A., Nestlé S.A., Post Holdings, F.lli De Cecco di Filippo Fara San Martino S.p.A., Banza, Egglife Foods, ZENB, Ancient Harvest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Pasta Market Evolving Landscape
Extrusion engineering and protein fortification chemistry are actively reshaping product architecture, while regulatory disclosure requirements and channel fragmentation redistribute competitive advantage across manufacturer tiers.
Modified extrusion temperature protocols are converging with precision moisture control systems to achieve sub-2 gram fat content per serving without sacrificing structural integrity. Food service operators and institutional buyers are adopting these reformulated products for menu labeling compliance. The technology is converging with clean-label positioning to compress price premiums between traditional and low fat pasta categories.
USDA organic certification standards now mandate supply chain transparency documentation from field to finished good, extending audit requirements for imported durum wheat. European manufacturers face parallel pressure from EFSA health claim evidentiary rules that demand clinical substantiation for cardiovascular benefit positioning. Italian exporters are responding by consolidating vertically into North American durum wheat sourcing to satisfy both regulatory frameworks.
Health-conscious consumers are fragmenting procurement across multiple channels rather than consolidating supermarket purchases. Direct-to-consumer nutrition platforms and subscription replenishment services are displacing conventional retail stocking for repeat purchases of certified low fat SKUs. This behavioral shift is most visible in US metropolitan markets where time-constrained professionals prioritize convenience and nutritional verification over in-store browsing.
Low Fat Pasta Market Segmentation
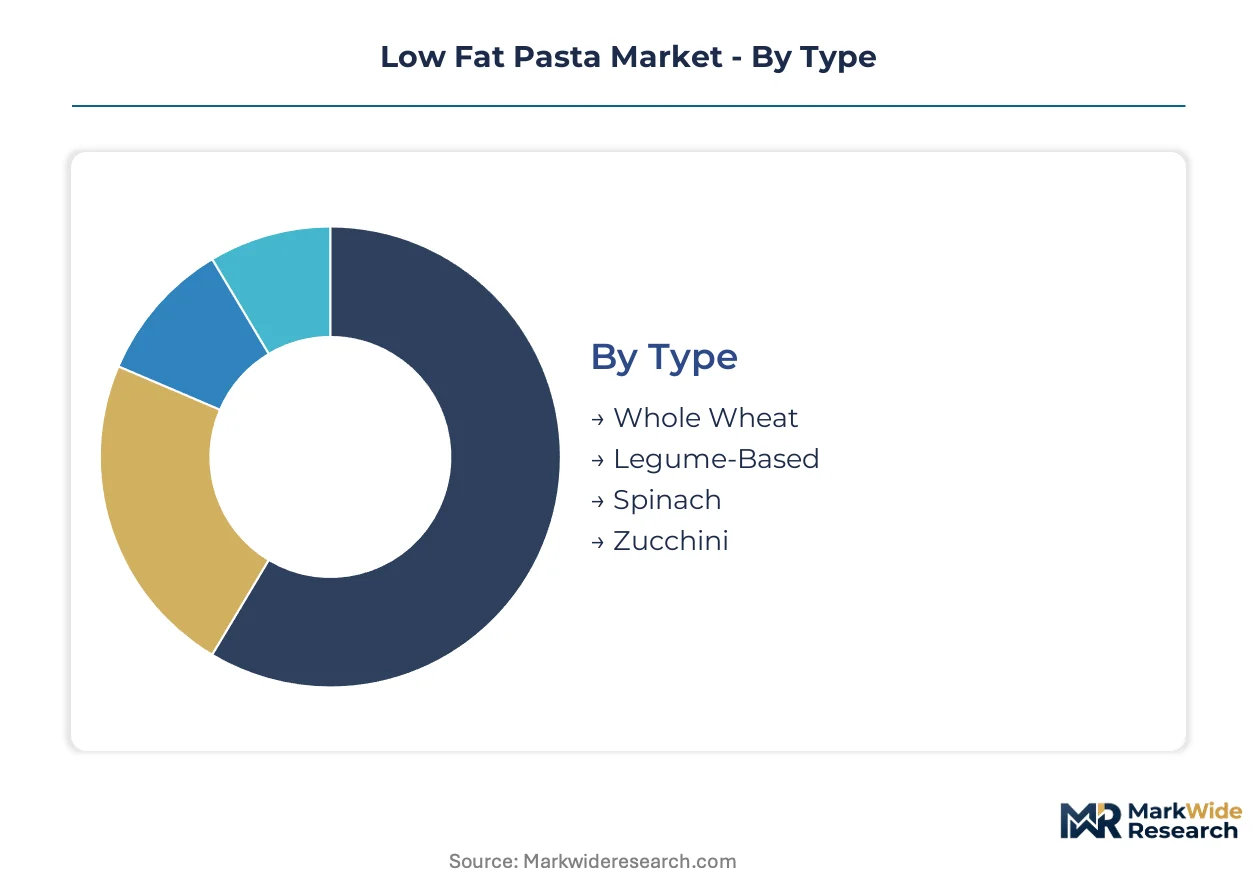
Low fat pasta segmentation reveals divergent certification burdens across ingredient bases and distribution channels. FDA nutritional labeling requirements apply unevenly, with dried shelf-stable formats facing stricter disclosure thresholds than fresh refrigerated alternatives.
Type:
Whole wheat varieties carry USDA organic certification complexity, while legume-based formulations trigger FDA protein content claim validation. Spinach and zucchini derivatives navigate vegetable content disclosure rules that vary by retail channel.
- Whole Wheat:Durum wheat semolina processed at modified extrusion temperatures achieves sub-2 gram fat content per serving. Demand concentrates in Italian export markets where Mediterranean diet heritage commands retail shelf space premiums. EFSA health claim regulations enforce stricter evidentiary thresholds for cardiovascular benefit positioning on European packaging.
- Legume-Based:Chickpea and lentil flour matrices require lower-temperature drying protocols to preserve protein integrity. Fitness enthusiasts in US metropolitan markets drive procurement through direct-to-consumer nutrition platforms seeking amino acid profile verification. Modified screw profiles in extrusion equipment enable al dente texture parity with traditional durum wheat.
- Spinach:Vegetable puree integration at 8-12% dry weight basis delivers chlorophyll-derived color stability and micronutrient density.
- Zucchini:Summer squash flour substitution at 15-20% inclusion rates reduces caloric density while maintaining structural integrity during boiling.
Whole wheat sits at the top of the volume ranking, with legume-based climbing the fastest.
Form:
Manufacturing scale and logistics efficiency create three distinct cost tiers across moisture content gradients. Dried formats dominate production economics, while fresh and frozen segments capture margin through shorter ingredient lists and minimal processing claims.
- Dried:Shelf-stable products below 12% moisture content achieve 24-month ambient storage stability through precision-controlled drying tunnels. Grocery stores in North American retail channels stock these SKUs for inventory turnover efficiency and reduced cold chain dependency.
- Fresh:Refrigerated pasta with 30-35% moisture content requires HACCP compliance for pathogen control but captures health-conscious consumers seeking minimal processing. Restaurants in urban food service markets specify these formats for menu labeling transparency and shorter cook times.
- Frozen:Blast-frozen at -40°C to preserve starch gelatinization state, these products occupy intermediate shelf space between dried convenience and fresh positioning.
- Ready-to-Cook:Pre-portioned and sauce-paired formats target time-constrained professionals through subscription replenishment services.
Dried commands the widest distribution footprint, with fresh expanding most quickly in food service procurement.
Packaging Type:
Material selection and unit economics stratify across retail versus food service channels. Bags and boxes dominate mass-market penetration, while pouches and cups align with convenience-oriented consumption occasions.
- Bags:Flexible film laminates with oxygen barrier properties extend shelf life for high-turnover SKUs in club store formats. Fitness enthusiasts purchasing bulk quantities favor resealable zipper configurations for portion control.
- Boxes:Paperboard cartons with windowed film panels support clean-label visibility and stackable retail display efficiency. Grocery stores allocate end-cap positioning to these formats for brand blocking and seasonal promotion flexibility.
- Cups:Single-serve polypropylene containers with vented lids target microwave preparation in workplace and travel contexts.
- Pouches:Stand-up flexible packaging with spout fitments enables sauce integration and reduced preparation steps for ready-to-cook variants.
Boxes lead in retail shelf presence, with pouches gaining share fastest through e-commerce fulfillment optimization.
Customer Type:
Procurement behavior fragments across channel-specific nutritional verification requirements. Health-conscious consumers and fitness enthusiasts prioritize certified claims, while restaurants and grocery stores balance margin targets with inventory velocity constraints.
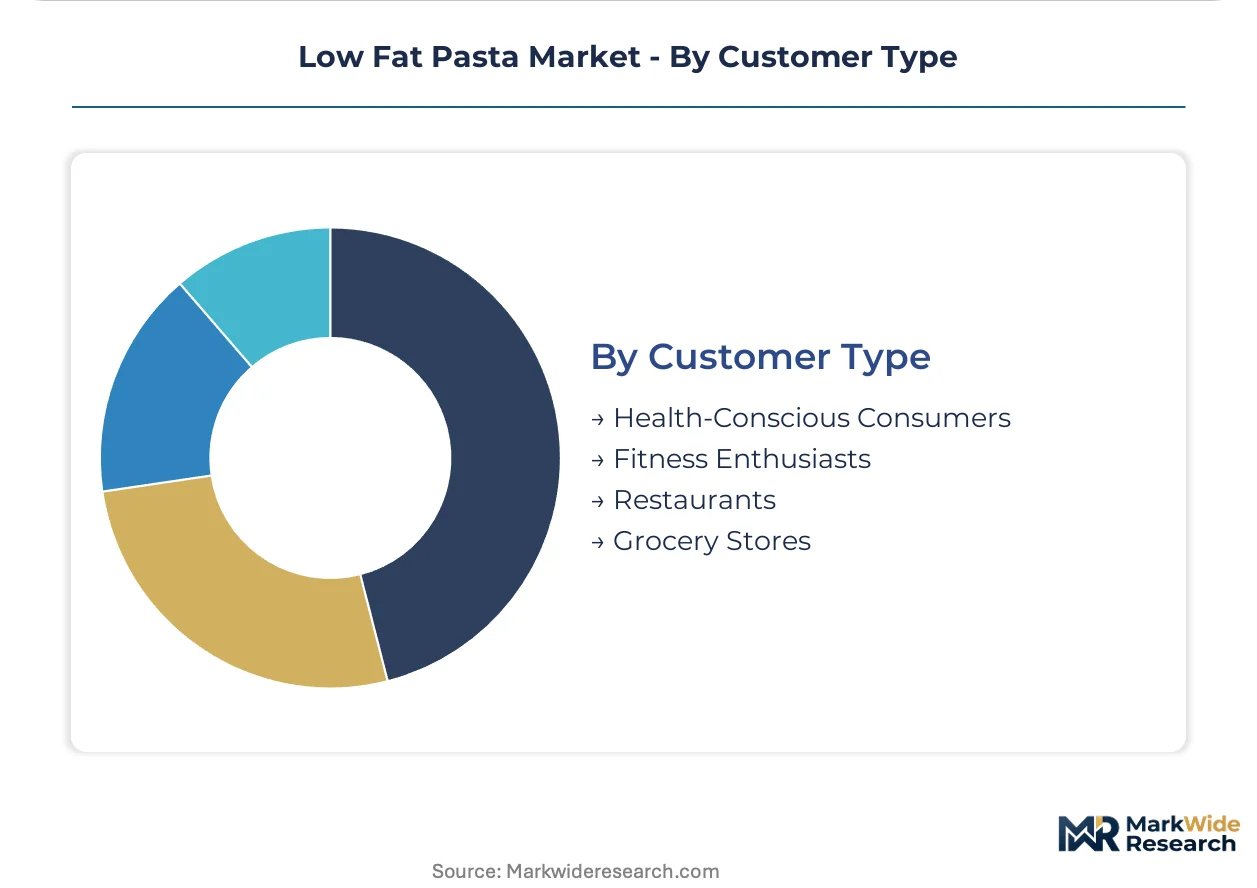
- Health-Conscious Consumers:Household purchasers willing to pay premiums for FDA-qualified health claims and USDA organic certification. This segment concentrates procurement through direct-to-consumer platforms that bypass retail slotting fees and enable subscription-based replenishment.
- Fitness Enthusiasts:Macro-tracking consumers prioritizing protein density and amino acid completeness in legume-based formulations. Demand clusters in US coastal metropolitan markets where athletic lifestyle positioning drives social media-influenced brand discovery.
- Restaurants:Food service operators seeking menu labeling compliance and consistent cook times for back-of-house efficiency.
- Grocery Stores:Retail buyers negotiating trade promotion allowances and category management fees for shelf space allocation.
Grocery stores anchor volume throughput, with fitness enthusiasts showing the steepest expansion trajectory in digital channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy commands premium positioning through Mediterranean diet heritage, while the United States drives volume expansion via health-conscious procurement across direct-to-consumer channels. Regulatory divergence between FDA nutritional labeling and EFSA health claim standards creates distinct compliance pathways across Atlantic markets.
United States
Fitness enthusiasts in coastal metropolitan markets prioritize protein density verification through subscription replenishment services. FDA nutritional labeling requirements mandate sub-2 gram fat disclosure thresholds per serving for qualified health claims. California's Bay Area and New York Metro anchor direct-to-consumer platform concentration for certified organic SKUs.
Italy
Mediterranean diet positioning commands retail shelf space premiums across European export markets. EFSA health claim regulations enforce stricter evidentiary thresholds for cardiovascular benefit substantiation on packaging. Emilia-Romagna's durum wheat processing clusters integrate innovation infrastructure with heritage brand manufacturing.
Canada
Climate-driven durum wheat cultivation in prairie provinces supplies North American semolina demand despite yield volatility. Health Canada nutritional disclosure standards align with FDA frameworks while maintaining distinct bilingual labeling requirements. Alberta and Saskatchewan anchor agricultural input concentration for cross-border manufacturing.
Germany
Clean-label enforcement intensity extends product development timelines for reformulated organic SKUs entering retail distribution. EU Green Deal sustainability metrics pressure packaging material selection across export-oriented manufacturers. Bavaria's food processing infrastructure integrates precision extrusion technology with certified supply chain documentation.
United Kingdom
Post-Brexit regulatory divergence complicates dual certification for manufacturers serving both UK and EU-27 markets. Health-conscious consumers in London and Southeast England fragment procurement across direct-to-consumer platforms and premium grocery channels. Midlands manufacturing clusters adapt extrusion capacity for legume-based alternative flour processing.
Low Fat Pasta Market Competitive Landscape
Top-tier vendors anchor premium whole wheat positioning through Mediterranean supply chain control, while mid-tier specialists compete on legume-based protein fortification. The vendor base stratifies across three concentration levels: heritage Italian manufacturers with vertical supply control, North American alternative-flour innovators, and private-label converters serving retail channel consolidation. Strategic archetypes include Mediterranean heritage brands, chickpea-flour technology specialists, and plant-based protein fortifiers. Capacity expansion and portfolio diversification dominate competitive moves as manufacturers retrofit legacy extrusion lines for alternative matrices.
Among heritage Mediterranean manufacturers, Barilla G. e R. Fratelli S.p.A. and F.lli De Cecco di Filippo Fara San Martino S.p.A. exemplify supply chain-anchored positioning through durum wheat sourcing concentration. Banza occupies a distinct archetype as a chickpea-derived formulation specialist targeting legume-based segment growth. Nestlé S.A. represents diversified conglomerate participation through sustained R&D intensity across plant-based protein fortification vectors.
| Leading Market Players |
|---|
| Barilla G. e R. Fratelli S.p.A. |
| Ebro Foods, S.A. |
| Nestlé S.A. |
| Post Holdings |
| F.lli De Cecco di Filippo Fara San Martino S.p.A. |
| Banza |
| Egglife Foods |
| ZENB |
| Ancient Harvest |
| Others |
Value Network & Pricing Analysis
FDA nutritional labeling requirements for sub-2 gram fat disclosure thresholds are compressing formulation timelines and forcing manufacturers toward certified ingredient sourcing, which elevates input costs and compresses margins across standard-tier SKUs while creating pricing power for USDA organic-certified alternatives.
Pricing Analysis
Capacity additions in Italy's Emilia-Romagna processing clusters are reshaping price floors for premium whole wheat positioning. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic-certified SKUs with supply chain documentation from conventional formulations and private-label alternatives. Price differentiation rests on certification grade and volume scale, with club store bulk formats commanding per-unit discounts against specialty retail packaging. Pricing pressure stems from climate-driven semolina volatility in Canadian prairies, while food service operators show least price sensitivity due to menu labeling compliance mandates.
Supply Chain Analysis
USDA organic certification standards and EFSA health claim regulations gate supplier qualification and extend audit timelines for imported durum wheat. Geographic supply concentration centers on Italy, Canada, and the United States, with Canadian prairie cultivation feeding North American semolina demand. Raw material dependencies include durum wheat, chickpea flour, and pea protein isolates. Single-source vulnerability runs through Italian heritage processors controlling Mediterranean export infrastructure. Distribution runs through grocery retail channels, direct-to-consumer nutrition platforms, and institutional food service procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between Italian heritage supply chain premiums and North American alternative-flour innovation, justified by the cost differential between EFSA-compliant clinical validation requirements and FDA nutritional disclosure frameworks.
For Market Incumbents: Deploy backward integration into Canadian durum wheat sourcing to buffer semolina price volatility and secure USDA organic certification compliance. Consolidate extrusion engineering talent through specialized recruitment in Italy's processing clusters to constrain competitor scale-up velocity. Defensive positioning must counter chickpea-flour entrants by accelerating protein fortification R&D timelines. For New Entrants and Emerging Players: Capture white-space in direct-to-consumer subscription replenishment services targeting fitness enthusiasts in US coastal metropolitan markets. Legume-based formulations offer the most penetrable segment given al dente texture parity achievements through modified screw profiles. A go-to-market angle anchored on amino acid profile verification bypasses retail slotting fee barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with chickpea-flour technology specialists possessing proprietary extrusion IP and established direct-to-consumer channel relationships. Long-term viability across the projection horizon hinges on regulatory certification moats and captive supply arrangements. The signal to watch is FDA protein content claim enforcement intensity as an inflection indicator for legume-based segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Durum Wheat Sourcing | Captive supply from Canadian prairies buffers semolina price volatility against climate-driven yield fluctuations. |
| Direct-to-Consumer Platform Launch | Subscription replenishment services bypass grocery retail slotting fees and capture recurring revenue from fitness enthusiasts. |
| USDA Organic Certification Investment | Supply chain transparency documentation from field to finished good commands shelf space premiums in North American retail. |
| Chickpea Flour Extrusion Scale-Up | Modified screw profiles and lower-temperature processing enable protein-fortified SKUs with al dente texture parity. |
| EFSA Health Claim Clinical Validation | Cardiovascular benefit substantiation elevates certified low fat products above commodity positioning in European export markets. |
Research Methodology
Bottom-up food service procurement modeling reconciled against top-down durum wheat supply tracking forms the analytical core of this study. Primary interviews with pasta manufacturing executives, retail category buyers, extrusion engineering specialists, and supply chain documentation auditors combined with secondary validation from FDA nutritional labeling filings, USDA organic certification databases, EFSA health claim registers, and customs trade data. Triangulation across these sources ensures convergence between demand-side adoption patterns and supply-side capacity utilization.
Historical trendline analysis of volume and value trajectories across the analysis window established baseline growth parameters. Segmentation dimensions modeled include ingredient base, moisture content form, packaging type, and customer procurement channel, with regional regulatory framework clusters as an industry-specific overlay. CAGRs were derived through regression analysis of historical shipment data and forward projection of certification-driven demand shifts, incorporating durum wheat yield volatility and clean-label enforcement intensity as forecast inputs.
Underlying measurement precision varies by segment; dried shelf-stable formats carry tighter precision than fresh refrigerated alternatives due to standardized manufacturing reporting. Forecasts reflect documented assumptions regarding regulatory compliance timelines and alternative-flour technology maturation. A model refresh is warranted upon material change in FDA protein content claim standards or EFSA evidentiary threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Fermented Foods Market
Processed Foods
Industrial Margarine Market
Processed Foods
Processed Superfruits Market
Processed Foods
Europe Soup Market
Processed Foods
Butter Crisco Market
Processed Foods
Spray Cheese Market
Processed Foods
Coffee Creamer Market
Processed Foods
Tomato Puree Market
Processed Foods
Egg White Cubes Market
Processed Foods
Processed Eucheuma Seaweed Market
Processed Foods
Low Fat Chicken Soup Market
Processed Foods
Global Dried Processed Food Market
Processed Foods
Ready-To-Whip Toppings Market
Processed Foods
India Ready to Mix Food Market
Processed Foods
Global Malted Milk Market
Processed Foods
United States Fresh Noodles Market