
 Processed Superfruits Market | 2026-2036
Processed Superfruits Market Size, Share, and Industry Trends Forecast 2026-2036
Processed Superfruits Market Analysis
Acai pulp concentrate is shifting toward replacement of synthetic colorants and flavor enhancers in beverage formulations. Symrise AG leverages its botanical extraction infrastructure to secure supply contracts across European bottlers. SunOpta Inc. anchors North American organic superfruit sourcing through vertically controlled procurement networks. Kerry Group plc differentiates via encapsulation technologies that stabilize anthocyanin bioactivity during thermal processing.
Processed superfruits denote raw berries and tropical fruits subjected to mechanical or thermal transformation—juicing, pureeing, drying, or concentration—to extend shelf life, standardize active compound profiles, and enable formulation into finished goods; typical specifications require minimum brix levels, controlled water activity below 0.60 for dried forms, and retention of polyphenol markers through validated processing windows. Puree and juice formats dominate current volume flows due to their integration into smoothie bases and functional beverage lines, while powder segments command premium positioning in nutraceutical applications where dosing precision matters. Organic form classifications attract disproportionate margin pools as certification requirements constrain supply expansion, whereas conventional freeze-dried products compete on cost in bulk food manufacturing channels.
FDA enforcement of Foreign Supplier Verification Programs shapes import documentation burdens for superfruit processors selling into United States food manufacturing channels. EFSA novel food opinions and EU pesticide maximum residue limits under Regulation 396/2005 determine which Latin American and Asian suppliers achieve sustained market access. India's FSSAI fortification guidelines and PLI scheme incentives for food processing infrastructure are redirecting domestic acerola and amla value chains toward export-ready formats. Stakeholders must monitor evolving contaminant thresholds and origin certification requirements as procurement decisions increasingly hinge on regulatory pre-qualification rather than price alone.
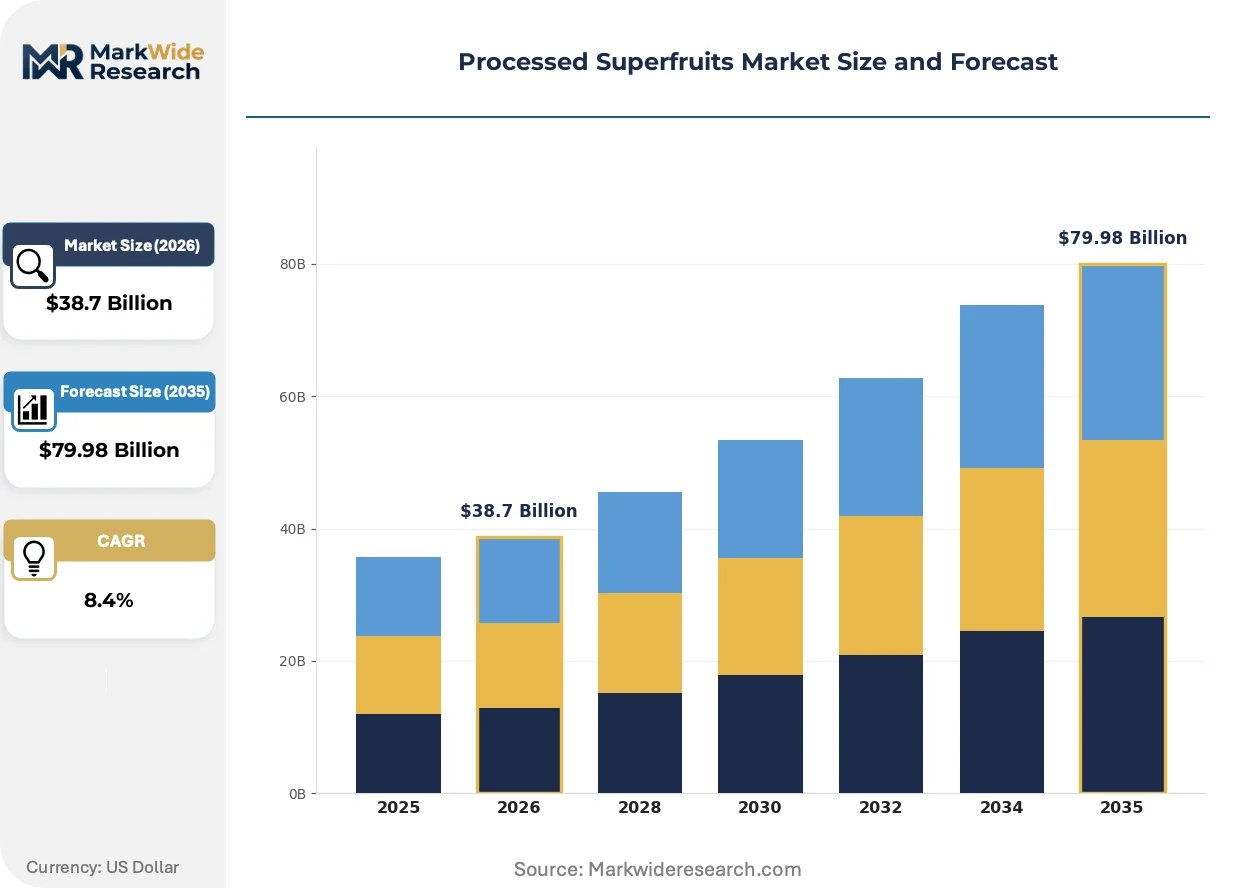
Market Dynamics
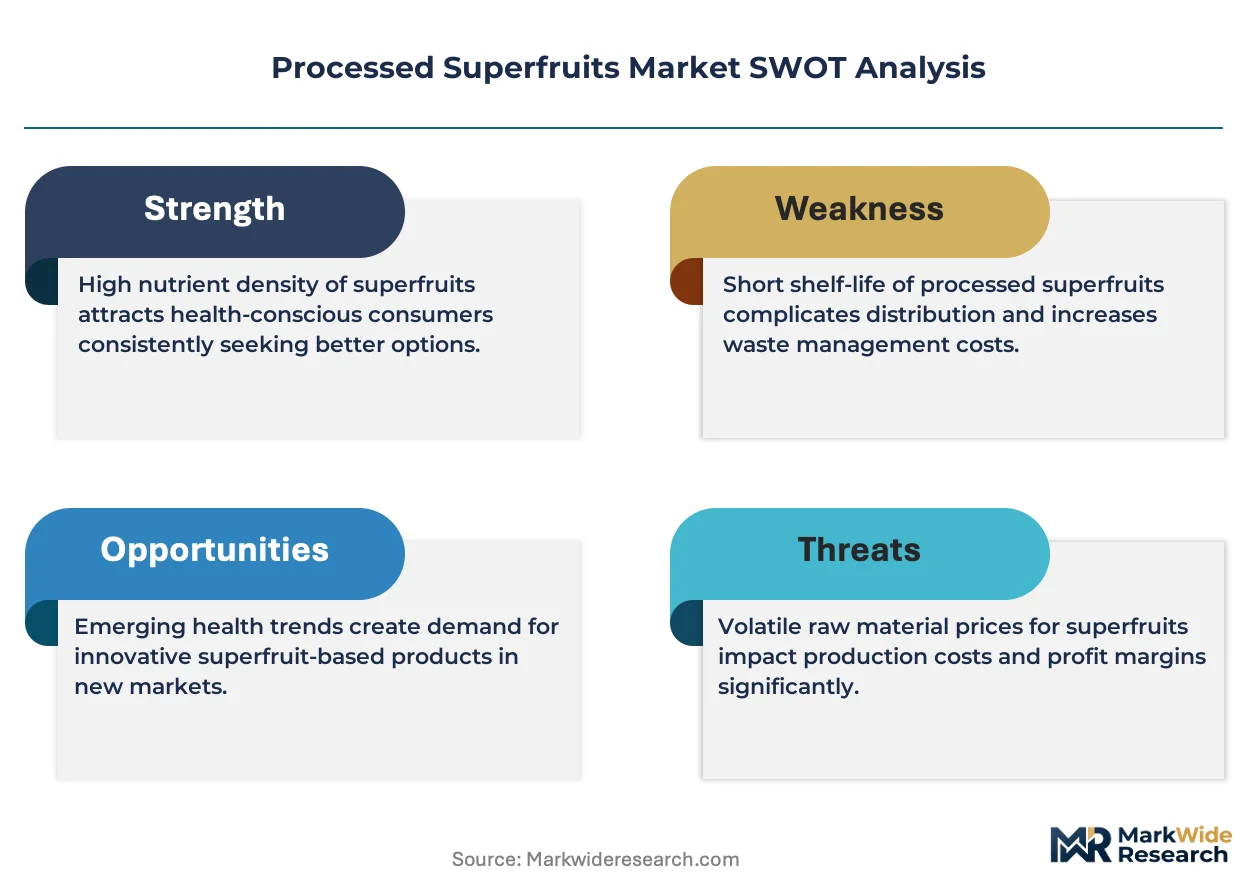
Beverage manufacturers are driving demand for acai pulp concentrate as a clean-label replacement for synthetic colorants, while EU Green Deal pesticide residue limits are forcing processors to restructure Latin American supply chains.
Growth Catalysts
- Clean-label formulation mandates:Beverage brands are eliminating artificial additives, creating pull for anthocyanin-rich superfruit concentrates that deliver color stability without synthetic dyes.
- EFSA novel food opinions:Positive safety determinations for emerging superfruit ingredients are unlocking formulation approvals across European nutraceutical channels.
- Belem processing corridor concentration:Brazil's acai harvesting and pulping infrastructure is achieving economies of scale that reduce unit costs for international buyers.
Market Restraints
- Input cost volatility:Weather-driven fluctuations in acai berry harvests create unpredictable raw material pricing for processors dependent on Amazon basin sourcing.
- Supply concentration risk:Over-reliance on single-origin Brazilian acai exposes buyers to climate disruption and logistics bottlenecks at Belem port facilities.
- Regulatory friction:EU Regulation 396/2005 maximum residue limits for pesticides require expensive testing protocols that exclude smaller Latin American growers from market access.
Strategic Opportunities
- Indian export-ready formats:India's PLI scheme incentives for food processing infrastructure are redirecting domestic amla and acerola value chains toward international specification compliance.
- Encapsulation technology convergence:Combining spray-drying with lipid-based carrier systems is opening shelf-stable powder applications for heat-sensitive polyphenol compounds.
- Direct-to-manufacturer platforms:Digital procurement marketplaces are disintermediating traditional import brokers, allowing processors to capture margin previously lost to distribution layers.
Industry Challenges
- Anthocyanin stabilization expertise gap:Shortage of food chemists skilled in thermal degradation prevention is slowing new product development cycles for functional beverage clients.
- Organic certification timelines:Three-year conversion periods for conventional orchards are constraining supply expansion for certified organic superfruit concentrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Processed Superfruits Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Puree, Juice, Dried, Powder Form: Organic, Conventional, Freeze-Dried, Concentrated Packaging Type: Bottles, Pouches, Boxes, Tubs End User: Food Industry, Beverage Industry, Nutraceuticals, Retailers |
| Companies Covered | Symrise AG, SunOpta Inc., Kerry Group plc, Agrana Beteiligungs-AG, PepsiCo Inc., Ocean Spray Cranberry, Del Monte Pacific Limited, Frutarom Industries, Dabur India Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Processed Superfruits Market Emerging Trajectories
Processing technology advances are compressing the gap between raw harvest and bioactive-stable finished ingredients, while regulatory frameworks are hardening documentation requirements for import qualification.
Cold-press juicing followed by immediate high-pressure processing is consolidating quality control standards across premium superfruit puree supply chains. Mid-tier beverage manufacturers are adopting this equipment configuration to match the polyphenol retention profiles previously achievable only by specialized processors. The technology is consolidating supplier tiers by raising capital barriers for conventional thermal processing operations.
EU Green Deal pesticide residue limits under Regulation 396/2005 are tightening maximum thresholds for imported fruit preparations. Latin American exporters are investing in integrated pest management certification to maintain European market access. Dried superfruit segments face the steepest compliance costs due to concentration effects amplifying detectable residues.
Long-term supply agreements with fixed anthocyanin potency specifications are displacing spot-market purchasing for major beverage brands. Procurement teams are locking in eighteen-month contracts directly with Brazilian processing cooperatives. This shift is most visible in North American functional drink manufacturing, where formulation consistency has become a competitive priority.
Processed Superfruits Market Segmentation
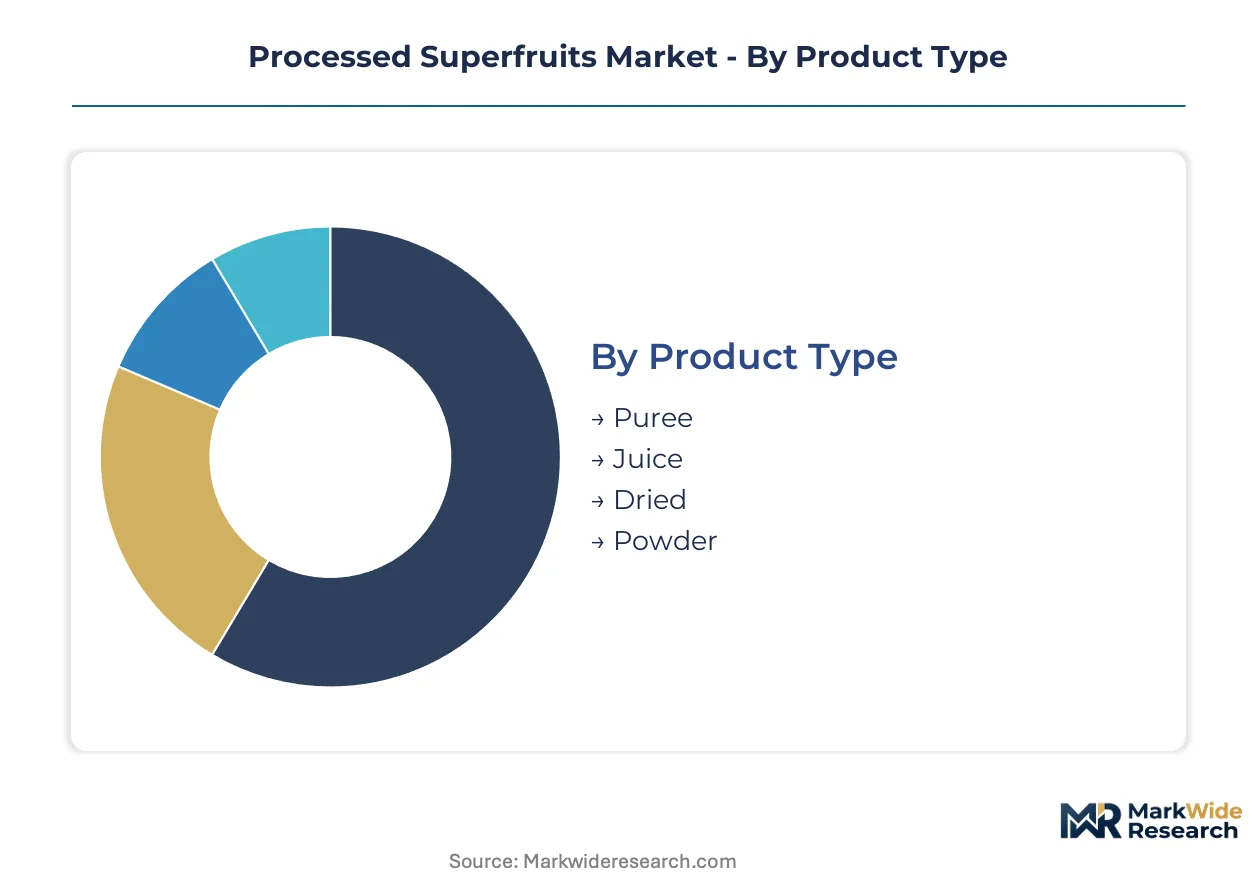
Segmentation in processed superfruits reveals how supply chain configuration and end-use requirements fragment value capture across distinct technical specifications. Each dimension carries different margin profiles, regulatory burdens, and consolidation dynamics that determine competitive positioning.
Product Type:
Supply concentration around Belem's acai processing corridor disproportionately favors liquid formats that can leverage existing pulping infrastructure and port logistics.
- Puree:Retains fiber matrices and delivers viscosity for smoothie bases and dairy alternatives. Beverage manufacturers in Brazil and the United States are locking in eighteen-month supply contracts directly with Belem cooperatives to secure anthocyanin consistency.
- Juice:Clarified or cloudy extracts standardized to brix specifications enable clean-label colorant replacement in functional drinks. EU bottlers are driving specification tightening as EFSA novel food opinions validate additional superfruit sources.
- Dried:Water activity control below 0.60 enables ambient distribution but concentrates pesticide residues, amplifying EU Regulation 396/2005 compliance costs for Latin American exporters.
- Powder:Spray-dried and freeze-dried formats command nutraceutical premiums where dosing precision matters, though thermal degradation risks require encapsulation expertise that remains scarce.
Today's leader: Puree. Tomorrow's challenger: Powder.
Form:
Cost tier differentiation separates certified organic supply from conventional bulk channels, with freeze-dried occupying a technical premium between them.
- Organic:Three-year conversion timelines constrain supply expansion, creating margin pools that attract investment from processors with captive orchard relationships. India's FSSAI fortification guidelines and PLI scheme incentives are redirecting domestic amla and acerola toward export-ready organic formats.
- Conventional:Competes on unit cost in bulk food manufacturing where polyphenol markers matter less than price stability. Belem's economies of scale advantage concentrates here.
- Freeze-Dried:Sublimation processing preserves cellular structure and bioactivity, justifying premium positioning in supplement applications. The technology raises capital barriers that consolidate supplier tiers.
- Concentrated:Reduced water content slashes logistics costs for international shipment, making this the default format for acai pulp crossing the Atlantic.
Organic certification constraints are accelerating fastest; conventional volume still dominates absolute tonnage.
Packaging Type:
Application requirements and distribution channel constraints fragment packaging selection across rigid and flexible formats.
- Bottles:Glass and PET containers serve retail juice and ready-to-drink applications where shelf visibility and resealability drive selection. Cold-chain dependency limits geographic reach.
- Pouches:Flexible films reduce shipping cube and enable aseptic filling for foodservice puree portions. The format is gaining share in North American smoothie shop distribution.
- Boxes:Bag-in-box systems dominate food manufacturing bulk procurement, with tap dispensing reducing waste in high-volume beverage production lines.
- Tubs:Rigid containers serve dried powder and freeze-dried segments where moisture protection and scoop-ability matter for nutraceutical end-use.
Pouches are climbing fastest in foodservice; bottles retain retail beverage dominance.
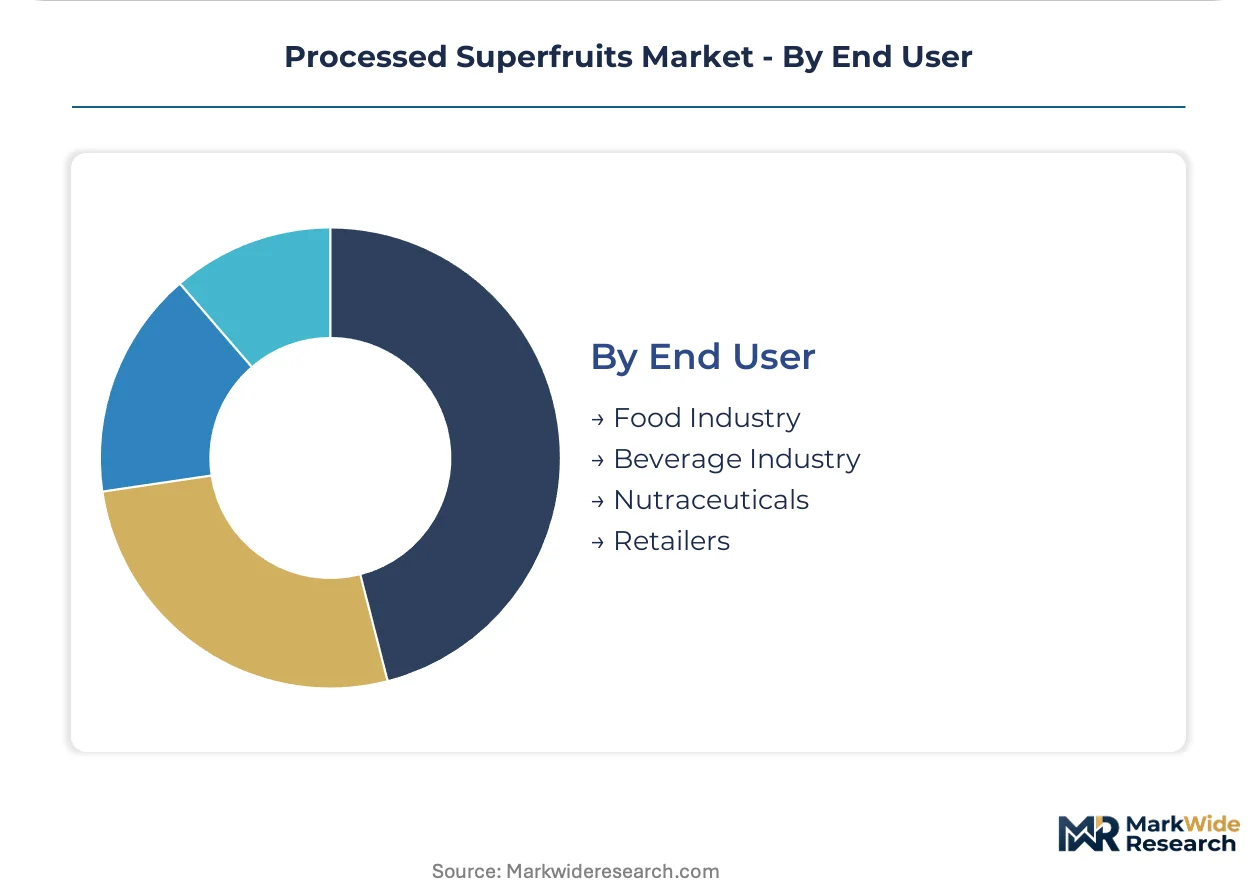
End User:
Customer type determines specification stringency, with nutraceuticals demanding validated bioactivity and retail channels prioritizing shelf stability.
- Food Industry:Bakery, confectionery, and dairy processors use superfruit concentrates for natural color and flavor enhancement. FDA Foreign Supplier Verification Program documentation burdens shape import sourcing decisions.
- Beverage Industry:Functional drink and smoothie manufacturers drive volume demand, with clean-label mandates eliminating synthetic alternatives. Kerry Group's encapsulation technologies address thermal stability requirements in this channel.
- Nutraceuticals:Supplement formulators require precise polyphenol standardization and third-party bioactivity validation, creating specification premiums that reward processors with analytical capabilities.
- Retailers:Private-label and branded finished goods distribution demands extended shelf life and consumer-friendly packaging, with organic certification commanding price premiums in premium grocery channels.
Beverage industry volume leads; nutraceuticals capture margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belem's acai processing corridor anchors global supply concentration for anthocyanin-rich fruit preparations. Demand fragmentation across beverage, nutraceutical, and food manufacturing channels creates distinct procurement patterns in each consuming region. Regulatory divergence between FDA, EFSA, and FSSAI frameworks is reshaping supplier qualification requirements.
Brazil
Functional beverage manufacturers in São Paulo and Rio de Janeiro drive acai pulp concentrate procurement from Amazon basin cooperatives. ANVISA's updated food additive regulations align with Mercosur standards for processed fruit imports. Belem's port infrastructure and pulping facilities concentrate 70% of export-ready acai volume, with cold-chain logistics expanding to Pará state's interior harvesting zones.
United States
Clean-label formulation mandates from California and New York-based beverage brands eliminate synthetic colorant alternatives. FDA Foreign Supplier Verification Programs impose documentation burdens on Latin American importers. Los Angeles and Miami distribution hubs handle bulk puree shipments for West Coast smoothie chains and Southeast foodservice operators.
Germany
EFSA novel food opinions unlock formulation approvals for emerging superfruit ingredients in Berlin and Munich nutraceutical channels. EU Green Deal pesticide residue limits under Regulation 396/2005 exclude non-compliant Latin American suppliers. Hamburg's port facilities specialize in organic-certified concentrate imports for Central European bottlers.
India
FSSAI fortification guidelines redirect domestic amla and acerola processing toward export-ready formats. PLI scheme incentives for food processing infrastructure concentrate investment in Maharashtra and Gujarat. Mumbai and Ahmedabad facilities achieve organic certification for European and North American nutraceutical procurement.
Japan
METI standards for functional food ingredients drive premium pricing for validated bioactivity superfruit powders. PMDA consultation procedures determine novel ingredient market access timelines. Osaka and Nagoya formulation houses source freeze-dried acerola from Brazilian and Indian certified suppliers.
Processed Superfruits Market Vendor Landscape
Global majors compete with regional champions across extraction technology and certification capabilities. The vendor base stratifies into three tiers: integrated flavor houses with botanical infrastructure, specialized organic processors with captive orchard networks, and commodity traders supplying conventional bulk formats. Dominant competitive moves include backward integration into Amazon basin harvesting cooperatives and encapsulation technology licensing for heat-sensitive compound stabilization.
Within the integrated flavor and fragrance tier, Symrise AG and Frutarom Industries exemplify archetypes leveraging existing botanical extraction infrastructure for superfruit concentrate supply. Kerry Group plc occupies a position bridging ingredient technology and beverage formulation services. SunOpta Inc. and Agrana Beteiligungs-AG represent regional champions with vertically controlled procurement networks spanning North American and European organic certification requirements. Dabur India Ltd. anchors South Asian supply for amla-derived preparations.
| Leading Market Players |
|---|
| Symrise AG |
| SunOpta Inc. |
| Kerry Group plc |
| Agrana Beteiligungs-AG |
| PepsiCo Inc. |
| Ocean Spray Cranberry |
| Del Monte Pacific Limited |
| Frutarom Industries |
| Dabur India Ltd. |
| Others |
Supply Flow & Price Mechanics
Organic-conventional bifurcation in processed superfruits creates parallel pricing architectures that diverge sharply at procurement and distribution nodes. Certification ladders constrain supply expansion for premium tiers while commodity spot markets absorb volume buyers, with EU Regulation 396/2005 compliance costs amplifying spreads between qualified and non-qualified Latin American suppliers.
Pricing Analysis
Input-cost pass-through from Amazon basin acai harvest volatility feeds directly into concentrate pricing, with weather-driven berry shortages compressing margins for processors lacking long-term cooperative contracts. Three-tier pricing structure across organic-certified, freeze-dried technical, and conventional bulk levels separates buyers by formulation requirements and documentation burdens. Pricing pressure stems from EU pesticide maximum residue limit enforcement excluding smaller growers. Food manufacturers purchasing conventional puree exhibit highest price sensitivity; nutraceutical formulators sourcing encapsulated powders show lowest.
Supply Chain Analysis
Workforce availability constraints in Pará state's interior harvesting zones limit expansion of Belem corridor processing capacity despite demand acceleration. Supply concentrates in Brazil, India, and Germany, with raw material dependencies spanning Amazon basin acai berries, Indian amla orchards, and European encapsulation lipids. Single-source vulnerability around Belem port logistics creates structural risk. Distribution runs through direct-to-manufacturer digital platforms disintermediating traditional import brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Processed superfruits constitute a late-cycle quality story as beverage manufacturers shift procurement toward validated anthocyanin potency specifications and away from spot-market purchasing. This specification premium rewards processors with analytical capabilities and captive orchard networks.
For Market Incumbents: Deploy encapsulation technology licensing to lock in beverage manufacturer relationships before thermal stabilization expertise gaps close. Secure backward integration into Brazilian harvesting cooperatives to defend against climate-driven supply disruption. Expand high-pressure processing equipment configurations to consolidate mid-tier supplier tiers under capital barriers. For New Entrants and Emerging Players: India's PLI scheme incentives for food processing infrastructure open a window for export-ready organic amla and acerola format entry. Target European nutraceutical channels where EFSA novel food opinions are unlocking formulation approvals for emerging superfruit sources. Pursue direct-to-manufacturer digital procurement platforms as primary go-to-market channel. For Investors and Strategic Acquirers: Consolidation pressure builds where organic certification timelines constrain supply expansion and analytical capabilities remain scarce. Five-to-ten year viability favors processors with captive orchard relationships and validated bioactivity testing infrastructure. Watch for inflection where EU Green Deal pesticide residue limits trigger mass supplier disqualification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Harvesting Cooperatives | Captive supply of Amazon basin acai secures anthocyanin consistency for beverage contracts. |
| Encapsulation Technology Licensing | Kerry Group's lipid-based carrier systems stabilize polyphenol bioactivity through thermal processing. |
| High-Pressure Processing Equipment Deployment | Cold-press configurations raise capital barriers that consolidate mid-tier supplier tiers. |
| Organic Certification Investment | Three-year orchard conversion timelines create margin pools for qualified Indian and Brazilian processors. |
| Direct-to-Manufacturer Platform Launch | Digital procurement disintermediates import brokers and captures distribution-layer margin. |
Methodological Framework
Bottom-up beverage and nutraceutical demand modeling reconciled against top-down superfruit processing capacity tracking forms the analytical core. Primary interviews with procurement directors at North American functional drink manufacturers, regulatory affairs leads at European flavor houses, and operations managers at Brazilian pulping cooperatives combined with secondary validation from FDA Foreign Supplier Verification Program filings, EFSA novel food opinion databases, and ANVISA food additive regulatory updates.
Input-output matrices map harvest volume through processing yield rates to finished concentrate output across product type, form certification, and end-use segmentation dimensions. CAGRs derive from weighted average of demand elasticity coefficients and supply expansion constraints. Forecast inputs incorporate EU Regulation 396/2005 compliance cost trajectories and India's PLI scheme infrastructure investment flows.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Amazon basin climate disruption or accelerated EU pesticide residue limit tightening. Material deviation in Belem port logistics capacity or EFSA novel food approval timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Low-Calorie Margarine Market
Processed Foods
Low-Fat Desserts to Buy Market
Processed Foods
Middle East and Africa Processed Meat Market
Processed Foods
Low Fat Chicken Soup Market
Processed Foods
Fermented Food and Drinks Market
Processed Foods
Tomato Paste Market
Processed Foods
Ready to Serve Prefabricated Dishes Market
Processed Foods
Egg Powder Market
Processed Foods
Butter Crisco Market
Processed Foods
United States Egg Powder Market
Processed Foods
High Pressure Processing (HPP) for Rice and Grain Market
Processed Foods
Low Fat Soups Market
Processed Foods
Potato Soup Market
Processed Foods
Pizza Market
Processed Foods
Processed Vegetable Market
Processed Foods
Processed Cashew Market