
 North America Dairy Desserts Market | 2026-2036
North America Dairy Desserts Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dairy Desserts Market Insights
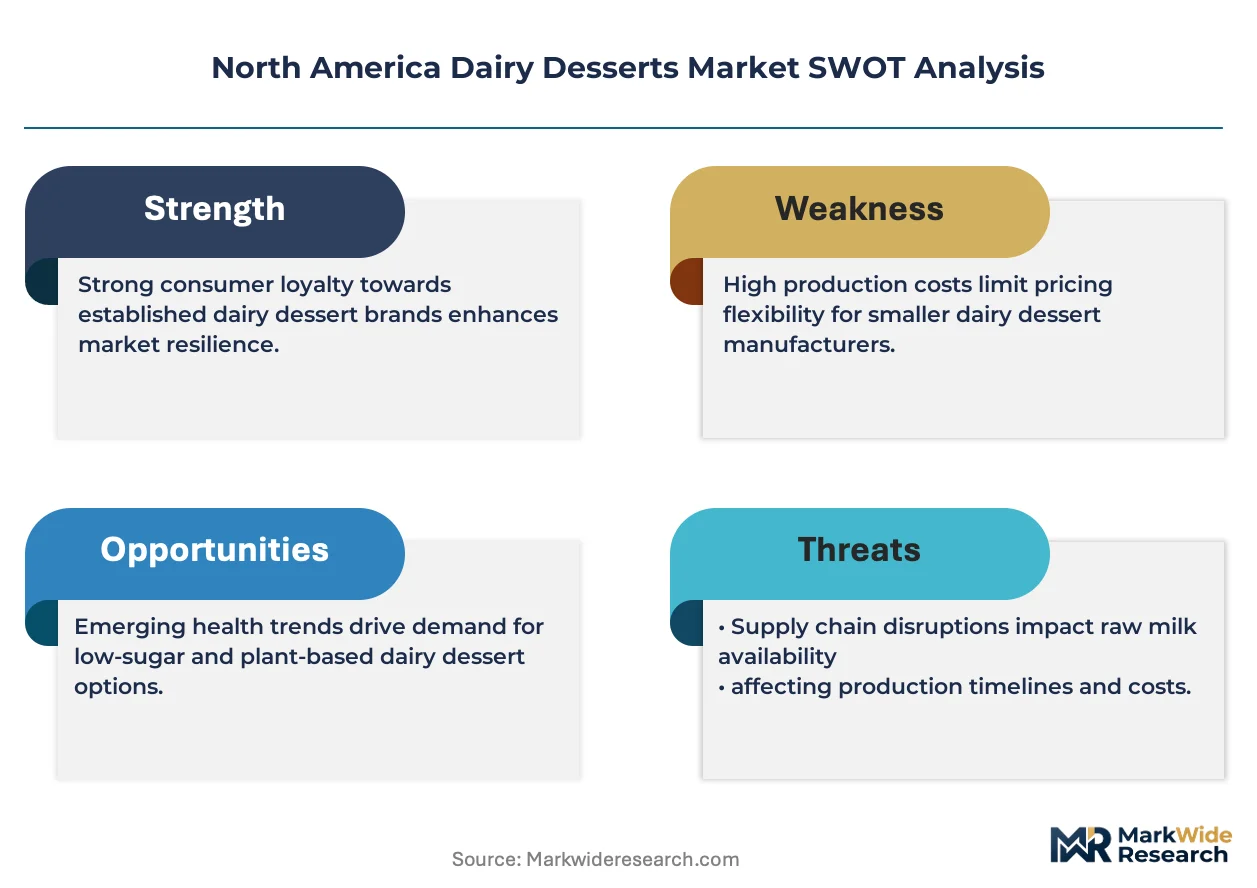
Capital-intensity divergence between artisan-scale creameries and billion-dollar multinationals is reorganizing competitive dynamics across the North America Dairy Desserts Market. Nestlé S.A. leverages its global dairy procurement network to secure cost-advantaged milk solids. Unilever PLC anchors its position through proprietary freezing technology and controlled distribution infrastructure. Blue Bell Creameries competes on regional brand loyalty and localized flavor portfolios rather than scale.
North America dairy desserts comprise frozen, chilled, and ambient sweet preparations derived from milk, cream, or cultured dairy bases, typically formulated with minimum milkfat thresholds ranging from 10% in ice cream to 4% in puddings, and stabilized through homogenization and pasteurization processes to achieve shelf-life and texture specifications. Ice cream commands the largest revenue pool among product types due to premium pricing and year-round consumption patterns. Pudding segments are gaining traction through single-serve cup formats targeting convenience-oriented households. Non-dairy ingredient formulations represent the fastest-adjusting category as almond, oat, and coconut bases displace conventional milk solids in plant-forward product lines.
FDA enforces standards of identity for ice cream and frozen desserts under 21 CFR 135, while USDA organic certification governs label claims for dairy-derived inputs across interstate commerce. State-level dairy compacts in Wisconsin and California impose additional fluid milk grading requirements that cascade into dessert manufacturing specifications. Stakeholders must monitor evolving FDA guidance on bioengineered food disclosure and state-level clean-label mandates to anticipate reformulation costs and label redesign cycles.
Market Dynamics
Plant-based formulation R&D is fragmenting traditional dairy dessert supply chains as oat and almond protein isolates achieve functional parity with milk solids, forcing processors to dual-source or retool production lines.
Growth Catalysts
- USDA Organic Certification expansion:Retailers are expanding shelf space for certified organic dairy desserts, pulling reformulation investment toward pasture-raised milk sourcing and non-GMO stabilizer systems.
- Single-serve convenience formats:Food service operators and C-store chains are driving cup-sized pudding and frozen novelty placements, compressing per-unit margins but expanding household penetration.
- California-Texas corridor demand concentration:Metropolitan population growth in Los Angeles, Dallas-Fort Worth, and Houston is anchoring regional distribution hub expansion and localized flavor development.
Market Restraints
- Butterfat and cream input volatility:Dairy commodity price swings tied to regional herd sizes constrain margin predictability for premium ice cream manufacturers.
- FDA 21 CFR 135 identity standards:Strict compositional thresholds for ice cream and frozen desserts limit formulation flexibility when substituting plant-based fats.
- Midwest fluid milk supply concentration:Wisconsin and Minnesota processing cooperatives control a disproportionate share of Grade A milk volumes, creating geographic sourcing risk.
Strategic Opportunities
- Mexico cross-border retail expansion:Untapped modern trade channels in Monterrey and Guadalajara present white-space for US-manufactured premium frozen desserts.
- Clean-label state mandates:Vermont and California additive disclosure laws are creating first-mover advantage for brands with simplified ingredient panels.
- Precision fermentation convergence with dessert bases:Cellular agriculture-derived dairy proteins are enabling animal-free products that meet FDA identity standards without supply chain volatility.
Industry Challenges
- Homogenization and HTST pasteurization technician scarcity:Specialized dairy processing skills are aging out of the workforce faster than community college pipeline programs can replace them.
- Organic certification timeline compression:Three-year pasture conversion requirements and audit backlogs are delaying new product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dairy Desserts Market |
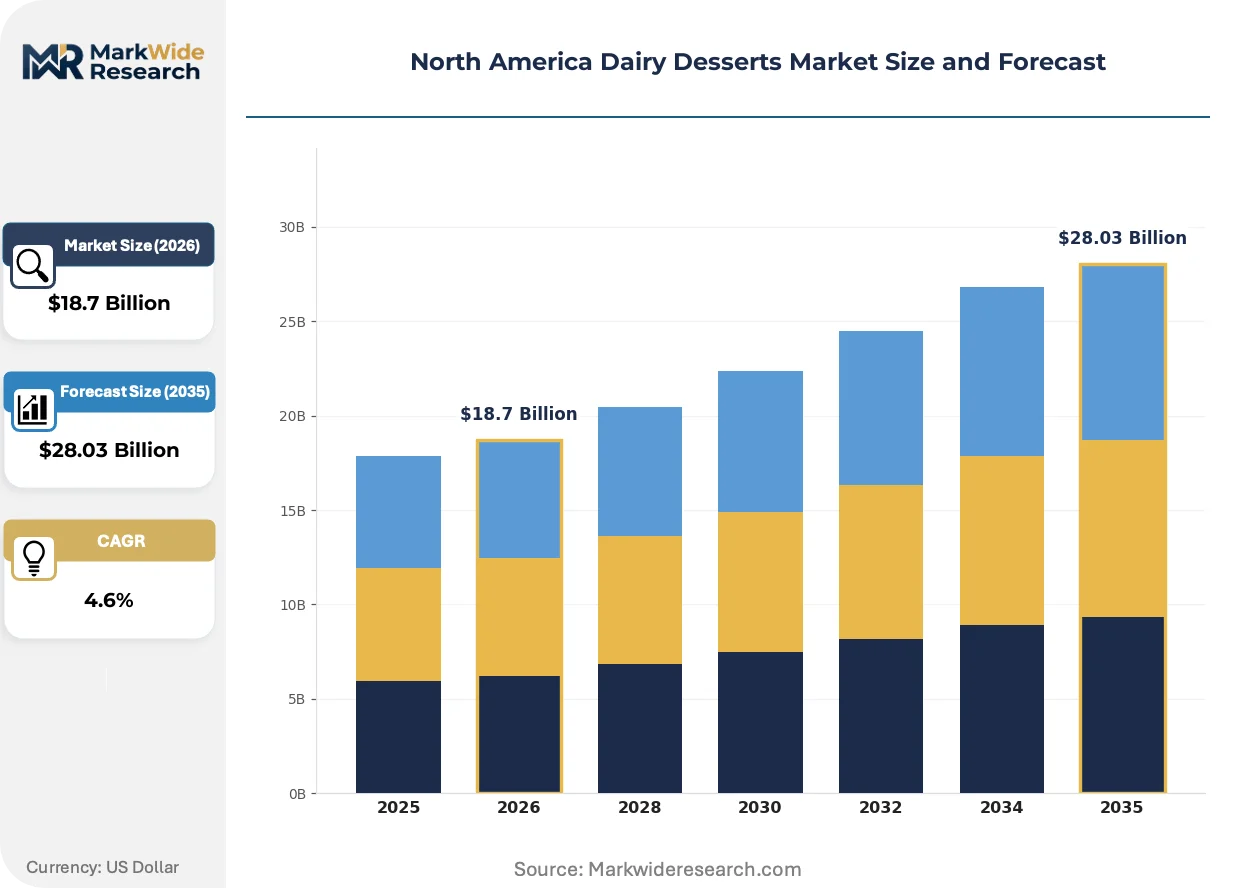
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ice Cream, Pudding, Yogurt, Cheesecake Ingredient Type: Dairy, Non-Dairy, Sugar Alternatives, Flavorings Packaging Type: Cup, Tub, Tube, Sachet Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service |
| Companies Covered | Unilever PLC, Nestlé S.A., General Mills Inc., The Kraft Heinz Company, Blue Bell Creameries, Wells Enterprises Inc., Dairy Farmers of America Inc., Danone S.A., Froneri International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dairy Desserts Market Trends and Innovations
Precision fermentation and cellular agriculture are destabilizing conventional ingredient sourcing models while state-level clean-label mandates accelerate reformulation cycles.
Precision fermentation-derived whey and casein proteins are fragmenting traditional dairy procurement structures. Mid-size creameries in Colorado and Oregon are piloting these inputs to bypass commodity butterfat markets. The technology is fragmenting supplier relationships as manufacturers dual-source from both dairy cooperatives and biotech ingredient firms.
FDA guidance on bioengineered food disclosure is tightening label requirements for precision fermentation and gene-edited inputs. Dessert manufacturers must now navigate overlapping federal disclosure rules and state-level clean-label mandates. Organic-certified product lines face the steepest compliance burden as they exclude both conventional and novel bioengineered inputs.
Direct-to-consumer subscription models are compressing traditional grocery channel dependence. Premium ice cream brands are building captive e-commerce fulfillment networks with dry ice logistics. This shift is most visible in coastal metropolitan markets where delivery density supports frozen last-mile economics.
North America Dairy Desserts Market Segmentation
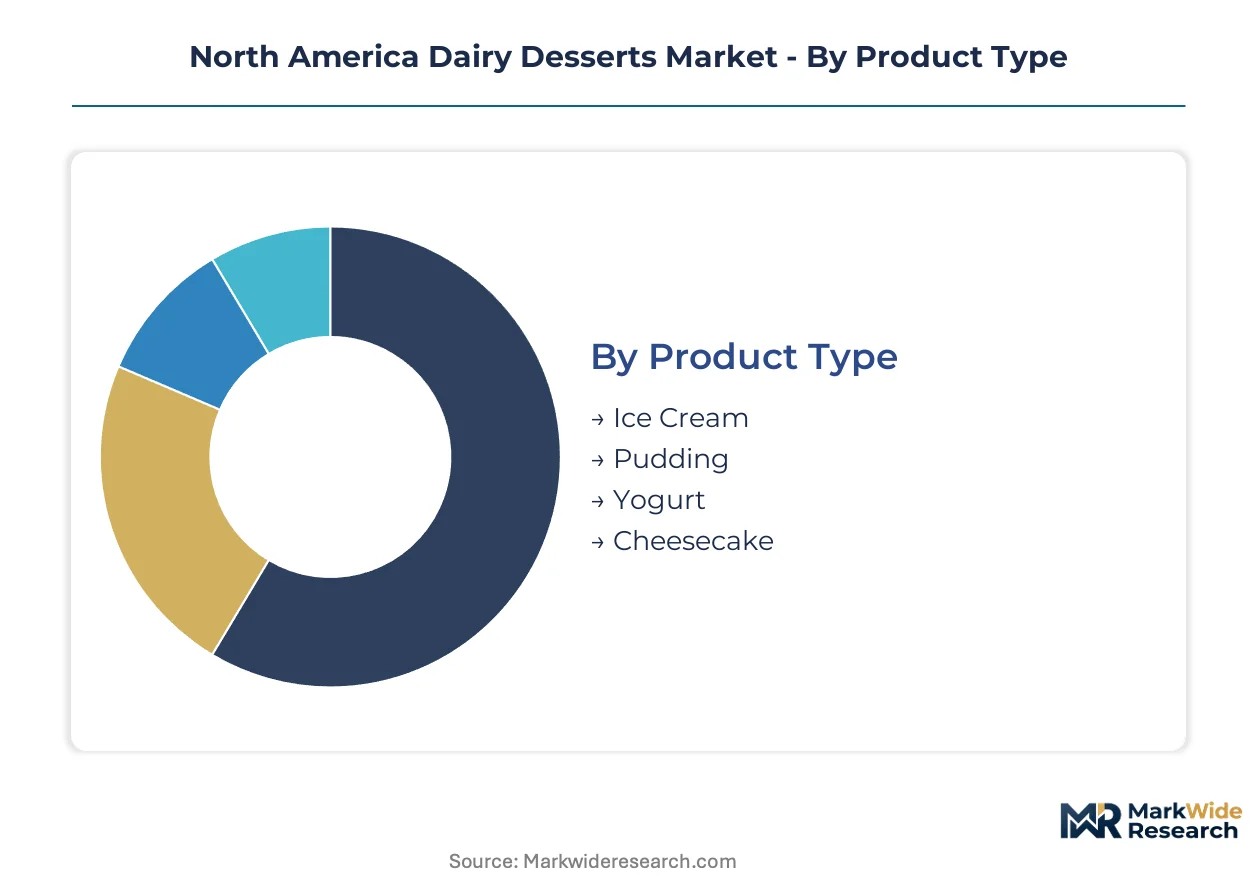
Dairy dessert manufacturers route distinct product configurations through channel-specific packaging and formulation strategies. Each segmentation axis determines margin structure, regulatory exposure, and capital deployment intensity across frozen, chilled, and ambient categories.
Product Type:
Channel placement varies sharply by temperature requirement and impulse versus planned purchase behavior.
- Ice Cream:Frozen formulations with minimum 10% milkfat under FDA 21 CFR 135 anchor year-round household replenishment through supermarket freezer cases. Demand concentrates in California and Texas metropolitan corridors where premium pint formats command shelf space.
- Pudding:Chilled, starch-thickened preparations with 4% minimum milkfat flow through convenience store single-serve placements and food service portion cups. Single-serve formats are expanding fastest through C-store chains targeting on-the-go consumption.
- Yogurt:Cultured dairy bases with live and active cultures span Greek-style strained preparations to drinkable formats, routing through both refrigerated retail cases and food service parfait programs.
- Cheesecake:Cream cheese and cultured dairy composite desserts with baked or no-bake preparations concentrate in food service dessert menus and frozen retail novelty lines.
Ice Cream dominates installed base. Pudding is where expansion concentrates.
Ingredient Type:
Cost tier stratification separates commodity formulations from certified organic and precision fermentation alternatives.
- Dairy:Conventional milk solids, cream, and butterfat sourced through Midwest cooperative networks remain the volume foundation for standard-tier products.
- Non-Dairy:Almond, oat, and coconut protein isolates achieve functional parity in frozen dessert applications, climbing the fastest as plant-forward portfolios expand retail shelf space.
- Sugar Alternatives:Erythritol, allulose, and monk fruit formulations target reduced-sugar label claims, concentrated in diabetic-friendly and keto-positioned product lines.
- Flavorings:Natural and artificial flavor systems, including inclusions and variegates, differentiate regional and seasonal limited-edition releases.
Dairy commands volume leadership. Non-Dairy is where portfolio investment concentrates.
Packaging Type:
Customer type determines format selection between household stock-up and immediate consumption occasions.
- Cup:Single-serve plastic or paperboard containers dominate food service and convenience channel placements for pudding and frozen novelties.
- Tub:Multi-serve paper or plastic pails anchor family-size ice cream and yogurt purchases through supermarket channels.
- Tube:Flexible squeeze formats for frozen novelty products target impulse purchase at checkout and C-store freezer sections.
- Sachet:Dry-mix powder packets for instant pudding preparation concentrate in value-oriented retail and institutional food service accounts.
Tub formats dominate household penetration. Cup formats are where channel expansion concentrates.
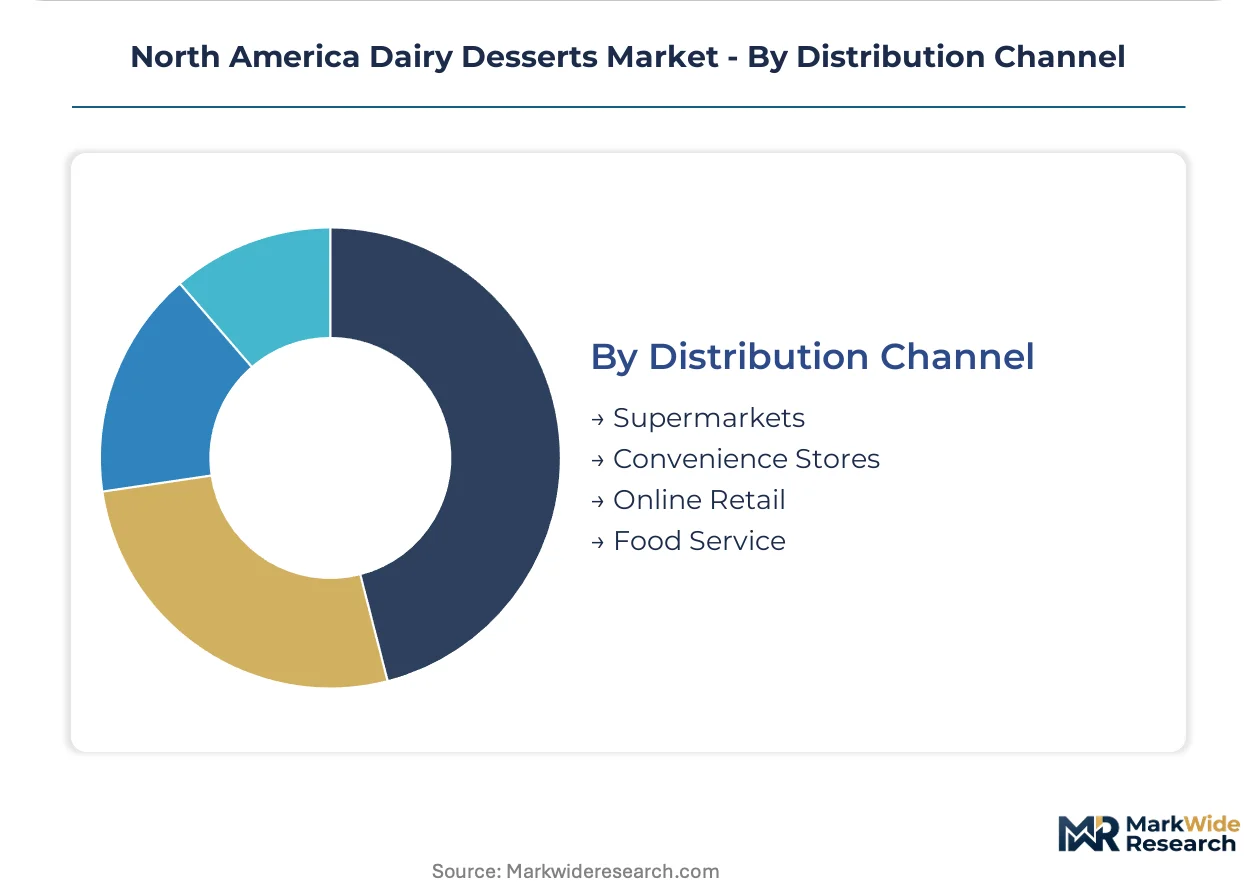
Distribution Channel:
Margin structure and cold-chain requirements segment route-to-market strategies across temperature-controlled and ambient pathways.
- Supermarkets:Full-line grocers with extensive frozen and refrigerated dairy cases provide the primary volume outlet for multi-serve ice cream, yogurt, and cheesecake.
- Convenience Stores:Limited-assortment retailers with grab-and-go freezer and cooler sections drive single-serve cup and tube format velocity.
- Online Retail:Direct-to-consumer and third-party delivery platforms with dry ice logistics are gaining fastest in coastal metropolitan markets with delivery density economics.
- Food Service:Restaurants, cafeterias, and institutional operators purchase bulk and portion-controlled formats for dessert menu inclusion.
Supermarkets dominate installed volume. Online Retail is where infrastructure investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California and Texas metropolitan corridors while Canadian and Mexican markets operate on thinner margin structures. This asymmetry shapes capital deployment patterns across the North American dairy desserts landscape.
United States
Los Angeles, Dallas-Fort Worth, and Houston metropolitan clusters anchor demand for premium pint formats and single-serve novelties. FDA 21 CFR 135 standards govern ice cream identity requirements, forcing reformulation discipline for plant-based alternatives. Wisconsin and Minnesota Grade A milk cooperatives supply the Midwest processing infrastructure that feeds national distribution networks.
Canada
Ontario and Quebec dairy boards administer supply-managed fluid milk quotas that stabilize input costs for dessert manufacturers. Health Canada and the Canadian Food Inspection Agency enforce bilingual labeling and compositional standards that extend product development timelines. Toronto and Vancouver retail corridors concentrate demand for organic-certified frozen desserts.
Mexico
Monterrey and Guadalajara modern trade channels present expansion targets for US-manufactured premium frozen novelties. NOM-185-SCFI-2012 establishes labeling and quality specifications for dairy-derived products sold through formal retail. Northern border states absorb cross-border production from Texas-based facilities serving price-sensitive segments.
North America Dairy Desserts Market Competitive Landscape
Concentration sits with multinational packaged food conglomerates wielding global dairy procurement networks and controlled cold-chain infrastructure. The vendor base stratifies across three archetypes: billion-dollar multinationals with integrated supply chains, regional creameries competing on localized flavor portfolios, and emerging precision fermentation ingredient suppliers. Competitive dynamics center on M&A activity consolidating regional brands and strategic partnerships locking in exclusive distribution through food service channels.
Within the multinational tier, Nestlé S.A. and Unilever PLC occupy positions defined by scale-advantaged milk solids sourcing and proprietary freezing technology deployment. Blue Bell Creameries exemplifies the regional loyalty archetype, competing through state-level market penetration rather than national distribution breadth. These three anchors illustrate the structural divergence between capital-intensive global platforms and geographically concentrated heritage brands.
| Leading Market Players |
|---|
| Unilever PLC |
| Nestlé S.A. |
| General Mills Inc. |
| The Kraft Heinz Company |
| Blue Bell Creameries |
| Wells Enterprises Inc. |
| Dairy Farmers of America Inc. |
| Danone S.A. |
| Froneri International Limited |
| Others |
Pricing and Supply Chain Analysis
Oat and almond protein isolates displacing conventional milk solids across frozen dessert formulations are redrawing procurement geography from Wisconsin dairy cooperatives toward California ingredient technology clusters while compressing butterfat-linked pricing premiums.
Pricing Analysis
The customization-premium spread separates configured-to-order organic certifications from standard-tier commodity formulations. Three-tier pricing structure across premium, standard, and economy levels reflects USDA organic grade, volume scale, and geographic delivery cost from Midwest processing hubs. Pricing pressure stems from plant-based alternatives forcing reformulation investments without corresponding price recovery. Food service operators exhibit highest price sensitivity due to compressed per-unit margins, while direct-to-consumer subscribers show lowest sensitivity.
Supply Chain Analysis
Just-in-time fluid milk delivery dominates standard-tier manufacturing, while strategic stockpiling of precision fermentation-derived proteins is emerging among premium-positioned creameries. Supply concentrates in the United States, Canada, and Mexico, with raw material dependencies on Grade A milk, oat protein isolates, and non-GMO stabilizer systems. Single-source vulnerability runs through Wisconsin and Minnesota cooperative networks controlling disproportionate Grade A volumes. Distribution runs through temperature-controlled supermarket and food service channels anchored by regional cold-chain infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America dairy desserts market is tightening around scarce HTST pasteurization and homogenization technician pools, with community college pipeline programs failing to replenish aging workforce cohorts faster than retirements accelerate.
For Market Incumbents: Fortify technician retention through apprenticeship partnerships with technical colleges and captive certification programs. Lock in exclusive distribution through food service channel partnerships before precision fermentation suppliers achieve scale. Vertical integration into precision fermentation R&D offsets commodity butterfat volatility threatening margin stability. For New Entrants and Emerging Players: Anchor in Mexico cross-border retail corridors where modern trade channels in Monterrey and Guadalajara remain underpenetrated by US premium frozen novelties. Exploit clean-label state mandates in Vermont and California as regulatory tailwinds for simplified ingredient panels. Pursue direct-to-consumer subscription models with dry ice logistics to bypass entrenched supermarket slotting fees. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors precision fermentation ingredient platforms over conventional dairy procurement networks. Long-term viability centers on cellular agriculture convergence enabling animal-free products meeting FDA identity standards. Acquisition targets should demonstrate dual-sourcing capabilities across dairy cooperatives and biotech ingredient firms. Monitor FDA guidance evolution on bioengineered food disclosure as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Cellular agriculture-derived proteins bypass commodity butterfat markets and supply volatility. |
| Organic Certification Investment | USDA three-year pasture conversion timelines secure shelf space expansion at major retailers. |
| Direct-to-Consumer Launch | Dry ice logistics networks in coastal metros compress traditional grocery channel dependence. |
| Food Service Distribution Lock | Exclusive dessert menu placements with regional restaurant chains defend volume against multinationals. |
| Clean-Label Reformulation | Non-GMO stabilizer systems meet Vermont and California additive disclosure mandates ahead of competitors. |
Research Methodology
Initial hypotheses were tested against primary input from dairy processing plant managers, retail category buyers, food service procurement directors, and precision fermentation R&D leads and refined through secondary validation against FDA 21 CFR 135 filings, USDA organic certification databases, Nielsen retail audit data, and SEC 10-K disclosures from packaged food conglomerates. Bottom-up volume builds triangulated with top-down macroeconomic anchors across the analysis window.
Variance decomposition isolated drivers across product type, ingredient category, packaging format, distribution channel, and metropolitan demand cluster segmentation dimensions. CAGRs were derived from slope-stabilized growth curves fitted to historical trajectory and structural breakpoint analysis. Forecast inputs incorporated fluid milk futures volatility patterns and precision fermentation capacity buildout announcements.
Decision-makers should treat outputs as directional under assumptions of stable FDA identity standards and continued organic certification expansion; material deviation would warrant model refresh. Revision becomes warranted when precision fermentation cost parity crosses thresholds or clean-label mandates propagate beyond California and Vermont.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
North America A2 Milk Market
Dairy Products
Dry Buttermilk Market
Dairy Products
Citrus Yogurt Market
Dairy Products
Filled Cheese Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Germany Casein and Caseinates Market
Dairy Products
UAE Camel Dairy Market
Dairy Products
Dry Whole Milk Powder Market
Dairy Products
Goat Milk Products Market
Dairy Products
Lactose-Free Cheese Market
Dairy Products
Goat Milk Powder Market
Dairy Products
United States Casein Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
Fruit Yogurt Market
Dairy Products
Sweet Whey Market
Dairy Products
Cheese Packaging Market