
 Africa Telecom Towers and Allied Market | 2026-2036
Africa Telecom Towers and Allied Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Telecom Towers and Allied Market Analysis
Market Context
A chronic shortage of certified tower riggers and RF engineers across East and West Africa is unwinding deployment timelines for several infrastructure programs. IHS Towers leverages its scale across multiple markets to sustain co-location revenue streams in Nigeria and Côte d'Ivoire. American Tower Corporation anchors its position through long-term lease agreements with MTN Group and Airtel Africa in South Africa and Kenya. Helios Towers differentiates by specializing in markets with lower tower density such as Madagascar, Malawi, and Senegal.
Technical Definition and Segments
Africa telecom towers and allied infrastructure comprise steel or concrete structures ranging from 30 to 120 meters in height, designed to host antennas, transmission equipment, and power systems for wireless communication networks across varied terrain and climate conditions. These structures enable mobile broadband coverage extension, backhaul connectivity, and emergency communication services in both urban centers and remote rural settlements. Lattice towers dominate new construction across the Sahel and savanna regions where wind load tolerance and structural durability justify higher steel content and foundation costs. Co-location services generate the most stable revenue pools as operators seek to reduce capital intensity per site. Managed services including remote monitoring and energy optimization are expanding fastest as tower companies assume operational burdens previously retained by mobile network operators.
Regulatory Environment
Nigeria's Nigerian Communications Commission mandates infrastructure sharing guidelines that compel operators to lease rather than build proprietary towers. South Africa's Independent Communications Authority enforces universal service obligations requiring coverage extension to underserved municipalities. Ghana's National Communications Authority implements tower zoning and environmental assessment protocols that lengthen permitting cycles. Stakeholders must monitor how spectrum auction timelines in Ethiopia and the Democratic Republic of Congo align with tower readiness commitments.
Market Dynamics
Tower sharing mandates across Nigeria, South Africa, and Kenya are compressing capital deployment cycles and forcing mobile network operators to divest proprietary infrastructure to independent tower companies.
Growth Catalysts
- 4G/5G Spectrum Allocations:Regulators in Ethiopia and the Democratic Republic of Congo are releasing mid-band frequencies that require densified tower networks for effective coverage propagation.
- Nigerian Communications Commission Sharing Guidelines:These infrastructure-sharing mandates compel operators to lease rather than build, accelerating co-location velocity across Lagos and Abuja corridors.
- Hybrid Energy Systems:Solar-diesel hybrid power installations are reducing opex burdens at off-grid rural sites where grid electricity remains unreliable.
Market Restraints
- Steel Price Volatility:Lattice tower fabrication costs fluctuate with international steel indices, squeezing margins for greenfield construction programs in the Sahel.
- Certified Rigger Shortage:East and West Africa lack sufficient trained personnel for tower erection and antenna installation, extending deployment timelines by months.
- Permitting Delays:Ghana's National Communications Authority environmental assessment protocols lengthen zoning approval cycles, freezing site readiness schedules.
Strategic Opportunities
- Madagascar and Malawi Expansion:These lower tower-density markets offer first-mover positioning for independent infrastructure providers seeking portfolio diversification.
- Managed Services Contracts:Remote monitoring and energy optimization services allow tower companies to assume operational burdens previously retained by mobile network operators.
- South Africa Universal Service Obligations:The Independent Communications Authority's coverage mandates to underserved municipalities create anchor tenancy commitments for new rural builds.
Industry Challenges
- RF Engineer Scarcity:The chronic shortage of radio frequency specialists across sub-Saharan markets unwinds network optimization timelines for 5G readiness programs.
- Legacy Power Infrastructure:Diesel-dependent sites face escalating fuel logistics costs and carbon compliance pressures from emerging ESG disclosure requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Telecom Towers and Allied Market |
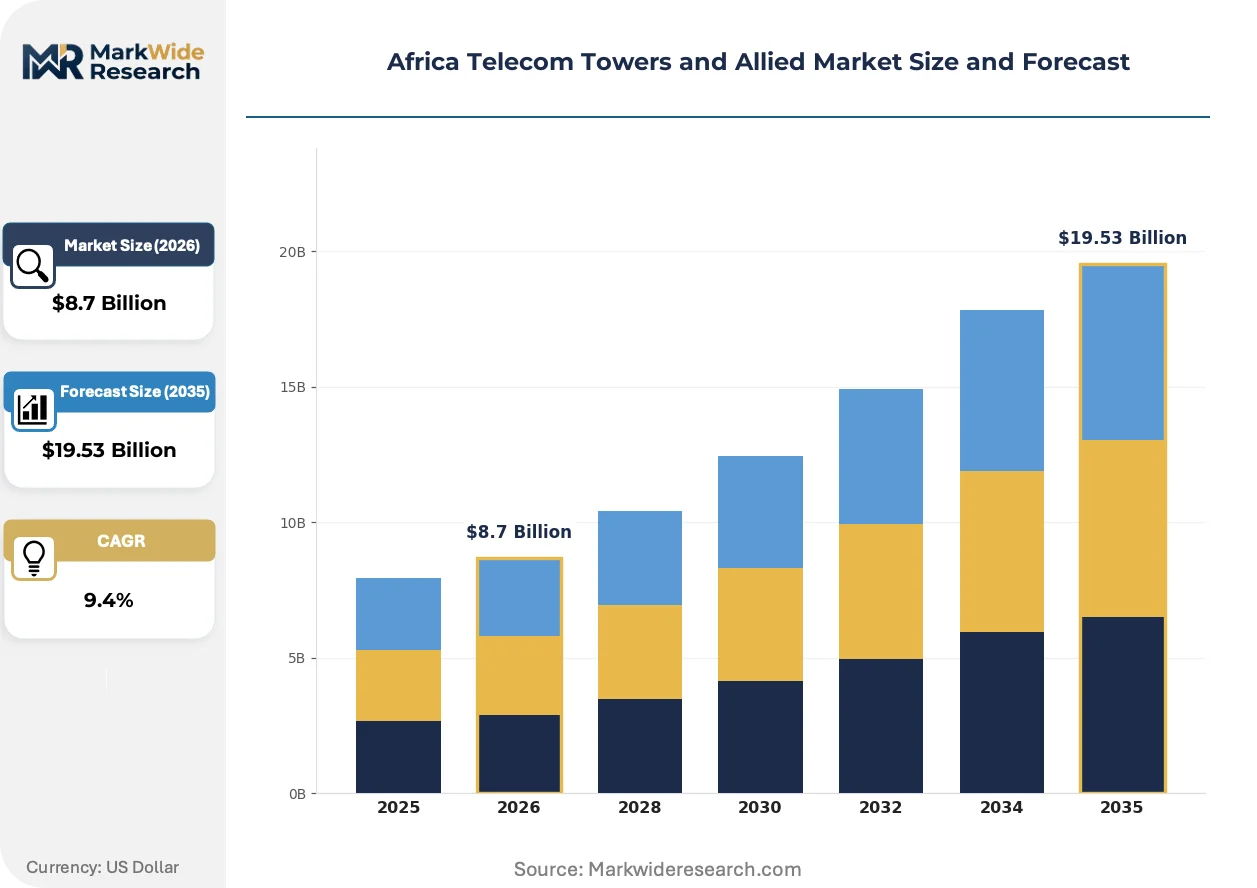
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Infrastructure Type: Monopole, Lattice, Stealth, Guyed Service Type: Co-location, Managed Services, Maintenance, Construction Deployment Model: Shared, Dedicated, Distributed, Mobile Client Type: Telecom Operators, Private Enterprises, Government, Others |
| Companies Covered | IHS Towers (IHS Holding Limited), American Tower Corporation, Helios Towers Plc, SBA Communications Corporation, MTN Group Ltd., Vodacom Group Ltd., Airtel Africa plc, Telkom SA SOC Ltd., Liquid Intelligent Technologies, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Telecom Towers and Allied Market Emerging Trajectories
Active network sharing architectures and renewable energy integration are restructuring how tower assets are financed, operated, and monetized across African telecommunications infrastructure.
Modular rapid-deployment towers are displacing conventional steel lattice structures for emergency coverage restoration and temporary event capacity. Mobile network operators in Kenya and Nigeria are adopting these containerized systems for disaster response scenarios. The technology is displacing permanent construction timelines in politically unstable or geographically inaccessible regions where conventional civil works face security risks.
South Africa's Independent Communications Authority has tightened universal service obligation enforcement, requiring coverage extension to underserved municipalities as a license condition. This regulatory pressure is accelerating rural tower construction commitments from major operators. The policy is reshaping capex allocation patterns, with infrastructure funds redirecting investment toward low-ARPU regions previously deprioritized.
Co-location tenancy aggregation is consolidating buyer power among mobile network operators seeking to reduce per-site capital intensity. Tower companies are responding with multi-tenant pricing frameworks that reward volume commitments across national portfolios. This behavioral shift is most visible in Nigeria, where MTN Group and Airtel Africa are standardizing lease negotiations through centralized procurement functions.
Africa Telecom Towers and Allied Market Segmentation
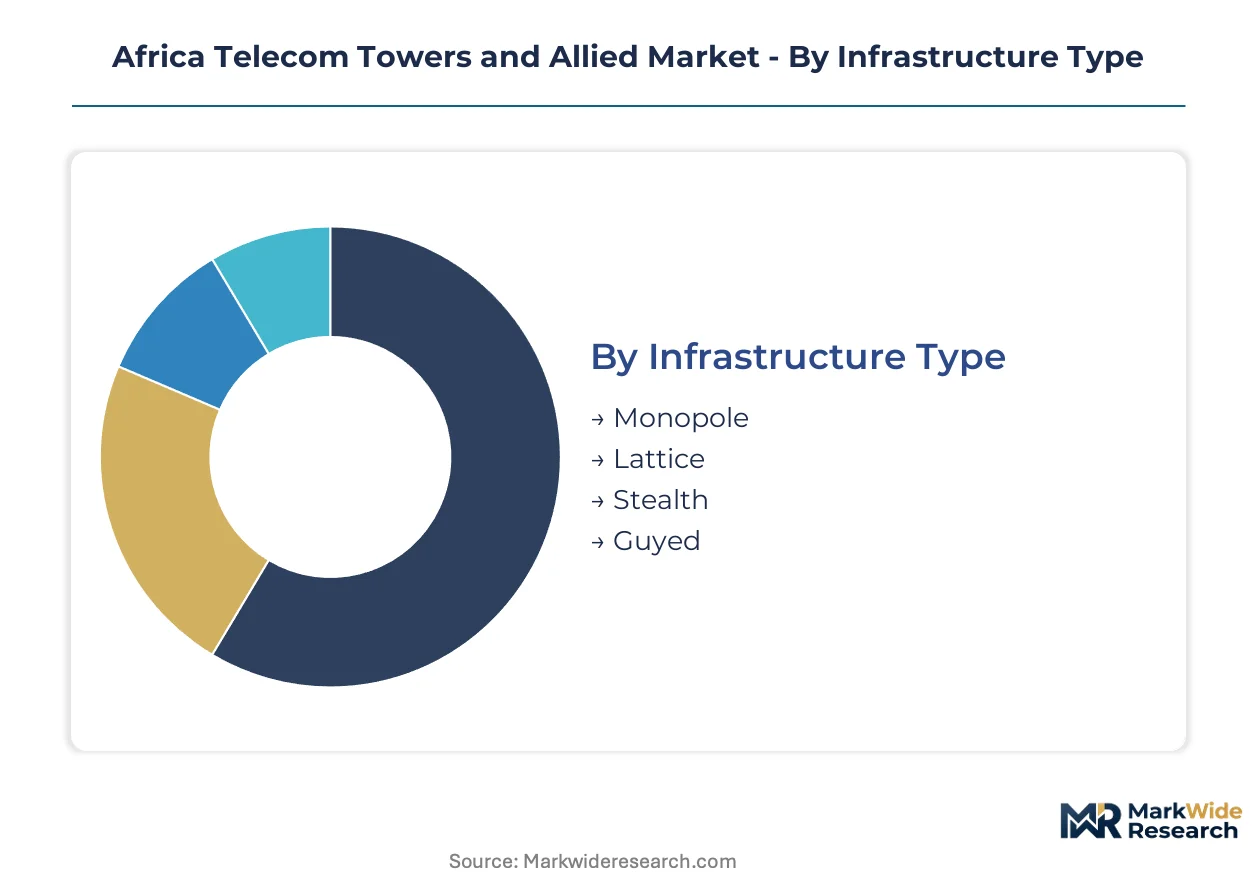
Africa's telecom tower market fragments across infrastructure design, service delivery, and client economics. Understanding these segment boundaries clarifies where capital efficiency and tenancy density determine profitability for independent tower companies and mobile network operators alike.
Infrastructure Type:
Margin pools concentrate in lattice and monopole deployments where steel procurement scale and foundation engineering expertise create defensible cost positions.
- Lattice:Triangular or square steel frameworks withstand high wind loads across Sahel and savanna regions. Nigerian and Kenyan operators specify lattice designs for macro-coverage sites where structural durability justifies higher material costs and extended civil works timelines.
- Monopole:Single-shaft concrete or steel structures minimize ground footprint for urban deployments. Demand clusters in Lagos, Nairobi, and Johannesburg where zoning restrictions and land scarcity compress site availability.
- Stealth:Architecturally disguised towers blend into heritage or residential zones. South African municipalities enforce aesthetic requirements that elevate stealth premiums in Cape Town and Durban corridors.
- Guyed:Tension-wire supported masts reduce steel tonnage for height requirements above 80 meters. Madagascar and Malawi deployments favor guyed structures where transport logistics constrain lattice component delivery.
Lattice holds installed capacity across rural Africa. Monopole is rotating up the share rankings in dense urban corridors.
Service Type:
Revenue stability varies sharply by service depth, with operational assumption contracts commanding longer tenors than transactional construction work.
- Co-location:Multi-tenant leasing of antenna space generates recurring revenue streams with 10-15 year contract structures. IHS Towers and American Tower Corporation anchor portfolios on co-location density in Nigeria and South Africa where regulatory sharing mandates accelerate tenancy stacking.
- Managed Services:Remote monitoring, energy optimization, and passive infrastructure operations transfer operational burdens from mobile network operators to tower companies. Ethiopian and Democratic Republic of Congo rollouts drive fastest expansion as operators divest non-core functions.
- Maintenance:Preventive and corrective site upkeep sustains network availability metrics. Demand concentrates in aging West African portfolios where original build quality varies.
- Construction:Greenfield tower erection and civil works deliver project-based revenue with lump-sum pricing. Ghana's extended permitting cycles compress construction margins despite pipeline depth.
Co-location holds installed capacity. Managed services is climbing the fastest as operational outsourcing deepens across sub-Saharan markets.
Deployment Model:
Capital efficiency and tenancy economics diverge meaningfully across ownership and operational structures.
- Shared:Infrastructure pooling among multiple operators reduces per-site capital intensity. Nigerian Communications Commission guidelines mandate shared deployment as default for new macro sites in Lagos and Abuja.
- Dedicated:Single-tenant proprietary towers retain strategic value for coverage leadership in competitive markets. MTN Group maintains dedicated assets in South Africa for universal service obligation compliance.
- Distributed:Small-cell and micro-site networks densify coverage in urban centers. Nairobi and Johannesburg pilots test distributed architectures for 5G capacity layers.
- Mobile:Rapid-deployment containerized systems serve emergency restoration and temporary events. Kenyan operators deploy mobile towers for political rally coverage and disaster response.
Shared infrastructure holds installed capacity. Distributed deployment is gaining share fastest as mid-band spectrum allocations drive densification requirements.
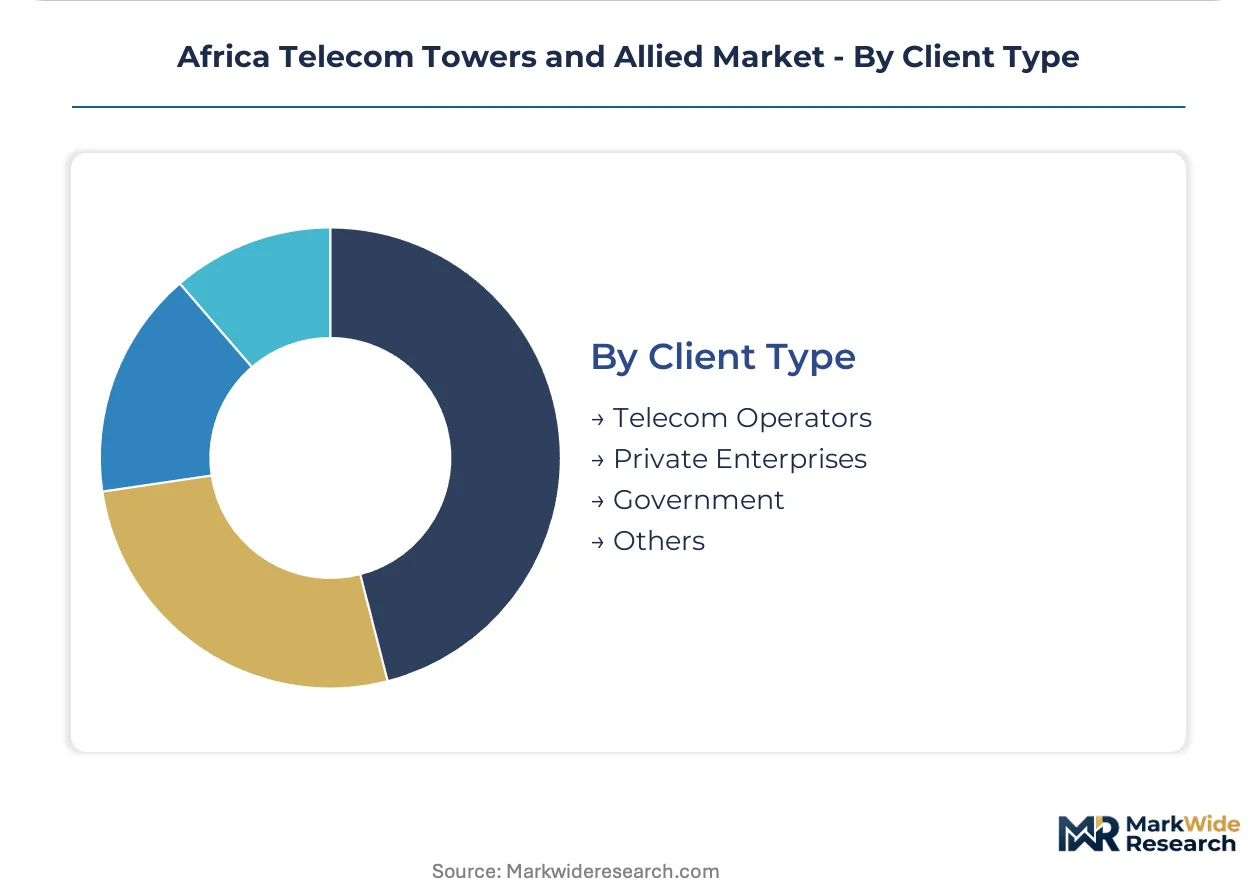
Client Type:
Purchasing power and contract sophistication vary across public and private demand pools.
- Telecom Operators:Mobile network operators generate core demand through lease-back arrangements and anchor tenancy commitments. Airtel Africa and MTN Group consolidate procurement functions to strengthen negotiating position across national portfolios.
- Private Enterprises:Mining, logistics, and agricultural operations procure captive coverage for remote facilities. Congolese mining concessions and South African platinum belt operations drive private enterprise demand.
- Government:Universal service funds and emergency communication networks anchor rural builds. South Africa's Independent Communications Authority enforces coverage mandates that redirect infrastructure investment toward underserved municipalities.
- Others:Broadcasters, utilities, and neutral host providers occupy residual demand segments. Limited scale constrains dedicated tower construction for these verticals.
Telecom operators hold installed capacity. Private enterprise is rotating up the share rankings as industrial digitization extends beyond cellular backhaul.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Nigerian Communications Commission anchors the continent's largest tower market through infrastructure-sharing mandates that compel lease-based deployment models. Regulators across sub-Saharan Africa are accelerating 4G and 5G spectrum releases while enforcing coverage obligations that reshape capital allocation patterns.
Nigeria
Lagos and Abuja corridors concentrate co-location demand as MTN Group and Airtel Africa consolidate procurement functions. The Nigerian Communications Commission's sharing guidelines compress proprietary build timelines and accelerate tenancy stacking. IHS Towers leverages scale advantages across multiple state clusters to sustain recurring revenue streams.
South Africa
Johannesburg and Cape Town urban corridors drive monopole deployments where zoning restrictions compress site availability. The Independent Communications Authority enforces universal service obligations requiring coverage extension to underserved municipalities. American Tower Corporation anchors position through long-term lease agreements with major operators.
Kenya
Nairobi's dense urban fabric favors distributed small-cell architectures for 5G capacity layering. Tower sharing regulations reshape capital deployment patterns and force divestiture of proprietary infrastructure. Mobile rapid-deployment systems serve emergency restoration scenarios in politically sensitive regions.
Ethiopia
Addis Ababa anchors subscriber growth programs where penetration remains below regional averages. Mid-band spectrum allocations require densified tower networks for effective coverage propagation. Managed services contracts expand fastest as operators divest non-core operational functions.
Democratic Republic of Congo
Kinshasa and mining belt concessions drive private enterprise demand for captive coverage solutions. Spectrum auction timelines must align with tower readiness commitments for effective network rollout. Lower tower density creates first-mover positioning opportunities for independent infrastructure providers.
Africa Telecom Towers and Allied Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the African tower ecosystem. Independent tower companies concentrate co-location revenue pools while mobile network operators retain strategic coverage assets for competitive differentiation. Three archetypes dominate: scale-driven multi-market platforms, geography-specialized regional operators, and captive infrastructure divisions of major carriers. Consolidation proceeds through tower portfolio acquisitions and long-term anchor tenancy commitments that lock in revenue visibility.
Within the scale-driven tier, IHS Towers and American Tower Corporation exemplify multi-market platform strategies that span Nigeria, South Africa, and Kenya. Helios Towers occupies a specialized position targeting lower-density markets including Madagascar, Malawi, and Senegal where first-mover advantages compound. These three anchors represent divergent geographic concentration philosophies rather than competing directly for identical site portfolios.
| Leading Market Players |
|---|
| IHS Towers (IHS Holding Limited) |
| American Tower Corporation |
| Helios Towers Plc |
| SBA Communications Corporation |
| MTN Group Ltd. |
| Vodacom Group Ltd. |
| Airtel Africa plc |
| Telkom SA SOC Ltd. |
| Liquid Intelligent Technologies |
| Others |
Supply Flow & Price Mechanics
Ninety-day steel inventory cycles at Nigerian and South African fabrication yards concentrate pricing power among lattice tower suppliers serving the Sahel corridor. This lead-time compression amplifies margin pressure when international steel indices spike, while co-location tenancy density determines which tower companies absorb input volatility versus passing through escalation clauses.
Pricing Analysis
Nigerian lease rates for co-location services command premiums over Malawian and Senegalese equivalents, reflecting Lagos corridor tenancy density and regulatory-mandated sharing velocity. Contract structures stratify across anchor tenancy commitments, volume-scaled multi-tenant frameworks, and project-based greenfield construction with divergent margin profiles. Steel price volatility and certified rigger scarcity are compressing construction margins in Ghana and Kenya, where extended permitting timelines freeze site readiness schedules. Mobile network operators consolidating procurement functions exhibit acute price sensitivity, while mining enterprises procuring captive coverage accept premium positioning for remote site reliability.
Supply Chain Analysis
Port congestion at Durban and Lagos gateways elevates inbound logistics costs for lattice steel sections sourced from Chinese and Turkish mills. Tower fabrication concentrates in South Africa, Nigeria, and Egypt where domestic steel rolling capacity supports regional deployment programs. Supply chains rest on galvanized steel coil, concrete foundation materials, and hybrid solar-diesel power systems as critical inputs. Single-source vulnerability in certified rigger labor pools across East and West Africa threatens erection timelines. Distribution runs through independent tower company site portfolios and mobile network operator lease-back arrangements rather than merchant wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Co-location platform economics are reaching an inflection as active network sharing architectures and neutral host interoperability standards restructure tenancy aggregation mechanics across sub-Saharan markets.
For Market Incumbents: Compound tenancy density in Nigerian and South African corridors through anchor lease extensions and energy optimization service bundling. Defend against modular rapid-deployment tower substitutes by accelerating rural site hardening programs. Secure captive rigger training pipelines to unwind deployment timeline extensions threatening co-location revenue recognition. For New Entrants and Emerging Players: Differentiate on managed services depth in Ethiopian and Democratic Republic of Congo markets where operational outsourcing accelerates fastest. Target Madagascar and Malawi expansion corridors where lower tower density offers first-mover positioning without incumbent scale advantages. Pursue government universal service obligation contracts as anchor tenancy foundations for greenfield portfolio builds. For Investors and Strategic Acquirers: Carve-out targets emerge from mobile network operator captive infrastructure divisions divesting non-core tower assets to comply with Nigerian Communications Commission sharing mandates. Long-term viability hinges on tenancy stack density and power opex optimization capabilities across the analysis window. Monitor spectrum auction timelines in Ethiopia and the Democratic Republic of Congo as inflection indicators for tower readiness commitment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Anchor Tenancy Consolidation | Long-term lease agreements with MTN Group and Airtel Africa lock in revenue visibility across Nigerian state clusters. |
| Hybrid Energy System Deployment | Solar-diesel installations at off-grid rural sites reduce operational expenditure burdens and carbon compliance exposure. |
| Managed Services Expansion | Remote monitoring and energy optimization contracts transfer operational burdens from Ethiopian operators to tower companies. |
| Rapid-Deployment Tower Piloting | Containerized systems for Kenyan disaster response displace permanent construction timelines in security-constrained regions. |
| Rural Coverage Mandate Compliance | South Africa's universal service obligations redirect infrastructure investment toward underserved municipalities. |
Methodological Framework
Cross-validation between tower company tenancy disclosure patterns and mobile network operator capex allocation filings anchors the qualitative findings. Primary interviews with infrastructure portfolio managers, regulatory affairs directors at the Nigerian Communications Commission and South Africa's Independent Communications Authority, procurement leads at MTN Group and Airtel Africa, and site engineering supervisors across Lagos and Nairobi clusters combine with secondary validation. Secondary sources include tower company lease-back agreement disclosures, national communications authority spectrum auction notices, customs data on steel section imports, and universal service fund disbursement records. Bottom-up tenancy aggregation models and top-down infrastructure investment flow analysis provide triangulation.
Sensitivity analysis around steel price index trajectories and co-location tenancy ramp rates frames projection robustness across the modeling period. Segmentation dimensions include infrastructure type, service depth, deployment model, and client archetype with geographic concentration overlays. CAGRs derive from tenancy stacking velocity assumptions and per-site revenue yield trajectories. Forecast inputs incorporate spectrum release schedules in Ethiopia and the Democratic Republic of Congo and hybrid energy system penetration curves at off-grid sites.
Material uncertainties — regulatory enforcement intensity, rigger labor pool expansion, and steel index volatility — sit outside the modeled envelope. Forecasts reflect assumptions about tenancy commitment duration and power system cost curves. Recalibration cycles align with material shifts in spectrum allocation timelines and infrastructure-sharing mandate enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Small Cell Backhaul Market
Telecommunications Infrastructure
United States Telecom Towers Market
Telecommunications Infrastructure
Nigeria Telecom Tower Market
Telecommunications Infrastructure
Vietnam Telecom Towers Market
Telecommunications Infrastructure
Global Optical Transport Network (OTN) Equipment Market
Telecommunications Infrastructure
Chile Telecom Tower Market
Telecommunications Infrastructure
OTN Equipment Market
Telecommunications Infrastructure
Colombia Telecom Tower Market
Telecommunications Infrastructure
5G Infrastructure Equipment Market
Telecommunications Infrastructure
Israel Telecom Market
Telecommunications Infrastructure
Global Integrated Telecom Infrastructure Market
Telecommunications Infrastructure
Slovenia Telecom Market
Telecommunications Infrastructure
5G Infrastructure Market
Telecommunications Infrastructure
Saudi Arabia Telecom Towers Market
Telecommunications Infrastructure
Kenya Telecom Tower Market
Telecommunications Infrastructure
NLD and ILD Telecom Service Market