
 South Africa Cybersecurity Market | 2026-2036
South Africa Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Cybersecurity Market Analytics
Multi-source vendor strategies is recalibrating how South African enterprises build resilience against distributed threats. Cisco Systems leverages its channel depth to dominate network security installations across mining and energy corridors. Deloitte Cyber Risk Services anchors its position through advisory-led engagements that merge compliance mapping with incident response retainers. Palo Alto Networks competes on platform consolidation, reducing tool sprawl for mid-market clients migrating from point-product stacks.
South Africa cybersecurity encompasses technologies, services, and governance frameworks designed to protect digital assets from unauthorized access, disruption, or exfiltration, spanning firewalls with deep packet inspection, endpoint detection and response agents, and zero-trust architecture implementations. Its primary purpose centers on safeguarding critical infrastructure, financial transaction integrity, and citizen data across connected enterprise environments. Network Security leads current procurement volumes as legacy perimeter upgrades absorb the bulk of enterprise capital allocation, while Cloud Security represents the fastest-expanding category as South African banks and insurers accelerate SaaS migration. Managed Security Services captures disproportionate margin pools because local skills scarcity allows providers to command premium pricing for 24/7 security operations center coverage.
South Africa's national cybersecurity policy framework intersects with the Protection of Personal Information Act enforced by the Information Regulator, the Financial Sector Conduct Authority's operational resilience guidelines, and ISO 27001 certification requirements adopted by major listed enterprises. These standards collectively elevate baseline security spending by mandating breach notification timelines, encryption standards, and third-party risk assessments. Stakeholders must monitor whether proposed critical infrastructure protection legislation expands regulatory scope beyond financial services into energy, transport, and healthcare networks.
Market Dynamics
The Protection of Personal Information Act enforcement is compressing enterprise procurement cycles as Johannesburg financial institutions race to upgrade data governance frameworks before regulatory deadlines.
Growth Catalysts
- POPIA Compliance Deadlines:The Protection of Personal Information Act mandates encryption standards and breach notification protocols, forcing enterprise security budget reallocations across Gauteng headquarters.
- Banking Cloud Migration:South African financial institutions are accelerating SaaS adoption, creating immediate demand for cloud-native security architectures and zero-trust implementations.
- Managed Security Services Premium Pricing:Local cybersecurity skills scarcity allows Johannesburg-based providers to command elevated rates for 24/7 security operations center coverage.
Market Restraints
- Specialized Talent Scarcity:South Africa produces insufficient certified security architects and incident response specialists, inflating personnel costs for enterprise security teams.
- Legacy Infrastructure Debt:Mining and energy corridors operate decades-old operational technology systems that resist modern endpoint detection integration without complete replacement.
- Import-Dependent Hardware Supply:Firewall appliances and specialized network security hardware concentrate manufacturing in East Asian supply chains, exposing procurement to currency volatility and shipping delays.
Strategic Opportunities
- Western Cape Expansion:Cape Town's emerging fintech cluster generates underserved demand for mid-market security platforms as venture-backed startups scale beyond basic protections.
- Critical Infrastructure Legislation:Proposed expansion of regulatory scope beyond financial services into energy, transport, and healthcare networks would create compliance-driven procurement waves.
- AI-Augmented Threat Detection:Convergence of machine learning analytics with traditional security information and event management systems enables predictive threat hunting for enterprise clients.
Industry Challenges
- Certification Pipeline Bottlenecks:ISO 27001 and specialized cloud security certification timelines stretch 8-14 months, delaying contract eligibility for service providers.
- Operational Technology Integration Friction:Industrial control systems in mining and energy sectors require customized security architectures that resist standardized product deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Cybersecurity Market |
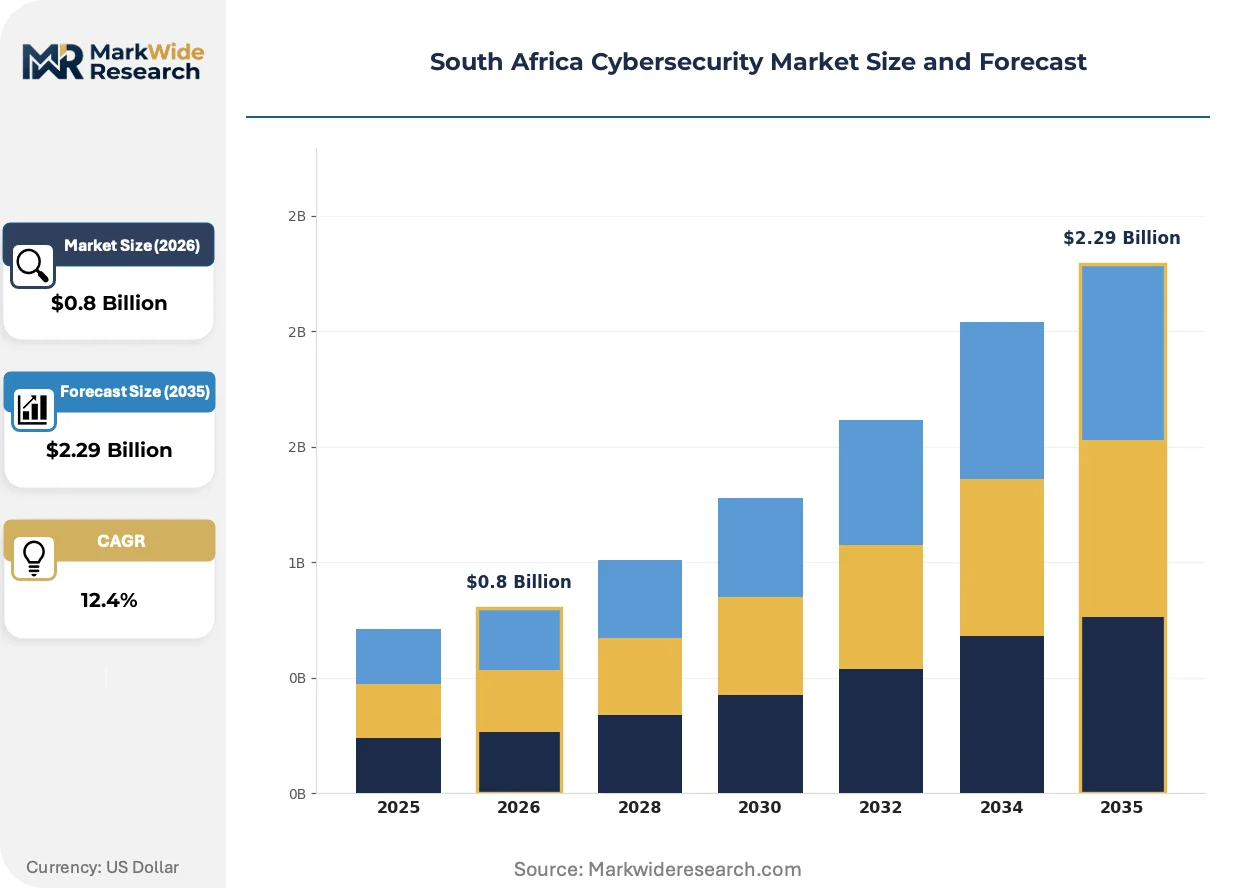
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $2.29 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endpoint Security, Network Security, Cloud Security, Application Security Deployment Model: On-premises, Cloud-based, Hybrid, Managed Services End User: Government, BFSI, Healthcare, Telecommunications Service Type: Consulting, Managed Security Services, Training, Incident Response |
| Companies Covered | Fortinet, Deloitte Cyber Risk Services, Cisco Systems, Factosecure, PwC Cybersecurity & Privacy, Palo Alto Networks, Trend Micro, Orange Cyberdefense, Check Point Software Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Cybersecurity Market Evolving Landscape
Zero-trust architecture is displacing perimeter-based security models as South African enterprises confront distributed workforces and multi-cloud environments. Three distinct shifts are restructuring competitive positioning and procurement patterns.
Extended detection and response platforms aggregate telemetry across endpoints, networks, and cloud workloads into unified analyst consoles. Mid-market enterprises in Johannesburg and Cape Town are adopting these consolidated stacks to reduce tool sprawl and staffing overhead. This consolidation is expanding into the managed security services segment, where providers differentiate through integrated threat intelligence feeds rather than point-product reselling.
The Financial Sector Conduct Authority's operational resilience guidelines now mandate maximum recovery time objectives for critical banking systems. This regulatory pressure forces institutions to deploy automated failover architectures and redundant security operations centers. Tier-one banks respond by establishing secondary processing sites in Durban and Pretoria to satisfy geographic distribution requirements.
Enterprise buyers are unbundling traditional annual security software licenses in favor of consumption-based pricing tied to monitored asset volumes. This shift compresses vendor cash conversion cycles while aligning costs to actual deployment scale. The Western Cape fintech cluster exhibits the most aggressive adoption of this model, negotiating monthly billing arrangements with emerging security-as-a-service providers.
South Africa Cybersecurity Market Segmentation
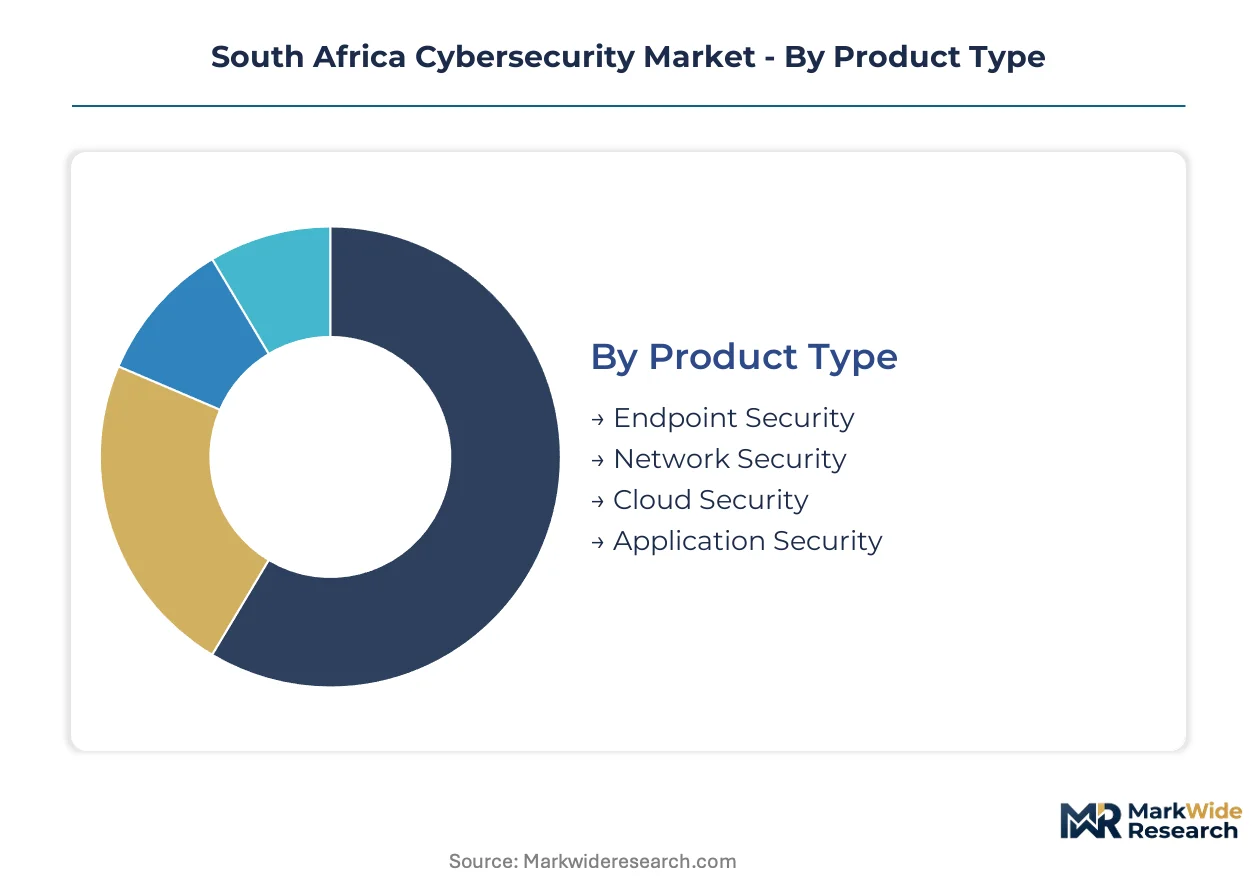
South African enterprises navigate procurement through four intersecting dimensions. Product type determines capital allocation between perimeter upgrades and cloud-native architectures. Deployment model shapes skills requirements and regulatory compliance pathways. End user concentration in Johannesburg's financial district drives premium pricing. Service type selection reflects chronic talent scarcity.
Product Type:
ISO 27001 certification mandates vary sharply across product categories, with cloud security suites requiring the most extensive third-party attestation.
- Network Security:Firewalls with deep packet inspection and intrusion prevention systems form the backbone of legacy perimeter protection. Mining and energy corridors in Mpumalanga and the Northern Cape absorb the bulk of current procurement as these sectors upgrade decades-old infrastructure. POPIA encryption requirements are forcing wholesale replacement of uninspectable legacy appliances.
- Cloud Security:Cloud-native architectures encompassing CASB, CWPP, and zero-trust network access solutions protect distributed SaaS environments. Johannesburg-based banks and insurers are accelerating adoption as core systems migrate off-premises. The Protection of Personal Information Act compels encryption key management and data residency controls that on-premises tools cannot satisfy.
- Endpoint Security:EDR and XDR agents monitor device-level threats across hybrid workforces.
- Application Security:SAST, DAST, and runtime protection tools secure DevOps pipelines.
Leading the category by volume: Network Security. Growing fastest: Cloud Security.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises builds from operational expenditure models favored by mid-market entrants.
- Managed Services:Johannesburg-based providers deliver 24/7 SOC coverage, threat hunting, and incident response through subscription arrangements. Local skills scarcity allows premium pricing at 40-60% above equivalent internal staffing costs. The Western Cape fintech cluster exhibits particular appetite for consumption-based billing tied to monitored asset volumes.
- Cloud-based:Pure SaaS delivery eliminates hardware procurement cycles and enables rapid scaling. Tier-two banks in Durban and Pretoria favor this model for secondary processing sites required under Financial Sector Conduct Authority resilience guidelines.
- On-premises:Self-managed appliances retain dominance in classified government environments.
- Hybrid:Mixed architectures balance legacy system constraints with cloud agility.
Dominant by revenue: Managed Services. Steepest expansion trajectory: Cloud-based.
End User:
Application criticality determines security spend intensity, with financial transaction integrity commanding the highest investment thresholds.
- BFSI:Banking, financial services, and insurance institutions face overlapping compliance burdens from POPIA, the Financial Sector Conduct Authority, and international card network standards. Johannesburg's financial district concentrates headquarters procurement for zero-trust architectures and redundant SOC facilities.
- Government:National and provincial departments manage citizen data under strict information classification regimes. State Security Agency requirements for air-gapped systems sustain demand for specialized on-premises deployments resistant to cloud migration.
- Healthcare:Hospitals and medical schemes protect patient records under POPIA and professional council guidelines.
- Telecommunications:Mobile network operators defend signaling infrastructure and subscriber databases.
Highest spend per employee: BFSI. Fastest procurement cycle acceleration: Government.
Service Type:
Margin concentration follows capability scarcity, with incident response retainers capturing disproportionate value pools.
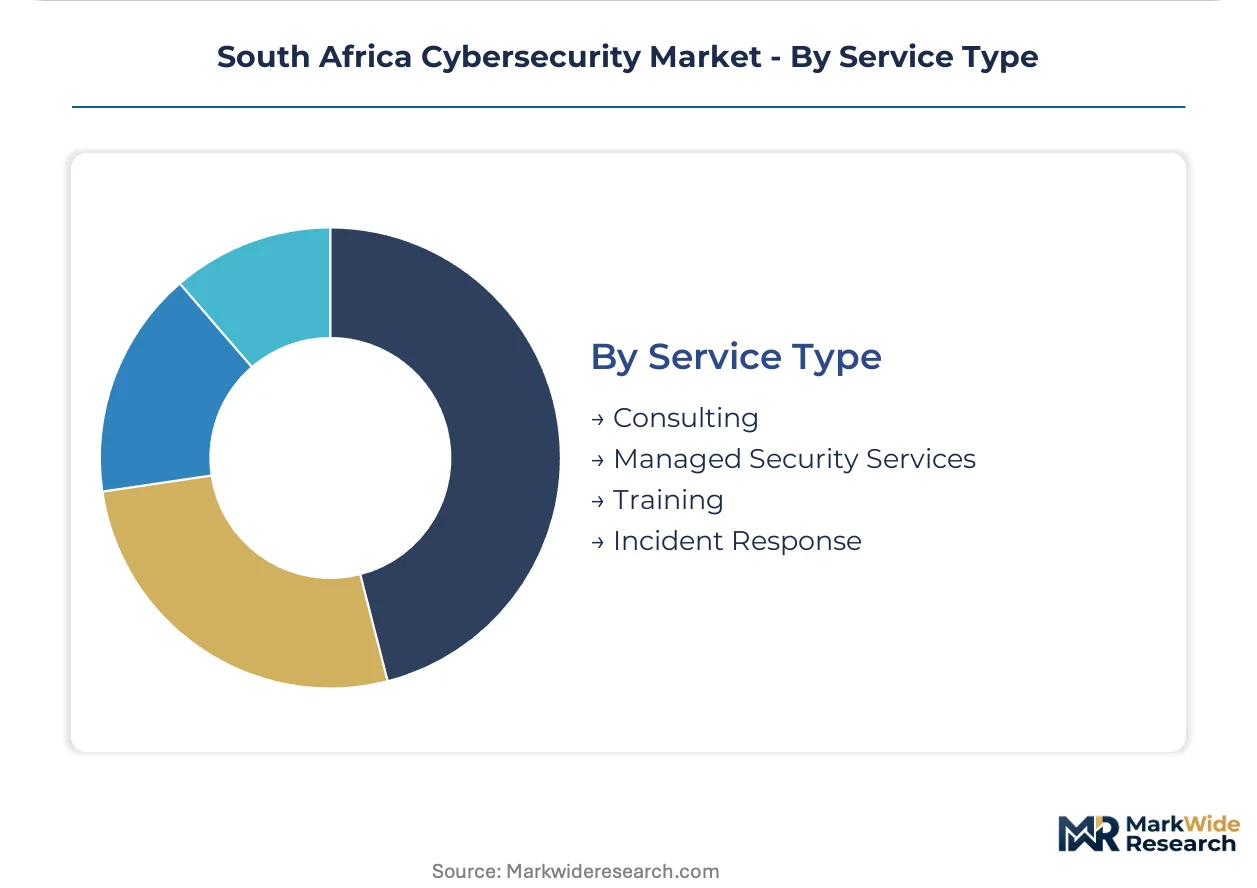
- Managed Security Services:Continuous monitoring, threat detection, and response automation delivered through Johannesburg-based SOCs. Providers differentiate through integrated threat intelligence rather than point-product resale. Local certification bottlenecks restrict qualified supplier pools.
- Incident Response:Retainer-based breach containment and forensic investigation services command premium pricing. Mining sector demand is rising as operational technology networks face targeted ransomware campaigns.
- Consulting:Compliance mapping, architecture design, and POPIA readiness assessments.
- Training:Certification preparation and security awareness programs addressing skills gaps.
Largest revenue pool: Managed Security Services. Gaining share fastest: Incident Response.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Johannesburg's financial district concentrates platinum-group metals wealth that funds enterprise security procurement. Gauteng province anchors national demand through banking headquarters and mining conglomerate offices.
Gauteng
Johannesburg's banking sector drives cloud security adoption as institutions migrate core systems off-premises. The Protection of Personal Information Act enforces encryption standards that legacy perimeter tools cannot satisfy. Sandton's financial district hosts redundant security operations centers established under Financial Sector Conduct Authority resilience guidelines.
Western Cape
Cape Town's fintech cluster generates demand for mid-market security platforms as venture-backed startups scale operations. POPIA compliance deadlines compress procurement cycles for data governance upgrades. The city's emerging technology corridor attracts security-as-a-service providers negotiating consumption-based billing arrangements.
KwaZulu-Natal
Durban's port infrastructure and secondary banking sites create demand for geographic distribution of critical systems. The Financial Sector Conduct Authority mandates maximum recovery time objectives that favor automated failover architectures. Financial institutions establish backup processing facilities to satisfy regulatory resilience requirements.
Mpumalanga
Mining corridors in this eastern province absorb network security procurement as operational technology upgrades accelerate. Decades-old industrial control systems resist modern endpoint detection without customized architectural intervention. Energy and extractive sectors replace uninspectable legacy appliances to meet POPIA encryption mandates.
Northern Cape
Remote mining operations in this sparsely populated region require specialized connectivity security for distributed sites. Limited local technical skills drive reliance on Johannesburg-based managed security services providers. Extractive companies deploy satellite-linked security operations center coverage to monitor isolated infrastructure.
South Africa Cybersecurity Market Competitive Landscape
Global majors compete with regional champions across channel depth and compliance advisory capabilities. The market structure tiered between platform consolidators, network security incumbents, and advisory-led consultancies. Three archetypes dominate: multinational technology vendors with established distribution, professional services firms bundling risk advisory with implementation, and emerging specialists targeting mid-market cloud migration. Competitive moves center on managed security service expansion and zero-trust architecture certification partnerships.
Within the advisory-led tier, Deloitte Cyber Risk Services and PwC Cybersecurity & Privacy exemplify professional services firms that merge compliance mapping with incident response retainers. Among platform consolidators, Palo Alto Networks occupies a position representing integrated security stack providers reducing tool sprawl for migrating enterprises. Cisco Systems anchors the network security incumbent archetype with channel infrastructure spanning mining and energy corridors.
| Leading Market Players |
|---|
| Fortinet |
| Deloitte Cyber Risk Services |
| Cisco Systems |
| Factosecure |
| PwC Cybersecurity & Privacy |
| Palo Alto Networks |
| Trend Micro |
| Orange Cyberdefense |
| Check Point Software Technologies |
| Others |
Value Network & Pricing Analysis
Channel-rolled-up managed security services providers in Johannesburg command pricing discipline through bundled 24/7 SOC coverage, while hardware-dependent vendors absorb currency volatility from East Asian manufacturing concentration. This ownership structure concentrates margin capture in advisory-led tiers and compresses procurement leverage for mid-market buyers facing POPIA compliance deadlines.
Pricing Analysis
Warranty and incident response retainer bundling separates premium-tier providers from unbundled product resellers in the South African market. Subscription-based SaaS pricing dominates cloud security procurement, with differentiation resting on ISO 27001 certification grade and geographic delivery cost for on-premises deployments. Cost compression in hardware appliances is intensifying because rand-dollar volatility inflates landed costs for firewall imports. Mid-market fintech startups in the Western Cape exhibit highest price sensitivity, while tier-one banks in Sandton prioritize compliance-grade service over unit cost.
Supply Chain Analysis
Workforce scarcity in South Africa's domestic cybersecurity labor pool forces Johannesburg-based providers to source certified architects from India, the United Kingdom, and Singapore through remote delivery models. Specialized hardware components including deep packet inspection chipsets and encryption appliances draw from Taiwanese and South Korean manufacturing clusters. Single-source vulnerability in East Asian semiconductor fabrication exposes procurement timelines to shipping delays. Distribution runs through value-added reseller networks anchored in Gauteng, with direct vendor relationships reserved for enterprise accounts exceeding threshold contract values.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Africa cybersecurity market functions as a cost-of-compliance story where POPIA enforcement creates a barrier-to-entry moat for providers holding Information Regulator attestations. This regulatory scaffolding protects certified incumbents while raising capital requirements for unqualified entrants.
For Market Incumbents: To counter cloud-native platform consolidation by global vendors, incumbent providers should deepen channel control through exclusive SOC partnership tiers with Johannesburg financial institutions. Certification investment in zero-trust architecture specializations creates defensible positioning against mid-market SaaS entrants. For New Entrants and Emerging Players: Direct-to-fintech digital sales channels bypass entrenched reseller relationships and unlock Cape Town's venture-backed startup cluster. The Western Cape mid-market segment offers the most penetrable white space, with consumption-based billing arrangements serving as the primary go-to-market angle against incumbent annual contracts. For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed managed security services boutiques in KwaZulu-Natal facing talent retention pressure. Long-term viability centers on compliance-advisory capabilities rather than pure technology resale, with proposed critical infrastructure protection legislation serving as the signal to watch for regulatory scope expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Certification | POPIA encryption mandates force enterprise migration from legacy perimeter models. |
| Managed SOC Geographic Expansion | Durban and Pretoria secondary sites satisfy Financial Sector Conduct Authority resilience guidelines. |
| AI-Augmented Threat Intelligence Integration | Machine learning analytics differentiate Johannesburg providers from point-product resellers. |
| Channel Partner Exclusive Tiers | Deepened reseller relationships protect incumbent margin pools in mining corridors. |
| Consumption-Based Billing Transition | Monthly arrangements align vendor cash conversion with Western Cape fintech scaling patterns. |
Research Methodology
Multi-period observation of enterprise procurement cycles and certification pipeline delays anchored the trend analysis, supplemented by interviews with CISOs at Johannesburg banks, SOC operations directors, Information Regulator compliance officers, and value-added reseller principals. Secondary validation drew from Protection of Personal Information Act enforcement notices, Financial Sector Conduct Authority operational resilience guidelines, ISO 27001 registry databases, and hyperscaler capex disclosures for African cloud regions. Bottom-up contract value aggregation and top-down sector spending estimates were triangulated to constrain projection variance.
Segment-weighting applied differential growth coefficients across deployment models, with cloud-based delivery assigned accelerated expansion rates reflecting banking SaaS migration. Product type, end-user industry, and service tier dimensions were modeled throughout the forecast period, with CAGRs derived from regression against historical compliance-driven spending spikes. Cybersecurity skills scarcity indices and rand volatility assumptions fed industry-specific scenario branches.
The model holds under stable POPIA enforcement intensity and moderate currency fluctuation; deviation in critical infrastructure legislation timing or severe supply chain disruption would shift trajectory. Forecasts reflect documented assumptions about regulatory adherence costs and talent pipeline recovery. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Enterprise Firewall Market
Cybersecurity
Singapore Cybersecurity Market
Cybersecurity
Global Network Security Policy Management Market
Cybersecurity
Corporate Web Security Market
Cybersecurity
Latin America Ransomware Protection Market
Cybersecurity
Global File Integrity Monitoring Market
Cybersecurity
Peru Cybersecurity Market
Cybersecurity
Internet of Things (IoT) Security Market
Cybersecurity
Europe Mobile Security Market
Cybersecurity
Ddos Protection and Mitigation Security Market
Cybersecurity
Artificial Intelligence-Based Cybersecurity Market
Cybersecurity
Italy Cybersecurity Market
Cybersecurity
Open RAN Security Market
Cybersecurity
North America Digital Forensics Market
Cybersecurity
Saas-Based IT Security Market
Cybersecurity
Germany Ransomware Protection Market