
 Global Online Fraud Detection and Prevention Market | 2026-2036
Global Online Fraud Detection and Prevention Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Fraud Detection and Prevention Market Outlook
Behavioral biometrics is rebalancing authentication economics as passive identity signals replace friction-heavy password layers. Socure leverages proprietary machine-learning pipelines to anchor verification accuracy for fintech issuers. Experian sustains broad data-network effects across credit and fraud-screening verticals. Feedzai competes through real-time transaction monitoring specialized for banking workloads.
Online fraud detection and prevention encompasses algorithmic systems that analyze behavioral patterns, device fingerprints, and transactional anomalies to intercept unauthorized access or financial crime before settlement. These platforms typically process thousands of signals per authentication event, applying risk-scoring thresholds that trigger step-up verification or session termination. Machine Learning and Artificial Intelligence segments lead deployment volume, while Biometrics commands premium pricing due to hardware integration requirements and liveness-detection standards. Cloud-Based delivery is expanding fastest among mid-market retailers, though On-Premises installations persist in BFSI entities with strict data-residency obligations.
The EU AI Act, GDPR, and the US FFIEC authentication guidance collectively reshape product roadmaps by mandating explainable decision logic and audit-ready risk models. India's Digital Personal Data Protection Act and BIS cybersecurity standards are creating parallel compliance obligations for vendors serving the subcontinent. Stakeholders must monitor divergence between regional algorithmic-accountability regimes to avoid fragmented certification costs.
Market Dynamics
AI-powered behavioral biometrics is compressing authentication friction while EU AI Act compliance mandates force explainable risk-scoring architectures into enterprise procurement specifications.
Growth Catalysts
- EU AI Act algorithmic accountability:Mandatory transparency requirements for automated decision systems are accelerating bank procurement of auditable fraud-detection infrastructure across Germany, France, and Italy.
- Real-time payment rails:Instant settlement networks in India, Brazil, and the United Kingdom eliminate chargeback windows, forcing issuers to deploy sub-100-millisecond transaction scoring.
- Behavioral biometrics maturation:Passive keystroke dynamics and mouse-movement pattern recognition now achieve parity with active authentication methods at lower operational cost.
Market Restraints
- GPU compute cost volatility:Training and inference workloads for large fraud-detection models remain exposed to NVIDIA datacenter chip pricing and cloud provider surcharge structures.
- Data residency fragmentation:Divergent sovereignty requirements across India's Digital Personal Data Protection Act, China's data-localization rules, and Russia's Federal Law 242-FZ force redundant infrastructure deployment.
- Adversarial attack surfaces:Deepfake injection techniques and synthetic identity fabrication exploit gaps between document verification and liveness-detection standards.
Strategic Opportunities
- Embedded finance penetration:Non-bank platforms in ride-hailing, gig-work, and embedded lending lack native fraud expertise, creating white-space demand for API-first verification stacks.
- Cross-border remittance corridors:High-velocity corridors between the United Arab Emirates, India, and the Philippines suffer elevated scam rates, opening specialized monitoring service opportunities.
- Convergence of open banking and fraud prevention:PSD2-driven account-access APIs in Europe enable transaction-data enrichment that strengthens risk models for payment initiators.
Industry Challenges
- Explainable AI talent scarcity:Regulatory mandates for interpretable model outputs outpace supply of machine-learning engineers with formal verification and audit-documentation expertise.
- Legacy core banking integration:Batch-oriented mainframe architectures at tier-one institutions resist real-time API ingestion, forcing expensive middleware abstraction layers.
- Certification timeline compression:ISO 27001, SOC 2 Type II, and regional financial-regulator approvals now run in parallel rather than sequence, straining compliance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Fraud Detection and Prevention Market |
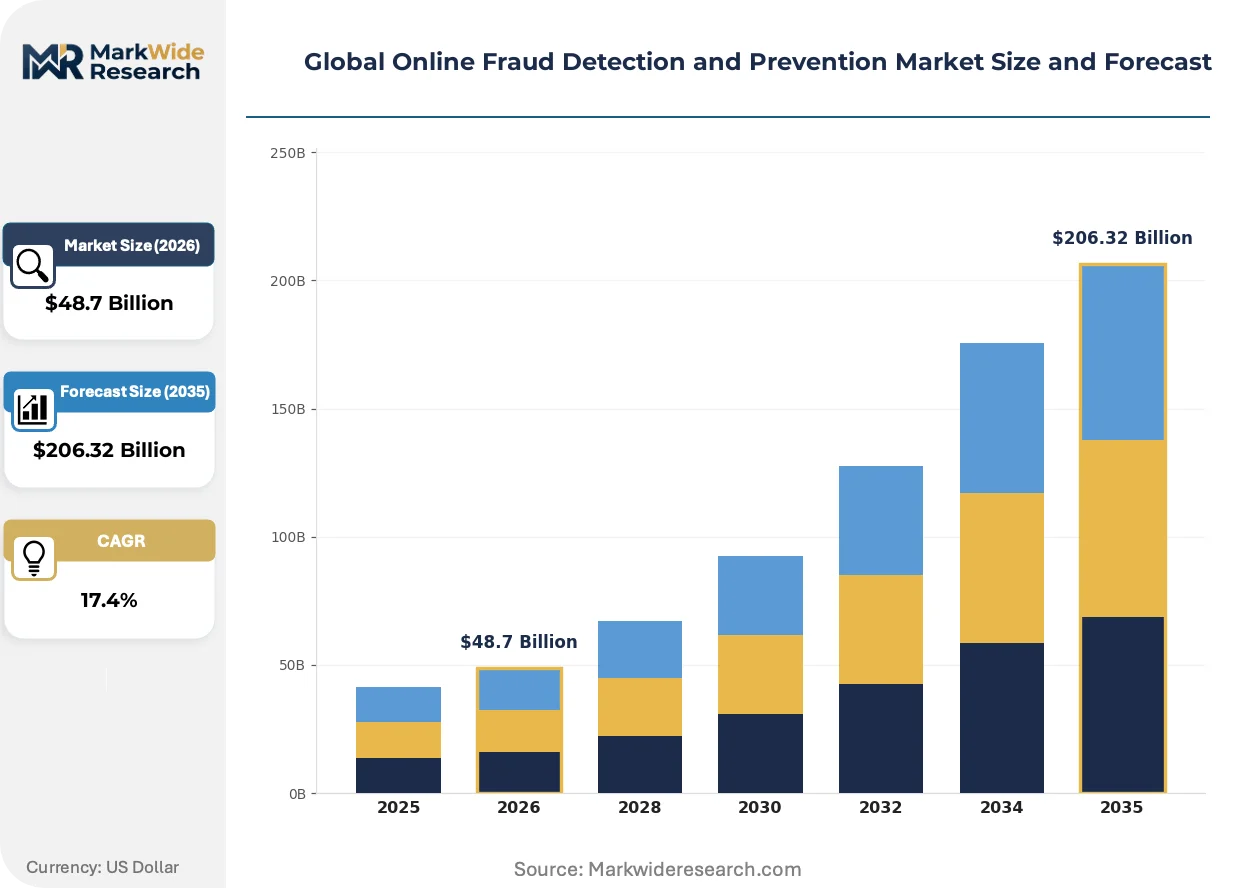
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $206.32 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Artificial Intelligence, Data Analytics, Biometrics Service Type: Managed Services, Professional Services, Consulting Services, Integration Services End User: BFSI, Retail, Telecom, Government Deployment: Cloud-Based, On-Premises, Hybrid, Mobile |
| Companies Covered | Socure, Accertify, Arkose Labs, Forter, Experian, SEON, Feedzai, Signifyd, Sift, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Fraud Detection and Prevention Market Strategic Shifts
Passive behavioral signals are displacing credential-based authentication across high-velocity transaction environments. Three interconnected developments are compressing implementation timelines and reshaping vendor competitive positioning.
Continuous authentication platforms are unifying device fingerprinting, behavioral biometrics, and transactional anomaly detection into single-pass risk pipelines. Tier-one card issuers in the United States and United Kingdom are deploying these systems for mobile banking login sessions. The technology is unifying previously siloed point solutions, forcing specialist vendors to integrate or exit.
The EU AI Act's risk-classification framework for biometric identification systems is mandating conformity assessments and post-market monitoring obligations. High-risk system providers must maintain technical documentation and human oversight protocols. Banking software vendors serving European markets are rearchitecting product roadmaps to embed explainability modules by default.
Merchant acquirers are unbundling fraud liability from transaction processing fees, creating standalone risk-transfer products. Retailers in Germany and the Netherlands are purchasing chargeback guarantees as separate line items rather than bundled interchange. This preference shift is visible most acutely among mid-market e-commerce platforms seeking predictable cost structures.
Global Online Fraud Detection and Prevention Market Segmentation
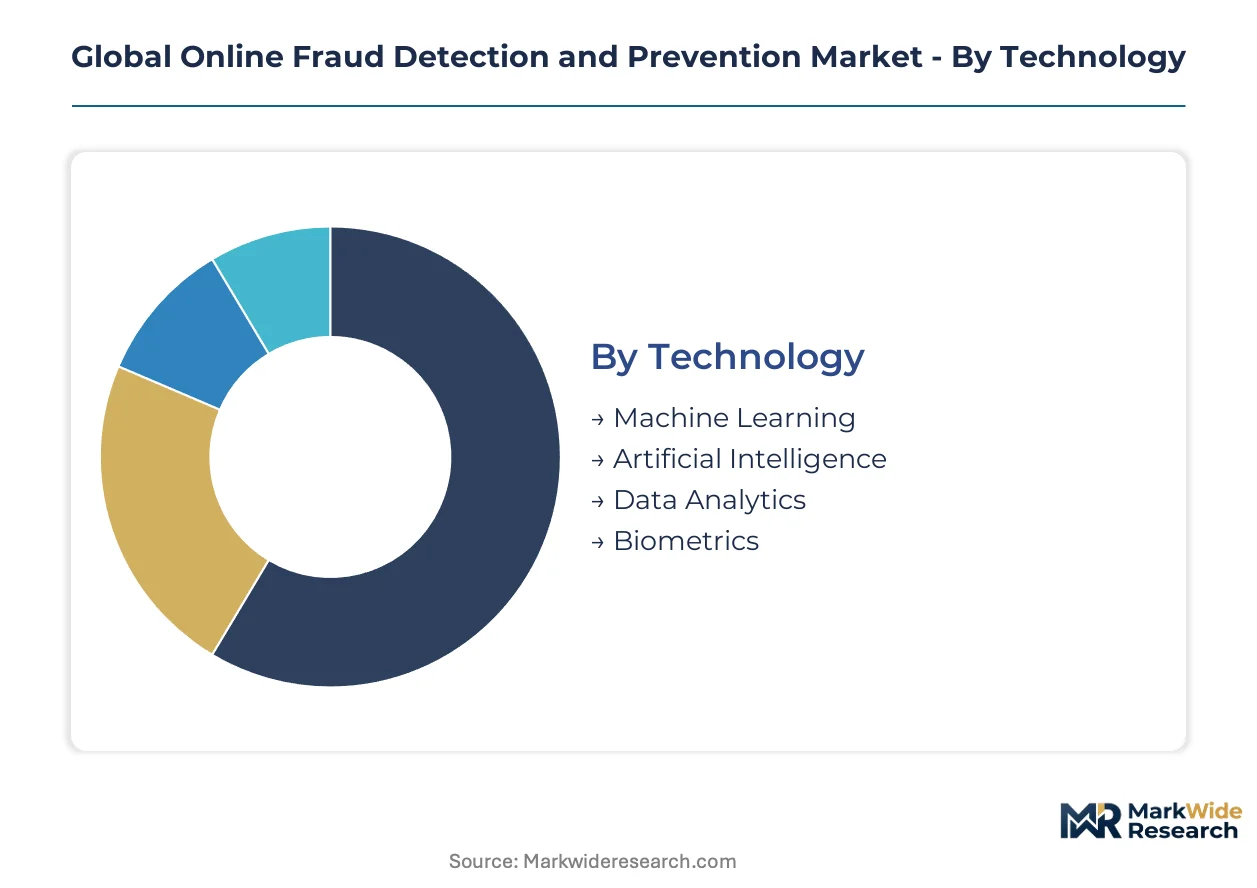
Technology deployment patterns in fraud detection vary sharply by risk tolerance and data sovereignty requirements. Enterprise procurement splits between high-volume algorithmic screening and premium biometric verification tiers.
Technology:
Machine Learning and Artificial Intelligence dominate transaction volumes while Biometrics commands pricing premiums through hardware integration and liveness-detection certification.
- Machine Learning:Supervised and unsupervised learning pipelines process thousands of behavioral signals per authentication event. Tier-one card issuers in the United States and United Kingdom deploy these systems for real-time transaction scoring with sub-100-millisecond latency requirements.
- Biometrics:Fingerprint, facial recognition, and voiceprint systems integrate specialized sensors with presentation-attack detection. Demand concentrates in India's Aadhaar-linked financial services and UAE digital banking platforms where regulatory mandates require multi-factor identity assurance.
- Artificial Intelligence:Deep learning architectures for anomaly detection and synthetic identity recognition.
- Data Analytics:Rules-based engines and statistical profiling for retrospective fraud investigation.
Today's leader: Machine Learning. Tomorrow's challenger: Biometrics.
Service Type:
Procurement patterns reveal a shift from one-time integration toward continuous risk management partnerships.
- Managed Services:Outsourced fraud operations centers handle alert triage, case investigation, and regulatory reporting for mid-market banks lacking in-house SOC capacity. German and French institutions under EU AI Act compliance timelines favor these arrangements for audit-documentation support.
- Professional Services:Model tuning, threshold calibration, and custom rule-set development for complex transaction environments. Indian payment processors leverage these engagements to adapt Western-trained algorithms to domestic behavioral patterns and UPI rail characteristics.
- Consulting Services:Risk assessment and control framework design for emerging embedded finance platforms.
- Integration Services:API connectivity and legacy core banking middleware deployment.
Managed Services currently anchor recurring revenue. Professional Services are gaining share fastest as model customization demands intensify.
End User:
Vertical risk profiles and transaction velocities create distinct authentication infrastructure requirements.
- BFSI:Banks, insurers, and payment networks operate under strict FFIEC guidance in the United States and parallel prudential frameworks elsewhere. Real-time payment adoption in Brazil and India eliminates chargeback windows, forcing sub-second decision architectures.
- Retail:E-commerce merchants and marketplaces face account takeover and friendly fraud exposure. Mid-market platforms in Germany and the Netherlands increasingly purchase chargeback guarantees as standalone risk-transfer products.
- Telecom:Subscription fraud and SIM-swap attacks drive device-centric verification adoption.
- Government:Tax, benefits, and identity credentialing systems require highest-assurance biometric standards.
BFSI retains the deepest infrastructure investment. Retail represents the steepest expansion trajectory as embedded finance penetrates non-bank platforms.
Deployment:
Data residency obligations and latency requirements fragment infrastructure choices across customer tiers.
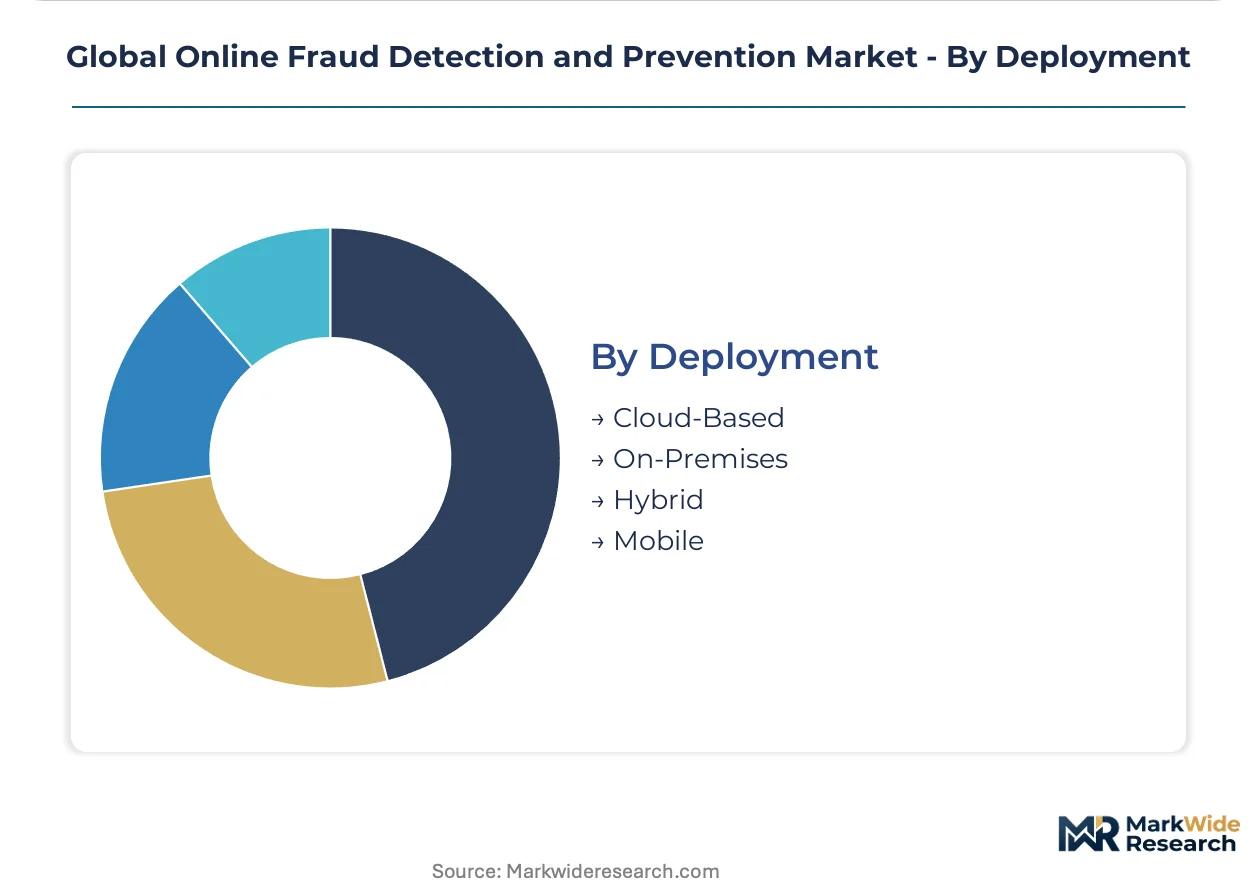
- Cloud-Based:Elastic compute for model training and inference supports seasonal transaction spikes. Mid-market retailers across Germany and India favor this delivery mode for rapid deployment without capital expenditure.
- On-Premises:Air-gapped installations satisfy Russia's Federal Law 242-FZ and China's data-localization mandates. Tier-one institutions in these jurisdictions maintain redundant on-premise stacks despite higher total cost of ownership.
- Hybrid:Split architectures with sensitive data on-premise and model development in cloud environments.
- Mobile:Edge-deployed SDKs for device-bound biometric capture and offline risk scoring.
Cloud-Based deployment leads new customer acquisition. Hybrid configurations are climbing fastest as sovereignty requirements multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Francisco Bay Area anchors fraud technology development through dense venture deployment and hyperscaler adjacency. Regulatory divergence across major economies fragments vendor certification requirements. Tier-one financial institutions in each geography now mandate explainable AI architectures for procurement eligibility.
United States
Real-time payment adoption through FedNow and The Clearing House rails compresses authentication windows to sub-100 milliseconds. FFIEC guidance mandates multi-factor authentication for high-risk transactions. New York and San Francisco financial centers concentrate vendor headquarters and tier-one bank procurement decisions.
Germany
EU AI Act conformity assessments force explainability modules into enterprise fraud stacks by default. BaFin prudential requirements align with GDPR data minimization principles for behavioral biometrics. Frankfurt's banking cluster drives continental procurement standards for audit-ready risk models.
India
UPI transaction volumes exceeding 10 billion monthly payments strain legacy screening infrastructure. RBI mandates and BIS cybersecurity standards create parallel compliance obligations for domestic and foreign vendors. Mumbai and Bengaluru fintech corridors concentrate startup innovation and bank technology centers.
United Kingdom
Open banking APIs under PSD2 enable transaction-data enrichment for payment initiators. FCA consumer duty rules elevate fraud reimbursement obligations for authorized push payment scams. London's regulatory technology cluster shapes European compliance tooling export markets.
United Arab Emirates
Cross-border remittance corridors to India and Philippines suffer elevated scam rates requiring specialized monitoring. Central Bank of the UAE digital banking licenses mandate biometric identity assurance for new entrants. Dubai International Financial Centre hosts regional headquarters for fraud technology vendors serving Gulf markets.
Global Online Fraud Detection and Prevention Market Competitive Environment
Global majors compete with regional champions across algorithmic specialization and data network depth. The vendor base stratifies between hyperscaler-backed platforms, credit bureau incumbents with cross-vertical data assets, and API-native challengers targeting embedded finance penetration. Three archetypes dominate: horizontal identity verification stacks, vertical banking workload specialists, and chargeback guarantee underwriters. Consolidation pressure intensifies through strategic partnerships bundling fraud screening with payment processing, while M&A activity targets behavioral biometrics capabilities.
Among identity-centric challengers, Socure and SEON exemplify the API-first archetype targeting fintech issuers with machine-learning pipelines. Experian occupies a position bridging credit data network effects into fraud-screening verticals. Feedzai anchors the real-time banking specialist tier with sub-latency transaction monitoring architectures.
| Leading Market Players |
|---|
| Socure |
| Accertify |
| Arkose Labs |
| Forter |
| Experian |
| SEON |
| Feedzai |
| Signifyd |
| Sift |
| Others |
Value Chain & Pricing Dynamics
Tier-one BFSI procurement clusters in the United States, Germany, and India command volume-based SaaS contracting with embedded professional services, compressing margins for vendors lacking scale economies while rewarding API-native platforms with embedded-finance penetration.
Pricing Analysis
GPU compute cost pass-through from NVIDIA datacenter chip pricing and cloud provider surcharge structures is intensifying cost compression in model training and inference tiers. Pricing stratifies across premium biometric verification with liveness-detection certification, standard machine-learning API tiers, and economy rules-based screening for retrospective investigation. Price differentiation hinges on explainable AI audit documentation for EU AI Act compliance and vertical integration of behavioral biometric sensors. Mid-market retailers exhibit highest price sensitivity due to seasonal transaction volatility, while tier-one card issuers prioritize sub-100-millisecond latency guarantees over unit economics.
Supply Chain Analysis
Direct-to-bank channels handle hyperscale buyer demand in the United States and United Kingdom, while systems integrators and cloud marketplaces serve mid-market penetration in Germany and India. Component sourcing concentrates on Taiwan for specialized biometric sensors, the United States for GPU and AI accelerator chips, and Ireland for EU data-residency compliant cloud infrastructure. Raw material dependencies include silicon wafers for sensor fabrication, rare earth elements for precision optics, and cobalt for battery systems in mobile edge deployments. Single-source vulnerability in NVIDIA's datacenter GPU supply creates procurement risk for real-time inference workloads. Distribution runs through API-first developer platforms, legacy core banking middleware vendors, and managed security service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Online Fraud Detection and Prevention Market functions as a stable compounder anchored by irreversible regulatory mandates for algorithmic accountability across European and Asian financial centers.
For Market Incumbents: Anchor defensive positioning through backward integration into behavioral biometric sensor supply and exclusive data-network arrangements with credit bureaus. Consolidation of API-first verification stacks neutralizes embedded-finance challengers. Certification investment in ISO 27001 and SOC 2 Type II parallel tracks preserves procurement eligibility against compliance timeline compression. For New Entrants and Emerging Players: Synthetic identity recognition algorithms offer the most penetrable wedge against legacy document-verification gaps. Target white-space demand in cross-border remittance corridors between the United Arab Emirates, India, and the Philippines where specialized monitoring services remain undersupplied. Chargeback guarantee products for mid-market German and Dutch e-commerce platforms provide a direct go-to-market angle bypassing bundled interchange relationships. For Investors and Strategic Acquirers: Payment processors expanding into risk-transfer products are the most active acquirer in this space, seeking behavioral biometrics capabilities to unbundle fraud liability from transaction fees. Long-term viability favors platforms with explainable AI architectures and multi-jurisdiction certification footprints. The signal to monitor is divergence between regional algorithmic-accountability regimes fragmenting vendor compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies device fingerprinting, behavioral biometrics, and transactional anomaly detection into single-pass risk pipelines for tier-one issuers. |
| Acquisition of Specialist Firm | Consolidates behavioral biometrics capabilities as payment processors unbundle fraud liability from interchange fees. |
| Strategic Partnership | Bundles fraud screening with real-time payment rails as FedNow and UPI adoption compresses authentication windows. |
| Product Launch | Deploys explainability modules by default to satisfy EU AI Act conformity assessments and BaFin audit requirements. |
| Geographic Expansion | Establishes data-residency compliant infrastructure for India's Digital Personal Data Protection Act and BIS cybersecurity standards. |
Study Parameters
Bottom-up BFSI and retail vertical modeling reconciled against top-down cloud infrastructure and GPU supply tracking forms the analytical core. Primary interviews with fraud operations executives, machine-learning engineering leads, regulatory compliance officers, and payment platform CTOs are validated against secondary sources including SEC filings from listed vendors, RBI and BaFin regulatory circulars, and hyperscaler capex disclosures. Cross-referencing of procurement patterns across tier-one card issuers and mid-market e-commerce platforms enables triangulation of deployment velocity and pricing trajectories.
Historical trendline analysis of authentication infrastructure spending patterns informs projection frameworks across the analysis window. Segmentation dimensions include technology tier, service type, end-use vertical, and deployment model, with regional regulatory clusters treated as distinct adoption curves. CAGR derivation rests on elasticity modeling of compliance mandate intensity against real-time payment rail penetration. Synthetic identity fraud incident rates and GPU compute cost volatility serve as industry-specific forecast sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to adversarial attack surface evolution and data residency fragmentation across India's Digital Personal Data Protection Act, China's localization rules, and Russia's Federal Law 242-FZ. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Dark Web Intelligence Market
Cybersecurity
Global Network Forensics Market
Cybersecurity
Global Cyber Security in Healthcare Market
Cybersecurity
Deception Technology Market
Cybersecurity
5G Security Market
Cybersecurity
Banking Cyber Security Market
Cybersecurity
Advanced Malware Detection (AMD) Market
Cybersecurity
Mobile Encryption Market
Cybersecurity
Cloud Encryption Gateways Market
Cybersecurity
Global Database Encryption Market
Cybersecurity
Botnet Detection Market
Cybersecurity
Japan Cybersecurity Market
Cybersecurity
Global Digital Forensic Laboratory As a Service Market
Cybersecurity
Network Edge Security Solutions Market
Cybersecurity
Malaysia Cybersecurity Market
Cybersecurity
Global Cyber Data Security Market