
 Europe Augmented Reality Market | 2026-2036
Europe Augmented Reality Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Augmented Reality Market Analytics
Modular AR software licensing is shifting how European enterprises procure immersive tools. Holo-Light GmbH leverages industrial-grade streaming protocols to anchor its position in manufacturing workflows. N-iX Games competes through specialized gaming engines optimized for mobile AR rendering. YORD differentiates by controlling full-stack creative production from concept to deployment.
Augmented Reality in Europe overlays digital information onto physical environments through head-mounted displays, smart glasses, or mobile screens, typically operating via markerless spatial mapping or projection-based tracking with sub-centimeter accuracy for industrial applications. The technology serves commercial purposes ranging from technician training to real-time navigation assistance in logistics corridors. Smart Glasses currently lead hardware revenue as German and French industrial buyers prioritize hands-free operation in regulated workspaces. AR Software captures expanding margin pools as vendors transition from perpetual licenses to recurring cloud subscriptions. Mobile Apps represent the fastest-growing access layer among retail and education end users seeking lower entry costs.
EMA guidelines on software-as-medical-device classification shape product development timelines for healthcare AR developers across the European Union. CE marking under the EU AI Act imposes conformity requirements on markerless vision systems processing biometric data. REACH compliance affects material selection for wearable headsets manufactured within the trading bloc. Stakeholders must monitor how the EU Green Deal's circular economy mandates will alter hardware refresh cycles and recycling obligations for deployed device fleets.
Market Dynamics
EU AI Act compliance requirements are forcing AR software vendors to reengineer computer vision pipelines, while German automotive buyers accelerate hands-free hardware procurement ahead of factory automation deadlines.
Growth Catalysts
- EMA software-as-medical-device pathways:Healthcare developers gain clearer certification routes for surgical navigation overlays, compressing time-to-market for clinical AR tools across the European Union.
- France aerospace maintenance demand:Projection-based training systems replace conventional simulators at Toulouse and Paris-Orly maintenance clusters, driving hardware procurement cycles.
- Cloud subscription transition:Vendors migrate from perpetual licenses to recurring SaaS models, expanding addressable budgets among mid-sized manufacturing enterprises.
Market Restraints
- CE marking complexity under EU AI Act:Markerless vision systems processing biometric data face extended conformity assessment timelines, delaying product launches by 8-14 months.
- Optics supply concentration:Waveguide manufacturing for smart glasses relies on a narrow supplier base concentrated in Bavaria and Baden-Württemberg, creating input bottlenecks.
- Mobile AR rendering limitations:Thermal constraints in un-tethered devices cap real-time polygon counts, restricting industrial-grade spatial mapping applications.
Strategic Opportunities
- Spain logistics corridor deployment:Barcelona and Valencia port operators pilot AR-guided container handling with minimal incumbent vendor presence, offering first-mover positioning.
- EU Green Deal circular economy mandates:Hardware refresh cycle regulations will create refurbishment and component recovery service lines for deployed headset fleets.
- 5G edge convergence:Low-latency streaming architectures enable lightweight client devices, opening industrial applications previously gated by local compute requirements.
Industry Challenges
- Computer vision engineering scarcity:Markerless tracking algorithm development requires specialized talent concentrated in Munich and Paris research clusters, constraining vendor scaling.
- Legacy MES integration friction:AR-guided assembly systems must interface with decades-old manufacturing execution software prevalent in German automotive plants, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Augmented Reality Market |
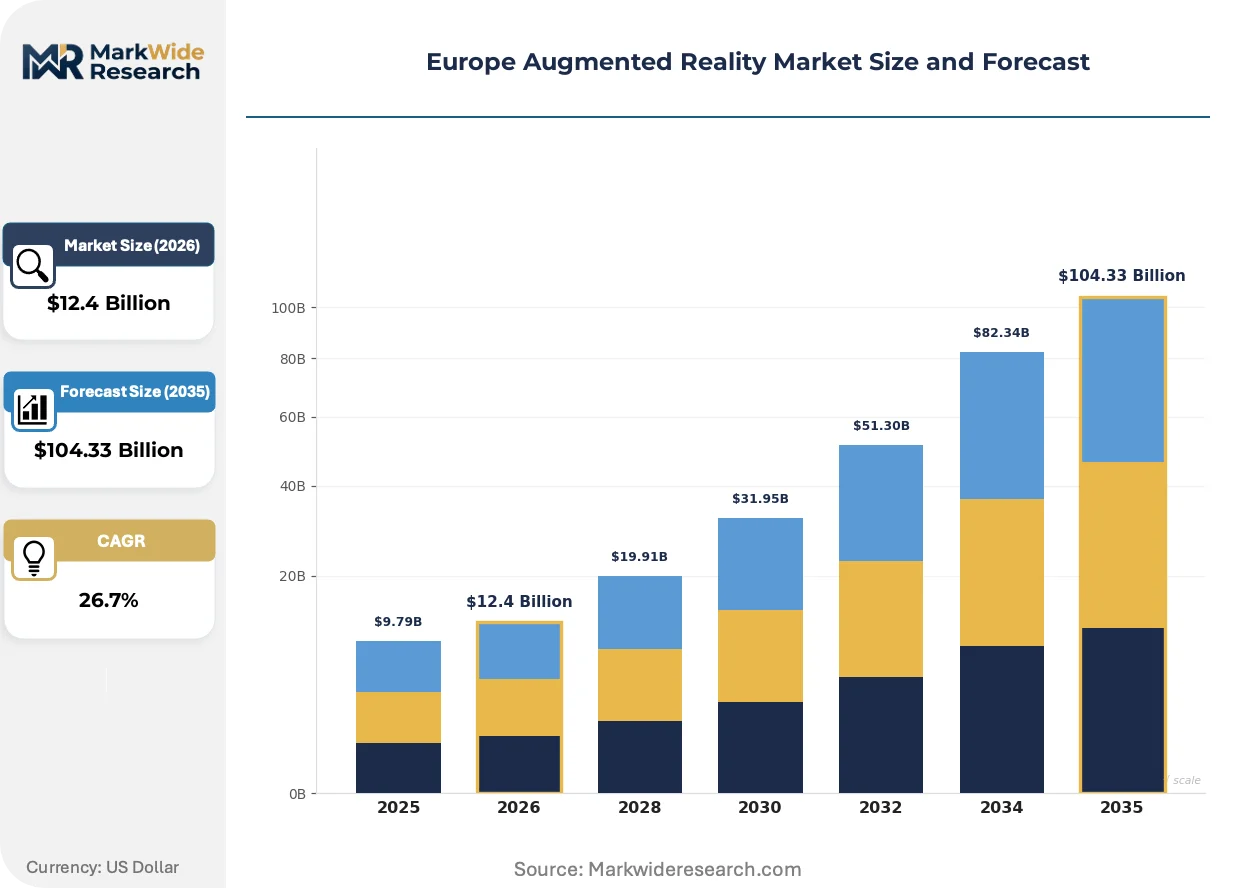
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $104.33 Billion |
| CAGR (2026 – 2036) | 26.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Glasses, AR Software, Mobile Apps, Head-Mounted Displays End User: Retail, Healthcare, Education, Gaming Technology: Marker-Based, Markerless, Projection-Based, Superimposition Application: Training, Navigation, Maintenance, Entertainment |
| Companies Covered | N-iX Games, nomtek, Lucid Reality Labs, Delta Reality, HQSoftware, YORD, ServReality, Holo-Light GmbH, Takeaway Reality, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Augmented Reality Market Evolving Landscape
Spatial computing architectures are fragmenting across edge, cloud, and hybrid configurations, with regulatory pressure on biometric data processing accelerating vendor investment in on-device inference.
Edge-native SLAM (simultaneous localization and mapping) is decentralizing spatial computation from centralized cloud servers to device-local silicon. German automotive assembly lines adopt these architectures to maintain sub-10-millisecond latency for safety-critical alignment tasks. This shift is decentralizing vendor power from cloud infrastructure providers to semiconductor designers specializing in low-power neural accelerators.
CE marking under the EU AI Act imposes conformity requirements on markerless vision systems processing biometric data in workplace monitoring applications. Industrial buyers in France and Germany now demand pre-certified software modules to de-risk procurement timelines. Healthcare AR developers face the steepest compliance burden as EMA software-as-medical-device classification intersects with AI Act risk-tiering for diagnostic overlays.
Enterprise procurement of AR software is fragmenting from centralized IT-led purchasing to departmental budgets controlled by operations and training managers. French aerospace maintenance divisions now acquire projection-based training systems directly, bypassing traditional enterprise software vendor relationships. This pattern is most pronounced in regulated industries where line-of-business units possess specialized compliance expertise that central procurement lacks.
Europe Augmented Reality Market Segmentation
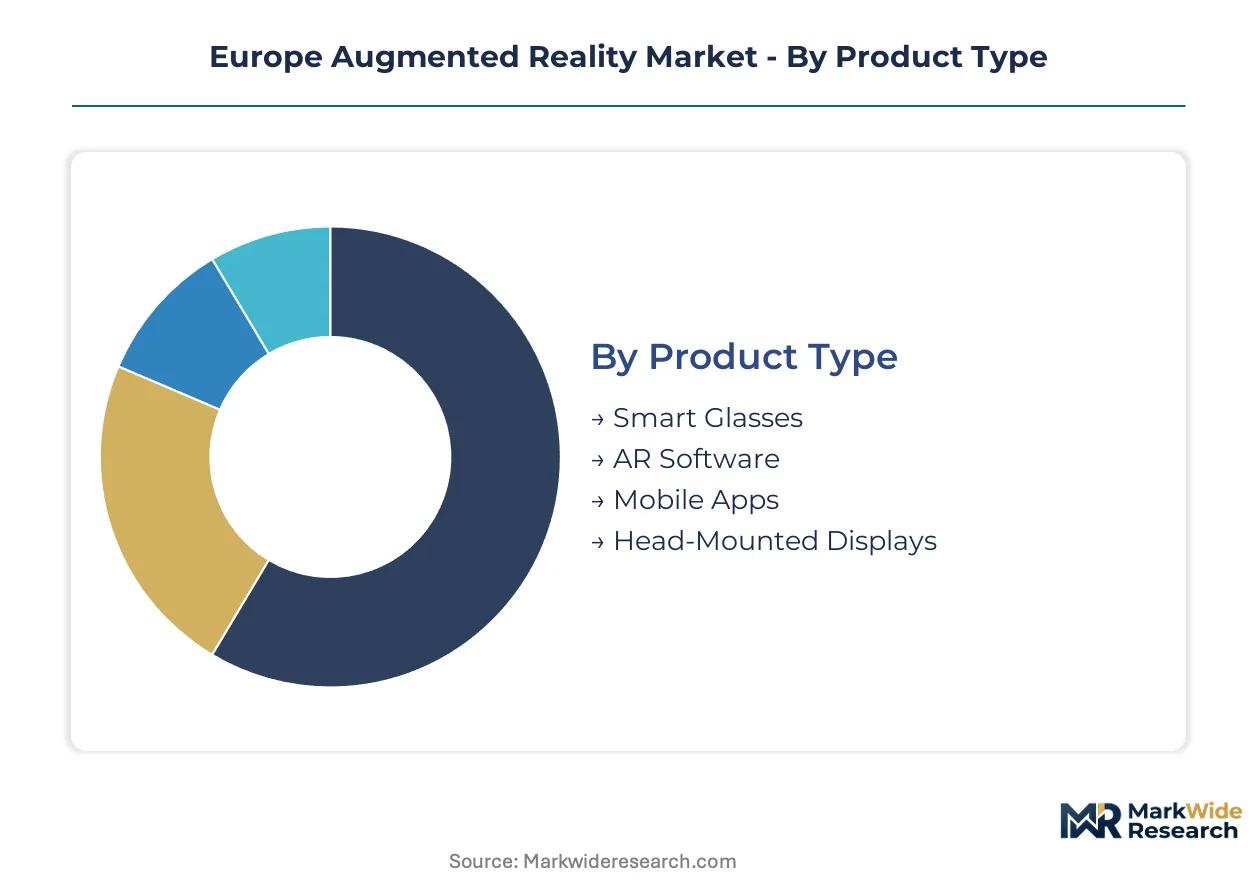
Segmentation reveals how procurement priorities diverge across European AR buyers. Hardware refresh cycles, software licensing transitions, and regulatory compliance requirements reshape competitive positioning differently for each category.
Product Type:
Upgrade cycles vary sharply across hardware and software layers, with industrial buyers demanding longer service intervals than consumer segments tolerate.
- Smart Glasses:Hands-free displays with waveguide optics and integrated cameras serve factory floors and maintenance bays. German automotive plants and French aerospace clusters drive procurement as EU AI Act biometric processing rules elevate demand for pre-certified devices.
- AR Software:Spatial computing platforms deliver markerless tracking and real-time overlay rendering through cloud or edge architectures. The shift from perpetual licenses to recurring SaaS subscriptions is expanding addressable budgets among mid-sized manufacturing enterprises across the trading bloc.
- Mobile Apps:Smartphone-based AR experiences leverage existing device penetration for retail and education use cases.
- Head-Mounted Displays:Tethered headsets with high-resolution panels target training and simulation applications requiring immersive visual fidelity.
Volume placements concentrate in Smart Glasses; the faster expansion belongs to AR Software.
End User:
Procurement authority is fragmenting from centralized IT to departmental budgets, with line-of-business managers gaining direct purchasing power in regulated sectors.
- Retail:Mobile AR powers virtual try-on and in-store navigation for fashion and furniture merchants. French and German retailers deploy these tools to bridge digital and physical commerce without heavy hardware investments.
- Healthcare:Surgical navigation overlays and diagnostic visualization tools face EMA software-as-medical-device classification alongside EU AI Act compliance. This dual regulatory burden compresses vendor margins but creates defensible positions for certified developers.
- Education:Projection-based and mobile AR delivers immersive learning modules for technical training and remote instruction.
- Gaming:Location-based entertainment and mobile AR titles drive consumer engagement through accessible smartphone platforms.
Healthcare commands premium pricing tiers; retail delivers the steepest volume expansion trajectory.
Technology:
Spatial tracking architectures are diverging as privacy regulations and latency requirements push computation toward device-local inference.
- Markerless:Computer vision algorithms map environments without predefined visual anchors, enabling seamless overlay placement. EU AI Act conformity requirements for biometric data processing are extending assessment timelines for these systems.
- Projection-Based:Spatial light modulation projects digital content directly onto physical surfaces for training and maintenance guidance. Toulouse and Paris-Orly aerospace clusters favor this approach for large-scale simulator replacement.
- Marker-Based:Visual fiducial recognition delivers reliable tracking for controlled industrial and educational settings.
- Superimposition:Real-time object replacement and augmentation techniques serve quality inspection and design visualization workflows.
Markerless systems dominate R&D investment; projection-based configurations gain share fastest in industrial training.
Application:
Use case maturity correlates with measurable ROI documentation, separating pilot programs from scaled deployments.
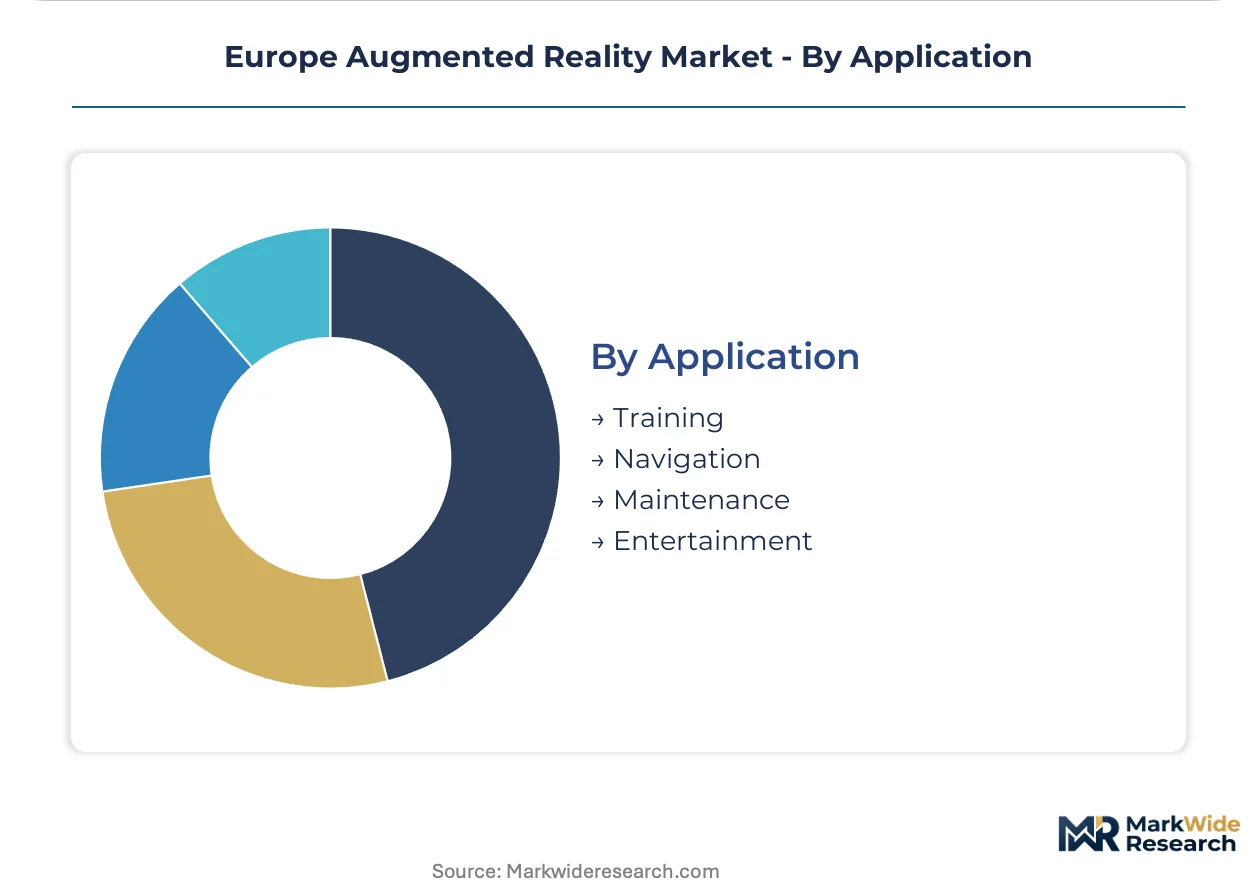
- Training:Immersive instruction reduces time-to-competency for complex technical procedures. French aerospace maintenance divisions now acquire these systems directly, bypassing traditional enterprise software procurement channels.
- Maintenance:Real-time guidance overlays deliver step-by-step repair instructions with hands-free operation. German automotive manufacturers deploy AR-guided assembly to reduce production errors and accelerate technician onboarding.
- Navigation:Spatial wayfinding assists logistics corridors and complex facility layouts.
- Entertainment:Location-based experiences and interactive media drive consumer engagement metrics.
Training applications anchor current revenue; maintenance is climbing the fastest as factory automation deadlines accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in German optics clusters while consumption spreads across aerospace, automotive, and healthcare hubs. France and Spain absorb the bulk of industrial deployment. Regulatory divergence between member states fragments procurement timelines.
Germany
Automotive manufacturers in Stuttgart and Munich drive demand for hands-free assembly guidance. KBA vehicle safety standards intersect with EU AI Act biometric processing rules, extending certification timelines for vision systems. Bavaria and Baden-Württemberg host waveguide manufacturing clusters supplying smart glass optics across the trading bloc.
France
Aerospace maintenance divisions at Toulouse and Paris-Orly replace conventional simulators with projection-based training systems. ANSM and CNIL guidance on workplace biometric monitoring shapes vendor compliance strategies. Île-de-France concentrates software development talent for markerless tracking algorithms serving regulated industries.
United Kingdom
Healthcare AR developers navigate MHRA software-as-medical-device pathways alongside post-Brexit regulatory divergence from EU frameworks. London fintech and creative sectors pilot mobile AR for customer engagement. Greater Manchester hosts logistics corridor trials for spatial wayfinding in warehouse environments.
Spain
Barcelona and Valencia port operators pilot AR-guided container handling with minimal incumbent vendor presence. The country's national logistics regulator supports digitalization incentives for maritime infrastructure. Catalonia concentrates gaming and creative studios developing location-based entertainment applications.
Netherlands
Eindhoven's semiconductor equipment ecosystem demands precision alignment overlays for cleanroom manufacturing. Dutch data protection authority guidance on workplace monitoring influences procurement specifications for vision systems. Randstad logistics hubs test low-latency streaming architectures for real-time navigation assistance.
Europe Augmented Reality Market Competitive Landscape
The competitive structure tilts toward specialized software boutiques over integrated hardware conglomerates. Vendor density remains moderate with clear stratification between industrial-grade platform providers and creative production studios. Two archetypes dominate: streaming-protocol specialists serving manufacturing workflows and full-stack creative agencies controlling concept-to-deployment pipelines. Competitive moves center on cloud subscription transitions and pre-certification investments to compress EU AI Act compliance timelines.
Among German-based industrial specialists, Holo-Light GmbH anchors the streaming-protocol tier, while N-iX Games and YORD occupy distinct positions on the creative production spectrum. These three exemplify how European AR vendors fragment across technical specialization rather than converging on unified platforms. Holo-Light GmbH represents the manufacturing-anchored archetype, N-iX Games sits within gaming-optimized rendering, and YORD exemplifies full-stack creative control. This dispersion reflects end-user procurement fragmentation from centralized IT to departmental budgets in regulated sectors.
| Leading Market Players |
|---|
| N-iX Games |
| nomtek |
| Lucid Reality Labs |
| Delta Reality |
| HQSoftware |
| YORD |
| ServReality |
| Holo-Light GmbH |
| Takeaway Reality |
| Others |
Value Network & Pricing Analysis
German automotive OEMs and French aerospace maintenance divisions concentrate procurement authority for industrial AR systems, anchoring a subscription-dominant pricing model that rewards pre-certified software modules and penalizes uncertified hardware.
Pricing Analysis
Margin tightening in AR software tiers reflects the forced migration from perpetual licenses to recurring SaaS models as vendors absorb EU AI Act compliance costs. Three-tier pricing structure across premium, standard, and economy levels separates pre-certified industrial platforms from consumer-grade mobile apps. Price differentiation hinges on CE marking status and volume commitment scale. Mid-sized manufacturing enterprises exhibit highest price sensitivity as they lack dedicated compliance budgets.
Supply Chain Analysis
CE marking and EMA software-as-medical-device classification gate market access for waveguide optics and neural accelerator components. Waveguide manufacturing concentrates in Bavaria and Baden-Württemberg, Germany, while semiconductor neural accelerators draw from Taiwan and South Korea. Single-source vulnerability in precision optics creates input bottlenecks for smart glass assembly. Distribution runs through specialized industrial integrators serving automotive and aerospace clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European AR vendors face a vertical-integration race into pre-certified software modules and captive waveguide supply as EU AI Act timelines compress procurement windows.
For Market Incumbents: To counter extended CE marking timelines for markerless vision systems, accelerate backward integration into certified software development kits and secure long-term waveguide supply agreements with Bavarian optics clusters. Channel control through direct departmental sales to French aerospace and German automotive buyers reduces procurement friction. For New Entrants and Emerging Players: Capture Spain's logistics corridor opportunity at Barcelona and Valencia ports where incumbent vendor presence remains minimal. White-space exists in 5G edge-native SLAM systems for container handling. Go-to-market through port authority digitalization incentives bypasses centralized IT procurement. For Investors and Strategic Acquirers: The window for entry favors pre-certified software boutiques with EMA pathway experience and industrial streaming protocol expertise. Long-term viability rests on compliance moats widening under EU AI Act enforcement. Watch for KBA vehicle safety standard revisions as inflection triggers for automotive AR procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certification Investment | CE marking under EU AI Act compresses competitor entry timelines for biometric-processing vision systems. |
| Streaming Protocol Development | Industrial-grade edge architectures reduce latency for safety-critical German automotive assembly tasks. |
| Departmental Sales Channel | Direct procurement by French aerospace maintenance divisions bypasses traditional enterprise software vendors. |
| Waveguide Supply Agreement | Captive optics supply from Bavarian clusters insulates against input bottlenecks in smart glass manufacturing. |
| 5G Edge Convergence | Low-latency streaming enables lightweight client devices for Spain logistics corridor deployments. |
Research Methodology
EMA guidance documents, EU AI Act regulatory filings, and automotive production databases formed the secondary backbone. Primary interviews with AR software engineering leads, aerospace maintenance procurement managers, automotive platform integration specialists, and semiconductor equipment planners validated demand assumptions. Bottom-up and top-down triangulation cross-checked vendor revenue disclosures against end-user deployment tracking.
Bottom-up modeling aggregated segment-level demand across product type, end user, technology, and application dimensions. Top-down validation referenced macroeconomic indicators and capital expenditure patterns across the projection horizon. CAGRs derived from logistic diffusion curves fitted to technology adoption rates in regulated industrial settings. Forecast inputs incorporated EU AI Act implementation timelines and EMA software-as-medical-device pathway completion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CE marking interpretation variance between member state notified bodies and waveguide supply concentration risk. A model refresh is warranted upon material change in EU AI Act enforcement guidance or KBA vehicle safety standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Collaboration Platform Market
Virtual Reality (VR) and Augmented Reality (AR)
Canada Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in BFSI Market
Virtual Reality (VR) and Augmented Reality (AR)
Internet of Senses Market
Virtual Reality (VR) and Augmented Reality (AR)
Consumer Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual and Augmented Reality in Tourism Market
Virtual Reality (VR) and Augmented Reality (AR)
Data Glove Market
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Learning Market