
 Egypt Cybersecurity Market | 2026-2036
Egypt Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Cybersecurity Market Insights
Managed security services is expanding as the dominant commercial layer in Egyptian cybersecurity procurement, shifting vendor relationships from perpetual licenses to recurring operational partnerships. Palo Alto Networks leverages its cloud-delivered security platform to anchor enterprise accounts across Cairo and Alexandria. Fortinet competes through integrated firewall-SD-WAN bundles that reduce deployment complexity for mid-market banks. Cyberteq specializes in sovereign security operations tailored to government and defense clients.
Cybersecurity encompasses technologies, processes, and controls designed to protect systems, networks, and data from digital attacks, with encryption standards such as AES-256 and TLS 1.3 forming core technical parameters for data confidentiality and integrity. Its primary purpose is to ensure operational continuity and regulatory compliance for organizations handling sensitive information. Network Security leads product spending as Egyptian enterprises harden perimeter defenses against escalating threat volumes. Cloud Security grows fastest as SaaS migration accelerates among financial services and healthcare providers. Endpoint Security occupies mature margin pools where antivirus replacement cycles generate predictable recurring revenue.
The Central Bank of Egypt mandates tiered cybersecurity controls for licensed financial institutions, while the Egyptian Computer Emergency Readiness Team coordinates national incident response standards. Compliance with these frameworks shapes procurement specifications and vendor qualification requirements across regulated sectors. Stakeholders must monitor evolving certification criteria and sovereign data-localization mandates to align product roadmaps with enforcement trajectories.
Market Dynamics
Egyptian financial institutions face compressed compliance timelines as the Central Bank of Egypt tightens cybersecurity directives, forcing accelerated zero-trust architecture deployment across Cairo's fintech corridor and Alexandria's public-sector digital hubs.
Growth Catalysts
- Central Bank of Egypt Cybersecurity Directives:Tiered control mandates for licensed banks create immediate procurement pull for managed security services and cloud-delivered platforms.
- SaaS Migration in Healthcare:Egyptian healthcare providers accelerating cloud adoption generate demand for cloud security solutions as patient data volumes expand.
- Alexandria Public-Sector Digital Hubs:Government digital transformation initiatives concentrate procurement authority in sovereign security operations tailored to defense and civilian agencies.
Market Restraints
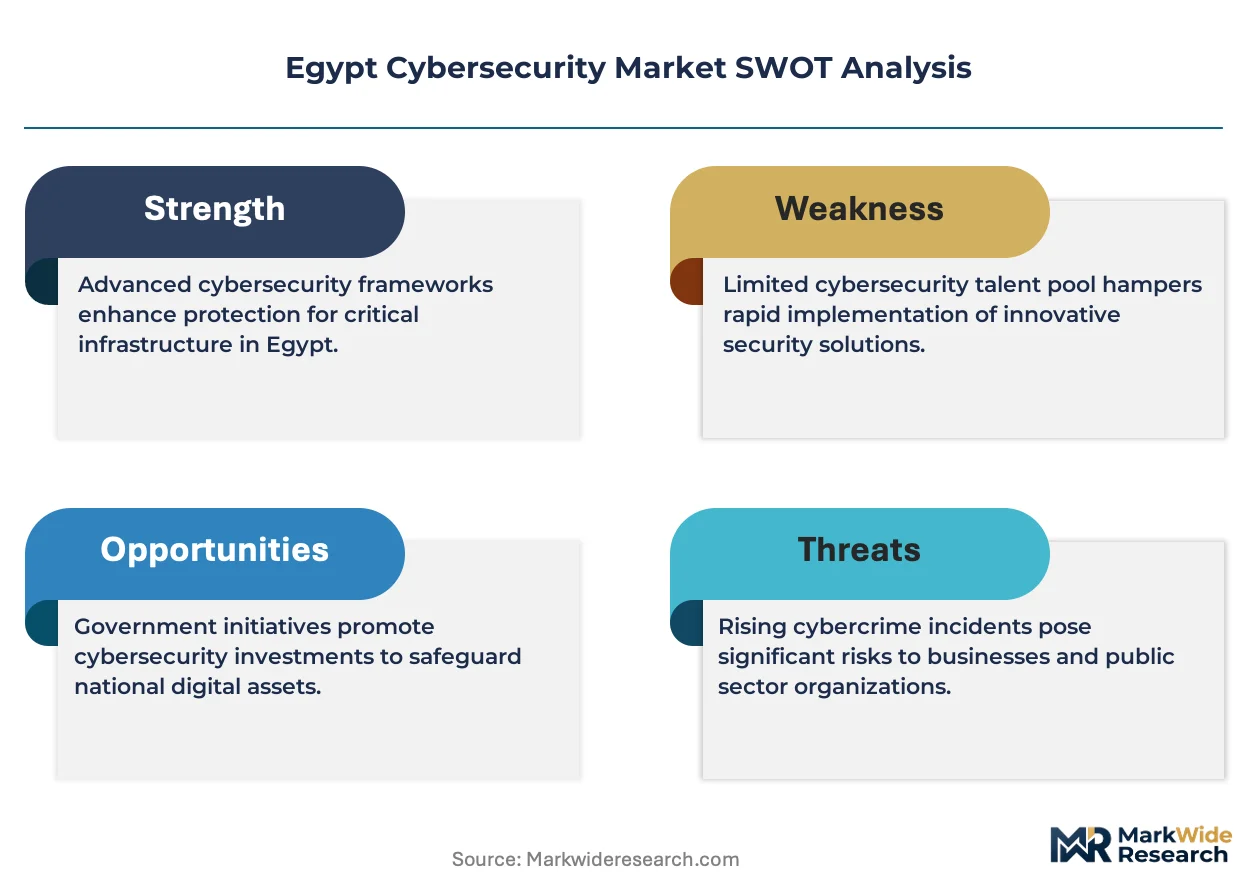
- Specialized Cybersecurity Talent Scarcity:Egypt's domestic labor pool lacks sufficient zero-trust architects and incident response specialists, inflating implementation costs.
- Import Dependency for Hardware:Network security appliances rely on foreign-manufactured components subject to currency volatility and extended lead times.
- Sovereign Data Localization Requirements:Egyptian regulations mandating in-country data storage create infrastructure capex burdens for multinational cloud providers.
Strategic Opportunities
- Upper Egypt Digital Inclusion:Underpenetrated governorates south of Cairo present greenfield opportunities for endpoint security and managed detection services.
- Healthcare Cloud Security:Emerging application segment as Egyptian hospitals migrate electronic medical records to hybrid cloud environments.
- AI-ML Security Convergence:Threat detection platforms combining machine learning with behavioral analytics offer differentiation in financial services procurement.
Industry Challenges
- Zero-Trust Architecture Skill Gap:Egyptian enterprises struggle to source certified architects capable of segmenting legacy banking infrastructure without operational disruption.
- Multi-Vendor Integration Complexity:Financial institutions deploying Palo Alto cloud platforms alongside Fortinet firewall-SD-WAN bundles face interoperability testing delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Cybersecurity Market |
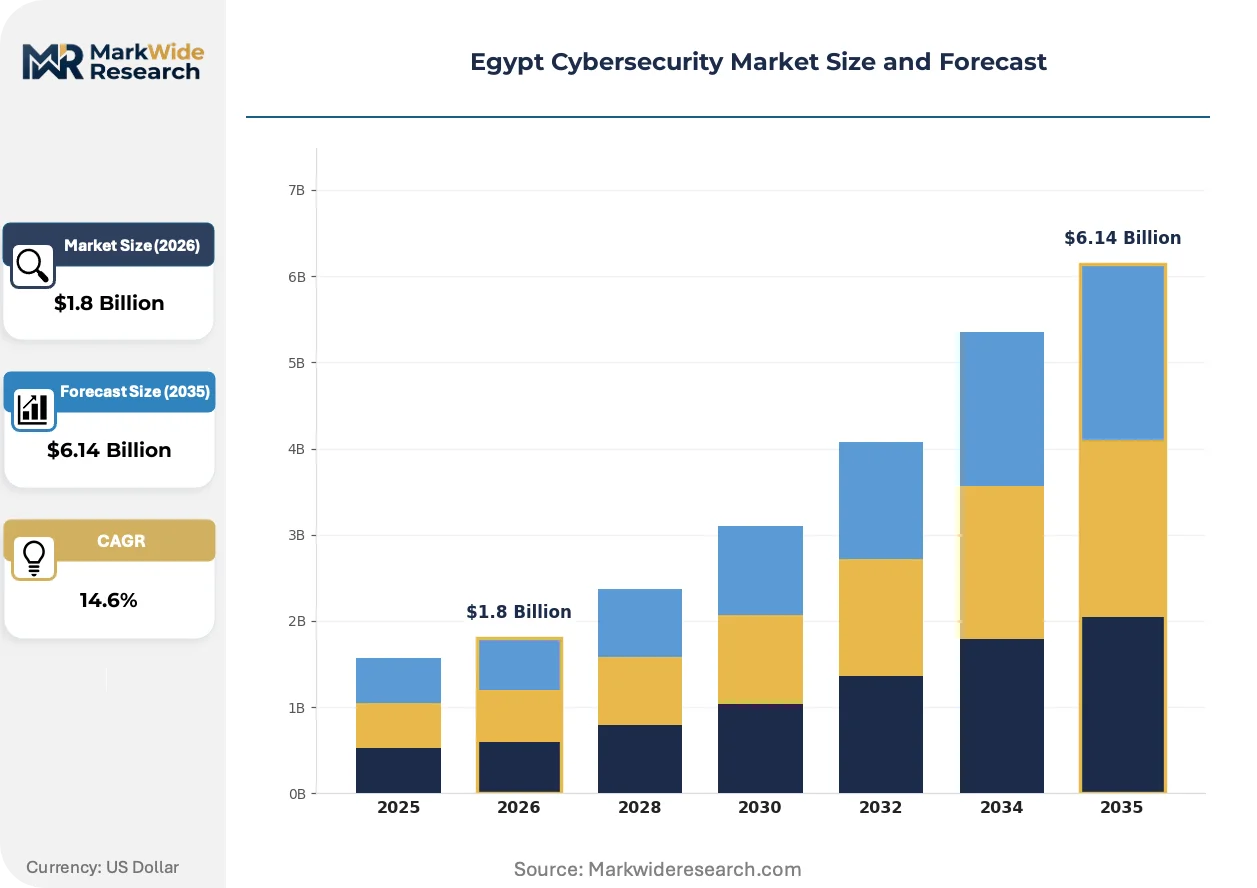
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
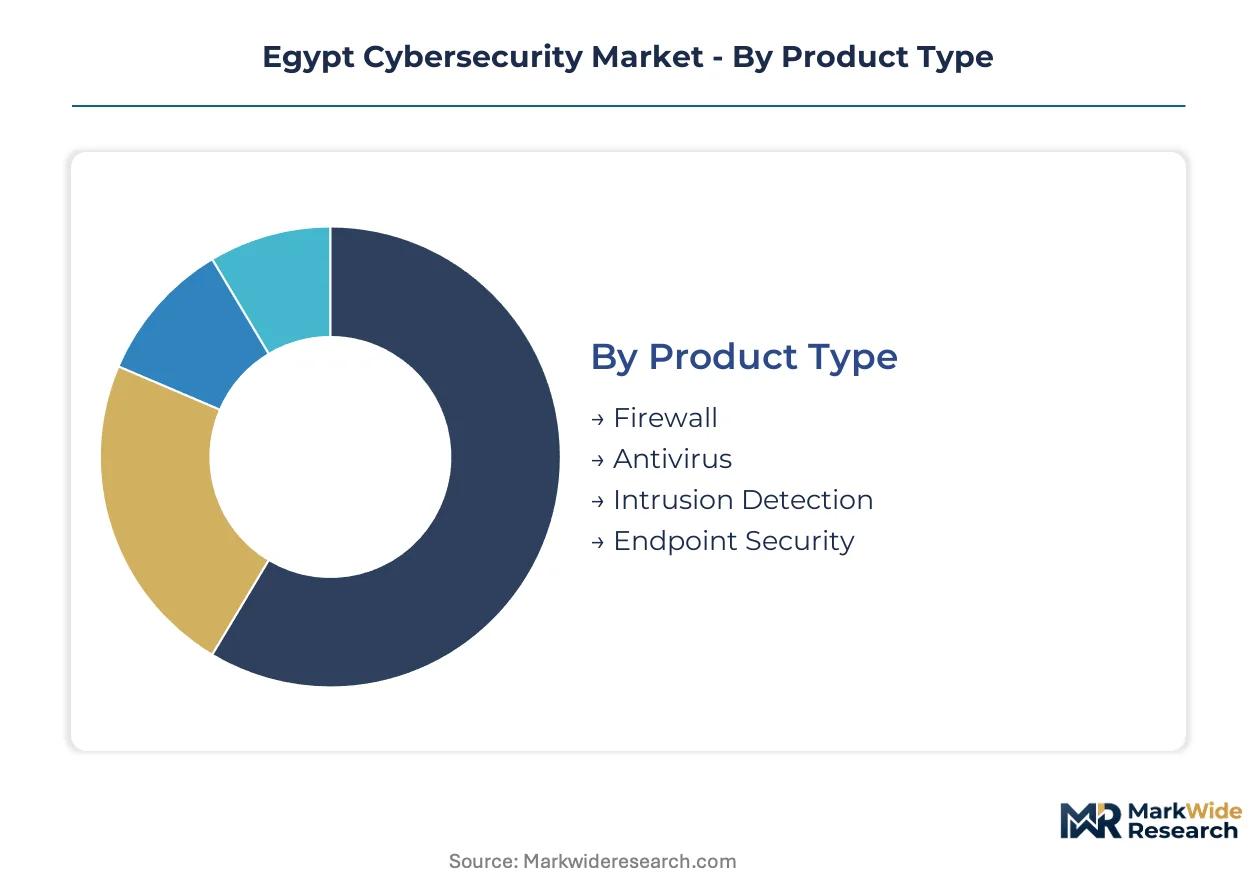
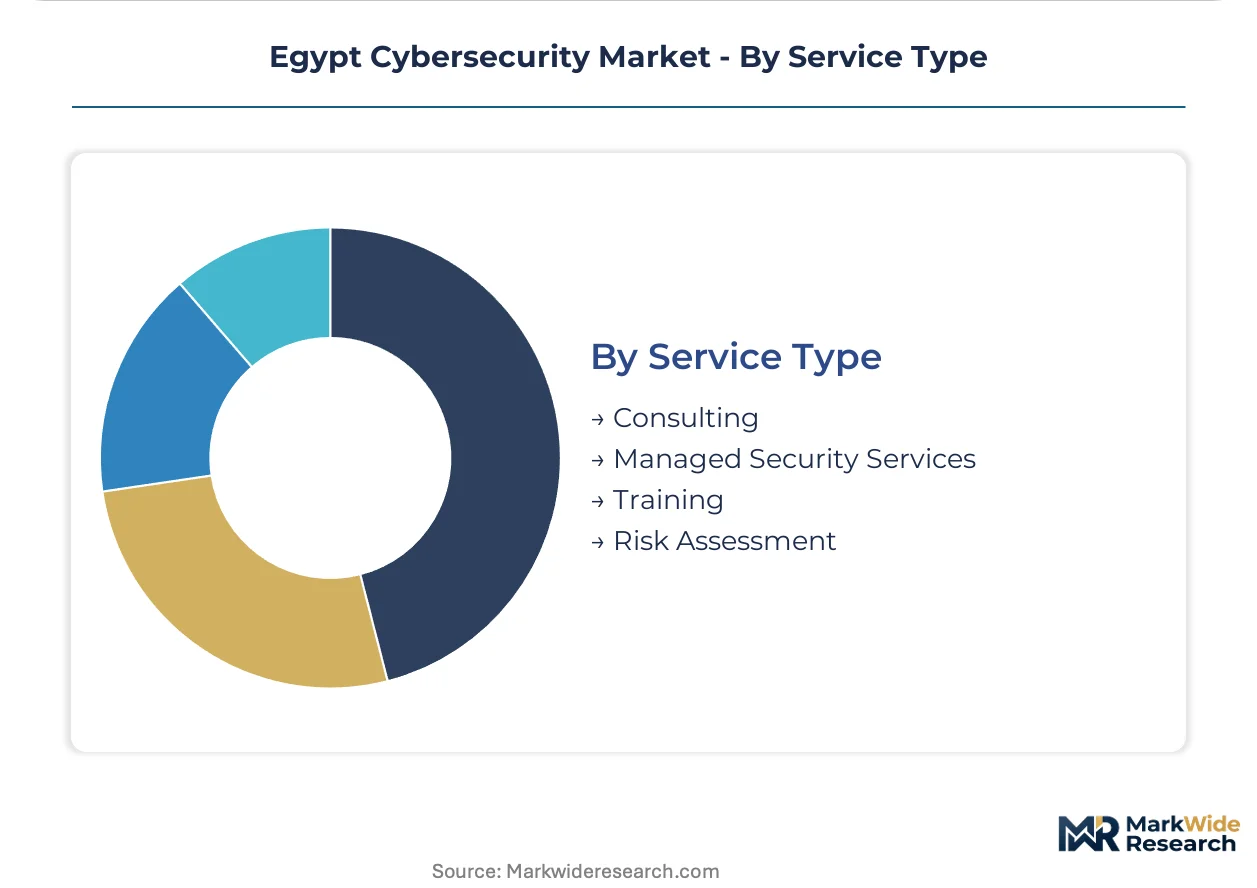
| Segmentation | Product Type: Firewall, Antivirus, Intrusion Detection, Endpoint Security End User: Government, Financial Services, Healthcare, Retail Technology: Cloud Security, Application Security, Network Security, Data Encryption Service Type: Consulting, Managed Security Services, Training, Risk Assessment |
| Companies Covered | IBM Corporation, Palo Alto Networks, Microsoft Corporation, Fortinet, Absega Egypt Technology Services, Orange Cyberdefense Egypt, Cyberteq, Check Point Software Technologies, Keys Cyber, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Cybersecurity Market Trends and Innovations
Artificial intelligence is reshaping threat detection capabilities across Egyptian cybersecurity procurement, compressing response timelines and elevating predictive analytics above signature-based defenses in enterprise RFPs.
Extended Detection and Response platforms aggregate telemetry across endpoints, networks, and cloud workloads into unified threat visibility. Egyptian banks in Cairo's fintech corridor are adopting these platforms at accelerated pace to satisfy Central Bank of Egypt audit requirements. The technology is integrating previously siloed security operations into single-pane workflows that reduce mean-time-to-detect metrics.
The Central Bank of Egypt's tiered cybersecurity framework mandates specific control implementations based on institution size and systemic importance. This regulatory architecture forces mid-market banks to upgrade perimeter defenses and incident response capabilities within shortened compliance windows. Financial institutions are responding by consolidating vendor relationships around cloud-delivered security platforms that automate control mapping.
Subscription-based managed security services are displacing perpetual license procurement across Egyptian enterprise accounts. Cairo-based financial services firms and Alexandria government agencies now prioritize operational partnerships over capital expenditure models. This shift concentrates vendor selection criteria on service-level agreements and threat intelligence quality rather than feature checklists.
Egypt Cybersecurity Market Segmentation
Egypt's cybersecurity procurement patterns diverge sharply across buyer sophistication, compliance exposure, and infrastructure maturity. Understanding these fault lines reveals where vendor consolidation versus fragmentation will concentrate over the forecast window.
Product Type:
Buyer differentiation in this category hinges on perimeter hardening urgency versus endpoint proliferation management.
- Firewall:Hardware and virtual appliances enforcing traffic policies at network boundaries dominate Cairo financial district deployments. Egyptian banks prioritize next-generation capabilities with integrated intrusion prevention as Central Bank audit cycles compress.
- Endpoint Security:Agent-based protection for laptops, servers, and mobile devices absorbs the largest procurement volumes from Alexandria government agencies rolling out civil servant device fleets. Agent consolidation and behavioral detection now displace signature-heavy legacy suites.
- Antivirus:Traditional malware scanning tools persist in cost-constrained healthcare and retail segments across Upper Egypt governorates.
- Intrusion Detection:Signature and anomaly-based network monitoring systems see concentrated uptake in defense-adjacent installations requiring sovereign operation.
Firewall leads volumes today; Endpoint Security is gaining share fastest.
End User:
Regulatory enforcement intensity separates procurement authority across this dimension.
- Financial Services:Licensed banks and fintech operators face mandatory tiered controls from the Central Bank of Egypt, driving premium platform adoption. Cairo's fintech corridor concentrates demand for cloud-delivered security with automated compliance mapping.
- Government:Civilian and military agencies in Alexandria and Cairo digital hubs require sovereign security operations with domestic data residency. Procurement prioritizes managed detection services over perpetual licenses.
- Healthcare:Hospital networks migrating electronic medical records to hybrid cloud generate emerging demand for encryption and access controls.
- Retail:Point-of-sale protection and e-commerce fraud prevention dominate merchant priorities, with payment processor mandates shaping vendor selection.
Financial Services anchors current spending; Healthcare is expanding most quickly.
Technology:
Infrastructure location—on-premises, hybrid, or pure cloud—determines architectural choices here.
- Network Security:Perimeter defense, segmentation, and secure access technologies command immediate priority from institutions with legacy datacenter investments. Egyptian enterprises harden these layers first under regulatory pressure.
- Cloud Security:Workload protection, configuration management, and SaaS access security attract fastest-growing interest as healthcare and financial services accelerate migration. Sovereign data localization requirements complicate multinational provider selection.
- Application Security:Code scanning, runtime protection, and API security see selective adoption among Cairo software development shops serving export markets.
- Data Encryption:AES-256 and TLS 1.3 implementation services underpin compliance across all regulated sectors, often bundled into broader platform deals.
Network Security dominates current deployment; Cloud Security shows the steepest expansion trajectory.
Service Type:
Capability ownership versus outsourcing preference splits this category.
- Managed Security Services:24/7 threat monitoring, incident response, and platform management delivered via subscription now displace capital-intensive self-operation. Egyptian banks and government agencies favor operational partnerships that transfer talent scarcity risk to vendors.
- Consulting:Architecture design, zero-trust transformation planning, and compliance readiness assessments attract project-based spending from institutions navigating Central Bank directive implementation.
- Risk Assessment:Vulnerability scanning, penetration testing, and control gap analysis serve audit preparation cycles with predictable seasonal demand.
- Training:Certification programs and security awareness curricula address the domestic zero-trust architect shortage, though procurement volumes trail operational services.
Managed Security Services leads procurement value; Consulting is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt outpaces Morocco in cybersecurity procurement velocity, while South Africa maintains deeper enterprise penetration. Saudi Arabia and UAE dominate Gulf spending, though Egypt's regulatory tightening is compressing implementation timelines fastest.
Cairo Governorate
The Central Bank of Egypt's tiered directives drive zero-trust deployment across licensed banks and fintech operators. Cairo's fintech corridor concentrates demand for cloud-delivered security platforms with automated compliance mapping. Financial institutions here prioritize managed security services over perpetual licenses.
Alexandria Governorate
Public-sector digital transformation initiatives generate sovereign security procurement from civilian and military agencies. The Egyptian Computer Emergency Readiness Team coordinates incident response standards for government installations. Alexandria's digital hubs favor domestic managed detection services with in-country data residency.
Giza Governorate
Healthcare providers migrating electronic medical records to hybrid cloud create emerging demand for encryption and access controls. Hospital networks here face patient data volume expansion without matching security infrastructure. Medical facilities prioritize workload protection and configuration management tools.
Upper Egypt Governorates
Underpenetrated markets south of Cairo present greenfield opportunities for endpoint security and managed detection services. Digital inclusion programs expand civil servant device fleets across Sohag, Assiut, and Minya. Procurement concentrates on cost-constrained antivirus replacement and basic network monitoring.
Suez Canal Economic Zone
Logistics and industrial tenants require perimeter hardening against escalating threat volumes. Port operators and free-zone manufacturers face compressed compliance windows from sector-specific cybersecurity mandates. The zone attracts firewall and intrusion detection deployments tied to critical infrastructure protection.
Egypt Cybersecurity Market Competitive Landscape
Top-tier vendors anchor enterprise accounts in Cairo and Alexandria, while mid-market specialists compete on deployment simplicity and sovereign data handling. The market exhibits tiered concentration with multinational platforms dominating financial services and domestic operators capturing government mandates. Three archetypes prevail: cloud-native platform providers, integrated firewall-SD-WAN bundlers, and sovereign security operations specialists. Competitive moves center on subscription model conversion and managed service partnership structures.
Among Egypt-based operators, Absega Egypt Technology Services and Keys Cyber occupy positions serving public-sector and mid-market commercial accounts. Palo Alto Networks and Fortinet exemplify the cloud-delivered and integrated hardware archetypes respectively, while Cyberteq anchors sovereign security operations tailored to defense and government clients. These named entities represent the competitive spectrum from multinational platform deployment to domestically controlled security operations.
| Leading Market Players |
|---|
| IBM Corporation |
| Palo Alto Networks |
| Microsoft Corporation |
| Fortinet |
| Absega Egypt Technology Services |
| Orange Cyberdefense Egypt |
| Cyberteq |
| Check Point Software Technologies |
| Keys Cyber |
| Others |
Pricing and Supply Chain Analysis
Zero-trust architect scarcity across Cairo and Alexandria inflates implementation costs for financial institutions, compressing mid-tier margins while premium managed security services command widening spreads. Egyptian banks absorbing Central Bank compliance mandates face labor-cost differentials that stratify procurement into sovereign-certified premium tiers versus standardized cloud-delivered platforms.
Pricing Analysis
Capacity additions in cloud-delivered security platforms are reshaping price floors across Cairo's fintech corridor. Subscription-based managed security services now dominate, with pricing stratifying across premium sovereign-certified tiers, standard cloud-native bundles, and economy antivirus replacements for Upper Egypt. Price differentiation hinges on Central Bank compliance certification and domestic data residency guarantees. Pricing pressure stems from compressed compliance timelines forcing rapid procurement. Healthcare providers show highest price sensitivity; government agencies least.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale bank demand, while tier-two integrators serve mid-market healthcare and retail segments. Hardware components for network security appliances concentrate in Taiwan, China, and the United States. Software-defined platforms draw from cloud infrastructure anchored in European and Gulf data centers with Egyptian edge nodes. Single-source vulnerability in specialized encryption chipsets poses structural risk. Distribution runs through Cairo-based systems integrators with Alexandria government contracting expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's cybersecurity market compounds steadily as regulatory tightening from the Central Bank of Egypt mandates recurring compliance investment across financial services. Sovereign data localization requirements create durable demand for domestic managed security operations.
For Market Incumbents: Acquire certified zero-trust architect teams to address talent scarcity constraining deployment velocity. Fortify managed security service partnerships with Cairo financial institutions facing compressed Central Bank audit cycles. Consolidate channel control through exclusive distribution agreements with Alexandria government integrators to preempt emerging sovereign security specialists. For New Entrants and Emerging Players: Enter via Upper Egypt governorates where endpoint security penetration remains minimal and digital inclusion programs expand device fleets. Target Sohag and Assiut healthcare networks migrating electronic medical records without matching security infrastructure. Deploy cost-optimized managed detection services through mobile-first distribution partnerships with local telecom operators. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic managed security services operators with established Central Bank compliance track records. Long-term viability centers on recurring revenue durability as regulatory mandates institutionalize security spending. Watch for inflection when Alexandria government digital hub procurement shifts from perpetual licenses to subscription models at scale.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Deployment | Central Bank tiered directives mandate segmentation upgrades across Cairo's licensed banking infrastructure. |
| Sovereign Security Operations Buildout | Alexandria government hubs require domestic data residency and Egyptian-staffed incident response capabilities. |
| Healthcare Cloud Security Expansion | Giza hospital networks migrating electronic medical records generate encryption and workload protection demand. |
| Managed Security Service Partnership | Subscription models displace perpetual licenses as Cairo financial institutions prioritize operational expenditure structures. |
| AI-ML Threat Detection Platform | Behavioral analytics integration differentiates vendor proposals in compressed Central Bank procurement cycles. |
Research Methodology
Multiple input streams — primary interviews with CISOs and IT procurement officers at Egyptian banks, conversations with Alexandria government digital transformation leads, and engagements with Cairo-based systems integrators — were reconciled against Central Bank regulatory filings, Egyptian Computer Emergency Readiness Team incident reports, and healthcare provider cloud migration disclosures. Secondary validation drew from customs data on network security hardware imports, hyperscaler capex announcements for Egyptian cloud regions, and financial institution annual reports. Bottom-up segment sizing triangulated with top-down market construction across deployment models and end-user verticals.
Historical spending patterns were cross-referenced against expert panel assessments of compliance timeline compression and SaaS migration velocity across the analysis window. Segmentation modeling incorporated product type, end-user industry, infrastructure location, and service delivery mode. CAGRs were derived from regression analysis of regulatory enforcement intensity, cloud adoption curves, and managed service penetration rates. Forecast inputs included Central Bank directive implementation schedules and healthcare digitization program milestones.
Inputs from primary stakeholder interviews and published regulatory frameworks were available through the study window; gaps in Upper Egypt governorates' actual security spending introduce uncertainty bands around endpoint security projections. Forecasts reflect assumptions regarding sustained regulatory enforcement and cloud provider data localization compliance. Periodic stress-testing of base assumptions against Central Bank policy shifts and currency volatility impacts is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Mexico Cybersecurity Market
Cybersecurity
Cloud Security in Banking Market
Cybersecurity
Africa Cybersecurity Market
Cybersecurity
Wireless Lan Security Market
Cybersecurity
China Ransomware Protection Market
Cybersecurity
Next-Gen Firewall Market
Cybersecurity
Multi-Cloud Data Protection Market
Cybersecurity
Cloud Endpoint Protection Market
Cybersecurity
Greece Cybersecurity Market
Cybersecurity
Europe Software Defined Perimeter Market
Cybersecurity
Global Container and Kubernetes Security Market
Cybersecurity
Open RAN Security Market
Cybersecurity
Asia Pacific Digital Forensics Market
Cybersecurity
Europe Cloud DLP Market
Cybersecurity
United States Virtualization Security Market
Cybersecurity
Cloud Siem Market