
 Pipe Manufacturing Machines Market | 2026-2036
Pipe Manufacturing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Pipe Manufacturing Machines Market Analytics
The EU Green Deal's embodied carbon thresholds for construction materials is repositioning European pipe producers toward low-energy extrusion lines. KraussMaffei leverages its Munich engineering base to dominate high-output twin-screw extruders for pressure pipe applications. Battenfeld-Cincinnati anchors Central European demand through integrated downstream calibration and cooling systems. Davis-Standard competes in North America with specialized corrugated pipe extrusion technology.
Pipe manufacturing machines encompass extrusion lines, benders, welders, and cutters that transform thermoplastic resins or metal feedstock into finished tubular products with controlled wall thickness, diameter tolerance, and pressure ratings. Extruders command the largest installed base due to polyethylene and PVC pipe dominance in water and gas distribution networks. CNC technology segments are expanding fastest as fabricators automate complex bend geometries and orbital welding for oil and gas gathering systems. Construction end users sustain the bulk of replacement demand through municipal water main rehabilitation programs.
The US EPA Lead and Copper Rule Revision mandates lead-free infrastructure replacement, driving demand for new extrusion capacity among domestic pipe producers. China's GB standards for plastic pipe pressure ratings and the EU F-Gas Regulation restricting fluorinated blowing agents in insulation pipe production both reshape machine specification requirements. REACH compliance in Europe and evolving state-level plumbing codes across California and Texas further fragment certification burdens. Stakeholders must monitor how diverging energy-efficiency benchmarks across these jurisdictions influence capital allocation for next-generation extrusion platforms.
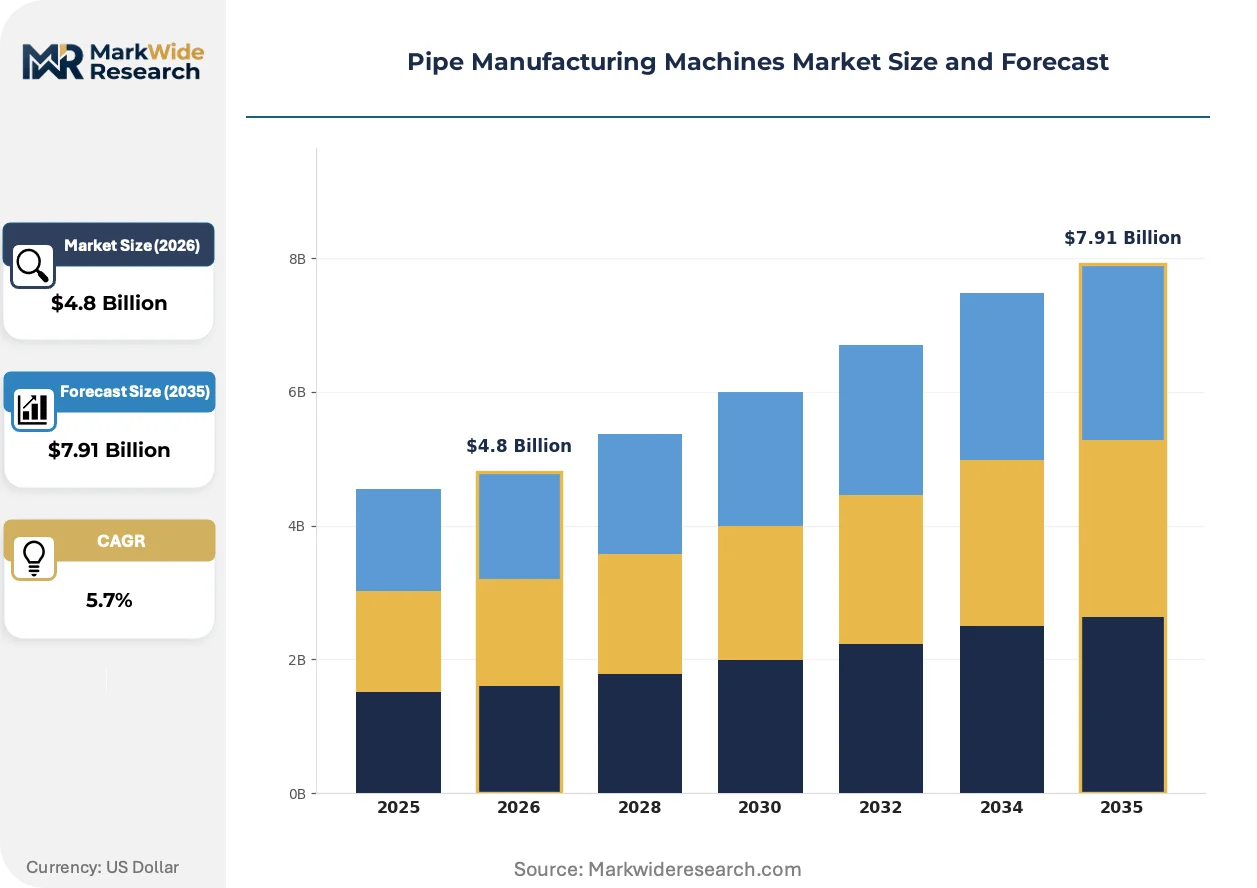
Market Dynamics
The EU Green Deal's embodied carbon thresholds for construction materials are forcing pipe producers to retire energy-intensive extrusion lines ahead of normal replacement cycles. This regulatory compression is reshaping capital allocation across the installed base.
Growth Catalysts
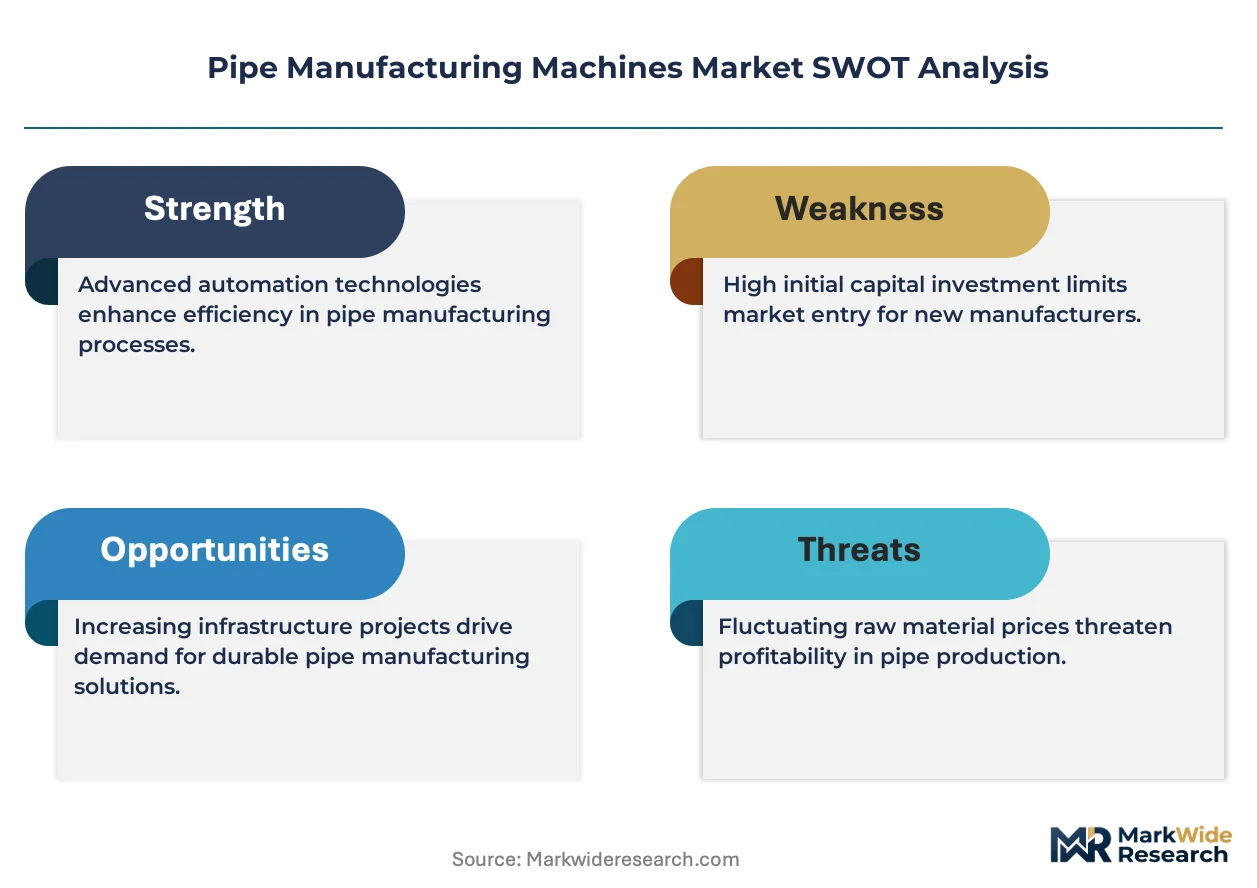
- US EPA Lead and Copper Rule Revision:The mandate for lead-free water infrastructure replacement is accelerating extrusion capacity expansion among domestic pipe producers serving municipal utilities.
- China's GB standards for plastic pipe pressure ratings:Upgraded technical specifications are compelling domestic manufacturers to modernize aging machine fleets with higher-precision extrusion controls.
- Polyethylene pipe dominance in gas distribution:Utility infrastructure upgrades across North American shale basins are sustaining demand for high-output extrusion lines rated for pressure pipe applications.
Market Restraints
- Steel and aluminum price volatility:Input cost swings for metal feedstock destabilize quoting cycles for welded pipe machinery producers serving oil and gas gathering systems.
- REACH compliance burden:The EU's chemical registration requirements create certification friction for imported extrusion additives and blowing agents used in insulation pipe production.
- Technical limitation in multi-layer co-extrusion:Complex barrier layer bonding for hydrogen distribution pipes remains below commercial yield thresholds, constraining equipment deployment.
Strategic Opportunities
- India's municipal water infrastructure:Underpenetrated urban distribution networks present white space for extrusion line suppliers as the country's national standards body escalates pressure rating requirements.
- EU F-Gas Regulation phase-down:The restriction on fluorinated blowing agents creates tailwinds for physical foaming extrusion technology in district heating pipe insulation.
- CNC pipe bender and orbital welder convergence:Fabricators serving offshore oil platforms are integrating automated bend-weld cells for complex subsea gathering system geometries.
Industry Challenges
- Controls engineering talent scarcity:The shortage of PLC programming specialists for multi-axis extrusion line synchronization is extending commissioning timelines.
- Legacy analog system integration:Brownfield sites struggle to retrofit Industry 4.0 data architectures onto 1990s-vintage extruder control platforms without full line replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipe Manufacturing Machines Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extruders, Benders, Welders, Cutters Technology: Automatic, Semi-Automatic, Manual, CNC End User: Construction, Oil & Gas, Automotive, Manufacturing Capacity: Small Scale, Medium Scale, Large Scale, Custom |
| Companies Covered | KraussMaffei, Battenfeld-Cincinnati, Milacron, Davis-Standard, DEKUMA, Sica, Everplast, Corma, Bandera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipe Manufacturing Machines Market Evolving Landscape
Electrification of extrusion drive systems is compressing the competitive window for hydraulic machinery suppliers. Machine builders are racing to deliver all-electric platforms before regulatory deadlines harden.
All-electric servo-driven extrusion systems are electrifying the replacement cycle for hydraulic twin-screw platforms in pressure pipe applications. German and Austrian machine builders are capturing early adoption among polyethylene pipe producers facing EU carbon accounting requirements. The technology is electrifying margin compression across mid-tier hydraulic equipment suppliers unable to fund R&D transitions.
The EU F-Gas Regulation's phase-down schedule for fluorinated greenhouse gases is forcing insulation pipe extruders to abandon chemical blowing agents. Physical foaming with nitrogen and carbon dioxide is displacing hydrofluorocarbon systems in district heating pre-insulated pipe production. Nordic and Baltic district heating operators are most affected, accelerating retrofit demand for gas-injection extrusion heads.
Outcome-based service contracting is displacing traditional break-fix maintenance models among large pipe fabricators. Equipment suppliers are unbundling predictive maintenance analytics from hardware sales, creating recurring revenue streams. This shift is most visible in North American shale gas gathering system fabricators, where uptime guarantees now dominate procurement evaluations.
Pipe Manufacturing Machines Market Segmentation
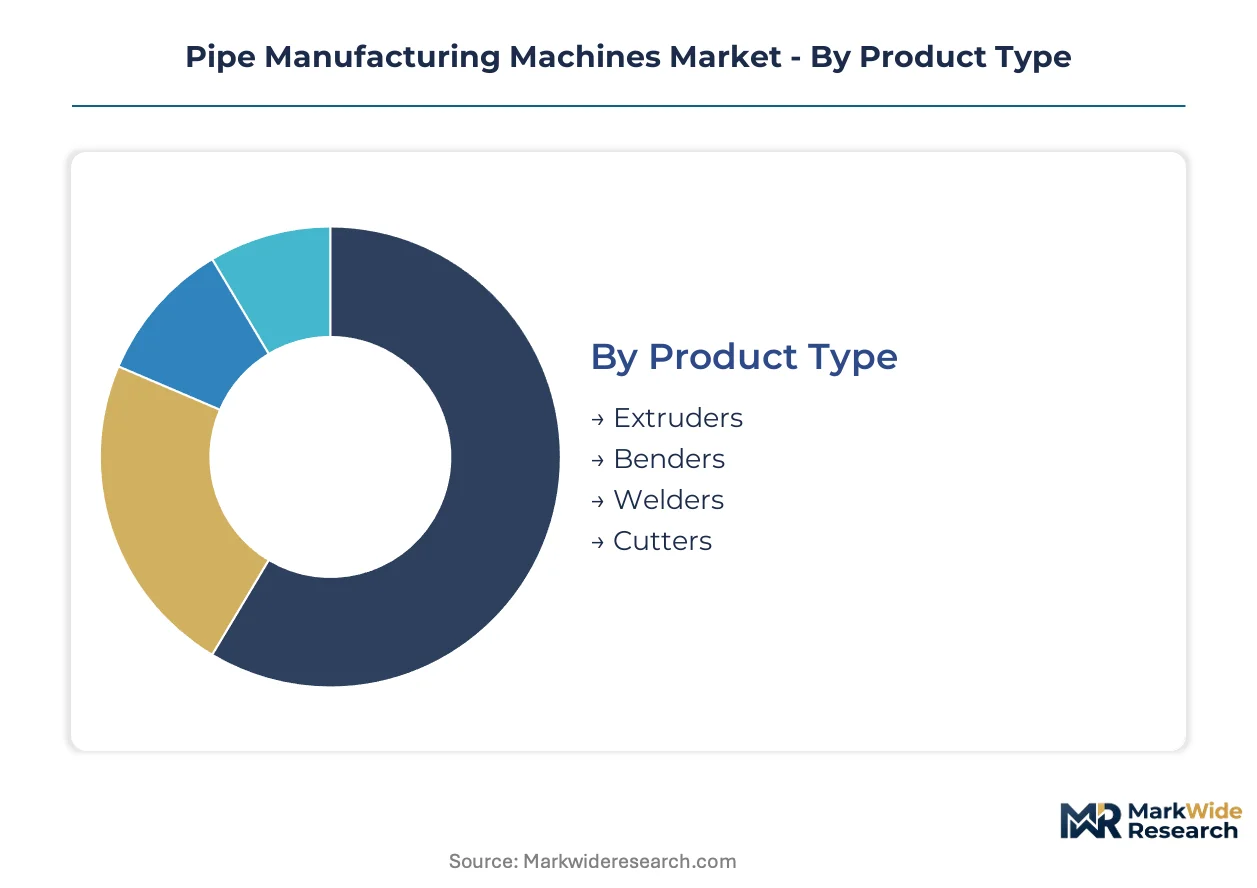
Segmentation in pipe manufacturing machines reveals how capital deployment, regulatory pressure, and end-use specifications fragment procurement patterns across the installed base. Machine builders align R&D roadmaps with the segments commanding replacement premiums.
Product Type:
Capital intensity varies sharply across equipment categories, with extrusion lines requiring the heaviest upfront outlays for melt processing, die engineering, and downstream calibration systems.
- Extruders:Twin-screw and single-screw configurations dominate thermoplastic pipe production, with melt pressure controls determining wall thickness precision. Demand concentrates among polyethylene pipe producers serving German municipal water utilities under EU Green Deal carbon accounting rules.
- Benders:Mandrel and rotary-draw systems shape metal and thermoplastic tubes to specified radii without wall thinning. CNC-equipped benders are gaining share fastest among automotive exhaust fabricators in the United States chasing complex geometry tolerances.
- Welders:Orbital and butt-fusion systems join pipe segments for pressure-rated applications.
- Cutters:Cold-cutting and thermal systems trim finished pipe to length with diameter-specific blade configurations.
Most installed capacity flows through extruders. Expansion is steepest in benders.
Technology:
Automation tier determines labor substitution economics and regulatory compliance pathways, with fully automatic platforms commanding premium pricing for continuous production environments.
- Automatic:Unattended operation through integrated material handling, process monitoring, and defect rejection systems. Automatic extrusion lines anchor Chinese pipe producers modernizing under upgraded GB pressure rating standards.
- CNC:Computer-numerical control enables multi-axis synchronization for complex bend sequences and weld path programming. CNC pipe benders are expanding most quickly among oil and gas gathering system fabricators in Texas shale basins.
- Semi-Automatic:Operator-supervised cycles with automated process stages and manual loading interventions.
- Manual:Hand-cranked or lever-actuated systems for low-volume custom fabrication and prototyping shops.
Automatic systems carry the largest installed base. CNC platforms are climbing the fastest.
End User:
End-use verticals impose divergent certification burdens and performance specifications that reshape machine configuration requirements at the quoting stage.
- Construction:Municipal water, drainage, and HVAC infrastructure applications specify pressure-rated polyethylene and PVC pipe. Construction demand concentrates in India where underpenetrated urban distribution networks are escalating pressure rating requirements.
- Oil & Gas:Gathering systems, transmission pipelines, and downhole applications require high-strength steel and corrosion-resistant alloy pipe. North American shale producers are driving replacement demand for orbital welding equipment under EPA methane monitoring rules.
- Automotive:Exhaust, fuel line, and structural tubing applications with tight bend radius tolerances.
- Manufacturing:General industrial fluid handling and process piping for chemical and food processing plants.
Construction absorbs the majority of installed capacity. Oil and gas represents the steepest expansion trajectory.
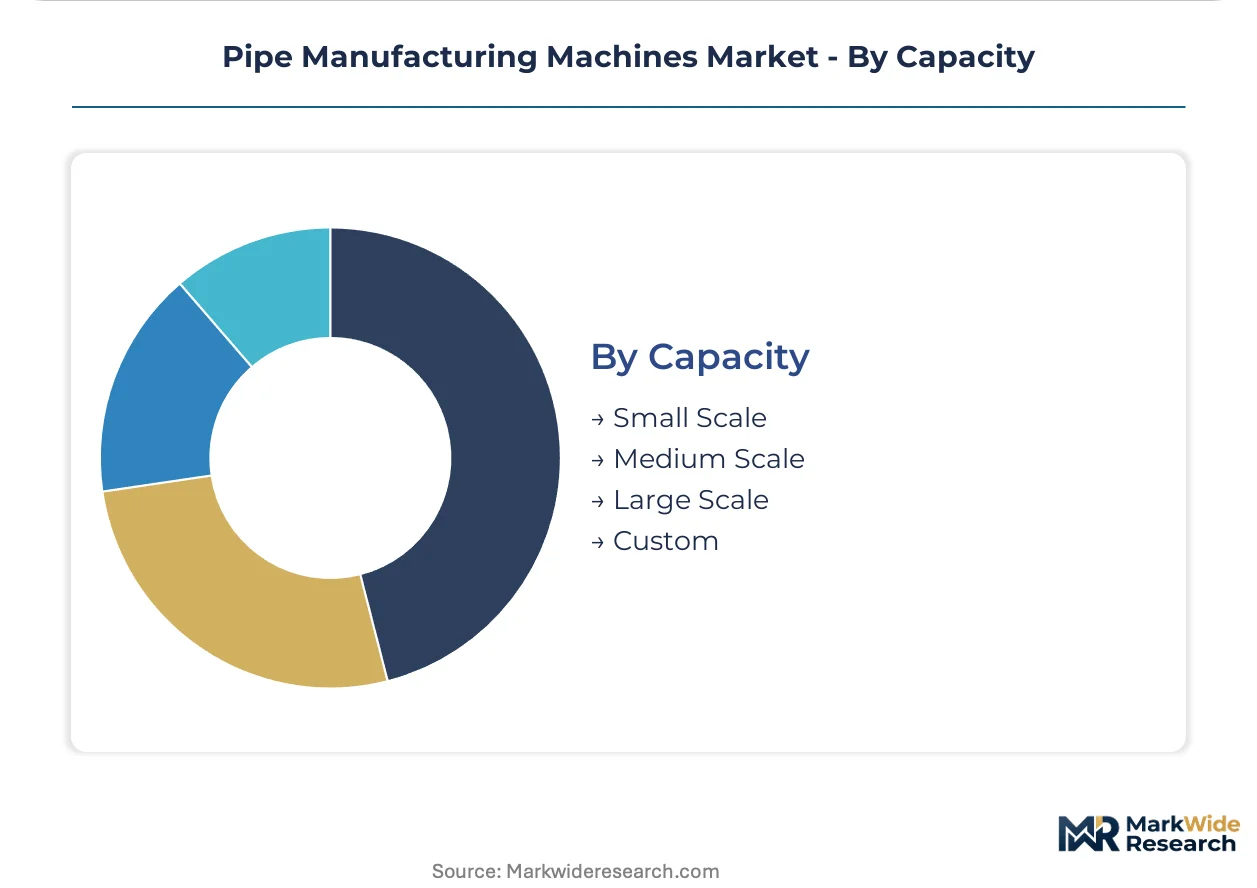
Capacity:
Scale tier determines supply chain integration depth, with large-scale producers captive-producing feedstock while small-scale operators source resins and coils spot-market.
- Large Scale:Continuous production lines exceeding 500kg/hour melt throughput for national distribution networks. Large-scale extrusion capacity clusters among German producers retrofitting for EU F-Gas Regulation compliance in district heating pipe insulation.
- Custom:Engineered-to-order systems for specialized alloys, multi-layer barrier constructions, or extreme diameter ranges. Custom machine demand is expanding fastest among hydrogen distribution pilot projects testing multi-layer co-extrusion bonding technologies.
- Medium Scale:Batch production systems serving regional distributors and specialty contractors.
- Small Scale:Job-shop equipment for prototype runs, repair segments, and localized distribution.
Large-scale systems dominate current installed capacity. Custom configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial extrusion technology in the post-war period, establishing Munich and Düsseldorf as centers for twin-screw engineering. This heritage now shapes regional specialization across pipe manufacturing machine demand.
United States
The EPA Lead and Copper Rule Revision mandates lead-free water infrastructure replacement, accelerating extrusion capacity expansion among domestic producers. State-level plumbing code evolution in California and Texas fragments certification requirements. Houston anchors orbital welding equipment demand for shale gas gathering systems under methane monitoring protocols.
Germany
The EU Green Deal's embodied carbon thresholds force early retirement of energy-intensive extrusion lines. Munich-based engineering groups dominate high-output twin-screw platforms for pressure pipe applications. Bavarian machine builders capture retrofit demand for physical foaming extrusion heads as the F-Gas Regulation phases down fluorinated blowing agents.
China
Upgraded GB standards for plastic pipe pressure ratings compel domestic manufacturers to modernize aging machine fleets. The MIIT dual carbon goals reshape capital allocation toward energy-efficient extrusion platforms. Yangtze River Delta pipe producers concentrate automatic line procurement for municipal water infrastructure scale-up.
India
Underpenetrated urban water distribution networks create white space for extrusion line suppliers. The BIS escalation of pressure rating requirements forces equipment upgrades among regional producers. Gujarat and Maharashtra industrial corridors concentrate demand for medium-scale batch production systems.
Japan
METI energy-efficiency benchmarks for industrial machinery accelerate electrification of extrusion drive systems. JIS standards for polyethylene pipe applications shape specification requirements at the quoting stage. Osaka-Kobe manufacturing clusters drive CNC pipe bender adoption for automotive exhaust fabrication.
Pipe Manufacturing Machines Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the pipe manufacturing machine landscape. The installed base fragments between integrated European engineering groups and specialized Asian fabricators. Three archetypes dominate: Munich-based precision engineering houses, Chinese scale-driven manufacturers, and North American application specialists. Consolidation pressure intensifies through technology licensing partnerships and selective geographic expansion into underpenetrated municipal water markets.
Within the European precision tier, KraussMaffei GmbH and Battenfeld-Cincinnati GmbH exemplify engineering-intensive positioning. Davis-Standard, LLC occupies a position among North American application specialists. These three anchors represent divergent strategic postures: German integrated platform dominance versus US corrugated pipe specialization.
| Leading Market Players |
|---|
| KraussMaffei |
| Battenfeld-Cincinnati |
| Milacron |
| Davis-Standard |
| DEKUMA |
| Sica |
| Everplast |
| Corma |
| Bandera |
| Others |
Value Network & Pricing Analysis
Captive in-house production of precision extrusion screws and die heads anchors pricing power among German engineering houses, while outsourced fabrication of standard hydraulic components exposes mid-tier Asian suppliers to margin compression. This integration divide separates premium machinery pricing from commodity equipment tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement, with KraussMaffei and Battenfeld-Cincinnati commanding certification-grade premiums for EU Green Deal-compliant extrusion lines. Price differentiation hinges on energy-efficiency ratings and after-sales predictive maintenance bundling. Cost compression in economy-tier hydraulic equipment is intensifying because Chinese scale manufacturers flood spot markets with undifferentiated single-screw platforms. Municipal utilities in Germany exhibit lowest price sensitivity due to regulatory compliance mandates, while Indian regional distributors remain most cost-conscious.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's MIIT dual carbon goals are reshaping sourcing patterns for critical drive components and control systems. Supply concentrates in Germany, China, and Italy for precision extrusion screws, melt pumps, and downstream calibration systems. Component sourcing draws from specialty steel foundries in Austria, servo motor producers in Japan, and PLC architecture from German automation houses. Single-source vulnerability persists for high-torque twin-screw gearboxes. Distribution runs through direct OEM sales teams for large-scale lines and regional machinery distributors for batch-production equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pipe manufacturing machines function as a stable compounder anchored by municipal infrastructure replacement cycles that transcend economic volatility.
For Market Incumbents: Deepen backward integration into precision screw manufacturing to defend margin position against Chinese scale entrants. Prioritize captive production of servo drive systems. Invest in predictive maintenance software certification under EU F-Gas Regulation timelines to lock in replacement demand from Nordic district heating operators. For New Entrants and Emerging Players: Launch via equipment-as-a-service models targeting India's underpenetrated municipal water infrastructure. White space exists in medium-scale batch extrusion lines for Gujarat and Maharashtra industrial corridors. Pursue technical licensing partnerships with German engineering houses to bypass R&D barriers in multi-layer co-extrusion bonding. For Investors and Strategic Acquirers: Roll-up economics work for regional service specialists with captive maintenance contracts because outcome-based contracting is displacing break-fix models across North American shale gas fabricators. Five-to-ten year viability frames around electrification retrofit cycles. Target mid-cap CNC bender manufacturers with orbital welding integration capabilities. Monitor EPA methane monitoring rule enforcement as inflection signal for oil and gas capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Captive screw manufacturing insulates German producers from Chinese spot-market volatility. |
| Predictive Maintenance Platform Launch | Outcome-based contracts lock in recurring revenue from EPA-regulated shale gas fabricators. |
| Physical Foaming Technology Retrofit | F-Gas Regulation phase-down forces district heating pipe producers toward nitrogen-based insulation systems. |
| CNC-Orbital Welding Cell Integration | Automated bend-weld convergence captures offshore platform fabrication demand under tightening geometry tolerances. |
| India Market Entry via Licensing | BIS pressure rating escalation creates equipment upgrade window for extrusion line suppliers. |
Research Methodology
Multiple input streams — plant engineer interviews, OEM procurement director discussions, regulatory filing analysis, and trade customs data — were reconciled to construct demand estimates. Primary fieldwork engaged maintenance directors at polyethylene pipe producers, aftermarket service heads at German engineering groups, and municipal utility procurement officers across India and the United States. Secondary validation drew from EPA enforcement databases, EU ECHA registration filings, MIIT equipment efficiency disclosures, and BIS standard revision notices. Bottom-up line-by-line demand aggregation and top-down macroeconomic scaling were cross-checked for consistency.
Data-stream reconciliation across product type, automation tier, end-use vertical, and capacity scale produced volume and value outputs. Segmentation dimensions modeled include extrusion versus bending versus welding equipment, automatic versus CNC versus manual control architectures, construction versus oil and gas versus automotive end-use, and large-scale continuous versus custom batch versus small-scale job-shop production. CAGRs were derived from replacement cycle analysis and regulatory deadline mapping. Industry-specific forecast inputs incorporated EU Green Deal carbon accounting phase-in schedules and EPA Lead and Copper Rule Revision implementation timelines.
Several conditions sit outside the modeled scope, including hypothetical breakthroughs in hydrogen distribution pipe bonding yields and unannounced revisions to REACH additive restrictions. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and municipal budget execution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
CNC Router Market
Construction Equipment
Global Submerged Arc Welding Market
Construction Equipment
Hydraulic Packers Market
Construction Equipment
Induction Furnace Market
Construction Equipment
Global Wheel Aligner Equipment Market
Construction Equipment
Excavator Wheels Market
Construction Equipment
Boring Bar Market
Construction Equipment
Manhole Housing Lifter Hook Market
Construction Equipment
Global Riveting Equipment Market
Construction Equipment
Europe Forklift Rental Market
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
Mexico Flexible Concrete Vibrator Market
Construction Equipment
Rotary Trommel Market
Construction Equipment
Grader Blades Market
Construction Equipment
Rail Welding Equipment Market
Construction Equipment
Global Hot Runner Market