
 Lifeboat Market | 2026-2036
Lifeboat Market Size, Share, and Industry Trends Forecast 2026-2036
Lifeboat Market Analysis
The International Maritime Organization's updated LSA Code is expanding the cost-of-entry calculus for lifeboat manufacturers, mandating enhanced structural integrity and launching-system redundancy. Norsafe AS leverages its Norwegian heritage to dominate freefall lifeboat engineering for harsh-environment platforms. VIKING Life-Saving Equipment anchors its position through extensive service networks spanning commercial shipping and offshore sectors. Survitec Group Limited differentiates via integrated survival solutions that extend beyond hardware into training and maintenance contracts.
A lifeboat is a self-contained survival craft engineered to evacuate personnel from vessels or offshore installations, typically constructed with fire-retardant fiberglass or aluminum hulls rated for wave-impact loads and thermal exposure. These craft must maintain positive stability in seas up to six meters and provide protected enclosure for occupants during freefall or davit-assisted descent to waterline. Freefall lifeboats command premium positioning due to their deployment speed in emergency scenarios on offshore platforms. Engineered lifeboats built from composite materials represent the fastest-growing material-product intersection, as weight reduction improves payload capacity without sacrificing SOLAS-mandated structural margins. Rigid lifeboats in steel retain volume leadership in commercial shipping retrofit cycles, though margin pools increasingly shift toward integrated launching-system packages.
The IMO's SOLAS convention and the EU's MDR framework collectively shape product certification timelines, with Notified Bodies in Germany and Norway conducting extended conformity assessments for launching appliances. The US Coast Guard enforces separate approval pathways under 46 CFR requirements, adding compliance layers for suppliers serving American-flagged fleets. Stakeholders must monitor divergence between IMO harmonized standards and emerging national cybersecurity mandates for connected survival craft monitoring systems.
Market Dynamics
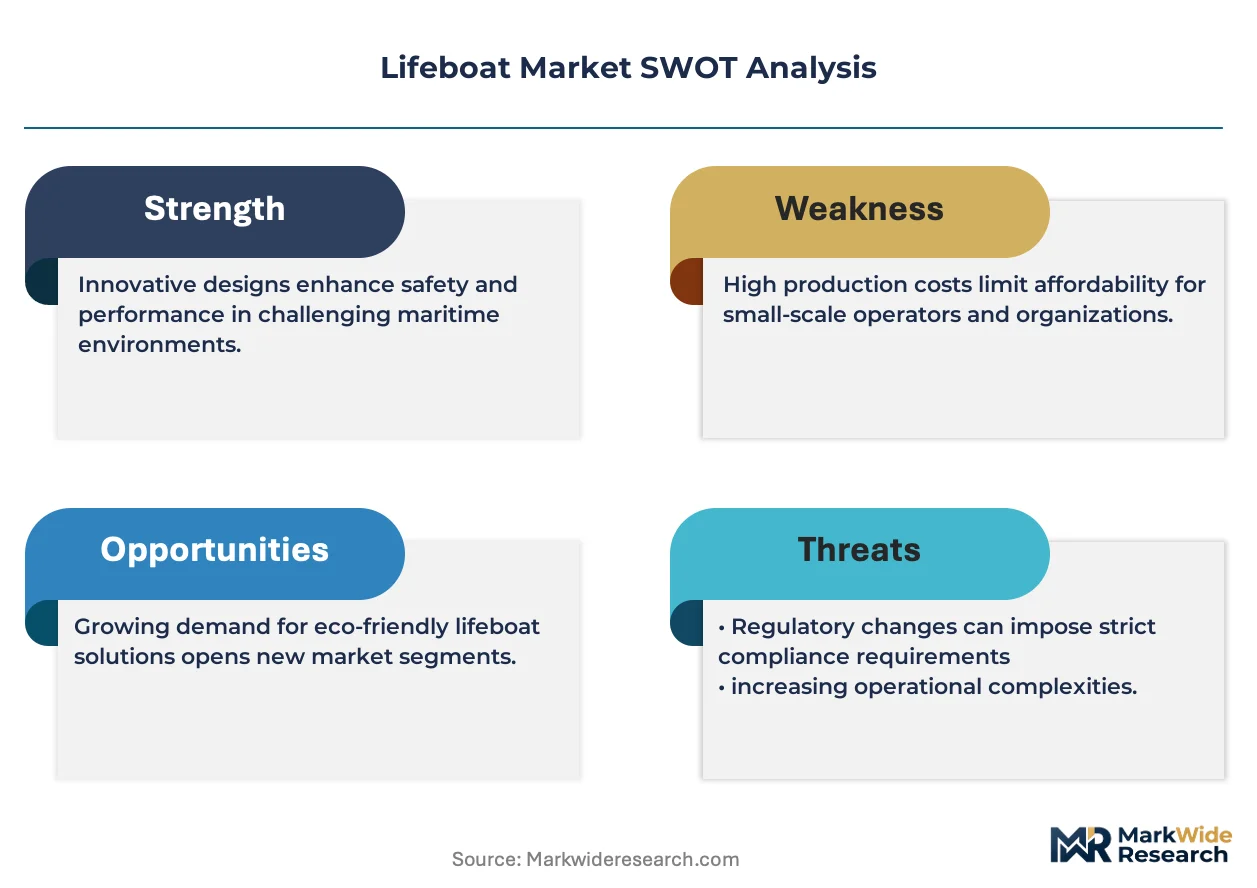
The International Maritime Organization's updated LSA Code is compressing product lifecycles by mandating redundant launching systems and enhanced hull integrity for freefall lifeboats deployed on harsh-environment platforms.
Growth Catalysts
- Deepwater exploration expansion:Offshore operators in Norway's North Sea cluster require advanced freefall systems as drilling moves beyond 500-meter depths.
- EU MDR framework harmonization:Notified Bodies in Germany and Norway now conduct extended conformity assessments, accelerating certification standardization across European-flagged fleets.
- Fiberglass-aluminum hybrid hulls:Composite material advances reduce craft weight while maintaining SOLAS-mandated structural margins, improving payload capacity for platform operators.
Market Restraints
- Aluminum and resin input volatility:Fire-retardant fiberglass hull production faces raw material cost swings tied to petrochemical supply chains.
- Launching appliance supply concentration:Specialized davit and winch manufacturing clusters in Northern Europe create single-source dependencies for system integrators.
- US Coast Guard 46 CFR divergence:Separate approval pathways for American-flagged vessels add compliance layers that delay product rollouts versus IMO-harmonized standards.
Strategic Opportunities
- Brazilian pre-salt field development:ANVISA and maritime regulator alignment on survival craft standards creates entry paths for certified suppliers in South Atlantic offshore expansion.
- Connected monitoring convergence:IoT sensor integration with hull integrity systems enables predictive maintenance contracts beyond hardware sales.
- Training and maintenance bundling:Integrated survival solutions that combine lifeboat deployment with crew certification programs capture recurring revenue streams.
Industry Challenges
- Marine engineer talent scarcity:Specialized expertise in freefall trajectory modeling and wave-impact simulation remains concentrated among aging workforce cohorts in Nordic shipbuilding regions.
- Extended Notified Body timelines:EU MDR conformity assessments for launching appliances now stretch 18-24 months, compressing product refresh windows.
- Legacy fleet retrofit complexity:Steel-hulled commercial vessels require structural deck reinforcement to accommodate modern davit systems, raising installation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lifeboat Market |
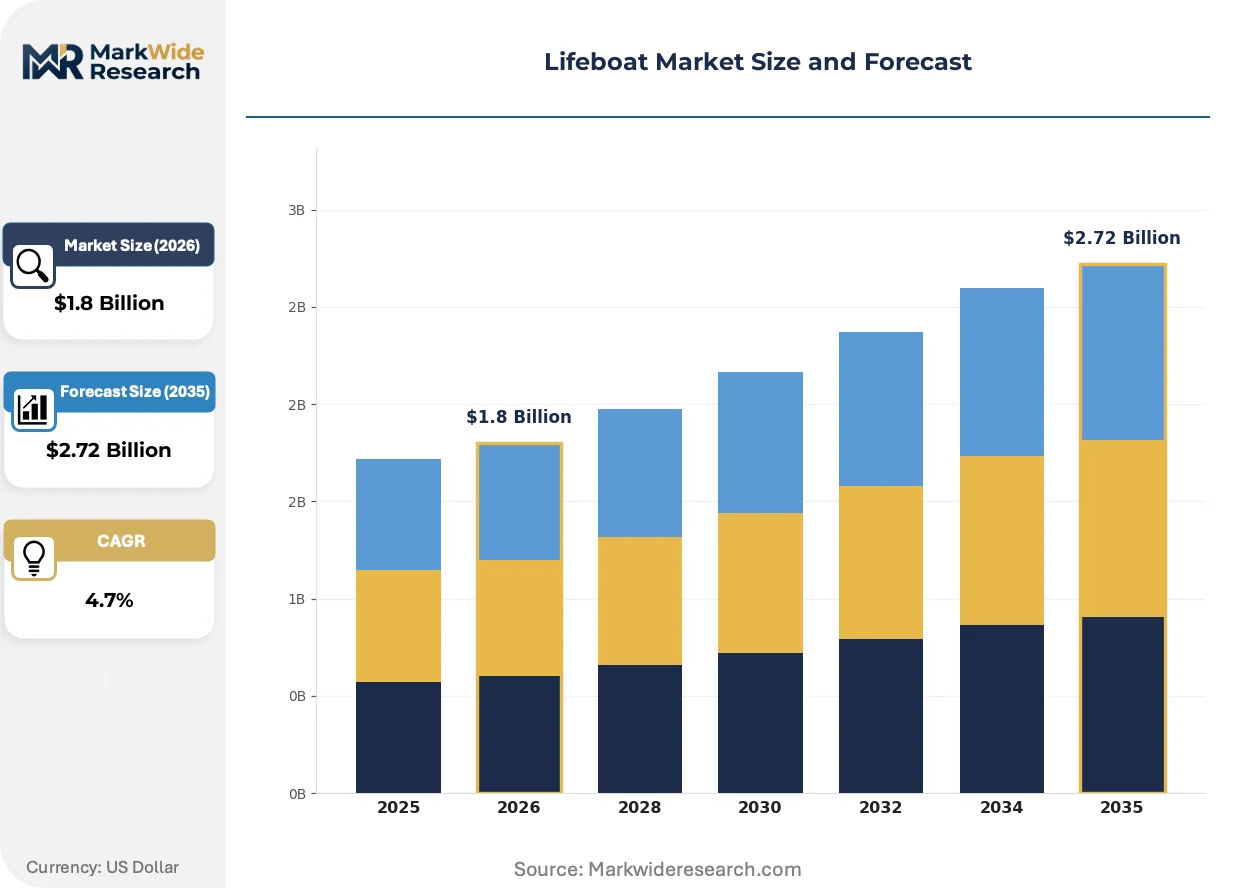
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engineered Lifeboats, Freefall Lifeboats, Rigid Lifeboats, Inflatable Lifeboats Material: Fiberglass, Steel, Aluminum, Composite End User: Marine Operators, Commercial Shipping, Offshore Platforms, Government Agencies Deployment Method: Onboard Launching, Davit Launching, Gravity Launching, Manual Launching |
| Companies Covered | Norsafe AS, HLB Lifesaving Equipment, VIKING Life-Saving Equipment, Jiangsu Jiaoyan Marine Equipment, Vanguarde, Fassmer, Palfinger Marine, Survival Systems International, Survitec Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lifeboat Market Emerging Trajectories
Survival craft engineering is pivoting toward autonomous deployment capabilities and real-time condition monitoring as offshore operators prioritize evacuation speed over legacy manual protocols.
Composite material engineering is integrating nanofiber-reinforced resin matrices into lifeboat hull lamination. North Sea platform operators are specifying these constructions for newbuild installations. The technology is integrating fire-retardant performance with weight reduction that expands occupant capacity without exceeding crane load limits.
REACH chemical restrictions are phasing out legacy halogenated flame retardants in fiberglass resin systems. German Notified Bodies now require alternative intumescent coatings in conformity assessments. Freefall lifeboat manufacturers serving EU-flagged fleets are reformulating hull specifications to maintain thermal exposure ratings under revised substance restrictions.
Platform operators are unbundling hardware procurement from service contracts, creating direct relationships with specialized maintenance providers. Traditional shipyard intermediaries are losing exclusivity in aftermarket support. This pattern is most visible in Norway's North Sea cluster, where Statoil-Equinor heritage operators now specify multi-year training and inspection packages separately from initial craft acquisition.
Lifeboat Market Segmentation
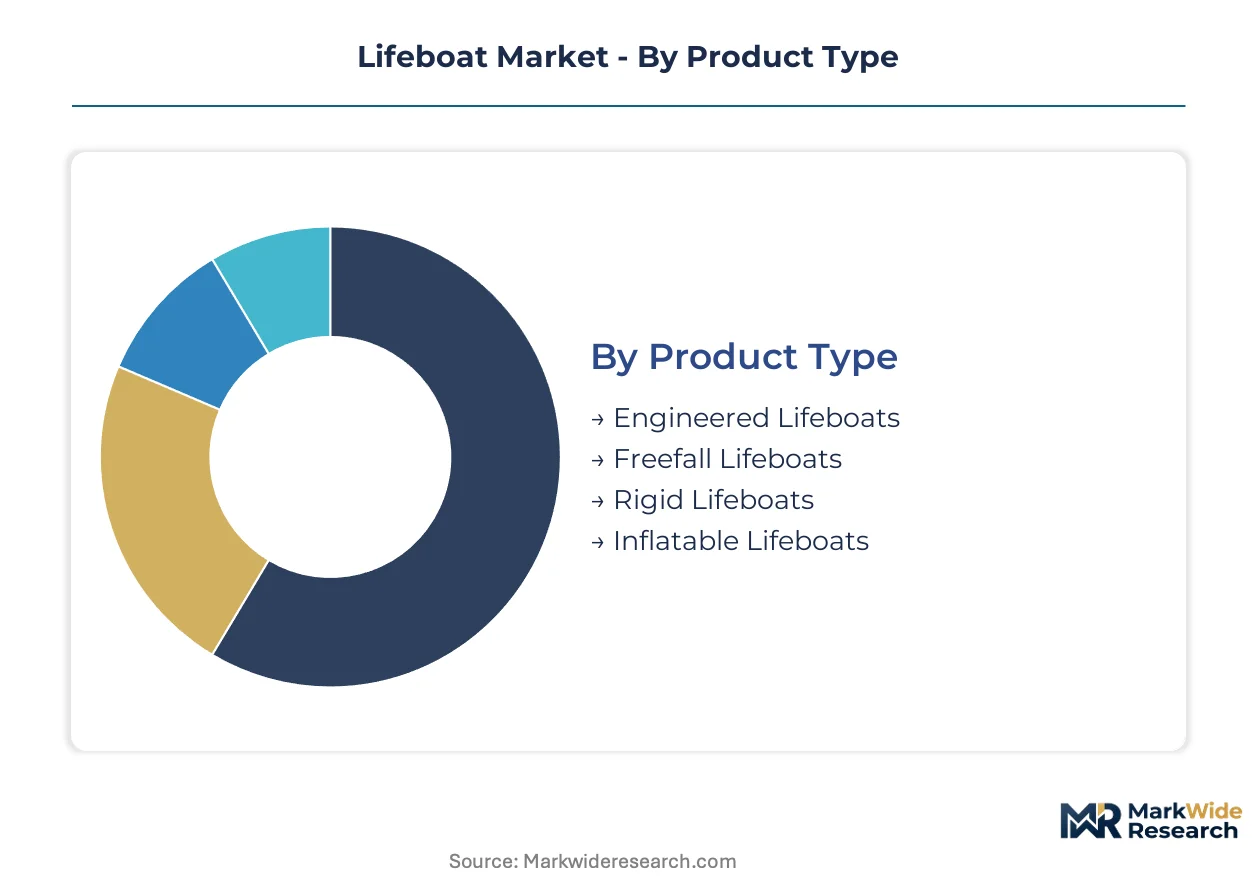
Lifeboat procurement patterns diverge sharply between volume-driven commercial shipping retrofits and premium offshore platform specifications. Understanding these segment dynamics reveals where margin pools concentrate and which technical specifications command pricing power across regulatory environments.
Product Type:
Freefall systems capture premium positioning through deployment speed advantages, while rigid craft dominate retrofit volumes in commercial fleets.
- Engineered Lifeboats:Custom-fabricated composite hulls with integrated launching systems designed for specific platform architectures. Norwegian North Sea operators specify these for harsh-environment installations where wave-impact simulation and trajectory modeling exceed standard SOLAS margins.
- Freefall Lifeboats:Self-righting enclosed craft launched via steep slipway descent, enabling rapid evacuation without davit dependency. Offshore platform operators in Brazil's pre-salt fields and Norway's deepwater cluster drive specification as drilling moves beyond 500-meter depths where conventional launching becomes impractical.
- Rigid Lifeboats:Steel-hulled enclosed survival craft meeting baseline SOLAS requirements for commercial vessel carriage.
- Inflatable Lifeboats:Collapsible fabric constructions for yacht and small craft emergency backup.
Today's leader: Rigid Lifeboats. Tomorrow's challenger: Freefall Lifeboats.
Material:
Weight reduction imperatives are displacing legacy steel specifications as payload capacity and crane load limits tighten across offshore fleets.
- Fiberglass:Fire-retardant resin-matrix laminates forming the dominant hull construction for commercial shipping retrofits. REACH chemical restrictions are forcing reformulation of halogenated flame retardants, with German Notified Bodies now requiring alternative intumescent coatings in conformity assessments.
- Composite:Nanofiber-reinforced hybrid laminates integrating fiberglass and advanced resin systems. North Sea platform operators specify these for newbuild installations where weight reduction expands occupant capacity without exceeding crane load limits, climbing the fastest among material categories.
- Steel:Welded plate hulls retaining volume leadership in legacy fleet replacement cycles.
- Aluminum:Marine-grade alloy constructions specified for corrosion resistance in tropical operating environments.
Composite constructions gain specification momentum where payload optimization intersects with thermal exposure mandates.
End User:
Procurement authority is fragmenting as platform operators unbundle hardware from service contracts, creating direct relationships with specialized maintenance providers.
- Offshore Platforms:Exploration and production installations requiring freefall and advanced davit systems for harsh-environment evacuation. Statoil-Equinor heritage operators in Norway now specify multi-year training and inspection packages separately from initial craft acquisition.
- Commercial Shipping:Container, tanker, and bulk carrier fleets subject to SOLAS carriage requirements. Retrofit demand concentrates in steel-hulled rigid craft, though structural deck reinforcement requirements raise installation costs for modern davit accommodation.
- Marine Operators:Ferry and passenger vessel fleets with high-capacity evacuation requirements.
- Government Agencies:Naval and coast guard specifications with customized performance parameters.
Offshore Platforms command specification authority for highest-margin integrated systems. Commercial Shipping provides volume stability through regulatory-mandated replacement cycles.
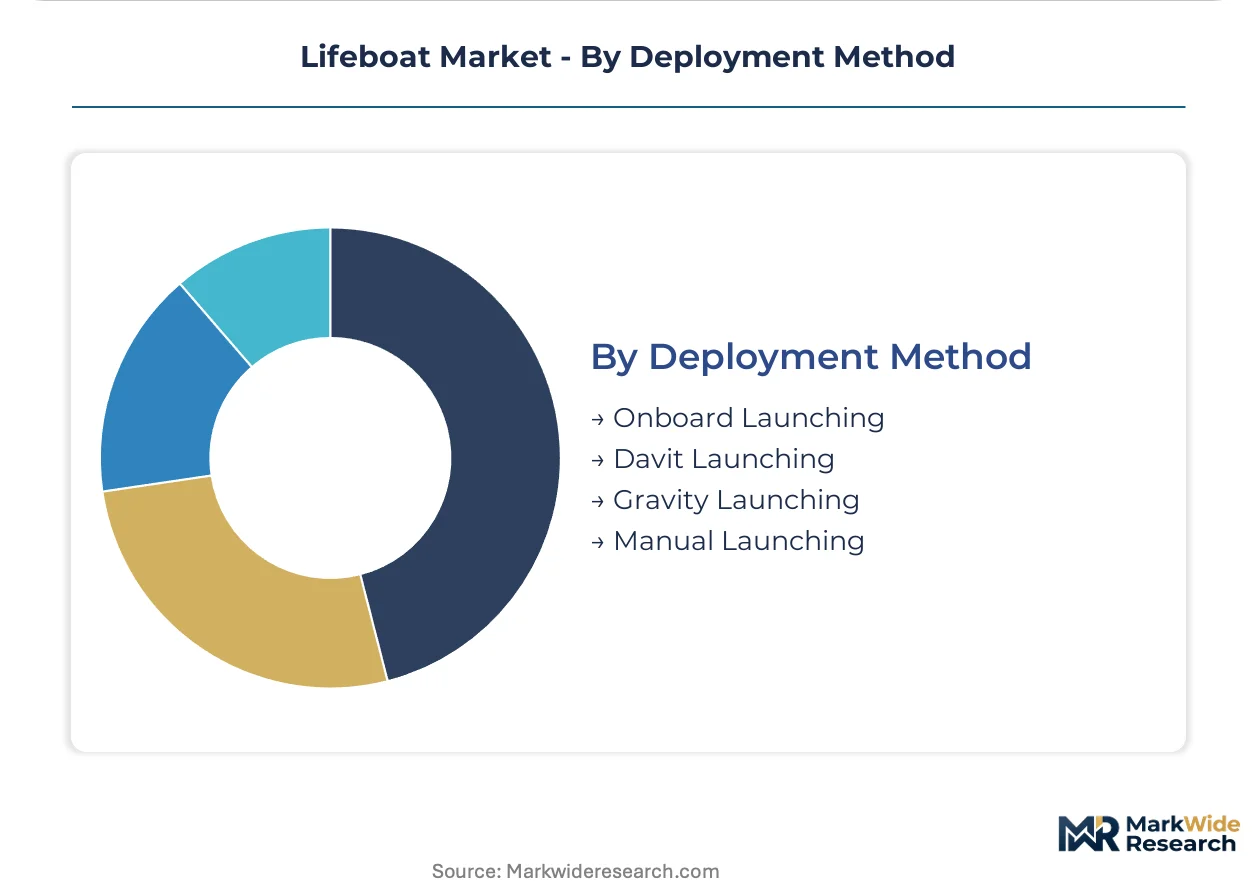
Deployment Method:
Launching appliance supply concentration in Northern Europe creates single-source dependencies that shape procurement risk calculations.
- Davit Launching:Crane-suspended descent systems with winch-controlled lowering to waterline. Specialized manufacturing clusters in Germany and Norway conduct extended conformity assessments under EU MDR frameworks, stretching certification timelines to 18-24 months.
- Gravity Launching:Freefall slipway systems enabling rapid unpowered descent. Norwegian Norsafe AS engineering heritage dominates this category for North Sea harsh-environment platforms where deployment speed outweighs legacy manual protocols.
- Onboard Launching:Integrated ship-side systems for commercial vessel evacuation.
- Manual Launching:Human-powered deployment for small craft and yacht applications.
Davit Launching retains installed base dominance. Gravity Launching captures newbuild specification in deepwater frontier basins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine engineering expertise concentrates in Nordic coastal regions where freefall trajectory modeling and wave-impact simulation capabilities developed over decades of harsh-environment platform operations.
Norway
Statoil-Equinor heritage operators in the North Sea cluster drive specification for advanced freefall and davit-launched systems as drilling moves beyond 500-meter depths. The Norwegian Maritime Authority enforces SOLAS compliance alongside national offshore safety regulations for platform evacuation craft. Stavanger and Bergen anchor engineering clusters where Norsafe AS and specialized suppliers maintain proximity to operator headquarters.
Brazil
Pre-salt field development in the South Atlantic creates demand for rapid-deployment survival craft suited to deepwater floating production units. ANVISA alignment with maritime regulators on survival craft standards streamlines certification pathways for certified suppliers. Rio de Janeiro state concentrates procurement authority where Petrobras heritage operators unbundle hardware from multi-year service contracts.
Germany
Commercial shipping retrofit cycles sustain volume demand for rigid steel-hulled craft and integrated launching appliances. Notified Bodies in Hamburg and Bremen conduct extended EU MDR conformity assessments stretching certification timelines to 18-24 months. Northern shipbuilding regions harbor specialized davit and winch manufacturing clusters that create single-source dependencies for system integrators.
United States
Gulf of Mexico offshore operators require survival craft rated for tropical corrosion environments and hurricane evacuation protocols. The US Coast Guard enforces separate 46 CFR approval pathways that add compliance layers versus IMO-harmonized standards. Louisiana and Texas coastal yards handle installation and maintenance for American-flagged fleets serving domestic energy production.
China
State-owned shipyard complexes drive volume production of standard SOLAS-compliant rigid lifeboats for commercial fleet replacement cycles. GB standards and maritime safety administration rules shape domestic certification requirements for survival craft. Yangtze River Delta manufacturing bases supply cost-optimized hull constructions for export markets and coastal shipping operators.
Lifeboat Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around engineering heritage in freefall systems, integrated survival solutions, and volume fabrication of standard craft. Three archetypes dominate: Norwegian-origin harsh-environment specialists, diversified maritime safety conglomerates with service network scale, and Asian fabricators optimizing cost-position for commercial shipping retrofits. Competitive moves concentrate on backward integration into launching appliance manufacturing and geographic expansion through local certification partnerships.
Within the Norwegian-origin specialist tier, Norsafe AS exemplifies engineering heritage in freefall trajectory systems for North Sea platforms. VIKING Life-Saving Equipment A/S occupies a diversified position spanning commercial shipping and offshore sectors through extensive service networks. Survitec Group Limited sits within the integrated solutions archetype, bundling hardware with training and maintenance contracts. Jiangsu Jiaoyan Marine Equipment Co., Ltd. represents the volume-fabrication segment serving standard SOLAS replacement demand.
| Leading Market Players |
|---|
| Norsafe AS |
| HLB Lifesaving Equipment |
| VIKING Life-Saving Equipment |
| Jiangsu Jiaoyan Marine Equipment |
| Vanguarde |
| Fassmer |
| Palfinger Marine |
| Survival Systems International |
| Survitec Group Limited |
| Others |
Supply Flow & Price Mechanics
Platform operator unbundling of hardware from multi-year service contracts in Norway's North Sea cluster forces suppliers to restructure revenue models toward recurring inspection and training packages, compressing upfront craft margins while extending customer lifetime value.
Pricing Analysis
Bundled-versus-unbundled procurement splits now define pricing architecture across offshore and commercial shipping segments. Three-tier pricing structure across premium freefall systems, standard davit-launched craft, and economy rigid hulls tracks certification grade and after-sales service inclusion. Price differentiation reflects SOLAS baseline versus enhanced IMO LSA Code compliance tiers. Cost compression in economy rigid hulls is intensifying because Chinese state-owned yards optimize standard SOLAS replacement volumes. Commercial shipping retrofit buyers exhibit highest price sensitivity; offshore platform operators accept premium positioning for deployment speed advantages.
Supply Chain Analysis
Certification gating through German and Norwegian Notified Bodies under EU MDR frameworks restricts supply base participation to qualified manufacturers with extended conformity assessment capabilities. Manufacturing concentrates in Norway, Germany, and China. Hull lamination draws from fire-retardant fiberglass resin systems, marine-grade aluminum alloys, and nanofiber-reinforced composite matrices. Single-source vulnerability runs through specialized davit and winch manufacturing clusters in Northern Europe. Distribution runs through direct operator relationships for offshore platforms and shipyard intermediaries for commercial fleet retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in integrated survival solutions where hardware bundling with predictive maintenance contracts captures recurring revenue, while composite material advances reduce production costs without sacrificing thermal exposure ratings.
For Market Incumbents: Lock in service contract exclusivity through multi-year training and inspection packages that platform operators now specify separately from initial craft acquisition. Deepen backward integration into launching appliance manufacturing to reduce dependency on Northern European davit and winch clusters. Invest in nanofiber-reinforced composite lamination capabilities to defend premium positioning against Asian volume fabricators. For New Entrants and Emerging Players: Launch via direct relationships with Brazilian pre-salt field operators where ANVISA alignment on survival craft standards streamlines certification pathways. Target connected monitoring system integration as the most penetrable white-space segment, offering IoT sensor packages that enable predictive maintenance contracts beyond hardware sales. Pursue local certification partnerships in Rio de Janeiro state to bypass established Norwegian engineering heritage barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated survival solution providers that bundle hardware with training and maintenance contracts. Long-term viability favors vendors with captive supply of launching appliances and established Notified Body relationships. The signal to watch is ANVISA regulatory alignment progress in Brazil, which would validate South Atlantic offshore expansion as a demand inflection point.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Launching Appliances | Captive supply of davits and winches reduces single-source dependency risk from Northern European clusters. |
| Composite Material Certification Investment | Nanofiber-reinforced hull lamination meets REACH chemical restrictions while expanding payload capacity. |
| Connected Monitoring Platform Development | IoT sensor integration enables predictive maintenance contracts beyond transactional hardware sales. |
| Local Certification Partnership in Brazil | ANVISA alignment streamlines entry into pre-salt field procurement cycles. |
| Training and Maintenance Bundling | Multi-year service packages capture recurring revenue as platform operators unbundle hardware procurement. |
Methodological Framework
Multiple input streams — primary interviews with lifeboat engineering directors, offshore platform safety managers, and Notified Body certification leads; secondary validation through IMO SOLAS amendments, EU MDR conformity assessment records, and customs trade data — were reconciled through bottom-up craft shipment analysis and top-down market sizing triangulation.
Data-stream reconciliation across product type, material composition, deployment method, and end-user vertical dimensions anchored volume and value outputs throughout the forecast period. CAGRs were derived from segment-level growth trajectory analysis. Industry-specific forecast inputs included offshore drilling depth expansion rates and REACH chemical restriction implementation timelines for fire-retardant resin systems.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended Notified Body assessment timelines or abrupt raw material input volatility. Deviation in IMO LSA Code enforcement intensity across flag state administrations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
Survival Tools Market
Emergency and Disaster Management
Outdoor Emergency Safety Shower Market
Emergency and Disaster Management
Emergency Shutdown System Market
Emergency and Disaster Management
Homeland Security and Emergency Management Market
Emergency and Disaster Management
Global Emergency Beacon Transmitter Market
Emergency and Disaster Management
Advanced Disaster Management Simulator Market
Emergency and Disaster Management
Global Emergency Notification Software Market
Emergency and Disaster Management
Cyber Crisis Management Market
Emergency and Disaster Management
Emergency Lighting Market
Emergency and Disaster Management
Asia-Pacific Process Safety Services Market
Emergency and Disaster Management
Global Emergency Medical Service (EMS) Products Market
Emergency and Disaster Management
Emergency Location Transmitter Market
Emergency and Disaster Management
Hazard Control Market
Emergency and Disaster Management
Disaster Restoration Services Market
Emergency and Disaster Management
Emergency Shower and Eyewash Station Market
Emergency and Disaster Management
Emergency and Disaster Response Market