
 Disaster Restoration Services Market | 2026-2036
Disaster Restoration Services Market Size, Share, and Industry Trends Forecast 2026-2036
Disaster Restoration Services Market Insights
Certified restoration technicians is rotating toward shortage in multiple metropolitan zones, tightening project timelines and elevating labor costs for regional operators. BELFOR leverages its international footprint to cross-train technicians across flood and fire disciplines. Servpro sustains franchise density in suburban corridors, anchoring rapid-response capacity. Paul Davis Restoration competes through contractor network exclusivity in insurance-preferred vendor programs.
Disaster restoration services encompass emergency mitigation, structural drying, contaminant removal, and reconstruction of properties damaged by water, fire, mold, or severe weather events; technicians deploy thermal imaging to locate hidden moisture pockets and industrial-grade dehumidifiers to achieve specific humidity thresholds before rebuilding commences. Water damage restoration occupies the largest revenue share due to persistent plumbing failures and storm-related flooding across coastal and riverine zones. Mold remediation represents the fastest-expanding service type as liability awareness and indoor air quality standards tighten in commercial lease agreements. Reconstruction services command elevated margins relative to cleanup services because they require licensed subcontractor coordination and extended project oversight.
OSHA mandates govern worker exposure limits during mold abatement and demolition activities, while EPA guidelines under the Lead Renovation, Repair and Painting Rule constrain restoration practices in pre-1978 structures. State-level contractor licensing boards in Florida, Texas, and California impose continuing education requirements that filter out undercapitalized entrants. Stakeholders must monitor evolving federal flood risk maps and insurance rate recalibrations that will redirect capital toward resilient building retrofits rather than reactive restoration alone.
Market Dynamics
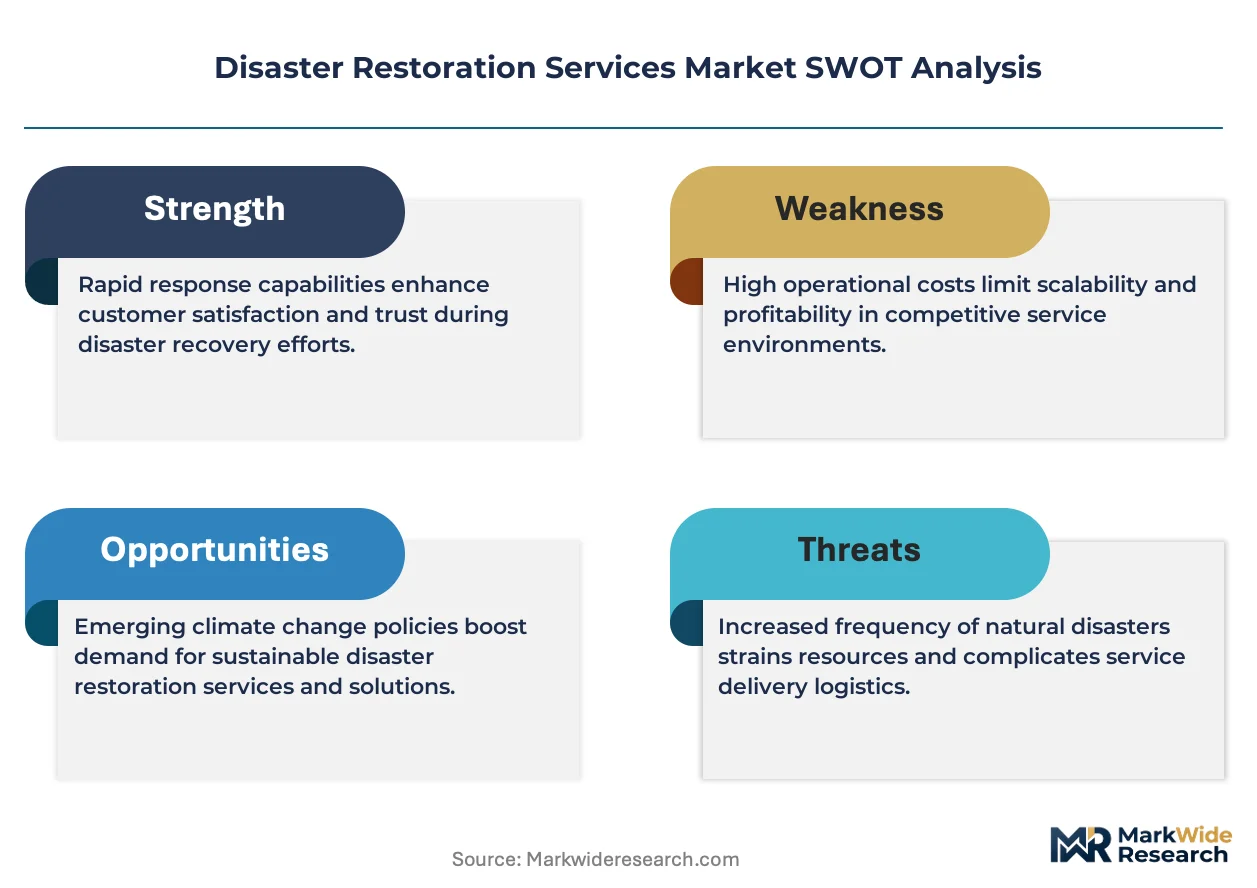
Thermal imaging and moisture-mapping technologies are compressing inspection timelines while OSHA mold abatement mandates and state-level contractor licensing boards in Florida, Texas, and California raise capital barriers for new entrants.
Growth Catalysts
- EPA Lead Renovation, Repair and Painting Rule:Pre-1978 structure remediation creates recurring compliance-driven contract volume for certified restoration firms across the United States.
- Commercial real estate portfolios:Institutional landlords are consolidating vendor relationships under master service agreements to satisfy tightening building safety mandates and insurance audit requirements.
- Climate-driven weather volatility:Intensified storm frequency across coastal and riverine zones sustains emergency mitigation demand and reconstruction backlogs.
Market Restraints
- Certified technician shortage:Labor scarcity in multiple metropolitan zones tightens project timelines and elevates regional operator wage costs.
- Industrial-grade dehumidifier supply:Equipment lead times from specialized manufacturers create capacity bottlenecks during peak disaster seasons.
- Insurance rate recalibration:Federal flood risk map revisions redirect capital toward resilient retrofits, compressing reactive restoration contract values in high-risk zones.
Strategic Opportunities
- Mold remediation service expansion:Liability awareness and indoor air quality standards in commercial lease agreements open fastest-expanding revenue segment.
- Reconstruction margin capture:Licensed subcontractor coordination and extended project oversight command elevated margins relative to cleanup-only services.
- Cross-training technician mobility:Flood and fire discipline versatility enables labor deployment optimization across disaster type fluctuations.
Industry Challenges
- State continuing education compliance:Florida, Texas, and California licensing boards impose ongoing training requirements that filter undercapitalized entrants.
- Humidity threshold verification:Achieving specified moisture levels before rebuilding commences demands precise thermal imaging interpretation and documentation.
- Subcontractor network coordination:Reconstruction services require licensed trade management across electrical, plumbing, and structural disciplines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disaster Restoration Services Market |
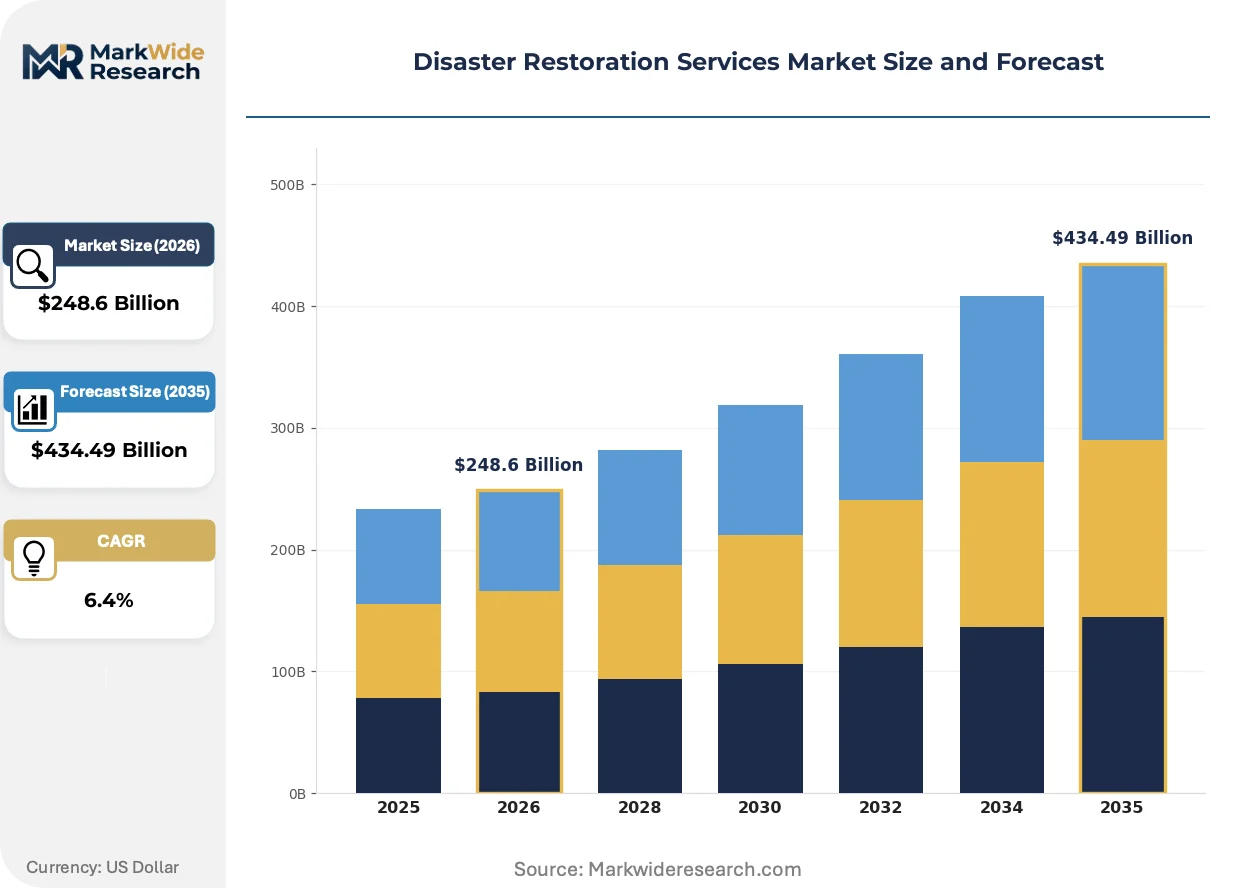
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $434.49 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Water Damage Restoration, Fire Damage Restoration, Mold Remediation, Storm Damage Restoration End User: Residential, Commercial, Industrial, Government Solution: Inspection Services, Cleanup Services, Repair Services, Reconstruction Services Technology: Thermal Imaging, Dehumidifiers, Air Movers, Water Extraction Equipment |
| Companies Covered | BELFOR, Servpro, Paul Davis Restoration, 911 Restoration, Restoration 1, GDI Integrated Facility Services, ServiceMaster Restore, BluSky Restoration Contractors, ATI Restoration, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disaster Restoration Services Market Trends and Innovations
Digital inspection tools and predictive moisture analytics are compressing traditional assessment timelines while regulatory frameworks tighten documentation standards across restoration protocols.
Advanced thermal imaging systems with embedded moisture-mapping algorithms are fragmenting the competitive landscape between technology-enabled national operators and equipment-constrained regional firms. Commercial property managers and institutional insurers are adopting these platforms for pre-loss baseline documentation and post-event verification. The technology is fragmenting service delivery into data-intensive inspection specialists separate from physical remediation crews.
OSHA worker exposure limits during mold abatement and demolition activities are mandating enhanced personal protective equipment protocols and airborne contaminant monitoring. Industrial hygienist oversight requirements are extending project initiation timelines and elevating documentation burdens. Commercial restoration contracts in the United States are absorbing these compliance costs through adjusted pricing structures and extended scoping phases.
Insurance-preferred vendor programs are consolidating buyer relationships around contractor network exclusivity and rapid-response capacity metrics. Suburban corridor franchise density is displacing dispersed independent operators in catastrophe response procurement. Property insurers in hurricane-exposed states are prioritizing pre-positioned equipment inventories and guaranteed response time commitments over price competition.
Disaster Restoration Services Market Segmentation
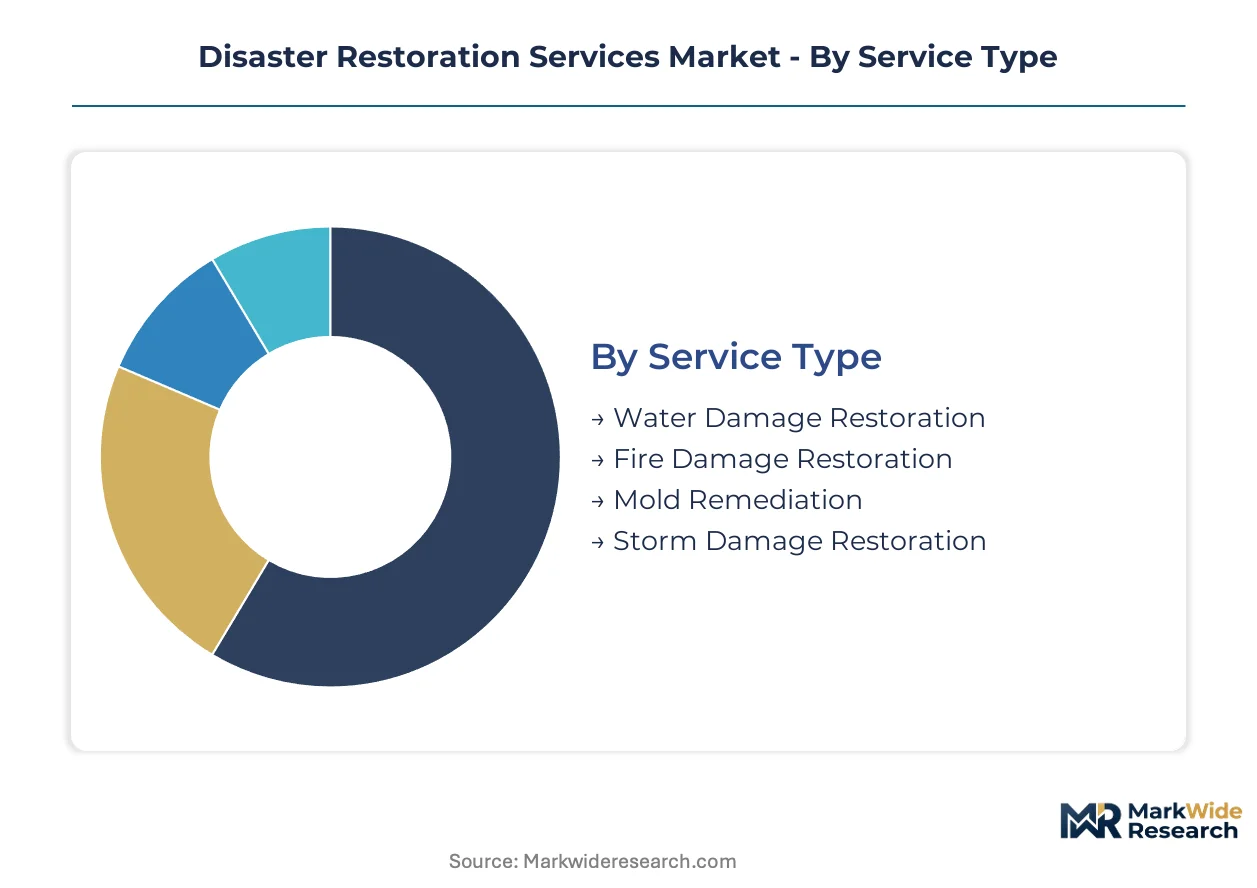
Service differentiation in disaster restoration determines pricing power, equipment requirements, and regulatory exposure. Segmentation reveals where technology substitution threatens incumbent models and where specialized capabilities command premium positioning.
Service Type:
Water damage restoration faces the strongest substitution pressure from in-house facilities management teams equipped with portable dehumidifiers, while mold remediation's technical barriers protect specialized providers.
- Water Damage Restoration:Emergency mitigation and structural drying following plumbing failures, storm flooding, or appliance leaks. Demand concentrates in coastal Florida and riverine Texas zones where aging infrastructure and climate volatility sustain contract volumes despite equipment commoditization.
- Mold Remediation:Contaminant removal and air quality restoration following moisture intrusion, governed by OSHA exposure limits and EPA guidelines. Commercial lease agreements in California and institutional insurer mandates are tightening liability standards and extending project scopes.
- Fire Damage Restoration:Soot removal, odor neutralization, and structural stabilization following combustion events.
- Storm Damage Restoration:Emergency board-up, debris removal, and temporary weatherproofing for wind and hail damage.
Water damage restoration anchors the volume base while mold remediation gains share at the steepest rate.
End User:
Cost tier stratification separates price-sensitive residential repair from commercial portfolios consolidating under master service agreements.
- Commercial:Institutional landlords and property management firms requiring rapid-response capacity and documentation for insurance audits. Master service agreements with national operators are displacing fragmented local vendor relationships in hurricane-exposed states.
- Residential:Homeowners and rental property owners purchasing restoration through insurance claims or out-of-pocket. Suburban corridor franchise density determines capture rates, with independent operators losing procurement share to pre-positioned national networks.
- Industrial:Manufacturing facilities and warehouses requiring containment protocols to protect operational continuity.
- Government:Municipal buildings, schools, and public infrastructure subject to procurement regulations and extended payment cycles.
Commercial contracts anchor the volume base while residential demand expands most quickly as insurance-preferred vendor programs penetrate suburban markets.
Solution:
Margin concentration separates data-intensive inspection from labor-heavy cleanup and capital-intensive reconstruction.
- Reconstruction Services:Licensed subcontractor coordination across electrical, plumbing, and structural trades to return properties to pre-loss condition. Extended project oversight and trade management complexity command elevated margins relative to mitigation-only services in commercial portfolios.
- Inspection Services:Thermal imaging and moisture-mapping documentation to establish damage scope and verify completion thresholds. Digital platforms with embedded analytics are fragmenting delivery between technology-enabled specialists and physical remediation crews.
- Cleanup Services:Debris removal, contaminant extraction, and surface sanitization using industrial-grade equipment.
- Repair Services:Component-level restoration of damaged systems without full reconstruction.
Cleanup services anchor the volume base while reconstruction services capture margin expansion fastest.
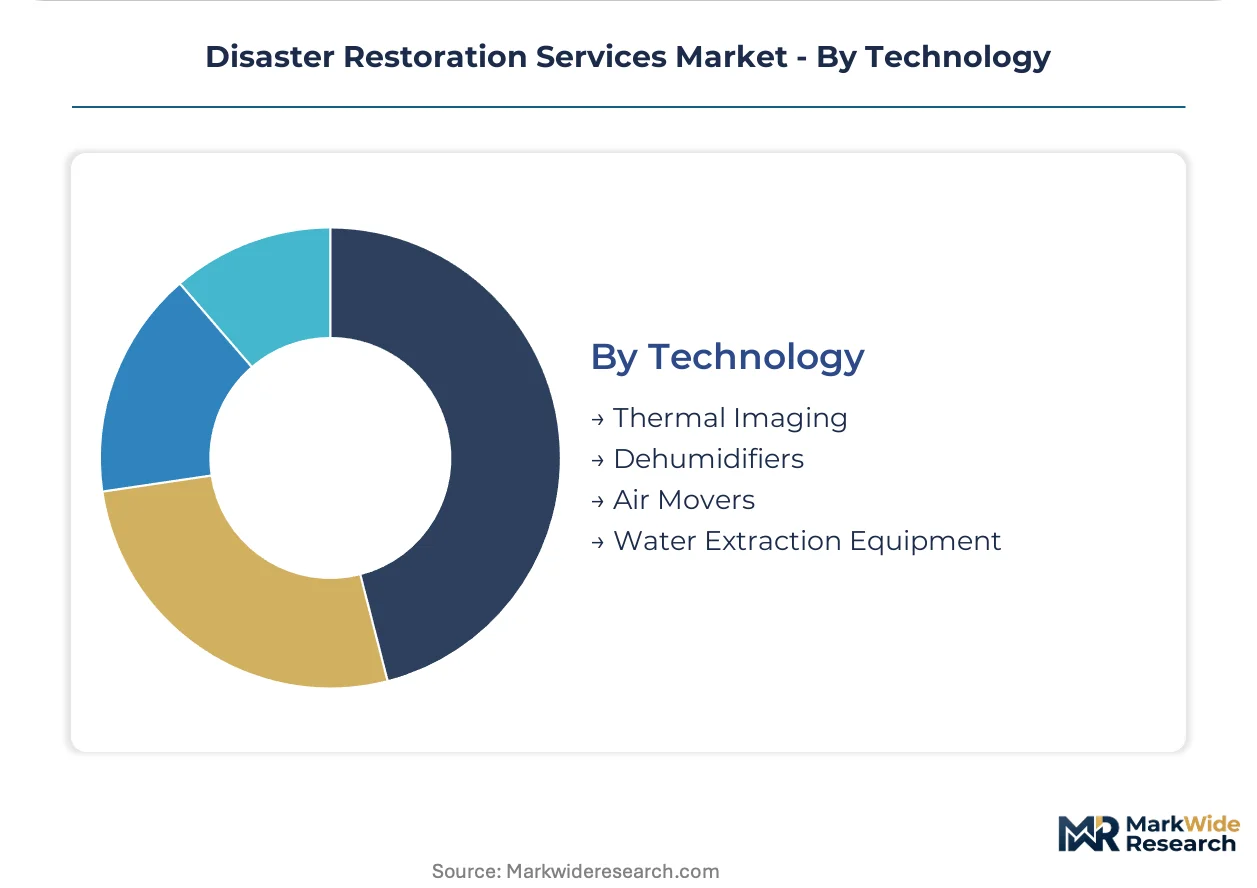
Technology:
Supply concentration in specialized manufacturing creates equipment bottlenecks during peak disaster seasons.
- Thermal Imaging:Infrared camera systems with moisture-mapping algorithms to locate hidden water pockets behind walls and under flooring. Property insurers and commercial managers are adopting these platforms for pre-loss baseline documentation and post-event verification protocols.
- Dehumidifiers:Industrial-grade desiccant and refrigerant units achieving specific humidity thresholds before rebuilding commences. Lead times from specialized manufacturers constrain regional operator capacity during surge demand periods.
- Air Movers:High-velocity fans accelerating evaporation rates in structural drying protocols.
- Water Extraction Equipment:Truck-mounted and portable pumps for standing water removal.
Dehumidifiers anchor the volume base while thermal imaging climbs the fastest as digitization reshapes inspection protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes disaster restoration services through insurance-preferred vendor programs and rapid-response capacity contracts, while European markets emphasize regulatory compliance documentation and certified technician training protocols.
United States
Coastal Florida and riverine Texas zones sustain water damage contract volumes through aging infrastructure and climate-driven storm frequency. OSHA mandates govern worker exposure limits during mold abatement and demolition activities. The suburban corridor franchise density in hurricane-exposed states anchors rapid-response procurement networks.
Germany
Industrial facility restoration and commercial portfolio master service agreements drive demand in manufacturing-heavy regions. REACH regulations and ECHA guidelines constrain chemical use in contaminant removal protocols. The North Rhine-Westphalia industrial corridor concentrates reconstruction service contracts for operational continuity protection.
Japan
Seismic event preparedness and typhoon recovery protocols shape service procurement through METI-coordinated resilience programs. JIS standards govern building material specifications in post-disaster reconstruction phases. The Kanto region surrounding Tokyo maintains the densest concentration of certified restoration technicians and thermal imaging specialists.
Canada
Flood risk mapping revisions and federal disaster assistance programs redirect capital toward resilient retrofits in riverine and coastal municipalities. Health Canada guidelines intersect with provincial contractor licensing requirements in Ontario and Quebec. The Prairie Provinces experience concentrated spring thaw flooding that sustains seasonal contract surges.
Australia
Bushfire recovery and cyclone damage restoration dominate service procurement through state-level emergency management frameworks. TGA-aligned safety protocols govern airborne contaminant monitoring during smoke damage remediation. New South Wales and Queensland coastal zones sustain the highest reconstruction backlog volumes.
Disaster Restoration Services Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the disaster restoration services market. National operators with international footprints cross-train technicians across flood and fire disciplines to optimize labor deployment. Franchise networks anchor suburban corridor density for rapid-response capacity. Three archetypes dominate: technology-enabled nationals, insurance-preferred vendor consolidators, and regional specialist contractors. Competitive moves concentrate on master service agreement consolidation and thermal imaging platform adoption.
Within the integrated leader tier, BELFOR leverages its international footprint to anchor cross-training protocols across disaster disciplines. Servpro exemplifies the franchise-density archetype through suburban corridor rapid-response positioning. Paul Davis Restoration occupies a position within insurance-preferred vendor programs through contractor network exclusivity arrangements.
| Leading Market Players |
|---|
| BELFOR |
| Servpro |
| Paul Davis Restoration |
| 911 Restoration |
| Restoration 1 |
| GDI Integrated Facility Services |
| ServiceMaster Restore |
| BluSky Restoration Contractors |
| ATI Restoration |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at industrial-grade dehumidifier manufacturers in the United States and Germany anchors price floors for regional restoration operators, with equipment lead times stretching to eight weeks during peak disaster seasons and compressing margins for undercapitalized entrants unable to pre-position inventory.
Pricing Analysis
Long-term master service agreements with commercial real estate portfolios anchor pricing stability, while spot-market emergency calls command premium multiples. Price differentiation rests on EPA Lead Renovation, Repair and Painting Rule certification tiers and thermal imaging documentation capabilities. Cost compression in residential water damage restoration intensifies as portable equipment enables in-house facilities management teams. Commercial portfolios demonstrate the lowest price sensitivity due to insurance audit requirements and liability exposure.
Supply Chain Analysis
Inventory lead times from specialized dehumidifier manufacturers in the United States, Germany, and Japan create surge-capacity bottlenecks during hurricane and spring thaw seasons. Equipment sourcing draws from refrigerant compressor suppliers in China and desiccant media producers in the United States. Single-source vulnerability concentrates at thermal imaging sensor foundries in Japan. Distribution runs through manufacturer-authorized dealer networks and direct procurement by national franchise operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disaster restoration incumbents face substitution pressure from in-house facilities management teams equipped with portable dehumidifiers and basic moisture detection tools, requiring defensive positioning around certification moats and technology-enabled inspection protocols.
For Market Incumbents: Secure cross-training certification pipelines across flood and fire disciplines to optimize labor deployment during disaster-type fluctuations. Anchor master service agreement renewals through thermal imaging platform investments that in-house teams cannot replicate. Vertical integration into dehumidifier leasing pools buffers equipment shortage risks during surge demand periods. For New Entrants and Emerging Players: EPA Lead Renovation, Repair and Painting Rule certification fast-tracks open procurement access in pre-1978 structure-dense metropolitan zones. Target mold remediation specialization in California commercial lease markets where liability standards tighten fastest. Pursue insurance-preferred vendor program enrollment as the primary go-to-market channel. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors thermal imaging platform operators with embedded moisture-mapping analytics over labor-heavy cleanup specialists. Five-to-ten-year viability hinges on digitization differentiation rather than equipment scale alone. Monitor federal flood risk map revision schedules as the signal indicating capital rotation toward resilient retrofits versus reactive restoration.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Training Certification Investment | OSHA-compliant technician versatility optimizes labor deployment across disaster-type demand fluctuations. |
| Thermal Imaging Platform Acquisition | Moisture-mapping analytics differentiate inspection services from commoditized cleanup competitors. |
| Master Service Agreement Consolidation | Commercial real estate portfolio contracts anchor recurring revenue against spot-market volatility. |
| Dehumidifier Leasing Pool Expansion | Pre-positioned equipment inventory guarantees response time commitments for insurance-preferred programs. |
| Mold Remediation Specialization | Commercial lease liability standards in California and Texas command premium pricing power. |
Research Methodology
Initial hypotheses were tested against primary input from restoration operations directors, insurance claims managers, commercial property portfolio directors, and industrial hygienist consultants and refined through secondary validation against OSHA enforcement data, EPA guideline publications, state contractor licensing board records, and equipment manufacturer shipment disclosures. Bottom-up service segmentation sizing triangulated against top-down macroeconomic indicators.
Variance decomposition across service type, end user tier, solution complexity, and technology adoption intensity shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate distributions weighted by revenue exposure. Forecast inputs incorporated climate volatility indices, federal flood risk map revision schedules, and commercial real estate transaction velocity.
Decision-makers should treat outputs as directional under assumptions of sustained climate-driven weather volatility and stable insurance rate structures; material deviation in federal disaster assistance policy or equipment supply chain configuration would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
Incident and Emergency Management Market
Emergency and Disaster Management
EHS Market
Emergency and Disaster Management
Crisis Emergency and Incident Management Platform Market
Emergency and Disaster Management
Emergency Shower and Eyewash Station Market
Emergency and Disaster Management
Cyber Crisis Management Market
Emergency and Disaster Management
Survival Tools Market
Emergency and Disaster Management
Intelligent Evacuation System Market
Emergency and Disaster Management
Global Emergency Medical Service (EMS) Products Market
Emergency and Disaster Management
Advanced Disaster Management Simulator Market
Emergency and Disaster Management
Emergency Shutdown System Market
Emergency and Disaster Management
Emergency Lighting Market
Emergency and Disaster Management
Asia-Pacific Process Safety Services Market
Emergency and Disaster Management
Free Fall Lifeboats Market
Emergency and Disaster Management
Earthquake Early Warning System Market
Emergency and Disaster Management
North America Emergency Shower and Eye Wash Station Market
Emergency and Disaster Management
Homeland Security and Emergency Management Market