

Emergency Vent Cover Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Vent Cover Market Insights
Capital-intensity divergence between integrated metal-forming operations and assembly-only competitors is unwinding competitive stability in the emergency vent cover supply base. Honeywell International leverages captive manufacturing of aluminum alloy vent assemblies to sustain price discipline across North American industrial accounts. Pentair competes through specialized marine-grade coating capabilities that extend product lifespans in corrosive chemical environments. Emerson Electric anchors its position via integrated sensing technology that differentiates its covers in automated facility monitoring systems.
An emergency vent cover is a mechanically actuated or passive pressure-relief device, typically fabricated from aluminum alloy or silicone rubber composite materials, designed to open at calibrated differential pressures between 0.5 and 5 psi to protect tanks, vessels, and ductwork from structural failure during thermal expansion or combustion events. Its primary industrial purpose is to prevent catastrophic rupture while maintaining environmental containment under normal operating conditions. Rigid covers fabricated from aluminum alloy dominate installed base value due to their durability in petrochemical settings, while flexible covers manufactured from silicone rubber represent the fastest-expanding segment as food processing and pharmaceutical facilities prioritize cleanability and chemical resistance. The application split reveals fire protection as the mature revenue pool with established specification channels, whereas environmental safety applications are capturing expanding margin pools driven by tightened emissions containment requirements.
NFPA standards governing emergency venting of flammable liquid storage tanks shape product design mandates across US industrial facilities, while OSHA process safety management regulations enforce inspection intervals that sustain replacement demand. EPA risk management program requirements for chemical accident prevention further tighten material specification and documentation burdens for cover suppliers serving hazardous chemical handlers. Stakeholders must monitor evolving state-level amendments to building codes and process safety rules, as these local overlays increasingly dictate whether rigid metal or flexible polymer designs qualify for specific installation categories.
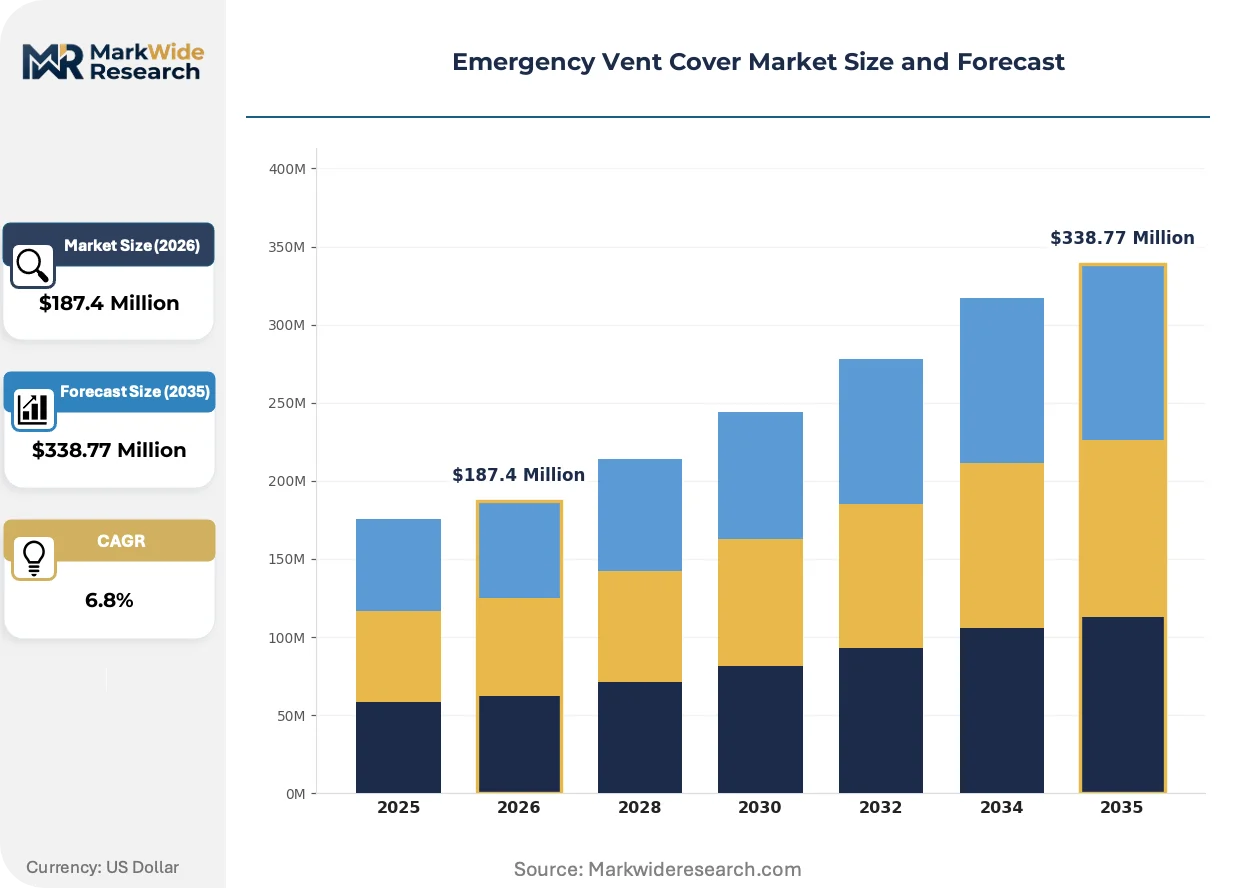
Market Dynamics
Capital-intensity divergence between integrated metal-forming operations and assembly-only competitors is unwinding competitive stability in the emergency vent cover supply base. Honeywell International leverages captive manufacturing of aluminum alloy vent assemblies to sustain price discipline across North American industrial accounts.
Growth Catalysts
- NFPA 30 compliance mandates:US petrochemical storage facilities must install engineered emergency venting systems for flammable liquid tanks above specific capacity thresholds, sustaining replacement demand cycles.
- Silicone rubber composites:Food processing and pharmaceutical facilities prioritize cleanable flexible covers that withstand aggressive sanitization protocols without material degradation.
- OSHA PSM inspection intervals:Mandatory process safety management audits enforce documented vent cover condition assessments, creating recurring revenue pools for certified inspection services.
Market Restraints
- Aluminum alloy price volatility:Raw material input costs for rigid cover fabrication fluctuate with London Metal Exchange pricing, compressing margins for non-integrated assemblers.
- Specialized coating supply concentration:Marine-grade corrosion protection chemistries concentrate among limited chemical suppliers serving Gulf Coast petrochemical clusters.
- EPA RMP documentation burdens:Risk management program record-keeping requirements extend sales cycles for hazardous chemical handlers seeking qualified vent cover vendors.
Strategic Opportunities
- Underpenetrated pharmaceutical bioprocessing:Single-use facility construction in Ireland and Singapore creates demand for flexible silicone covers compatible with cleanroom protocols.
- Integrated sensing convergence:Pressure transducer and IoT telemetry integration enables predictive maintenance contracts for automated tank farm operators.
- EU Green Deal emissions containment:Tightened volatile organic compound release standards position emergency vent covers as dual-purpose environmental safety devices.
Industry Challenges
- Certified welding technician scarcity:Aluminum alloy cover fabrication requires ASME-qualified pressure vessel welders, with training pipelines failing to match Gulf Coast industrial expansion.
- Legacy tank retrofit integration:Pre-1990 storage vessels lack standardized mounting interfaces, forcing custom engineering for each emergency vent cover installation.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Vent Cover Market Trends and Innovations
Material science advances and regulatory digitization are restructuring how emergency vent covers are specified, procured, and maintained across hazardous material handling industries.
Smart vent cover technology embedding differential pressure sensors and wireless telemetry is bifurcating the installed base between passive mechanical devices and connected predictive systems. Automated tank farm operators in Texas and Louisiana are specifying sensor-integrated covers for real-time structural integrity monitoring. This capability split is compressing margins for pure hardware suppliers while expanding service revenue pools for integrated solution vendors.
EPA's proposed revisions to risk management program digital reporting requirements will mandate electronic submission of vent cover inspection records and pressure-test documentation. Chemical facility operators must upgrade data management infrastructure to maintain compliance eligibility. Small and mid-sized handlers lacking enterprise resource planning integration face the steepest adaptation costs.
Buyer consolidation among integrated oil companies has compressed vendor qualification timelines while extending contract durations. Procurement teams now demand ten-year total cost of ownership models replacing upfront capital expenditure comparisons. This analytical shift favors suppliers with documented field performance data and predictive maintenance capabilities over lowest-bid offerings.
Emergency Vent Cover Market Segmentation
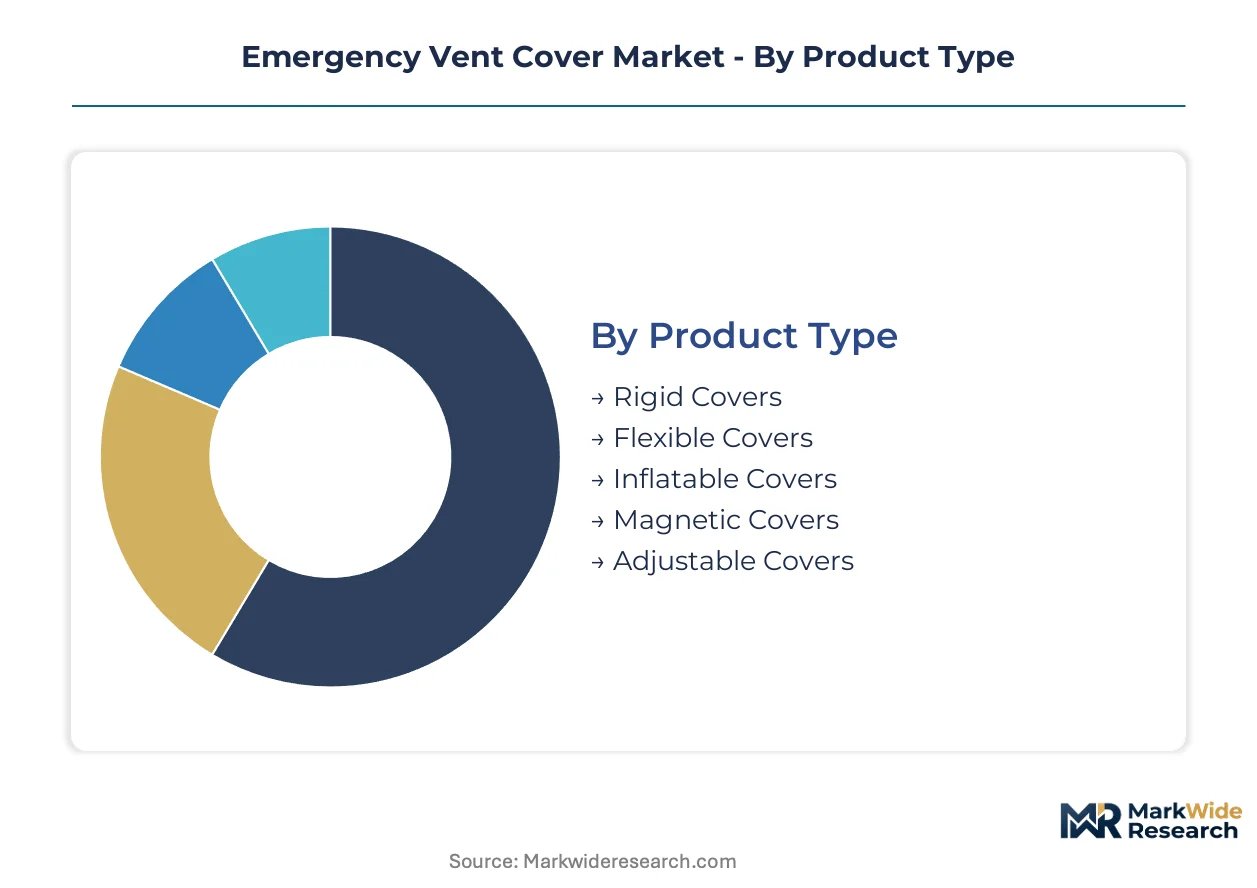
Emergency vent cover procurement patterns diverge sharply across installation contexts, with material specifications and actuation mechanisms driving qualification requirements. Understanding segment-level margin distribution enables suppliers to align R&D investment with regulatory enforcement intensity.
Product Type:
Margin pools concentrate in rigid metal-forming operations where ASME certification barriers limit competitive entry, while flexible polymer segments reward coating chemistry specialization.
- Rigid Covers:Fabricated from aluminum alloy or steel plate with calibrated hinge mechanisms designed to release at 0.5–5 psi differential pressure. Petrochemical tank farms in Texas and Louisiana specify these for NFPA 30 compliance on flammable liquid storage above 1,200 gallons.
- Flexible Covers:Manufactured from silicone rubber or neoprene composites with fabric reinforcement layers. Pharmaceutical cleanrooms in Ireland and Singapore prioritize these for cleanability under aggressive sanitization protocols without particle shedding.
- Inflatable Covers:Deploy gas-actuated bladder systems for oversized ductwork applications in mining ventilation.
- Magnetic Covers:Utilize rare-earth magnet arrays for rapid-deployment temporary installations in construction site dust containment.
- Adjustable Covers:Feature modular pressure calibration for facilities handling multiple chemical classes with varying vapor pressure profiles.
Rigid covers hold installed capacity. Flexible covers are rotating up the share rankings.
Application:
Volume concentrates in fire protection specifications with established engineering channels, while environmental safety applications capture expanding margins from tightened emissions containment mandates.
- Fire Protection:Mandated by NFPA 30 for flammable liquid storage tanks and by OSHA PSM for process vessels handling reactive chemicals. US Gulf Coast refineries drive replacement cycles through mandated inspection intervals.
- Environmental Safety:EPA Risk Management Program requirements position vent covers as dual-purpose devices preventing catastrophic release. EU Green Deal VOC standards are accelerating specification in German and Dutch chemical clusters.
- Dust Prevention:Agricultural grain elevators and woodworking facilities deploy covers to prevent combustible dust accumulation in ductwork.
- Pest Control:Food processing plants integrate vent covers with mesh screening to exclude rodents and insects from ventilation systems.
- Security Enhancement:Critical infrastructure facilities specify tamper-evident vent covers for air intake protection against deliberate contamination.
Fire protection commands specification authority. Environmental safety is climbing the fastest.
End User:
Customer concentration patterns reflect regulatory inspection intensity, with industrial facilities sustaining premium pricing for documented compliance records.
- Industrial Facilities:Oil and gas storage terminals, chemical processing plants, and refineries constitute the core revenue base. OSHA PSM and EPA RMP enforcement in the United States sustains recurring inspection and replacement demand.
- Commercial Buildings:High-rise HVAC systems and data center cooling infrastructure specify emergency venting for thermal expansion protection.
- Public Infrastructure:Wastewater treatment plants and transit tunnel ventilation systems deploy corrosion-resistant covers in aggressive humidity environments.
- Healthcare Centers:Hospital isolation wards and pharmaceutical manufacturing require covers compatible with biological containment protocols.
- Educational Institutions:University research laboratories handling hazardous chemicals specify vent covers under institutional risk management policies.
Industrial facilities anchor procurement volume. Healthcare centers are gaining share fastest.
Material:
Cost tier stratification separates commodity polymer supply from certified alloy fabrication with pressure vessel documentation.
- Aluminum Alloy:ASME-qualified weldments with marine-grade anodized finishes dominate petrochemical specifications. Honeywell International and integrated metal-formers control supply through captive foundry operations.
- Silicone Rubber:Platinum-cured formulations withstand repeated steam sterilization cycles. Food and pharmaceutical facilities in Singapore and Ireland specify these for cleanroom compatibility.
- Steel:Carbon and stainless grades serve heavy industrial applications with structural load requirements exceeding aluminum capacity.
- Neoprene:Chloroprene-based compounds offer intermediate chemical resistance for wastewater and marine environments.
- Plastic Polymer:Polypropylene and PVC formulations serve cost-sensitive temporary installations with limited thermal exposure.
Aluminum alloy dominates specification authority. Silicone rubber is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the Netherlands exhibit the least price sensitivity due to stringent EU Green Deal enforcement, while procurement teams in India and Southeast Asia prioritize cost efficiency over premium certification tiers.
United States
Gulf Coast petrochemical clusters in Texas and Louisiana drive specification volume for NFPA 30-compliant aluminum alloy covers. OSHA process safety management rules mandate documented inspection intervals that sustain replacement demand cycles. Houston-area refineries anchor procurement authority for rigid metal-forming products.
Germany
Chemical processing facilities in the Rhine-Ruhr industrial belt prioritize dual-purpose vent covers satisfying both fire protection and VOC emissions containment. EU Green Deal standards tighten volatile organic compound release thresholds beyond legacy national requirements. BASF-Ludwigshafen and Bayer-Leverkusen complexes set specification benchmarks for neighboring Dutch and Belgian handlers.
Singapore
Pharmaceutical bioprocessing construction creates demand for platinum-cured silicone rubber covers compatible with cleanroom sanitization protocols. The country's national pharmaceutical regulator enforces documentation burdens matching FDA-level stringency for sterile manufacturing environments. Tuas Biomedical Park and one-north research clusters concentrate facility investment.
India
Petrochemical storage terminal expansion along the Gujarat coastline generates volume demand for cost-optimized rigid covers. BIS pressure vessel standards create certification barriers that favor domestic metal-formers with captive foundry operations. Reliance Industries' Jamnagar complex and Mundra Port chemical handlers anchor regional procurement.
Netherlands
Rotterdam-Antwerp chemical corridor facilities specify marine-grade coated covers for salt-air corrosion resistance in North Sea environments. REACH compliance documentation requirements extend vendor qualification timelines for hazardous chemical handlers. Shell-Pernis and Dow-Terneuzen installations drive premium-tier demand for integrated sensing capabilities.
Emergency Vent Cover Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the emergency vent cover supply base. Honeywell International and Emerson Electric anchor the upper tier through captive manufacturing of aluminum alloy assemblies and integrated sensing technology respectively. The middle tier fragments across regional metal-formers and coating specialists serving corrosive environment niches. Two competitive moves dominate: backward integration into aluminum foundry operations to offset London Metal Exchange price volatility, and technology licensing partnerships for IoT-enabled predictive maintenance capabilities.
Among North American industrial conglomerates, Honeywell International and Emerson Electric exemplify the integrated-leader archetype through diversified safety systems portfolios. Pentair occupies a position within the specialized-coating tier, representing marine-grade corrosion protection capabilities. Fike and Protectoseal sit within the dedicated pressure-relief device specialist tier, anchoring pure-play positioning against diversified competitors. Groth Corporation exemplifies the regional metal-former archetype with concentrated Gulf Coast petrochemical relationships.
| Leading Market Players |
|---|
| 3M |
| Honeywell International |
| Emerson Electric |
| Pentair |
| Fike |
| Protectoseal |
| Groth Corporation |
| Air System Components |
| Schneider Electric |
| Others |
Pricing and Supply Chain Analysis
ASME pressure vessel certification gates both supplier qualification and price tiering simultaneously, forcing non-certified metal-formers into commodity assembly margins while integrated foundry operators capture premium positioning through documented weld integrity. Buyers in the United States Gulf Coast petrochemical corridor demand ten-year total cost of ownership models that bundle hardware, inspection services, and predictive maintenance contracts into unified pricing structures.
Pricing Analysis
After-sales service revenue from certified inspection contracts and pressure-test documentation drives lifetime value capture beyond initial hardware sales. Three-tier pricing structure across premium, standard, and economy levels separates ASME-qualified aluminum alloy fabricators with captive foundry operations from assembly-only competitors sourcing commodity hinge mechanisms. Price differentiation rests on certification grade and geographic delivery cost to Gulf Coast versus Midwest industrial clusters. Cost compression in the standard tier is intensifying because London Metal Exchange aluminum price volatility squeezes non-integrated assemblers. Procurement teams at integrated oil companies exhibit least price sensitivity due to mandated NFPA 30 compliance documentation burdens, while agricultural grain elevator operators in the Midwest demonstrate highest sensitivity.
Supply Chain Analysis
Strait of Hormuz transit underwrites marine-grade anodizing chemistry supply for corrosion-resistant coatings serving North Sea and Gulf Coast petrochemical installations. Manufacturing concentrates in the United States, Germany, and China, with aluminum alloy raw material sourcing anchored in domestic foundry operations or London Metal Exchange contract positions. Component dependencies include platinum-cured silicone rubber formulations, rare-earth magnet arrays for temporary deployment covers, and specialized marine-grade coating chemistries. Single-source vulnerability concentrates in Gulf Coast chemical suppliers serving corrosion protection specifications for salt-air environments. Distribution runs through industrial safety distributors and direct OEM procurement channels serving tank farm operators and refinery maintenance departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent suppliers face substitution pressure from integrated sensing technology vendors embedding differential pressure transducers and IoT telemetry into vent cover assemblies, compressing margins for pure hardware manufacturers.
For Market Incumbents: Shield core aluminum alloy fabrication revenue by deepening backward integration into captive foundry operations to offset London Metal Exchange price volatility. Secure exclusive distribution partnerships with industrial safety distributors serving OSHA PSM-mandated inspection intervals. The priority defensive lever is technology licensing for IoT-enabled predictive maintenance capabilities that matches Emerson Electric's integrated sensing differentiation. For New Entrants and Emerging Players: Anchor in pharmaceutical bioprocessing construction in Singapore and Ireland where platinum-cured silicone rubber cover demand outpaces established supplier capacity. Target food processing facilities prioritizing cleanable flexible covers under aggressive sanitization protocols without particle shedding. The most penetrable entry angle is cleanroom-compatible coating chemistry specialization for pharmaceutical cleanroom specifications exceeding legacy petrochemical corrosion resistance requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated sensing technology sub-segments as predictive maintenance capabilities separate premium-tier vendors from commodity hardware suppliers. Long-term viability favors acquisition targets with documented ASME pressure vessel certification and established Gulf Coast petrochemical relationships. The signal to watch is EPA risk management program digital reporting mandate implementation timelines forcing facility operator data infrastructure upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Foundry Operations | Captive supply of ASME-qualified weldments insulates Honeywell International from London Metal Exchange volatility. |
| IoT Sensor Integration Partnership | Pressure transducer embedding enables predictive maintenance contracts for automated Texas and Louisiana tank farms. |
| Marine-Grade Coating Chemistry Licensing | Specialized corrosion protection extends product lifespan in Rotterdam-Antwerp chemical corridor salt-air environments. |
| Pharmaceutical Cleanroom Certification Investment | Platinum-cured silicone rubber compatibility opens Singapore Tuas Biomedical Park specification channels. |
| Long-Term Inspection Service Contracting | OSHA PSM-mandated audit intervals create recurring revenue pools beyond initial hardware sales. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers at Gulf Coast refineries, procurement leads at integrated oil companies, aftermarket service heads at industrial safety distributors, and technical R&D directors at coating chemistry suppliers. Secondary validation drew from OSHA process safety management enforcement records, EPA risk management program filings, NFPA standard revision documentation, and SEC 10-K disclosures from diversified industrial conglomerates. Bottom-up triangulation across facility-level procurement patterns and top-down validation against regulatory mandate implementation timelines anchored market sizing.
Across the projection horizon, the analytical framework modeled segmentation dimensions including material specification tier, actuation mechanism type, end-use industry vertical, and regional regulatory enforcement intensity. CAGRs were derived from facility expansion pipelines and replacement cycle analysis tied to mandated inspection intervals. Forecast inputs incorporated aluminum alloy price trajectory assumptions and pharmaceutical cleanroom construction permitting activity in Singapore and Ireland.
Material uncertainties — aluminum price volatility spikes, ASME welder training pipeline constraints, and EPA digital reporting mandate delay or acceleration — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as EU Green Deal VOC standard enforcement timelines and state-level building code amendments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.