

Emergency Backpack Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Backpack Market Insights
The capital-intensity divergence between integrated manufacturers and assembly-focused competitors is rotating competitive advantage toward firms controlling fabric development and frame production in-house. PAX Bags leverages European manufacturing depth to sustain premium positioning in rescue and tactical segments. Mystery Ranch anchors its market presence through specialized load-carrying systems designed for extended field operations. 5.11 Tactical competes across law enforcement and civilian channels by extending its brand from apparel into purpose-built emergency packs.
An emergency backpack constitutes a purpose-engineered portable containment system, typically constructed from water-resistant ballistic nylon or Cordura with reinforced stitching at stress points, designed to organize and transport medical supplies, survival equipment, or tactical gear under adverse conditions. Its primary commercial purpose centers on enabling rapid deployment of critical tools by professionals operating in unpredictable environments. Tactical backpacks currently occupy the largest product segment, reflecting sustained institutional procurement from military and law enforcement end users, while survival gear backpacks represent the fastest-expanding category as civilian preparedness culture deepens across multiple geographies. The distribution channel structure concentrates margin capture among specialized retailers and direct sales operations, with online marketplaces gaining volume share at lower per-unit profitability.
The EU PPE Regulation and CE marking framework govern product safety and market access across European jurisdictions, while OSHA standards in the United States establish workplace equipment requirements that influence institutional purchasing specifications for first responder agencies. These regulatory structures elevate compliance costs for new entrants while rewarding incumbents with certified testing infrastructure and established auditor relationships. Stakeholders must monitor evolving material standards and procurement certification timelines to preserve market position.
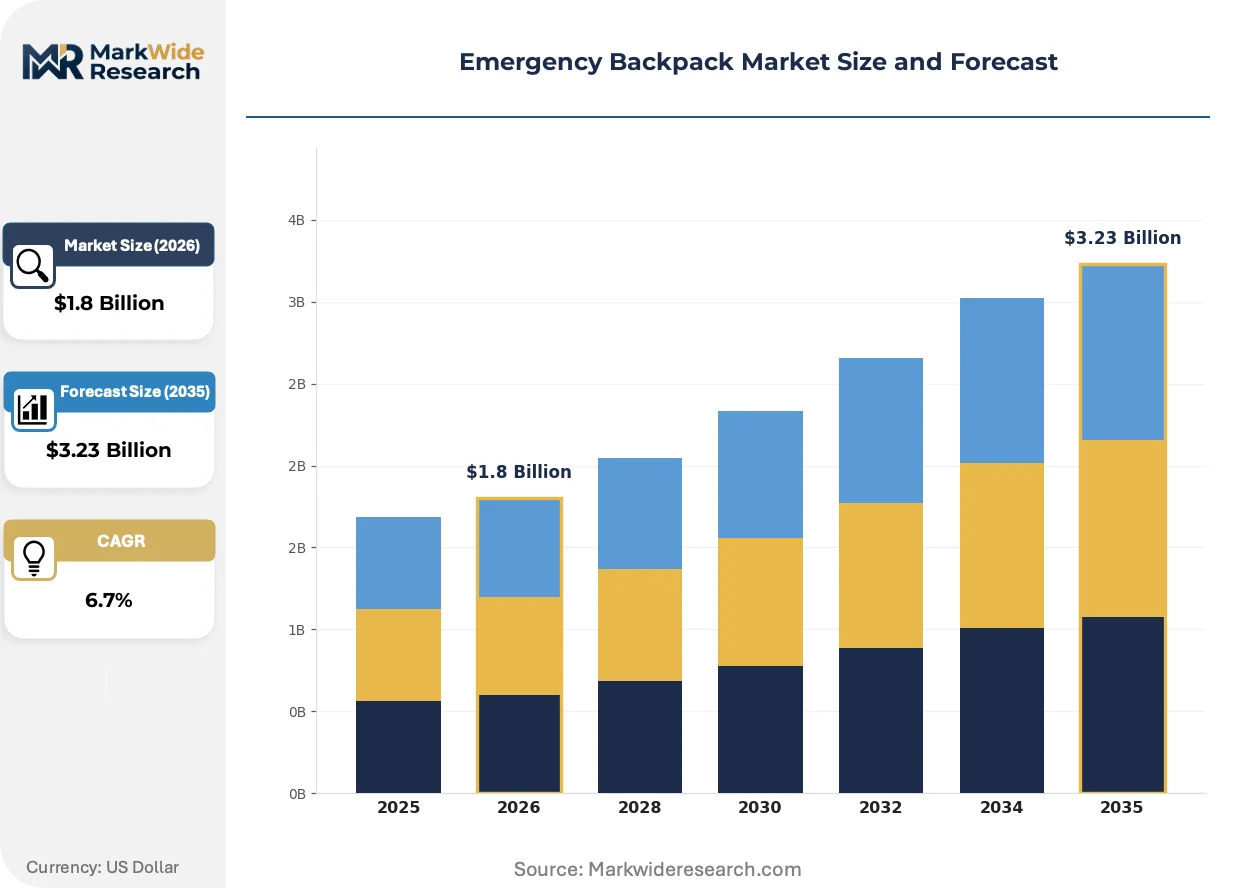
Market Dynamics
Federal disaster preparedness grants in the United States are channeling institutional investment toward modular load-bearing systems, while the EU's tightening PPE Regulation and CE marking requirements are elevating material certification barriers across European procurement channels.
Growth Catalysts
- OSHA workplace equipment standards:Institutional purchasing specifications for first responder agencies in the United States mandate certified gear, creating sustained demand pull from municipal and state emergency services.
- Ballistic nylon and Cordura advancement:Reinforced stitching technologies and water-resistant fabric treatments are extending equipment lifespan under adverse field conditions, reducing total cost of ownership for search and rescue deployments.
- German modular procurement expansion:Search and rescue teams across Germany are scaling acquisition of configurable load-bearing systems designed for rapid equipment reconfiguration between mission types.
Market Restraints
- CE marking compliance costs:The EU PPE Regulation elevates testing infrastructure requirements and auditor relationship investments, creating capital barriers for new market entrants without established certification pathways.
- Specialized polymer supply concentration:High-tenacity nylon yarn production concentrates among Asian chemical manufacturers, exposing finished goods producers to input cost volatility and geographic supply risk.
- Load distribution engineering limitations:Extended field operation requirements for tactical segments demand frame geometry optimization that exceeds current off-the-shelf suspension system capabilities.
Strategic Opportunities
- Civilian preparedness culture deepening:Survival gear backpacks represent an underpenetrated consumer segment as household emergency planning expands beyond institutional buyers into individual preparedness markets.
- Direct-to-institution sales channels:Manufacturers are bypassing specialized retail intermediaries to capture margin through direct sales operations targeting federal and state procurement offices.
- ISO 9001 quality management convergence:Integration of ISO quality standards with national PPE frameworks is creating certification harmonization opportunities for suppliers serving multiple jurisdictional markets.
Industry Challenges
- Multi-standard certification timelines:Parallel CE marking, OSHA compliance, and ISO testing requirements create extended product launch cycles that compress competitive response windows.
- Load-bearing system integration complexity:Modular component interoperability demands precision manufacturing tolerances that strain quality control systems across distributed supplier networks.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Backpack Market Trends and Innovations
Active reshaping of the emergency backpack market centers on three vectors: component miniaturization enabling payload density gains, regulatory harmonization across transatlantic safety frameworks, and procurement centralization altering channel economics.
Radio-frequency identification tagging is miniaturizing inventory tracking capabilities down to individual medical supply compartments within tactical packs. Military medical units and urban search teams are deploying these systems at accelerating rates to reduce equipment accountability time during deployment. Component miniaturization is compressing the physical footprint of embedded electronics, freeing internal volume for additional mission-critical payload.
REACH chemical registration requirements in Europe are forcing reformulation of flame-retardant fabric treatments previously standard in ballistic nylon production. Industrial consequence includes accelerated R&D investment in halogen-free alternatives among European textile suppliers. Tactical backpack segments serving cross-border institutional buyers are most affected, with manufacturers dual-certifying materials to maintain transatlantic market access.
Buying committees at municipal emergency management departments are consolidating vendor relationships to reduce procurement administrative burden, displacing fragmented multi-supplier arrangements. Specialized retailers historically capturing margin through distribution are experiencing channel compression as direct manufacturer relationships expand. This concentration is most visible across United States federal grant recipients modernizing first responder gear inventories.
Emergency Backpack Market Segmentation
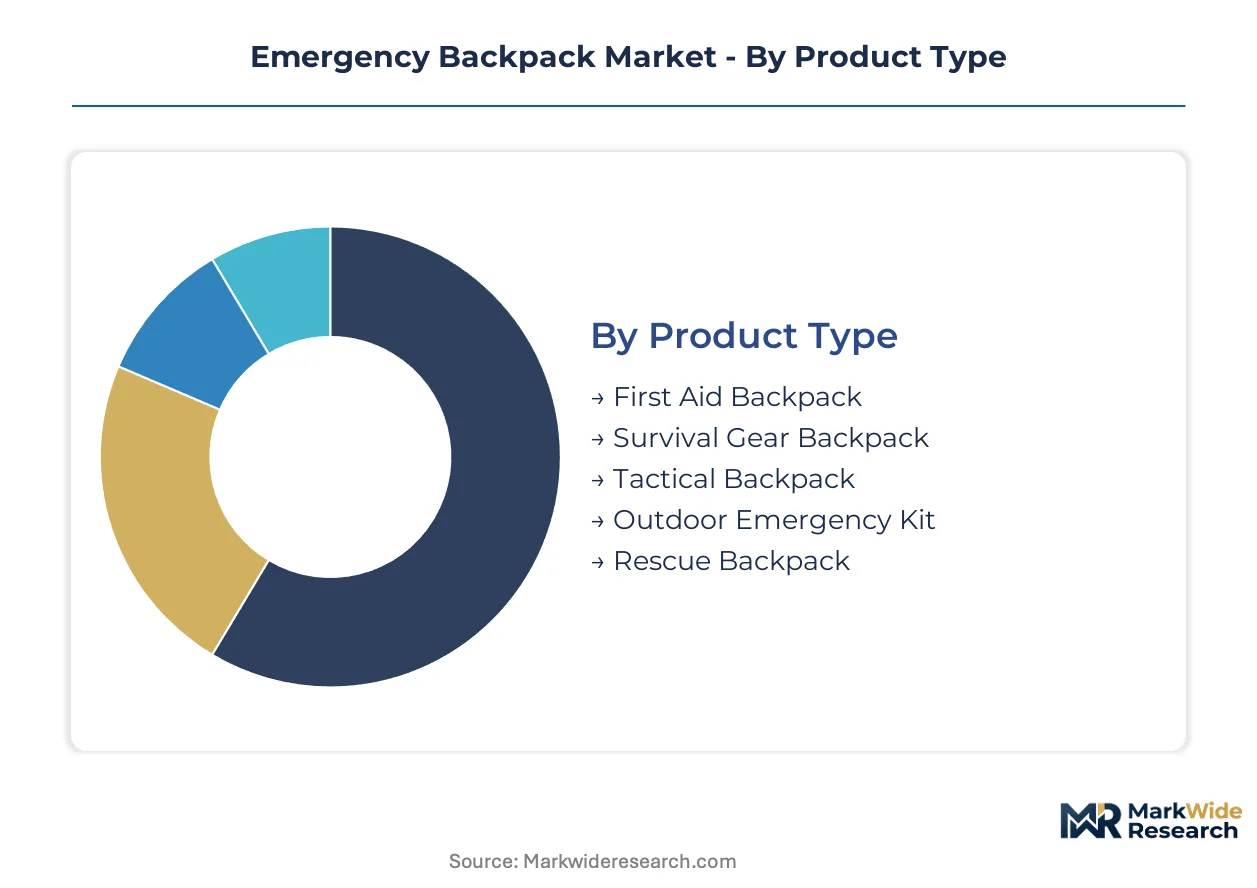
Emergency backpack segmentation reveals divergent compliance burdens and procurement pathways across institutional and civilian buyer profiles. Regulatory frameworks fragment demand characteristics, with OSHA-certified gear commanding premium positioning in United States municipal contracts while CE marking requirements reshape European material specifications.
Product Type:
CE marking and OSHA compliance create divergent certification costs across fabric treatments and frame geometries, concentrating margin capture among segments with established testing infrastructure.
- Tactical Backpack:Constructed from water-resistant ballistic nylon with reinforced stitching at stress points and modular MOLLE webbing for equipment attachment. Institutional procurement from United States military and law enforcement agencies sustains volume leadership, though REACH chemical registration requirements in Europe are forcing halogen-free flame-retardant reformulations that elevate R&D overhead for cross-border suppliers.
- Survival Gear Backpack:Purpose-engineered for civilian emergency preparedness with compartmentalized storage for multi-day sustenance and shelter systems. Household emergency planning expansion across Germany and United States suburban markets drives steepest expansion trajectory, as FEMA preparedness messaging and Bundesamt für Bevölkerungsschutz campaigns normalize individual readiness investment.
- First Aid Backpack:Medical-grade containment systems with color-coded supply organization and rapid-access trauma compartments.
- Outdoor Emergency Kit:Compact configurations targeting recreational users with integrated signaling and navigation tools.
- Rescue Backpack:Load-bearing systems optimized for urban search teams with configurable component architecture.
Established volume favors Tactical Backpack; emerging adoption favors Survival Gear Backpack.
Application:
Cost tier stratification separates capital-intensive institutional deployments from discretionary consumer purchases, with federal grant funding concentrating in high-specification mission profiles.
- Search and Rescue:Extended field operation requirements demand frame geometry optimization and load distribution engineering that exceeds off-the-shelf suspension capabilities. German modular procurement expansion across Landesfeuerwehrverbände and Berufsfeuerwehr units concentrates demand for configurable systems supporting rapid equipment reconfiguration between technical rescue and water recovery missions.
- Disaster Response:Rapid deployment protocols require standardized equipment accountability systems compatible with federal incident command structures. United States FEMA Urban Search and Rescue task forces and comparable European civil protection units drive specification convergence around RFID-enabled inventory tracking and interoperability with National Incident Management System protocols.
- Military Operations:Specialized load-carrying systems designed for combat medic roles and prolonged dismounted patrols.
- Outdoor Expeditions:Recreational demand concentrated in alpine guiding services and backcountry skiing operations.
- Emergency Evacuations:Pre-positioned kits for institutional shelter-in-place protocols and residential grab-and-go scenarios.
Institutional procurement depth favors Search and Rescue; civilian market penetration favors Disaster Response.
End User:
Customer type fragmentation separates certified professional equipment from recreational-grade alternatives, with procurement authority residing in distinct organizational hierarchies.
- Law Enforcement:Specialized tactical load-bearing systems with weapon retention integration and ballistic protection compatibility. United States Department of Justice equipment grants channel investment toward modular systems supporting SWAT, patrol, and emergency response unit reconfiguration without redundant inventory.
- Paramedics:Medical supply organization systems with oxygen tank carriage and defibrillator accommodation. European emergency medical services standardization through EN 1789 and comparable national frameworks creates certification harmonization opportunities for suppliers serving multiple jurisdictional markets.
- Firefighters:Heat-resistant material specifications and SCBA compatibility requirements for structural and wildland roles.
- Search Teams:Configurable architecture supporting technical rescue, confined space, and wilderness search specializations.
- Outdoor Enthusiasts:Price-sensitive demand with performance expectations shaped by recreational rather than mission-critical reliability standards.
Procurement scale favors Law Enforcement; specification complexity favors Paramedics.
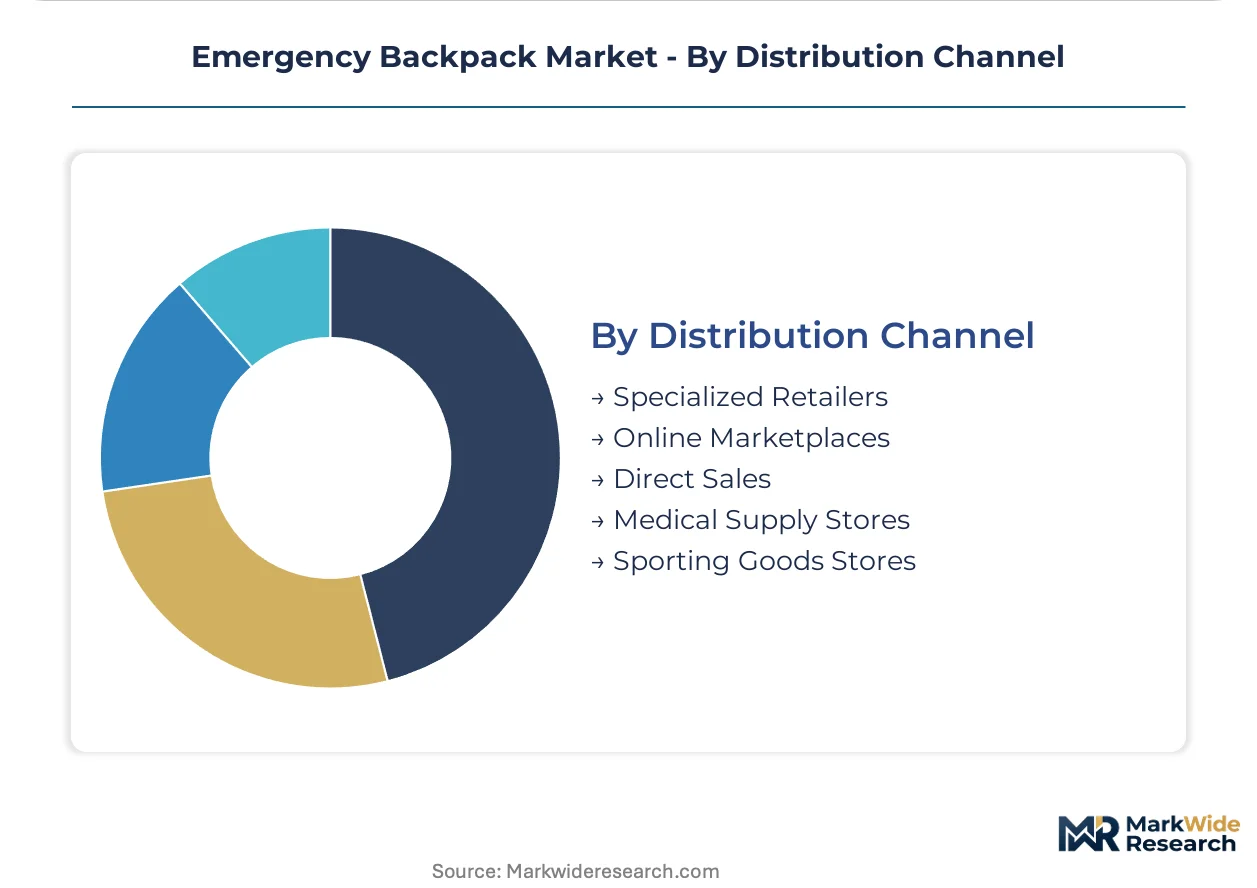
Distribution Channel:
Margin concentration shifts as buying committees consolidate vendor relationships and manufacturers bypass traditional intermediaries.
- Direct Sales:Manufacturer relationships with federal and state procurement offices capture margin historically absorbed by specialized retail intermediaries. United States municipal emergency management department consolidation of vendor relationships accelerates this displacement, particularly among federal grant recipients modernizing first responder gear inventories.
- Online Marketplaces:Volume expansion at compressed per-unit profitability as price transparency intensifies competitive pressure. Consumer preparedness culture deepening across multiple geographies drives traffic, though conversion concentrates in lower-specification survival gear segments rather than certified professional equipment.
- Specialized Retailers:Technical consultation and fitting services sustaining relevance in professional segments despite channel compression.
- Medical Supply Stores:Institutional purchasing specifications and GSA schedule alignment for healthcare-adjacent emergency services.
- Sporting Goods Stores:Recreational outdoor emergency kit distribution with seasonal demand fluctuation.
Margin preservation favors Direct Sales; volume expansion favors Online Marketplaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in German manufacturing clusters while cost-competitive sourcing dominates Asian supply corridors. United States federal procurement channels sustain volume leadership through disaster preparedness grant flows. Regulatory divergence between CE marking and OSHA frameworks fragments certification pathways across transatlantic markets.
United States
FEMA Urban Search and Rescue task forces and municipal emergency management departments drive institutional procurement of modular load-bearing systems. OSHA workplace equipment standards mandate certified gear specifications for first responder agencies, creating compliance pull-through from federal grant recipients. California and Texas metropolitan clusters concentrate vendor relationships as buying committees consolidate procurement administrative functions.
Germany
Landesfeuerwehrverbände and Berufsfeuerwehr units scale acquisition of configurable systems for technical rescue and water recovery missions. EU PPE Regulation and CE marking requirements elevate material certification barriers for ballistic nylon and Cordura treatments. Bavaria and North Rhine-Westphalia host specialized textile suppliers reformulating halogen-free flame-retardant alternatives under REACH chemical registration pressure.
China
High-tenacity nylon yarn production concentrates among chemical manufacturers serving finished goods producers with input cost exposure. GB standards and MIIT industrial policy frameworks shape domestic equipment specifications for emergency services modernization. Yangtze River Delta manufacturing clusters supply fabric components to European and North American assembly operations.
United Kingdom
London and Southeast England emergency services standardize procurement around EN 1789-aligned medical containment systems for paramedic deployment. National Health Service equipment frameworks create certification harmonization opportunities for suppliers serving adjacent European markets. Midlands industrial corridors sustain specialized stitching and reinforcement manufacturing for tactical pack stress-point engineering.
Australia
Urban search teams and rural fire services generate demand for extended field operation load-bearing systems compatible with Commonwealth disaster response protocols. TGA and state-level emergency management specifications influence institutional purchasing criteria for wilderness search and alpine rescue deployments. New South Wales and Victoria concentrate procurement authority through centralized state emergency service headquarters.
Emergency Backpack Market Competitive Landscape
Concentration sits with integrated manufacturers controlling in-house fabric development and frame production against assembly-focused competitors dependent on distributed supplier networks. The vendor base stratifies across three tiers: European heritage specialists commanding premium positioning through manufacturing depth, transatlantic brands leveraging law enforcement channel relationships, and volume-oriented fabricators competing on cost efficiency. Strategic moves center on direct-to-institution sales channel expansion and modular component interoperability certification.
Within the European heritage tier, PAX Bags and Savotta exemplify manufacturing-anchored positioning sustained through rescue and tactical segment specialization. Mystery Ranch occupies a position exemplifying extended field operation engineering focus. 5.11 Tactical represents the law enforcement-civilian channel bridge archetype, extending brand presence from apparel into purpose-built emergency packs through institutional relationship leverage.
| Leading Market Players |
|---|
| PAX Bags |
| 5.11 Tactical |
| Mystery Ranch |
| Blackhawk |
| Vanquest |
| Direct Action |
| First Tactical |
| Condor Outdoor |
| Savotta |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Asian high-tenacity nylon yarn producers shapes both supply concentration and price floors for finished emergency backpack manufacturers, with German and United States assembly operations absorbing margin compression from upstream chemical feedstock volatility while CE marking and OSHA compliance costs establish certification-grade price minimums.
Pricing Analysis
Configured-to-order pricing for modular load-bearing systems commands substantial premiums over standard tactical backpack configurations, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and customization depth. Price differentiation centers on ISO 9001 quality management integration and CE marking tier, with brand premium and after-sales service bundling widening spreads. Pricing pressure stems from online marketplace volume expansion compressing per-unit profitability in survival gear segments. Civilian preparedness buyers exhibit highest price sensitivity, while United States federal grant recipients and German Landesfeuerwehrverbände demonstrate lowest sensitivity due to mission-critical procurement mandates.
Supply Chain Analysis
Strategic stockpile preferences dominate institutional procurement channels, with FEMA Urban Search and Rescue task forces and European civil protection units maintaining buffer inventories against deployment unpredictability. High-tenacity nylon yarn production concentrates in China, with Yangtze River Delta chemical manufacturers feeding fabric treatment operations in Vietnam and Bangladesh. Ballistic nylon, Cordura, and halogen-free flame-retardant formulations constitute critical input dependencies. Single-source vulnerability from Asian polymer supply concentration exposes finished goods producers to geographic disruption risk. Distribution runs through direct sales channels capturing margin from federal and state procurement offices alongside specialized retailers sustaining technical consultation relevance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Emergency backpack procurement is shifting toward platform economics as modular component interoperability and RFID-enabled inventory tracking create ecosystem lock-in effects, with ISO 9001 convergence and EN 1789 standardization rewarding suppliers achieving cross-jurisdictional certification harmonization.
For Market Incumbents: Secure certification infrastructure advantages by deepening captive supply of frame geometry engineering and fabric treatment capabilities, insulating against REACH chemical registration volatility and emerging assembly-focused competitors from Asian manufacturing clusters. Channel control through direct-to-institution relationships with United States municipal emergency management departments and German Berufsfeuerwehr procurement offices preserves margin capture against online marketplace compression. For New Entrants and Emerging Players: Differentiate on civilian preparedness segment specialization, targeting survival gear backpack white space in United States suburban markets and German household emergency planning initiatives where institutional procurement relationships remain unformed. Direct-to-consumer digital-native positioning with FEMA and Bundesamt für Bevölkerungsschutz messaging alignment offers lowest barrier go-to-market entry. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated manufacturers with in-house fabric development and frame production capabilities over assembly-dependent competitors. Five-to-ten year viability hinges on regulatory harmonization execution across CE marking and OSHA frameworks. Watch for CE marking and ISO 9001 dual-certification completion rates as inflection indicator for transatlantic market access scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Component Interoperability Certification | EN 1789 and ISO 9001 convergence enables single-SKU deployment across German and United States institutional buyers. |
| Halogen-Free Flame-Retardant Reformulation | REACH chemical registration compliance preserves European market access for ballistic nylon-dependent product lines. |
| RFID Inventory Tracking Integration | FEMA Urban Search and Rescue task force specification alignment creates federal procurement preference. |
| Direct-to-Institution Sales Channel Expansion | Bypassing specialized retail intermediaries captures margin from consolidated municipal buying committees. |
| Strategic Polymer Supply Agreement | Yangtze River Delta yarn sourcing contracts mitigate input cost volatility from high-tenacity nylon concentration. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory documentation anchors the qualitative findings, with tactical load-bearing system procurement officers, German Landesfeuerwehrverbände equipment managers, United States municipal emergency management directors, paramedic service chiefs, and specialized retailer category buyers constituting the stakeholder interview base. Secondary sources encompass OSHA equipment standard filings, EU PPE Regulation guidance documents, CE marking technical dossiers, FEMA Urban Search and Rescue equipment specifications, and customs trade data for high-tenacity nylon yarn flows. Bottom-up segment sizing triangulates against top-down grant funding allocation analysis.
Sensitivity analysis across demand scenarios tests forecast robustness, with segmentation dimensions encompassing product type, application mission profile, end-user procurement authority, and distribution channel structure modeled throughout the projection horizon. CAGRs derive from grant funding trajectory analysis, institutional replacement cycle timing, and civilian preparedness culture penetration rates. Ballistic nylon and Cordura input cost indices, REACH chemical registration timeline assumptions, and modular procurement adoption curves constitute industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained federal disaster preparedness grant flows and stable CE marking compliance timelines would require recalibration. Forecasts reflect documented assumptions regarding German modular procurement expansion velocity and United States institutional buying committee consolidation patterns. Revision becomes warranted when REACH chemical registration enforcement intensity or high-tenacity nylon supply concentration crosses threshold disruption levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.