
 Free Fall Lifeboats Market | 2026-2036
Free Fall Lifeboats Market Size, Share, and Industry Trends Forecast 2026-2036
Free Fall Lifeboats Market Analytics
Buyer concentration among integrated offshore operators is recalibrating procurement patterns across the free fall lifeboat supply base. VIKING leverages its Nordic manufacturing footprint to sustain long-term service contracts with North Sea platform owners. Hatecke GmbH anchors its position through specialized engineering for extreme-temperature deployments in Arctic waters. Fr. Fassmer GmbH & Co. KG differentiates via integrated rescue vessel systems that combine free fall launch with fast-recovery capabilities.
Free fall lifeboats are self-propelled survival craft engineered for gravity-assisted launch from elevated platforms, typically constructed of fire-retardant glass-reinforced polyester or aluminum alloy hulls rated for impact velocities exceeding five meters per second at water entry. Their primary purpose is to evacuate personnel from offshore installations where conventional davit systems cannot operate within required timeframes due to platform height or sea state conditions. Fully-enclosed variants dominate value generation because they command premium pricing tied to thermal protection and self-righting specifications demanded in harsh-environment contracts. The Oil & Gas end user segment leads volume absorption, while Fast-Rescue product types represent the fastest-growing margin pool as operators integrate secondary recovery functions into primary evacuation assets.
The International Maritime Organization's SOLAS Convention, the American Bureau of Shipping classification rules, and ISO 21867 standards collectively define structural integrity, launch performance, and maintenance protocols that manufacturers must satisfy for market access. ABS type-approval processes in particular shape competitive positioning by requiring full-scale drop testing that smaller fabricators cannot readily fund. Stakeholders must monitor how proposed amendments to the IMO LSA Code affect minimum freeboard requirements and whether classification societies harmonize testing regimes or fragment compliance costs further.
Market Dynamics
Platform decommissioning timelines across the North Sea and West Africa are compressing replacement cycles for free fall lifeboats, forcing manufacturers to absorb surge capacity demands while maintaining ABS type-approval compliance for each hull configuration.
Growth Catalysts
- SOLAS LSA Code amendments:The International Maritime Organization's updated evacuation timeframes are mandating conversions from open davit-launched systems to free fall configurations on aging offshore installations.
- Arctic exploration expansion:Extreme-temperature engineering requirements for Barents Sea developments are pulling specialized hull insulation and thermal protection specifications into standard procurement packages.
- Fleet standardization:Integrated offshore operators are consolidating supplier relationships to reduce maintenance protocol fragmentation across multi-platform portfolios.
Market Restraints
- Fire-retardant resin volatility:Glass-reinforced polyester feedstock costs fluctuate with petrochemical pricing, compressing margin predictability for hull fabricators.
- Testing infrastructure concentration:Full-scale drop certification facilities cluster in Norway and Germany, creating geographic bottlenecks for new market entrants.
- Aluminum alloy substitution limits:Weight-to-buoyancy ratios in aluminum hulls restrict deployment on platforms exceeding 30-meter launch heights.
Strategic Opportunities
- Floating offshore wind integration:Turbine installation vessels are adopting free fall lifeboats for crew transfer operations in the North Sea.
- Fast-Rescue function bundling:Secondary recovery capabilities merged with primary evacuation assets command premium positioning in Norwegian contract tenders.
- Digital twin maintenance:Predictive hull integrity monitoring is opening recurring revenue streams beyond initial equipment sales.
Industry Challenges
- Certification timeline compression:ABS full-scale testing queues extend 14-18 months, delaying platform commissioning schedules.
- Welding specialist scarcity:Fire-retardant GRP lamination technicians and aluminum hull welders face cross-industry competition from aerospace and automotive sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Free Fall Lifeboats Market |
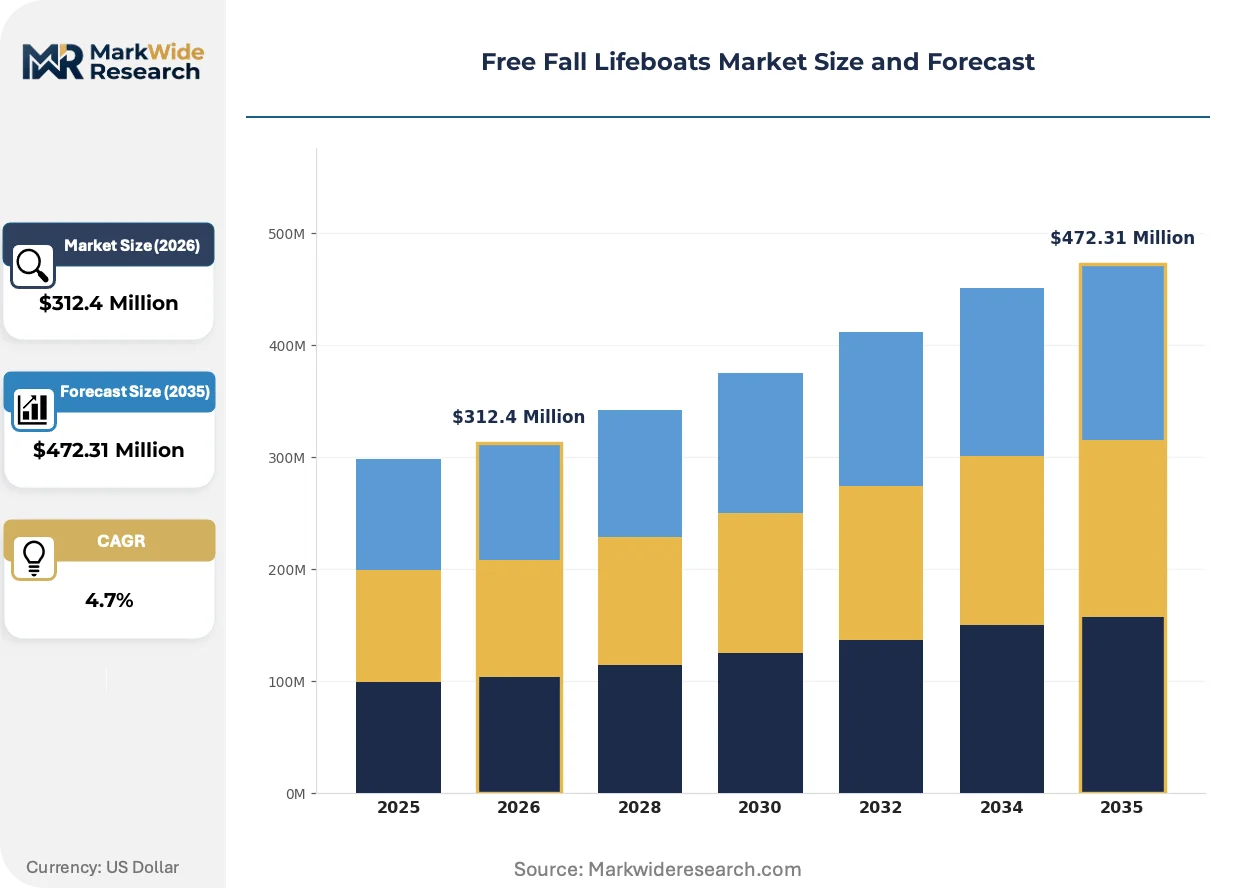
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Fully-Enclosed, Open, Fast-Rescue End User: Oil & Gas, Maritime, Shipping, Fishing Deployment Type: Surface Vessels, Submersible, Offshore Platforms, Research Vessels Compliance Standard: ISO, SOLAS, ABS, BV |
| Companies Covered | VIKING, Hatecke GmbH, Survival Systems International, Inc., Fr. Fassmer GmbH & Co. KG, Palfinger Marine, DSB Engineering CO. Ltd, Jiangsu Jiaoyan Marine Equipment Co.,Ltd, Qingdao Beihai Shipbuilding Heavy Industry Co.,Ltd, Vanguard Composite Engineering PTE LTD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Free Fall Lifeboats Market Evolving Landscape
Material science advances and regulatory harmonization pressures are restructuring how free fall lifeboats are engineered, certified, and procured across offshore energy markets.
Fire-retardant glass-reinforced polyester is consolidating its position as the dominant hull material for harsh-environment deployments. North Sea platform operators specify GRP for thermal protection and impact resistance at water entry velocities exceeding five meters per second. This material shift is compressing aluminum alloy market share to specialized high-temperature Arctic applications.
REACH chemical registration requirements in Europe are restricting legacy flame-retardant additives in GRP resin formulations. Manufacturers reformulate hull laminates to maintain IMO fire-performance ratings while eliminating restricted halogenated compounds. Norwegian fabricators lead this transition, leveraging proximity to ECHA regulatory intelligence and testing infrastructure.
Long-term service contracts are displacing transactional equipment sales in North Sea procurement. Integrated operators bundle lifeboat supply with fifteen-year maintenance and recertification obligations, locking in supplier relationships and transferring obsolescence risk to manufacturers. This model concentrates most visibly in Norway's mature offshore cluster, where aging infrastructure mandates systematic renewal programs.
Free Fall Lifeboats Market Segmentation
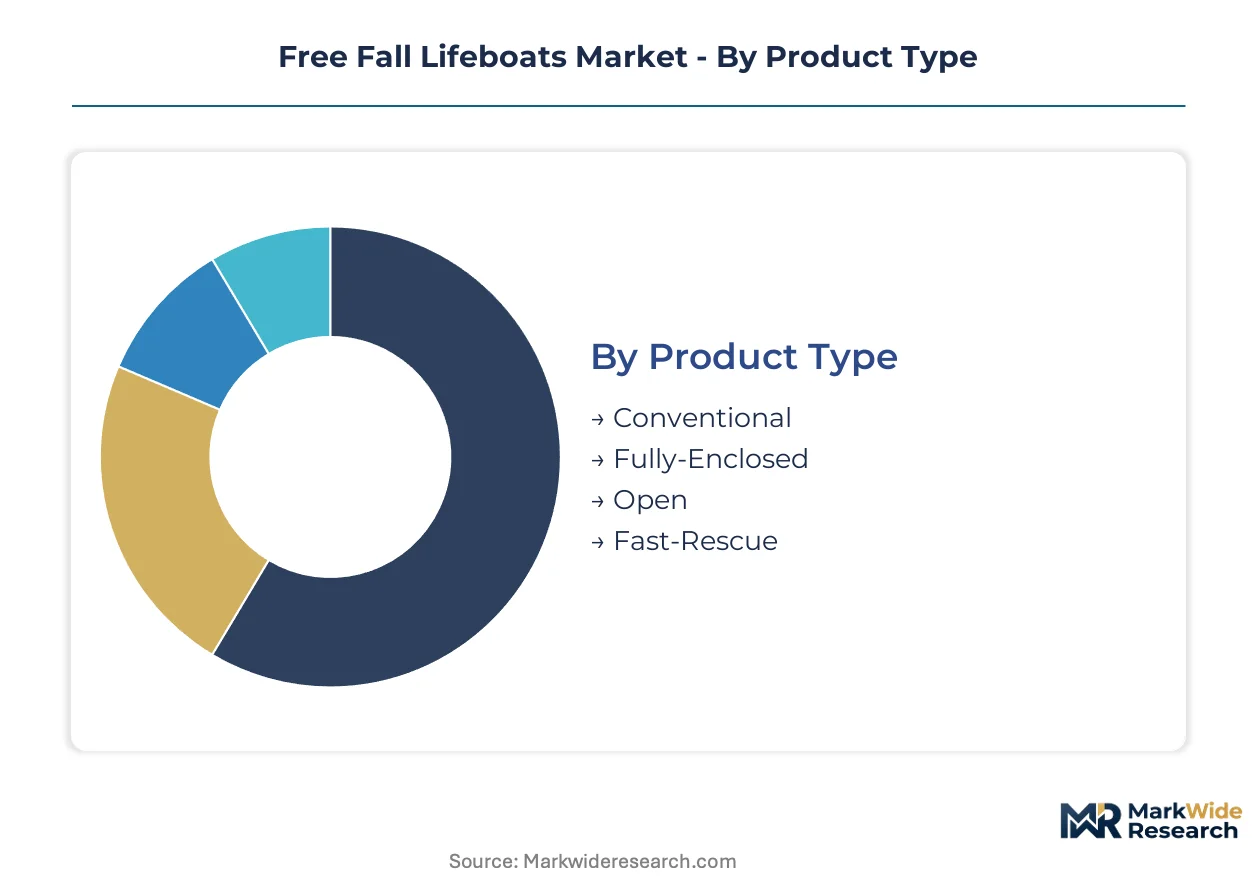
Free fall lifeboat procurement patterns diverge sharply across hull specifications, end-use environments, and certification regimes. Each segmentation axis reveals distinct margin structures and supplier concentration dynamics that shape competitive positioning.
Product Type:
Material composition and thermal protection ratings define the technology hierarchy across hull configurations.
- Fully-Enclosed:Fire-retardant glass-reinforced polyester construction with self-righting capabilities and thermal insulation rated for Arctic evacuation. Norwegian platform operators specify these for Barents Sea developments where water entry velocities exceed five meters per second. Premium pricing reflects IMO thermal protection mandates.
- Fast-Rescue:Hybrid designs merging primary evacuation with secondary recovery functions through integrated fast-launch davits. North Sea integrated operators bundle these into fifteen-year service contracts. Steepest expansion trajectory as procurement shifts from standalone evacuation to multi-function assets.
- Conventional:Standard gravity-launch configurations with basic impact-resistant hulls for temperate-zone platforms.
- Open:Unenclosed variants restricted to warm-water jurisdictions with minimal thermal protection requirements.
Mature deployment sits with Fully-Enclosed variants. Newer deployment is concentrated in Fast-Rescue configurations.
End User:
Operational risk profiles and regulatory exposure intensity vary substantially across maritime sectors.
- Oil & Gas:Offshore platform operators in Norway and West Africa drive volume through systematic fleet replacement programs. SOLAS LSA Code amendments force conversions from davit systems on aging North Sea infrastructure. Procurement concentrates among integrated majors with multi-platform portfolios.
- Maritime:Cruise and cargo vessel operators adopt free fall configurations for stern-launched evacuation where conventional side-davit systems face height restrictions.
- Shipping:Tanker and bulk carrier fleets specify compact variants for limited deck space, with ABS type-approval as baseline entry requirement.
- Fishing:Industrial trawler fleets in Arctic waters pull extreme-temperature specifications into smaller-vessel procurement.
Established demand anchors in Oil & Gas. Emerging demand is shifting toward Maritime applications.
Deployment Type:
Launch height and sea state conditions dictate hull engineering requirements across vessel categories.
- Offshore Platforms:Fixed installations in the North Sea and West Africa generate replacement cycles through decommissioning timelines. Thirty-meter-plus launch heights restrict aluminum alloy deployment and favor GRP composite construction. ABS full-scale testing queues extend procurement lead times.
- Surface Vessels:Merchant and cruise ships adopt free fall systems for stern-mounted evacuation stations where conventional davits cannot meet IMO evacuation timeframes.
- Research Vessels:Scientific expedition operators in polar waters specify extreme-temperature variants with enhanced thermal protection.
- Submersible:Limited deployment for specialized underwater support vessels with pressure-rated launch requirements.
Platform-based deployment dominates current procurement. Vessel-based deployment is expanding most quickly.
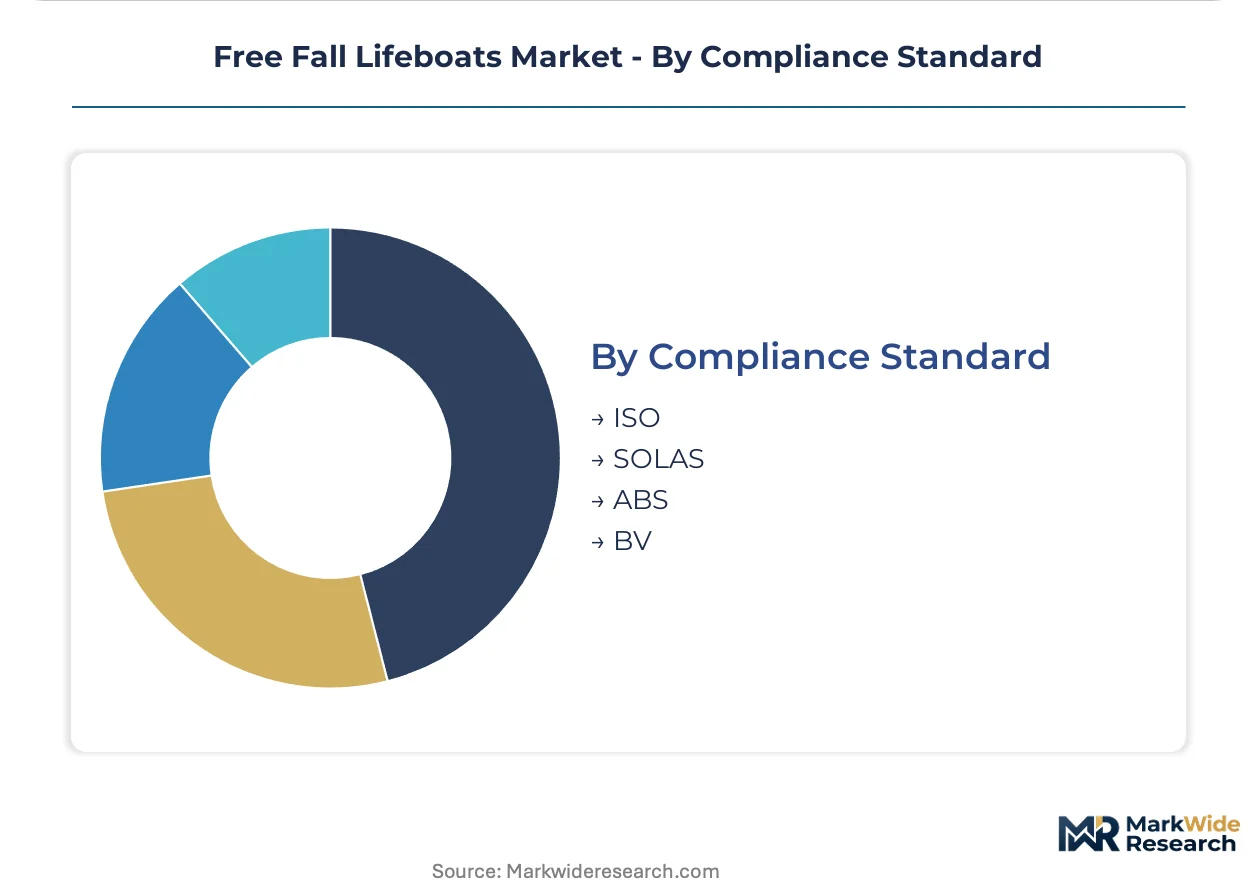
Compliance Standard:
Certification regime selection determines market access costs and geographic eligibility for hull fabricators.
- ABS:American Bureau of Shipping rules mandate full-scale drop testing that shapes competitive positioning through capital barriers. Norwegian fabricators dominate ABS-approved production through proximity to testing infrastructure.
- SOLAS:IMO Convention requirements set baseline evacuation timeframes and structural integrity protocols. Amendments to the LSA Code are accelerating conversion demand.
- ISO:ISO 21867 standards define maintenance protocols and launch performance benchmarks adopted by European operators.
- BV:Bureau Veritas classification offers alternative certification pathways for operators outside ABS-preferred supplier networks.
ABS certification commands premium positioning. BV pathways are gaining traction among new market entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore platform operators in Norway drive the highest procurement density, with decommissioning timelines and SOLAS compliance mandates compressing replacement cycles across the North Sea basin.
Norway
Statoil and Aker BP are accelerating fleet renewal programs on aging Ekofisk and Statfjord installations. The Norwegian Maritime Authority enforces strict NORSOK standards for free fall launch certification. Bergen and Stavanger host concentrated fabrication and testing infrastructure serving Barents Sea developments.
United Kingdom
North Sea decommissioning schedules are forcing conversions from davit systems on platforms exceeding thirty-meter launch heights. The Health and Safety Executive mandates evacuation timeframes under the Offshore Installations Regulations. Aberdeen maintains specialized service yards for ABS recertification and hull refurbishment.
United States
Gulf of Mexico operators are adopting fast-rescue configurations for deepwater tension-leg platforms. The US Coast Guard enforces 46 CFR standards for survival craft on offshore facilities. Houston engineering clusters coordinate procurement for floating production installations in the Walker Ridge and Mississippi Canyon blocks.
Brazil
Pre-salt field developments are pulling extreme-temperature specifications into standard procurement packages for Campos Basin platforms. The National Petroleum Agency requires ANP-certified evacuation systems for all offshore concessions. Rio de Janeiro fabrication yards are expanding capacity to meet Petrobras fleet standardization timelines.
China
State-owned offshore operators are consolidating supplier relationships for Bohai Bay and South China Sea platforms. The Maritime Safety Administration implements GB standards aligned with SOLAS evacuation protocols. Dalian and Qingdao shipyards are integrating free fall systems into newbuild floating production units for CNOOC developments.
Free Fall Lifeboats Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue fast-rescue specialization and digital maintenance bundling. The supply base clusters around Nordic engineering heritage and East Asian fabrication scale. Three archetypes dominate: integrated marine safety conglomerates, specialized survival craft fabricators, and shipyard-integrated system providers. Capacity expansion and fifteen-year service contract capture represent the dominant competitive moves.
Among Nordic fabricators, VIKING and Hatecke GmbH exemplify the engineering-specialist archetype, with Fr. Fassmer GmbH & Co. KG occupying a position that bridges integrated rescue systems with platform-specific customization. These entities anchor the premium tier through proximity to North Sea testing infrastructure and long-term operator relationships.
| Leading Market Players |
|---|
| VIKING |
| Hatecke GmbH |
| Survival Systems International, Inc. |
| Fr. Fassmer GmbH & Co. KG |
| Palfinger Marine |
| DSB Engineering CO. Ltd |
| Jiangsu Jiaoyan Marine Equipment Co.,Ltd |
| Qingdao Beihai Shipbuilding Heavy Industry Co.,Ltd |
| Vanguard Composite Engineering PTE LTD |
| Others |
Value Network & Pricing Analysis
ABS certification tiers bifurcate the free fall lifeboat market into premium validated and standard-compliant segments, with Norwegian fabricators commanding pricing power through proximity to full-scale drop testing infrastructure while Asian producers compete on hull delivery cost for warm-water jurisdictions. This tier divergence manifests in supply chain configurations where ABS-approved production clusters around Bergen and Stavanger testing facilities, while non-ABS supply routes through Dalian and Qingdao shipyards serve price-sensitive operators in Brazil and West Africa.
Pricing Analysis
Volume absorption concentrates in mid-tier fully-enclosed GRP configurations, while margin generation pools in fast-rescue variants bundled with fifteen-year service obligations. Price differentiation rests on ABS type-approval status and thermal protection ratings for Arctic deployment. Cost compression in standard hull fabrication is intensifying because REACH-compliant resin reformulations add material overhead. Integrated offshore operators in Norway show lowest price sensitivity; independent platform contractors in West Africa exhibit highest.
Supply Chain Analysis
Direct-to-platform procurement channels handle integrated operator demand in the North Sea, while shipyard-integrated supply serves newbuild floating production units in China and Brazil. Manufacturing gravity centers on Norway, Germany, and China. Fire-retardant polyester resin, aluminum alloy plate, and specialized welding consumables constitute critical input dependencies. Single-source vulnerability concentrates in full-scale drop certification facilities clustered in Northern Europe. Distribution runs through long-term service contracts that bundle equipment supply with recertification obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Free fall lifeboats operate as a cost-of-compliance market where ABS full-scale testing requirements erect capital barriers that protect validated incumbents from commodity competition. The International Maritime Organization's SOLAS LSA Code amendments deepen this moat by mandating conversion timelines that compress procurement cycles.
For Market Incumbents: Lock in fifteen-year service contract renewals with Statoil and Aker BP before decommissioning timelines peak, while adding captive GRP lamination capacity to offset welding specialist scarcity from aerospace sector competition. Prioritize fast-rescue engineering investment to defend margin pools against emerging entrants bundling digital twin maintenance.
For New Entrants and Emerging Players: Predictive hull integrity monitoring software offers a technology-first wedge into aftermarket service revenue streams that incumbents underprice. Target floating offshore wind turbine installation vessels in the North Sea as the most penetrable deployment segment, entering through fast-rescue configuration partnerships with vessel operators seeking secondary recovery capabilities.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized survival craft fabricators holding ABS testing queue priority given IMO regulatory acceleration compressing platform commissioning schedules. Long-term viability favors entities with backward integration into fire-retardant resin formulation and proximity to Norwegian testing infrastructure. Watch ABS certification backlog length as the signal for inflection in pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| ABS Certification Investment | Full-scale drop testing capacity in Norway secures queue priority for North Sea platform renewals. |
| Fast-Rescue Function Bundling | Secondary recovery capabilities merged with evacuation assets command premium in Norwegian tenders. |
| Digital Twin Maintenance Platform | Predictive hull monitoring opens recurring revenue beyond initial equipment sales to integrated operators. |
| Fire-Retardant Resin Backward Integration | In-house REACH-compliant formulation reduces feedstock volatility exposure for GRP hull fabricators. |
| Floating Wind Vessel Partnership | Crew transfer operations in North Sea turbine installations expand addressable market beyond oil and gas. |
Research Methodology
IMO regulatory filings, ABS classification records, and offshore platform decommissioning databases formed the secondary backbone, supplemented by customs data tracking GRP hull and aluminum alloy trade flows. Primary interviews with platform safety officers, shipyard procurement managers, and classification society surveyors validated segment assumptions. Bottom-up hull configuration demand was triangulated against top-down offshore operator capex disclosures across the analysis window.
Historical replacement cycle analysis established baseline demand patterns without year-specific anchoring. The forecast framework modeled segmentation across hull material type, deployment platform category, end-use sector, and certification regime. CAGRs were derived from elasticity-adjusted absorption rates tied to SOLAS amendment implementation timelines. Industry-specific inputs included Barents Sea development schedules and floating offshore wind installation vessel orderbooks.
Forecast precision tightens around the base case; tail outcomes carry wider variance under IMO LSA Code amendment delays or aluminum alloy substitution breakthroughs for high-launch-height platforms. Projections reflect assumptions regarding ABS testing capacity expansion and resin feedstock cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
Emergency Shutdown System Market
Emergency and Disaster Management
Emergency Shower and Eyewash Station Market
Emergency and Disaster Management
Automatic Floodgate Market
Emergency and Disaster Management
Outdoor Emergency Safety Shower Market
Emergency and Disaster Management
Homeland Security and Emergency Management Market
Emergency and Disaster Management
Cyber Crisis Management Market
Emergency and Disaster Management
Emergency Location Transmitter Market
Emergency and Disaster Management
Crisis Emergency and Incident Management Platform Market
Emergency and Disaster Management
Emergency Blankets Market
Emergency and Disaster Management
Hazard Control Market
Emergency and Disaster Management
Incident and Emergency Management Market
Emergency and Disaster Management
Disaster Restoration Services Market
Emergency and Disaster Management
North America Emergency Shower and Eye Wash Station Market
Emergency and Disaster Management
Intelligent Evacuation System Market
Emergency and Disaster Management
Emergency and Disaster Response Market
Emergency and Disaster Management
North America Homeland Security and Emergency Management Market