
 Twisted Handle Bags Market | 2026-2036
Twisted Handle Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Twisted Handle Bags Market Analytics
India is reconfiguring twisted handle bag production capacity through new kraft paper mill investments and converting facilities. International Paper leverages its integrated pulp-to-bag supply chain to sustain cost advantages in Asian markets. Mondi Group anchors European demand with certified recyclable paper grades that meet supermarket specifications. Novolex competes through geographic breadth across North American retail and grocery channels.
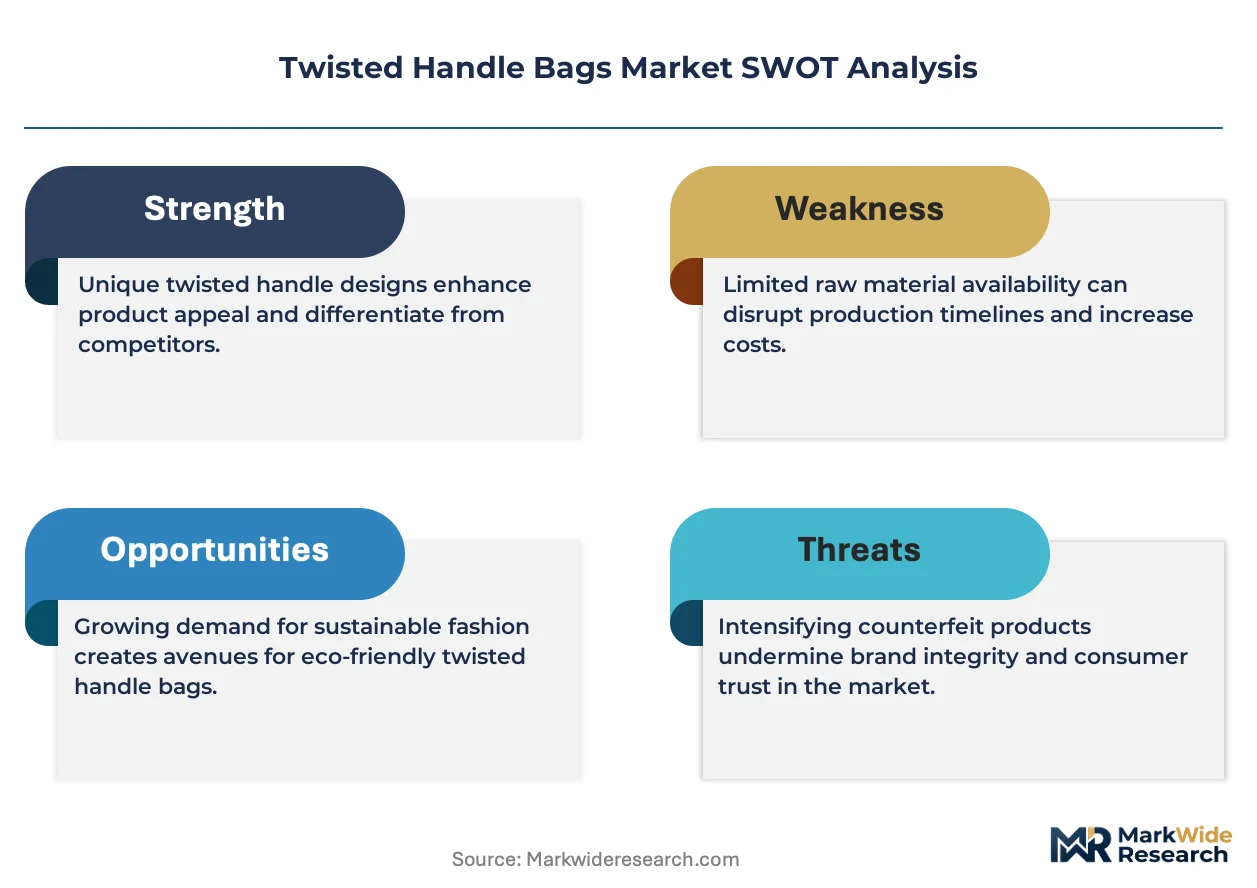
Twisted handle bags are carry containers constructed with rope-style handles twisted from the same material as the bag body, typically formed from kraft paper weights between 80–150 gsm or reinforced polyethylene, using automatic handle-fixing machinery that threads and knots handles through die-cut apertures. Their primary commercial purpose is branded merchandise transport and grocery checkout where hand-carry comfort and load capacity matter. Paper bags within the product type dimension dominate unit volumes in regulated markets where plastic restrictions apply, while cotton bags capture premium margin pools in specialty shop segments. E-commerce within the end user dimension represents the fastest-growing application as unboxing aesthetics drive packaging decisions.
FDA food-contact regulations and EPA recycled content mandates shape material specifications for US-market twisted handle bags, while EU Green Deal packaging requirements and REACH chemical compliance dictate fiber sourcing and adhesive formulations for European distribution. India's BIS quality standards and PLI scheme incentives for paper-based products are accelerating domestic manufacturing substitution for imported plastic alternatives. Stakeholders must monitor how fragmented municipal bag bans across US states and evolving EU CSRD reporting obligations reshape procurement criteria before committing to capacity expansions.
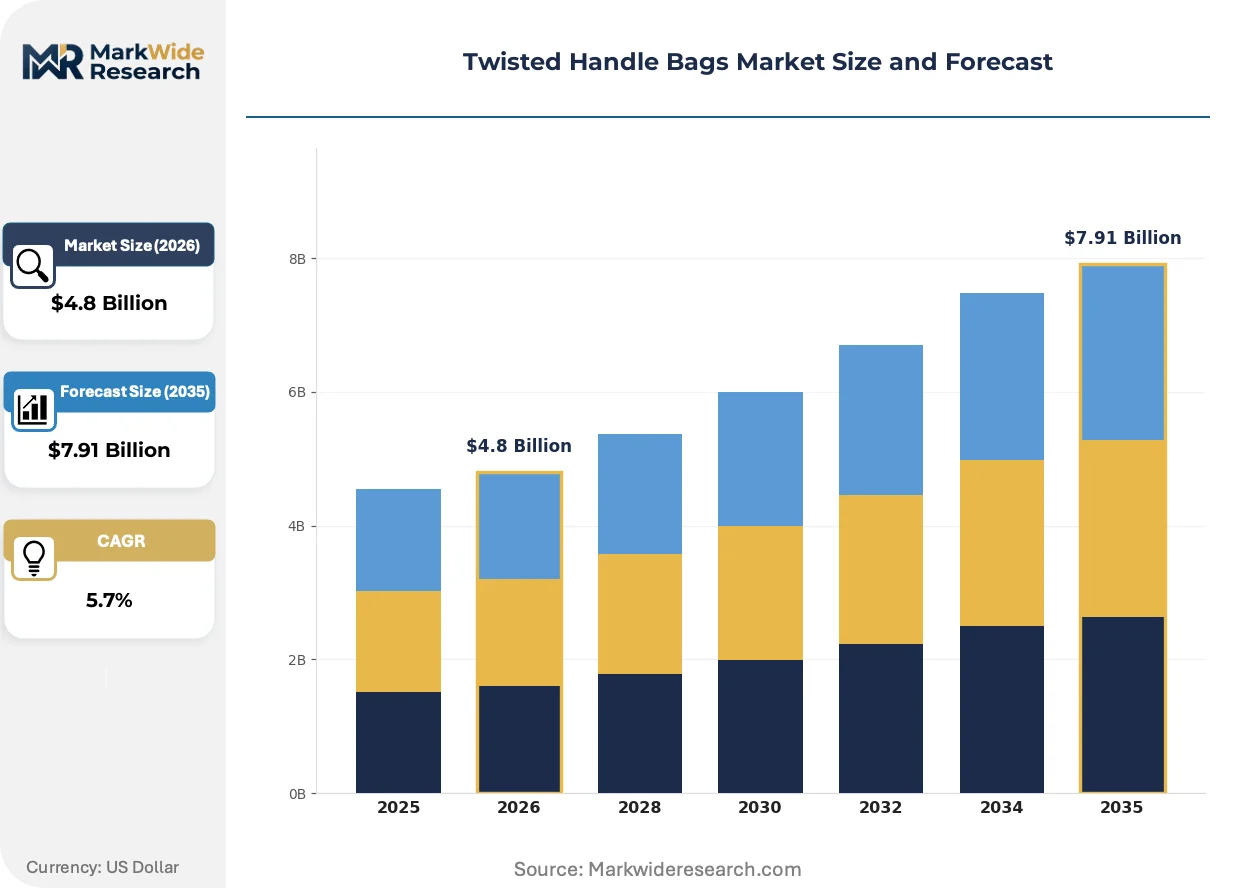
Market Dynamics
The twisted handle bags market pivots on EU Green Deal packaging mandates that are forcing retail chains to eliminate single-use plastic carry bags ahead of 2030 deadlines, redirecting procurement volumes toward certified paper alternatives and rewiring supplier qualification criteria across European distribution networks.
Growth Catalysts
- EU Green Deal packaging rules:Supermarket chains in Germany and France are accelerating paper bag adoption to meet 2030 single-use plastic elimination targets, creating sustained demand for recyclable kraft paper grades.
- India PLI scheme for paper products:Domestic manufacturers are expanding kraft paper mill capacity to capture government incentives, reducing import dependence for retail bag supply.
- Automatic handle-fixing machinery:Production lines deploying high-speed knotting equipment are lowering per-unit labor costs and enabling shorter order runs for customized branded bags.
Market Restraints
- Pulp price volatility:Kraft paper producers face margin compression when softwood pulp futures spike, as bag converters cannot pass full input cost increases to price-sensitive grocery retailers.
- China kraft paper concentration:Asian supply chains depend on a narrow base of integrated pulp-to-paper mills for virgin fiber, creating disruption risk during regional environmental inspections or export quota adjustments.
- Reusable cotton bag substitution:Premium specialty shops in urban centers are switching to durable fabric alternatives for customer retention programs, eroding paper bag volume in high-margin segments.
Strategic Opportunities
- BIS-certified domestic production in India:Quality-standard compliance is unlocking government procurement contracts for state-run retail cooperatives seeking plastic-free alternatives.
- E-commerce unboxing aesthetics:Direct-to-consumer brands are specifying custom-printed twisted handle bags as signature packaging elements, opening design-service revenue streams beyond commodity bag sales.
- Water-based adhesive convergence with digital printing:Combining food-safe bonding chemistry with short-run variable printing enables personalized bag campaigns for regional product launches.
Industry Challenges
- REACH-compliant adhesive sourcing:European bag manufacturers face extended qualification timelines when reformulating hot-melt glues to meet ECHA substance restrictions on formaldehyde-releasing compounds.
- Die-cutting precision for handle apertures:Automated production lines require skilled maintenance technicians to prevent fiber tear-out at high speeds, and qualified operators remain scarce in emerging manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Twisted Handle Bags Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Bags, Plastic Bags, Cotton Bags, Jute Bags End User: Retail Stores, E-commerce, Grocery Stores, Specialty Shops Size: Small, Medium, Large, Extra Large Closure Type: Open Top, Snap Closure, Zipper, Magnetic Closure |
| Companies Covered | International Paper, Mondi Group, WestRock, Novolex, Shamrock Kraft Bags, Jet Paper Bags, Uline, Pacific Bag, S.B. Packagings Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Twisted Handle Bags Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to redefine twisted handle bag specifications, with sustainability certifications now functioning as primary procurement filters rather than secondary marketing claims.
Water-based barrier coatings are migrating from niche organic food applications to mainstream grocery retail as European supermarkets demand grease-resistant paper bags that maintain recyclability under EU Green Deal criteria. German discount chains are piloting these coatings at scale for fresh bakery sections. The technology is compressing the performance gap between virgin and recycled fiber grades, allowing higher post-consumer content without sacrificing moisture protection.
REACH chemical compliance is tightening adhesive formulations across European supply chains as ECHA adds formaldehyde-releasing substances to restricted candidate lists. Bag converters are qualifying alternative hot-melt chemistries that maintain bond strength at reduced application temperatures. Small-batch specialty producers in Italy and Spain are most affected, as their legacy equipment requires longer revalidation cycles for new glue specifications.
Brand-direct procurement models are consolidating purchasing power among mid-sized retail chains that previously bought through distribution intermediaries. These buyers are establishing direct relationships with integrated paper-to-bag manufacturers to secure volume commitments and custom print capabilities. The shift is most visible in India's organized retail sector, where Reliance Retail and Future Group are centralizing packaging specifications across store formats.
Twisted Handle Bags Market Segmentation
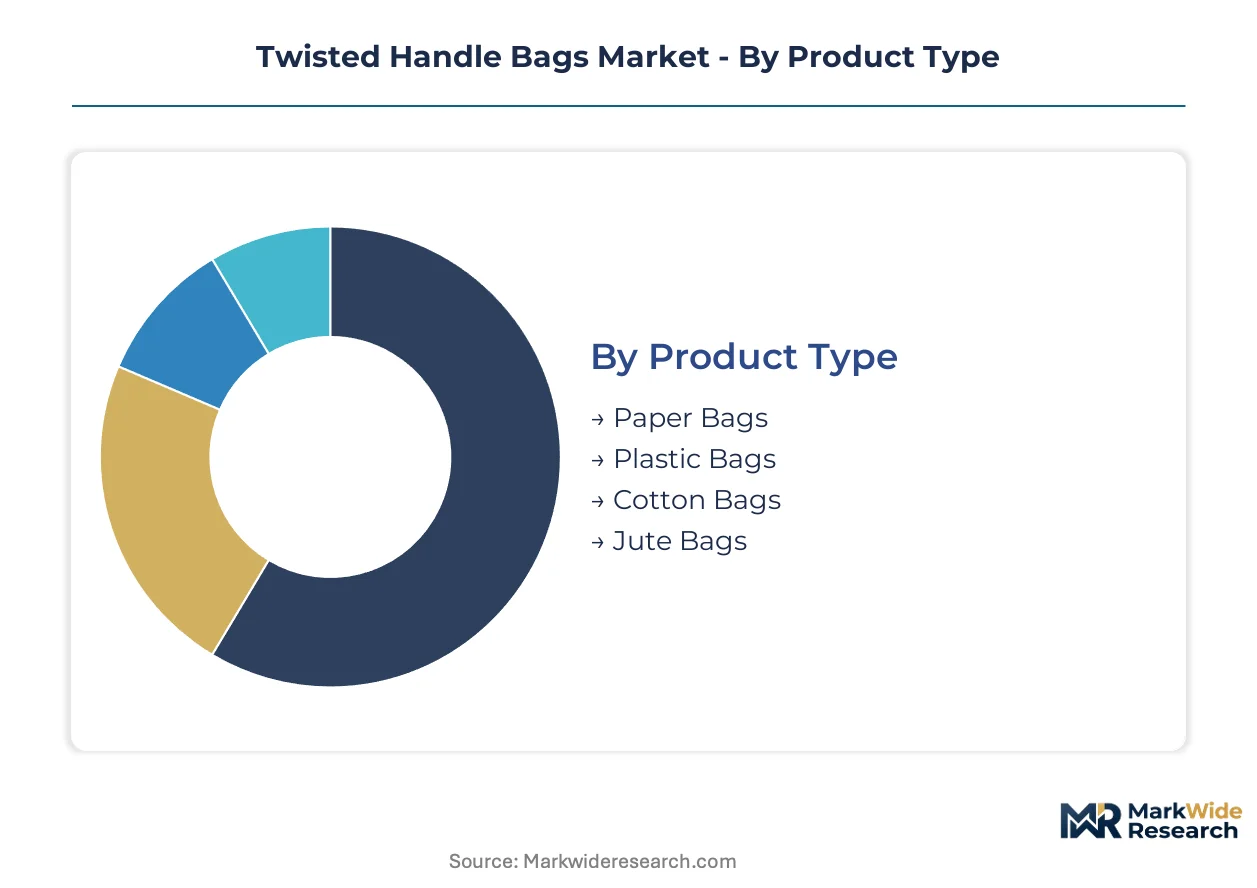
Twisted handle bag procurement splits across material chemistry, retail channel requirements, dimensional specifications, and security features. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier qualification and capacity planning.
Product Type:
Material cost tiers separate commodity volume from premium positioning, with fiber sourcing and recyclability credentials driving procurement filters.
- Paper Bags:Constructed from kraft paper between 80–150 gsm with twisted paper handles formed from the same fiber stock. Supermarket chains in Germany and France are accelerating procurement to meet EU Green Deal single-use plastic elimination targets, though pulp price spikes compress converter margins.
- Plastic Bags:Reinforced polyethylene constructions with twisted polymer handles offering moisture resistance and load capacity. Demand concentrates in markets without plastic restrictions, with grocery retailers in price-sensitive segments maintaining volume commitments.
- Cotton Bags:Woven or non-woven natural fiber constructions targeting reusable programs. Urban specialty shops specify these for customer retention initiatives.
- Jute Bags:Coarse vegetable fiber constructions with rustic aesthetic positioning. Organic food retailers and fair-trade channels drive niche procurement.
Paper bags command the established base. The steepest expansion runs through cotton bags as reusable mandates proliferate.
End User:
Application context dictates performance specifications, with load capacity and branding surface requirements varying sharply across channels.
- Retail Stores:Department stores and apparel chains specify custom-printed constructions with reinforced bottoms for merchandise transport. Unboxing aesthetics now drive specification upgrades as direct-to-consumer brands treat bags as signature packaging elements.
- E-commerce:Direct-to-consumer fulfillment operations prioritize tear-resistant constructions with flat storage profiles for warehouse efficiency. This channel is expanding most quickly as digital-native brands specify premium paper grades for unboxing differentiation.
- Grocery Stores:High-volume checkout operations demand cost-optimized kraft paper with food-contact compliance. German discount chains are piloting water-based barrier coatings at scale for fresh bakery sections.
- Specialty Shops:Boutique retailers prioritize tactile quality and custom print fidelity over unit cost. Italian and Spanish producers serve this segment with small-batch capabilities.
Retail stores anchor volume commitments. E-commerce is climbing the fastest as fulfillment packaging gains strategic attention.
Size:
Dimensional segmentation tracks customer type and purchase occasion, with volume scale concentrating in mid-range formats.
- Small:Compact formats for jewelry, cosmetics, and confectionery with single-item capacity. Premium cosmetic chains drive specification.
- Medium:Standard apparel and general merchandise dimensions representing the procurement sweet spot for retail chains. This format captures the highest unit volumes across European and Indian distribution networks.
- Large:Expanded capacity for bulk grocery and multi-item retail with reinforced handle attachments. Supermarket private-label programs specify these for weekly shopping trips.
- Extra Large:Oversized constructions for home goods, bedding, and bulky merchandise. Furniture retailers and warehouse clubs maintain limited but stable demand.
Medium sizes dominate procurement volumes. Large formats are gaining share fastest as grocery consolidation increases average basket sizes.
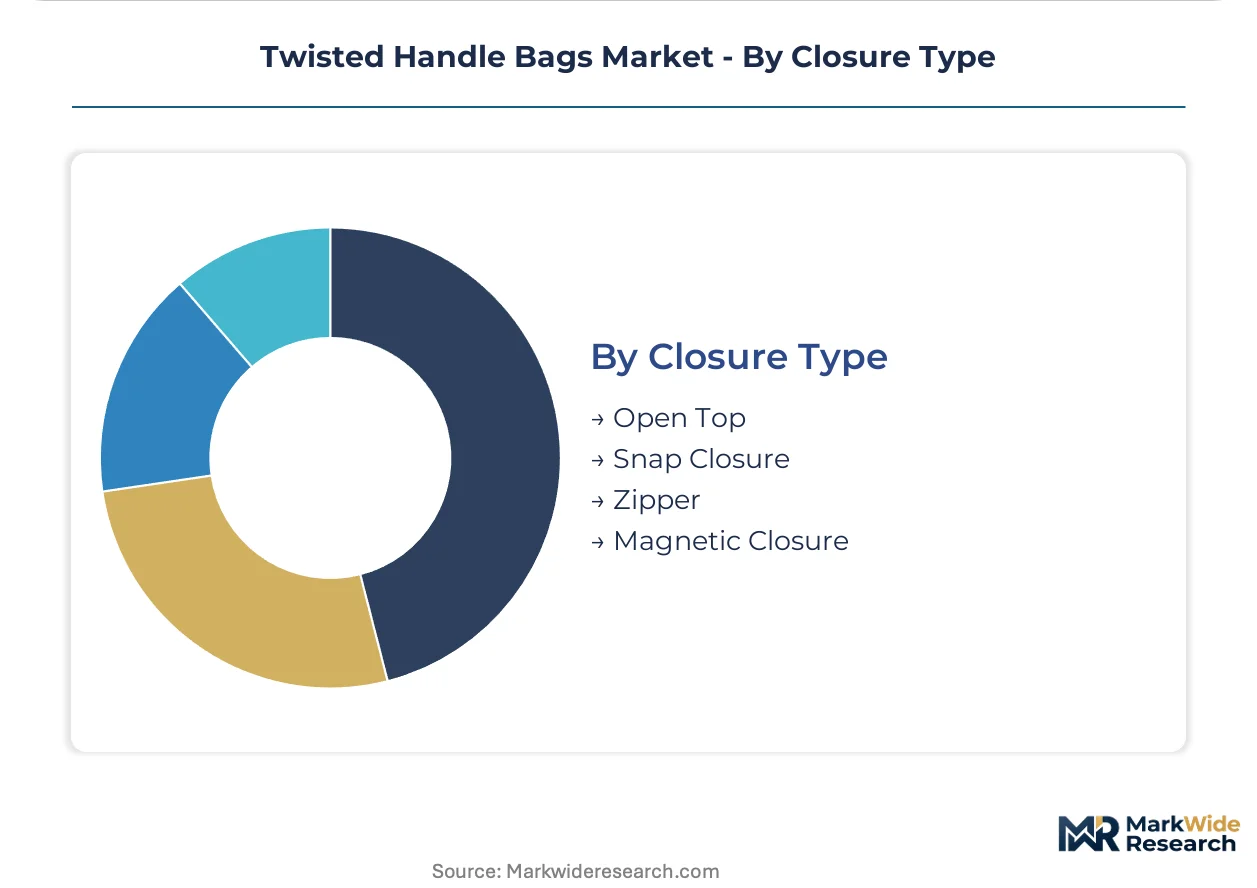
Closure Type:
Security features segment by contents protection requirements and premium positioning, with open-top constructions maintaining cost advantage.
- Open Top:Standard die-cut aperture construction with twisted handle threading, offering lowest unit cost and fastest production speeds. This configuration captures overwhelming share in grocery and mass retail applications.
- Snap Closure:Integrated plastic or metal fasteners for contents security in transit. Pharmacy and specialty retail channels specify these for controlled substances or high-value items.
- Zipper:Extended-use resealable constructions migrating from plastic to paper-based laminated formats. Gourmet food and organic retail segments pilot these for premium positioning.
- Magnetic Closure:Concealed fastener systems for luxury retail with tactile opening experience. High-end department stores in Paris and Milan specify these for gift packaging.
Open-top constructions maintain the volume base. Magnetic closures are expanding most quickly as luxury retail elevates packaging to brand touchpoint status.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal packaging mandates are redirecting procurement volumes toward certified paper alternatives across European distribution networks, while India's PLI scheme accelerates domestic kraft paper mill investments to displace imported plastic bag supply.
Germany
German discount chains are piloting water-based barrier coatings at scale for fresh bakery sections. The EU Green Deal single-use plastic elimination targets force supermarket chains to accelerate paper bag adoption ahead of 2030 deadlines. Industrial clusters in North Rhine-Westphalia host integrated pulp-to-bag manufacturers serving pan-European retail networks.
France
Paris-based luxury department stores specify magnetic closure twisted handle bags for gift packaging differentiation. REACH chemical compliance tightens adhesive formulations as ECHA adds formaldehyde-releasing substances to restricted candidate lists. Producers in the Hauts-de-France region maintain small-batch specialty capabilities for boutique retail channels.
India
Reliance Retail and Future Group centralize packaging specifications across store formats through brand-direct procurement models. BIS quality standards and PLI scheme incentives for paper-based products accelerate domestic manufacturing substitution for imported plastic alternatives. Gujarat and Maharashtra kraft paper mill investments expand converting capacity for organized retail supply.
United States
FDA food-contact regulations and EPA recycled content mandates shape material specifications for twisted handle bags distributed through grocery and retail channels. Fragmented municipal bag bans across states reshape procurement criteria for national retail chains. The Southeast manufacturing corridor maintains production capacity for price-sensitive mass retail segments.
Italy
Italian specialty producers serve boutique retail segments with small-batch custom print capabilities. REACH-compliant adhesive sourcing extends qualification timelines for bag converters reformulating hot-melt glues. Industrial districts in Emilia-Romagna cluster legacy equipment operators requiring longer revalidation cycles for new glue specifications.
Twisted Handle Bags Market Competitive Landscape
Integrated paper-to-bag manufacturers and regional converting specialists split the market between scale-driven commodity supply and design-intensive premium positioning. The vendor base concentrates around three strategic archetypes: integrated pulp-to-bag conglomerates with captive fiber supply, mid-scale converters leveraging automatic handle-fixing machinery for cost efficiency, and boutique specialists commanding premium margins through custom print fidelity. Dominant competitive moves include backward integration into kraft paper mill assets and geographic expansion through distributor network partnerships.
Within the integrated conglomerate tier, International Paper and Mondi Group exemplify archetypes leveraging captive pulp supply chains to sustain cost advantages across Asian and European markets respectively. Novolex occupies a position representing geographic breadth strategies across North American retail and grocery channels. These three entities anchor competitive dynamics by demonstrating how fiber integration, regional regulatory compliance, and channel-specific distribution depth constitute distinct strategic vectors.
| Leading Market Players |
|---|
| International Paper |
| Mondi Group |
| WestRock |
| Novolex |
| Shamrock Kraft Bags |
| Jet Paper Bags |
| Uline |
| Pacific Bag |
| S.B. Packagings Ltd. |
| Others |
Value Network & Pricing Analysis
China's integrated pulp-to-paper mill concentration upstream dictates margin distribution downstream, with kraft paper converters in Germany and India capturing differential value based on captive fiber access versus spot-market procurement exposure.
Pricing Analysis
Geographic price spreads between European and Asian supply bases exceed transport-cost differentials, reflecting certification premiums for EU Green Deal-compliant grades. Three-tier pricing structure across premium, standard, and economy levels segments by fiber content percentage and food-contact certification tier. Pricing pressure stems from pulp futures volatility that converters cannot fully pass to grocery retailers. Mass retail chains exhibit highest price sensitivity, while luxury department stores in Paris and Milan tolerate premium positioning for magnetic-closure gift specifications.
Supply Chain Analysis
Extended payment terms from European supermarket chains strain converter working capital, accelerating supply-chain finance facility adoption among mid-scale producers. Raw material sourcing draws from softwood pulp mills in Sweden, Finland, and Brazil, with handle-fixing machinery components anchored in German and Italian industrial clusters. Single-source vulnerability concentrates in Asian virgin fiber supply during regional environmental inspection cycles. Distribution runs through direct procurement relationships consolidating among India's organized retail networks and European supermarket private-label programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive positioning through regulatory entrenchment, where EU Green Deal compliance certification creates switching costs that lock in supermarket supply relationships across multi-year procurement cycles.
For Market Incumbents: Pre-empt margin compression from pulp price volatility by securing backward integration into Scandinavian or South American kraft paper mill assets. Anchor channel control through multi-year volume commitments with German and French supermarket chains ahead of 2030 plastic elimination deadlines. Invest in water-based barrier coating R&D to defend premium positioning against cotton bag substitution in bakery and fresh food segments.
For New Entrants and Emerging Players: Pursue white-space opportunity in Indian state-run retail cooperatives seeking BIS-certified domestic suppliers for plastic-free transitions. Target e-commerce fulfillment packaging where unboxing aesthetics command design-service premiums beyond commodity bag economics. Establish go-to-market presence through direct relationships with direct-to-consumer brands specifying custom-printed twisted handle bags as signature packaging elements.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European converters holding REACH-compliant adhesive formulations and supermarket qualification credentials. Five-to-ten-year viability hinges on regulatory compliance durability rather than technology disruption risk. Monitor EU ECHA substance restriction updates as inflection indicators for adhesive reformulation capital requirements and consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Paper Mills | Captive pulp supply from Scandinavian mills insulates margin compression from spot-market volatility. |
| Water-Based Barrier Coating Scale-Up | German discount chains pilot these coatings for fresh bakery sections under EU Green Deal criteria. |
| REACH-Compliant Adhesive Reformulation | ECHA formaldehyde restrictions force Italian and Spanish producers into extended revalidation cycles. |
| Direct-to-Consumer Brand Partnerships | Reliance Retail and Future Group centralize packaging specifications across Indian store formats. |
| Automatic Handle-Fixing Machinery Deployment | High-speed knotting equipment lowers per-unit labor costs for customized short-run orders. |
Research Methodology
Operator-level perspectives from kraft paper mill managers, bag converter production heads, supermarket category buyers, and specialty retail procurement leads anchored the qualitative base. Primary interview findings triangulated against customs trade data for pulp and paper flows, EU ECHA substance restriction databases, BIS certification registries, and SEC filings from integrated paper conglomerates. Bottom-up capacity assessments across Gujarat and Maharashtra mill investments combined with top-down retail procurement volume estimates.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning material chemistry, end-user channel, dimensional specification, and closure security features. CAGRs derived from elasticity-adjusted demand curves incorporating EU Green Deal compliance timelines and India PLI scheme incentive trajectories. Forecast inputs included pulp futures price corridors and automatic handle-fixing machinery deployment rates across converting facilities.
Sensitivities concentrate around EU ECHA substance restriction expansions, China environmental inspection intensity, and India PLI scheme renewal terms. Forecasts reflect documented assumptions on regulatory enforcement consistency and fiber substitution elasticity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Archive Boxes Market
Bags and Containers
Cross Corner Industrial Bags Market
Bags and Containers
Bin Liners Market
Bags and Containers
Global Bubble Lined Courier Bag Market
Bags and Containers
Trash Bags Market
Bags and Containers
Cross Bottom Bags Market
Bags and Containers
Silicone Storage Bags Market
Bags and Containers
Self-Sealing Ziplock Bags Market
Bags and Containers
Bag-In-Box Container Market
Bags and Containers
Trash Can Liners Market
Bags and Containers
Tote and Ingredient Bags Packaging Market
Bags and Containers
Frosted Bag Market
Bags and Containers
Nonwoven Containers Market
Bags and Containers
Tamper Evident Bag Sealers Market
Bags and Containers
Loose-Fill Peanuts Market
Bags and Containers
2 Loop FIBC Bags Market