
 Frosted Bag Market | 2026-2036
Frosted Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Frosted Bag Market Foresight
Specialty food retailers and boutique cosmetic brands is collapsing into frosted bag procurement as mass-market grocers retreat from premium packaging formats. Ziploc leverages its retail shelf presence to sustain volume leadership in zip-lock frosted formats across North American club stores. SC Johnson anchors its position through R&D intensity in resealable closure systems that extend product freshness claims. Dongguan Pasike Packaging Co., Ltd. competes on manufacturing scale, dominating contract production for European personal care distributors seeking cost-optimized laminated film bags.
A frosted bag is a translucent or semi-opaque flexible packaging container manufactured from blown polyethylene, cast polypropylene, or multi-layer laminated films with surface etching or additive dispersion to achieve light-diffusing properties, typically sealing at 120-180°C and offering tensile strength of 15-30 MPa for retail and industrial containment. Gusseted bags and stand-up pouches occupy the highest margin pools, as dimensional stability commands premium pricing in food packaging and personal care applications where shelf presentation determines purchase conversion. Zip-lock bags lead volume throughput through repeat-use functionality, while vacuum bags represent the fastest-growing structural segment as electronics protection demands hermetic barrier properties against moisture and oxidation.
The FDA regulates direct food contact materials through 21 CFR 177.1520 for olefin polymers, while the EU Packaging and Packaging Waste Regulation mandates recyclability targets that reshape material selection toward mono-polyethylene structures. California's SB 54 imposes extended producer responsibility requirements that force reformulation of laminated film constructions to meet state-designated recycling infrastructure compatibility. Stakeholders must monitor evolving state-level packaging laws and polymer recycling certification schemes to preempt compliance-driven sourcing disruptions.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing material choice toward mono-polyethylene constructions, forcing converters to abandon multi-layer laminates that previously dominated premium cosmetic and food applications. This regulatory pressure intersects with specialty retailers' shelf differentiation strategies, creating a structural tension between compliance costs and brand positioning requirements.
Growth Catalysts
- REACH compliance migration:Chemical safety registrations under ECHA are accelerating substitution of legacy plasticizers with bio-based additives in frosted film formulations.
- Electronics protection demand:Hermetic vacuum bag formats are capturing volume from desiccant-based packaging as semiconductor and component manufacturers prioritize moisture barrier reliability.
- German packaging mandates:Extended producer responsibility frameworks in Germany are concentrating demand for recyclable frosted formats among food processing clusters in Bavaria and Baden-Württemberg.
Market Restraints
- Resin input volatility:Ethylene and propylene feedstock price swings compress converter margins, particularly for small-batch specialty orders with fixed pricing contracts.
- Asian supply concentration:Blown film capacity clusters in Guangdong and Zhejiang provinces create geographic risk exposure for European distributors dependent on contract manufacturing.
- California SB 54 friction:Extended producer responsibility requirements impose reformulation costs that disadvantage mid-tier converters lacking R&D scale.
Strategic Opportunities
- India personal care penetration:Boutique cosmetic brands in Mumbai and Delhi are accelerating premium packaging adoption as organized retail expands.
- Mono-material innovation:Advances in polyethylene surface etching are enabling light-diffusing properties without laminated constructions.
- Direct-to-consumer channel expansion:Subscription beauty boxes and meal kit services are creating pull for zip-lock frosted formats with unboxing aesthetic requirements.
Industry Challenges
- Polymer recycling certification timelines:RecyClass and How2Recycle approval processes extend product development cycles by 8-14 months.
- Closure system integration complexity:Resealable zipper welding with frosted films requires precision calibration that strains legacy converting equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frosted Bag Market |
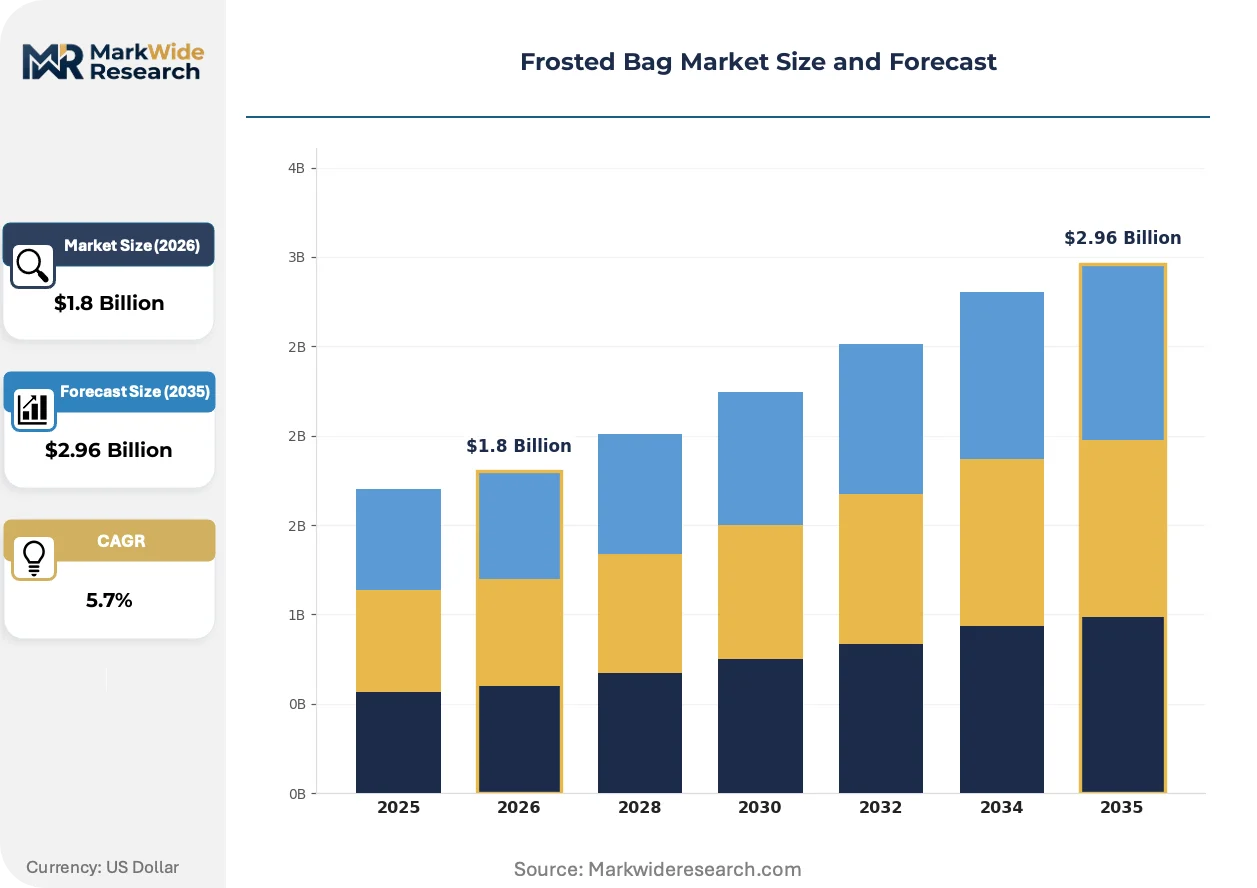
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gusseted Bags, Flat Bags, Stand-up Pouches, Zip-lock Bags, Vacuum Bags Material: Polyethylene, Polypropylene, Laminated Film, Cellophane, Kraft Paper Application: Food Packaging, Personal Care, Electronics Protection, Industrial Packaging, Gift Wrapping Distribution Channel: Supermarkets, E-commerce Platforms, Specialty Stores, Wholesale Suppliers, Direct Sales |
| Companies Covered | Ziploc, SC Johnson, Glad Products Company, Hefty, SynPack, Multi-Pak USA, Inc., Reynolds, Dongguan Pasike Packaging Co., Ltd., Minigrip, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frosted Bag Market Shifts & Advancements
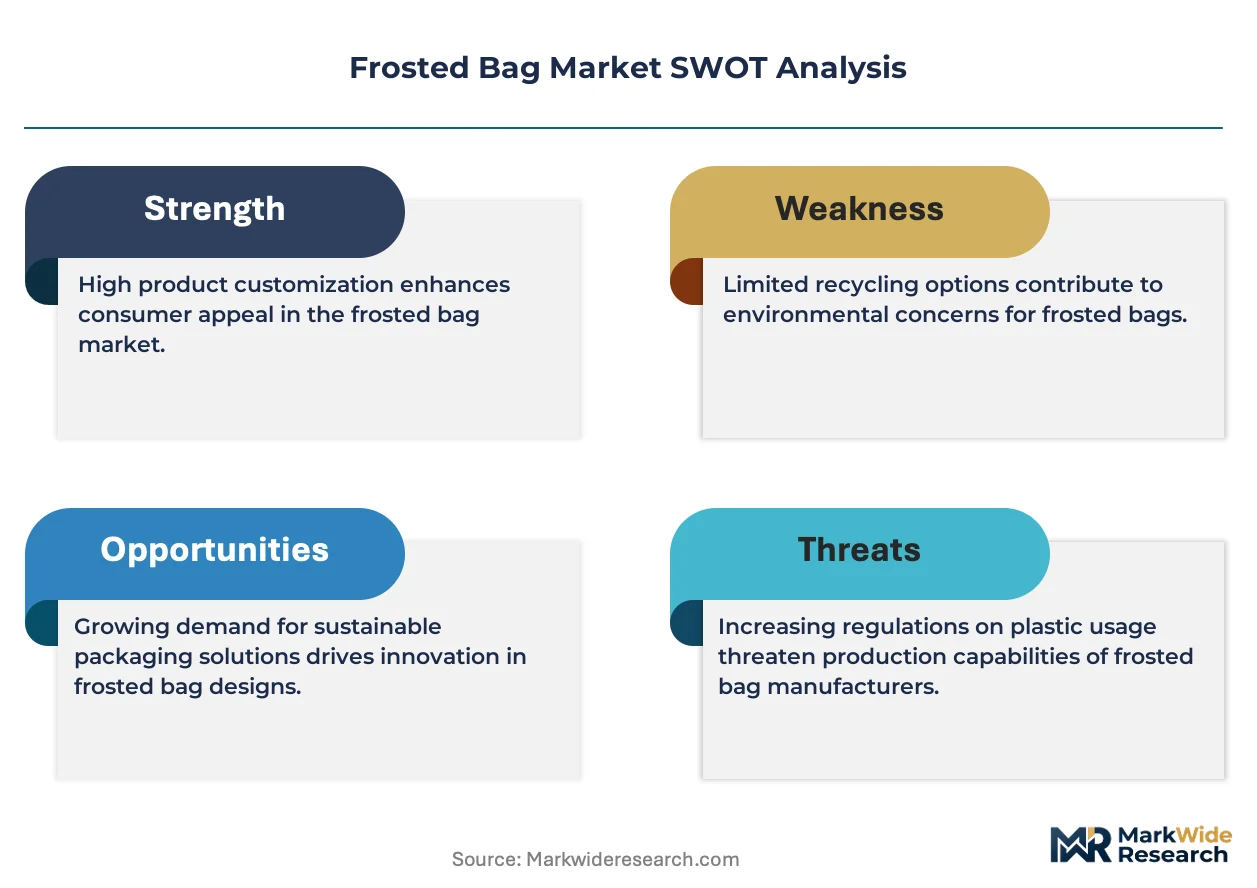
Material science advances and regulatory compliance requirements are actively restructuring competitive advantage in frosted bag manufacturing. Converters must now balance optical performance specifications against recyclability certifications that were previously secondary considerations.
Mono-polyethylene surface etching technology is bifurcating the premium segment. Specialty food retailers in Germany and France are adopting etched mono-PE frosted bags at accelerated pace to satisfy EU Packaging and Packaging Waste Regulation recyclability targets. This technology is bifurcating margin pools between compliant converters with in-house etching capability and legacy players dependent on laminated imports.
California's SB 54 extended producer responsibility framework is reshaping material selection across North American supply chains. Brand owners now face state-mandated recycling infrastructure compatibility requirements that eliminate certain adhesive and ink combinations. Personal care and food packaging segments are responding with simplified material stacks and third-party certification investments.
Subscription box procurement models are compressing supplier qualification timelines. Beauty and meal kit services in the United States and United Kingdom are consolidating vendor bases around converters offering rapid prototyping and short-run flexibility. This channel rotation is most visible in zip-lock frosted formats where unboxing experience directly influences customer retention metrics.
Frosted Bag Market Segmentation
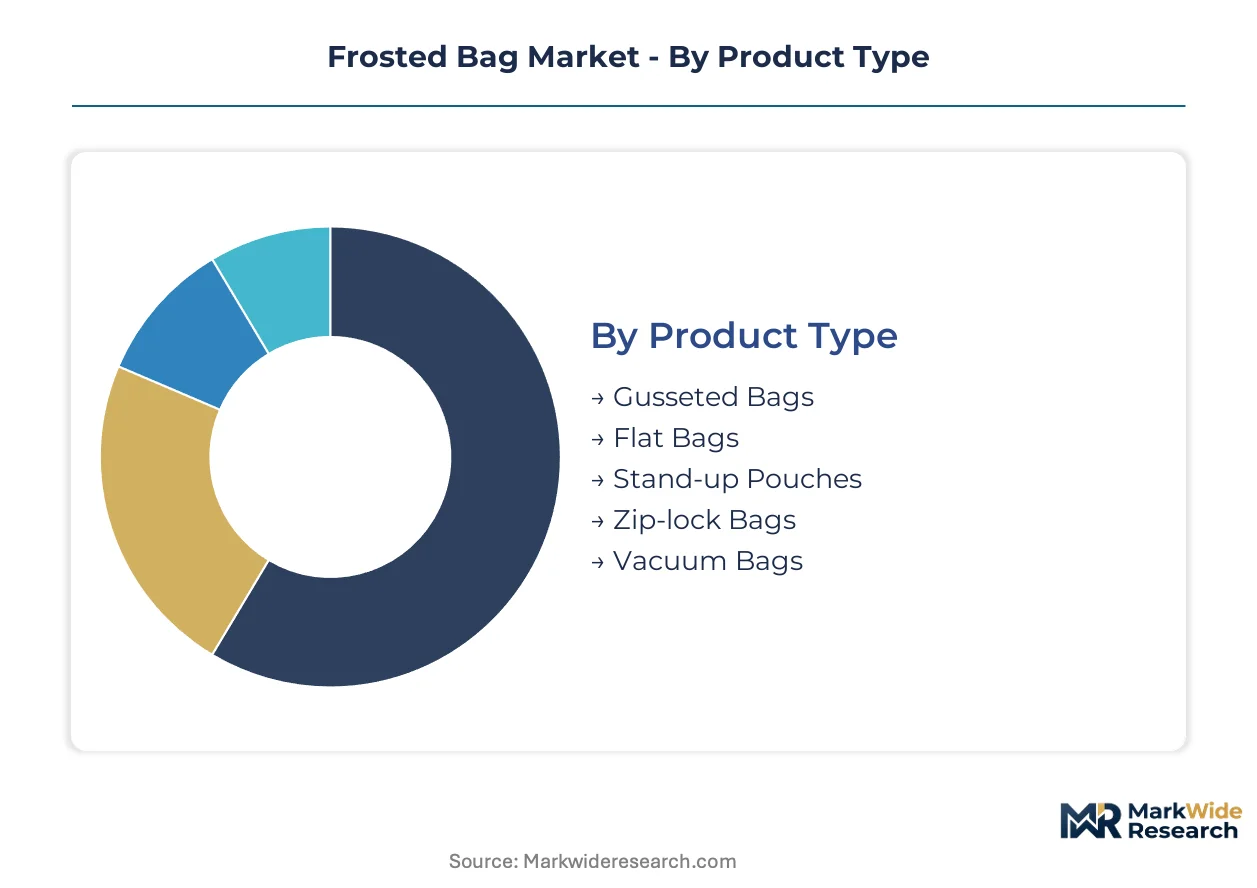
Segmentation in frosted bag markets reveals how regulatory pressure and end-use performance requirements split demand across material stacks and structural formats. Converters must align product development with specific channel compliance obligations rather than pursuing universal specifications.
Product Type:
Domestic consumption clusters around zip-lock and flat bag formats in North American club stores, while gusseted bags and stand-up pouches flow disproportionately to export-led specialty retail channels in Germany and France.
- Gusseted Bags:Side-folded constructions with expandable base panels provide dimensional stability for bulk dry goods presentation. German food processing clusters in Bavaria are accelerating procurement of recyclable mono-polyethylene gusseted formats to satisfy extended producer responsibility mandates.
- Stand-up Pouches:Bottom-gusseted structures with self-supporting bases command premium positioning in personal care and specialty food retail. French boutique cosmetic brands are consolidating supplier bases around converters offering rapid prototyping for unboxing-optimized formats.
- Zip-lock Bags:Resealable interlocking closure systems dominate repeat-use functionality in subscription meal kits and beauty boxes.
- Flat Bags:Two-dimensional sealed pouches serve cost-sensitive industrial and gift applications with minimal barrier requirements.
- Vacuum Bags:Hermetic multi-layer constructions with oxygen and moisture barriers protect semiconductor components during shipping.
Zip-lock bags hold the largest share; momentum sits with vacuum bags.
Material:
Cost tier stratification separates commodity polyethylene volumes from laminated film premiums, with regulatory compliance costs compressing mid-tier polypropylene positioning.
- Polyethylene:Blown and cast olefin films provide base substrates for light-diffusing additive dispersion. California SB 54 recyclability mandates are forcing brand owners toward simplified mono-PE stacks compatible with state-designated recycling infrastructure.
- Laminated Film:Multi-layer coextruded or adhesive-bonded constructions combine barrier polymers with aesthetic outer layers. EU Packaging and Packaging Waste Regulation targets are displacing laminated formats in German and French premium cosmetic applications.
- Polypropylene:Cast film clarity and stiffness properties suit high-temperature filling operations in food processing.
- Cellophane:Regenerated cellulose films offer biodegradable positioning for gift and confectionery segments with limited barrier demands.
- Kraft Paper:Uncoated and clay-coated paper stocks provide sustainable substrate alternatives for dry goods with minimal moisture sensitivity.
Polyethylene dominates volume; laminated film faces steepest displacement pressure.
Application:
Customer type differentiation separates specification-heavy industrial buyers from aesthetic-driven consumer brands, with channel concentration varying sharply by end-use.
- Food Packaging:Direct-contact formats require FDA 21 CFR 177.1520 compliance for olefin polymers or EFSA migration testing for European distribution. Specialty retailers in Germany are prioritizing surface-etched mono-PE constructions that satisfy both shelf presentation and recyclability certification requirements.
- Personal Care:Premium positioning demands drive specification for haptic surface finishes and precise opacity control. Mumbai and Delhi boutique cosmetic brands are accelerating premium packaging adoption as organized retail penetration expands.
- Electronics Protection:Hermetic barrier specifications protect semiconductors from moisture-induced oxidation during extended storage.
- Industrial Packaging:Functional containment priorities minimize unit costs for bulk component and subassembly shipment.
- Gift Wrapping:Seasonal demand volatility favors converters with short-run flexibility and rapid graphic changeover capability.
Food packaging anchors volume concentration; personal care commands premium margin pools.
Distribution Channel:
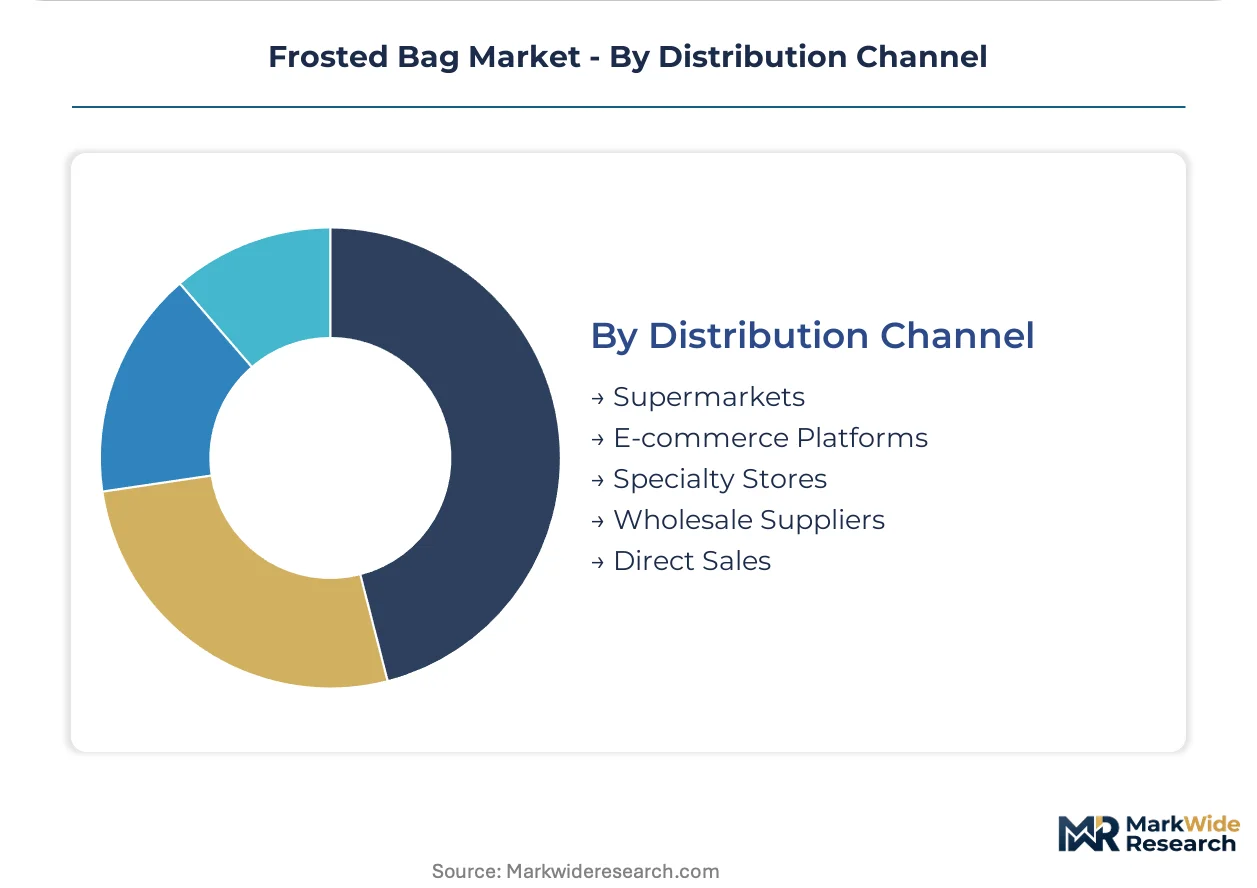
Volume throughput concentrates in wholesale and direct sales for industrial accounts, while margin extraction shifts toward specialty stores and e-commerce platforms with unboxing experience requirements.
- E-commerce Platforms:Direct-to-consumer fulfillment demands packaging that survives individual parcel shipment while delivering aesthetic opening moments. Subscription beauty and meal kit services in the United States and United Kingdom are compressing supplier qualification timelines around rapid prototyping capability.
- Specialty Stores:Curated retail environments amplify shelf differentiation investments for boutique brands. German and French specialty food retailers are specifying custom frosted formats with proprietary surface finishes to reinforce brand positioning.
- Supermarkets:Mass-market volume flows through centralized procurement with standardized specifications and extended payment terms.
- Wholesale Suppliers:Industrial and commercial buyers source through distributor networks with inventory pooling and technical support services.
- Direct Sales:Large-volume accounts bypass intermediaries to negotiate custom specifications and captive capacity arrangements.
Supermarkets and wholesale suppliers capture volume share; e-commerce platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese contract manufacturers in Guangdong and Zhejiang provinces supply laminated film capacity to European personal care distributors, while German converters pivot toward mono-polyethylene etching technology to satisfy EU Packaging and Packaging Waste Regulation mandates.
Germany
Extended producer responsibility frameworks under the EU Packaging and Packaging Waste Regulation are concentrating demand for recyclable frosted formats among food processing clusters in Bavaria and Baden-Württemberg. ECHA chemical safety registrations are accelerating substitution of legacy plasticizers with bio-based additives in frosted film formulations. Specialty retailers in Berlin and Hamburg are specifying custom surface finishes to reinforce brand positioning against mass-market alternatives.
United States
California's SB 54 extended producer responsibility requirements are forcing reformulation of laminated film constructions to meet state-designated recycling infrastructure compatibility. Subscription beauty boxes and meal kit services in Los Angeles and New York are compressing supplier qualification timelines around rapid prototyping capability. FDA 21 CFR 177.1520 compliance for olefin polymers remains mandatory for direct food contact applications nationwide.
China
Blown film capacity clusters in Guangdong and Zhejiang provinces dominate contract production for European and North American distributors seeking cost-optimized laminated film bags. The country's national packaging regulator is tightening material compliance requirements that reshape export-oriented converter strategies. Dongguan and Shenzhen manufacturing hubs are experiencing margin compression from resin input volatility and extended RecyClass certification timelines.
France
Boutique cosmetic brands in Paris and Lyon are consolidating supplier bases around converters offering rapid prototyping for unboxing-optimized formats. EU Packaging and Packaging Waste Regulation recyclability targets are displacing laminated formats in premium cosmetic applications. Surface-etched mono-polyethylene frosted bags are capturing shelf differentiation investments as compliance costs reshape procurement priorities.
India
Boutique cosmetic brands in Mumbai and Delhi are accelerating premium packaging adoption as organized retail penetration expands. BIS standards for plastic packaging materials are tightening quality specifications for imported film substrates. Maharashtra and Gujarat industrial corridors are attracting converter investments targeting domestic personal care and specialty food segments.
Frosted Bag Market Competitive Landscape
Listed leaders compete with private specialists across closure system technology and regional manufacturing footprint. The vendor base separates into three tiers: multinational consumer goods conglomerates with retail shelf presence, mid-scale contract manufacturers serving private label demand, and specialized converters focused on barrier film technology. Strategic archetypes include resealable closure innovators, scale-driven Asian fabricators, and compliance-focused European specialists. Capacity expansion and portfolio diversification toward mono-material formats represent the dominant competitive moves as regulatory pressure intensifies.
Within the multinational tier, SC Johnson anchors positioning through R&D intensity in resealable closure systems, while Ziploc leverages retail shelf presence to sustain volume leadership in zip-lock formats. Dongguan Pasike Packaging Co., Ltd. exemplifies the scale-driven contract manufacturing archetype, occupying a position within Guangdong province's blown film capacity cluster. These three entities represent the structural tension between brand-owned distribution control and outsourced production economics that defines competitive positioning across the analysis window.
| Leading Market Players |
|---|
| Ziploc |
| SC Johnson |
| Glad Products Company |
| Hefty |
| SynPack |
| Multi-Pak USA, Inc. |
| Reynolds |
| Dongguan Pasike Packaging Co., Ltd. |
| Minigrip |
| Others |
Supply & Pricing Matrix
Fourteen-to-eighteen-week lead times for RecyClass-certified mono-polyethylene frosted bags concentrate pricing power with Guangdong converters possessing in-house etching capability, while European buyers absorb premium markups for compliant formats that bypass laminated film disqualification under EU Packaging and Packaging Waste Regulation mandates.
Pricing Analysis
Surface-etched mono-PE technology commands a 15-25% premium over legacy laminated constructions, while conventional blown polyethylene occupies the cost-optimized tier for industrial buyers with minimal barrier requirements. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with California SB 54 recyclability compliance emerging as the dominant price differentiation driver. Pricing pressure stems from ethylene feedstock volatility and extended certification timelines that compress converter margins on small-batch specialty orders. Mass-market grocers exhibit highest price sensitivity, while German specialty food retailers and French boutique cosmetic brands absorb premiums for shelf-differentiated formats.
Supply Chain Analysis
Just-in-time inventory strategies dominate European and North American brand procurement, while Asian contract manufacturers maintain strategic resin stockpiles to buffer against ethylene and propylene price swings. Supply concentrates in China, Germany, and the United States, with blown film capacity clustering in Guangdong and Zhejiang provinces feeding European personal care distributors. Raw material dependencies center on polyethylene resin, bio-based additive formulations, and resealable closure components sourced from specialized Taiwanese and South Korean suppliers. Single-source vulnerability from Asian supply concentration creates geographic risk exposure for mid-tier converters lacking dual-sourcing arrangements. Distribution runs through wholesale supplier networks for industrial accounts and direct sales relationships for large-volume food processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation recyclability mandates are disrupting material selection economics, with mono-polyethylene surface etching technology collapsing the historical premium attached to laminated film constructions.
For Market Incumbents: Shield market position by accelerating backward integration into in-house polyethylene surface etching capability, eliminating dependence on imported laminated films disqualified under German extended producer responsibility frameworks. Prioritize captive capacity additions in Bavaria and Baden-Württemberg to serve food processing clusters with localized, certified supply. Defend against Asian contract manufacturer encroachment by embedding rapid prototyping services that compress qualification timelines for subscription box channels. For New Entrants and Emerging Players: Lead with mono-material innovation targeting mid-tier converters stranded between legacy laminated expertise and compliance-driven reformulation requirements. White-space exists in Indian personal care penetration, where Mumbai and Delhi boutique brands seek premium packaging partners as organized retail expands. Another entry vector sits with vacuum bag formats for semiconductor protection, where hermetic barrier reliability demands outpace incumbent converter specialization. Go-to-market should emphasize RecyClass certification bundling that accelerates buyer qualification. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with stranded laminated film assets requiring compliance-driven repositioning. Long-term viability over the next decade hinges on mono-material technology ownership and regional manufacturing footprint in regulated European markets. Acquisition candidates include mid-scale German converters with etching capability and established relationships with Bavarian food processors. Signal to watch: California SB 54 enforcement intensity and corresponding brand owner reformulation urgency crossing thresholds that trigger consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Technology Licensing | Etching process partnerships enable European converters to displace laminated film imports under EU recyclability mandates. |
| Backward Integration into Resin Compounding | In-house bio-based additive formulation secures REACH compliance and insulates margins from specialty chemical supplier pricing. |
| Regional Manufacturing Footprint Expansion | Bavaria and Baden-Württemberg capacity placement reduces logistics costs for German food processing clusters. |
| RecyClass Certification Fast-Track Program | Accelerated approval timelines capture subscription box procurement cycles compressing supplier qualification windows. |
| Direct-to-Consumer Channel Partnership | Beauty and meal kit service alliances secure volume commitments with unboxing-optimized format specifications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade association reports, and customs data, combining structured interviews with packaging converters, brand owner procurement leads, and retail category buyers with validation across ECHA chemical safety registrations, FDA 21 CFR 177.1520 compliance databases, and RecyClass certification records. Primary engagement spanned plant managers at blown film facilities, technical R&D directors developing surface etching processes, and supply chain planners at European personal care distributors. Secondary sources included EU Packaging and Packaging Waste Regulation implementation guidance, California SB 54 extended producer responsibility frameworks, and BIS plastic packaging standards. Bottom-up demand modeling triangulated against top-down macroeconomic indicators.
Segmentation dimensions modeled include product type, material stack, application end-use, and distribution channel, with additional granularity on regulatory compliance tier and geographic production cluster. Volume and value outputs reflect reconciliation across converter capacity assessments, brand owner procurement surveys, and channel inventory observations over the projection horizon. CAGRs derived from trend extrapolation of historical shipment data adjusted for regulatory inflection impacts and technology substitution curves. Industry-specific forecast inputs incorporated resin price elasticity coefficients and certification timeline distributions.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement, stable ethylene feedstock pricing, and continued Asian contract manufacturing access would require recalibration. Forecasts reflect assumptions regarding recyclability target implementation schedules and brand owner reformulation willingness. Revision becomes warranted when California SB 54 enforcement intensity or EU Packaging and Packaging Waste Regulation penalty structures cross thresholds that accelerate material substitution timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Child Resistant Bags Market
Bags and Containers
Bag Making Machine Market
Bags and Containers
Shopping Bag Market
Bags and Containers
PE Jumbo Bags Market
Bags and Containers
Flip-Up Vacuum Pack Market
Bags and Containers
Global Bubble Lined Courier Bag Market
Bags and Containers
Bin Liners Market
Bags and Containers
Hanging Bags Market
Bags and Containers
Conical Bags Packaging Market
Bags and Containers
Packaging Peanuts Market
Bags and Containers
Padding Bags Market
Bags and Containers
Clay Desiccant Bag Market
Bags and Containers
Trash Bags Market
Bags and Containers
Silicone Storage Bags Market
Bags and Containers
Foam Tube Mailer Market
Bags and Containers
Bag in Drum Market