
 Anti-Corrosion Bags Market | 2026-2036
Anti-Corrosion Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Corrosion Bags Market Outlook
Buyer concentration in the automotive supply chain is recalibrating procurement patterns across the anti-corrosion packaging sector. Tier-1 suppliers now consolidate vendor lists, favoring partners with validated VCI chemistries and ISO-certified production lines. Cortec Corporation leverages its proprietary migrating corrosion inhibitor technology to anchor long-term contracts with North American automotive OEMs. Daubert Cromwell competes through specialized foil-laminate barrier films designed for extended outdoor storage of machined components.
Anti-corrosion bags are engineered barrier packaging systems incorporating volatile corrosion inhibitors or metalized film layers to create a protective microenvironment around ferrous and non-ferrous metal surfaces, typically maintaining humidity below 40% RH within sealed enclosures. The manufacturing process involves co-extrusion of polyethylene substrates with vapor-phase corrosion inhibitors or aluminum oxide vapor deposition onto polyester films to achieve oxygen transmission rates below 0.1 cc/m²/day. VCI bags command the largest share among product types due to their compatibility with automated packaging lines and minimal residue requirements for precision electronics. Marine components represent the fastest-growing application segment as offshore wind infrastructure expands and salt-exposure protection standards tighten for sub-assembly transit.
EPA regulations under the Toxic Substances Control Act govern VCI chemical formulations in the United States, while REACH restrictions in Europe limit certain amine-based corrosion inhibitors, compelling reformulation investments across the supply base. BIS certification requirements in India mandate migration testing for metal-contact packaging used in precision engineering exports, creating compliance barriers for uncertified imports. Stakeholders must monitor evolving substance restrictions across multiple jurisdictions while building regional formulation capabilities to maintain uninterrupted market access.
Market Dynamics
Tier-1 automotive suppliers are consolidating vendor lists around validated VCI chemistries and ISO-certified production lines, compressing the supplier base while elevating technical compliance barriers for market entry.
Growth Catalysts
- REACH amine restrictions:European reformulation mandates are accelerating migration toward nitrite-free and primary amine-free VCI chemistries, creating replacement cycles across existing installed base.
- Offshore wind sub-assembly logistics:Salt-exposure protection standards for marine component transit are tightening as floating wind platforms multiply, expanding specification-grade bag demand.
- Automated packaging line compatibility:VCI film heat-sealing speeds below 0.5 seconds per unit are enabling throughput gains at German and Chinese precision component facilities.
Market Restraints
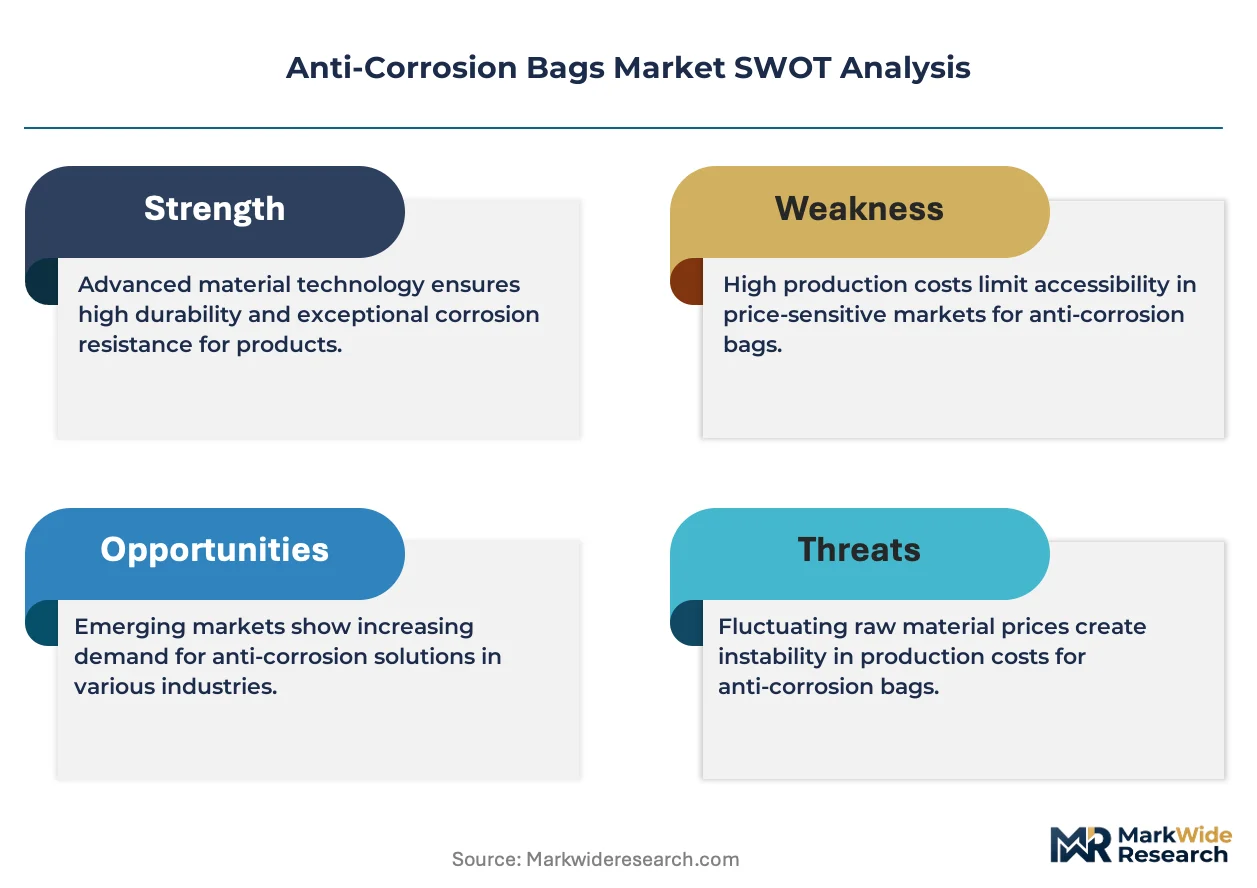
- Ethylene-vinyl acetate resin volatility:Co-extrusion substrate costs fluctuate with petrochemical feedstock pricing, compressing margin stability for mid-volume converters.
- Aluminum oxide deposition equipment concentration:Vapor deposition chambers for ultra-barrier films cluster with Korean and Japanese equipment suppliers, creating capex bottlenecks.
- Biodegradable film performance gap:Starch-based alternatives fail humidity suppression below 40% RH, limiting substitution in precision electronics applications.
Strategic Opportunities
- India precision engineering export corridor:BIS certification requirements for metal-contact packaging create captive demand for locally formulated VCI products.
- Pharmaceutical cold chain convergence:Temperature-stable VCI laminates combining corrosion inhibition with thermal insulation address biologics shipping requirements.
- Extended producer responsibility frameworks:EU packaging waste directives incentivize mono-material recyclable barrier designs over multi-layer laminates.
Industry Challenges
- Migration testing laboratory capacity:ISO 9227 salt spray validation queues extend 8-12 weeks at accredited European facilities, delaying product qualification timelines.
- Legacy ERP integration with batch traceability:VCI concentration logging requirements demand shop-floor system upgrades at small and mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Corrosion Bags Market |
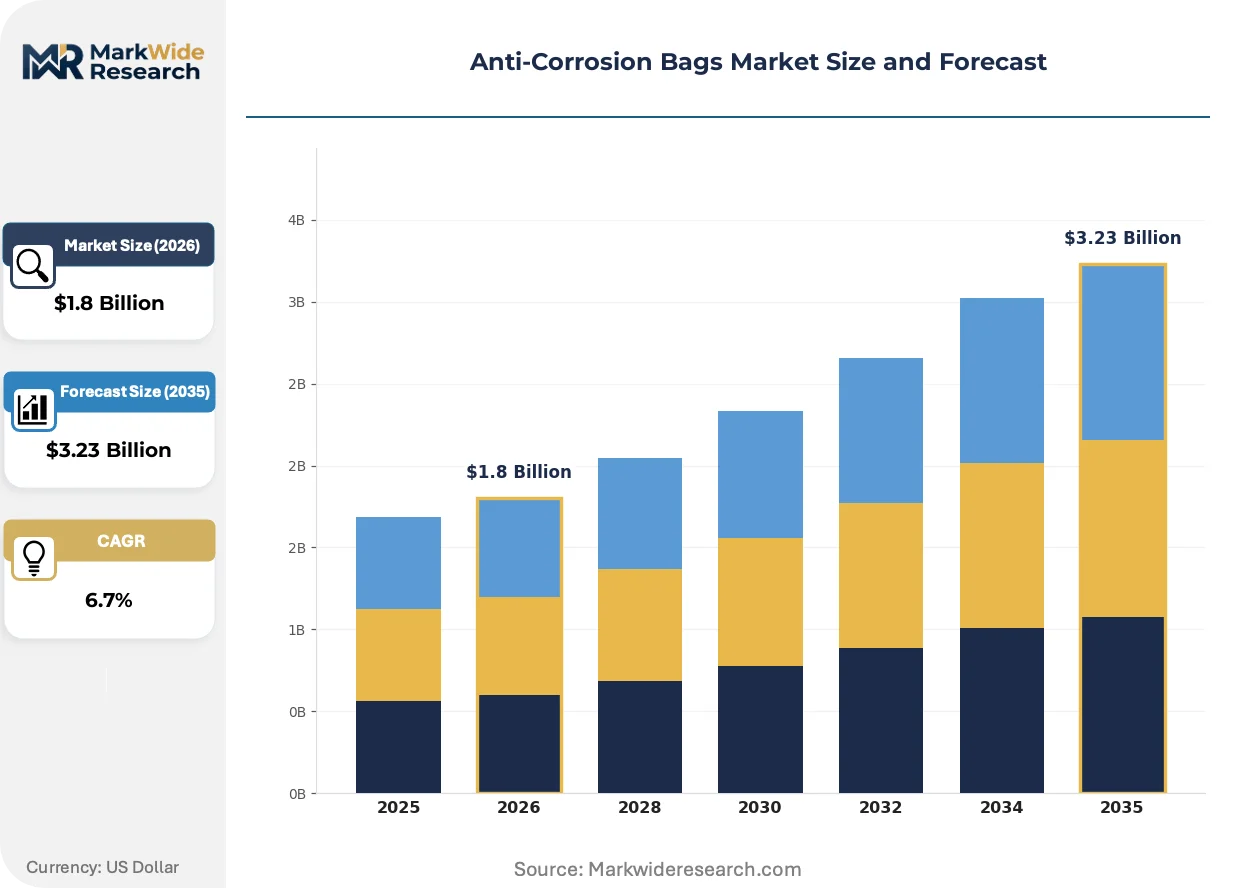
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
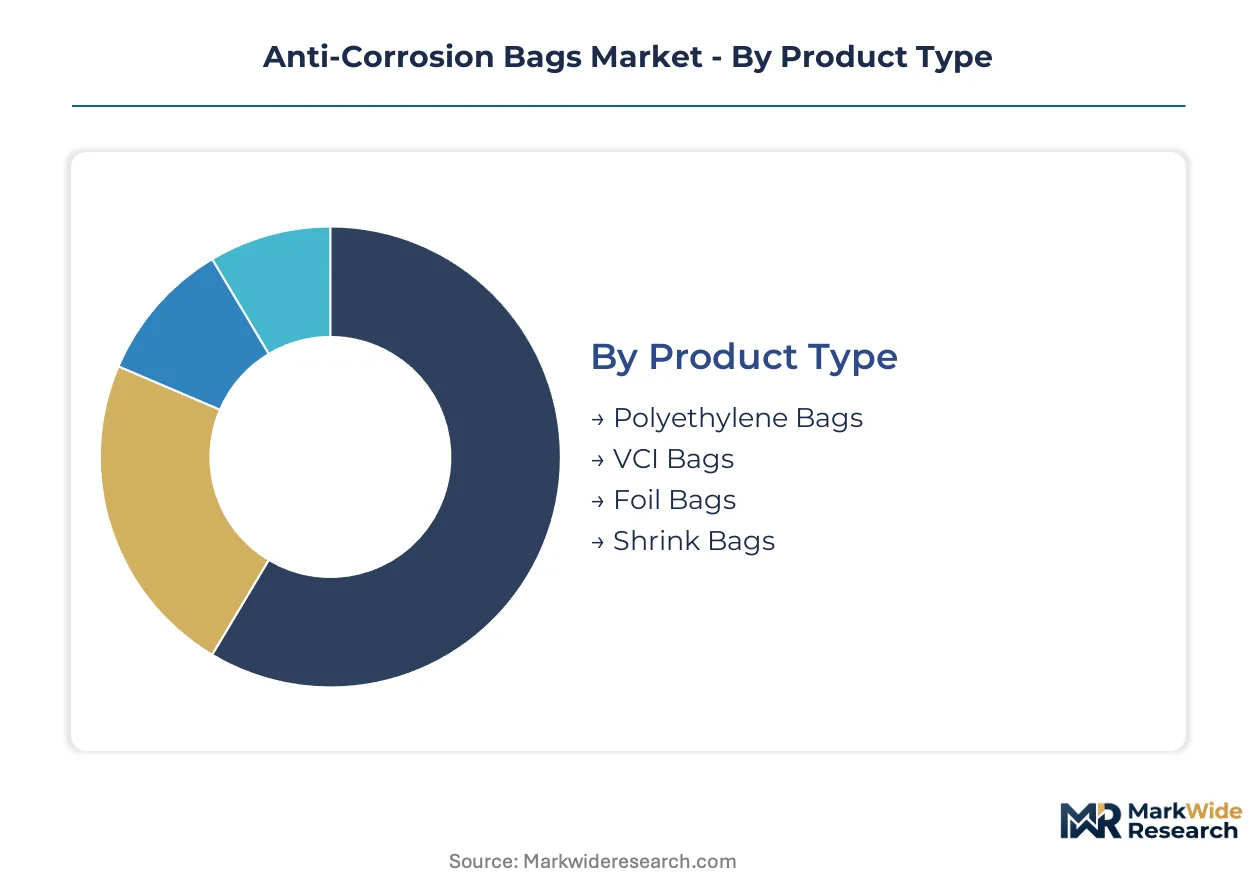
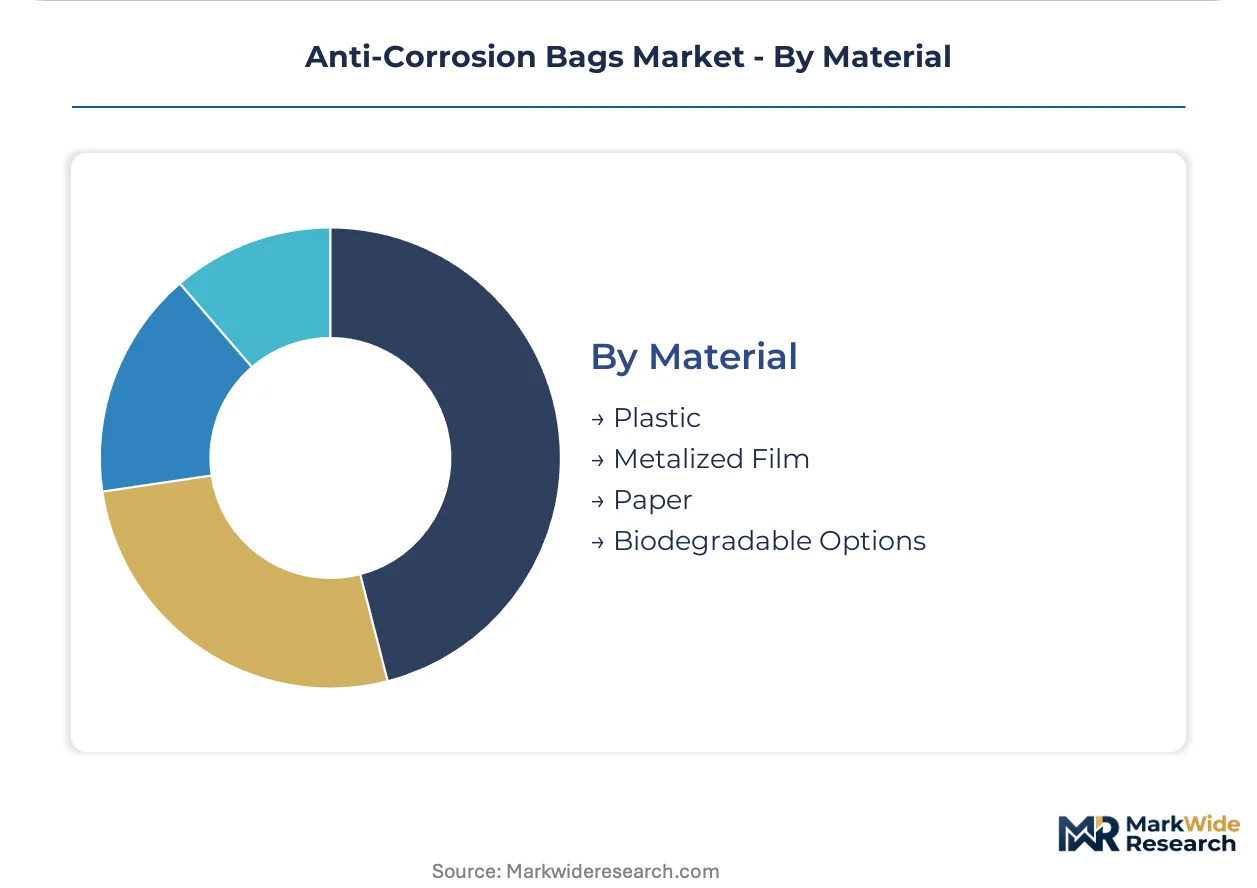
| Segmentation | Product Type: Polyethylene Bags, VCI Bags, Foil Bags, Shrink Bags Application: Industrial Packaging, Automotive Parts, Electronics, Marine Components End User: Manufacturers, Distributors, Retailers, Exporters Material: Plastic, Metalized Film, Paper, Biodegradable Options |
| Companies Covered | EXCOR, Armor Protective Packaging, Cortec Corporation, Daubert Cromwell, Green Packaging, Polyplus Packaging, BENZ Packaging, Zerust, Northern Technologies International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Corrosion Bags Market Strategic Shifts
Active material science advances and regulatory chemistry restrictions are converging to reshape barrier packaging specifications across precision manufacturing supply chains.
Multi-layer co-extrusion with embedded vapor-phase corrosion inhibitors is consolidating technical standards around nitrite-free amine salt formulations. Automotive OEMs in the US Great Lakes region and Germany's industrial belt specify these chemistries for transmission component transit. The technology is consolidating supplier tiers by disqualifying converters lacking in-house compounding capabilities.
REACH restrictions on cyclohexylamine and dicyclohexylamine nitrites are forcing systematic reformulation across European VCI supply chains. Manufacturers must resubmit safety data sheets and migration profiles for previously grandfathered chemistries. Marine component suppliers face the steepest compliance burden as salt-spray performance standards tighten simultaneously.
Specification-driven vendor consolidation is compressing approved supplier lists at tier-1 automotive and aerospace buyers. Long-term framework agreements with validated chemistry portfolios are displacing spot purchasing through distributors. This pattern is most pronounced in Germany, where OEMs integrate VCI qualification into IATF 16949 supplier audits.
Anti-Corrosion Bags Market Segmentation
Anti-corrosion bag specifications diverge sharply across end-use environments, from automated automotive lines demanding heat-seal compatibility to marine logistics requiring extended salt-spray protection. Material chemistry and barrier architecture determine qualification status at tier-1 buyers, making segment-level technical compliance a commercial gatekeeper.
Product Type:
Volume production concentrates in commodity polyethylene substrates, while premium positioning attaches to engineered vapor-phase inhibitor systems and ultra-barrier laminates.
- VCI Bags:Co-extruded polyethylene films impregnated with volatile corrosion inhibitors that vaporize to form protective molecular layers on metal surfaces. Demand concentrates at German automotive OEMs and China's eastern manufacturing corridor, where automated packaging lines require heat-seal cycles below 0.5 seconds per unit. REACH amine restrictions are forcing systematic reformulation toward nitrite-free chemistries.
- Foil Bags:Multi-layer laminates incorporating aluminum oxide vapor-deposited polyester films achieving oxygen transmission rates below 0.1 cc/m²/day. Procurement is expanding for offshore wind sub-assembly transit, where salt-exposure protection standards are tightening for floating platform components. Equipment concentration with Korean and Japanese vapor deposition suppliers creates capex bottlenecks for new entrants.
- Polyethylene Bags:Standard co-extruded barrier films without active corrosion inhibitors, serving cost-sensitive short-term storage applications in general industrial packaging.
- Shrink Bags:Heat-shrinkable polyethylene formulations conforming tightly to irregular component geometries, common in bundling applications for machined parts distribution.
Mature deployment sits with Polyethylene Bags in general industrial logistics. Newer deployment is concentrated in Foil Bags for specification-grade marine and aerospace applications.
Application:
End-use segmentation tracks directly against corrosion risk severity, from controlled factory environments to salt-laden maritime supply chains.
- Automotive Parts:Precision transmission and engine components requiring VCI protection through multi-modal transit to assembly plants. Tier-1 suppliers in the US Great Lakes region and Germany's industrial belt specify validated chemistries integrated into IATF 16949 supplier audits. Vendor list consolidation is compressing approved supplier bases around ISO-certified production lines.
- Marine Components:Offshore wind sub-assemblies and shipboard equipment facing extended salt-spray exposure during floating platform construction logistics. This segment is expanding most quickly as floating wind installations multiply and salt-exposure protection standards tighten for sub-assembly transit.
- Industrial Packaging:General machinery and metal fabrication storage applications, representing high-volume but lower-specification demand.
- Electronics:Precision circuit boards and semiconductor components requiring humidity suppression below 40% RH with zero VCI residue.
Procurement maturity clusters in Industrial Packaging for legacy metal fabrication. Specification intensity is highest in Automotive Parts, where chemistry validation gates long-term framework agreements.
End User:
Channel structure determines technical support requirements and batch traceability obligations, from direct OEM relationships to distributor spot purchasing.
- Manufacturers:Tier-1 automotive and aerospace OEMs with in-house packaging engineering teams specifying custom VCI formulations and demanding full batch traceability.
- Distributors:Industrial supply intermediaries serving mid-tier metal fabricators with standard catalog products and technical specification support.
- Exporters:Precision engineering firms in India's export corridor requiring BIS-certified metal-contact packaging for international shipment compliance.
- Retailers:Limited presence in consumer-facing hardware and tool protection, primarily standard polyethylene barrier products.
Direct technical engagement concentrates with Manufacturers. Compliance-driven specification is expanding fastest among Exporters facing destination-country certification requirements.
Material:
Substrate selection balances barrier performance against end-of-life regulatory pressure, particularly EU packaging waste directives favoring mono-material designs.
- Plastic:Dominant polyethylene and ethylene-vinyl acetate co-extrusions, subject to petrochemical feedstock cost volatility compressing converter margins.
- Metalized Film:Aluminum oxide vapor-deposited polyester achieving ultra-low oxygen and moisture transmission for extended outdoor storage applications.
- Paper:VCI-impregnated kraft formulations for environmentally positioned packaging, with performance limitations in high-humidity environments.
- Biodegradable Options:Starch-based alternatives failing humidity suppression below 40% RH, limiting substitution in precision electronics despite regulatory pressure.
Performance-critical deployment remains with Metalized Film for specification-grade applications. Regulatory momentum is pushing development investment toward Biodegradable Options, though technical performance gaps persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for anti-corrosion bags clusters in three industrial corridors where precision manufacturing and export logistics intersect. Germany's automotive belt, China's eastern manufacturing zone, and the United States Great Lakes region concentrate procurement volumes and specification authority.
United States
Automotive OEMs in Michigan and Ohio specify validated VCI chemistries for transmission component transit through IATF 16949 supplier audits. EPA regulations under the Toxic Substances Control Act govern formulation compliance, compelling reformulation investments for amine-based inhibitors. Tier-1 suppliers in the Great Lakes automotive region are consolidating vendor lists around ISO-certified production lines with full batch traceability.
Germany
Precision engineering exports from Bavaria and Baden-Württemberg drive specification-grade foil bag demand for extended outdoor storage. REACH restrictions on cyclohexylamine and dicyclohexylamine nitrites force systematic chemistry reformulation across the supply base. Stuttgart's automotive engineering cluster integrates VCI qualification directly into supplier development programs.
China
Eastern manufacturing corridors in Jiangsu and Zhejiang provinces deploy automated packaging lines requiring heat-seal cycles below 0.5 seconds per unit. MIIT standards and evolving GB standards for industrial packaging create compliance frameworks for metal-contact materials. Shanghai's precision component export hub is expanding procurement of nitrite-free VCI formulations for European-bound shipments.
India
Precision engineering exporters in Maharashtra and Gujarat require BIS-certified metal-contact packaging for international compliance. BIS certification mandates migration testing, creating captive demand for locally formulated VCI products. Pune's automotive component cluster is driving vendor qualification programs for validated corrosion inhibitor systems.
South Korea
Shipbuilding and offshore wind equipment manufacturers in Busan-Ulsan specify ultra-barrier foil bags for salt-exposure protection during floating platform construction. MFDS and industrial standards govern packaging material safety for precision component exports. Gyeongnam's marine engineering cluster is tightening transit protection specifications for sub-assembly logistics.
Anti-Corrosion Bags Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized barrier technologies and regional certification capabilities. The market structure compresses around validated chemistry portfolios and ISO-certified production infrastructure. Three archetypes dominate: integrated compounders with in-house VCI formulation, specialized converters of ultra-barrier laminates, and regional certification specialists serving export corridors. Competitive moves center on chemistry reformulation investments for REACH compliance and strategic partnerships with automotive OEMs for long-term framework agreements.
Among North American chemistry-integrated players, Cortec Corporation anchors the proprietary technology tier, while Daubert Cromwell exemplifies specialized barrier film positioning. European compounders including EXCOR occupy the reformulation-responsive segment addressing amine-free mandates. These three represent distinct competitive postures: technology licensing leverage, specification-grade laminate expertise, and regulatory-adaptive formulation capabilities respectively.
| Leading Market Players |
|---|
| EXCOR |
| Armor Protective Packaging |
| Cortec Corporation |
| Daubert Cromwell |
| Green Packaging |
| Polyplus Packaging |
| BENZ Packaging |
| Zerust |
| Northern Technologies International Corporation |
| Others |
Value Chain & Pricing Dynamics
Specification-grade certification tiers separate validated VCI compounders from commodity polyethylene converters, with REACH-compliant nitrite-free formulations commanding premium positioning while standard co-extruded bags compete on throughput scale. This bifurcation concentrates margin capture among German and US automotive belt suppliers with in-house chemistry capabilities, while forcing price-sensitive general industrial buyers toward distributor channels with limited technical support.
Pricing Analysis
Volume production of standard polyethylene bags generates thin margins vulnerable to ethylene-vinyl acetate resin volatility, while premium VCI laminates sustain pricing power through chemistry validation and IATF 16949 certification requirements. Price differentiation hinges on REACH compliance status and heat-seal speed performance below 0.5 seconds per unit. Cost compression in commodity tiers is intensifying as petrochemical feedstock fluctuations squeeze converter margins. Tier-1 automotive OEMs exhibit lowest price sensitivity due to framework agreement structures, whereas general industrial distributors face acute pressure from spot-purchasing metal fabricators.
Supply Chain Analysis
Workforce availability constraints in Jiangsu and Zhejiang provinces are elevating labor costs for automated packaging line operations serving China's precision component export hub. Manufacturing gravity centers on Germany, China, and the United States, with vapor deposition equipment for ultra-barrier films clustering among Korean and Japanese suppliers. Raw material dependencies include ethylene-vinyl acetate resins, aluminum oxide deposition targets, and proprietary amine salt formulations. Single-source vulnerability sits with vapor deposition chamber suppliers, constraining capacity expansion for foil-laminate converters. Distribution runs through direct OEM relationships for specification-grade volumes and industrial distributors for catalog products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-corrosion bags market is becoming a vertical-integration race as compounders pursue captive control over VCI formulation and batch traceability systems to lock in tier-1 automotive qualification status.
For Market Incumbents: Lock in long-term framework agreements with German and US Great Lakes automotive OEMs by accelerating nitrite-free chemistry reformulation ahead of REACH enforcement waves. Prioritize backward integration into ethylene-vinyl acetate compounding to defend margin position against petrochemical volatility. Incumbent compounders must also secure ISO 17025-accredited migration testing partnerships to circumvent 8-12 week validation queues at European laboratories. For New Entrants and Emerging Players: E-commerce platforms serving mid-tier Indian precision engineering exporters represent the most penetrable white-space channel, as BIS certification requirements create compliance barriers for uncertified imports. Target Maharashtra and Gujarat export corridors with locally formulated VCI products and BIS-certified production partnerships. A technical specification support model bundled with certification consulting offers differentiation against commodity distributors. For Investors and Strategic Acquirers: Re-rating potential sits with regional certification specialists given tightening substance restrictions across multiple jurisdictions and captive demand from export-corridor manufacturers. Five-to-ten year viability favors compounders with validated chemistry portfolios and in-house migration testing capabilities. The signal to watch is REACH expansion of amine restrictions beyond cyclohexylamine derivatives, which would accelerate replacement cycles and consolidate supplier tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VCI Chemistry | In-house formulation capabilities satisfy REACH amine restrictions and anchor tier-1 automotive contracts. |
| ISO 17025 Migration Testing Accreditation | Captive validation capacity circumvents European laboratory bottlenecks and accelerates product qualification timelines. |
| BIS Certification Partnership in India | Local compliance infrastructure unlocks Maharashtra and Gujarat precision engineering export corridors. |
| Nitrite-Free Formulation R&D Investment | Primary amine-free chemistry development aligns with evolving ECHA restrictions and grandfathered product replacement cycles. |
| Mono-Material Recyclable Barrier Design | EU packaging waste directive compliance positions converters for extended producer responsibility frameworks. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with VCI compounders, automotive tier-1 procurement directors, industrial packaging distributors, and BIS certification laboratory managers. ECHA substance restriction databases, EPA TSCA chemical inventories, and MIIT industrial packaging standards provided regulatory boundary conditions. Bottom-up modeling of converter capacity and top-down demand triangulation from automotive production clusters validated volume estimates.
Segmentation-level granularity modeled product type chemistry, application corrosion risk severity, end-user channel structure, and material substrate performance across the projection horizon. CAGRs derived from regression analysis of historical procurement patterns and regulatory-driven replacement cycle assumptions. Forecast inputs incorporated offshore wind installation trajectories, REACH amine restriction implementation timelines, and automated packaging line penetration rates at precision component facilities.
The model holds under stable petrochemical feedstock pricing and incremental regulatory tightening; deviation in abrupt resin cost spikes or accelerated ECHA substance bans would shift competitive positioning toward integrated compounders. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bulk Tote Dumpers Market
Bags and Containers
Bags and Containers Market
Bags and Containers
Bag-On-Valve Laminates Market
Bags and Containers
Non-Barrier Bag Market
Bags and Containers
Loose-Fill Peanuts Market
Bags and Containers
Drum Liners Market
Bags and Containers
Piping Bags Market
Bags and Containers
Handle Gusseted Bags Market
Bags and Containers
Net Bags Market
Bags and Containers
Hermetic Storage Bags Market
Bags and Containers
Compression Baggers Market
Bags and Containers
Self-Sealing Ziplock Bags Market
Bags and Containers
Block Sack Market
Bags and Containers
Wooden Boxes Market
Bags and Containers
Self-Sealed Bubble Bags Market
Bags and Containers
Heat Sealing Bags Market