
 Hermetic Storage Bags Market | 2026-2036
Hermetic Storage Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Hermetic Storage Bags Market Insights
Specialized polymer compounding expertise is unwinding capacity bottlenecks across the hermetic storage bags supply base. GrainPro leverages vertical integration into multilayer film extrusion to secure barrier consistency for coffee and cocoa exporters. GreenPak sustains technology leadership in high-barrier metallized laminates for pharmaceutical cold chain applications. Ecotact dominates the South Asian grain preservation segment through localized manufacturing and direct farmer engagement programs.
Hermetic storage bags are engineered multilayer flexible containers designed to achieve near-zero gas exchange through heat-sealed closures and coextruded barrier films, typically incorporating polyethylene tie layers with metallized or nylon cores to maintain oxygen transmission rates below specified thresholds. Their primary commercial purpose is to extend shelf stability of moisture-sensitive and oxidation-prone commodities across ambient storage conditions. Vacuum seal bags and stand-up pouches anchor the product portfolio, with metallized film variants capturing disproportionate margin pools due to technical complexity in sputter deposition and lamination. Food preservation applications lead volume demand while pharmaceutical storage commands premium pricing through compliance with stringent extractables and leachables protocols.
The EU's Packaging and Packaging Waste Regulation and REACH chemical restrictions are reshaping material specifications for food-contact and pharmaceutical-grade hermetic bags, driving substitution toward recycle-ready mono-material structures. India's BIS certification requirements for food packaging plastics and the FDA's 21 CFR 177.1520 compliance standards for polyethylene resins create layered compliance obligations that filter supplier participation. Stakeholders must monitor evolving extended producer responsibility frameworks and migration testing protocols to anticipate specification shifts before they disrupt qualification timelines.
Market Dynamics
Material science breakthroughs in coextruded barrier films are compressing oxygen transmission thresholds below 0.1 cc/m²/day, forcing converters to retool extrusion lines or exit premium pharmaceutical and specialty coffee segments entirely.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Migration limit tightening for food-contact plastics is accelerating converter investment in multilayer metallized film capacity across German and Italian processing corridors.
- Pharmaceutical cold chain expansion:Temperature-sensitive biologics distribution is pulling hermetic bag specifications toward ultra-high-barrier laminates with validated seal integrity protocols.
- India's grain belt states:Post-harvest loss reduction mandates from FSSAI and state agricultural departments are driving hermetic adoption among rice and wheat cooperatives in Punjab, Haryana, and Uttar Pradesh.
Market Restraints
- Aluminum and ethylene-vinyl alcohol resin volatility:Sputter deposition feedstock costs swing 15-40% quarterly, squeezing margin on metallized film variants.
- Specialized extrusion equipment concentration:Nine-layer blown film lines are captive to three European and two Japanese machinery suppliers, creating 18-month delivery backlogs.
- Competing modified atmosphere packaging:Rigid container and tray-sealer systems are capturing premium protein and ready-meal applications where hermetic bags once dominated.
Strategic Opportunities
- Nigeria's cocoa processing corridor:Bean-to-bar traceability requirements from European buyers are creating first-mover advantage for hermetic exporters with localized sealing service networks.
- Recycle-ready mono-material structures:EU Green Deal circular economy mandates are opening design space for polyethylene-only hermetic bags that maintain barrier performance without metallization.
- Direct-to-farmer digital channels:Mobile-enabled agritech platforms in South Asia are disintermediating traditional distributor networks for hermetic grain storage kits.
Industry Challenges
- Multilayer lamination technician scarcity:Adhesiveless extrusion lamination and solventless curing expertise is concentrated among aging workforces in Northern Italy and Osaka prefecture.
- FDA 21 CFR 177.1520 extractables validation:Polyethylene resin qualification timelines stretch 14-22 months, freezing formulation changes mid-development cycle.
- Legacy warehouse management system integration:Hermetic bag serialization and seal-integrity data logging require middleware development that most agricultural cooperatives lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hermetic Storage Bags Market |
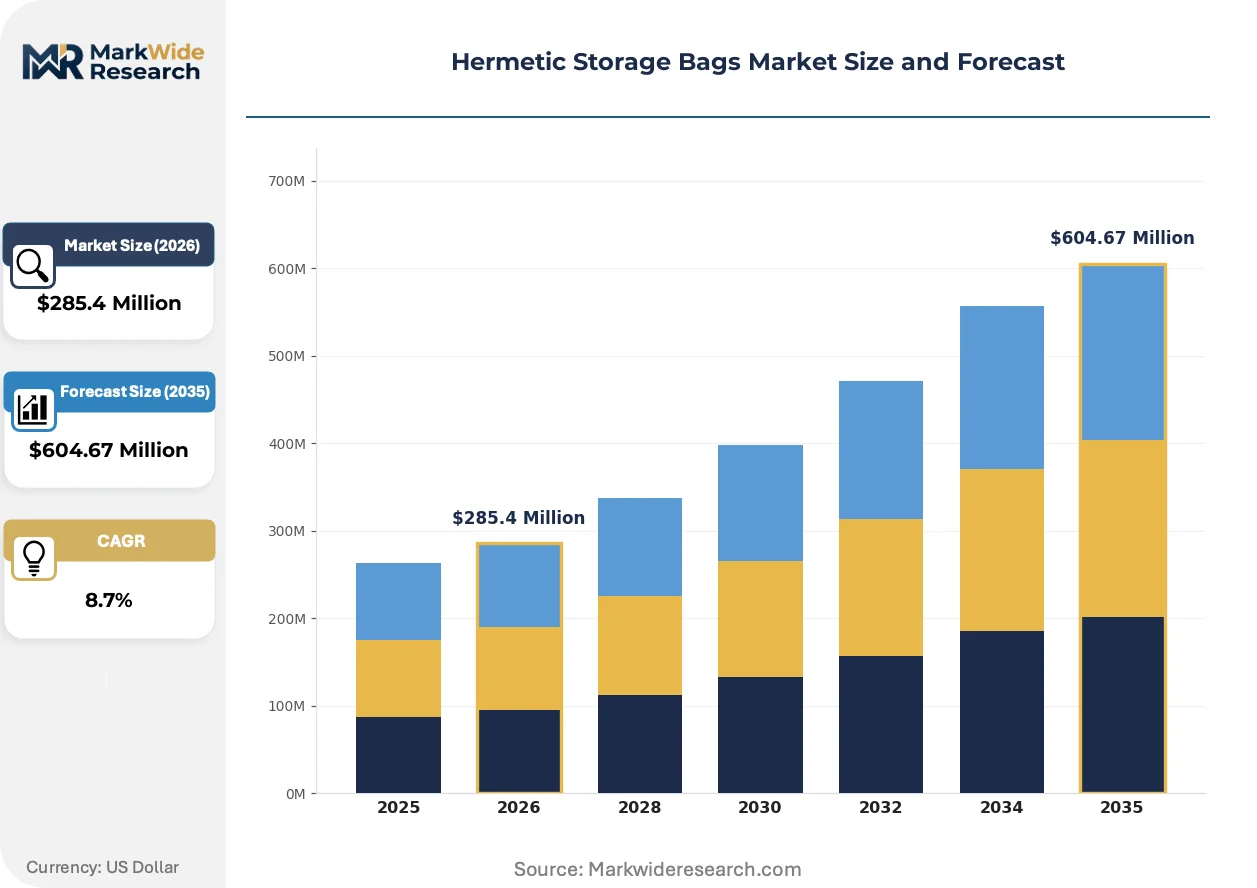
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Seal Bags, Zip Lock Bags, Stand-Up Pouches, Gusseted Bags Material: Polyethylene, Polypropylene, Nylon, Metallized Film Application: Food Preservation, Pharmaceutical Storage, Chemical Containment, Electronic Component Packaging End User: Food Processing Firms, Pharmaceutical Manufacturers, Chemical Producers, Electronics Assemblers |
| Companies Covered | Sesi Technologies, AgroZ, GrainPro, GreenPak, Elite Innovations, Ecotact, Rishi FIBC, Supreme, Storezo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hermetic Storage Bags Market Trends and Innovations
Active barrier technologies and smart packaging integration are redefining performance benchmarks, while regulatory chemistry restrictions are accelerating material substitution cycles beyond historical resin qualification timelines.
Nano-clay reinforced polyethylene tie layers are miniaturizing effective barrier thickness from 12-micron metallized cores to 3-micron hybrid structures without oxygen permeability degradation. Specialty coffee exporters in Colombia and Ethiopia are piloting these laminates for containerized ocean freight. The technology is miniaturizing capital requirements for regional converters, enabling mid-scale entrants to compete on pharmaceutical-grade specifications previously captive to multinationals.
REACH chemical restrictions on per- and polyfluoroalkyl substances are banning fluoropolymer coatings used in high-barrier hermetic seals, forcing adhesive reformulation across EU-serving production lines. German and Dutch converters are accelerating bio-based hot-melt development to maintain seal strength at reduced activation temperatures. Pharmaceutical cold chain applications face the steepest compliance cliff, with 18-month transition windows compressing validation schedules.
Consolidated buying by Indian food processing conglomerates is displacing fragmented procurement through village-level agricultural input dealers. Direct contracting for hermetic grain storage volumes now covers 60% of Maharashtra and Karnataka rice miller demand, with specifications negotiated at headquarters rather than field level. This concentration is most visible in the basmati export corridor, where three processors dictate barrier film standards across their supplier bases.
Hermetic Storage Bags Market Segmentation
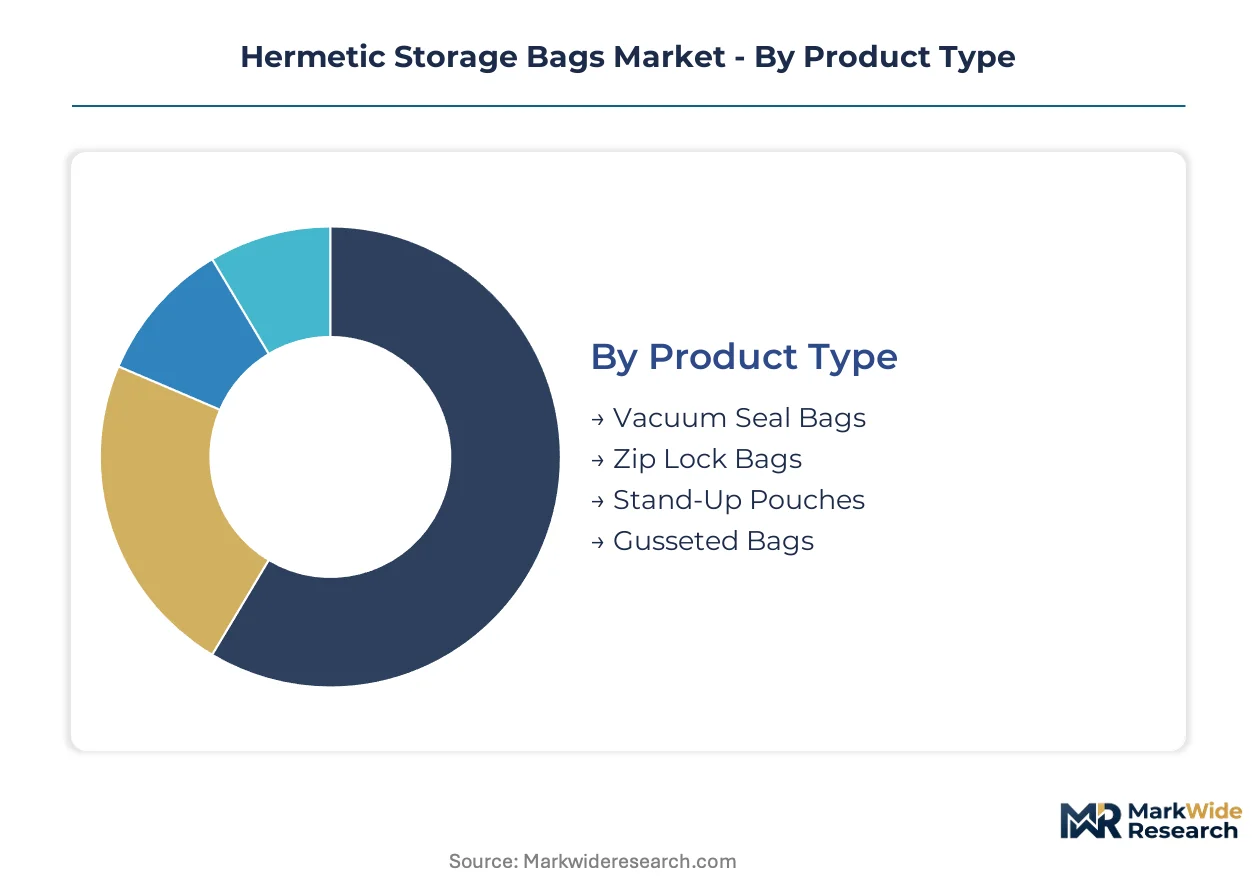
Hermetic storage bag specifications diverge sharply across regulatory jurisdictions, with FDA 21 CFR 177.1520 compliance separating pharmaceutical-grade laminates from commodity food packaging. Material selection and barrier architecture directly determine qualification timelines and end-market access.
Product Type:
REACH chemical restrictions and FDA migration limits create divergent specification pathways for each format.
- Vacuum Seal Bags:Multi-layer coextruded structures with metallized or aluminum oxide-coated cores achieve oxygen transmission rates below 0.1 cc/m²/day. Demand concentrates in pharmaceutical cold chain distribution for temperature-sensitive biologics, where EMA validation protocols require documented seal integrity across transport temperature excursions.
- Stand-Up Pouches:Gusseted bottom configurations with resealable zipper closures incorporate nine-layer blown film barriers for ambient shelf stability. Indian basmati rice exporters in Punjab and Haryana are adopting these formats for direct-to-retail packaging, driven by FSSAI post-harvest loss reduction mandates.
- Zip Lock Bags:Interlocking polyethylene tracks with silicone gaskets provide repeatable access for laboratory and clinical settings.
- Gusseted Bags:Side-folded geometries expand cubic capacity for bulk grain and cocoa bean storage; Nigerian processors favor these for traceability-compliant exports to European buyers.
Established volume favors vacuum seal configurations; emerging adoption favors stand-up pouches with integrated reseal features.
Material:
Cost tiers stratify around barrier performance thresholds and resin qualification burden.
- Metallized Film:Sputter-deposited aluminum layers on polyethylene terephthalate substrates deliver the highest barrier performance. German and Italian converters dominate capacity, though aluminum feedstock volatility squeezes margins unpredictably.
- Polyethylene:Linear low-density and high-density grades constitute the volume base, with BIS certification requirements in India and FDA 177.1520 compliance in the US creating dual qualification tracks for exporters.
- Nylon:Polyamide tie layers provide puncture resistance and mechanical strength for abrasive agricultural commodities.
- Polypropylene:Cast and oriented films offer clarity and stiffness for retail-facing applications; lower barrier performance limits penetration in pharmaceutical segments.
Premium-mid-economy pricing differentiation separates metallized pharmaceutical grades from commodity polyethylene food packaging.
Application:
Customer type determines compliance intensity and contract duration.
- Food Preservation:Oxygen and moisture barrier specifications vary by commodity sensitivity—coffee and cocoa require sub-1 cc/m²/day transmission rates, while cereal grains tolerate higher thresholds. Southeast Asian and Indian grain belt adoption is climbing fastest among agricultural cooperatives.
- Pharmaceutical Storage:Extractables and leachables testing under USP <661> and EMA guidelines extends qualification to 22 months. Cold chain biologics distribution is pulling specifications toward ultra-high-barrier laminates with validated thermal stability.
- Chemical Containment:UN-certified designs for hazardous material transport require burst strength validation and chemical compatibility documentation.
- Electronic Component Packaging:Moisture vapor transmission rate specifications below 0.001 g/m²/day protect semiconductors from humidity-induced corrosion during ocean freight.
Food preservation commands volume share; pharmaceutical storage captures margin concentration.
End User:
Procurement centralization is reshaping supplier relationships across buyer categories.
- Food Processing Firms:Consolidated buying by Indian conglomerates in Maharashtra and Karnataka now covers 60% of hermetic grain storage demand, with headquarters-level specification setting displacing fragmented village-level procurement.
- Pharmaceutical Manufacturers:Multinational cold chain operators require serialized seal-integrity data logging and middleware integration that filters supplier participation.
- Chemical Producers:Hazardous material handlers prioritize UN certification and lot traceability over barrier performance optimization.
- Electronics Assemblers:Semiconductor and component manufacturers specify desiccant-integrated designs for moisture-sensitive device protection.
Direct-to-farmer digital channels are gaining share fastest among food processing procurement routes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI mandates anchor the dominant geography. India's grain belt states drive volume adoption while EU regulatory tightening reshapes material specifications. Nigerian cocoa corridors and Southeast Asian processing hubs concentrate emerging demand.
India
Punjab and Haryana rice cooperatives scale hermetic procurement under FSSAI post-harvest loss reduction programs. BIS certification requirements for food-contact plastics filter supplier participation to qualified converters. Maharashtra and Karnataka basmati exporters now negotiate barrier specifications at headquarters level, displacing fragmented village procurement.
Germany
Converters in the Rhine-Ruhr industrial corridor invest in nine-layer blown film capacity to meet EU Packaging and Packaging Waste Regulation migration limits. ECHA REACH restrictions on per- and polyfluoroalkyl substances force adhesive reformulation across production lines. Bavarian metallized film specialists face aluminum feedstock volatility squeezing quarterly margins.
Nigeria
Cocoa processors in Ondo and Cross River states adopt hermetic solutions for bean-to-bar traceability compliance with European buyer requirements. The country's national agricultural regulator pushes quality standards alignment with export market protocols. Lagos-based sealing service networks create first-mover advantage for localized technical support.
United States
Pharmaceutical cold chain operators in the Boston-Cambridge biotech cluster demand ultra-high-barrier laminates with FDA 21 CFR 177.1520 extractables validation. Serialized seal-integrity data logging requirements filter supplier participation to middleware-capable vendors. Midwest agricultural cooperatives lag in warehouse management system integration for hermetic grain storage deployment.
Vietnam
Rice exporters in the Mekong Delta region adopt hermetic stand-up pouches for direct-to-retail packaging expansion. The country's national food safety authority tightens import packaging standards to align with EU market access requirements. Ho Chi Minh City converters pilot nano-clay reinforced polyethylene tie layers for containerized ocean freight applications.
Hermetic Storage Bags Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the hermetic storage bags supply base. Specialized polymer compounding expertise concentrates among European and Japanese machinery-captive converters while regional fabricators compete on localized service networks. Three archetypes dominate: multilayer film extrusion specialists, metallized barrier technology leaders, and direct-to-farmer engagement platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure barrier film consistency or build sealing service networks.
Among the named participants, GrainPro and GreenPak occupy positions on the technology-specialist vector, with the former exemplifying backward integration into multilayer film extrusion and the latter representing metallized laminate capability for pharmaceutical-grade applications. Ecotact anchors the regional-engagement archetype through South Asian manufacturing presence and farmer-direct distribution channels. These three illustrate how competitive positioning stratifies across technical complexity tiers rather than converging on a single dominant model.
| Leading Market Players |
|---|
| Sesi Technologies |
| AgroZ |
| GrainPro |
| GreenPak |
| Elite Innovations |
| Ecotact |
| Rishi FIBC |
| Supreme |
| Storezo |
| Others |
Pricing and Supply Chain Analysis
FDA 21 CFR 177.1520 and EMA validation protocols gate both supplier qualification timelines and price differentiation simultaneously, compressing margin pools for converters unable to secure pharmaceutical-grade certifications while amplifying premiums for those that do.
Pricing Analysis
German metallized film converters command 40-60% premiums over Indian polyethylene specialists, with pricing stratifying across premium, standard, and economy tiers driven by barrier performance thresholds and extractables validation burden. Aluminum feedstock volatility and nine-layer blown film equipment scarcity squeeze margins unpredictably on metallized variants. Agricultural cooperatives in Punjab and Haryana exhibit highest price sensitivity, while Boston-Cambridge biotech clusters accept premium positioning for validated cold chain specifications.
Supply Chain Analysis
Eighteen-month delivery backlogs for nine-layer blown film lines from European and Japanese machinery suppliers concentrate inventory risk among converters scaling pharmaceutical-grade capacity. Raw material flows draw from Saudi ethylene crackers, German aluminum sputtering feedstock, and Indian BIS-certified polyethylene resin streams. Single-source vulnerability sits with the three European equipment manufacturers controlling precision extrusion technology. Distribution runs through sealing service networks in Lagos and direct-to-farmer mobile platforms in South Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rigid modified atmosphere packaging and tray-sealer systems threaten hermetic bag incumbents in premium protein and ready-meal segments, forcing defensive repositioning around barrier performance advantages that substitutes cannot replicate.
For Market Incumbents: Compound technology leadership in ultra-high-barrier laminates through captive multilayer film extrusion capacity, insulating margin pools from aluminum feedstock volatility. Secure FDA 21 CFR 177.1520 and EMA validation protocols ahead of REACH chemical restriction enforcement windows to freeze out underqualified competitors. Prioritize backward integration into polymer compounding for pharmaceutical cold chain specifications. For New Entrants and Emerging Players: Lead with nano-clay reinforced polyethylene tie layers to miniaturize capital requirements for regional converters serving Colombian and Ethiopian specialty coffee exporters. Target Nigeria's cocoa processing corridor with localized sealing service networks that satisfy bean-to-bar traceability requirements from European buyers. Deploy mobile-enabled agritech platforms to disintermediate traditional agricultural input dealer networks in South Asian grain belt states. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed metallized film specialists in Northern Italy and Osaka prefecture facing adhesive reformulation cliffs under REACH restrictions. Five-to-ten year viability hinges on recycle-ready mono-material structure development aligned with EU Green Deal circular economy mandates. Watch for FDA extractables validation timeline compression as signal of qualification bottleneck easing or intensifying.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Multilayer Film Extrusion | GrainPro secures barrier consistency for coffee and cocoa exporters through captive polymer compounding capacity. |
| Localized Sealing Service Network Deployment | Lagos-based technical support creates first-mover advantage for Nigerian cocoa processors meeting European traceability standards. |
| Recycle-Ready Mono-Material Structure Development | German and Dutch converters accelerate bio-based hot-melt development to maintain seal strength under reduced activation temperatures. |
| Direct-to-Farmer Digital Channel Expansion | Mobile-enabled agritech platforms in Maharashtra and Karnataka disintermediate fragmented village-level procurement networks. |
| Pharmaceutical-Grade Extractables Validation Investment | EMA and FDA compliance protocols filter supplier participation to middleware-capable vendors in cold chain biologics distribution. |
Research Methodology
The analysis maps vacuum seal bags, stand-up pouches, metallized laminates, and polyethylene commodity formats, each validated through converter operations directors, agricultural cooperative procurement managers, pharmaceutical cold chain logistics leads, and regulatory affairs specialists at FDA and EMA. Primary fieldwork combined with secondary validation against customs records, BIS certification databases, SEC filings from packaging multinationals, and EU Packaging and Packaging Waste Regulation implementation guidance. Bottom-up unit economics triangulated against top-down market sizing across the projection horizon.
Consistency checks against external benchmarks validated volume and value outputs across material tiers, application segments, and regional regulatory clusters. Segmentation dimensions modeled include product format, barrier architecture, compliance grade, end-use industry, and geographic procurement concentration. CAGRs derived from fitted growth curves applied to baseline adoption rates, with specific inputs including FSSAI post-harvest loss reduction mandate penetration curves and pharmaceutical cold chain biologics distribution expansion trajectories.
Forecasts assume regulatory continuity in FDA 21 CFR 177.1520, EMA validation protocols, and REACH chemical restriction enforcement; material policy shifts would require re-modeling. Aluminum and ethylene-vinyl alcohol resin volatility, nine-layer blown film equipment delivery backlogs, and competing modified atmosphere packaging substitution represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Vertical Form Fill Seal Baggers Market
Bags and Containers
Bag-In-Box Filler Market
Bags and Containers
Bin Liners Market
Bags and Containers
Volatile Corrosion Inhibitor Bags Market
Bags and Containers
Heat Sealing Bags Market
Bags and Containers
Portion Bags Market
Bags and Containers
Crates Market
Bags and Containers
Carry Bag Market
Bags and Containers
Handle Gusseted Bags Market
Bags and Containers
Cross Bottom Bags Market
Bags and Containers
Bag Dump Stations Market
Bags and Containers
Side Gusset/Quad Seal Bag Market
Bags and Containers
Cross Corner Industrial Bags Market
Bags and Containers
Americas Plastic Bags and Sacks Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
Single Lip Bags Market