
 Scented Trash Bags Market | 2026-2036
Scented Trash Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Scented Trash Bags Market Analytics
China is rewriting regional supply dynamics for polyethylene-based consumer goods. Novolex leverages vertical integration across resin conversion and retail distribution to sustain cost leadership in North American scented bag production. Berry Global Inc. anchors its position through blown-film manufacturing scale and proprietary fragrance-encapsulation technology that extends shelf appeal.
Scented trash bags are thermoplastic film containers, typically 0.5–1.5 mil in gauge, infused with volatile organic fragrance compounds or odor-neutralizing additives during extrusion, designed to suppress malodors from decomposing organic waste in enclosed environments. Kitchen bags dominate volume due to daily household consumption patterns and premium pricing attached to fragrance differentiation. Biodegradable material grades represent the fastest-expanding structural segment as composting infrastructure expands and retail procurement policies prioritize certified compostable films over conventional polyethylene.
The EPA regulates volatile organic compound emissions from fragrance additives in consumer products, while state-level extended producer responsibility frameworks in California and New York reshape material compliance obligations for film converters. ISO 17088 certification for compostable plastics creates market access gates for European and North American suppliers targeting municipal organic waste diversion programs. Stakeholders must monitor how fragmented municipal composting standards across jurisdictions determine which material certifications unlock shelf placement in regulated retail environments.
Market Dynamics
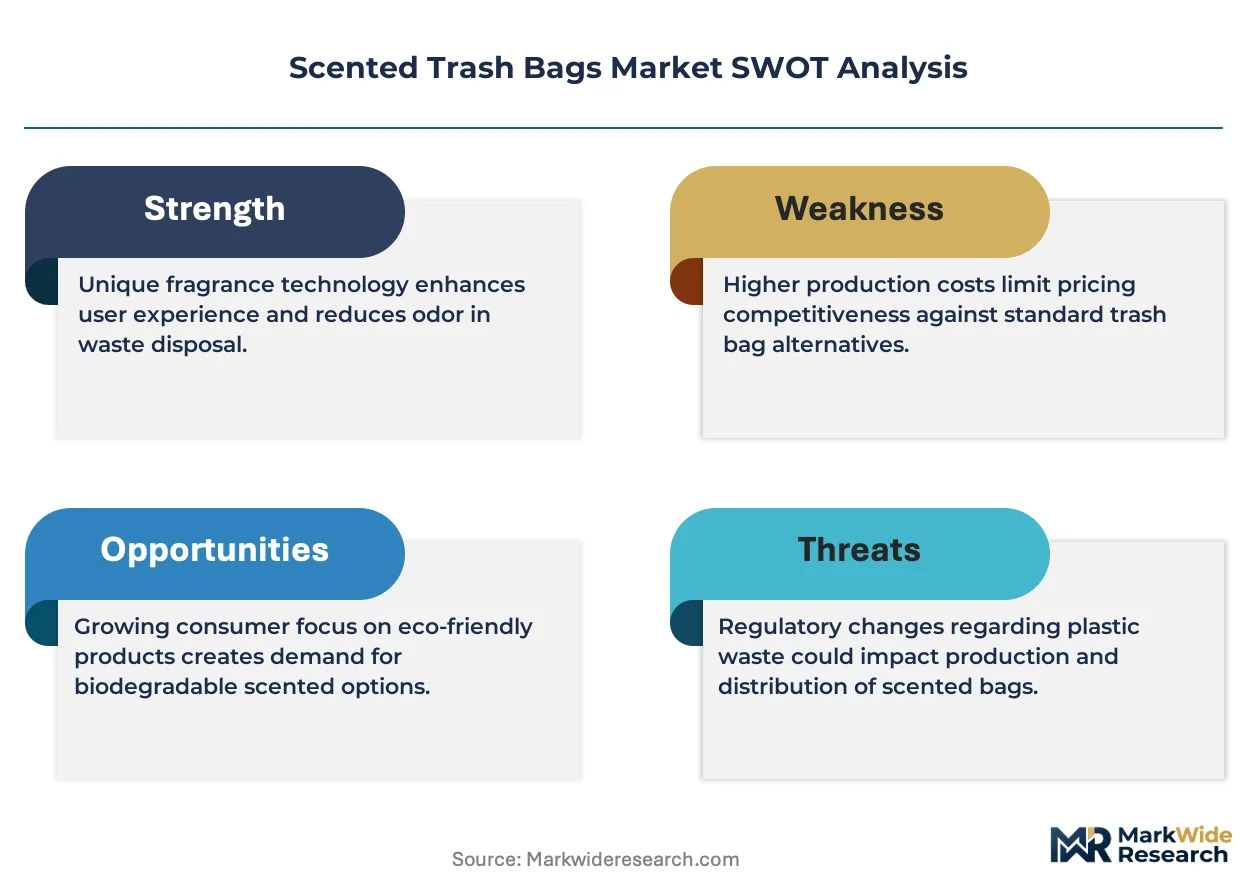
The European Union's Single-Use Plastics Directive is forcing material transitions across the scented trash bag supply chain, converting virgin polyethylene demand toward certified compostable resins and reshaping converter capital allocation priorities.
Growth Catalysts
- Extended Producer Responsibility frameworks:California and New York state mandates obligate film converters to fund end-of-life collection infrastructure, accelerating biodegradable grade adoption in premium kitchen bag segments.
- Suburban household density patterns:Enclosed waste storage in multi-unit residential developments amplifies odor-control requirements, driving fragrance-infused bag penetration in US mass retail channels.
- Composting infrastructure expansion:Municipal organic waste diversion programs in Germany and France create certified demand pools for ISO 17088-compliant film suppliers.
Market Restraints
- Resin cost volatility:Polyethylene feedstock prices track ethylene monomer spreads, compressing margin structures for converters lacking backward integration into resin production.
- Fragrance additive regulation:EPA volatile organic compound emission limits restrict formulation latitude, increasing compliance testing burdens for small and mid-cap manufacturers.
- Performance gap in biodegradable grades:Current PLA and starch-blend films exhibit inferior puncture resistance and moisture barrier properties versus conventional polyethylene in heavy kitchen waste applications.
Strategic Opportunities
- Underpenetrated Indian urban markets:Rising middle-class household formation in Mumbai and Delhi metropolitan regions creates first-mover positioning for odor-control waste solutions in modern retail.
- Healthcare facility applications:Acute care and long-term care facilities generate regulated medical waste streams requiring malodor suppression, opening institutional procurement channels beyond residential.
- Smart dispenser integration:Sensor-enabled automatic trash systems in commercial food service settings create bundled supply contracts linking bag replenishment to IoT-enabled consumption monitoring.
Industry Challenges
- Fragrance encapsulation expertise scarcity:Proprietary microencapsulation processes for controlled scent release require polymer chemistry specializations concentrated among a limited supplier base.
- Multi-jurisdiction certification timelines:Securing compostable certifications across fragmented municipal standards in North America and Europe extends product launch cycles and raises qualification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scented Trash Bags Market |
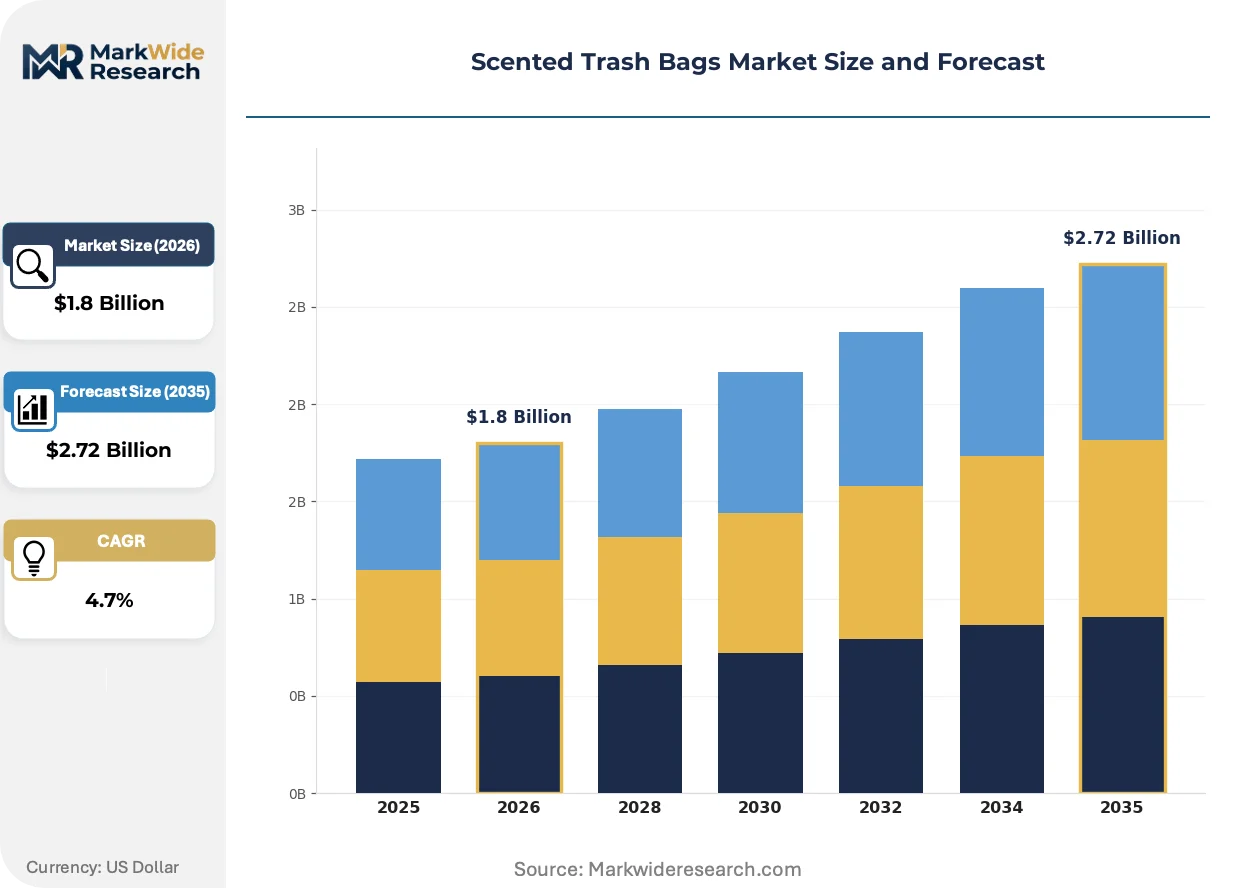
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kitchen Bags, Yard Waste Bags, Pet Waste Bags, Lawn & Leaf Bags Material: Plastic, Biodegradable, Recycled, Compostable Fragrance Type: Fresh Citrus, Floral, Ocean Breeze, Vanilla End User: Household, Commercial, Industrial, Institutional |
| Companies Covered | Novolex, Poly-America, L.P., Berry Global Inc., Four Star Plastics, International Plastics Inc., The Clorox Company, Inteplast Group, Aluf Plastics, Reynolds Consumer Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scented Trash Bags Market Evolving Landscape
Active innovation fronts in scented trash bags center on material science convergence, regulatory compliance automation, and channel-specific product configuration. These forces are compressing traditional product lifecycles while opening differentiated positioning avenues.
Biodegradable resin technology is hybridizing conventional polyethylene processability with compostable end-of-life performance. Blown-film converters in Germany and the Netherlands are adopting starch-PLA coextrusion systems that maintain fragrance retention during shelf storage. The resulting film structures enable European suppliers to serve municipal organic waste contracts without sacrificing manufacturing throughput.
REACH chemical registration requirements in the European Union are extending compliance obligations to fragrance additive suppliers, forcing reformulation of volatile organic compound profiles. Film converters must now document full material substance inventories across their supply base. Kitchen bag segments targeting German and French retail channels are responding by consolidating supplier relationships toward pre-registered additive portfolios.
Subscription-based replenishment models are displacing traditional retail stocking patterns among affluent US suburban households. Direct-to-consumer channels bundle scented kitchen bags with complementary household consumables, capturing higher lifetime value per account. This pattern is most visible in coastal metropolitan markets where e-commerce penetration in household supplies exceeds inland regions by significant margins.
Scented Trash Bags Market Segmentation
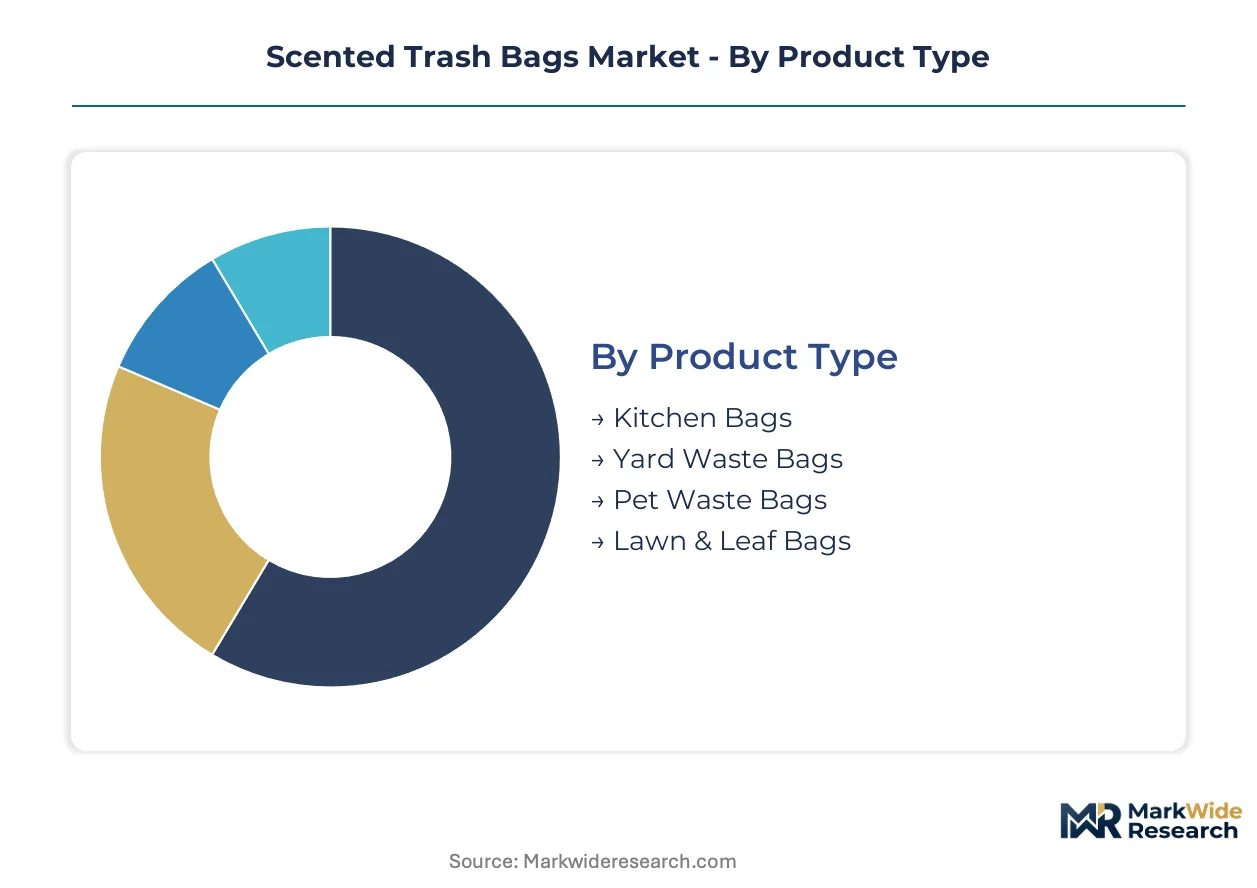
Segmentation in scented trash bags reveals how odor-control technology, material compliance, and channel economics intersect. Each dimension carries distinct margin profiles and regulatory exposure that reshape supplier priorities across residential and institutional demand pools.
Product Type:
After-sales service intensity varies sharply across product types, with kitchen bags requiring sustained fragrance performance validation and institutional segments demanding compliance documentation support.
- Kitchen Bags:These 0.8–1.2 mil gauge films incorporate microencapsulated fragrance systems designed for 7–14 day odor suppression in food waste applications. Demand concentrates in US suburban households where premium positioning commands mass retail shelf space and repeat purchase loyalty.
- Yard Waste Bags:Heavier 1.5–2.0 mil constructions with reinforced seams handle branch and grass clipping loads. Municipal composting programs in Germany and France specify these for organic waste diversion, linking procurement to ISO 17088 certification requirements.
- Pet Waste Bags:Compact roll-format films with masking fragrances target dog park and walking trail consumption. Urban pet ownership density in coastal US metros drives volume.
- Lawn & Leaf Bags:Seasonal high-capacity designs for autumn debris collection. Big-box retail seasonal resets determine annual production scheduling for converters.
Kitchen bags hold the largest share; momentum sits with yard waste bags as municipal composting mandates expand.
Material:
Cost tier stratification separates commodity polyethylene from certified alternatives, with converters managing dual supply chains to serve regulated and unregulated channels simultaneously.
- Plastic:Conventional polyethylene and polypropylene films dominate manufacturing throughput. Virgin resin price volatility compresses margins for non-integrated converters serving US mass retail.
- Biodegradable:Starch-PLA hybrid formulations degrade under industrial composting conditions. European Union Single-Use Plastics Directive procurement rules are accelerating specification in German and French retail.
- Recycled:Post-consumer resin incorporation responds to California and New York extended producer responsibility frameworks. FDA food-contact limitations restrict kitchen bag applications.
- Compostable:Films meeting ASTM D6400 and EN 13432 standards for municipal organic waste streams. Certification timelines and fragmented municipal standards complicate market entry.
Plastic retains volume leadership; biodegradable grades are climbing the fastest as regulatory thresholds tighten.
Fragrance Type:
Application context determines fragrance selection, with kitchen environments favoring masking potency and commercial settings prioritizing neutral perception.
- Fresh Citrus:Limonene-based formulations dominate kitchen bag positioning. EPA volatile organic compound emission limits constrain formulation latitude for US suppliers.
- Floral:Rose and lavender profiles target bathroom and bedroom waste applications. Seasonal variant launches align with retail reset calendars.
- Ocean Breeze:Synthetic marine accords position in premium tier assortments. Coastal metropolitan markets show higher penetration.
- Vanilla:Warm gourmand profiles differentiate mass-market value tiers. Fragrance load levels adjust to price point requirements.
Fresh citrus commands household penetration; ocean breeze is gaining share fastest in premium channel expansion.
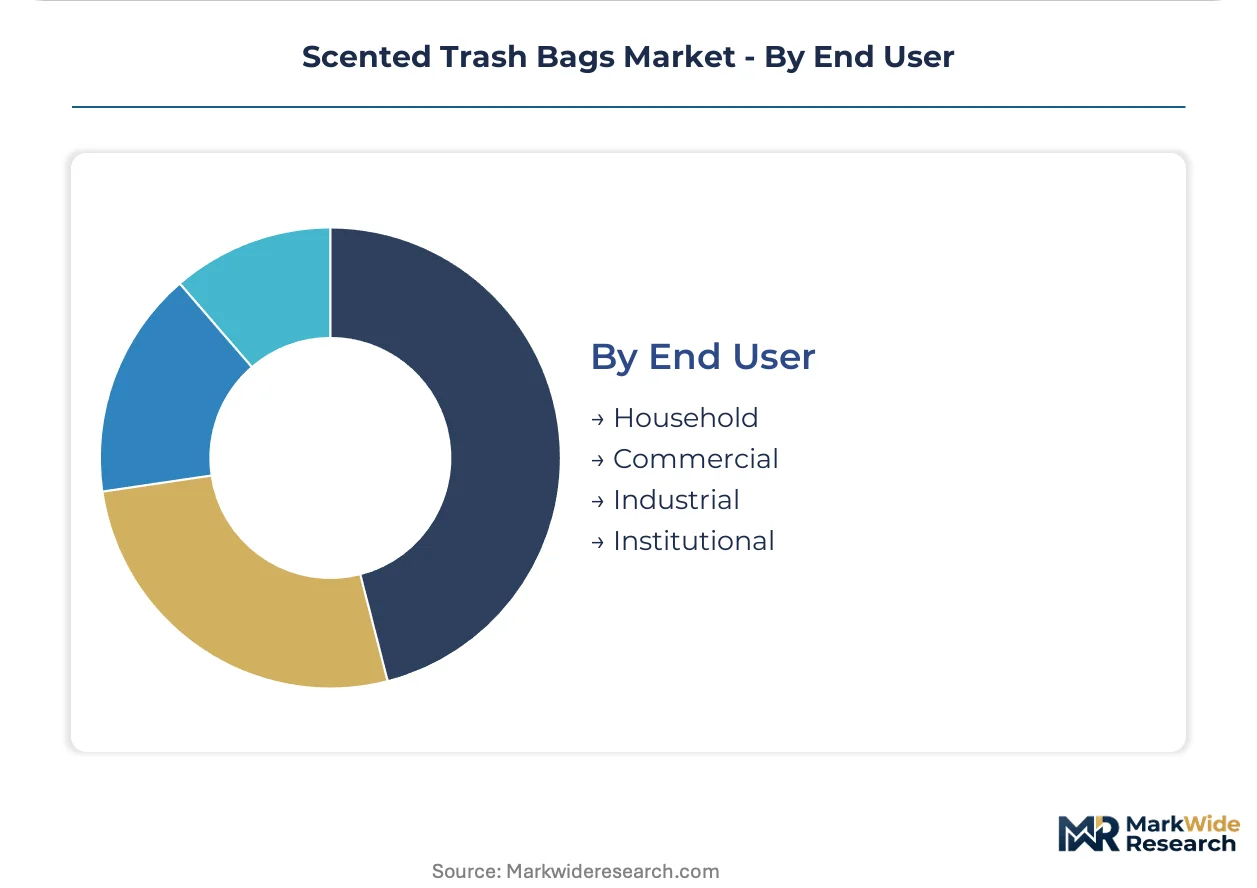
End User:
Customer type segmentation exposes divergent procurement logic, with households responding to shelf appeal and institutions requiring specification compliance.
- Household:Individual consumers purchasing through mass retail, club, and e-commerce channels. Subscription replenishment models are displacing traditional stocking patterns in affluent US suburbs.
- Commercial:Food service, hospitality, and office facility procurement. Smart dispenser integration in restaurant chains creates bundled supply contracts.
- Industrial:Manufacturing and warehouse waste containment with odor suppression requirements. Volume pricing and custom sizing predominate.
- Institutional:Healthcare, education, and government facility procurement. Acute care medical waste streams require malodor suppression with infection control compatibility.
Household generates absolute volume; institutional channels show the steepest expansion trajectory as healthcare procurement standards formalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's polymer logistics hub underwrites European supply security for polyethylene resin, while the Union Pacific rail network distributes converted film products across the North American interior. These infrastructure assets anchor regional production footprints and determine cost-competitive reach.
United States
Suburban household formation in Texas and Florida metro corridors drives kitchen bag volume through mass retail channels. EPA volatile organic compound emission limits constrain fragrance formulation latitude for domestic converters. The Southeast manufacturing belt, anchored by Georgia and South Carolina film extrusion clusters, supplies private-label programs for club store chains.
Germany
Municipal organic waste diversion mandates in Bavaria and North Rhine-Westphalia create certified demand pools for compostable film grades. The EU Single-Use Plastics Directive accelerates specification shifts in retail procurement rules. The Rhine-Main industrial corridor hosts blown-film converters adopting starch-PLA coextrusion systems for fragrance-retentive biodegradable structures.
China
Rising urban household density in Shanghai and Shenzhen amplifies odor-control requirements in high-rise residential waste storage. The country's national environmental regulator enforces stricter plastic pollution controls under dual carbon policy frameworks. The Yangtze River Delta manufacturing cluster supplies polyethylene resin conversion for both domestic consumption and export-oriented production.
India
Middle-class household formation in Mumbai and Delhi metropolitan regions creates first-mover positioning for premium fragrance-infused waste solutions. The Bureau of Indian Standards is developing compostable plastics certification protocols aligned with international norms. Maharashtra's industrial belt near Pune hosts emerging film extrusion capacity targeting modern retail channel growth.
France
Extended producer responsibility frameworks obligate film converters to fund end-of-life collection infrastructure for household waste streams. ANSM chemical registration requirements extend compliance obligations to fragrance additive suppliers. The Lyon-Grenoble polymer chemistry cluster supports microencapsulation process development for controlled scent release applications.
Scented Trash Bags Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in resin conversion and fragrance technology. The vendor base organizes around three structural tiers: multinational film converters with captive resin supply, regional extrusion houses serving private-label programs, and specialty additive suppliers holding proprietary encapsulation intellectual property. Strategic moves concentrate on backward integration into resin production and geographic expansion into underpenetrated Asian markets.
Among North American-based integrated manufacturers, Novolex, Berry Global Inc., and Reynolds Consumer Products exemplify scale-driven competitive positioning. Novolex occupies a position representing backward integration across resin conversion and retail distribution channels. Berry Global Inc. anchors the proprietary technology tier through blown-film manufacturing scale and fragrance-encapsulation capabilities. Reynolds Consumer Products sits within the branded consumer goods archetype, leveraging household name recognition in mass retail shelf placement negotiations.
| Leading Market Players |
|---|
| Novolex |
| Poly-America, L.P. |
| Berry Global Inc. |
| Four Star Plastics |
| International Plastics Inc. |
| The Clorox Company |
| Inteplast Group |
| Aluf Plastics |
| Reynolds Consumer Products |
| Others |
Value Network & Pricing Analysis
Ethylene monomer price volatility compresses margin structures for non-integrated converters while simultaneously widening spreads between premium fragrance-encapsulated tiers and commodity polyethylene alternatives. This feedstock instability determines both the three-tier pricing architecture across certified biodegradable, recycled-content, and virgin resin grades and the geographic clustering of backward-integrated production capacity near Gulf Coast petrochemical complexes.
Pricing Analysis
Volume-discount tiering structures separate club store pallet pricing from convenience retail single-roll premiums by ratios exceeding three-to-one in equivalent gauge specifications. Price differentiation hinges on ISO 17088 certification status and proprietary microencapsulation technology ownership, with fragrance-retentive biodegradable films commanding sustained premiums. Cost compression in standard polyethylene kitchen bags intensifies as Chinese resin exports displace domestic supply in Southeast Asian export markets. Mass retail private-label buyers exhibit highest price sensitivity, while healthcare institutional procurement prioritizes compliance documentation over unit cost.
Supply Chain Analysis
Upstream ethylene cracker output from Texas and Louisiana Gulf Coast complexes feeds North American blown-film extrusion clusters concentrated in Georgia and South Carolina. Virgin polyethylene resin, starch-PLA hybrid compounds, and proprietary fragrance additive concentrates constitute critical input dependencies. Single-source vulnerability concentrates in microencapsulation chemistry specializations held by limited European additive houses. Distribution runs through Union Pacific rail networks to inland mass retail distribution centers, with coastal port access enabling export-oriented production from Charleston and Savannah.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proprietary fragrance-encapsulation expertise and multi-jurisdiction compostable certification capabilities constitute scarce, defensible assets that separate margin-accretive positioning from commodity trap vulnerability. The gap between converters with captive polymer chemistry R&D and resin-dependent extrusion houses is widening.
For Market Incumbents: Insulate margin structures by securing captive supply of starch-PLA hybrid resins through offtake agreements with emerging biopolymer producers in the Netherlands and Germany. Accelerate ISO 17088 pre-certification across multiple municipal standards before fragmented compliance timelines extend product launch cycles. Defend against private-label encroachment by embedding smart dispenser integration capabilities in food service channel contracts. For New Entrants and Emerging Players: Build out biodegradable grade production capacity targeting Maharashtra's industrial belt near Pune, where Bureau of Indian Standards certification protocols are creating first-mover positioning in Mumbai and Delhi modern retail channels. Prioritize pet waste bag segments with lower fragrance encapsulation complexity and faster qualification cycles. Pursue direct-to-consumer subscription bundling with complementary household consumables to bypass mass retail slotting fee barriers. For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors converters with pre-certified compostable film portfolios and established municipal procurement relationships. Long-term viability hinges on material science capabilities bridging polyethylene processability with certified end-of-life performance. Target acquisition archetypes include regional extrusion houses with latent blown-film capacity and pending certification submissions. Monitor EPA volatile organic compound emission limit revisions as inflection indicators for reformulation cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Grade Certification | ISO 17088 pre-certification unlocks German and French municipal organic waste procurement contracts. |
| Backward Integration into Resin | Captive ethylene supply from Gulf Coast crackers insulates margin compression from spot market volatility. |
| Direct-to-Consumer Channel Launch | Subscription bundling in affluent US coastal metros displaces traditional retail stocking patterns. |
| Smart Dispenser Integration | Sensor-enabled replenishment contracts with restaurant chains create sticky institutional revenue streams. |
| Fragrance Encapsulation R&D | Proprietary controlled-release polymer chemistry extends shelf appeal and commands sustained pricing premiums. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with film converter plant managers, mass retail category buyers, municipal waste diversion program administrators, and fragrance additive technical directors. Secondary validation drew from EPA volatile organic compound emission filings, EU Single-Use Plastics Directive implementation reports, customs trade data for polyethylene resin flows, and blown-film equipment manufacturer order backlogs. Bottom-up segment volume builds were cross-checked against top-down resin consumption estimates across the analysis window.
Calibration approaches anchored volume projections to historical polyethylene price elasticity patterns and municipal composting infrastructure deployment schedules. Segmentation dimensions modeled include material grade tier, fragrance type, end-use application, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves rather than mechanical extrapolation. Industry-specific forecast inputs incorporated EU procurement rule phase-in timelines and Indian modern retail channel expansion trajectories.
Practitioners should monitor ethylene cracker operating rate announcements and Bureau of Indian Standards certification protocol finalizations for early signals of supply cost or market access revisions. Cross-checking against American Chemistry Council resin production data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Volatile Corrosion Inhibitor Bags Market
Bags and Containers
Non-Barrier Bag Market
Bags and Containers
Vacuum Sealer Bags Market
Bags and Containers
Packaging Peanuts Market
Bags and Containers
Anti-Static Collapsible Tote Bins Market
Bags and Containers
Bulk Bag Unloaders Market
Bags and Containers
Circular Industrial Bags Market
Bags and Containers
Bag-In-Box Filler Market
Bags and Containers
Bagster Bag Market
Bags and Containers
Woven Sacks Market
Bags and Containers
Global Bubble Lined Courier Bag Market
Bags and Containers
Bag-In-Box Market
Bags and Containers
Twisted Handle Bags Market
Bags and Containers
Double Zipper Bags Market
Bags and Containers
Portion Bags Market
Bags and Containers
Garbage Bag Market